
 North America Air Conditioning Equipment Market | 2026-2036
North America Air Conditioning Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Air Conditioning Equipment Market Analytics
Data center cooling demand is hardening as the fastest-growing end-use vertical across the North American landscape. Carrier Global leverages its chiller technology leadership to anchor positions in hyperscale facilities. Daikin Industries competes through inverter compressor specialization that trims energy draw during partial-load operation. Trane Technologies sustains geographic dominance in the southeastern United States through extensive service networks.
North America air conditioning equipment encompasses vapor-compression and absorption systems engineered to maintain indoor thermal comfort and process cooling across residential, commercial, and industrial environments. These systems typically operate with refrigerants such as R-410A or lower-GWP alternatives like R-32, achieving seasonal energy efficiency ratios (SEER) ranging from 14 to 25 depending on equipment class. Split systems occupy the largest installed base across the region, reflecting their adaptability to varied building envelopes and zoning requirements. Smart technology integration represents the fastest-expanding technology segment, with connected thermostats and predictive maintenance protocols reshaping aftermarket service revenue pools. Central air systems retain mature volume positions in single-family residential construction, though margin compression from commodity competition has shifted manufacturer focus toward higher-efficiency premium tiers.
The U.S. Department of Energy sets minimum efficiency standards under the National Appliance Energy Conservation Act, while the Environmental Protection Agency governs refrigerant phase-down schedules through authority delegated from the AIM Act. Canada's Natural Resources Canada administers parallel EnerGuide labeling and minimum energy performance standards that align with U.S. tiers to preserve cross-border supply chain fluidity. Stakeholders must monitor refrigerant transition timelines and efficiency tier escalations to avoid stranded inventory and qualify for federal tax credits under the Inflation Reduction Act.
Market Dynamics
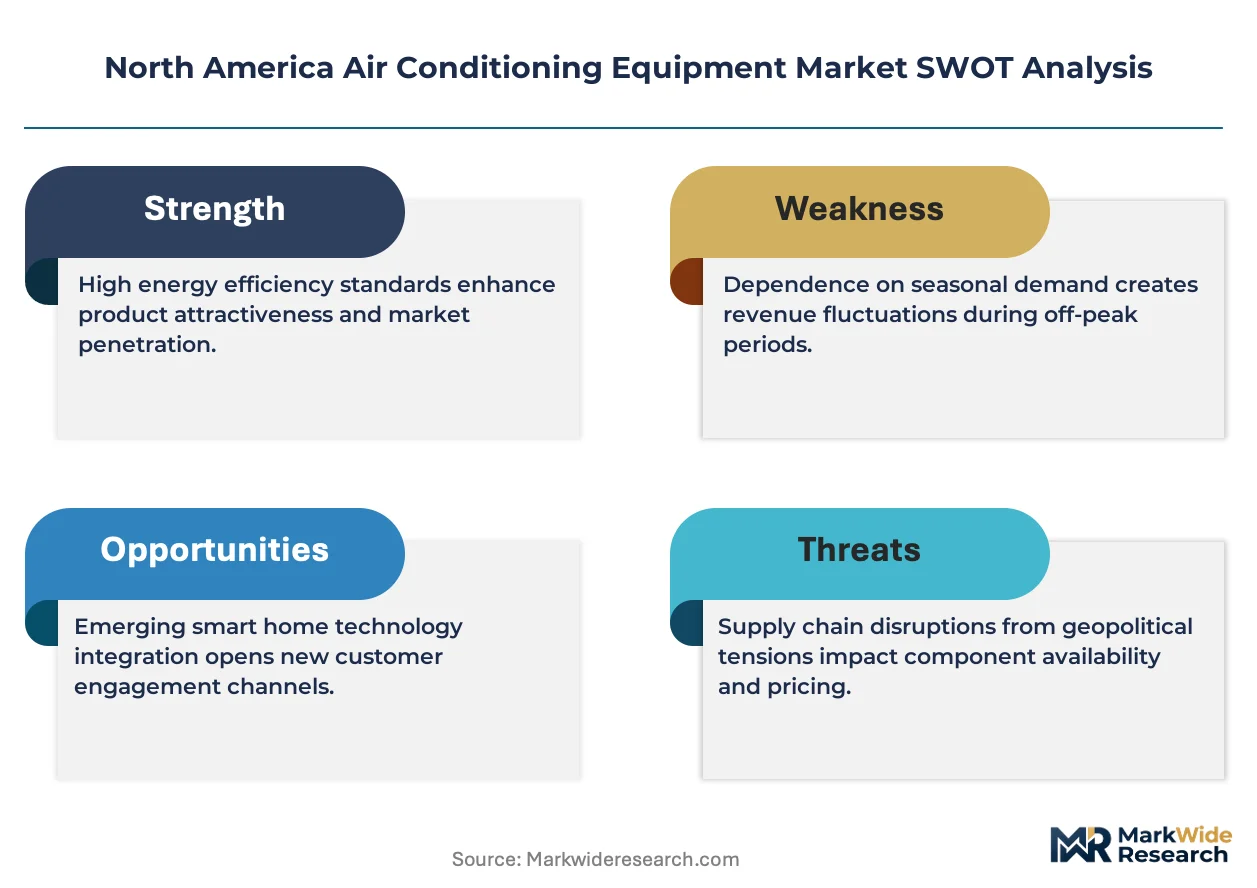
The U.S. Department of Energy's escalating SEER minimums are compressing manufacturer margins while simultaneously accelerating inverter technology adoption across residential and commercial product lines.
Growth Catalysts
- Inverter compressor penetration:Variable-speed drives now dominate new construction specifications across the U.S. Sun Belt, cutting energy draw during partial-load operation.
- Data center buildouts:Hyperscale facility expansion across northern Virginia and Phoenix is pulling precision cooling systems at volumes unseen in traditional commercial HVAC.
- Inflation Reduction Act rebates:Federal tax credits for heat pump installations are shortening replacement cycles in single-family residential segments.
Market Restraints
- Copper and aluminum input volatility:Raw material price swings compress fabrication margins for coil and heat exchanger producers.
- Refrigerant transition friction:The EPA's phasedown schedule under AIM Act authority strands R-410A inventory while R-32 supply chains mature.
- Skilled technician scarcity:HVAC installer shortages in Texas and Florida extend project timelines and inflate labor costs.
Strategic Opportunities
- Smart thermostat convergence:Predictive maintenance algorithms bundled with connected controls open recurring revenue streams beyond equipment sales.
- Mexico manufacturing expansion:Nearshoring assembly to Monterrey and Tijuana reduces tariff exposure and trims logistics costs to U.S. distribution hubs.
- Commercial electrification mandates:Building performance standards in New York City and Vancouver are banning fossil fuel heating, expanding heat pump addressable markets.
Industry Challenges
- Certification lag for low-GWP refrigerants:Underwriters Laboratories and AHRI testing backlogs delay product launches by 8-14 months.
- Legacy control system incompatibility:BACnet and Modbus integration failures with 1990s-era building management systems stall retrofit projects.
- Inventory stranding risk:Distributors holding pre-2023 efficiency-tier stock face write-downs as DOE minimums escalate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Air Conditioning Equipment Market |
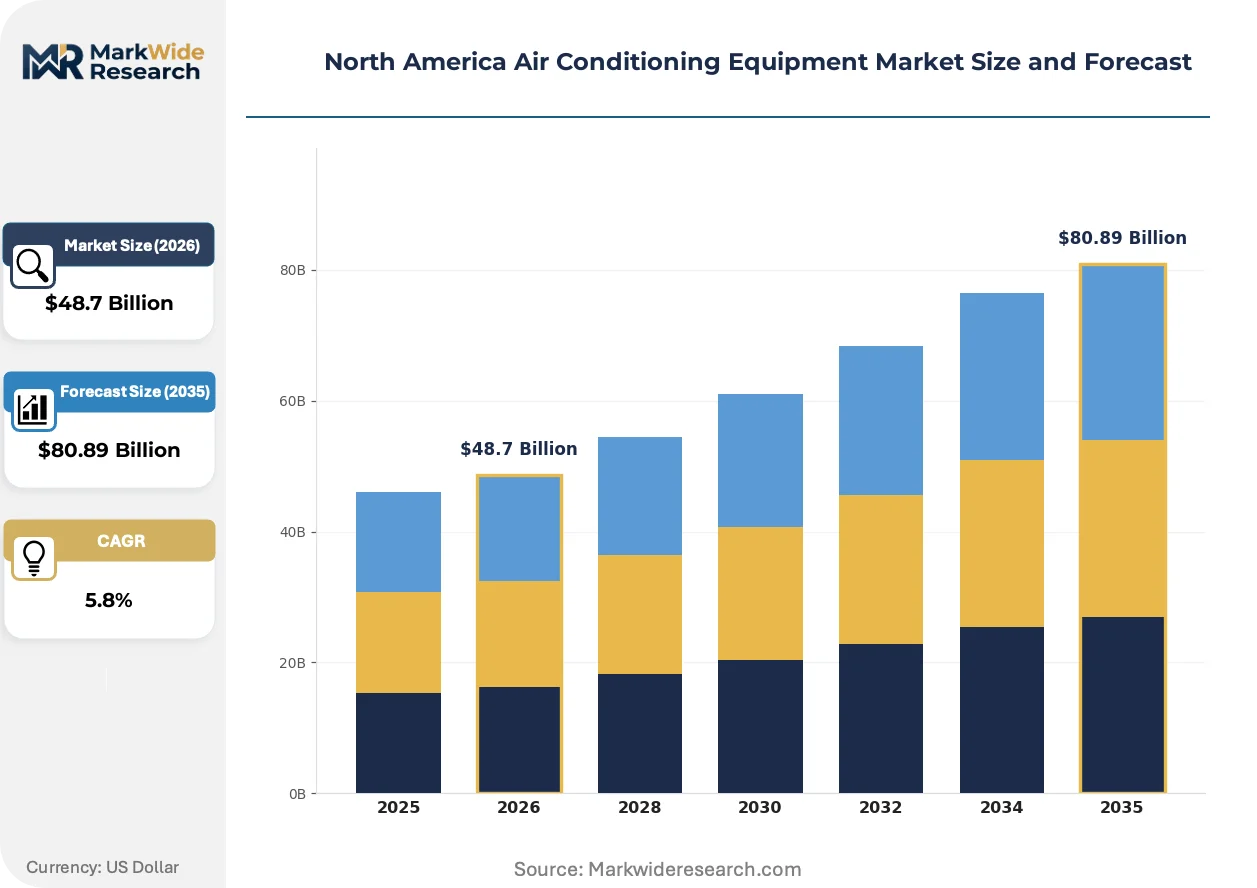
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Split Systems, Window Units, Portable Units, Central Air Technology: Inverter, Non-Inverter, Smart Technology, Conventional End User: Residential, Commercial, Industrial, Institutional Installation Type: Direct Install, DIY, Retrofit, New Construction |
| Companies Covered | Trane Technologies, Daikin Industries, Carrier Global, Johnson Controls, Lennox International, Rheem Manufacturing Company, Mitsubishi Electric, Nortek Global HVAC, AAON, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Air Conditioning Equipment Market Evolving Landscape
Refrigerant chemistry, compressor architecture, and control intelligence are converging to redefine equipment value propositions beyond raw cooling capacity.
Variable refrigerant flow systems are consolidating market share in mid-rise commercial construction across the southeastern United States. Developers in Atlanta and Charlotte specify VRF for its zoning flexibility and reduced ductwork footprint. The technology is consolidating specification authority away from traditional split-system contractors toward integrated building solution providers.
The EPA's refrigerant management regulations under Clean Air Act authority are forcing wholesale equipment redesigns ahead of 2025 production deadlines. Manufacturers must validate new charge sizes and safety protocols for mildly flammable A2L refrigerants. Commercial chiller lines face the steepest compliance costs, accelerating consolidation among smaller fabrication shops.
Performance-based service contracts are displacing time-and-materials maintenance arrangements in institutional buyer segments. Universities and hospital systems in California and Ontario now specify uptime guarantees rather than preventive visit schedules. This shift concentrates aftermarket revenue with OEMs possessing remote diagnostic platforms, squeezing independent service contractors.
North America Air Conditioning Equipment Market Segmentation
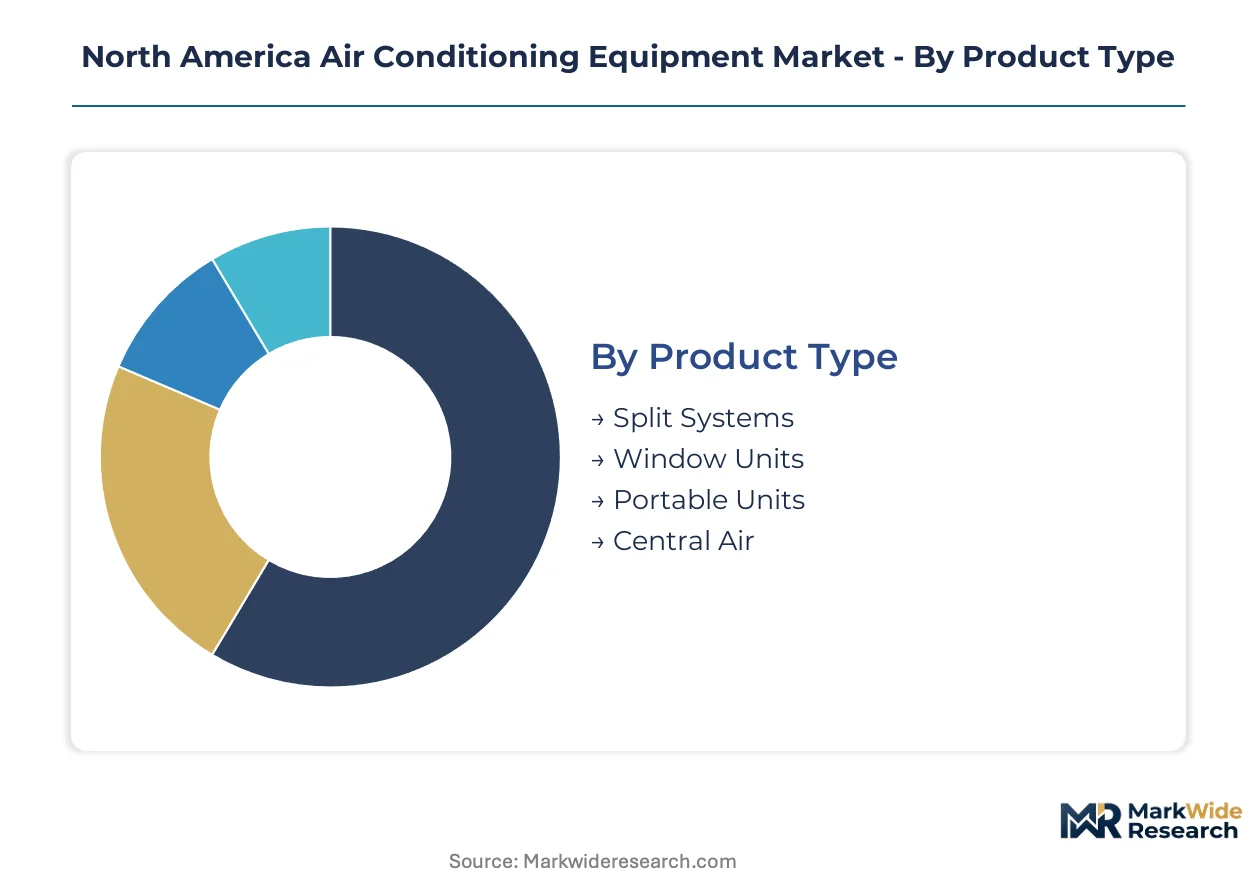
Equipment segmentation in North America air conditioning reveals divergent capital requirements across product architectures and installation modalities. Technology tiers and end-use specifications determine margin structures, refrigerant compliance pathways, and aftermarket service revenue potential for manufacturers and distributors.
Product Type:
Capital intensity varies sharply across product architectures, with ducted central systems demanding the highest upfront equipment and installation investment while portable units require minimal fixed asset deployment.
- Split Systems:Compressor-condenser units paired with indoor evaporators operate with SEER ratings from 16 to 25. Demand concentrates across Texas and Florida single-family retrofits where zoning flexibility offsets higher installed costs against operating savings.
- Central Air:Ducted whole-house systems with air handlers and condensing units dominate new construction specifications. Sun Belt tract home builders specify these systems for cost efficiency at volume, though efficiency tier escalation under DOE standards is compressing base-model margins.
- Window Units:Self-contained through-wall systems serve rental housing and supplemental cooling in legacy buildings. Seasonal replacement cycles in the U.S. Northeast drive volume.
- Portable Units:Mobile evaporative and compressor-based units target apartments with installation restrictions. Big-box retail channels dominate distribution.
Most installed capacity flows through Split Systems. Expansion is steepest in Central Air as new construction rebounds across Arizona and Nevada.
Technology:
Technology segmentation tracks power electronics sophistication, with inverter drives and connected controls commanding premium positioning against fixed-speed conventional architectures.
- Inverter:Variable-frequency drives modulate compressor speed to match cooling loads, cutting partial-load energy draw. California Title 24 building codes and federal tax credits under the Inflation Reduction Act are accelerating specification across mid-rise commercial and high-end residential segments.
- Smart Technology:Connected thermostats, predictive diagnostics, and demand-response integration reshape aftermarket economics. Institutional buyers in Ontario and British Columbia now specify uptime-guarantee contracts tied to remote monitoring platforms.
- Non-Inverter:Fixed-speed compressors cycle on-off to maintain setpoints. Volume concentrates in replacement markets where first-cost sensitivity dominates.
- Conventional:Basic electromechanical controls without connectivity or variable-speed operation. Distribution channels in Mexico retain significant volume for price-sensitive segments.
Technology margins concentrate in Smart Technology. Inverter is gaining share fastest as efficiency regulations harden across U.S. federal and state jurisdictions.
End User:
End-user segmentation maps to building typology and cooling load profiles, with industrial process cooling and data center applications demanding precision environmental control distinct from comfort conditioning.
- Residential:Single-family and multifamily comfort conditioning across owner-occupied and rental housing. Sun Belt replacement cycles and Inflation Reduction Act heat pump incentives are shortening equipment lifecycles.
- Commercial:Office, retail, and hospitality environments with occupancy-driven load variability. Variable refrigerant flow systems are displacing traditional split configurations in Atlanta and Charlotte mid-rise construction.
- Industrial:Process cooling for manufacturing, cold chain, and heavy industrial applications. Food processing facilities across the U.S. Midwest specify ammonia-based and CO2 transcritical systems for low-temperature requirements.
- Institutional:Healthcare, education, and government facilities with 24/7 uptime requirements. Performance-based service contracts with guaranteed availability are displacing preventive maintenance schedules in California hospital systems.
Revenue concentration sits with Residential volume. Industrial is climbing the fastest as data center buildouts across northern Virginia and Phoenix pull precision cooling at unprecedented scale.
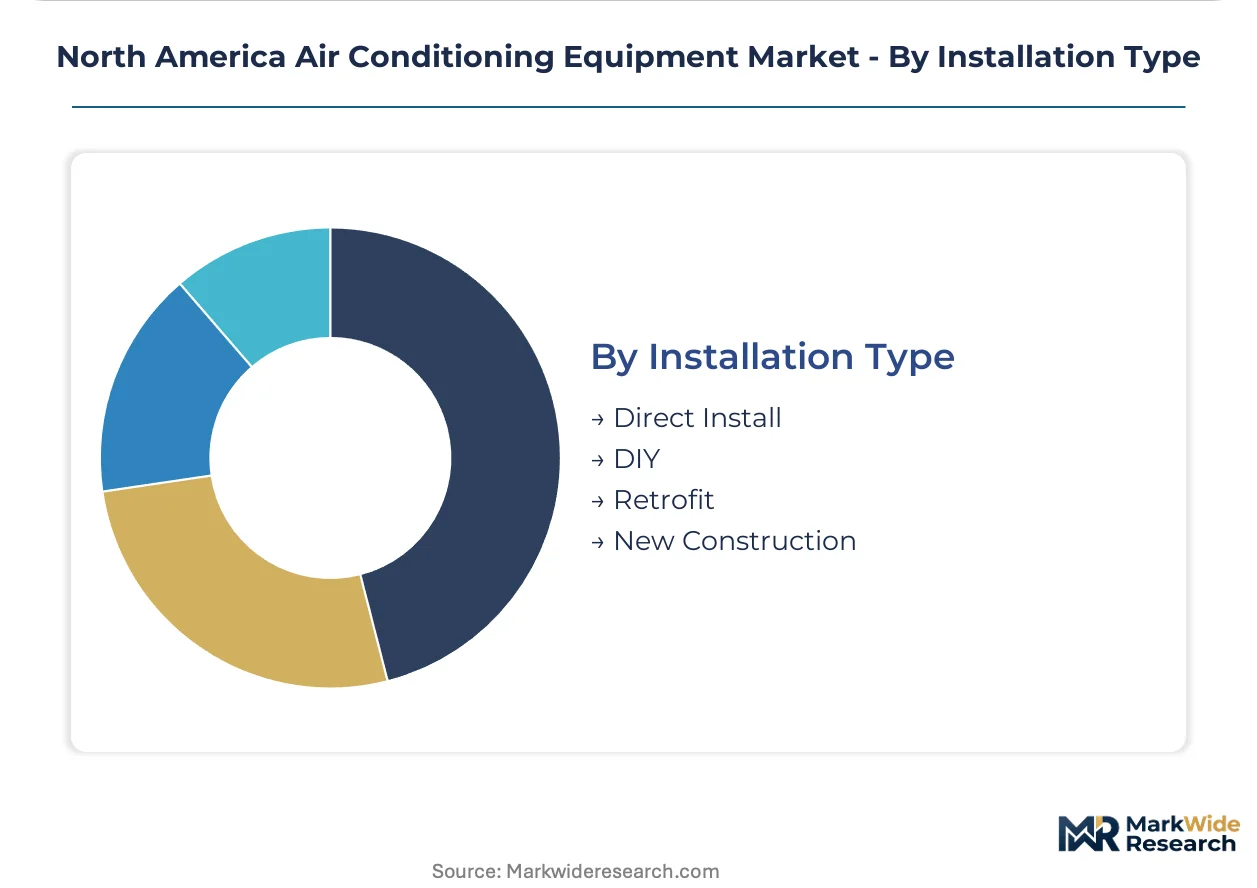
Installation Type:
Installation modality determines channel economics and labor allocation, with new construction offering volume efficiency against retrofit complexity and DIY segments minimizing professional labor capture.
- New Construction:Equipment specified during building design with integrated ductwork and controls. Tract home builders in Texas and Arizona drive volume through national account purchasing agreements.
- Retrofit:Replacement of legacy systems within existing building envelopes. R-410A phase-down under EPA AIM Act authority is accelerating replacement timelines as distributors avoid stranded inventory.
- Direct Install:Contractor-managed installation with full warranty and permitting compliance. Skilled technician scarcity in Florida and Texas is extending project timelines and inflating labor costs.
- DIY:Consumer-purchased equipment with self-managed installation, primarily window and portable units. E-commerce channels are capturing share from hardware retail.
Volume flows through New Construction. Retrofit is expanding most quickly as efficiency tier escalations and refrigerant transitions compress replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing migration toward Mexico accelerates as producers arbitrage cost-of-compliance gaps between EPA refrigerant mandates and Mexico's transitional regulatory framework. Assembly lines in Monterrey and Tijuana capture tariff advantages while maintaining logistics proximity to U.S. distribution hubs.
United States
Data center construction in northern Virginia and Phoenix pulls precision cooling equipment at volumes exceeding traditional commercial HVAC demand. The U.S. Department of Energy's escalating SEER minimums under the National Appliance Energy Conservation Act compress margins while accelerating inverter technology adoption. Sun Belt states from Texas to Florida drive replacement cycles through prolonged cooling seasons and Inflation Reduction Act heat pump incentives.
Canada
Cold climate heat pump deployment expands across Ontario and British Columbia as Natural Resources Canada aligns EnerGuide standards with U.S. efficiency tiers. The federal government's Greener Homes Grant program subsidizes high-efficiency residential installations, shortening equipment lifecycles in Vancouver and Toronto metropolitan markets. Cross-border supply chain integration preserves component sourcing fluidity with U.S. fabrication networks.
Mexico
Nearshoring assembly operations concentrate in Nuevo León and Baja California to service U.S. demand with reduced logistics costs. Mexico's Secretariat of Energy maintains refrigerant phase-down schedules lagging EPA timelines by 24-36 months, creating cost-of-compliance arbitrage for export-oriented production. Monterrey-based fabrication facilities supply split-system components to Texas and Arizona distribution corridors.
North America Air Conditioning Equipment Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers reposition assembly assets to capture nearshoring advantages and refrigerant transition windows. The vendor structure consolidates around integrated building solution providers with captive distribution networks, while independent coil fabricators face margin compression from raw material volatility. Three archetypes define competitive positioning: full-system OEMs with service network density, component specialists with inverter compressor expertise, and integrated controls providers with predictive maintenance platforms. Geographic expansion into Mexico and strategic partnerships for R-32 supply chain access represent the dominant competitive moves.
Among U.S.-based full-system providers, Trane Technologies and Carrier Global occupy positions defined by service network scale and chiller technology leadership. Daikin Industries, a Japan-based Co., Ltd., exemplifies the inverter specialization archetype through variable-frequency drive integration. These three anchors illustrate how competitive advantage flows from either captive installation infrastructure or power electronics sophistication rather than raw manufacturing scale.
| Leading Market Players |
|---|
| Trane Technologies |
| Daikin Industries |
| Carrier Global |
| Johnson Controls |
| Lennox International |
| Rheem Manufacturing Company |
| Mitsubishi Electric |
| Nortek Global HVAC |
| AAON |
| Others |
Value Network & Pricing Analysis
EPA refrigerant phase-down mandates under AIM Act authority gate qualified supply access and premium-tier pricing power, compressing margins for distributors holding pre-2023 efficiency-tier inventory while rewarding OEMs with certified R-32 product lines and inverter-ready distribution networks.
Pricing Analysis
Distributor margin compression runs through the wholesale-to-contractor channel as DOE efficiency tier escalations force write-downs on stranded R-410A stock. Three-tier pricing structure across premium inverter, standard fixed-speed, and economy non-certified levels separates SEER 20+ systems eligible for IRA tax credits from base-code compliance units. Cost compression in the standard tier intensifies because copper and aluminum input volatility erodes fabrication margins. Single-family residential retrofits in Texas and Florida show highest price sensitivity, while data center precision cooling buyers prioritize uptime guarantees over capital expenditure.
Supply Chain Analysis
Regional distribution centers in Texas, Arizona, and California anchor hub-and-spoke patterns feeding Sun Belt contractor networks. Manufacturing concentrates in Mexico, China, and the United States, with Monterrey and Tijuana assembly lines capturing nearshoring advantages for U.S. distribution corridors. Coil and heat exchanger production draws from copper cathode and aluminum sheet inputs vulnerable to commodity price swings. Single-source vulnerability sits with inverter compressor modules sourced from concentrated Asian electronics suppliers. Distribution runs through national account agreements with tract home builders and independent HVAC contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where DOE efficiency standard escalations and EPA refrigerant timelines continuously reset equipment replacement cycles and premium-tier demand.
For Market Incumbents: Deepen captive service network density across northern Virginia and Phoenix data center corridors to lock in performance-based uptime contracts. Accelerate backward integration into R-32 refrigerant supply chains before certification backlogs widen. Defend against inverter compressor specialists by bundling predictive maintenance platforms with equipment sales. For New Entrants and Emerging Players: Launch via direct-to-installer digital channels targeting independent HVAC contractors in Texas and Florida facing skilled technician scarcity. White-space opportunity concentrates in cold climate heat pump retrofits across Ontario and British Columbia where Natural Resources Canada subsidies shorten replacement cycles. Target institutional buyers in California hospital systems with outcome-based service contracts displacing preventive maintenance schedules. For Investors and Strategic Acquirers: Roll-up economics work for regional HVAC service aggregators because technician scarcity and refrigerant transition complexity favor scaled diagnostic platforms over independent operators. Long-term viability hinges on exposure to IRA-subsidized residential heat pump volume and data center precision cooling buildouts. Watch EPA refrigerant certification timelines as inflection indicator for inventory stranding risk and OEM consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Technology Certification | UL and AHRI testing completion unlocks IRA tax credit eligibility and premium-tier pricing. |
| Mexico Manufacturing Expansion | Monterrey assembly reduces tariff exposure and trims logistics costs to Arizona distribution hubs. |
| Predictive Maintenance Platform Launch | Remote diagnostic bundling captures recurring revenue from California hospital uptime guarantees. |
| R-32 Supply Chain Partnership | Refrigerant access agreements prevent production delays ahead of EPA 2025 phase-down deadlines. |
| Data Center Service Network Density | Northern Virginia technician concentration secures hyperscale precision cooling contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with HVAC contractor operations managers, OEM product strategy directors, distributor procurement leads, and commercial building facilities engineers with secondary validation against DOE appliance standard filings, EPA refrigerant phase-down schedules, and SEC 10-K disclosures from listed equipment manufacturers. Bottom-up equipment shipment modeling and top-down construction spending allocation triangulated volume estimates.
Segment-weighting approaches applied product type, technology tier, end-use vertical, and installation modality dimensions across the analysis window. CAGRs derived from equipment replacement cycle compression, efficiency regulation escalations, and end-use demand elasticity modeling. Forecast inputs incorporated Inflation Reduction Act incentive uptake curves and data center cooling load intensity projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under refrigerant supply disruption or copper price spike scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC Louvers Market
HVAC Equipment
Europe Heat Exchanger Market
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
Warming Cabinet Market
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
Middle-East and Africa Compressor Market
HVAC Equipment
Hydronic Radiators Market
HVAC Equipment
Italy HVAC Market
HVAC Equipment
Variable Air Volume Box Market
HVAC Equipment
ASEAN Heat Exchanger Market
HVAC Equipment
Europe Commercial HVAC Market
HVAC Equipment
Canada Commercial HVAC Market
HVAC Equipment
Europe Heat Pump Market
HVAC Equipment
Europe HVAC Equipment Market
HVAC Equipment
Global Modular Chillers Market
HVAC Equipment
Recirculating Chillers Market