
 Global Conveyor System Market | 2026-2036
Global Conveyor System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Conveyor System Market Analysis
The capital-intensity divergence between conveyor system specialists and diversified industrial conglomerates is reorganizing competitive tiers. Daifuku Co., Ltd. leverages its deep integration with semiconductor and automotive cleanroom logistics to command premium positioning in precision material handling. Continental AG anchors its conveyor belt division through captive polymer compounding and in-house rubber formulation, securing supply continuity for mining and bulk goods applications. Siemens AG competes by embedding its conveyor controls within broader factory automation architectures, reducing standalone system margins while expanding attach rates.
A conveyor system comprises motorized or gravity-driven mechanisms—belt, roller, chain, or screw configurations—engineered to transport bulk materials, unit loads, or packaged goods across fixed or adjustable paths, with throughput capacities typically rated in tons per hour or units per minute. These systems serve as the physical backbone of manufacturing flow lines, distribution sortation, and interfacility material transfer, replacing forklift-dependent workflows with continuous, directional movement. Belt conveyor installations dominate installed base value due to their versatility across bulk and unit-load environments, though IoT-enabled segments are capturing disproportionate growth as predictive maintenance contracts and throughput analytics become standard procurement criteria. Roller conveyor systems remain structurally mature in warehousing applications, where margin pools have shifted from hardware sales toward retrofit automation kits and controls integration.
The EU Machinery Directive, ISO 5048 for bulk handling safety, and OSHA workplace standards collectively shape conveyor system design mandates, forcing manufacturers to embed emergency stop protocols, guarding systems, and noise reduction into base configurations rather than optional accessories. The EU AI Act and emerging MEE emissions guidelines in China are extending compliance burdens into software-driven sortation and energy-intensive pneumatic subsystems. Stakeholders must weigh capital deployment timing against the accelerating regulatory cost of retrofitting legacy installations with connected safety and emissions controls.
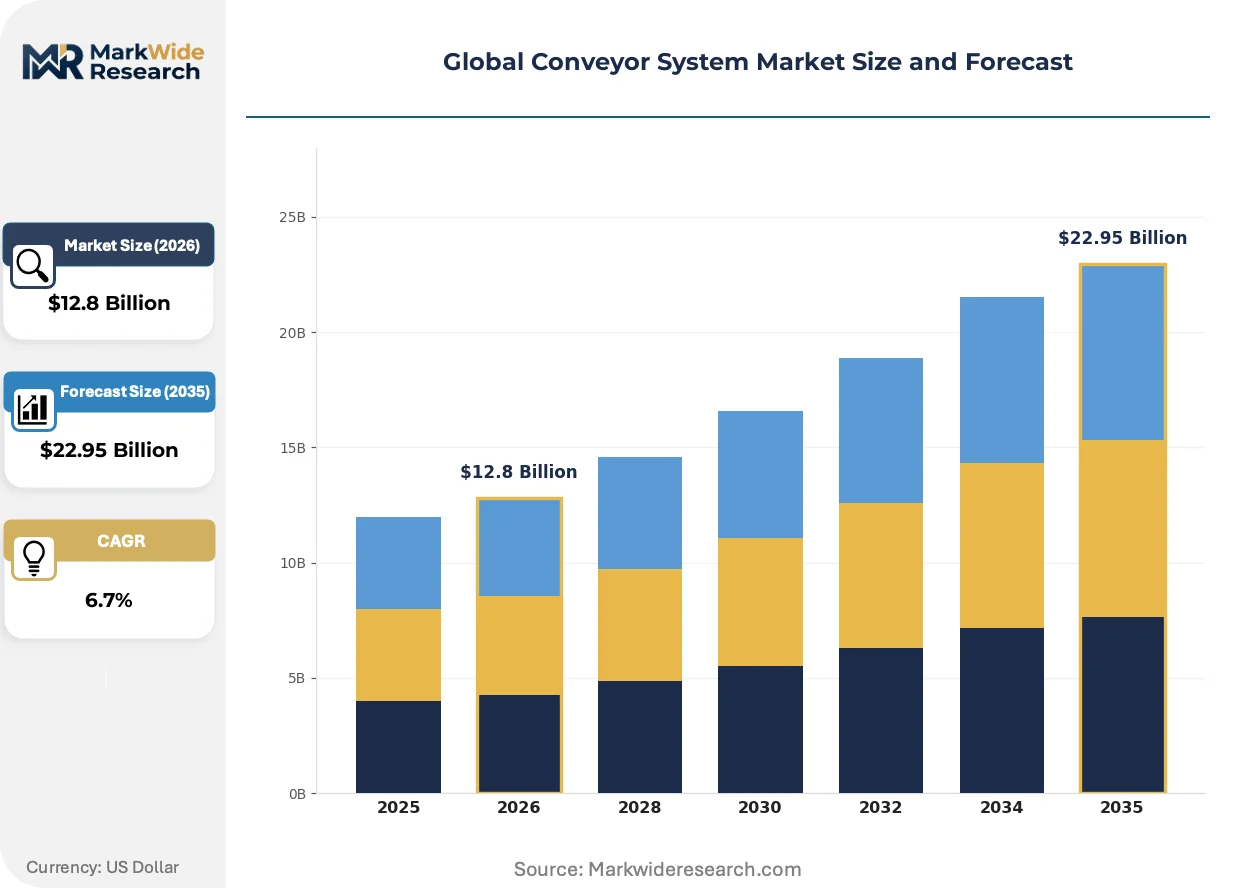
Market Dynamics
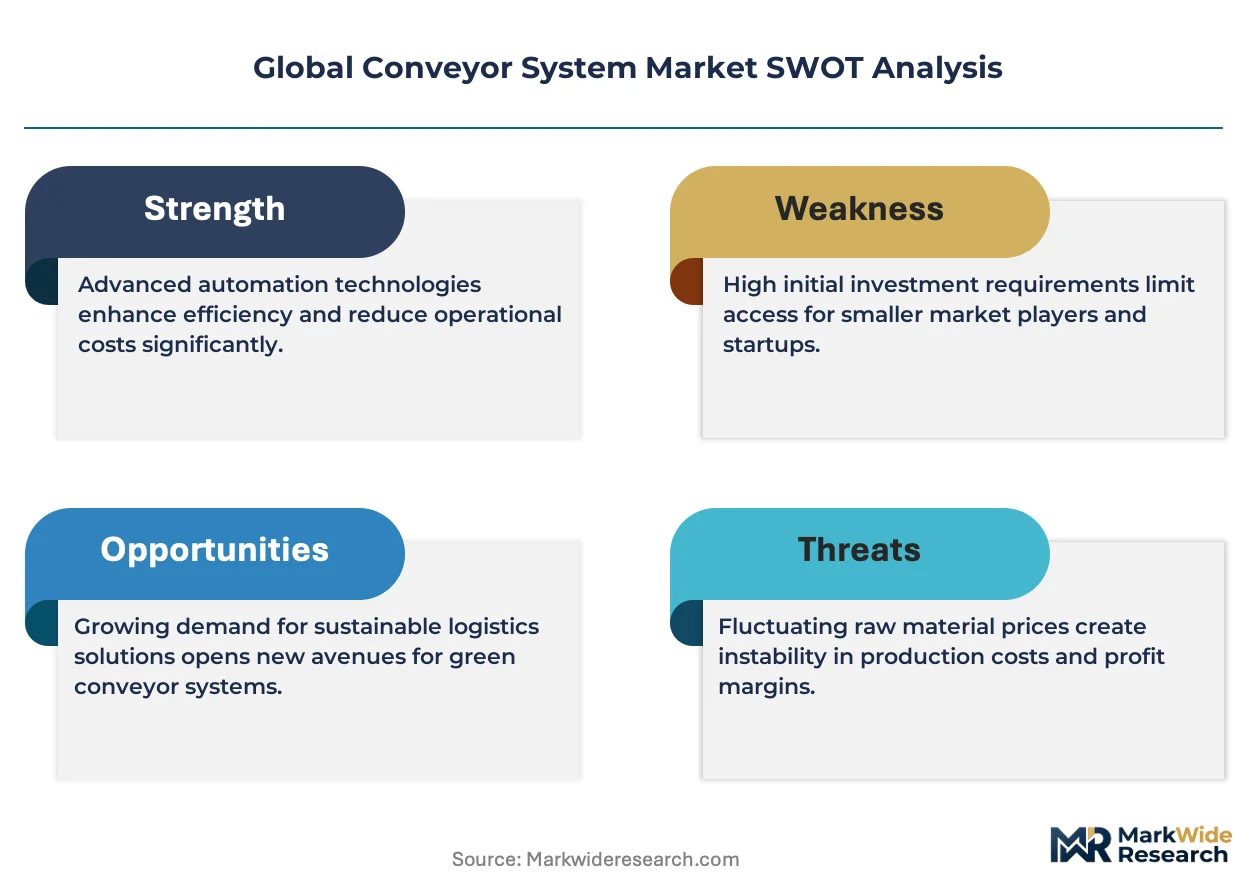
The EU Machinery Directive's 2023 update mandating integrated safety-by-design is forcing conveyor manufacturers to absorb sensor and guarding costs into base system pricing, compressing hardware margins while expanding service attach opportunities.
Growth Catalysts
- E-commerce fulfillment automation:Third-party logistics providers in Germany's Ruhr industrial corridor are deploying high-speed sortation systems to meet same-day delivery service-level agreements.
- REACH polymer compliance:EU rubber belt manufacturers are reformulating compounds to eliminate restricted phthalates, creating replacement demand across installed mining and bulk handling bases.
- Semiconductor cleanroom logistics:Wafer fabrication facilities require ISO Class 1-3 compatible conveyor modules with ionizing static control and stainless steel construction.
Market Restraints
- Steel price volatility:Roller conveyor frames and chain assemblies face input cost swings tied to Chinese HRC export quotas and EU carbon border adjustment mechanisms.
- German automotive supplier concentration:OEM conveyor procurement decisions cluster around Stuttgart and Wolfsburg, creating pricing pressure through buyer power consolidation.
- Pneumatic subsystem energy intensity:Compressed air-driven diverters and pushers face substitution by electric linear actuators under factory decarbonization mandates.
Strategic Opportunities
- India warehouse modernization:The country's PLI scheme for logistics infrastructure is attracting foreign system integrators to Mumbai-Pune and Delhi-NCR distribution corridors.
- Predictive maintenance convergence:Vibration sensors and edge analytics are merging with conveyor controls to enable condition-based service contracts.
- EU AI Act compliance services:Automated sortation software requiring algorithmic transparency documentation creates consulting revenue streams for controls vendors.
Industry Challenges
- Mechatronics skill scarcity:System integrators struggle to recruit technicians fluent in both mechanical belt tensioning and PLC programming.
- Legacy controls retrofit complexity:Brownfield installations with 1990s-era relay logic require custom gateway hardware to interface with IoT platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Conveyor System Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belt Conveyor, Roller Conveyor, Chain Conveyor, Screw Conveyor End User: Manufacturing, Warehousing, Food & Beverage, Pharmaceuticals Technology: Automated, Semi-automated, Manual, IoT-enabled Installation: Onsite, Modular, Integrated, Portable |
| Companies Covered | Daifuku Co., Ltd., Continental AG, Siemens AG, KION Group, Honeywell Intelligrated, Fives Group, Interroll Holding AG, Beumer Group, Dürr Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Conveyor System Market Emerging Trajectories
Modular conveyor architectures are displacing fixed-path installations as facilities prioritize reconfigurable production lines and seasonal throughput adjustments without capital-intensive reconstruction.
Magnetic levitation track systems are displacing conventional belt and roller configurations in cleanroom and high-precision assembly environments. Pharmaceutical manufacturers in Switzerland and medical device producers in Massachusetts are piloting contactless transport to eliminate particulate generation from mechanical friction. This displacement is compressing maintenance intervals from quarterly to annual while enabling ±0.1mm positioning accuracy for automated component placement.
The EU AI Act's risk classification framework for automated decision-making systems is imposing documentation burdens on sortation software vendors. Conveyor controls incorporating machine learning for package routing must now maintain algorithmic audit trails and human oversight protocols. German postal operators and Dutch e-commerce hubs are front-loading compliance costs into 2024-2025 procurement cycles ahead of enforcement deadlines.
Buying organizations are consolidating vendor relationships to reduce integration complexity across multi-site warehouse networks. Retail fulfillment operators in France and automotive suppliers in Mexico now specify single-source responsibility for mechanical, controls, and software subsystems. This concentration favors turnkey providers with in-house engineering capabilities over specialized component vendors.
Global Conveyor System Market Segmentation
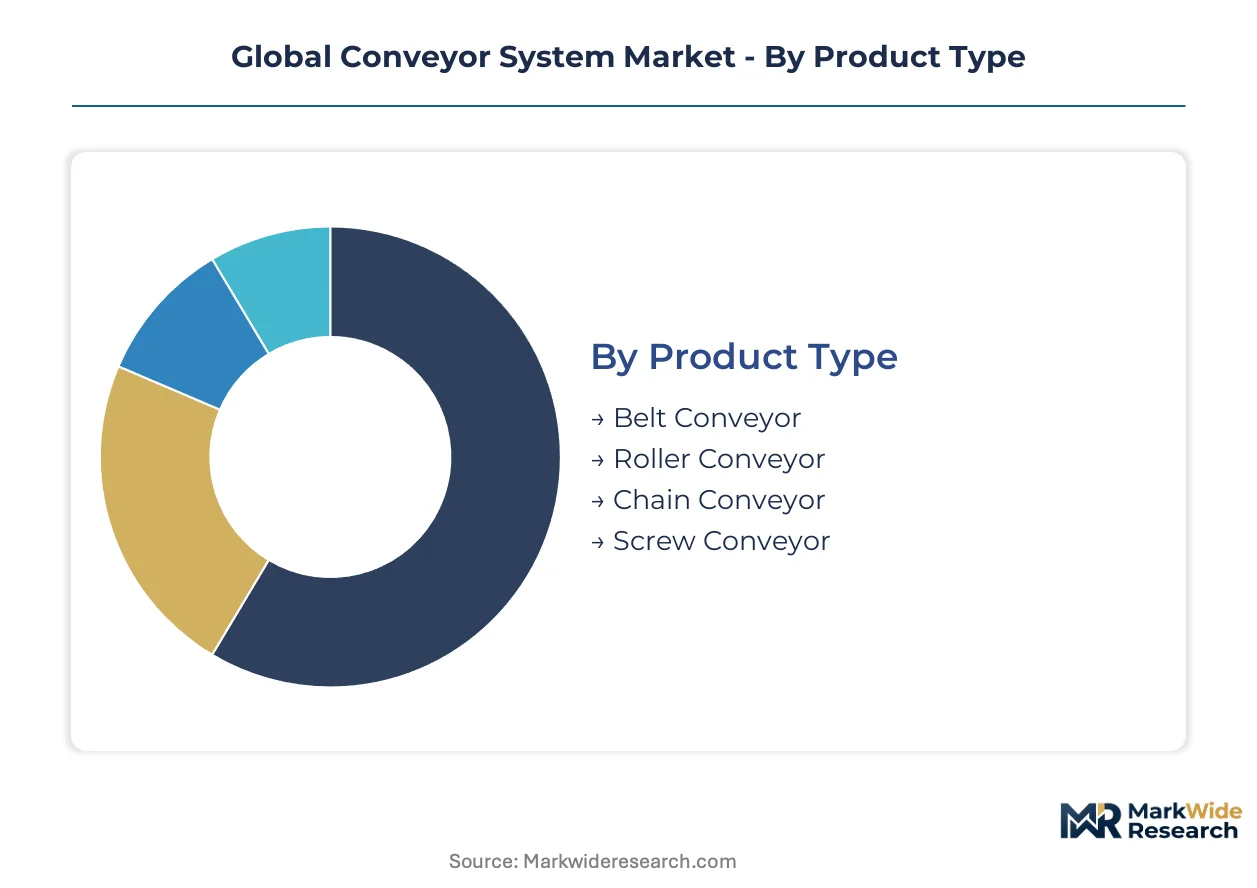
Conveyor system procurement increasingly hinges on matching specific regulatory burdens to segment capabilities. Buyers now segment their supplier base not by hardware specifications alone, but by which segments can absorb compliance costs without margin collapse.
Product Type:
REACH polymer compliance and ISO 5048 safety mandates create divergent cost structures across mechanical configurations. Belt systems face compound reformulation expenses; roller systems confront guarding and sensor integration requirements.
- Belt Conveyor:Constructed from multi-ply rubber or polymer composites with tensile ratings typically spanning 315-2000 N/mm. Mining operations in Germany's Ruhr Valley and bulk grain handlers in Ukraine's Black Sea corridor drive replacement cycles as REACH phthalate restrictions force compound upgrades.
- Roller Conveyor:Gravity or motorized roller arrays with zinc-plated or stainless steel construction, rated for unit loads from 50kg to 2,000kg per linear meter. E-commerce fulfillment centers in France's Île-de-France region specify these for carton handling under EU Machinery Directive emergency-stop mandates.
- Chain Conveyor:Engineered steel or plastic link chains for palletized loads and heavy automotive components. Assembly plants in Stuttgart and Wolfsburg specify these for powertrain module transport.
- Screw Conveyor:Helical flighting within enclosed troughs for powder and granular bulk materials. Cement and chemical processors in India's Gujarat state deploy these for dust-controlled material transfer.
Belt conveyor handles the majority of throughput; IoT-enabled retrofits of legacy belt installations are expanding most quickly on share.
End User:
Customer procurement sophistication varies sharply by vertical, with automotive and pharmaceutical buyers commanding engineering resources that warehousing operators cannot replicate internally.
- Manufacturing:Automotive OEMs and tier suppliers in Mexico's Bajío region specify integrated conveyor-robot cells for just-in-sequence assembly. Semiconductor fabs in South Korea's Gyeonggi Province demand ISO Class 1-3 cleanroom compatibility with ionizing static control.
- Warehousing:Third-party logistics providers operating multi-tenant distribution centers. Operators in the Netherlands' Randstad logistics corridor prioritize modular reconfiguration for seasonal volume swings.
- Food & Beverage:Washdown-rated stainless steel construction with FDA-compliant belting materials. Dairy processors in Wisconsin and Wisconsin's Fox Valley specify these for HACCP-aligned material flow.
- Pharmaceuticals:Containment and serialization tracking for batch integrity. Swiss manufacturers in Basel's pharmaceutical cluster pilot magnetic levitation conveyors to eliminate particulate generation.
Manufacturing commands the largest capital deployment; pharmaceutical applications are climbing the fastest as serialization mandates expand.
Technology:
Control architecture determines service revenue potential and regulatory exposure under emerging algorithmic transparency requirements.
- Automated:PLC-controlled sortation and routing with machine vision package identification. German postal operators deploy these for high-speed letter and parcel processing under EU AI Act documentation requirements.
- Semi-automated:Operator-staffed induction stations with automated downstream sortation. Mid-market distributors in Brazil's São Paulo state favor these for capital-constrained automation roadmaps.
- Manual:Gravity or hand-push configurations for low-throughput operations. Small-batch manufacturers in Italy's Emilia-Romagna region retain these for flexibility in artisanal production.
- IoT-enabled:Edge-deployed vibration sensors and cloud-connected predictive analytics. Mining operators in Western Australia's Pilbara region subscribe to condition-based maintenance contracts for remote bulk handling systems.
Automated systems move the highest volume; IoT-enabled retrofits of brownfield installations are gaining share fastest.
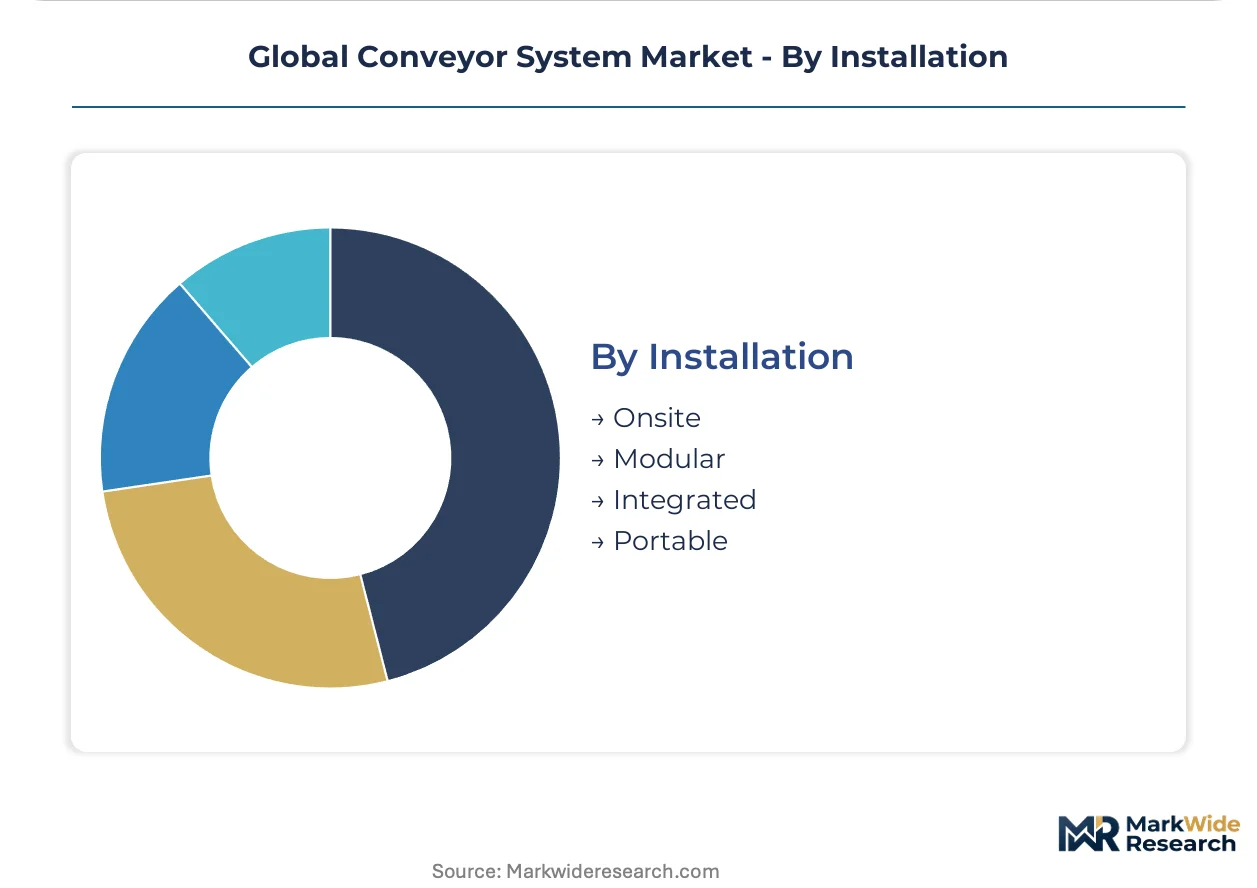
Installation:
Facility lifecycle strategy dictates installation mode, with leased warehouses and owned manufacturing plants diverging sharply on capital recovery horizons.
- Onsite:Permanent structural steel and concrete-anchored systems for 15-20 year asset lives. Steel mills in China's Hebei province specify these for continuous casting lines.
- Modular:Reconfigurable aluminum framing with plug-and-play drive units. Seasonal retail fulfillment operations in the United Kingdom's Midlands deploy these for peak-period capacity expansion.
- Integrated:Conveyor subsystems embedded within broader factory automation architectures. Siemens and Rockwell Automation specify these for automotive greenfield plants.
- Portable:Castor-mounted or skid-based units for temporary material flow. Construction material suppliers in the United Arab Emirates' Dubai logistics corridor deploy these for project-site distribution.
Onsite installations anchor the installed base; modular configurations are expanding most quickly as facility reconfiguration cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's industrial corridor while procurement leverage shifts toward India's emerging logistics hubs. The EU Machinery Directive's safety-by-design mandates inflate base system costs across European manufacturing clusters. Meanwhile, India's PLI scheme for logistics infrastructure attracts foreign system integrators to Mumbai-Pune and Delhi-NCR distribution corridors with capital subsidy offsets.
Germany
Automotive OEMs and tier suppliers in Stuttgart and Wolfsburg drive conveyor procurement for just-in-sequence powertrain assembly. The EU Machinery Directive's 2023 update forces sensor and guarding costs into base pricing, compressing hardware margins. Ruhr Valley mining operations and bulk grain handlers trigger replacement cycles as REACH phthalate restrictions mandate compound upgrades.
United States
Dairy processors in Wisconsin's Fox Valley specify washdown-rated stainless steel conveyors for HACCP-aligned material flow. OSHA workplace standards shape emergency stop protocol integration into base configurations. Pharmaceutical manufacturers in Massachusetts pilot magnetic levitation track systems to eliminate particulate generation from mechanical friction.
China
Steel mills in Hebei province specify permanent structural steel conveyors for continuous casting lines with 15-20 year asset lives. MEE emissions guidelines extend compliance burdens into energy-intensive pneumatic subsystems. Semiconductor fabs in Gyeonggi Province—serving Chinese supply chains—demand ISO Class 1-3 cleanroom compatibility with ionizing static control.
India
Cement and chemical processors in Gujarat deploy screw conveyors for dust-controlled material transfer. The PLI scheme for logistics infrastructure attracts foreign system integrators to Mumbai-Pune and Delhi-NCR corridors. Third-party logistics providers modernize warehouse networks to meet e-commerce fulfillment service-level agreements.
Switzerland
Pharmaceutical manufacturers in Basel's cluster pilot contactless magnetic levitation transport for automated component placement. Swissmedic and EU MDR alignment impose serialization tracking requirements for batch integrity. Medical device producers specify ±0.1mm positioning accuracy for high-precision assembly environments.
Global Conveyor System Market Vendor Landscape
Concentration sits with diversified industrial conglomerates that anchor conveyor divisions within broader factory automation portfolios. The vendor base stratifies across three tiers: precision material handling specialists, polymer-compounding belt manufacturers, and controls-integrated system integrators. Dominant competitive moves include M&A to absorb sensor technology capabilities and strategic partnerships to secure IoT platform integration.
Within the diversified industrial tier, Siemens AG and Continental AG exemplify distinct positioning archetypes. Siemens embeds conveyor controls within broader factory automation architectures, reducing standalone system margins while expanding attach rates for software and services. Continental anchors its conveyor belt division through captive polymer compounding and in-house rubber formulation, securing supply continuity for mining and bulk goods applications. Daifuku Co., Ltd. occupies a precision-specialist position, leveraging deep integration with semiconductor and automotive cleanroom logistics to command premium positioning in contamination-sensitive environments.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| Continental AG |
| Siemens AG |
| KION Group |
| Honeywell Intelligrated |
| Fives Group |
| Interroll Holding AG |
| Beumer Group |
| Dürr Group |
| Others |
Supply Flow & Price Mechanics
Fourteen-week lead times for German-engineered sensor modules concentrate pricing power with Stuttgart and Wolfsburg system integrators while compressing margins for tier-two belt manufacturers dependent on Asian polymer feedstock. This inventory-to-pricing linkage tightens whenever EU Machinery Directive compliance costs absorb into base configurations rather than line-item surcharges.
Pricing Analysis
The customization-premium spread separates configured-to-order cleanroom conveyors from standard roller configurations by a factor reflecting ISO Class 1-3 certification tier and ionizing static control integration. Project-based pricing dominates precision material handling, while commodity belt systems transact on per-meter spot contracts indexed to rubber compound formulations. Price differentiation hinges on REACH polymer compliance status and after-sales predictive maintenance bundling. Pricing pressure stems from steel frame input cost volatility tied to Chinese HRC export quotas, with third-party logistics providers exhibiting highest price sensitivity and semiconductor fabs showing lowest.
Supply Chain Analysis
Inbound logistics costs from Shanghai to Rotterdam surged during container availability crunches, forcing German automotive suppliers to absorb freight premiums or switch to air-cargo for critical PLC components. Supply concentrates in Germany for precision controls, China for steel frames and polymer compounding, and Japan for high-torque drive units. Raw material dependencies include natural rubber from Southeast Asia, specialty steel from Chinese mills, and sensor electronics from South Korean fabs. Single-source vulnerability sits with ionizing static control modules produced by a concentrated Swiss-German supplier cluster. Distribution runs through system integrator-direct channels for large automotive OEMs and distributor networks for mid-market warehousing operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic transparency mandates are disrupting competitive positioning by forcing documentation investments that favor capital-rich controls vendors over specialized mechanical suppliers.
For Market Incumbents: Fortify sensor technology capabilities through selective acquisition of vibration analytics specialists before predictive maintenance contracts become table stakes. Deepen backward integration into polymer compounding to offset REACH-driven compound reformulation costs. Threat substitution by magnetic levitation track systems in pharmaceutical cleanrooms demands stainless steel construction expertise as defensive moat. For New Entrants and Emerging Players: Anchor in India's PLI-subsidized logistics corridors where foreign system integrators face lower capital barriers and local mechatronics talent scarcity creates partnership opportunities. Target cement and chemical screw conveyor retrofits in Gujarat's dust-controlled material transfer segment. Go-to-market through condition-based maintenance subscriptions rather than hardware margin capture. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because conveyor controls vendors with embedded machine learning routing capabilities will command premium attach rates as algorithmic audit trail requirements mature. Acquisition target archetype: mid-cap IoT platform specialists with edge analytics IP and existing mining sector deployments. Signal to watch is German postal procurement cycles front-loading EU AI Act compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Technology Acquisition | Absorbs predictive maintenance capabilities before service contracts standardize across mining and automotive verticals. |
| Backward Integration into Polymer Compounding | Secures REACH-compliant rubber formulation continuity for bulk handling belt replacement cycles. |
| Modular Architecture Platform Launch | Captures seasonal reconfiguration demand from Netherlands Randstad logistics corridor operators. |
| Cleanroom Certification Investment | Unlocks ISO Class 1-3 semiconductor fab procurement in South Korea's Gyeonggi Province. |
| Joint Venture in Indian PLI Corridors | Accesses Mumbai-Pune capital subsidies while mitigating mechatronics skill scarcity through local workforce development. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EU Machinery Directive implementation guidance, ISO 5048 bulk handling safety standards, and customs trade data for rubber and steel inputs. Primary interviews engaged system integrator engineering directors, automotive OEM procurement leads, third-party logistics warehouse operations managers, and aftermarket service heads at mining bulk handling operators. Secondary validation drew from SEC filings of diversified industrial conglomerates, ECHA REACH substance restriction updates, and steel mill production disclosures. Bottom-up project pipeline aggregation triangulates against top-down industrial automation capex surveys.
Segmentation dimensions modeled span product type configuration, end-use vertical sophistication, control technology architecture, and installation mode lifecycle strategy across the projection horizon. CAGRs derive from installed base replacement cycle analysis and greenfield automation penetration curves. Industry-specific forecast inputs include semiconductor fab construction timelines and e-commerce fulfillment service-level agreement tightening rates.
Decision-makers should treat outputs as directional under sustained EU regulatory enforcement and stable Chinese steel export policy; material deviation would warrant model refresh. Specific risk factors include MEE emissions guideline expansion into pneumatic subsystems and German automotive supplier consolidation shifting procurement leverage. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Electric Single Beam Crane Market
Material Handling Equipment
Crushing Screening Equipment Market
Material Handling Equipment
Gravity Conveyor Market
Material Handling Equipment
Construction Lifts Market
Material Handling Equipment
Container Handling Equipment Market
Material Handling Equipment
Drive-In Pallet Racking Market
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Dynamic Compactor Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Loading Platform Canopies Market
Material Handling Equipment
Autonomous Material Handling Equipment Market
Material Handling Equipment
Industrial Parts Feeders Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Fluid Conveyance Systems Market
Material Handling Equipment
Material Handling Equipment Tires Market