
 Hooklifts Market | 2026-2036
Hooklifts Market Size, Share, and Industry Trends Forecast 2026-2036
Hooklifts Market Analytics
Aftermarket service revenue is reshaping margin distribution across the hooklifts value chain, pulling profitability away from pure equipment sales toward lifecycle maintenance contracts. Palfinger AG leverages its dense European service network to capture recurring revenue from fleet operators. Hiab AB anchors its competitive stance through deep specialization in lightweight aluminum hooklift designs that reduce chassis payload penalties. Hyva Global B.V. competes aggressively in emerging markets with standardized hydraulic platforms that simplify local assembly requirements.
A hooklift is a truck-mounted hydraulic mechanism that engages with demountable containers via a front hook and rear roller system, enabling single-operator loading and unloading of swap bodies within 60-90 seconds. The equipment eliminates dedicated vehicle downtime by allowing one chassis to cycle through multiple container types during a single shift. Dual axle configurations currently dominate municipal procurement specifications due to their balance of payload capacity and maneuverability in constrained urban environments. Electric technology installations are expanding fastest among logistics end users operating in European low-emission zones, though hydraulic systems retain overwhelming share in construction and waste management applications where power density requirements remain uncompromised.
EU Green Deal emissions standards and REACH material compliance obligations shape product design priorities across manufacturers serving European markets. Germany's KBA enforces strict vehicle modification approval protocols that create certification barriers for non-EU equipment suppliers. France's ANSM-aligned technical inspection regimes and the United Kingdom's post-Brexit Construction Products Regulation transitions add overlapping compliance layers. Stakeholders must monitor the divergence between EU-wide electrification timelines and member-state enforcement intensities when allocating R&D budgets across product portfolios.
Market Dynamics
The hooklifts market is undergoing structural transformation as electrification pressures collide with hydraulic system inertia across municipal and logistics fleets. EU Green Deal implementation timelines are forcing equipment manufacturers to reconcile power density requirements with zero-emission zone mandates.
Growth Catalysts
- EU Green Deal landfill diversion mandates:Germany, France, and the United Kingdom are expanding hooklift-equipped vehicle orders as waste management fleets scale container cycling capacity to meet tightening diversion targets.
- Urban noise ordinance proliferation:Electric actuation systems are gaining procurement preference in logistics corridors where diesel-powered equipment faces operational hour restrictions.
- Dual-axle chassis standardization:Municipal procurement specifications increasingly specify this configuration for its payload-maneuverability balance in constrained environments.
Market Restraints
- Steel and hydraulic component cost volatility:Input price swings compress margin predictability for manufacturers dependent on commodity-intensive hydraulic platforms.
- German KBA modification approval barriers:Non-EU equipment suppliers face certification friction that extends market entry timelines and raises compliance expenditure.
- Electric power density limitations:Battery-electric systems remain technically uncompetitive for construction applications requiring sustained high-torque container handling.
Strategic Opportunities
- Lifecycle maintenance contract expansion:Aftermarket service revenue streams are pulling profitability away from pure equipment sales toward recurring fleet operator relationships.
- Lightweight aluminum design specialization:Chassis payload penalty reduction through material substitution opens premium positioning in weight-sensitive logistics applications.
- Emerging market standardized platform deployment:Simplified local assembly requirements for hydraulic systems enable cost-competitive entry in regions with developing waste infrastructure.
Industry Challenges
- REACH material compliance timeline compression:Manufacturers must reconcile substance restriction obligations with existing supply chain configurations across European product portfolios.
- Electrification R&D budget allocation divergence:Stakeholders face execution risk when member-state enforcement intensities diverge from EU-wide electrification timelines.
- Post-Brexit Construction Products Regulation transition:United Kingdom technical inspection regime changes create overlapping compliance layers with retained EU obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hooklifts Market |
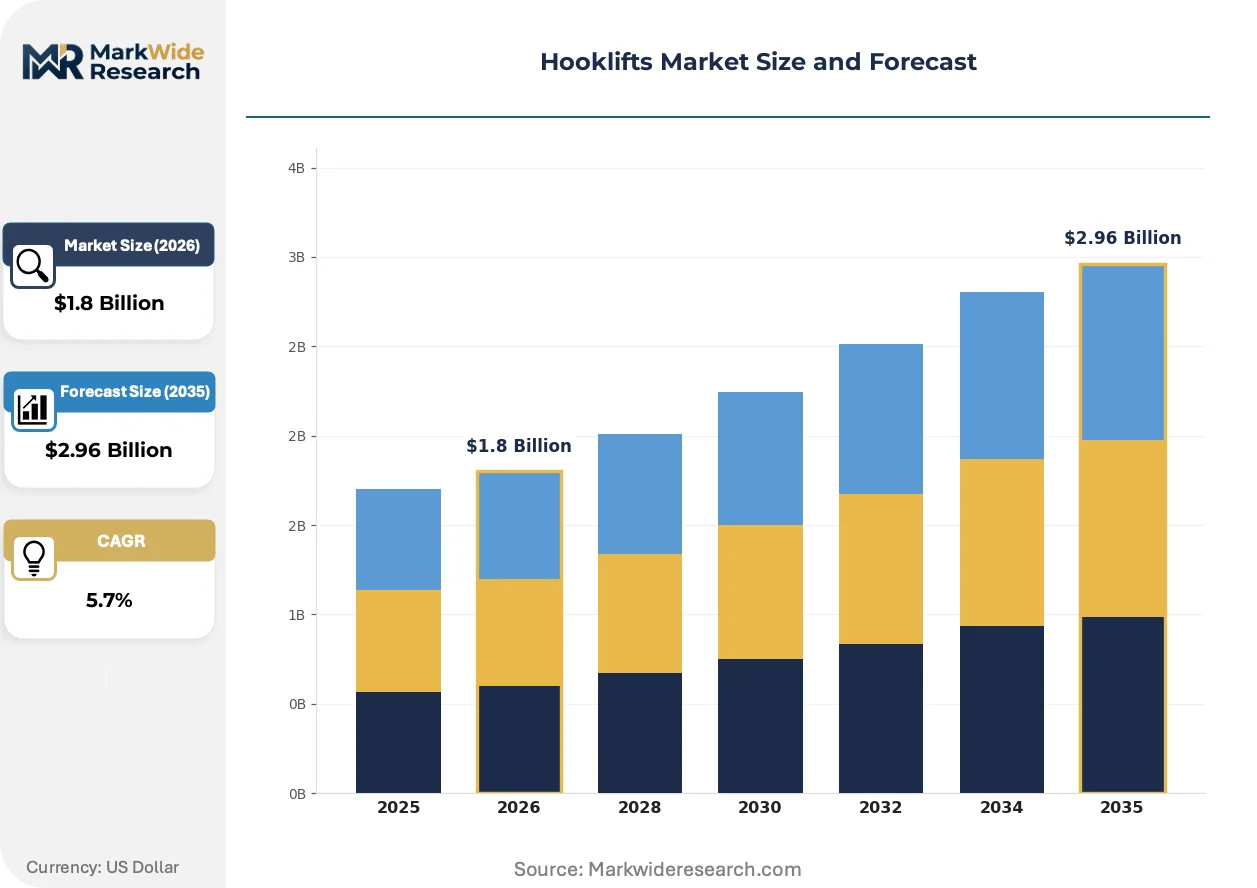
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Axle, Dual Axle, Tri Axle, Multi Axle Technology: Hydraulic, Pneumatic, Electric, Mechanical End User: Construction, Waste Management, Agriculture, Logistics Installation Type: Fixed, Mobile, Portable, Customizable |
| Companies Covered | Palfinger AG, Hiab AB, Hyva Global B.V., Cargotec Corporation, Marrel Corporation, Meiller Group, B.O.B. Sistemi Idraulici S.p.A, VDL Containersystemen BV, Ampliroll Hooklift Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hooklifts Market Evolving Landscape
Equipment functionality is splitting along urban-rural operational boundaries as noise and emissions constraints reshape technical specifications. Manufacturers are engineering divergent product architectures for identical end-use applications based on geographic regulatory intensity.
Electric actuation technology is migrating from experimental urban logistics pilots toward mainstream procurement specifications in European low-emission zones. Logistics end users operating under strict noise ordinances in German and French city centers are specifying battery-electric hooklift systems despite 15-20% payload capacity trade-offs. This technology is migrating from niche municipal demonstration fleets into standard equipment configurations as charging infrastructure density reaches operational viability thresholds.
France's ANSM-aligned technical inspection regimes are tightening equipment modification documentation requirements for commercial vehicle operators. The industrial consequence is elevated compliance expenditure for fleet owners seeking to retrofit existing chassis with hooklift mechanisms. Waste management contractors in France and the United Kingdom are responding by consolidating procurement around factory-integrated hooklift chassis rather than aftermarket installations.
Service contract unbundling is fragmenting traditional equipment-sale economics across European municipal fleets. Fleet operators in Germany and the United Kingdom are separating hooklift hardware procurement from maintenance obligations, creating discrete vendor relationships for each value chain segment. This pattern is most visible in large municipal waste authorities with sufficient scale to negotiate specialized service-level agreements independent of original equipment manufacturers.
Hooklifts Market Segmentation
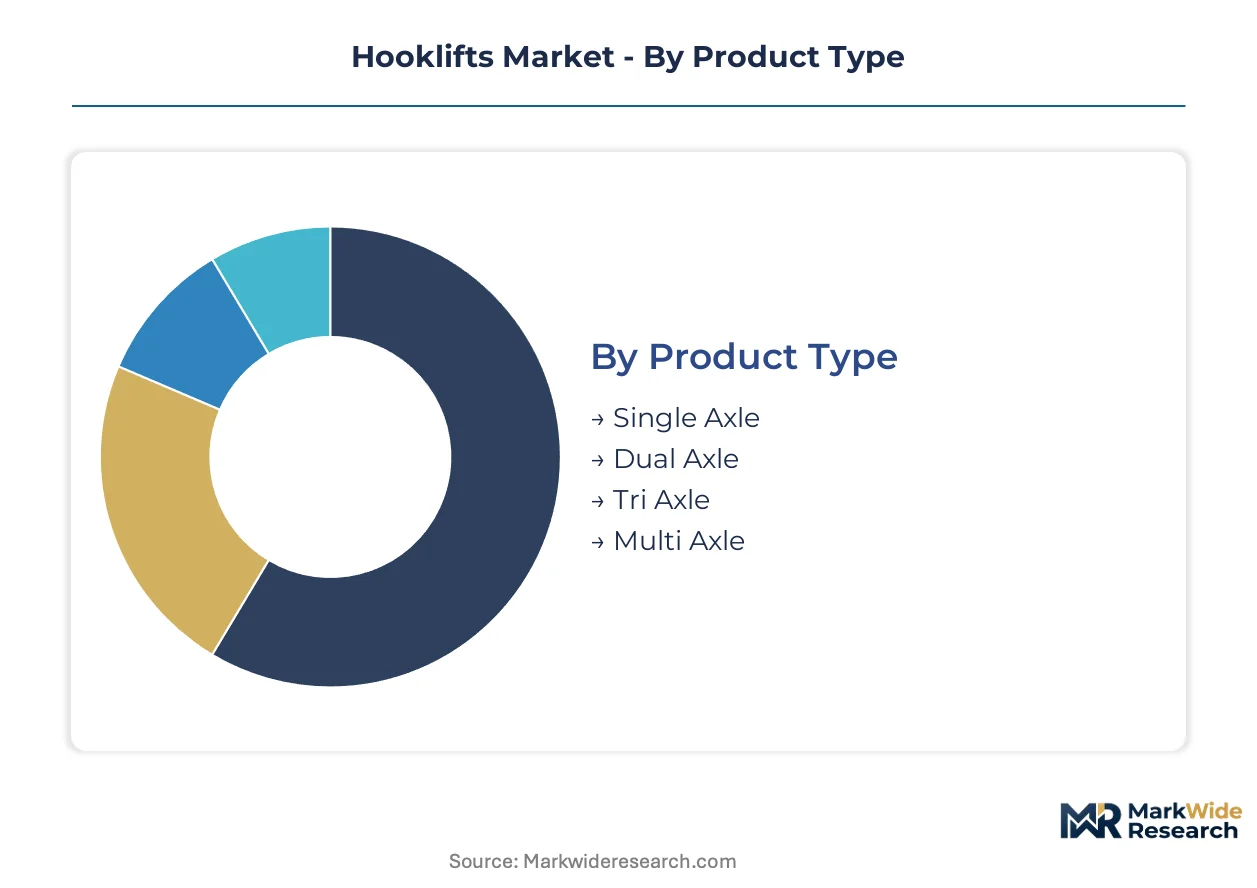
Hooklift configuration choices directly determine aftermarket service intensity, with hydraulic platforms requiring scheduled fluid maintenance and electric systems demanding specialized battery diagnostics. Fleet operators segment procurement by total cost of ownership rather than acquisition price alone.
Product Type:
After-sales service contracts vary sharply by axle configuration, with multi-axle units generating the highest per-unit maintenance revenue due to complex suspension integration requirements.
- Single Axle:Lightweight chassis mounting for restricted urban access routes. Demand concentrates among independent waste contractors in German city centers where maneuverability outweighs payload requirements. Narrow alley compliance drives specification.
- Dual Axle:Municipal procurement standard balancing container capacity with turning radius. French and UK waste authorities specify this configuration for landfill diversion fleet expansion. Payload-maneuverability equilibrium anchors its dominance.
- Tri Axle:Heavy-duty construction applications requiring sustained high-torque handling.
- Multi Axle:Specialized industrial container weights exceeding standard highway limits.
Dual Axle holds the largest share; momentum sits with Single Axle as urban emission zones tighten.
Technology:
Cost tier stratification separates premium electric installations from standardized hydraulic platforms, with procurement budgets determining technology access across fleet categories.
- Hydraulic:Dominant installation type using pressurized fluid systems for container engagement. Construction and waste management applications in Germany and France specify hydraulic power density for uncompromised lifting capacity. Mature service infrastructure supports lifecycle economics.
- Pneumatic:Compressed air actuation for specialized explosion-risk environments.
- Electric:Battery-powered actuation eliminating diesel auxiliary engines. Logistics operators in French and German low-emission zones accept payload trade-offs for compliance access. Charging infrastructure density now supports operational viability.
- Mechanical:Manual or semi-automated systems for developing market cost constraints.
Hydraulic retains volume leadership; electric configurations are climbing the fastest as urban ordinance proliferation accelerates.
End User:
Application-specific duty cycles determine component wear patterns and service interval frequency, with construction fleets generating the most intensive maintenance demands.
- Construction:Severe-duty container handling with abrasive material exposure. German and UK infrastructure projects specify reinforced hook mechanisms for aggregate transport. Component replacement rates exceed other segments.
- Waste Management:Municipal landfill diversion mandates drive fleet scaling across France, Germany, and the United Kingdom. Container cycling frequency maximizes chassis utilization rates.
- Agriculture:Seasonal grain and livestock input handling with intermittent duty cycles.
- Logistics:Urban distribution center container exchange with strict noise ordinance compliance requirements.
Waste Management commands the largest installed base; Logistics represents the steepest expansion trajectory as e-commerce fulfillment density intensifies.
Installation Type:
Customer type segmentation separates factory-integrated chassis purchasers from aftermarket retrofit operators, with compliance documentation requirements favoring original equipment mounting.
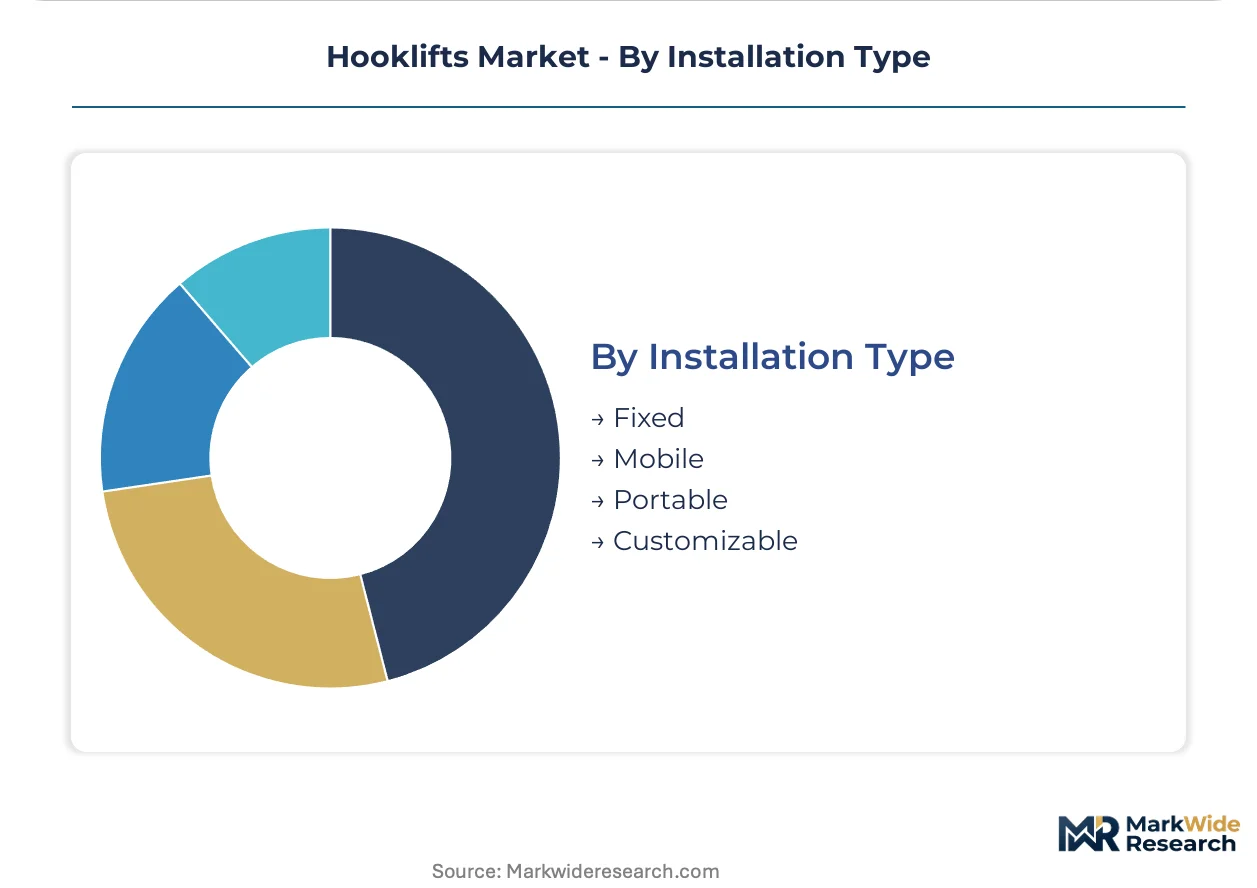
- Fixed:Permanent chassis integration with dedicated container pairing. French ANSM-aligned inspection regimes and UK post-Brexit technical standards elevate factory documentation value. Fleet consolidation favors this configuration.
- Mobile:Transferable mounting between chassis within qualified fleets.
- Portable:Temporary deployment for emergency response or seasonal demand spikes.
- Customizable:Modular adaptation for specialized container geometries or regulatory jurisdictions.
Fixed installation dominates municipal procurement; customizable configurations gain share as cross-border fleet standardization efforts advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Municipal fleet operators in Northern Europe absorb premium pricing for electric configurations, while construction contractors in emerging markets prioritize acquisition cost over lifecycle economics.
Germany
Kraftfahrt-Bundesamt modification approval protocols shape procurement patterns for hooklift chassis retrofits. The EU Green Deal landfill diversion mandates accelerate municipal waste fleet container cycling investments. Bavarian waste authorities in Munich and Nuremberg specify dual-axle configurations for urban landfill diversion routes.
France
ANSM-aligned technical inspection regimes elevate documentation requirements for commercial vehicle modifications. Logistics operators in Paris and Lyon low-emission zones specify electric actuation despite payload trade-offs. Île-de-France municipal fleets consolidate procurement around factory-integrated installations to streamline compliance.
United Kingdom
Post-Brexit Construction Products Regulation transitions create overlapping technical inspection obligations for fleet operators. Scottish and Welsh waste authorities expand hooklift-equipped vehicle orders under devolved landfill diversion targets. Midlands construction contractors drive severe-duty hydraulic platform demand for aggregate transport.
United States
EPA emissions standards and state-level zero-emission vehicle mandates fragment procurement specifications across municipal fleets. Texas and California represent divergent regulatory intensities, with West Coast logistics corridors specifying electric configurations. Midwest waste management contractors prioritize hydraulic power density for uncompromised lifting capacity.
China
MIIT vehicle modification standards and dual carbon goals reshape municipal fleet electrification timelines. Yangtze River Delta waste management authorities in Shanghai and Suzhou pilot electric hooklift configurations for urban container cycling. Pearl River Delta logistics operators balance acquisition costs against emerging low-emission zone restrictions.
Hooklifts Market Competitive Landscape
Capability concentration sits with specialized engineering houses; scale advantage sits with diversified industrial conglomerates. The vendor base organizes around three strategic archetypes: European precision manufacturers with dense service networks, Asian fabricators with standardized platform cost structures, and North American specialists in severe-duty applications. Competitive positioning hardens through M&A activity consolidating regional service capabilities and strategic partnerships securing battery-electric supply chains.
Among European-headquartered specialists, Palfinger AG and Hiab AB occupy positions emphasizing aftermarket service density and lightweight material specialization respectively. Hyva Global B.V. exemplifies the standardized platform archetype for emerging market entry. These three entities represent divergent strategic vectors within a market where regional regulatory fragmentation rewards localized capability investment over pure manufacturing scale.
| Leading Market Players |
|---|
| Palfinger AG |
| Hiab AB |
| Hyva Global B.V. |
| Cargotec Corporation |
| Marrel Corporation |
| Meiller Group |
| B.O.B. Sistemi Idraulici S.p.A |
| VDL Containersystemen BV |
| Ampliroll Hooklift Systems |
| Others |
Value Network & Pricing Analysis
Steel mill concentration in Germany and China anchors input cost volatility for hydraulic cylinder manufacturers, pushing margin pools downstream toward aftermarket service networks and lifecycle contract providers. Fleet operators capture pricing leverage through unbundled procurement separating chassis acquisition from maintenance obligations.
Pricing Analysis
Aftermarket service contracts including scheduled fluid maintenance and battery diagnostics drive lifetime value capture for hooklift vendors. Three-tier pricing structure across premium aluminum designs, standard hydraulic platforms, and economy mechanical systems stratifies procurement access. Cost compression in economy tiers intensifies as Asian fabricators expand standardized platform exports. Municipal waste authorities exhibit lowest price sensitivity due to compliance-driven specification requirements, while independent logistics contractors in emerging markets prioritize acquisition cost over lifecycle economics.
Supply Chain Analysis
Extended payment terms from European OEMs to hydraulic component suppliers have become standard working capital practice across the value chain. Manufacturing concentration rests on Germany, Italy, and China for precision-machined cylinder assemblies, high-pressure hose systems, and electronic control modules. Raw material dependencies draw from Swedish specialty steel, Chinese rare-earth magnets for electric actuation, and German-engineered hydraulic seals. Single-source vulnerability in semiconductor-dependent electric control units creates supply chain risk. Distribution runs through authorized dealer networks for factory-integrated chassis and independent distributors for aftermarket retrofit kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric skip loaders and automated container handling systems pose substitution threats that hooklift incumbents must navigate through service network densification and electrification roadmaps.
For Market Incumbents: Build dense aftermarket service moats through predictive maintenance platform deployment and certified technician networks. Secure battery-electric supply chains via strategic partnerships with charging infrastructure providers. Anchor defensive positioning against automated container handling startups through OEM-exclusive chassis integration agreements. For New Entrants and Emerging Players: Mid-market logistics fleets in Poland and Romania represent the most penetrable entry point for standardized hydraulic platform challengers. Electric retrofit kits for existing diesel chassis in French low-emission zones offer regulatory-arbitrage positioning. Go-to-market execution should leverage direct fleet operator relationships bypassing established dealer networks. For Investors and Strategic Acquirers: Capital is best deployed toward European precision manufacturers with captive service networks and aluminum lightweighting capabilities. Five-to-ten year viability hinges on electrification execution speed versus hydraulic incumbency defense. Monitor KBA certification timeline compression as inflection indicator for non-EU supplier market access.| Strategic Initiative | Industry Significance |
|---|---|
| Service Network Densification | Palfinger AG's European technician coverage creates recurring revenue lock-in against price competition. |
| Aluminum Lightweighting Investment | Hiab AB's chassis payload penalty reduction commands premium positioning in weight-sensitive logistics corridors. |
| Emerging Market Platform Standardization | Hyva Global B.V.'s simplified local assembly requirements enable cost-competitive entry in developing waste infrastructure. |
| Battery-Electric Supply Chain Partnership | Charging infrastructure density thresholds now support operational viability for urban low-emission zone compliance. |
| Factory-Integrated Chassis Consolidation | French ANSM-aligned inspection regimes elevate documentation value for OEM-mounted configurations over aftermarket retrofits. |
Research Methodology
Operator-level perspectives from fleet maintenance directors, municipal procurement officers, OEM platform engineers, and aftermarket service heads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation drawing from KBA modification filings, EU Green Deal implementation trackers, ANSM technical inspection protocols, and customs trade data for hydraulic component flows. Bottom-up unit economics triangulated against top-down market sizing across axle configurations, technology types, and end-use applications.
Scenario-bracketing around EU electrification timeline divergence and REACH compliance compression shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include axle configuration, actuation technology, installation type, end-use application, and regional regulatory intensity cluster. CAGRs derived from equipment replacement cycle analysis, fleet expansion pipelines, and landfill diversion mandate implementation schedules. Industry-specific forecast inputs incorporated charging infrastructure deployment curves and steel price volatility indices.
Macroeconomic conditions sit as an overlay; deviation in construction sector investment cycles and municipal budget allocations would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement intensity and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Material Handling Equipment Tires Market
Material Handling Equipment
Lever Hoist Market
Material Handling Equipment
Rotary Indexer Market
Material Handling Equipment
Push-Back Racking System Market
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Vertical Lifts Market
Material Handling Equipment
Canada Forklift Market
Material Handling Equipment
Conveying Equipment Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Pallet Circulation System Market
Material Handling Equipment
Europe Conveyor Belt Market
Material Handling Equipment
Vibrating Conveyor Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Linear Slides Market
Material Handling Equipment
Mobile Conveyor Market