
 Flex Pack Coatings Market | 2026-2036
Flex Pack Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Flex Pack Coatings Market Foresight
EU REACH regulation is hardening substrate and additive compliance requirements for flexible packaging sold across member states. Amcor plc leverages its integrated film-to-coating manufacturing footprint to pre-certify formulations against evolving substance restrictions. Berry Global Inc. anchors North American supply through captive resin and coating compounding operations that reduce external formulation dependency. Huhtamaki dominates emerging-market food-service packaging with heat-seal coating systems engineered for tropical humidity conditions.
Flex pack coatings are functional polymer layers applied to plastic films, foils, and paper substrates to impart barrier properties, heat sealability, or print receptivity, typically ranging from 0.5 to 5 microns in dry thickness. These coatings enable oxygen transmission rates below 1 cc/m²/day in high-barrier meat and cheese packaging structures. Water-based formulations lead volume in food applications where volatile organic compound limits constrain solvent-based alternatives, while UV curable systems capture premium pharmaceutical blister lidding demand for precise dose protection and rapid line speeds. Roll coating and gravure coating technologies occupy the majority of installed capacity, though slot die coating is displacing legacy methods in transparent barrier oxide deposition.
The EPA enforces National Emission Standards for Hazardous Air Pollutants on coating operations, pushing converters toward water-based and UV curable chemistries. FDA indirect food additive regulations under 21 CFR 175.300 govern migration limits for coatings in direct food contact, requiring extensive extraction testing for new formulations. BIS certification in India mandates coating adhesion and heat-resistance benchmarks for imported flexible packaging materials. Stakeholders must monitor how diverging regional chemical restriction lists reshape formulation portability and capital allocation across coating asset networks.
Market Dynamics
Mono-material packaging mandates across the European Union are compressing multi-layer substrate demand and forcing coating formulators to engineer single-polymer barrier solutions that maintain performance without adhesive lamination.
Growth Catalysts
- EU REACH substance restrictions:Hardening compliance requirements for per- and polyfluoroalkyl substances in food contact materials are accelerating investment in fluorine-free barrier coatings across member states.
- India FMCG expansion:Domestic packaged food consumption is concentrating coating demand in Maharashtra and Gujarat where regional converters are scaling gravure capacity.
- Water-based formulation advances:Polyurethane dispersion chemistry breakthroughs are matching solvent-based oxygen barrier performance at commercial line speeds.
Market Restraints
- Ethylene vinyl alcohol supply concentration:Three Asian resin producers control over 70% of high-barrier raw material supply, exposing formulators to feedstock volatility.
- Aluminum oxide deposition capex intensity:Vacuum metallization and atomic layer deposition equipment requires 18-24 month commissioning timelines that constrain capacity expansion.
- Polyethylene recycling contamination:Multi-material coatings complicate mechanical recycling streams, creating regulatory friction under extended producer responsibility frameworks.
Strategic Opportunities
- Brazil bio-based feedstocks:Underpenetrated coating demand in South America's largest packaged food market offers first-mover positioning for sugarcane-derived polymer suppliers.
- Pharmaceutical cold-chain expansion:Temperature-sensitive biologics distribution is creating specification pull for ultra-low permeability lidding structures.
- Digital printing convergence:Electron beam curing systems paired with inkjet deposition are enabling on-demand coating thickness variation without plate changeover.
Industry Challenges
- Migration testing expertise shortage:FDA 21 CFR 175.300 extraction protocol execution requires specialized analytical chemists that converters struggle to recruit.
- Legacy solvent recovery asset stranding:Water-based and UV coating transitions risk premature write-downs of thermal oxidizer investments at mid-size coating operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flex Pack Coatings Market |
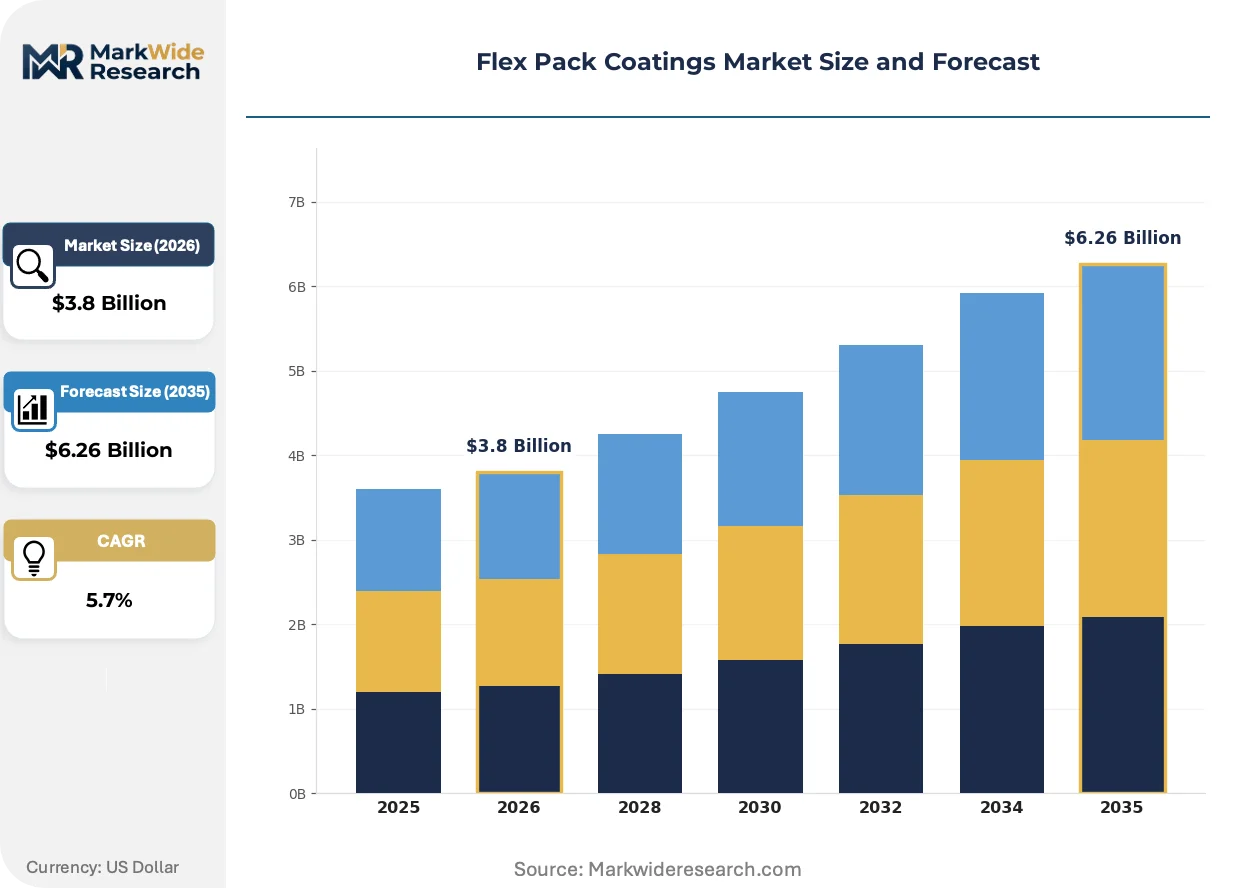
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, UV Curable, Silicone, Epoxy, Acrylic Application: Food Packaging, Pharmaceutical Packaging, Personal Care Packaging, Industrial Packaging, Consumer Electronics Packaging End User: Packaging Manufacturers, Brand Owners, Contract Packers, Coating Suppliers Coating Technology: Roll Coating, Gravure Coating, Slot Die Coating, Curtain Coating, Spray Coating |
| Companies Covered | Amcor plc, Berry Global Inc., Mondi plc, Sealed Air Corp, Uflex Ltd, Sonoco Products Company, Huhtamaki, DuPont Co., Winpak Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flex Pack Coatings Market Shifts & Advancements
Coating functionality is migrating from passive barrier layers toward active and intelligent systems that communicate package integrity, creating new specification categories between commodity converters and specialty chemical suppliers.
Atomic layer deposition of aluminum oxide onto oriented polypropylene films is consolidating transparent barrier supply by replacing metallized PET in snack and confectionery applications. European brand owners are specifying ALD-coated mono-PE structures for recyclability claims. This technology is consolidating high-barrier supply chains around equipment-limited specialist coaters with captive vacuum deposition assets.
REACH Annex XVII restrictions on perfluorinated compounds are forcing reformulation of grease-resistant coatings used in fast-food packaging across Germany, France, and Italy. Paperboard converters are certifying bio-wax and clay-based alternatives against migration limits. The quick-service restaurant segment is absorbing 15-20% cost premiums to maintain compliance with evolving substance restriction lists.
Brand owner direct specification of coating chemistries is compressing converter formulation autonomy. Nestlé and Unilever procurement teams are mandating pre-approved substance lists that narrow supplier qualification pools. This pattern is most visible in Western Europe where retailer sustainability scorecards amplify downstream chemical transparency requirements.
Flex Pack Coatings Market Segmentation
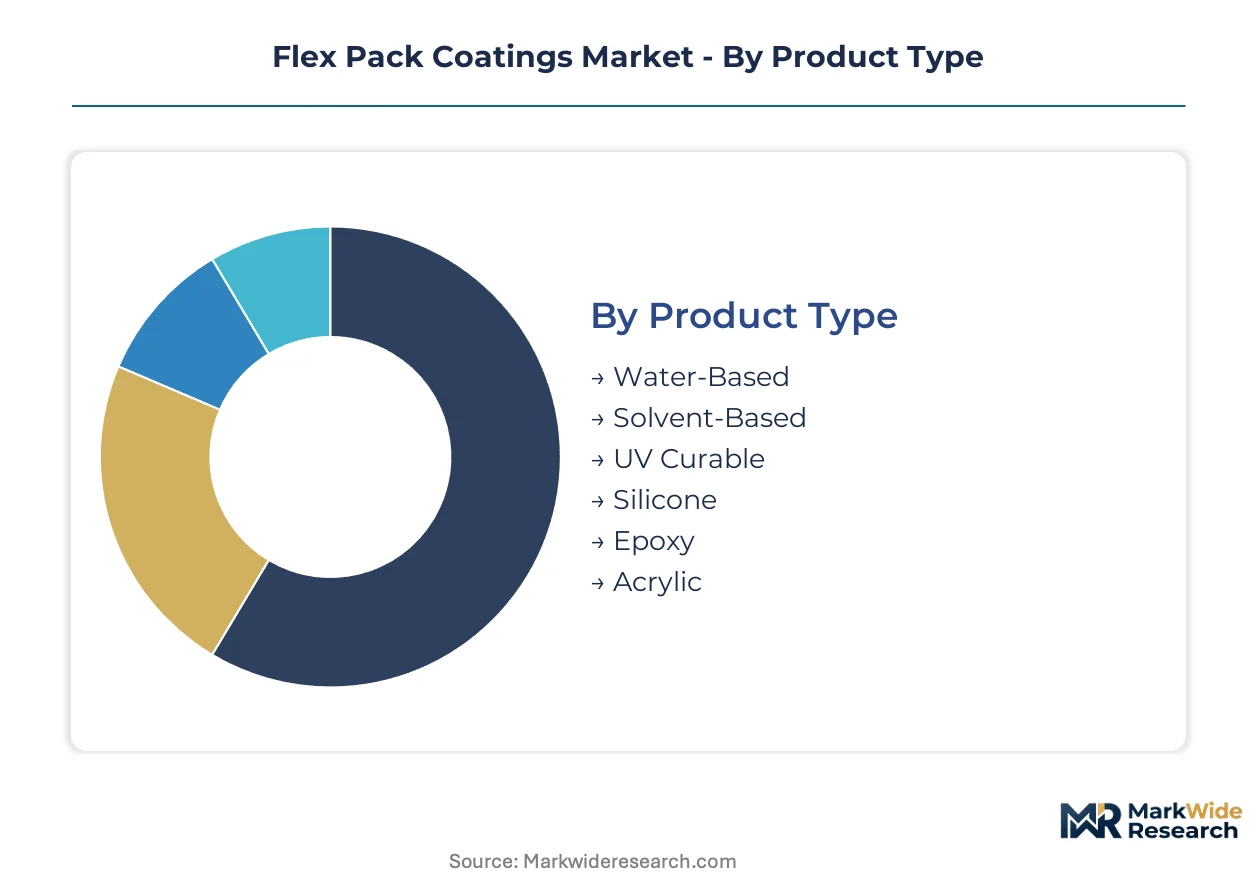
Flex pack coatings segment across formulation chemistry, deposition method, and downstream application, with each axis carrying distinct margin profiles and technical barriers. Procurement teams specify coating categories based on substrate compatibility, regulatory migration limits, and line speed requirements.
Product Type:
Formulation chemistry dictates VOC compliance, barrier performance, and curing energy requirements across coating operations.
- Water-Based:Polyurethane dispersions dominate food packaging specifications where EPA NESHAP limits constrain solvent emissions. Demand concentrates in North American meat and cheese lidding as converters retrofit gravure lines for aqueous chemistry.
- Solvent-Based:High-solids polyurethane and nitrocellulose systems retain share in pharmaceutical blister lidding requiring oxygen transmission rates below 0.5 cc/m²/day. European REACH substance restrictions are compressing formulation flexibility for this category.
- UV Curable:Acrylate oligomer formulations serve premium pharmaceutical applications demanding rapid line speeds and precise thickness control.
- Silicone:Release coatings for pressure-sensitive label stock and adhesive lamination structures.
- Epoxy:High-adhesion primers for metalized film substrates in industrial barrier applications.
- Acrylic:Print receptivity layers and heat-seal coatings for commodity snack packaging.
Water-based formulations lead on scale; UV curable systems lead on momentum as pharmaceutical specifications tighten.
Application:
End-use specifications diverge sharply on migration limits, barrier performance, and aesthetic requirements.
- Food Packaging:Oxygen and moisture barrier coatings for meat, cheese, and snack structures face FDA 21 CFR 175.300 extraction testing protocols. Brand owners in Germany and France are specifying fluorine-free grease-resistant alternatives under REACH Annex XVII.
- Pharmaceutical Packaging:Ultra-low permeability lidding for temperature-sensitive biologics demands atomic layer deposition compatibility. Cold-chain expansion in India and Brazil is pulling specification investment toward tropical-stability coating systems.
- Personal Care Packaging:Aesthetic and tactile coatings for flexible pouches and sachets with premium surface finish requirements.
- Industrial Packaging:Corrosion-resistant and chemical barrier coatings for agricultural and chemical product containment.
- Consumer Electronics Packaging:Anti-static and moisture barrier coatings for sensitive component protection during shipment.
Food packaging commands volume concentration; pharmaceutical packaging shows the steepest expansion trajectory as biologics distribution networks proliferate.
End User:
Customer type determines specification authority, volume scale, and technical service intensity.
- Packaging Manufacturers:Gravure and flexographic converters in Maharashtra and Gujarat are scaling coating capacity to serve domestic FMCG growth. These operators balance formulation cost against line speed and drying energy.
- Brand Owners:Nestlé and Unilever procurement teams are mandating pre-approved substance lists that narrow supplier qualification pools. Direct chemistry specification is compressing converter formulation autonomy.
- Contract Packers:Toll coating operations serving regional food processors with standardized specification requirements.
- Coating Suppliers:Specialty chemical formulators supplying masterbatch and concentrated coating systems to downstream converters.
Packaging manufacturers anchor volume; brand owners are gaining specification control fastest through sustainability scorecard mandates.
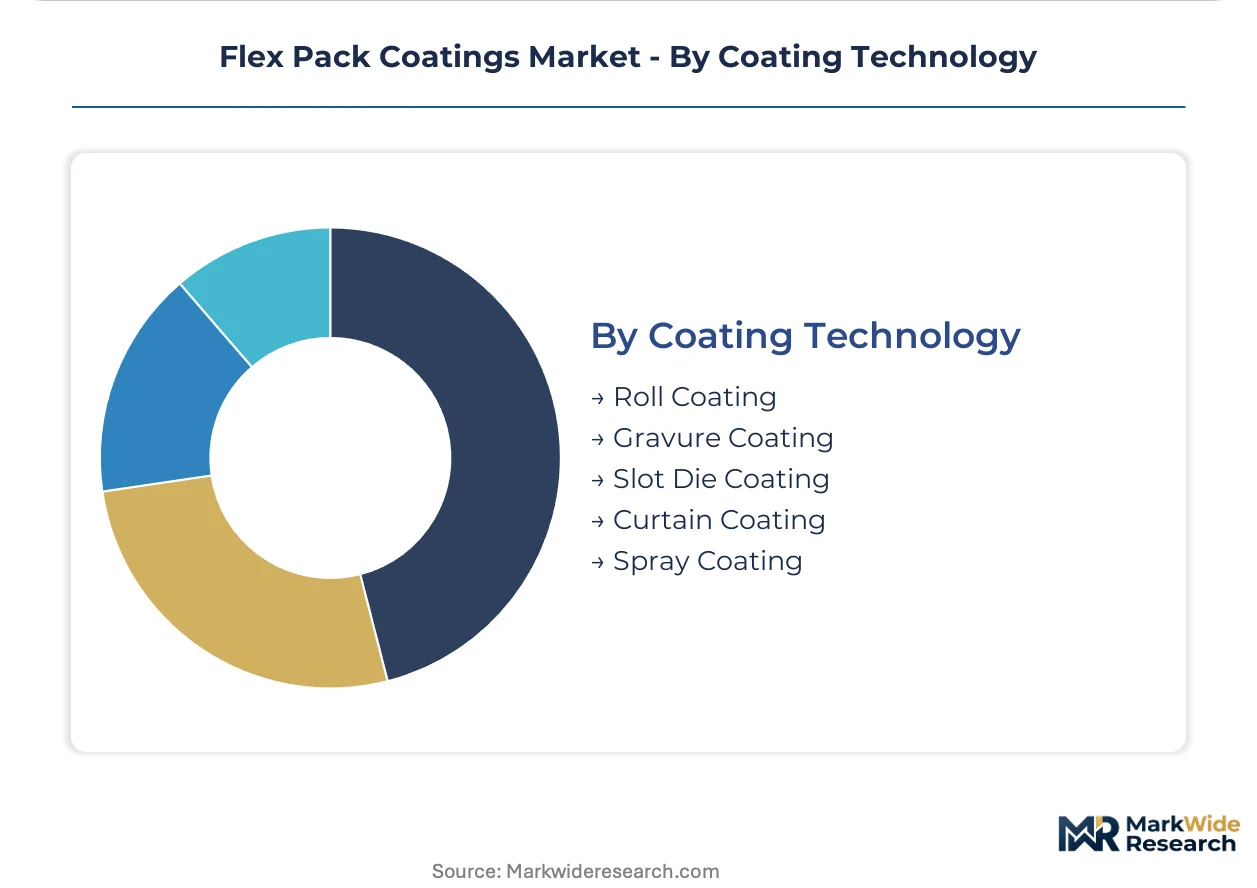
Coating Technology:
Deposition method determines thickness precision, substrate compatibility, and capital intensity.
- Roll Coating:Direct and reverse roll systems occupy the majority of installed flexible packaging capacity. Legacy assets in North American and European converter bases face stranding risk as water-based transitions accelerate.
- Gravure Coating:Engraved cylinder deposition delivers precise thickness control for high-barrier food and pharmaceutical applications. Indian converters in Ahmedabad and Pune are adding gravure coating towers to capture regional snack packaging growth.
- Slot Die Coating:Precision die systems are displacing legacy methods in transparent barrier oxide deposition for mono-material recyclability claims.
- Curtain Coating:High-speed flood coating for continuous web applications with uniform thickness requirements.
- Spray Coating:Selective deposition for patterned or registered coating applications in specialty packaging.
Gravure coating maintains installed base dominance; slot die coating is climbing the fastest as ALD and vacuum deposition integration expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized coating chemists and polymer scientists concentrate in Germany's industrial Rhine corridor, India's Gujarat chemical belt, and the US Gulf Coast petrochemical corridor. These talent clusters anchor formulation development and process engineering for barrier coating systems.
United States
EPA NESHAP enforcement on coating operations drives water-based and UV curable chemistry adoption across meat and cheese packaging converters. FDA 21 CFR 175.300 extraction testing protocols govern migration limits for food-contact coatings. Chicago and Milwaukee host gravure coating operations serving Midwestern protein processors with high-barrier lidding structures.
Germany
REACH Annex XVII restrictions on perfluorinated compounds force grease-resistant coating reformulation for quick-service restaurant packaging. ECHA substance restriction lists compress formulation flexibility for solvent-based systems. Düsseldorf and Hamburg anchor coating R&D clusters where specialty chemical suppliers certify fluorine-free alternatives.
India
FSSAI food safety standards and BIS certification mandates for imported flexible packaging materials tighten coating adhesion requirements. Domestic FMCG consumption concentrates demand in Maharashtra and Gujarat. Ahmedabad and Pune converters scale gravure coating towers to capture regional snack packaging growth from Uflex Ltd expansion.
China
GB standards for food-contact materials and MEE environmental enforcement reshape coating formulation roadmaps. Dual carbon goals accelerate water-based system investment. Yangtze River Delta coating operations supply barrier films for export-oriented electronics and pharmaceutical packaging.
Brazil
ANVISA pharmaceutical packaging regulations and sugarcane-derived polymer feedstock availability create bio-based coating opportunities. Underpenetrated demand in South America's largest packaged food market attracts first-mover positioning. São Paulo state converters evaluate regional barrier coating capacity for tropical humidity conditions.
Flex Pack Coatings Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across coating formulation and deposition equipment. The market structures around integrated film-to-coating manufacturers, captive resin compounders, and specialty chemical formulators. Three archetypes dominate: vertically integrated packaging conglomerates with in-house coating assets, independent coating specialists serving toll markets, and raw material suppliers backward-integrating into formulation. Capacity expansion and strategic partnerships represent the dominant competitive moves as converters seek pre-certified formulations against evolving substance restrictions.
Among integrated packaging conglomerates, Amcor plc exemplifies the film-to-coating manufacturing archetype with pre-certification capabilities against REACH restrictions. Berry Global Inc. occupies the North American captive resin and compounding position that reduces external formulation dependency. Uflex Ltd anchors emerging-market expansion with regional coating capacity scaled to serve Indian FMCG growth. These three represent distinct strategic postures: regulatory pre-certification, supply chain insulation, and geographic demand capture.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Mondi plc |
| Sealed Air Corp |
| Uflex Ltd |
| Sonoco Products Company |
| Huhtamaki |
| DuPont Co. |
| Winpak Ltd |
| Others |
Supply & Pricing Matrix
EU REACH Annex XVII restrictions on perfluorinated compounds gate qualified supply for grease-resistant food packaging coatings, limiting premium-tier pricing access to formulators with certified fluorine-free alternatives and ECHA pre-approval documentation.
Pricing Analysis
Bundled formulation-and-certification services command 15-20% premiums over unbundled coating supply where converters assume regulatory testing burden. Three-tier pricing structure separates REACH-certified barrier systems from standard food-grade formulations and commodity acrylic heat-seal coatings. Price differentiation rests on migration testing documentation depth and line-speed compatibility guarantees. Cost compression in mid-tier solvent-based formulations is intensifying as water-based polyurethane dispersions match performance at commercial speeds.
Supply Chain Analysis
Reverse-logistics flows for solvent recovery and coating waste reclaim are concentrating around German industrial chemical clusters and US Gulf Coast petrochemical corridors. Raw material supply draws from Japanese and South Korean ethylene vinyl alcohol resin producers, German polyurethane dispersion specialists, and Indian acrylic emulsion manufacturers. Single-source vulnerability in high-barrier EVOH feedstock exposes formulators to allocation risk during petrochemical turnaround cycles. Distribution runs through converter direct procurement and specialty chemical distributor networks serving regional gravure operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in flex pack coatings hinges on fluorine-free formulation premiums and water-based system cost-down curves displacing legacy solvent assets.
For Market Incumbents: To counter REACH substance restriction stranding risk, Amcor and Berry Global should accelerate captive bio-based barrier polymer development and pre-certify Indian coating capacity against EU migration limits before domestic competitors qualify. For New Entrants and Emerging Players: The 15-20% price-point gap between premium REACH-certified coatings and economy-grade acrylic systems offers entry through Brazilian sugarcane-derived polymer supply and tropical-stability formulation expertise for Indian cold-chain expansion. For Investors and Strategic Acquirers: Roll-up economics work for specialty coating formulators with captive vacuum deposition assets because ALD equipment scarcity and 18-24 month commissioning timelines create durable moats against commodity competition. Target mid-cap converters with pre-certified REACH portfolios and installed gravure capacity in Maharashtra or Gujarat. Monitor ECHA substance restriction list updates for fluorinated compound scope expansion as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Formulation Certification | ECHA pre-approval unlocks premium pricing in German and French quick-service restaurant packaging. |
| Atomic Layer Deposition Capacity Addition | Captive ALD assets consolidate transparent barrier supply for European mono-material recyclability mandates. |
| Water-Based Polyurethane Dispersion Scale-Up | EPA NESHAP compliance enables North American meat and cheese lidding market share capture. |
| Indian Gravure Coating Tower Expansion | Ahmedabad and Pune capacity positions capture Uflex Ltd-driven regional FMCG growth. |
| Bio-Based Feedstock Integration | Brazilian sugarcane-derived polymers differentiate supply for ANVISA-regulated pharmaceutical cold-chain applications. |
Research Methodology
Coverage spans the United States, Germany, India, China, and Brazil, with primary inputs from each market through interviews with coating formulator R&D directors, gravure converter plant managers, brand owner packaging procurement leads, and specialty chemical distribution channel partners. Secondary validation draws from EPA NESHAP enforcement records, ECHA substance restriction lists, FDA 21 CFR 175.300 guidance documents, and BIS certification registries. Bottom-up coating volume estimates triangulate against top-down flexible packaging demand projections.
Rate-of-change decomposition separates volume growth from value growth across the projection horizon. Segmentation dimensions modeled include formulation chemistry, deposition technology, end-use application, and regional regulatory cluster. CAGRs derive from segment-level growth rate blending weighted by base-year share. Forecast inputs incorporate line-speed compatibility curves for water-based systems and REACH substance restriction implementation timelines.
Caveats apply where ECHA Annex XVII expansion scope, EPA enforcement intensity shifts, or Indian BIS adhesion standard revisions could materially shift the outlook. Practitioners should monitor fluorine-free coating certification queue lengths and ALD equipment order backlogs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
North America Flexible Packaging Market
Flexible Packaging
Flexible Intermediate Bulk Container Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
Spain Flexible Plastic Packaging Market
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
Flexible Film Market
Flexible Packaging
Asia Pacific Single-Use Packaging Market
Flexible Packaging
Canada Flexible Packaging Market
Flexible Packaging
India Flexible Packaging Market
Flexible Packaging
United States Flexible Plastic Packaging Market
Flexible Packaging
Confectionery Flexible Packaging Market
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
Mexico Flexible Plastic Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
Canada Flexible Plastic Packaging Market