
 Morocco Flexible Packaging Market | 2026-2036
Morocco Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Flexible Packaging Market Foresight
Food and beverage export packaging is realigning toward lightweight barrier formats as Moroccan agri-processors target European retail channels. Amcor Group GmbH leverages its regional technical service network to anchor premium laminate supply for seafood and olive oil exporters. Mondi Pap Sac Maghreb SA specializes in kraft-paper flexible hybrids that navigate growing retailer sustainability specifications. Unibag Maghreb competes on short-run customization for mid-tier domestic brands.
Morocco flexible packaging comprises pliable substrates—polyethylene, polypropylene, paper, and aluminium in mono or multilayer constructions—sealed by heat, adhesive, or pressure to contain, protect, and extend shelf life of consumable and industrial goods. Stand-up pouches with reseal fitments dominate value pools as brand owners replace rigid formats for sauces, grains, and personal care liquids. Laminated films sustain margin concentration where oxygen and moisture barrier specifications justify higher unit economics for pharmaceutical and premium food applications. Shrink films occupy mature volume positions in beverage multipacks and pallet unitization with limited pricing flexibility.
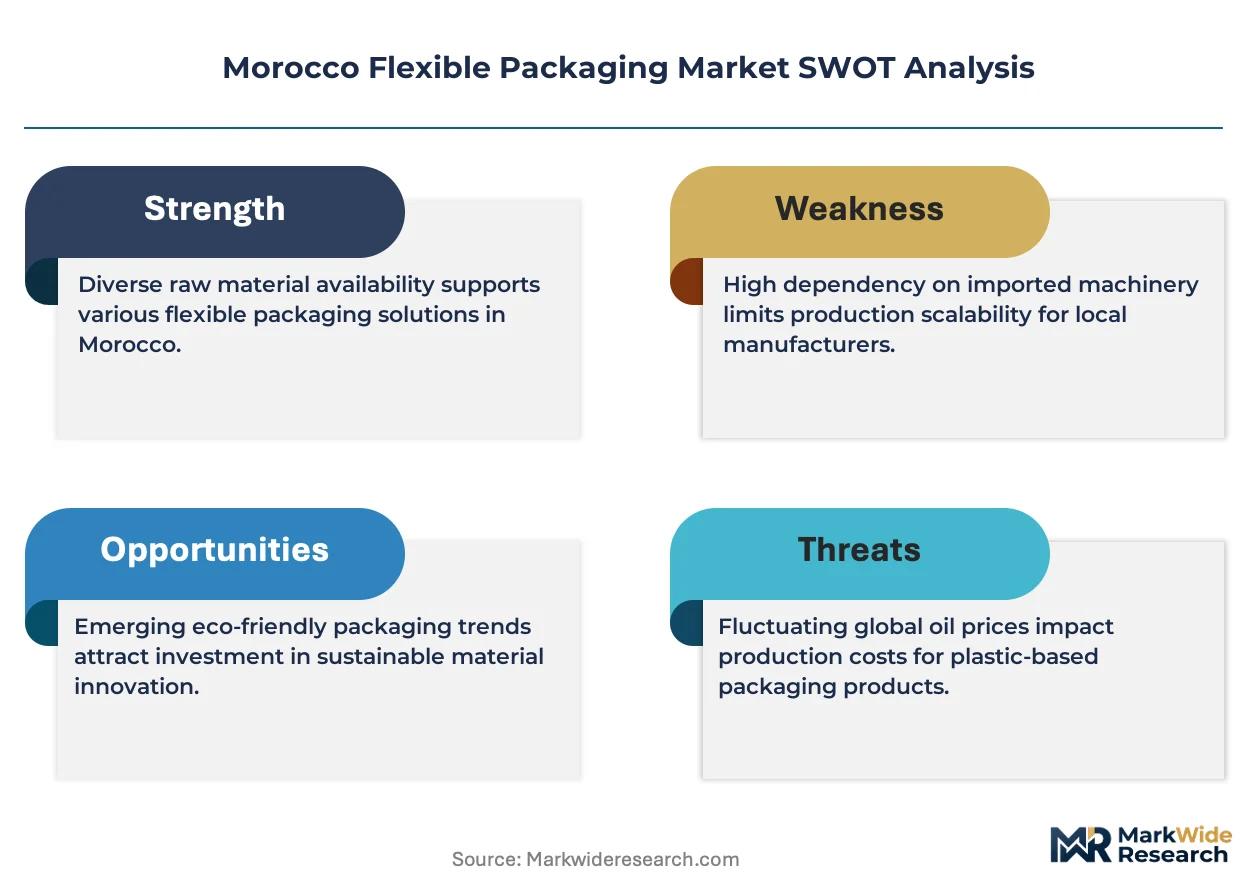
Morocco's Law 77-15 plastic reduction mandates and BSI-equivalent conformity assessments for food contact materials shape substrate selection and import qualification pathways for converters and resin distributors. The country's national standards body and Ministry of Industry enforce labeling and recyclability provisions that extend compliance burdens downstream to brand owners and retail channels. Stakeholders must monitor enforcement cadence against informal packaging streams and the pace of domestic mechanical recycling infrastructure buildout to anticipate raw material cost and availability shifts.
Market Dynamics
Law 77-15's plastic reduction mandates are compressing substrate selection windows for Moroccan converters, forcing rapid qualification of polyethylene and paper-based alternatives while BSI-equivalent food contact assessments lengthen import timelines for resin distributors.
Growth Catalysts
- Agri-export pouch migration:Casablanca-Settat food processors are replacing rigid formats with barrier laminates to meet European retail shelf-life specifications for shelf-stable seafood and olive oil exports.
- Law 77-15 compliance pull:Morocco's single-use plastic ban is accelerating converter investment in mechanical recycling-compatible polyethylene structures and kraft-paper flexible hybrids.
- Pharmaceutical barrier demand:Oxygen and moisture specifications for Casablanca-Rabat drug manufacturers are sustaining premium laminate margin pools as domestic production scales.
Market Restraints
- Resin import concentration:Polyethylene and polypropylene supply concentrates through Port Casablanca, exposing converters to freight volatility and customs clearance friction.
- Mechanical recycling gap:Domestic post-industrial flake capacity remains underdeveloped, forcing reliance on virgin resin for food-contact compliant structures.
- Multilayer incompatibility:Aluminium and adhesive layers in existing laminate stocks complicate mechanical recycling streams, limiting circularity claims for brand owners.
Strategic Opportunities
- Tangier-Tetouan-Al Hoceima corridor:Underpenetrated converting capacity near Mediterranean export ports offers greenfield sites for barrier film production serving European markets.
- Mono-material innovation:Polyethylene-only pouches with compatible fitments and inks are opening redesign contracts with multinational brand owners seeking recyclability certification.
- Digital print integration:Short-run customization for mid-tier domestic brands is compressing minimum order quantities and lead times against conventional flexographic workflows.
Industry Challenges
- Barrier film metallization expertise:Vacuum deposition and aluminium oxide coating capabilities remain concentrated among a limited converter base, constraining local supply of high-performance pharmaceutical and premium food laminates.
- Law 77-15 enforcement cadence:Uneven inspection intensity across informal packaging streams creates competitive distortion between compliant and non-compliant converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Flexible Packaging Market |
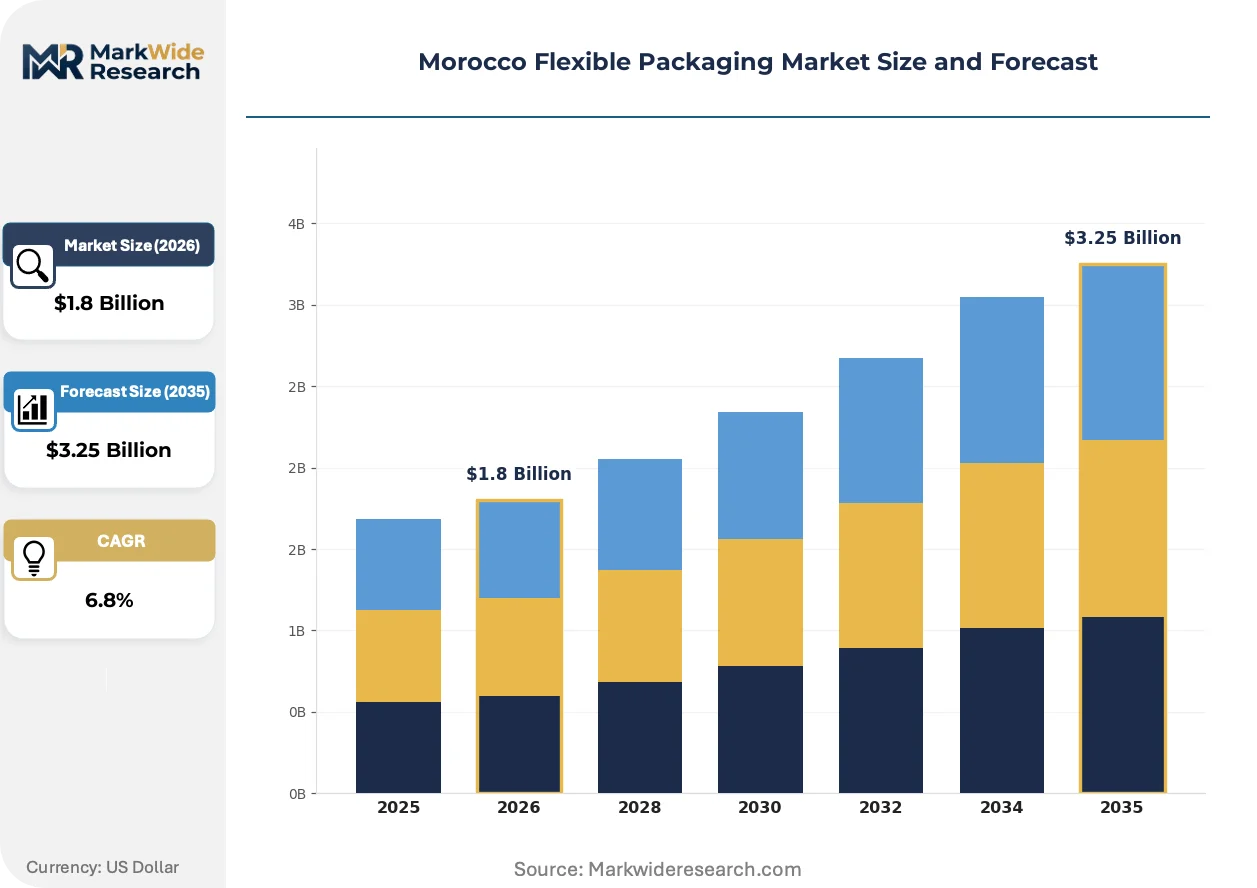
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Shrink Films, Laminated Films, Rigid Boxes Material: Polyethylene, Polypropylene, Paper, Aluminium End User: Food & Beverages, Pharmaceuticals, Personal Care, Household Products Distribution Channel: Supermarkets, Convenience Stores, E-commerce, Wholesale |
| Companies Covered | Amcor Group GmbH, Hotpack Packaging Industries LLC, Unibag Maghreb, Societe Nouvelle Des Etablissements Manusac, Atlantic Packaging SA, Compagnie Industrielle Des Fibres, ALPLA Werke Alwin Lehner GmbH & Co KG, Almapack, Mondi Pap Sac Maghreb SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Flexible Packaging Market Shifts & Advancements
Active substrate redesign and qualification acceleration are compressing technology adoption cycles across Moroccan converting operations, with sustainability specifications and export compliance requirements driving simultaneous material and process evolution.
High-barrier polyethylene terephthalate glycol (PETG) and ethylene vinyl alcohol (EVOH) coextrusions are electrifying oxygen transmission rate performance in mono-material structures. Casablanca-Rabat pharmaceutical and premium olive oil exporters are qualifying these laminates for twelve-to-eighteen-month shelf-life targets. The shift is compressing multilayer aluminium-dependent formats toward recyclable single-polymer solutions.
Morocco's national standards body is tightening BSI-equivalent food contact material conformity assessments under harmonized EU regulatory frameworks. Converters now face extended qualification timelines for imported resins and additives, particularly for direct-contact dairy and meat applications. The Casablanca-Settat industrial cluster is responding with captive laboratory investment to accelerate migration testing and documentation.
European retail channel sustainability specifications are reshaping procurement criteria for Moroccan agri-processors. Major supermarket chains now mandate recyclability labeling and post-consumer recycled content thresholds that domestic converters must meet to maintain export access. The specification compression is most visible in olive oil and prepared food segments, where brand owners are consolidating supplier bases around certified circularity partners.
Morocco Flexible Packaging Market Segmentation
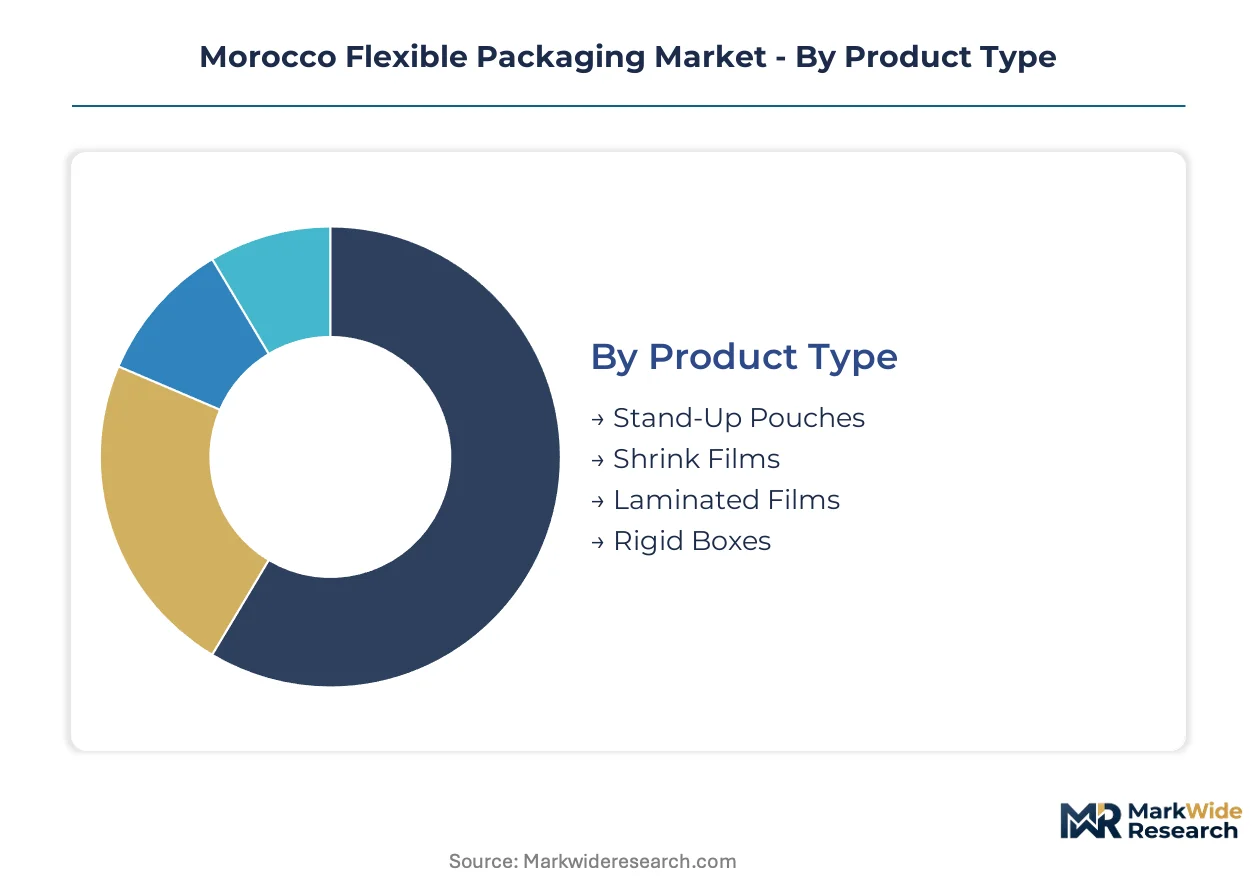
Flexible packaging segmentation in Morocco reflects divergent technical requirements across export-oriented food processing and domestic consumption channels. Substrate selection and format design vary sharply between European retail compliance mandates and local affordability constraints.
Product Type:
Integration depth separates standalone flexible formats from hybrid rigid-flexible combinations, with pure flexible solutions dominating export volumes while rigid hybrids persist in domestic premium positioning.
- Stand-Up Pouches:Multilayer barrier constructions with reseal fitments and spouts command premium positioning for shelf-stable olive oil and prepared sauces. Casablanca-Settat agri-processors are migrating rigid bottle formats to these structures to reduce freight cube and meet European retailer sustainability specifications.
- Laminated Films:Coextruded or adhesive-bonded multilayer webs incorporating EVOH or aluminium oxide deliver oxygen transmission rates below 1 cc/m²/day for pharmaceutical blister packs and premium seafood. Oxygen barrier specifications from Casablanca-Rabat drug manufacturers sustain margin concentration despite longer qualification timelines.
- Shrink Films:Mono-directional or biaxially oriented polyethylene terephthalate glycol webs dominate beverage multipack collation and pallet unitization with limited pricing flexibility.
- Rigid Boxes:Paperboard-based formats with flexible film windows occupy gift and premium confectionery segments where structural presentation outweighs lightweighting imperatives.
Volume placements concentrate in Shrink Films; the faster expansion belongs to Stand-Up Pouches.
Material:
Cost tiers stratify from commodity polyethylene through engineered barrier polymers to aluminium laminates, with Law 77-15 compliance costs compressing mid-tier material selection windows.
- Polyethylene:Linear low-density and high-density grades constitute the mechanical recycling-compatible backbone for mono-material pouch redesigns. Casablanca converters are qualifying PE-only structures with compatible fitments and inks to meet multinational brand owner recyclability certification requirements.
- Polypropylene:Biaxially oriented and cast film grades deliver clarity and moisture barrier for snack and bakery applications. Biaxially oriented polypropylene faces substitution pressure from polyethylene in export channels where European recyclability mandates dominate procurement criteria.
- Paper:Kraft and extensible sack papers in flexible hybrid constructions navigate retailer sustainability specifications for dry goods and agricultural inputs.
- Aluminium:Foil laminates and metallized films sustain pharmaceutical and premium food barrier performance where oxygen and light protection justify non-recyclable multilayer complexity.
Cost-sensitive domestic applications favor Polyethylene; engineered barrier requirements sustain Aluminium in pharmaceutical segments.
End User:
Application maturity divides between established food and beverage formats and emerging pharmaceutical barrier specifications, with personal care representing a conversion growth frontier.
- Food & Beverages:Olive oil, seafood, and prepared sauce exporters in Casablanca-Settat drive specification migration toward twelve-to-eighteen-month shelf-life barrier laminates. European retail channel sustainability mandates are consolidating supplier bases around certified circularity partners.
- Pharmaceuticals:Casablanca-Rabat drug manufacturers require oxygen and moisture barrier specifications that sustain premium laminate margin pools as domestic production scales. Extended BSI-equivalent conformity assessment timelines for imported resins compress converter qualification bandwidth.
- Personal Care:Liquid soap, shampoo, and cosmetic pouch formats are displacing rigid bottles in mid-tier domestic brand portfolios.
- Household Products:Detergent and cleaning chemical flexible packaging occupies mature volume positions with limited format innovation.
Established volume concentrates in Food & Beverages; Pharmaceuticals is climbing the fastest on domestic production scaling and barrier specification tightening.
Distribution Channel:
Customer type segmentation separates bulk wholesale procurement from retail-facing format complexity, with e-commerce emerging as a customization driver.
- Supermarkets:European retail channel sustainability specifications mandate recyclability labeling and post-consumer recycled content thresholds that shape converter design priorities for export-bound Moroccan agri-processors.
- Wholesale:Bulk dry goods and agricultural input packaging prioritizes unit cost minimization over format sophistication.
- Convenience Stores:Small-format single-serve pouches dominate snack and beverage impulse purchase occasions in urban Moroccan retail.
- E-commerce:Short-run customization and direct-to-consumer fulfillment are compressing minimum order quantities for mid-tier domestic brands.
Procurement scale concentrates in Wholesale; E-commerce is gaining share fastest on digital print integration and lead time compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Morocco's flexible packaging production clusters in the Casablanca-Rabat corridor while consumption spreads across urban centers and export channels. Domestic converting capacity outpaces local resin supply, creating import dependency for polyethylene and polypropylene feedstocks.
Casablanca-Settat
Food processing exporters dominate demand for barrier laminates and stand-up pouches. Law 77-15 plastic reduction mandates accelerate converter migration toward polyethylene-only structures. The Mohammedia-Kénitra industrial belt hosts the densest converting capacity serving European retail channels.
Rabat-Salé-Kénitra
Pharmaceutical manufacturers sustain premium laminate specifications for oxygen-sensitive drug packaging. BSI-equivalent conformity assessments from the national standards body extend resin import timelines. The Salé free zone concentrates cold-chain logistics supporting temperature-stable barrier film distribution.
Tangier-Tetouan-Al Hoceima
Mediterranean port access attracts greenfield converting investment for European export markets. The region's underpenetrated mechanical recycling infrastructure limits post-industrial flake supply for food-contact structures. Tangier Med port expansion reduces freight lead times for resin imports.
Marrakesh-Safi
Olive oil cooperatives drive seasonal demand for pouch formats replacing traditional tin containers. Domestic retail channel growth concentrates in urban supermarkets requiring standardized labeling compliance. The Safi industrial zone hosts emerging flexible film printing operations.
Fès-Meknès
Agri-input packaging for cereals and fertilizers sustains commodity polyethylene film volumes. Informal packaging streams create competitive distortion against Law 77-15 compliant converters. Meknès hosts specialized kraft-paper sack production for agricultural export cooperatives.
Morocco Flexible Packaging Market Competitive Landscape
Top-tier vendors anchor premium laminate supply for pharmaceutical and export food channels, while mid-tier domestic specialists compete on short-run customization and lead time compression. The vendor base stratifies across multinational technical service networks, regional paper-flexible hybrids, and local customization players. Three archetypes dominate: barrier film specialists with metallization expertise, kraft-paper flexible converters, and digital-integrated short-run suppliers. Competitive moves concentrate on mono-material innovation partnerships and mechanical recycling-compatible structure qualification.
Within the multinational technical service tier, Amcor Group GmbH and Mondi Pap Sac Maghreb SA occupy anchor positions representing divergent substrate strategies—premium laminates versus kraft-paper flexible hybrids. Unibag Maghreb exemplifies the mid-tier customization archetype competing on digital print integration and reduced minimum order quantities for domestic brand owners.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Hotpack Packaging Industries LLC |
| Unibag Maghreb |
| Societe Nouvelle Des Etablissements Manusac |
| Atlantic Packaging SA |
| Compagnie Industrielle Des Fibres |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Almapack |
| Mondi Pap Sac Maghreb SA |
| Others |
Supply & Pricing Matrix
Polyethylene resin price indices at Port Casablanca cascade through three distinct pricing tiers, compressing margins for mid-tier converters while premium laminate specialists retain pricing power through barrier certification. Law 77-15 compliance costs and freight volatility from concentrated resin imports reshape procurement economics across the Moroccan flexible packaging value chain.
Pricing Analysis
Margin tightening in mid-tier polyethylene structures reflects virgin resin dependency and mechanical recycling infrastructure gaps. Three-tier pricing structure across premium barrier laminates, standard coextruded films, and economy-grade commodity polyethylene separates converters by certification grade and volume scale. Cost-down pressure on domestic mid-tier brands accelerates as European retail sustainability mandates disqualify non-recyclable multilayer formats. Small domestic brand owners exhibit highest price sensitivity; pharmaceutical exporters demonstrate lowest sensitivity due to oxygen barrier specifications.
Supply Chain Analysis
Post-industrial flake returns and mechanical recycling flows remain underdeveloped, forcing reliance on virgin polyethylene and polypropylene imports through Port Casablanca. Raw material supply draws from Saudi Arabia, Qatar, and Belgium for resin feedstocks, with ink and adhesive additives sourcing from Germany and Italy. Single-source vulnerability concentrates at Port Casablanca customs clearance, exposing converters to freight volatility and extended BSI-equivalent conformity timelines. Distribution runs through converter-to-brand-owner direct contracts, with limited third-party logistics penetration in barrier film segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Morocco's flexible packaging sector sits in active substrate transition, with mono-material polyethylene structures displacing aluminium-dependent multilayer laminates under Law 77-15 compliance pressure and European retail recyclability mandates.
For Market Incumbents: Anchor premium positioning through captive metallization expertise and pharmaceutical barrier certifications that emerging competitors cannot rapidly replicate. Deepen backward integration into mechanical recycling-compatible polyethylene compounding to defend margin pools against resin price volatility. Invest in Tangier-Tetouan converting capacity to capture Mediterranean export freight advantages. For New Entrants and Emerging Players: The gap between premium barrier laminate pricing and economy polyethylene commodity rates offers entry space for mono-material pouch specialists. Target mid-tier domestic food brands in Casablanca-Settat with digital print-enabled short-run customization, compressing minimum order quantities against conventional flexographic workflows. Lead with BSI-equivalent food contact pre-certification to accelerate brand owner qualification timelines. For Investors and Strategic Acquirers: The window for entry favors kraft-paper flexible hybrid specialists with established European retail sustainability credentials. Long-term viability hinges on mechanical recycling infrastructure buildout pace and Law 77-15 enforcement cadence against informal packaging streams. Monitor domestic post-industrial flake capacity announcements and national standards body inspection intensity as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Pouch Redesign | Polyethylene-only structures with compatible fitments unlock European retail recyclability certification for Casablanca-Settat exporters. |
| Captive Metallization Investment | Vacuum deposition capabilities in Casablanca-Rabat constrain supply of high-barrier pharmaceutical laminates to qualified converters. |
| Digital Print Integration | Short-run customization compresses lead times for mid-tier domestic brands against conventional flexographic workflows. |
| Tangier Med Greenfield Capacity | Mediterranean port access reduces resin import freight costs and positions barrier film production for European export markets. |
| Mechanical Recycling Partnership | Domestic post-industrial flake supply agreements reduce virgin polyethylene dependency and Law 77-15 compliance cost exposure. |
Research Methodology
Multi-period observation of resin import volumes, converter capacity utilization, and Law 77-15 enforcement patterns anchored the trend analysis, supplemented by interviews with plant managers at Casablanca-Settat converting facilities, procurement leads at olive oil and seafood exporters, regulatory affairs specialists at the national standards body, and distribution channel partners in the Mohammedia-Kénitra industrial belt. Secondary validation drew from customs trade data, Ministry of Industry enforcement disclosures, BSI-equivalent conformity assessment records, and SEC filings of multinational packaging suppliers. Bottom-up capacity modeling and top-down export value triangulation cross-checked volume estimates.
Input-output matrices mapped polyethylene and polypropylene resin flows through Port Casablanca to converting clusters, segmented by product type, material grade, end-use application, and distribution channel across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating European retail sustainability specification adoption rates and domestic pharmaceutical production scaling. Industry-specific forecast inputs included EVOH coextrusion qualification timelines and digital print penetration rates in mid-tier brand portfolios.
Inputs from customs records and converter interviews were available through the study window; gaps in informal packaging stream volume data introduce uncertainty bands around Law 77-15 compliance cost estimates. Forecasts reflect documented assumptions about mechanical recycling infrastructure buildout pace and BSI-equivalent assessment timeline normalization. Practitioners should monitor national standards body inspection intensity announcements and Tangier Med port expansion milestones for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Multilayer Flexible Packaging Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
Bakery Flexible Packaging Market
Flexible Packaging
Flexible Detergent Packaging Market
Flexible Packaging
Europe Flexible Plastic Packaging Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
Latin America Flexible Packaging Market
Flexible Packaging
Flexible Food Packaging Market
Flexible Packaging
Flexible Paper for Food & Beverages Packaging Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
Metalized Flexible Packaging Market
Flexible Packaging
Thermoform Packaging Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market
Flexible Packaging
Nigeria Flexible Plastic Packaging Market
Flexible Packaging
India Flexible Plastic Packaging Market
Flexible Packaging
Kenya Flexible Packaging Market