
 Europe and USA Consumer Electronics Packaging Market | 2026-2036
Europe and USA Consumer Electronics Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe and USA Consumer Electronics Packaging Market Foresight
The premium-commodity split in Europe and USA consumer electronics packaging is expanding as luxury unboxing experiences diverge from cost-optimized e-commerce shipping formats. DS Smith PLC leverages its circular design capabilities to dominate molded fiber solutions for premium smartphone launches. WestRock Company sustains scale advantages in corrugated fulfillment packaging for online electronics retail across the southeastern United States.
Consumer electronics packaging encompasses protective and presentational enclosures engineered from fiber-based substrates, thermoformed plastics, and expanded foams with specified drop-test resilience and surface-print compatibility, serving to prevent damage during distribution while enabling brand communication at point of unboxing. Folding cartons and rigid boxes capture the highest margin pools in wearable and laptop segments where unboxing videos amplify brand equity. Thermoformed trays lead volume in smartphone packaging due to precise cavity tolerances and line-speed compatibility with automated assembly in Poland and Mexico border facilities.
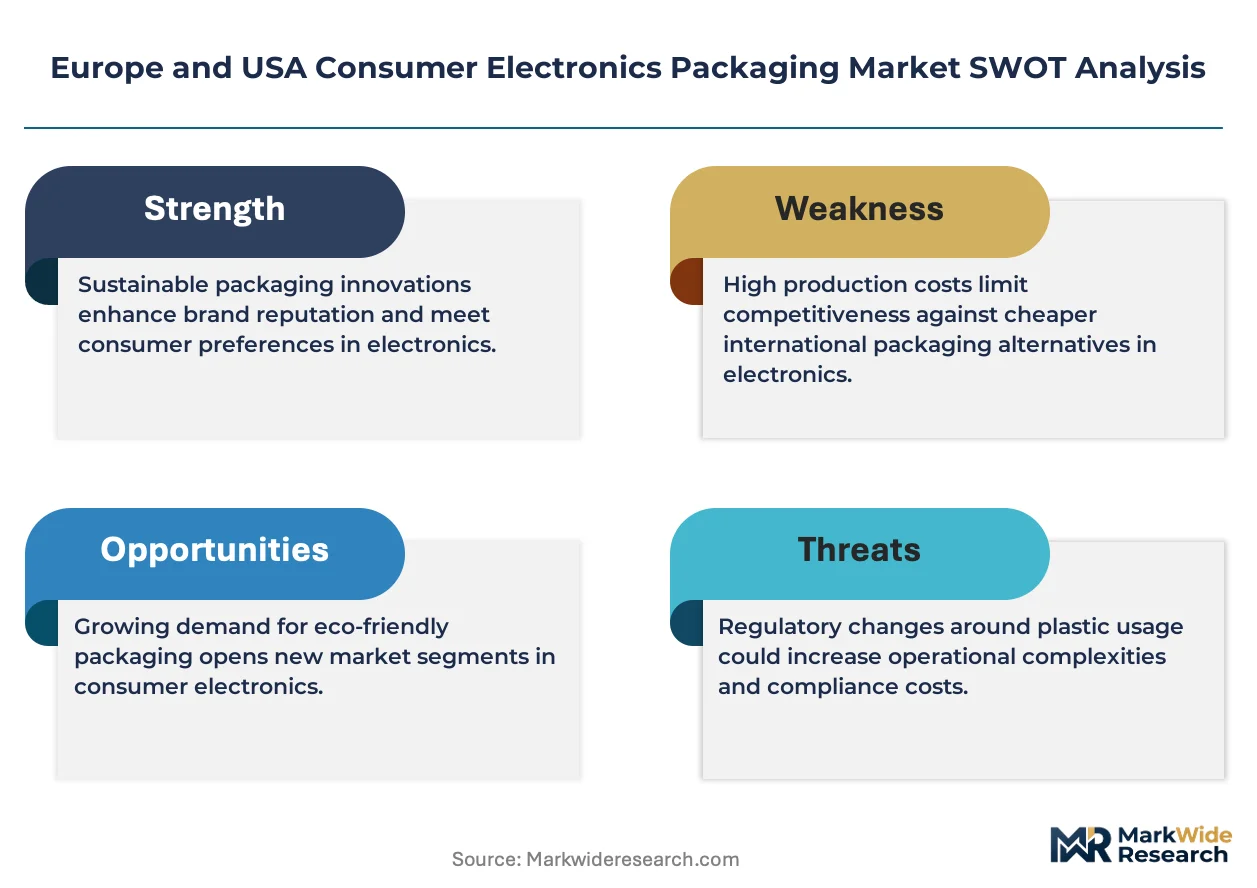
REACH compliance through ECHA and EPA toxic substance evaluations under TSCA are reshaping material qualification timelines for plasticizers and flame retardants in foam inserts. The EU Green Deal packaging targets and emerging US state-level extended producer responsibility laws are forcing reformulation roadmaps across the supply base. Stakeholders must monitor divergence between EU harmonized standards and patchwork US state regulations to avoid compliance fragmentation costs.
Market Dynamics
EU Packaging and Packaging Waste Regulation enforcement alongside California SB 54 implementation is forcing material transitions across smartphone, laptop, and wearable supply chains, compressing qualification timelines and reshaping supplier selection criteria.
Growth Catalysts
- EU Green Deal packaging targets:Mandated recycled content thresholds accelerate molded fiber tray adoption for premium electronics launches in Germany and France.
- Smartphone assembly automation:Precise cavity tolerance requirements in thermoformed trays align with high-speed pick-and-place lines at Polish and Mexican border facilities.
- Extended producer responsibility laws:Emerging state-level frameworks in Oregon and Colorado create compliance-driven demand for closed-loop packaging systems.
Market Restraints
- Pulp fiber input volatility:Recycled paperboard price swings constrain margin stability for molded fiber producers serving West Coast electronics brands.
- REACH chemical compliance:ECHA substance evaluation timelines extend plasticizer qualification cycles for foam insert manufacturers by 8-14 months.
- Thermoformed plastic substitution:Bio-based alternatives face performance gaps in drop-test resilience for high-value laptop shipments.
Strategic Opportunities
- Wearable unboxing experience premiumization:Rigid box and magnetic closure formats command margin pools in Apple and Samsung accessory lines.
- California SB 54 plastic reduction mandates:2032 compliance deadlines create procurement windows for fiber-based fulfillment packaging in e-commerce channels.
- Nearshoring to Mexico border zones:Electronics assembly relocation from Asia shortens packaging supply chains for US Southwest distribution.
Industry Challenges
- Cross-jurisdiction compliance fragmentation:Divergent EU harmonized standards and US state patchwork regulations multiply certification costs for multi-market suppliers.
- Automation retrofit capex:Line-speed compatibility requirements for molded fiber trays demand equipment upgrades at legacy thermoforming facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe and USA Consumer Electronics Packaging Market |
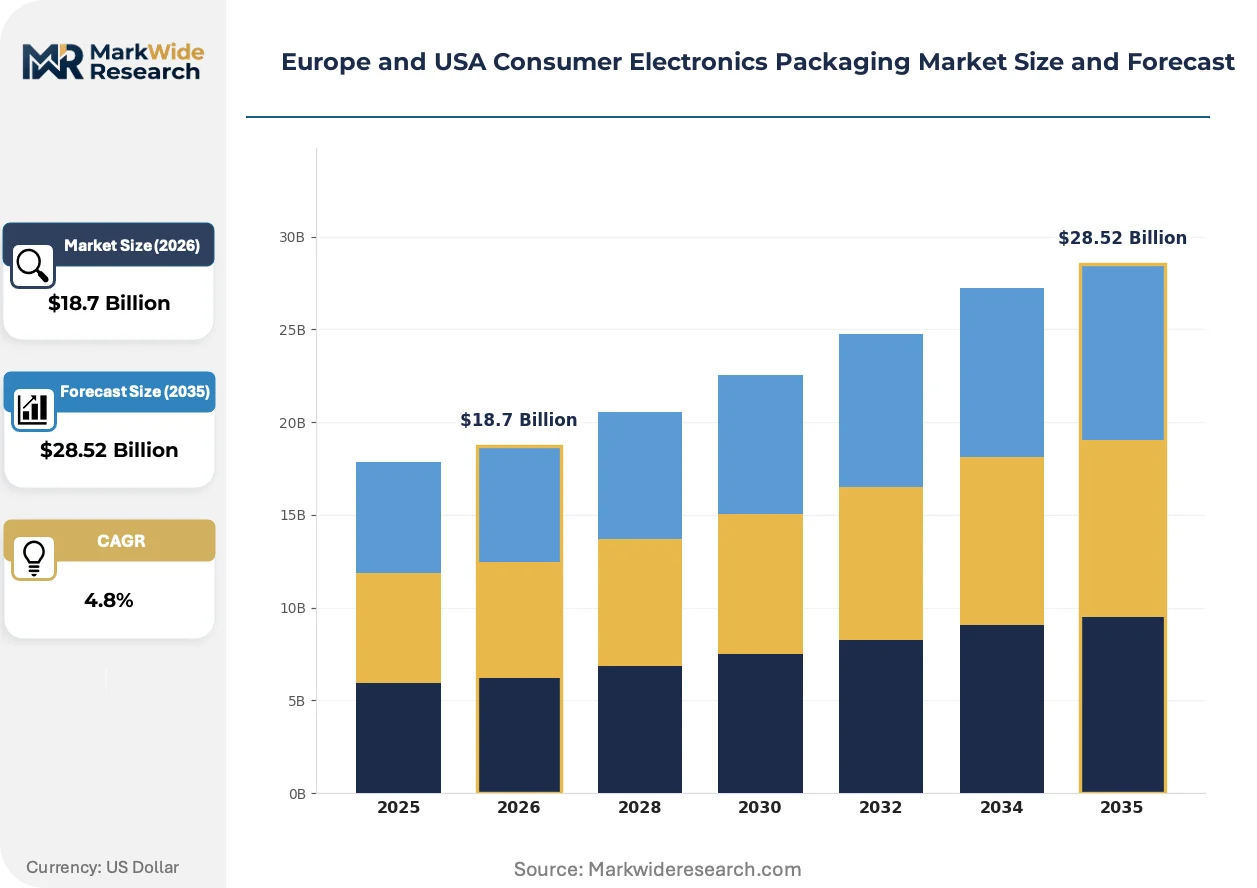
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Blister Packs, Folding Cartons, Rigid Boxes, Thermoformed Trays Material: Cardboard, Plastic, Paper, Foam End User: Smartphones, Laptops, Wearables, Home Appliances Design Type: Eco-Friendly, Luxury, Custom, Stand-Up Pouches |
| Companies Covered | DS Smith PLC, WestRock Company, Mondi Group, Sonoco Products Company, Smurfit Kappa Group PLC, Stora Enso Oyj, Pregis LLC, Sealed Air Corporation, UFP Technologies, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe and USA Consumer Electronics Packaging Market Shifts & Advancements
Active material science breakthroughs and regulatory compression timelines are reconfiguring competitive advantage around circular design capabilities and automated assembly compatibility rather than scale economies alone.
Molded fiber pulp technology is integrating nanocellulose reinforcement layers to achieve drop-test performance parity with expanded polystyrene. German smartphone brands and California laptop manufacturers are piloting these trays at 15-20% volume penetration for flagship launches. The technology is integrating premium unboxing aesthetics with closed-loop recyclability, collapsing the historical trade-off between protection and sustainability credentials.
REACH authorization requirements through ECHA are restricting legacy flame retardants and plasticizers in foam cushioning materials. Electronics packaging suppliers face reformulation roadmaps with 18-month qualification windows for alternative chemistries. Laptop and tablet segments in Northern Europe show fastest compliance adaptation due to retailer sustainability scorecards.
Unboxing video amplification on social platforms has elevated packaging to brand equity infrastructure. Electronics OEMs now specify hinge torque, magnetic closure force, and surface haptics for wearable and headphone boxes. This behavior concentrates in US and German metropolitan markets where influencer marketing budgets exceed traditional advertising allocations for consumer tech launches.
Europe and USA Consumer Electronics Packaging Market Segmentation
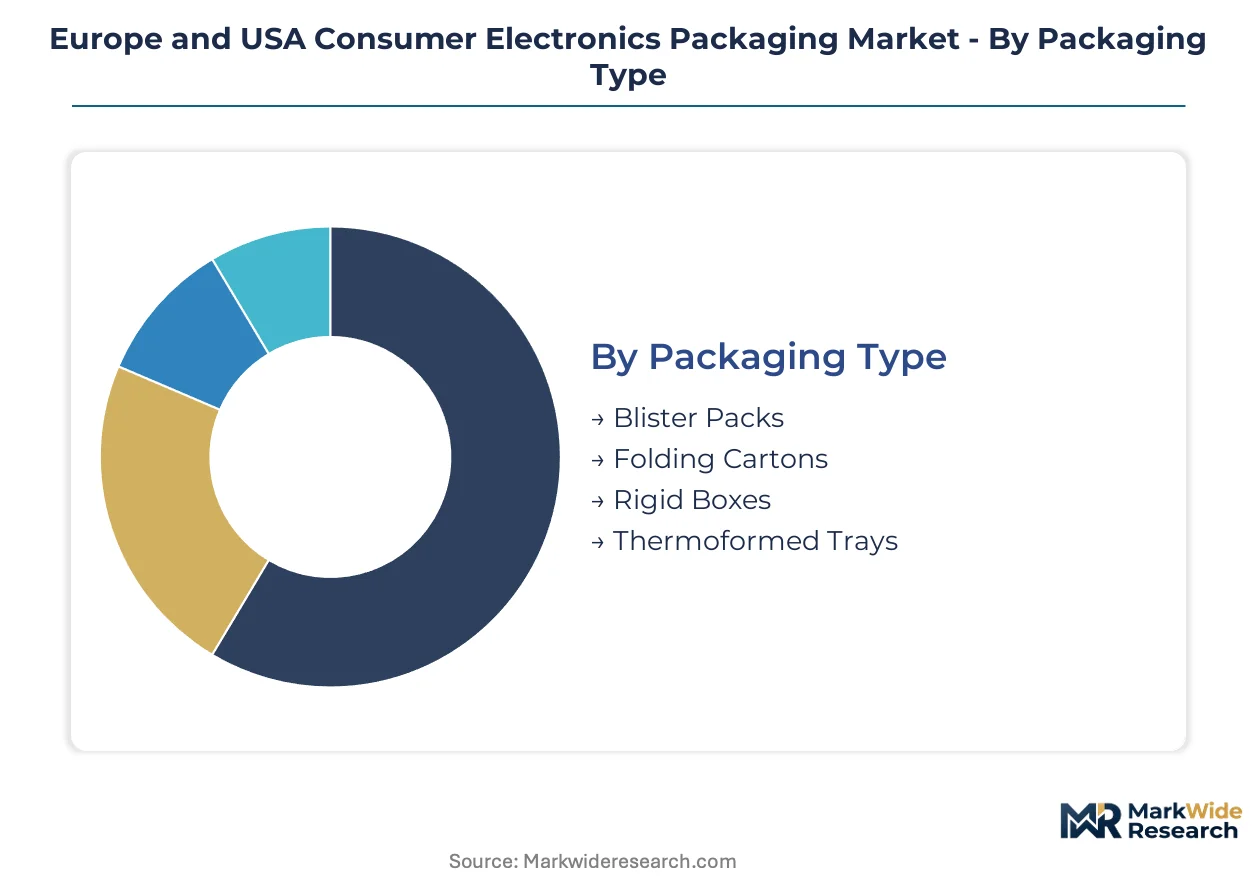
Packaging selection in Europe and USA consumer electronics hinges on automation compatibility and regulatory compliance timelines. Material and design choices now pivot on EU Green Deal targets and California SB 54 mandates rather than cost optimization alone.
Packaging Type:
Standalone formats dominate premium unboxing experiences while embedded trays integrate directly with assembly line robotics.
- Thermoformed Trays:Precision-molded cavities from PET or rPET substrates achieve ±0.2mm tolerance for component nesting. Polish and Mexican border assembly facilities specify these trays for smartphone pick-and-place automation at line speeds exceeding 200 units per minute.
- Folding Cartons:Multi-point glued structures from clay-coated recycled board enable high-resolution lithographic printing. German laptop brands and California wearable OEMs concentrate procurement here for e-commerce fulfillment where dimensional efficiency reduces shipping cube.
- Blister Packs:Heat-sealed thermoform films over printed card backing serve accessory and cable retail display requirements.
- Rigid Boxes:Wrapped paperboard over set-up construction commands unboxing video aesthetics for flagship device launches.
Thermoformed trays lead volumes today; rigid boxes are gaining share fastest in premium tier repositioning.
Material:
Cost tiers separate commodity substrates from certified circular alternatives with auditable chain-of-custody documentation.
- Cardboard:Recycled corrugated and solid bleached sulfate grades provide crush resistance for last-mile distribution. West Coast electronics fulfillment centers prioritize FSC-certified sources to meet retailer sustainability scorecards.
- Paper:Molded fiber pulp from post-consumer waste streams achieves drop-test parity with foam through nanocellulose reinforcement layers. German smartphone manufacturers pilot these trays at volume penetration for flagship circularity claims.
- Plastic:rPET and bio-based alternatives face qualification delays under REACH substance evaluations.
- Foam:Expanded polystyrene and polyurethane cushioning confront ECHA authorization restrictions on legacy flame retardants.
Cardboard dominates shipment volumes; molded fiber paper is climbing the fastest on regulatory compression.
End User:
Application intensity varies by device fragility, value density, and influencer marketing dependency.
- Smartphones:High-velocity SKUs demand thermoformed tray standardization across multiple OEM assembly partners. Mexico border zone facilities source packaging within 48-hour replenishment windows.
- Laptops:Higher value-to-weight ratios justify foam-to-fiber substitution investments despite 18-month qualification cycles.
- Wearables:Compact dimensions enable rigid box premiumization with magnetic closure specifications.
- Home Appliances:Bulkier units prioritize corrugated containment over presentational formats.
Smartphone packaging leads absolute volumes; wearable formats show steepest expansion trajectory on unboxing premiumization.
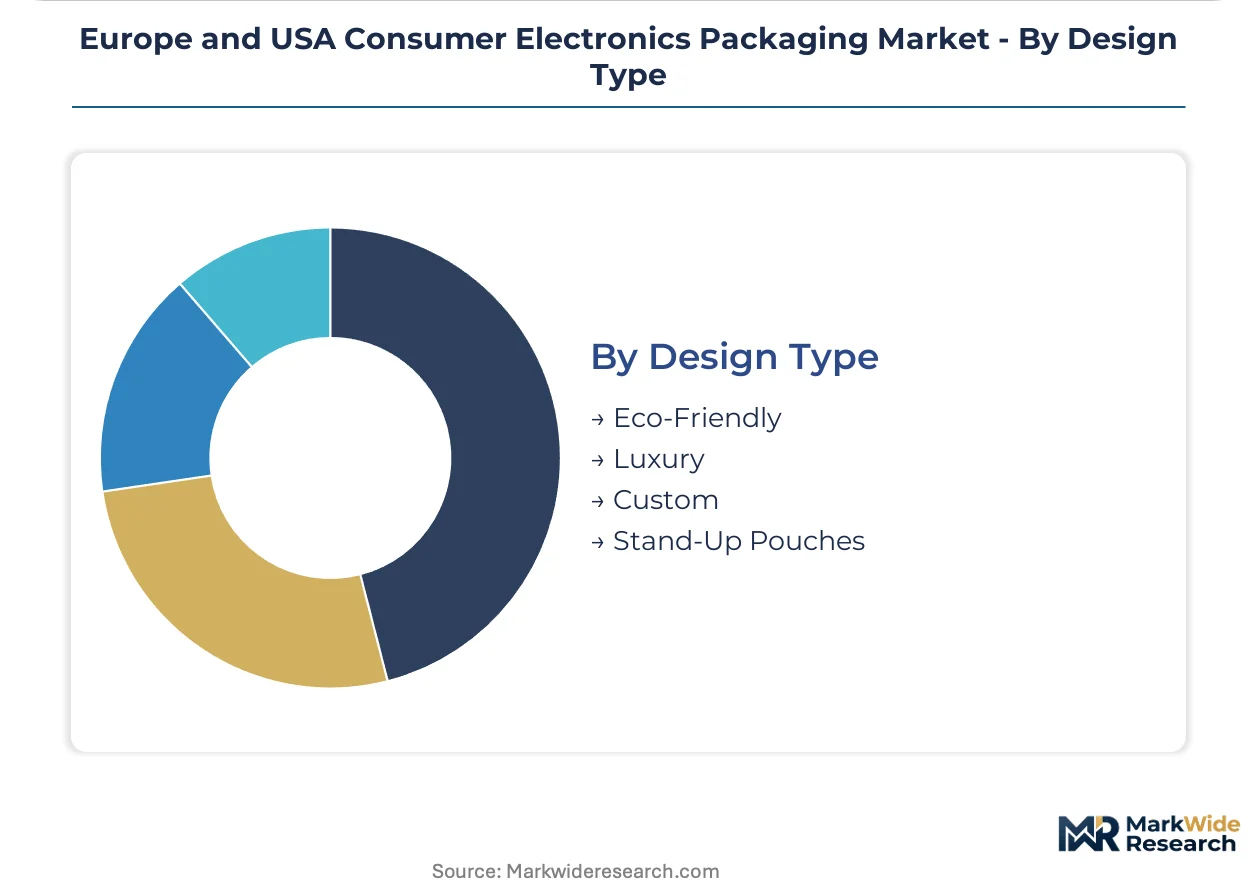
Design Type:
Customer type stratification separates compliance-driven procurement from brand equity investments.
- Eco-Friendly:Design-for-recycling specifications with mono-material construction and water-based adhesives. EU Packaging and Packaging Waste Regulation enforcement accelerates adoption across Northern European retail channels.
- Luxury:Hinge torque calibration and surface haptics engineering for social media amplification. US metropolitan markets concentrate demand where influencer marketing budgets exceed traditional advertising.
- Custom:Limited edition collaborations and seasonal variants for device launch windows.
- Stand-Up Pouches:Flexible format adoption remains limited to cable and accessory segments.
Eco-friendly designs lead procurement volumes today; luxury formats are expanding most quickly on unboxing video ROI metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineers cluster in Germany's industrial belt and California's Bay Area, anchoring design innovation for premium electronics brands. These talent concentrations sit adjacent to major assembly operations, compressing prototype-to-production cycles.
Germany
Smartphone OEMs in Bavaria and Baden-Württemberg drive molded fiber tray procurement for flagship circularity claims. REACH enforcement through ECHA restricts legacy plasticizers in foam cushioning, forcing 18-month reformulation cycles. Stuttgart's packaging innovation hub hosts pilot programs for nanocellulose-reinforced pulp trays achieving drop-test parity with expanded polystyrene.
United States
California SB 54 mandates 30% plastic reduction by 2032, accelerating fiber-based fulfillment packaging procurement by West Coast electronics brands. EPA TSCA evaluations extend chemical qualification timelines for thermoformed tray suppliers. Mexico border assembly zones in Texas and Arizona source packaging within 48-hour replenishment windows from regional corrugated converters.
France
EU Packaging and Packaging Waste Regulation thresholds concentrate demand for mono-material cartons in Paris-region e-commerce fulfillment. ECHA substance evaluations restrict flame retardants in laptop foam inserts. Lyon-based packaging specialists adapt rigid box formats for wearable unboxing experiences targeting influencer marketing amplification.
United Kingdom
Post-Brexit regulatory divergence complicates cross-border material qualification for suppliers serving EU and UK markets simultaneously. The Environment Agency's packaging waste recovery notes create compliance documentation burdens. Southeast England's logistics corridors prioritize dimensional-efficient folding cartons for last-mile electronics distribution.
Poland
Nearshored smartphone assembly in Lower Silesia and Greater Poland specifies thermoformed trays with ±0.2mm cavity tolerances for automated pick-and-place lines. EU Green Deal recycled content targets accelerate procurement from FSC-certified board suppliers. Warsaw packaging converters retrofit legacy equipment for molded fiber tray compatibility.
Europe and USA Consumer Electronics Packaging Market Competitive Landscape
Top-tier vendors anchor premium molded fiber and rigid box segments, while mid-scale converters compete on corrugated fulfillment speed and regional logistics proximity. The market exhibits tiered consolidation with three to four integrated fiber-based packaging groups commanding premium unboxing contracts, alongside specialized thermoforming operations focused on high-volume smartphone tray production. Strategic archetypes separate circular design specialists, automation-compatible tray fabricators, and e-commerce fulfillment scale players. Competitive moves center on equipment retrofit capex for molded fiber line-speed compatibility and backward integration into recycled pulp supply.
Within the integrated fiber-based tier, DS Smith PLC and WestRock Company exemplify divergent scale strategies. DS Smith occupies a position emphasizing circular design capabilities for premium smartphone launches, while WestRock anchors corrugated fulfillment scale across southeastern US electronics retail channels. Mondi Group sits within the specialty paperboard segment, representing European-based substrate innovation for mono-material packaging specifications.
| Leading Market Players |
|---|
| DS Smith PLC |
| WestRock Company |
| Mondi Group |
| Sonoco Products Company |
| Smurfit Kappa Group PLC |
| Stora Enso Oyj |
| Pregis LLC |
| Sealed Air Corporation |
| UFP Technologies, Inc. |
| Others |
Supply & Pricing Matrix
EU Packaging and Packaging Waste Regulation enforcement gates qualified supply access for premium-tier molded fiber trays while compressing margin pools for uncertified corrugated converters serving West Coast electronics brands. California SB 54 mandates simultaneously reshape procurement criteria and price differentiation between compliant and legacy material formats.
Pricing Analysis
Bundled design-for-recycling services versus unbundled commodity board sales split the competitive landscape. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified molded fiber from clay-coated recycled board and uncertified corrugated. Price differentiation stems from ECHA REACH compliance documentation and automation-compatible cavity tolerances. Pricing pressure stems from pulp fiber input volatility as recycled paperboard swings constrain converter margins. E-commerce fulfillment buyers exhibit highest price sensitivity while flagship smartphone OEMs prioritize circularity credentials over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Scandinavian pulp suppliers feeding German molded fiber tray production. Raw material flows draw from Swedish and Finnish forest products, recycled post-consumer waste streams in Poland, and rPET resin from Netherlands chemical complexes. Supply chain risk centers on ECHA substance evaluation timelines extending plasticizer qualification cycles for foam insert manufacturers. Distribution runs through Poland-Mexico border assembly corridors with 48-hour replenishment windows for smartphone OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through nanocellulose reinforcement adoption collapsing the protection-sustainability trade-off, while premium unboxing specifications capture influencer marketing budget shifts from traditional advertising.
For Market Incumbents: Anchor circular design capabilities with backward integration into recycled pulp supply to defend against emerging fiber-based specialists. DS Smith PLC's positioning demonstrates how ECHA REACH compliance documentation becomes a switching cost against uncertified rivals. Prioritize equipment retrofit capex for molded fiber line-speed compatibility at legacy thermoforming facilities.
For New Entrants and Emerging Players: Begin with rigid box premiumization for wearable accessory lines where magnetic closure specifications command unboxing video ROI. California SB 54 compliance deadlines create procurement windows for fiber-based fulfillment packaging in e-commerce channels. Target co-development partnerships with Bay Area influencer marketing agencies specifying hinge torque and surface haptics.
For Investors and Strategic Acquirers: Roll-up economics work for regional corrugated converters with Mexico border zone logistics proximity because nearshoring shortens replenishment windows for smartphone assembly. Long-term viability hinges on automation retrofit completion and ECHA certification asset bases. Watch for Poland-based packaging converters achieving molded fiber tray compatibility as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Nanocellulose Reinforcement Integration | Achieves drop-test parity with expanded polystyrene for German flagship launches. |
| Molded Fiber Equipment Retrofit | Compresses prototype-to-production cycles for California SB 54 compliance deadlines. |
| Backward Integration into Recycled Pulp | Captures margin pool erosion from Scandinavian pulp fiber input volatility. |
| Rigid Box Magnetic Closure Engineering | Commands unboxing video specifications from Apple and Samsung accessory procurement. |
| Poland-Mexico Border Logistics Positioning | Secures 48-hour replenishment contracts for nearshored smartphone assembly zones. |
Research Methodology
Bottom-up smartphone and laptop packaging volume modeling reconciled against top-down corrugated and molded fiber capacity tracking forms the analytical core. Primary interviews with packaging procurement managers at German and California OEMs, corrugated plant managers in Poland and Mexico border zones, ECHA regulatory affairs specialists, and e-commerce fulfillment directors supplied demand-side validation. Secondary sources include EU Packaging and Packaging Waste Regulation implementation guidance, EPA TSCA substance evaluation databases, FSC chain-of-custody certification registries, and SEC 10-K disclosures from integrated fiber-based packaging groups.
Input-output matrices map raw material flows from Scandinavian pulp suppliers through German and Polish converters to end-use assembly facilities. Segmentation dimensions span packaging type, material substrate, end-user device category, and design tier across the analysis window. CAGRs derive from regression analysis against EU Green Deal recycled content thresholds and California SB 54 plastic reduction mandates. Forecast inputs incorporate automation retrofit capex cycles and ECHA REACH authorization timelines for flame retardant alternatives.
Several conditions sit outside the modeled scope, including potential EU-US regulatory divergence post-2032, breakthrough bio-based drop-test performance parity, and smartphone OEM insourcing of packaging design. Forecasts reflect documented assumptions about compliance deadline adherence and pulp fiber price stabilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
Consumer Electronics Packaging Market
Electronics Packaging
North America Consumer Electronics Packaging Market
Electronics Packaging
Anti-Counterfeit Electrical and Electronics Packaging Market
Electronics Packaging
Global Mobile Phones Packaging Market
Electronics Packaging
Power Module Packaging Market
Electronics Packaging
Multi-Chip Module Packaging Market
Electronics Packaging
Electronic Goods Packaging Market
Electronics Packaging
Mobile Phone Accessories Packaging Market
Electronics Packaging
MEMS Packaging Solder Market
Electronics Packaging
Europe Consumer Electronics Packaging Market
Electronics Packaging
Fan-Out Wafer Level Packaging Market
Electronics Packaging
Global Display Packaging Market
Electronics Packaging
Electronic Wrapper Market
Electronics Packaging
Industrial Electronics Packaging Market
Electronics Packaging
Electronic Packaging Market
Electronics Packaging
Asia-Pacific Consumer Electronics Packaging Market