
 India Vinyl Flooring Market | 2026-2036
India Vinyl Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
India Vinyl Flooring Market Insights
Specialty store networks across western India is rewriting how vinyl flooring reaches end-users. Tarkett leverages its global formulation expertise to sustain premium positioning in commercial projects. Welspun Flooring anchors its competitive stance through backward integration into polymer supply chains. Gerflor dominates specification-driven institutional contracts with architects and project consultants.
Vinyl flooring comprises multi-layer synthetic polymer sheets or tiles, typically structured with a PVC wear layer, printed design film, and fiberglass-reinforced core, manufactured through calendering or extrusion processes to deliver water resistance and dimensional stability for high-traffic interior surfaces. Luxury Vinyl Tile leads product type demand due to superior aesthetic replication of natural materials and ease of installation, while Vinyl Plank records the fastest trajectory as residential consumers prioritize wood-grain visuals. The Commercial end user segment captures the deepest margin pools through large-format project specifications, whereas Online Retail distribution is gaining share among renovators seeking direct-to-home convenience.
BIS mandates on floor covering fire resistance and phthalate content directly determine which imported product lines gain market access, while CDSCO oversight on polymer additives influences raw material sourcing decisions for domestic manufacturers. The PLI scheme for specialty chemicals is incentivizing local PVC resin capacity that could reshape cost structures for vinyl flooring producers. Stakeholders must monitor how state-level RERA enforcement in Maharashtra and Karnataka alters project timelines and specification durability requirements.
Market Dynamics
Residential real estate developers in tier-2 cities are accelerating specification of luxury vinyl tile formats, compressing traditional ceramic tile procurement cycles and forcing distributors to reconfigure inventory depth toward polymer-based alternatives.
Growth Catalysts
- BIS certification tightening:Fire resistance and phthalate content mandates are filtering import flows and elevating compliant domestic production. Domestic manufacturers with certified lines capture specification share in institutional projects.
- PLI scheme for specialty chemicals:Local PVC resin capacity expansion is reducing raw material import dependency for flooring producers. Maharashtra and Gujarat manufacturing clusters benefit from feedstock proximity.
- Tier-2 urban housing:Residential developers in Surat, Indore, and Nagpur specify LVT for mid-premium apartment segments. Format flexibility and installation speed align with compressed construction timelines.
Market Restraints
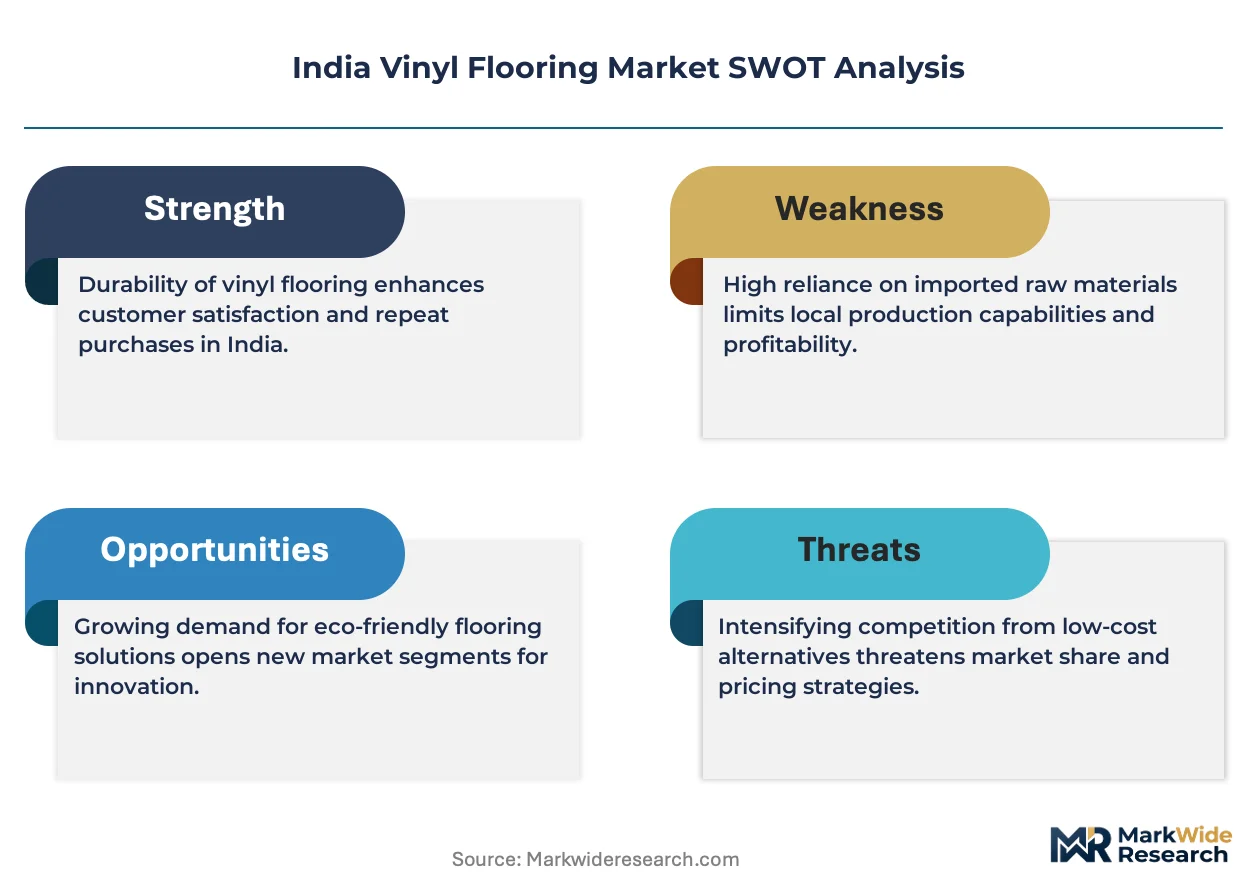
- PVC resin price volatility:Crude-linked ethylene costs transmit directly to flooring producer margins. Domestic manufacturers lack long-term supply contracts with Reliance Industries and Chemplast Sanmar.
- Import concentration from China:Unbranded vinyl sheet volumes from Zhejiang and Guangdong provinces dominate economy segments. Price arbitrage pressures domestic mid-tier producers.
- Technical limitation in outdoor durability:UV degradation and thermal expansion constrain vinyl flooring to interior applications. Terrace and balcony specifications default to porcelain tiles or natural stone.
Strategic Opportunities
- Kerala and Tamil Nadu underpenetration:Southern markets retain ceramic tile dominance with vinyl flooring share below western India levels. First-mover distributors in Kochi and Chennai capture specification relationships with regional developers.
- Healthcare facility expansion:Antimicrobial surface treatments align vinyl flooring with hospital and diagnostic center hygiene protocols. CDSCO oversight on polymer additives enables certified product positioning.
- Online retail channel emergence:Direct-to-home sampling and installation coordination platforms bypass traditional dealer networks. Renovators in Bangalore and Hyderabad adopt digital purchase journeys for residential projects.
Industry Challenges
- Skilled installation workforce scarcity:Click-lock and glue-down LVT formats require trained applicators distinct from ceramic tile masons. Vocational certification programs through ITIs remain underdeveloped in Rajasthan and Madhya Pradesh.
- BIS compliance timeline compression:Fire resistance testing at approved laboratories creates six-month product launch delays. Importers face DGFT clearance bottlenecks for non-certified shipments at Nhava Sheva and Mundra ports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Vinyl Flooring Market |
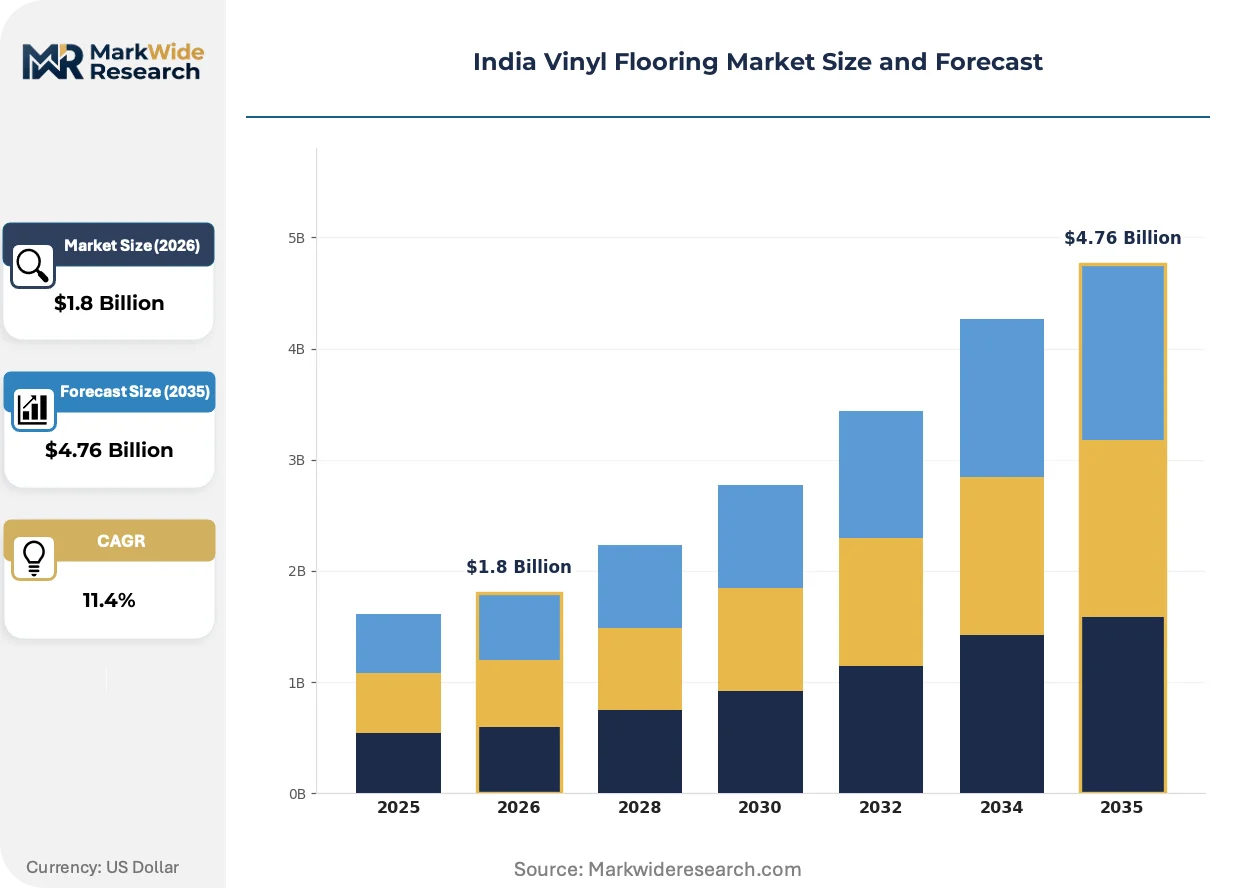
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Vinyl Tile, Vinyl Sheet, Vinyl Plank, Vinyl Composite Tile End User: Residential, Commercial, Industrial, Institutional Application: Floor Covering, Wall Covering, Decorative, Waterproofing Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Gerflor, Welspun Flooring, Tarkett, Duracare Flooring Solutions, Floorrex, Armstrong Flooring, LX Hausys, Mirage Flooring, Forbo Flooring Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Vinyl Flooring Market Trends and Innovations
Digital printing and rigid core engineering are compressing the performance gap between synthetic and natural materials, enabling vinyl flooring to capture specification share from wood and stone in premium residential and commercial interiors.
Surface visualization technology is digitizing design replication accuracy for wood-grain and mineral textures. High-definition inkjet printing systems now achieve 600+ DPI resolution on PVC wear layers. Commercial hospitality developers in Mumbai and Delhi specify these formats for hotel lobbies and co-working lounges, collapsing the traditional premium gap with engineered hardwood.
BIS mandates on floor covering fire resistance and phthalate content are restructuring import eligibility criteria. CDSCO oversight on polymer additives further constrains raw material sourcing flexibility for domestic producers. Maharashtra-based manufacturers with in-house compounding capabilities adjust formulation recipes to maintain certification continuity as testing protocols tighten.
Architects and interior designers are consolidating specification authority through direct manufacturer relationships, marginalizing traditional distributor influence. Project consultants in Ahmedabad and Pune source samples and technical data sheets through manufacturer digital platforms, bypassing dealer showrooms. This pattern concentrates in commercial and institutional segments where specification durability requirements align with certified product portfolios.
India Vinyl Flooring Market Segmentation
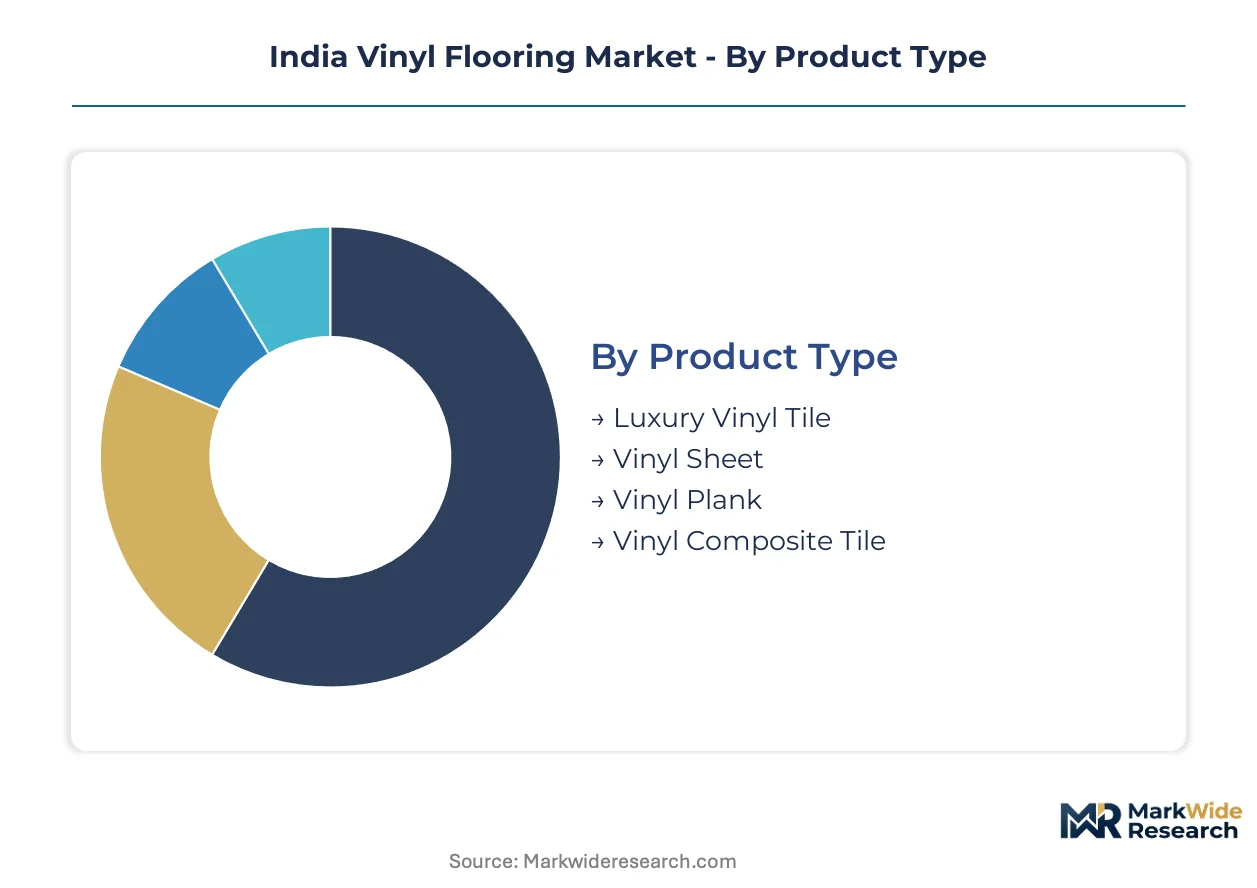
Vinyl flooring procurement cycles vary sharply across formats and end-use segments. Specification durability requirements and installation complexity create distinct inventory velocity patterns that distributors must calibrate against.
Product Type:
Replacement cycles stretch from rapid residential renovations to decade-long commercial installations, compressing or extending working capital requirements for manufacturers.
- Luxury Vinyl Tile:Multi-layer construction with PVC wear layer, printed design film, and fiberglass-reinforced core delivers dimensional stability for high-traffic surfaces. Residential developers in Surat and Indore specify LVT for mid-premium apartment segments where format flexibility aligns with compressed construction timelines.
- Vinyl Plank:Rigid core engineering replicates wood-grain visuals through high-definition inkjet printing at 600+ DPI resolution. Bangalore and Hyderabad renovators prioritize this format for direct-to-home digital purchase journeys, accelerating channel shift toward online retail.
- Vinyl Sheet:Continuous roll format manufactured through calendering processes serves economy segments in mass housing projects.
- Vinyl Composite Tile:Homogeneous construction targets institutional specifications requiring uniform wear characteristics across extended service life.
Luxury Vinyl Tile dominates installed base. Vinyl Plank is where expansion concentrates.
End User:
Margin structures diverge between price-sensitive mass residential procurement and specification-driven institutional contracts.
- Commercial:Large-format hospitality and co-working projects in Mumbai and Delhi capture deepest margin pools through certified product portfolios. Architects source technical data sheets through manufacturer digital platforms, consolidating specification authority and marginalizing traditional distributor influence.
- Residential:Tier-2 city developers in Maharashtra and Gujarat accelerate polymer-based alternatives procurement, compressing traditional ceramic tile cycles. RERA enforcement in these states alters project timelines and durability requirements.
- Institutional:Healthcare facility expansion in diagnostic centers aligns with CDSCO oversight on antimicrobial polymer additives.
- Industrial:Chemical resistance and load-bearing specifications dominate flooring selection for manufacturing floors.
Commercial captures premium specification value. Residential drives volume throughput.
Application:
Functional performance requirements segment demand between structural waterproofing and aesthetic surface treatments.
- Floor Covering:Primary application commanding specification share from wood and stone through digital printing advances. BIS fire resistance mandates filter import flows and elevate compliant domestic production for interior surface installations.
- Waterproofing:Bathroom and kitchen specifications leverage PVC core moisture resistance where porcelain tile installation costs exceed polymer alternatives. Kerala and Tamil Nadu underpenetration creates first-mover opportunities as southern markets retain ceramic dominance.
- Wall Covering:Vertical surface applications expand addressable market beyond traditional flooring boundaries.
- Decorative:Accent and feature wall specifications utilize high-visual-impact printed designs.
Floor Covering anchors revenue concentration. Waterproofing is climbing the fastest as renovation spending redirects toward moisture-prone interior zones.
Distribution Channel:
Customer acquisition economics fragment between high-touch specialty retail and low-margin digital fulfillment.
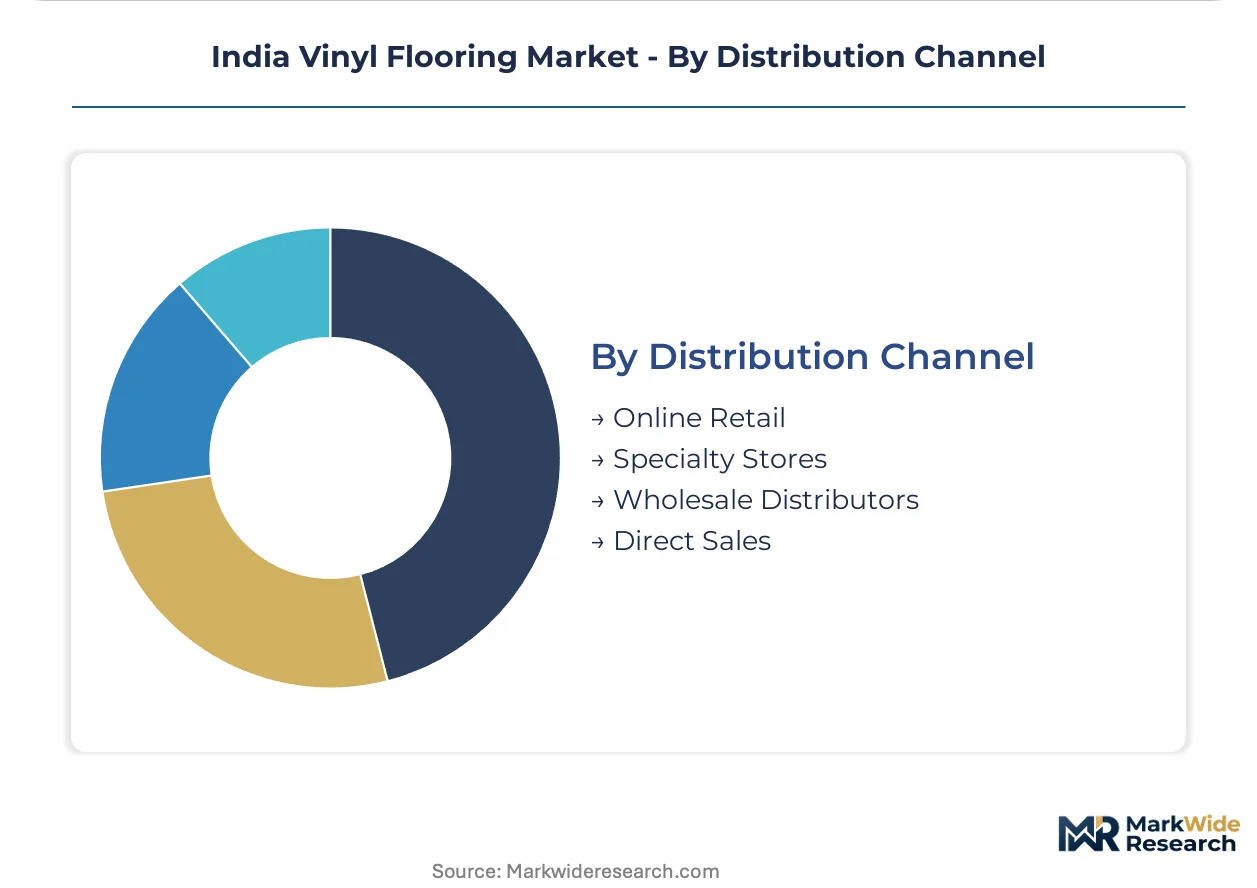
- Specialty Stores:Western India networks rewrite end-user reach through trained specification support and sample libraries. Ahmedabad and Pune project consultants bypass dealer showrooms for direct manufacturer relationships, concentrating influence in commercial segments.
- Online Retail:Direct-to-home sampling platforms with installation coordination capture renovator preference in Bangalore and Hyderabad. Digital purchase journeys gain share among residential consumers seeking convenience without dealer markup.
- Wholesale Distributors:Inventory depth reconfiguration toward polymer-based alternatives responds to tier-2 city developer demand shifts.
- Direct Sales:Manufacturer specification relationships with architects consolidate institutional contract capture.
Specialty Stores maintain specification authority. Online Retail is gaining share fastest among residential renovation segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification requirements and PLI scheme incentives are concentrating vinyl flooring manufacturing in Maharashtra and Gujarat manufacturing clusters, while southern states present expansion opportunities for first-mover distributors.
Maharashtra
Residential developers in Mumbai and Pune specify luxury vinyl tile for mid-premium apartment segments. RERA enforcement tightens project timelines and durability requirements. The Mumbai-Thane industrial corridor hosts compounding facilities serving domestic manufacturers with in-house formulation capabilities.
Gujarat
Surat and Ahmedabad project consultants source technical specifications through manufacturer digital platforms, bypassing traditional dealer networks. PLI scheme incentives for specialty chemicals expand local PVC resin capacity. The Vadodara-Ankleshwar chemical belt reduces feedstock logistics costs for flooring producers.
Karnataka
Bangalore renovators adopt digital purchase journeys for residential projects, accelerating online retail channel development. CDSCO oversight on polymer additives shapes antimicrobial product positioning for healthcare specifications. The state retains ceramic tile dominance with vinyl flooring penetration trailing western India levels.
Tamil Nadu
Chennai distributors face underpenetration relative to western markets, creating first-mover opportunities with regional developers. FSSAI-adjacent hygiene protocols in food processing facilities drive specification interest. The Sriperumbudur-Oragadam manufacturing zone hosts automotive and electronics facilities with limited vinyl flooring adoption to date.
Kerala
Kochi and Thiruvananthapuram markets maintain ceramic tile preference for residential waterproofing applications. Bathroom and kitchen renovation spending redirects toward moisture-prone interior zones. The state's construction sector shows nascent specification interest in polymer-based alternatives for hospitality projects.
India Vinyl Flooring Market Competitive Landscape
Global formulation specialists and domestic integrated manufacturers split the market between premium specification contracts and volume-driven residential supply. The vendor base concentrates around three strategic archetypes: multinational technical leaders with certified product portfolios, domestic producers leveraging backward integration into polymer supply chains, and regional distributors controlling specification relationships in tier-2 cities. Competitive moves center on BIS compliance acceleration and direct-to-architect digital platform deployment.
Within the multinational tier, Tarkett and Gerflor occupy positions anchored by global technical standards and institutional contract capture. Among domestic integrated producers, Welspun Flooring exemplifies the backward-integration archetype through captive polymer supply control. These three companies represent distinct competitive vectors: Tarkett sustains premium positioning through formulation expertise, Gerflor dominates specification-driven channels, and Welspun leverages supply chain integration for cost structure defense.
| Leading Market Players |
|---|
| Gerflor |
| Welspun Flooring |
| Tarkett |
| Duracare Flooring Solutions |
| Floorrex |
| Armstrong Flooring |
| LX Hausys |
| Mirage Flooring |
| Forbo Flooring Systems |
| Others |
Pricing and Supply Chain Analysis
PVC resin price volatility tethered to crude-linked ethylene costs compresses margin structures across all pricing tiers while simultaneously forcing domestic manufacturers toward long-term supply contracting strategies. This commodity exposure determines both the spread between certified premium lines and unbranded economy imports and the geographic clustering of compounding facilities near feedstock sources.
Pricing Analysis
The customization-premium spread separates architect-specified LVT with BIS fire resistance certification from standard-grade vinyl sheet rolls. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with large-format commercial projects capturing favorable unit economics. Cost compression in the economy tier is intensifying because unbranded Chinese imports arbitrage domestic production. Mass residential developers in tier-2 cities exhibit highest price sensitivity, while institutional healthcare specifications demonstrate lowest sensitivity due to CDSCO-mandated additive compliance requirements.
Supply Chain Analysis
Supplier-financing facilities extended by Reliance Industries and Chemplast Sanmar shape working capital dynamics for domestic flooring producers. Raw material sourcing draws from Saudi Arabia, China, and domestic Maharashtra-Gujarat petrochemical corridors, with PVC resin, plasticizers, and stabilizers as critical inputs. Single-source vulnerability concentrates in ethylene derivative supply chains exposed to crude price swings. Distribution runs through western India specialty store networks and emerging online retail platforms serving Bangalore and Hyderabad renovators directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-2 city residential developers and institutional project consultants, fragmenting traditional distributor influence and forcing manufacturers toward direct specification relationships.
For Market Incumbents: Build certification moats through accelerated BIS fire resistance and phthalate compliance investment ahead of mandate tightening. Domestic manufacturers should secure captive PVC resin supply through backward integration into Maharashtra polymer supply chains. Threat from unbranded Chinese import arbitrage demands channel control through architect-direct digital platforms. R&D priority centers on antimicrobial surface treatments for healthcare specification capture. For New Entrants and Emerging Players: Mid-market commercial buildings in Kerala and Tamil Nadu represent the most penetrable entry point given ceramic tile dominance and vinyl flooring underpenetration relative to western India levels. First-mover distributors in Kochi and Chennai can capture specification relationships with regional developers before incumbent networks establish presence. Go-to-market angle should emphasize waterproofing performance for bathroom and kitchen renovation segments where porcelain installation costs exceed polymer alternatives. For Investors and Strategic Acquirers: PLI scheme implementation for specialty chemicals reshapes the acquisition landscape by incentivizing local PVC resin capacity that could reshape cost structures. Long-term viability favors domestic manufacturers with in-house compounding capabilities and certified product portfolios over import-dependent traders. Acquisition target archetype: western India-based producers with established BIS-compliant lines and architect specification relationships. Signal to watch: DGFT clearance bottlenecks at Nhava Sheva and Mundra ports indicating tightening import filtration.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Acceleration | Fire resistance and phthalate compliance investment ahead of mandate tightening secures institutional contract access. |
| Backward Integration | Captive PVC resin supply from Maharashtra-Gujarat petrochemical corridors defends margin structures against crude volatility. |
| Digital Platform Deployment | Direct-to-architect specification channels marginalize traditional distributor influence in commercial segments. |
| Antimicrobial Surface Development | CDSCO-compliant additive formulations align product positioning with hospital and diagnostic center hygiene protocols. |
| Southern Market Expansion | First-mover distributor relationships in Kerala and Tamil Nadu capture specification share before incumbent network saturation. |
Research Methodology
Initial hypotheses were tested against primary input from residential real estate developers, project consultants, specialty store distributors, and polymer supply chain managers and refined through secondary validation. Primary fieldwork combined structured interviews with tier-2 city developers in Surat and Indore, specification conversations with Ahmedabad and Pune architects, and supply chain assessments with Maharashtra-based compounding facility operators. Secondary sources included BIS certification databases, CDSCO polymer additive regulations, PLI scheme documentation, customs import records at Nhava Sheva and Mundra, and state-level RERA enforcement filings. Bottom-up project pipeline analysis and top-down construction sector spend estimates were triangulated to anchor volume assumptions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling residential, commercial, institutional, and industrial end-use segments alongside product type splits between LVT, vinyl plank, sheet, and composite tile formats. Geographic demand patterns incorporated state-level urban housing project databases and RERA registration timelines. CAGRs were derived from segment-level demand build-ups calibrated against polymer consumption trends and import volume trajectories. Industry-specific forecast inputs included BIS certification pipeline velocity and PLI scheme disbursement schedules for specialty chemicals capacity.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, rupee-dollar exchange rates, or central bank interest rate cycles would shift the trajectory of residential construction finance availability and import parity calculations. Forecasts reflect underlying assumptions about regulatory enforcement continuity and petrochemical capacity expansion timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Laminate Flooring Market
Flooring, Carpets, and Rugs
Global Flooring Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
US Flooring Market
Flooring, Carpets, and Rugs
US Wood Flooring Market
Flooring, Carpets, and Rugs
Taiwan Floor Covering Market
Flooring, Carpets, and Rugs
Hardwood Flooring Market
Flooring, Carpets, and Rugs
Wood Plastic Composite (WPC) Floorings Market
Flooring, Carpets, and Rugs
Global Non-Resilient Flooring Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
China Engineered Wood Flooring Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
ASEAN Laminate Flooring Market