
 Taiwan Floor Covering Market | 2026-2036
Taiwan Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Floor Covering Market Analytics
GB/T 39600-2021 formaldehyde emission classification is unwinding competitive access for Taiwan flooring suppliers unable to certify E0 or ENF-grade substrates. Formosan United Corporation leverages captive resin production to control laminate core quality from source to finished plank. Lien Hwa Industrial Corp. anchors its position through decades-long relationships with Taiwan's largest construction consortia, securing specification on hospital and school projects. Green Building Material Corporation differentiates via exclusive distribution of low-VOC vinyl systems certified under Taiwan's Green Building Material Label.
Floor covering comprises finished surfacing materials installed over structural substrates to provide wear resistance, acoustic dampening, and aesthetic finish in built environments; Taiwan manufacturers predominantly employ hot-press lamination for engineered wood and calendering processes for homogeneous vinyl sheet, with thickness tolerances typically held within 0.1 millimeters for commercial-grade specifications. Tile and vinyl command the largest installed base across Taiwan's humid subtropical climate zones, where moisture resistance trumps natural fiber aesthetics in basement and ground-floor applications. Laminate surfaces are capturing specification share in mid-market residential towers where price sensitivity intersects with demand for wood-grain visual authenticity.
Taiwan's Environmental Protection Administration enforces indoor air quality standards that restrict formaldehyde and volatile organic compound emissions from installed flooring, while the Ministry of Interior's Green Building Material Label creates procurement preference for certified products on public works. The Bureau of Standards, Metrology and Inspection maintains compliance testing protocols that foreign imports must clear before customs release. Stakeholders must monitor pending revisions to Taiwan's building energy conservation code, which may extend green material mandates from public to large-scale private developments without grandfathering existing inventory.
Market Dynamics
Taiwan's floor covering market is being fundamentally restructured by the Environmental Protection Administration's tightening VOC emission standards, which are systematically disqualifying uncertified suppliers from public procurement channels and forcing rapid reformulation of adhesive and substrate chemistries across the supply base.
Growth Catalysts
- Green Building Material Label mandates:Taiwan's Ministry of Interior requires certified flooring on all public works above threshold contract values, creating guaranteed demand pull for compliant manufacturers.
- Residential tower densification:High-rise construction in Greater Taipei and Taichung is accelerating specification-grade procurement for acoustic-dampening engineered products.
- Formaldehyde emission reclassification:GB/T 39600-2021 E0 and ENF-grade standards are compressing import competition from uncertified regional suppliers.
Market Restraints
- Petrochemical input volatility:Vinyl resin and laminate substrate costs fluctuate with Taiwan's naphtha import exposure, compressing margin predictability for calendering operations.
- Testing protocol backlog:Bureau of Standards, Metrology and Inspection compliance queues extend customs clearance timelines for foreign material imports.
- Natural stone substitution:Porcelain tile retains dominant share in ground-floor and basement specifications across Taiwan's humid subtropical climate zones.
Strategic Opportunities
- Kaohsiung industrial corridor retrofit:Aging manufacturing facilities in southern Taiwan present untapped demand for rapid-install vinyl systems with minimal downtime.
- Healthcare facility expansion:Hospital and long-term care construction is creating specification windows for antimicrobial surface technologies.
- Cross-strait certification alignment:Harmonization prospects between Taiwan's Green Building Material Label and mainland China's green product standards could streamline supplier access.
Industry Challenges
- Skilled installation labor scarcity:Commercial-grade seam welding and moisture-barrier specification require certified technicians that outpace vocational training output in Greater Taipei.
- Legacy inventory stranding risk:Pending building energy conservation code revisions may render existing non-compliant stock unsellable without grandfathering provisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Floor Covering Market |
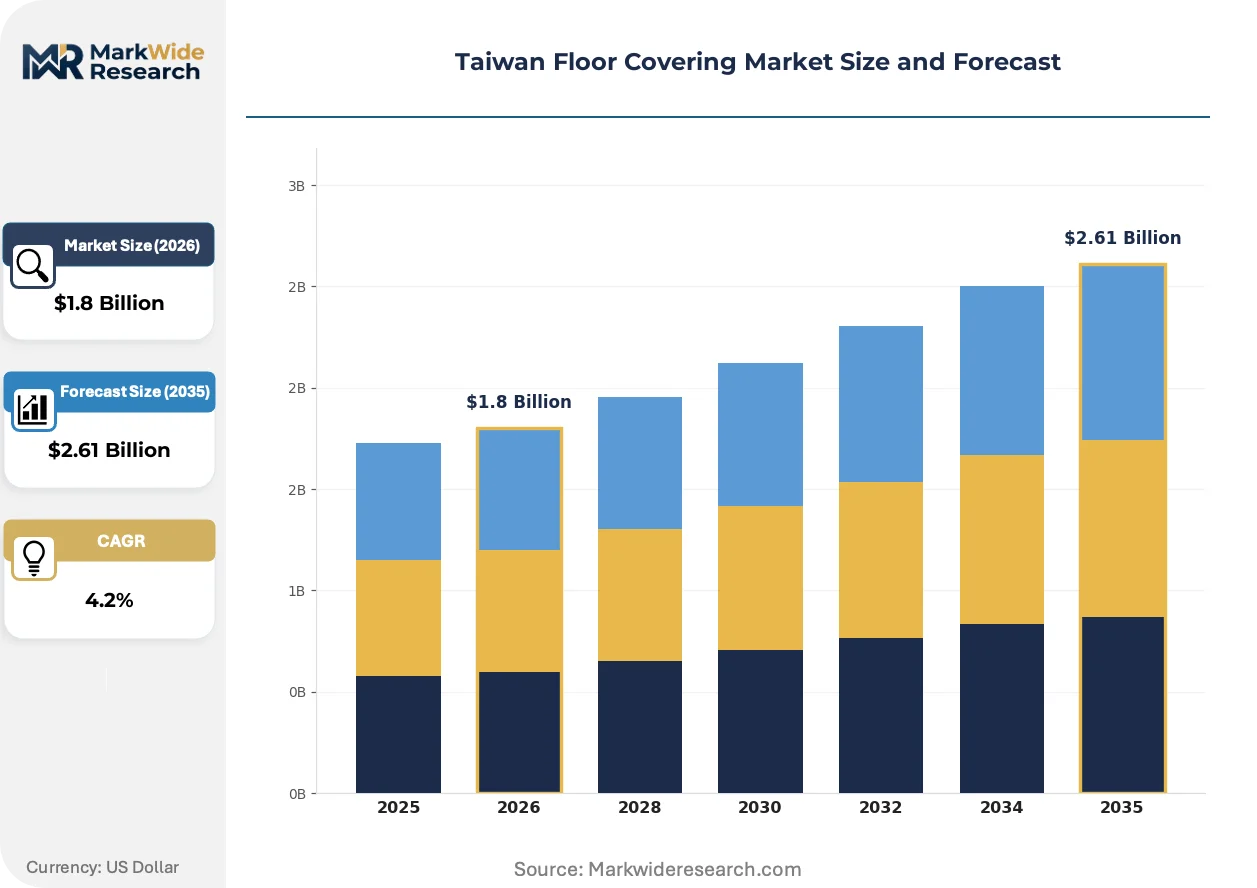
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpet, Vinyl, Tile, Laminate Material: Polypropylene, Natural Fiber, PVC, Wood End User: Residential, Commercial, Industrial, Hospitality Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Formosan United Corporation, Taiwan Her Sheng Industrial Co.Ltd., Lien Hwa Industrial Corp., Green Building Material Corporation, WINNER FLOOR Ltd., Everwood Ltd., Pacific Hardwood Flooring, HOURM ENG Industry, TAIWAN ENAMELWARE COMPANY LIMITED, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Floor Covering Market Evolving Landscape
Material science advances and procurement digitization are compressing traditional specification cycles while regulatory chemistry constraints are forcing concurrent reformulation across adhesive, substrate, and wear-layer technologies.
Digital printing technology is miniaturizing production run minimums for wood-grain visual authenticity in laminate and vinyl plank formats. Mid-market residential developers in Taoyuan and New Taipei are adopting these systems for customized lobby and common-area finishes. This capability is compressing the traditional six-to-eight-week import lead time for specialty aesthetic specifications.
Taiwan's Environmental Protection Administration indoor air quality standards are systematically elevating formaldehyde and VOC testing stringency for installed flooring materials. The Bureau of Standards, Metrology and Inspection maintains batch-release protocols that foreign suppliers struggle to navigate without local testing partnerships. Commercial retrofit contractors are responding by consolidating procurement around domestic distributors with established compliance documentation workflows.
Building information modeling integration is reshaping how flooring specifications flow from architect to contractor to supplier. Hospital and school consortia in Greater Taipei are requiring digital material libraries with embedded environmental product declarations before bid consideration. This behavioral shift is most visible in public works where green building certification points depend on traceable supply chain documentation.
Taiwan Floor Covering Market Segmentation
Taiwan's floor covering segmentation reflects regulatory chemistry mandates and climate-driven material selection. Procurement patterns bifurcate between public works requiring Green Building Material Label certification and private residential projects optimizing for moisture resistance in humid subtropical conditions.
Product Type:
Taiwan's Environmental Protection Administration indoor air quality standards create divergent compliance pathways across surface categories, with VOC emission thresholds and formaldehyde classifications determining specification eligibility on public contracts.
- Vinyl:Homogeneous and heterogeneous sheet systems manufactured through calendering processes dominate Taiwan's commercial retrofit and healthcare sectors. Greater Taipei hospital consortia specify welded-seam vinyl for infection control, while Kaohsiung industrial facilities prioritize rapid-install plank formats to minimize production downtime.
- Tile:Porcelain and ceramic surfaces retain specification dominance in ground-floor and basement applications across Taiwan's humid subtropical climate zones. Moisture resistance and thermal mass properties anchor demand in Taichung residential towers and Tainan commercial developments where natural stone aesthetics command premium positioning.
- Laminate:High-density fiberboard core products with melamine wear layers serve mid-market residential towers in New Taipei and Taoyuan where wood-grain visual authenticity intersects with price sensitivity. GB/T 39600-2021 E0 and ENF-grade certification requirements compress import competition.
- Carpet:Broadloom and modular tile systems concentrate in hospitality and corporate office segments within Taipei City's central business district. Acoustic dampening specifications and rapid replacement cycles drive procurement through specialized commercial distributors.
Established volume favors tile; emerging adoption favors vinyl.
Material:
Feedstock chemistry and certification trajectories segment Taiwan's supply base between petrochemical-derived synthetics and regulated natural substrates.
- PVC:Suspension and emulsion polymerization resins form the backbone of Taiwan's vinyl flooring manufacturing, with naphtha import exposure creating margin volatility for calendering operations. The Bureau of Standards, Metrology and Inspection maintains batch-release testing protocols that domestic compounders navigate more efficiently than foreign suppliers.
- Wood:Engineered substrates—high-density fiberboard and oriented strand board—supply laminate core production, with formaldehyde emission reclassification under GB/T 39600-2021 forcing reformulation of adhesive chemistries. Captive resin production capabilities differentiate integrated domestic manufacturers.
- Polypropylene:Solution-dyed synthetic fibers serve commercial carpet applications requiring stain resistance and colorfastness in high-traffic hospitality environments.
- Natural Fiber:Wool and sisal surfaces occupy niche premium positioning in boutique hotel and executive office specifications where tactile aesthetics override maintenance considerations.
Petrochemical feedstocks dominate volume; certified low-emission wood substrates are climbing the fastest.
End User:
Project scale and certification mandates concentrate procurement behavior across Taiwan's construction verticals.
- Residential:High-rise tower densification in Greater Taipei and Taichung accelerates specification-grade engineered flooring for acoustic dampening. Renovation activity in aging urban stock drives replacement demand for vinyl and laminate systems.
- Commercial:Office and retail fit-outs in Taipei's central business district prioritize rapid-install modular systems with embedded environmental product declarations for green building certification points.
- Hospitality:Hotel construction and renovation in Kaohsiung's tourism corridor creates specification windows for premium surface aesthetics combined with durability warranties.
- Industrial:Manufacturing facility flooring in Taoyuan and Taichung science parks demands chemical resistance and static control properties for cleanroom and assembly environments.
Residential renovation sustains baseline volume; healthcare and hospitality construction offers steepest expansion trajectory.
Distribution Channel:
Compliance documentation requirements and project scale determine channel selection across Taiwan's procurement landscape.
- Wholesale:Specialized flooring distributors with established Bureau of Standards, Metrology and Inspection documentation workflows consolidate commercial and public works procurement. Consolidated buying power and specification support services anchor relationships with Taiwan's largest construction consortia.
- Direct Sales:Manufacturer-direct relationships dominate large-scale hospital, school, and government projects above threshold contract values where Green Building Material Label certification and chain-of-custody documentation are mandatory.
- Retail:Home center and specialty store channels serve residential renovation and small-scale commercial replacement demand in urban and suburban markets.
- Online:Digital procurement platforms are compressing lead times for standardized vinyl plank and laminate products in residential segments, though compliance documentation limitations restrict penetration in certified public works.
Wholesale and direct sales capture specification-grade volume; online channels are gaining share fastest in residential replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration in Taiwan's floor covering market clusters around public works procurement officers, commercial construction consortia, and residential tower developers across five distinct metropolitan zones. Each sub-region exhibits divergent specification priorities shaped by local climate conditions, industrial base, and regulatory enforcement intensity.
Greater Taipei
Hospital and school construction consortia in Taipei City drive specification-grade procurement for welded-seam vinyl and acoustic-engineered systems. The Environmental Protection Administration's indoor air quality standards receive strictest enforcement here, compressing supplier eligibility to Green Building Material Label holders. New Taipei residential towers prioritize rapid-install laminate formats with E0-grade certification.
Taichung
Science park manufacturing facilities and mid-market residential densification create dual demand vectors for chemical-resistant industrial flooring and price-sensitive engineered wood. The Ministry of Interior's green building mandates apply to expanding public university and municipal hospital footprints. Tile retains basement specification dominance due to humidity exposure.
Kaohsiung
Aging industrial corridor retrofits generate replacement demand for minimal-downtime vinyl plank systems across former manufacturing zones. Tourism sector hotel renovation concentrates specification activity near the harbor district. The Bureau of Standards, Metrology and Inspection maintains southern Taiwan testing facilities that accelerate compliance documentation for regional distributors.
Taoyuan
Airport-adjacent logistics and hospitality construction creates specification windows for premium surface aesthetics combined with durability warranties. Residential tower development in this northern corridor adopts digital-print laminate systems for customized common-area finishes. Proximity to Taipei procurement networks enables faster compliance documentation workflows.
Tainan
Heritage district commercial restoration and ground-floor retail fit-outs sustain porcelain tile demand despite laminate encroachment in upper floors. Humid subtropical conditions reinforce moisture-resistant material specifications across all building classes. Local construction consortia exhibit stronger price sensitivity than Taipei-based counterparts.
Taiwan Floor Covering Market Competitive Landscape
Player mix skews toward integrated domestic manufacturers with captive substrate production and specialized distributors holding established compliance documentation workflows. Market structure exhibits moderate consolidation around construction consortia relationships rather than scale-driven concentration. Three archetypes dominate: vertically integrated resin-to-plank laminate producers, exclusive green-label vinyl distributors, and legacy construction network anchors. Competitive moves center on certification pre-positioning ahead of pending building code revisions and consolidation of testing partnership networks to accelerate customs clearance.
Among Taiwan-based integrated manufacturers, Formosan United Corporation and Lien Hwa Industrial Corp. occupy positions reflecting decades-long construction industry embeddedness. Green Building Material Corporation exemplifies the certification-specialist archetype through exclusive distribution relationships. These three entities represent distinct competitive vectors: captive upstream control, consortia relationship depth, and regulatory compliance exclusivity.
| Leading Market Players |
|---|
| Formosan United Corporation |
| Taiwan Her Sheng Industrial Co.Ltd. |
| Lien Hwa Industrial Corp. |
| Green Building Material Corporation |
| WINNER FLOOR Ltd. |
| Everwood Ltd. |
| Pacific Hardwood Flooring |
| HOURM ENG Industry |
| TAIWAN ENAMELWARE COMPANY LIMITED |
| Others |
Value Network & Pricing Analysis
Six-to-eight-week import lead times for specialty laminate finishes compress pricing power toward domestic distributors with established Bureau of Standards, Metrology and Inspection documentation workflows. Taiwan's naphtha import exposure for vinyl resin feeds directly into margin volatility for calendering operations, while construction consortia consolidation strengthens volume-based negotiation leverage.
Pricing Analysis
Cost-plus contracts indexed to Taiwan's naphtha import benchmarks dominate vinyl compounder agreements with downstream calendering operations. Three-tier pricing structure across premium, standard, and economy levels separates Green Building Material Label-certified systems from uncertified imports and commodity-grade alternatives. Price differentiation hinges on certification tier and volume scale, with public works procurement mandating premium-grade documentation. Pricing pressure stems from petrochemical input volatility, compressing margin predictability for mid-tier manufacturers. Residential renovation buyers exhibit highest price sensitivity, while hospital consortia prioritize compliance over cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate Greater Taipei commercial retrofit contractors, while strategic stockpiling of certified laminate substrates anchors specification-grade project bidding. Taiwan's vinyl manufacturing draws from naphtha imports originating in South Korea, Japan, and Singapore, with high-density fiberboard cores sourced from domestic engineered wood producers and select Malaysian suppliers. Single-source vulnerability concentrates in Bureau of Standards, Metrology and Inspection testing partnerships, where foreign suppliers without local documentation workflows face extended customs clearance. Distribution runs through specialized wholesale distributors with established compliance documentation networks serving construction consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan's floor covering market exhibits accelerating buyer power concentration as hospital and school construction consortia consolidate procurement around certified distributors with embedded compliance workflows.
For Market Incumbents: Compound certification pre-positioning advantages by deepening captive resin production capabilities ahead of pending building energy conservation code revisions. Secure exclusive testing partnerships with Bureau of Standards, Metrology and Inspection facilities to accelerate customs clearance timelines for strategic substrate imports. Vertical integration into high-density fiberboard core manufacturing defends margin position against formaldehyde emission reclassification pressures. For New Entrants and Emerging Players: Rapid-install vinyl system deployment for Kaohsiung industrial corridor retrofits represents the most penetrable white-space opportunity, where aging manufacturing facilities demand minimal-downtime flooring replacement. Antimicrobial surface technology for healthcare facility expansion offers specification-grade entry with lower certification barrier than public works mandates. Go-to-market execution should anchor on digital material libraries with embedded environmental product declarations required by Taipei hospital consortia. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified construction material parents with under-optimized flooring divisions lacking Green Building Material Label certification infrastructure. Long-term viability centers on regulatory compliance capability rather than scale, favoring acquisition of specialized distributors with established documentation workflows over commodity manufacturers. Watch for Bureau of Standards, Metrology and Inspection queue length expansion as inflection indicator for compliance-documentation scarcity value.| Strategic Initiative | Industry Significance |
|---|---|
| Green Building Material Label Certification Investment | Secures procurement eligibility on Taiwan public works above threshold contract values. |
| Captive Resin Production Expansion | Controls laminate core quality from source through finished plank against GB/T 39600-2021 standards. |
| Testing Partnership Network Consolidation | Accelerates Bureau of Standards, Metrology and Inspection batch-release protocols for foreign material imports. |
| Digital Material Library Development | Meets Building Information Modeling integration requirements from Taipei hospital and school consortia. |
| Antimicrobial Surface Technology Licensing | Captures specification windows in Taiwan healthcare facility expansion and long-term care construction. |
Research Methodology
Initial hypotheses were tested against primary input from flooring procurement managers at hospital consortia, commercial construction project directors, vinyl calendering plant managers, laminate manufacturing R&D leads, and wholesale distribution channel heads, and refined through secondary validation against Taiwan Environmental Protection Administration indoor air quality standards, Ministry of Interior Green Building Material Label databases, Bureau of Standards, Metrology and Inspection compliance protocols, customs import records, and construction industry association publications. Bottom-up volume estimates from product-level shipment data were triangulated against top-down market sizing derived from construction completion statistics.
Variance decomposition across the projection horizon isolates regulatory mandate impact, petrochemical input cost fluctuation, and buyer consolidation effects from baseline replacement demand. Segmentation dimensions modeled include product type, material feedstock, end-user vertical, and distribution channel, with certification tier treated as a cross-cutting attribute. CAGRs were derived from regression-adjusted trend extrapolation incorporating Environmental Protection Administration enforcement intensity indices and Ministry of Interior green building mandate expansion scenarios.
Forecasts assume regulatory continuity in Taiwan's indoor air quality and green building material regimes; material policy shifts would require re-modeling. Specific risks include pending building energy conservation code revisions without grandfathering provisions and Bureau of Standards, Metrology and Inspection testing capacity constraints. Revision becomes warranted when construction consortia procurement consolidation crosses concentration thresholds that alter distributor negotiation dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Europe Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
US Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Asia Pacific Flooring Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
United Kingdom Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
GCC Floor Covering Market
Flooring, Carpets, and Rugs
Resilient Flooring Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Europe Vinyl Flooring Market
Flooring, Carpets, and Rugs
China Laminate Flooring Market
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market
Flooring, Carpets, and Rugs
Europe Carpet Tile Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
India Vinyl Flooring Market
Flooring, Carpets, and Rugs
Bamboo Flooring Market