
 Africa Pea Protein Market | 2026-2036
Africa Pea Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Pea Protein Market Outlook
Ingredient formulation services is tilting toward value-added technical support as manufacturers seek customized emulsion stability and flavor masking solutions. Roquette Frères leverages its European extraction expertise to supply isolate grades for African beverage applications. Cargill Incorporated anchors regional distribution through its existing oilseed and grain infrastructure across the continent. Kerry Group plc differentiates with integrated taste and nutrition systems that combine pea protein with masking technologies.
Pea protein denotes the dried, dehulled, and processed protein fraction derived from Pisum sativum, typically containing 80-90% protein by dry weight in isolate form, extracted via wet fractionation and spray-dried into functional powders for binding, emulsification, and gelation in formulated foods. The concentrate segment dominates current import volumes due to lower unit costs and adequate functionality for bakery and meat extension applications. Isolate grades command premium positioning in nutritional supplements and high-protein beverages where solubility and minimal flavor carryover determine purchasing decisions. Textured pea protein is gaining traction among food manufacturers developing whole-muscle analogues for the expanding African flexitarian consumer base.
South Africa's Department of Health enforces protein content labeling standards that mandate minimum thresholds for products bearing "high protein" claims, directly influencing concentrate versus isolate procurement ratios. The country's National Regulator for Compulsory Specifications and Kenya's Kenya Bureau of Standards both scrutinize imported plant protein for heavy metal limits and microbial specifications, creating compliance barriers for non-certified suppliers. FSSAI-aligned importers in Nigeria and Ghana are adopting Codex Alimentarius protein quality metrics ahead of anticipated harmonization across the African Continental Free Trade Area. Stakeholders must monitor which national standards body moves first to mandate digestibility-corrected amino acid scoring as the definitive quality benchmark.
Market Dynamics
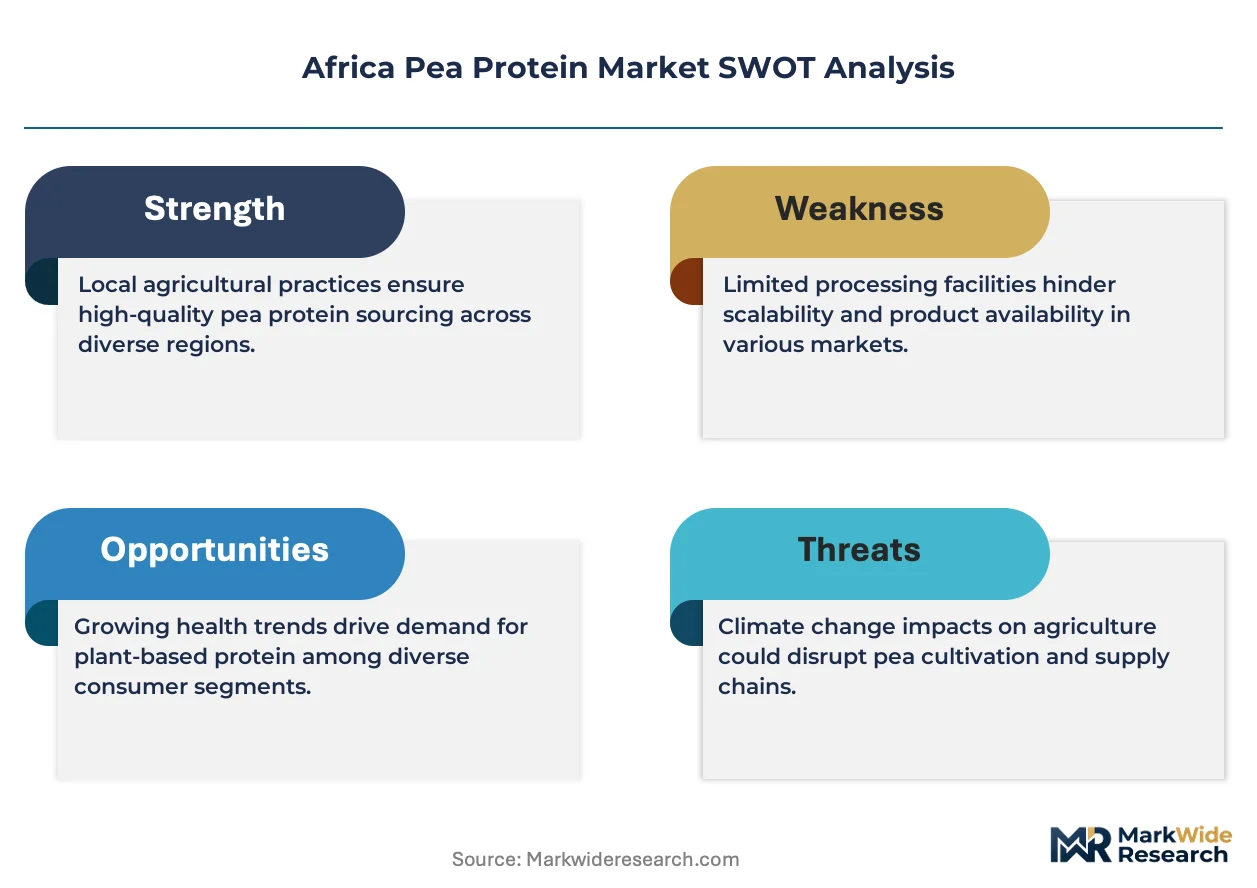
Formulation labs in Gauteng Province are compressing product development cycles as Johannesburg-based manufacturers build captive pulse-processing capabilities, shifting procurement from imported concentrates toward locally blended isolates with customized emulsion profiles.
Growth Catalysts
- Flexitarian dietary shifts:South African retail chains are absorbing rising volumes of pea protein isolate for plant-based dairy alternatives, creating pull-through demand for higher-grade functional ingredients.
- Tightening protein labeling standards:The country's Department of Health mandates minimum thresholds for "high protein" claims, forcing manufacturers toward isolate grades that meet digestibility-corrected amino acid scoring requirements.
- Pulse fractionation infrastructure:Wet extraction and spray-drying investments in Gauteng are reducing reliance on European supply chains for beverage-grade isolates.
Market Restraints
- Heavy metal compliance barriers:Kenya Bureau of Standards scrutiny of imported plant protein for cadmium and lead limits blocks non-certified suppliers from East African entry.
- Concentrate-isolate cost spread:The 40-60% unit cost premium for isolate grades constrains adoption in price-sensitive bakery and meat extension applications.
- Single-source extraction technology:Wet fractionation equipment for 80%+ protein isolates concentrates among European and North American vendors, creating procurement bottlenecks.
Strategic Opportunities
- Nigeria and Ghana FSSAI alignment:Codex Alimentarius protein quality metric adoption ahead of African Continental Free Trade Area harmonization creates first-mover certification advantages.
- Whole-muscle analogue development:Textured pea protein applications for flexitarian consumers remain underdeveloped outside South Africa's major urban centers.
- Integrated taste-nutrition systems:Convergence of pea protein with flavor masking technologies enables premium positioning in high-protein beverages.
Industry Challenges
- Formulation chemistry expertise scarcity:Emulsion stability and gelation optimization for pulse-derived ingredients requires food scientists with specialized hydrocolloid experience.
- Multi-jurisdiction certification timelines:Separate heavy metal and microbial testing protocols across South Africa's NRCS, Kenya's KEBS, and Nigeria's NAFDAC extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Pea Protein Market |
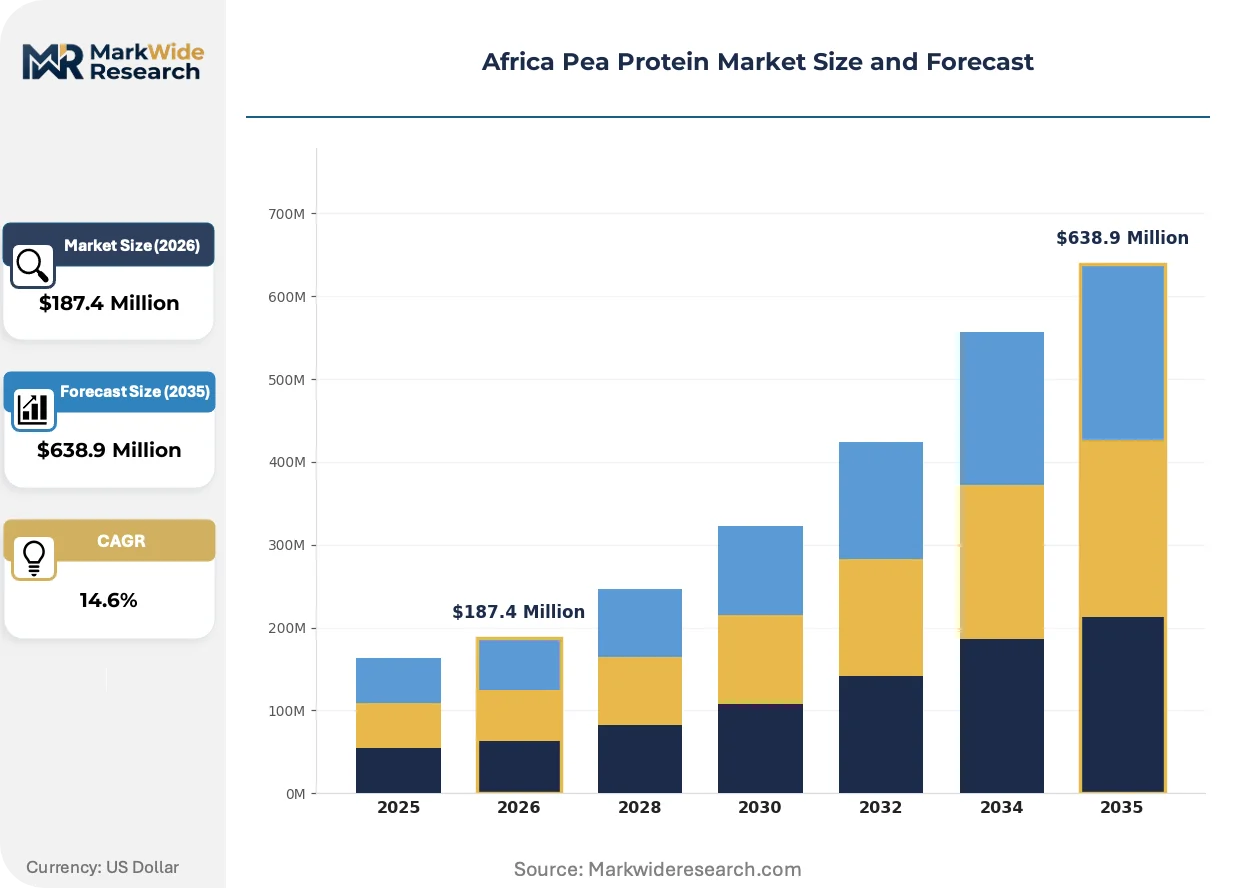
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
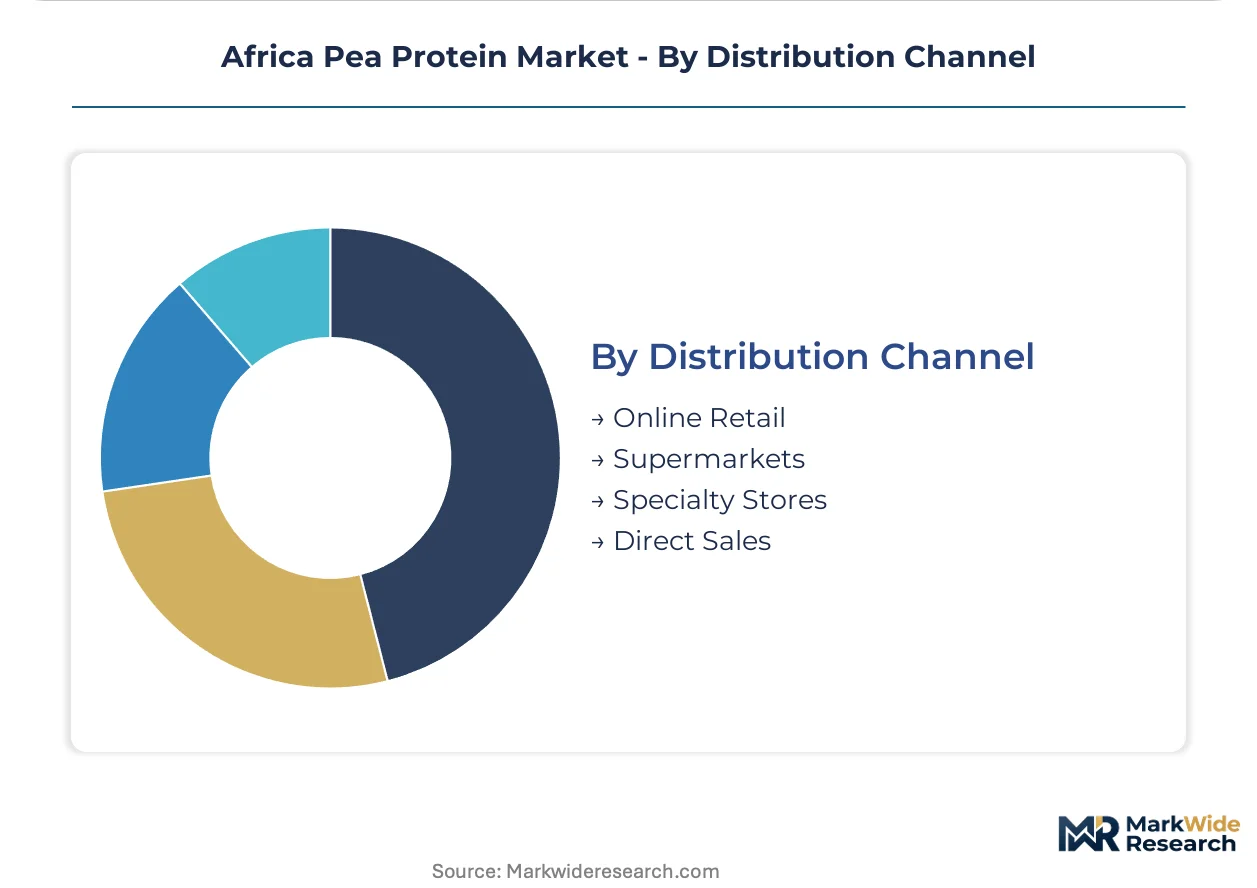
| Segmentation | Product Type: Concentrate, Isolate, Textured, Hydrolysate Application: Food & Beverages, Nutritional Supplements, Animal Feed, Bakery End User: Food Manufacturers, Fitness Centers, Pet Food Producers, Health Stores Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Cargill Incorporated, Roquette Frères, Ingredion Incorporated, The Scoular Company, Burcon NutraScience, Glanbia PLC, DuPont de Nemours, Cosucra Groupe Warcoing SA, Kerry Group plc, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Pea Protein Market Strategic Shifts
Digital twin modeling of extraction parameters is compressing pilot-scale validation timelines, while regulatory pressure on protein quality disclosures accelerates grade differentiation across import portfolios.
Precision fermentation-derived protein fractions are virtualizing traditional wet fractionation economics by enabling recombinant production of Pisum sativum analogues with tailored amino acid profiles. South African beverage manufacturers are piloting these inputs for solubility-critical applications. The technology is virtualizing capital allocation decisions by reducing spray-drying infrastructure requirements.
South Africa's Department of Health labeling requirements for protein content claims are tightening compliance standards that mandate minimum thresholds for "high protein" declarations. This forces importers to source isolate grades rather than concentrates for premium positioning. Nutritional supplement and high-protein beverage segments are responding by consolidating procurement around FSSAI-aligned suppliers with digestibility-corrected amino acid scoring documentation.
Direct manufacturer-to-formulator relationships are displacing traditional ingredient distributor networks as Gauteng-based food manufacturers build dedicated pulse-derived ingredient labs. Technical service unbundling is replacing standard concentrate sales with customized emulsion stability and flavor masking support contracts. This pattern concentrates most visibly in Johannesburg's specialty nutrition and plant-based dairy formulation clusters.
Africa Pea Protein Market Segmentation
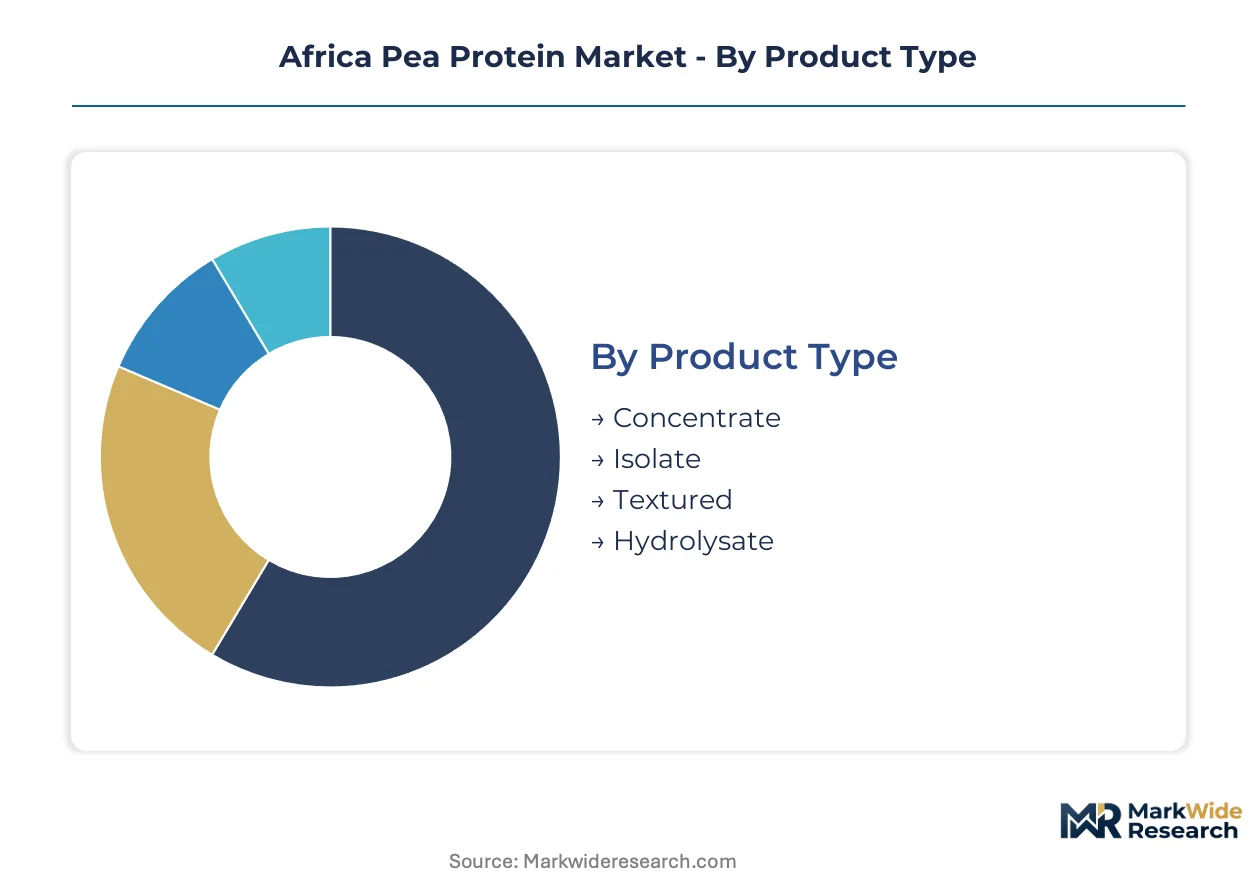
Pea protein procurement patterns across Africa diverge sharply by functional grade and end-use application, with regulatory compliance thresholds and formulation complexity driving premiumization in isolate grades while concentrate maintains volume dominance in cost-sensitive segments.
Product Type:
After-sales technical support intensity escalates dramatically from commodity concentrates through engineered isolates, with beverage-grade specifications demanding dedicated emulsion stability troubleshooting and flavor masking consultation that commodity grades rarely require.
- Concentrate:Typically 50-80% protein by dry weight, produced through dry fractionation without intensive wet processing. Gauteng Province food manufacturers absorb rising volumes for bakery and meat extension applications where solubility requirements remain modest. Kenya Bureau of Standards heavy metal screening creates compliance friction for non-certified suppliers targeting East African price-sensitive buyers.
- Isolate:Wet fractionation yields 80-90% protein content with superior solubility and minimal flavor carryover. Johannesburg formulation labs specify isolate grades for plant-based dairy alternatives and high-protein beverages where South Africa's Department of Health labeling mandates minimum thresholds for "high protein" claims. Digestibility-corrected amino acid scoring documentation determines supplier qualification.
- Textured:Extruded protein structures mimicking whole-muscle fiber orientation for flexitarian meat analogues.
- Hydrolysate:Enzymatically pre-digested fractions with reduced allergenicity for specialized nutritional applications.
By volume, Concentrate leads. By growth pace, Isolate is ahead.
Application:
Cost tier stratification separates commodity feed applications from premium beverage formulations, with protein quality disclosure requirements widening the procurement gap between basic and advanced grades.
- Food & Beverages:Plant-based dairy alternatives in South African retail chains absorb rising isolate volumes, while beverage manufacturers pilot precision fermentation-derived fractions for solubility-critical applications. Roquette Frères supplies European-extracted isolates for African beverage applications.
- Nutritional Supplements:Sports nutrition and clinical nutrition segments consolidate procurement around FSSAI-aligned suppliers with amino acid scoring documentation. Cargill Incorporated anchors regional distribution through existing oilseed infrastructure.
- Animal Feed:Compound feed manufacturers utilize lower-cost concentrate grades for protein fortification.
- Bakery:Bread and pastry applications favor concentrate functionality for dough conditioning and volume extension.
Food & Beverages commands the largest revenue pool. Nutritional Supplements climbs the fastest.
End User:
Customer type determines technical service bundling, with food manufacturers demanding integrated formulation support while retail channels prioritize supply reliability and certification documentation.
- Food Manufacturers:Johannesburg-based formulators build captive pulse-processing capabilities, shifting from imported concentrates toward locally blended isolates with customized emulsion profiles. Kerry Group plc differentiates with integrated taste and nutrition systems combining pea protein with masking technologies.
- Fitness Centers:Direct procurement of bulk supplements drives concentrate demand for protein fortification.
- Pet Food Producers:Premium pet nutrition segments adopt textured pea protein for digestibility and allergen management.
- Health Stores:Retail channel consolidation around certified organic and non-GMO isolate SKUs.
Food Manufacturers dominate procurement volume. Fitness Centers expand most quickly.
Distribution Channel:
Supply concentration in European extraction technology vendors shapes channel economics, with direct manufacturer relationships displacing traditional distributor networks for technical grades.
- Online Retail:E-commerce platforms aggregate niche isolate SKUs for nutritional supplement consumers across Nigeria and Ghana, with FSSAI-aligned importers adopting Codex Alimentarius metrics ahead of African Continental Free Trade Area harmonization.
- Supermarkets:South African retail chains drive volume absorption for plant-based dairy alternatives, with procurement consolidating around suppliers meeting National Regulator for Compulsory Specifications requirements.
- Specialty Stores:Health food and sports nutrition retailers curate premium isolate assortments.
- Direct Sales:Technical ingredient contracts link extraction specialists directly to Gauteng formulation labs.
Supermarkets move the most tonnage. Online Retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Africa diverge sharply by regulatory maturity and formulation capability. South Africa absorbs premium isolate grades for beverage applications while East African markets remain tethered to concentrate volumes constrained by compliance barriers.
South Africa
Johannesburg-based food manufacturers drive isolate demand for plant-based dairy alternatives in national retail chains. The Department of Health mandates minimum protein thresholds for "high protein" claims, forcing procurement toward digestibility-corrected amino acid scoring documentation. Gauteng Province formulation labs are compressing product development cycles through captive pulse-processing investments.
Nigeria
Lagos and Abuja importers consolidate procurement around FSSAI-aligned suppliers ahead of African Continental Free Trade Area harmonization. The country's national food safety regulator is adopting Codex Alimentarius protein quality metrics, creating certification advantages for early movers. Health store retail channels in Lagos metropolitan area are curating premium isolate SKUs for nutritional supplement consumers.
Kenya
Nairobi-based compound feed manufacturers absorb concentrate grades for protein fortification applications. The Kenya Bureau of Standards scrutinizes imported plant protein for cadmium and lead limits, blocking non-certified suppliers from East African market entry. Industrial clusters in the Rift Valley are piloting textured pea protein for emerging flexitarian meat analogue development.
Ghana
Accra's fitness center segment drives bulk supplement procurement of lower-cost concentrate grades. The country's food safety authority mirrors FSSAI alignment patterns, accelerating Codex metric adoption for protein quality disclosure. Online retail platforms aggregate niche isolate SKUs for nutritional consumers across Greater Accra and Ashanti Region.
Egypt
Cairo-based bakery manufacturers favor concentrate functionality for dough conditioning and volume extension applications. The country's national standards body maintains heavy metal screening protocols that create compliance friction for non-certified import sources. Alexandria port logistics clusters are consolidating as entry points for European-extracted pea protein shipments.
Africa Pea Protein Market Competitive Environment
Capability concentration sits with European extraction specialists; scale advantage sits with diversified agribusiness conglomerates with existing continental distribution infrastructure. The vendor base stratifies across three tiers: wet fractionation technology owners, integrated taste-nutrition system providers, and commodity traders with oilseed infrastructure leverage. Dominant competitive moves include strategic partnerships with Gauteng formulation labs and technology licensing agreements for spray-drying equipment access.
Within the extraction technology tier, Roquette Frères and Cosucra Groupe Warcoing SA represent European wet fractionation capability. Among integrated solution providers, Kerry Group plc occupies a position combining pea protein with masking technologies. Cargill Incorporated anchors the scale-driven commodity distribution archetype through existing oilseed and grain infrastructure across the continent.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Roquette Frères |
| Ingredion Incorporated |
| The Scoular Company |
| Burcon NutraScience |
| Glanbia PLC |
| DuPont de Nemours |
| Cosucra Groupe Warcoing SA |
| Kerry Group plc |
| Others |
Value Chain & Pricing Dynamics
European wet fractionation equipment vendors anchor upstream supply, concentrating margin capture in isolate grades while Gauteng-based formulators absorb cost premiums for customized emulsion stability. This concentration transfers pricing power downstream to extraction technology owners and away from commodity concentrate traders.
Pricing Analysis
Long-term offtake contracts dominate procurement between Johannesburg formulation labs and European extraction specialists, locking in isolate grade supply for beverage applications. Price differentiation rests on certification grade—FSSAI-aligned suppliers with digestibility-corrected amino acid scoring command premiums over non-certified concentrate sources. Pricing pressure stems from the 40-60% unit cost spread between isolate and concentrate tiers, compressing margins in price-sensitive bakery and meat extension segments. Food manufacturers in Gauteng Province show least price sensitivity for beverage-grade isolates, while Kenyan compound feed buyers remain tethered to lowest-cost concentrate options.
Supply Chain Analysis
Yellow pea feedstock draws from France, Canada, and Ukraine as dominant cultivation zones, with protein content variability influencing extraction yields. Wet fractionation equipment, spray-drying infrastructure, and flavor masking technology form critical input dependencies. Single-source vulnerability concentrates in European and North American vendors controlling 80%+ protein isolate extraction technology. Distribution runs through direct manufacturer-to-formulator relationships displacing traditional distributor networks for technical grades, while commodity concentrates flow via Cargill's existing oilseed infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation-derived protein fractions threaten incumbent pea protein positioning in solubility-critical beverage applications, forcing traditional extraction players to defend functional grade differentiation.
For Market Incumbents: Harden isolate grade positioning through captive spray-drying investments in Gauteng Province, reducing European supply chain dependency. Secure FSSAI-aligned certification documentation ahead of African Continental Free Trade Area harmonization to block precision fermentation substitutes from premium positioning. Backward integration into local pulse processing anchors margin control against commodity concentrate traders. For New Entrants and Emerging Players: Build out textured pea protein supply for whole-muscle analogue applications in Kenya's Rift Valley and Nigeria's Lagos metropolitan area, where flexitarian demand outpaces formulation capability. Target fitness center bulk supplement channels in Ghana's Greater Accra region with lower-cost concentrate grades. Differentiate through integrated taste-nutrition systems bundling flavor masking with protein supply. For Investors and Strategic Acquirers: Secondary-cycle assets sit with European extraction specialists holding wet fractionation technology licenses but lacking African distribution infrastructure. Five-to-ten year viability hinges on regulatory momentum toward digestibility-corrected amino acid scoring mandates. Monitor which national standards body—South Africa's Department of Health, Kenya Bureau of Standards, or Nigeria's NAFDAC—first mandates protein quality disclosure as the inflection signal for isolate grade premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Pulse-Processing Investment | Gauteng formulation labs compress development cycles through in-house wet extraction capability. |
| FSSAI Alignment Certification | Early Codex metric adoption creates competitive moats ahead of AfCFTA harmonization requirements. |
| Integrated Taste-Nutrition Systems | Kerry Group plc's masking technology bundling commands premium positioning in high-protein beverages. |
| Direct Manufacturer Relationships | Roquette Frères bypasses distributors to supply Johannesburg labs with European-extracted isolates. |
| Textured Protein Capacity Buildout | Extrusion infrastructure for whole-muscle analogues targets underdeveloped flexitarian segments outside South Africa. |
Study Parameters
Initial hypotheses were tested against primary input from food formulation scientists, procurement managers at Gauteng-based manufacturers, regulatory affairs specialists at national standards bodies, and distribution channel partners across Nigeria and Kenya, then refined against secondary validation. Trade flow databases, customs records for pea protein concentrate and isolate shipments, National Regulator for Compulsory Specifications filings, and FSSAI-aligned importer documentation provided quantitative grounding. Bottom-up segmentation modeling triangulated against top-down market sizing from extraction technology vendor capacity disclosures.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with volume forecasts derived from Gauteng formulation lab expansion timelines and isolate grade procurement ratios. Segmentation dimensions modeled include product type tier, application intensity, end-user technical service requirements, and distribution channel structure. CAGRs were computed from import volume trajectories and local production capacity buildout schedules. Precision fermentation technology maturation curves and regulatory adoption timelines for protein quality disclosure formed industry-specific forecast inputs.
Stress conditions across European feedstock price volatility, AfCFTA harmonization timing, and precision fermentation cost reduction curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory momentum and technology substitution rates. Cross-checking against customs shipment data and extraction equipment order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
South America Soy Beverages Market
Plant Based Food
Vegan Oatmeal Market
Plant Based Food
Plant-Based Bacon Market
Plant Based Food
Plant Based Meat Market
Plant Based Food
Global Isolate Organic Soy Protein Market
Plant Based Food
Fava Bean Protein Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
China Pea Protein Market
Plant Based Food
United States Meat Substitutes Market
Plant Based Food
Fermented Plant Extracts Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
Plant-Based Sausages Market
Plant Based Food
Africa Soy Beverages Market
Plant Based Food
Plant Based Pork Market
Plant Based Food
North America Plant-Based Egg Market
Plant Based Food
United States Plant Protein Market