
 Invoice Factoring Market | 2026-2036
Invoice Factoring Market Size, Share, and Industry Trends Forecast 2026-2036
Invoice Factoring Market Analysis
The divergence between premium and commodity tiers is hardening in invoice factoring. Large-ticket, non-recourse arrangements with embedded credit insurance now command tighter spreads and dedicated servicing teams, while small-ticket spot transactions flow through automated platforms with minimal human intervention. RTS Financial anchors its position through transportation-sector specialization and captive broker networks. FundThrough competes on velocity, leveraging API integrations with accounting software to compress funding timelines. Kapitus extends its footprint across SBA-adjacent lending and equipment finance, cross-selling factoring to existing borrowers.
Invoice factoring is a receivables-financing mechanism wherein a business sells its outstanding invoices to a third party at a discount, typically advancing 70-90% of face value within 24-48 hours and remitting the reserve less fees upon debtor payment. Its primary commercial purpose is to accelerate cash conversion cycles for businesses with extended payment terms or seasonal revenue patterns. Recourse factoring dominates transaction volume due to lower risk premiums and simpler legal structures, though non-recourse factoring captures disproportionate margin pools where credit insurance layers add fee stacking. Online platforms as a funding source are displacing traditional bank-led arrangements among freelancers and small businesses, while banks retain primacy for large corporations with audited financials.
The US Office of the Comptroller of the Currency supervises national bank participation in factoring, while the UK's Financial Conduct Authority regulates peer-to-peer and platform-based funders under its consumer and wholesale lending frameworks. India's Reserve Bank governs non-banking financial company factoring through its scale-based regulatory regime, tightening capital adequacy for upper-tier lenders. Stakeholders must monitor how Basel III endgame proposals reshape bank capital treatment of purchased receivables, as this will redirect institutional liquidity between balance-sheet and distributed funding models.
Market Dynamics
Open banking APIs and real-time credit scoring are compressing underwriting cycles from weeks to hours, forcing traditional factoring houses to rebuild their technology stacks or cede small-ticket volumes to automated platforms.
Growth Catalysts
- Working capital stress among SMEs:Extended payment terms from large buyers are pushing mid-sized suppliers toward receivables financing as a liquidity bridge.
- RBI's scale-based NBFC regulations:India's tightened capital adequacy rules for upper-tier non-bank lenders are professionalizing the sector and attracting institutional capital.
- API-first origination:Direct integrations with accounting software and ERP systems are embedding factoring into routine treasury workflows.
Market Restraints
- Debtor concentration risk:Single-buyer dependency in transportation and construction sectors amplifies default exposure in recourse structures.
- Basel III endgame uncertainty:Pending bank capital treatment of purchased receivables is freezing institutional deployment into warehouse funding vehicles.
- Invoice fraud vectors:Synthetic invoicing and double-pledging of receivables require enhanced verification layers that add operational cost.
Strategic Opportunities
- Cross-border trade corridors:India-UK and India-US payment term mismatches create demand for multi-currency factoring with embedded FX hedging.
- Embedded finance partnerships:B2B marketplaces and procurement platforms are integrating advance payment features at invoice generation.
- Green receivables financing:EU Green Deal-linked credit enhancement programs are lowering funding costs for sustainable supply chain invoices.
Industry Challenges
- Legacy system integration:Mid-sized factors face technical debt when connecting modern API stacks to core banking platforms.
- Specialized credit underwriting talent:Shortage of professionals combining trade finance expertise with data science capabilities constrains automated model deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Invoice Factoring Market |
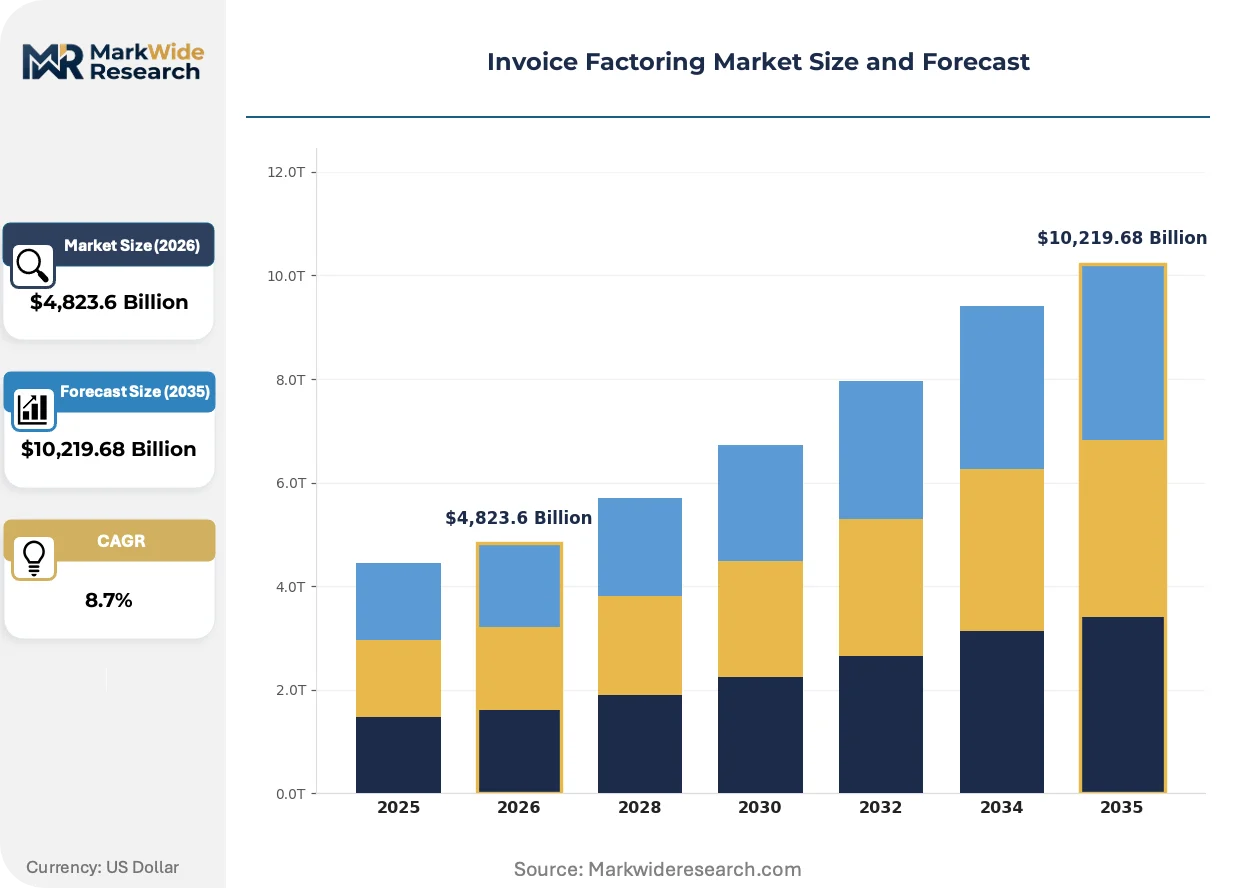
| Market Size in 2026 | $4,823.6 Billion |
| Market Size in 2035 | $10,219.68 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Recourse Factoring, Non-Recourse Factoring, Invoice Discounting, Spot Factoring Client Type: Small Businesses, Mid-Sized Enterprises, Freelancers, Large Corporations Invoice Type: Commercial Invoices, Government Invoices, Service Invoices, Retail Invoices Funding Source: Private Investors, Banks, Financial Institutions, Online Platforms |
| Companies Covered | RTS Financial, Kapitus, FundThrough, Viva Capital, Scale Funding, Riviera Finance, eCapital, Universal Funding Corporation, Triumph Business Capital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Invoice Factoring Market Emerging Trajectories
Artificial intelligence and distributed ledger technologies are rewriting how invoice authenticity gets verified and how funding liquidity gets distributed across fragmented supplier bases.
Machine learning models trained on payment behavior data are expanding into pre-shipment finance and purchase order funding, compressing the addressable market for traditional documentary trade products. Freight brokers and logistics operators are adopting these tools fastest, using cargo-tracking data as a secondary verification layer. The structural consequence is a blurring of boundaries between factoring, supply chain finance, and inventory lending.
The EU's Digital Operational Resilience Act is mandating granular risk-management frameworks for platform-based funders, forcing operational separation between origination and balance-sheet holding functions. UK-based peer-to-peer lenders must now maintain dedicated wind-down arrangements and client money segregation protocols. Smaller marketplace lenders are responding by seeking bank partnership structures rather than standalone licensing.
Buyer-led supply chain finance programs are displacing supplier-initiated factoring in sectors with concentrated procurement power, particularly automotive and retail. Large corporates are unbundling early payment offers from core banking relationships, sourcing liquidity through multi-funder platform structures. This pattern is most pronounced in the United States and Germany, where reverse factoring volumes now exceed traditional invoice discounting in several industrial verticals.
Invoice Factoring Market Segmentation
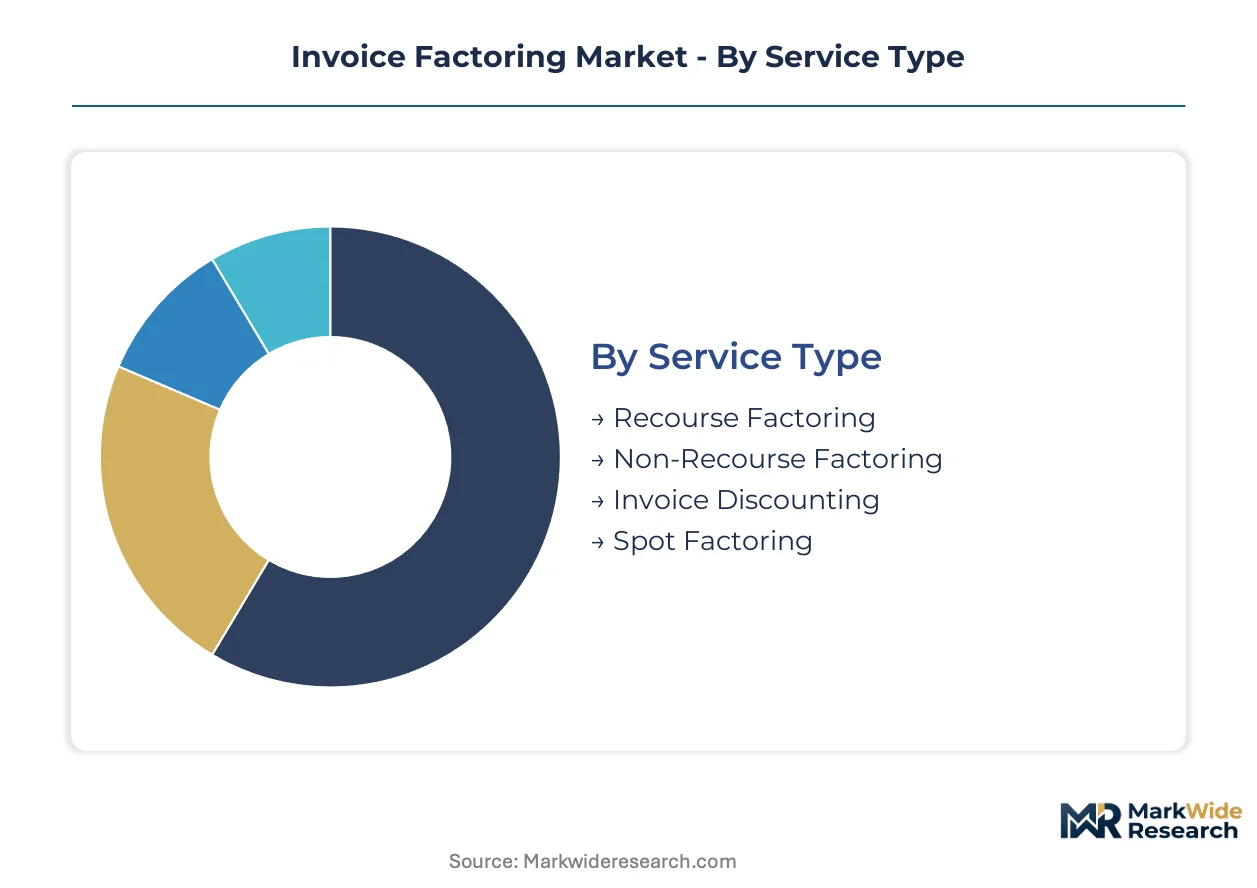
Segmentation in invoice factoring reveals how capital flows fragment across risk appetites and operational capabilities. Distinct service structures, client profiles, and funding channels create tiered pricing and servicing models that reshape competitive positioning.
Service Type:
Upgrade cycles in factoring services track regulatory capital treatment and credit insurance market depth.
- Recourse Factoring:The seller retains default risk if the debtor fails to pay, producing simpler legal documentation and lower fee structures. Demand concentrates among transportation and construction SMEs in the United States, where extended payment terms from large buyers strain working capital.
- Non-Recourse Factoring:The factor assumes credit risk, typically layered with trade credit insurance from A-rated carriers. Large-ticket arrangements in the United Kingdom command dedicated servicing teams and tighter spreads, reflecting institutional investor appetite for insured receivables.
- Invoice Discounting:Confidential arrangements where the seller retains collection responsibility while borrowing against receivables. Mid-sized manufacturers in Germany favor this structure to preserve customer relationships.
- Spot Factoring:Single-invoice transactions processed through automated platforms with minimal human intervention. Freelancers and micro-businesses in India access this via mobile-first interfaces integrated with GST e-invoicing infrastructure.
Recourse Factoring sits at the top of the volume ranking, with Spot Factoring climbing the fastest.
Client Type:
Cost tier segmentation separates self-service platform users from relationship-managed corporate accounts.
- Small Businesses:Firms with annual turnover below $10 million access factoring primarily through API-integrated platforms. Working capital stress from 60-90 day payment terms drives adoption among US-based specialty contractors and logistics operators.
- Mid-Sized Enterprises:Revenue-scale borrowers between $10-100 million combine recourse and non-recourse structures across multiple buyers. Indian NBFCs target this segment with industry-specialized underwriting teams.
- Freelancers:Individual service providers selling invoices from single-client engagements. UK platform lenders serve this cohort through automated risk scoring against open banking transaction histories.
- Large Corporations:Multi-billion dollar revenue entities with audited financials and concentrated buyer bases. Bank-led arrangements dominate, though reverse factoring programs are displacing traditional structures in automotive supply chains.
Mid-Sized Enterprises generate the deepest fee pools, while Freelancers are expanding most quickly as platform economics improve.
Invoice Type:
Application-based segmentation maps to verification complexity and collection risk profiles.
- Commercial Invoices:B2B trade receivables between incorporated entities, forming the core collateral base for most factoring arrangements. US transportation and UK manufacturing sectors supply the largest transaction flows.
- Government Invoices:Receivables from federal, state, or municipal contracting. Indian MSMEs factor these against delayed public procurement payments, though sovereign risk weighting varies by jurisdiction.
- Service Invoices:Intangible deliverables lacking physical shipment verification. Professional services firms in legal, consulting, and technology verticals access this segment through milestone-based advance structures.
- Retail Invoices:Consumer-facing receivables with higher default dispersion. Buy-now-pay-later originators in the United States are experimenting with factoring structures for merchant cash advances.
Commercial Invoices anchor transaction volume, with Government Invoices gaining share fastest as public procurement digitization accelerates.
Funding Source:
Margin-based segmentation distinguishes balance-sheet deployers from distributed liquidity models.
- Private Investors:Family offices and specialty credit funds deploying directly into factoring special purpose vehicles. Yield-seeking capital from US and Middle Eastern sources concentrates in transportation and energy receivables.
- Banks:Regulated depositories with cost-of-funding advantages for large corporate relationships. Basel III endgame uncertainty is freezing some institutional deployment into warehouse structures.
- Financial Institutions:Captive finance companies and insurance-affiliated lenders. Indian NBFCs in the upper regulatory tiers are professionalizing through RBI-mandated capital adequacy frameworks.
- Online Platforms:Marketplace lenders and peer-to-peer structures aggregating retail and institutional capital. UK platforms operate under FCA wind-down and client money segregation requirements.
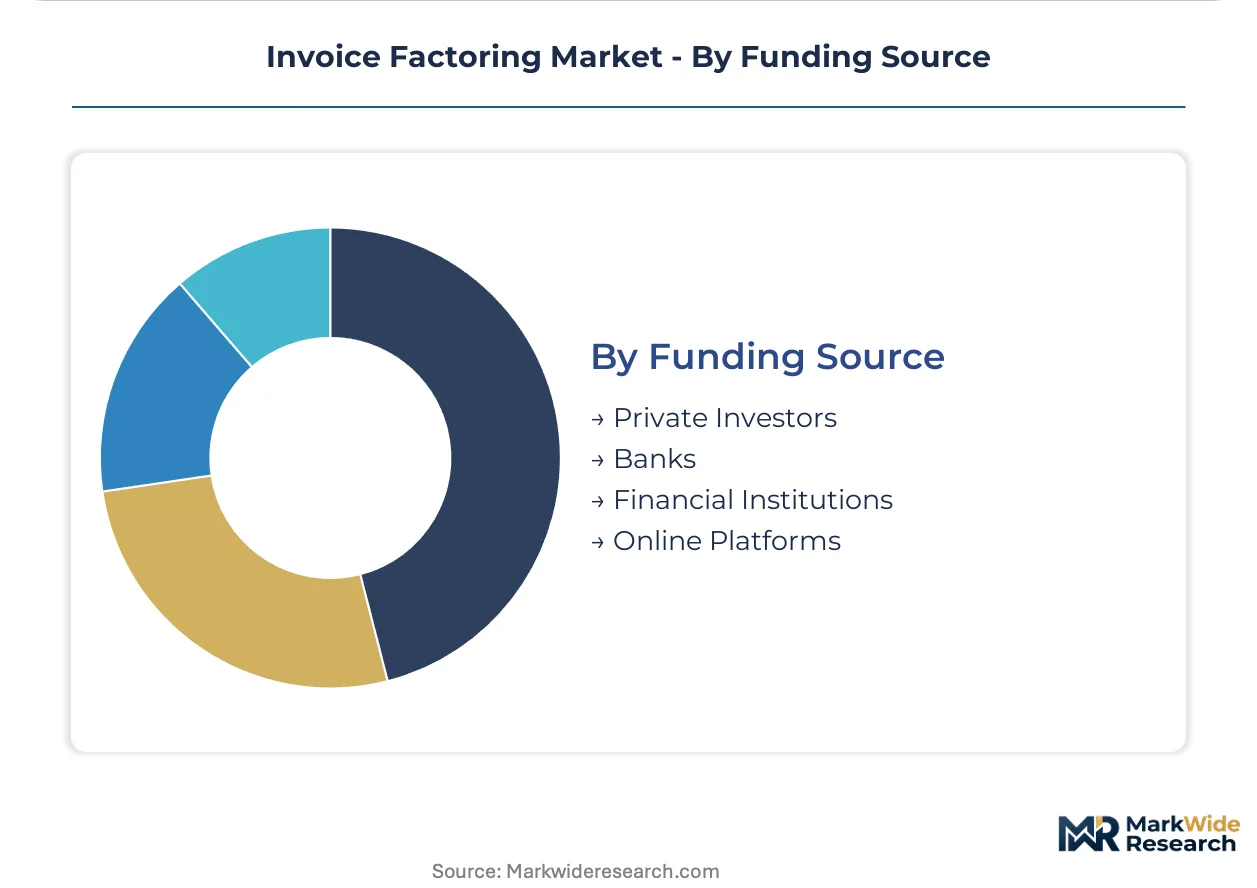
Banks retain the largest committed capacity, with Online Platforms showing the steepest expansion trajectory as embedded finance partnerships proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and India display divergent maturity profiles in invoice factoring adoption. American transportation and construction SMEs drive established recourse volumes, while Indian MSMEs accelerate platform-based spot transactions through GST-integrated infrastructure. Regulatory frameworks in the United Kingdom and Germany reshape capital deployment patterns across both markets.
United States
Transportation carriers and specialty contractors facing 60-90 day payment terms from large buyers generate sustained recourse factoring demand. The Office of the Comptroller of the Currency supervises national bank participation, creating compliance baselines for institutional funders. Dallas and Chicago anchor regional servicing hubs where transportation-sector specialization concentrates.
India
MSMEs delayed by public procurement payment cycles fuel government invoice factoring growth through platform lenders. The Reserve Bank of India's scale-based NBFC regulations tighten capital adequacy for upper-tier non-bank lenders, professionalizing the sector. Mumbai and Bangalore cluster fintech-integrated originators leveraging real-time GST e-invoicing verification.
United Kingdom
Mid-sized manufacturers and professional services firms access non-recourse structures with embedded credit insurance. The Financial Conduct Authority regulates peer-to-peer and platform-based funders through wholesale lending frameworks and wind-down arrangement mandates. London concentrates institutional capital deployment into insured receivables vehicles.
Germany
Automotive suppliers and industrial manufacturers favor confidential invoice discounting to preserve customer relationships. BaFin oversight of banking groups shapes capital treatment for purchased receivables. Bavaria and Baden-Württemberg host dense automotive supply chains where reverse factoring volumes now exceed traditional discounting.
United Arab Emirates
Trade finance demand from India-UAE and UK-UAE corridors drives multi-currency factoring adoption. The central bank governs non-bank lender licensing with emphasis on operational resilience. Dubai International Financial Centre clusters sharia-compliant and conventional funders serving cross-border working capital needs.
Invoice Factoring Market Vendor Landscape
Top-tier vendors anchor institutional balance-sheet capacity, while automated platforms capture velocity-driven small-ticket flows. The market structure stratifies across three functional tiers: transportation-specialized factors with captive broker networks, API-first platforms compressing funding timelines through accounting software integration, and diversified lenders cross-selling factoring from adjacent equipment finance and SBA-lending relationships. Consolidation pressure intensifies as technology investment requirements widen capability gaps between scaled operators and regional specialists.
Within the transportation-specialized tier, RTS Financial exemplifies sector-focused origination through captive distribution channels. FundThrough occupies the velocity-optimized position, leveraging direct ERP integrations to compress advance timelines. Kapitus represents the cross-selling archetype, extending factoring to existing equipment finance and SBA-lending borrowers. These three patterns illustrate how competitive differentiation fragments across operational specialization, technology integration depth, and portfolio diversification strategy.
| Leading Market Players |
|---|
| RTS Financial |
| Kapitus |
| FundThrough |
| Viva Capital |
| Scale Funding |
| Riviera Finance |
| eCapital |
| Universal Funding Corporation |
| Triumph Business Capital |
| Others |
Supply Flow & Price Mechanics
The premium-commodity bifurcation between large-ticket non-recourse arrangements and small-ticket spot transactions hardens pricing discipline and supply chain configuration simultaneously. Institutional funders command tighter spreads through dedicated servicing teams and captive credit insurance layers, while automated platforms strip cost from origination by embedding directly into accounting software workflows.
Pricing Analysis
Capacity additions in India and the United Kingdom are reshaping price floors for spot factoring as platform lenders deploy GST-integrated verification and open banking scoring. Three-tier pricing structure across premium non-recourse, standard recourse, and economy spot transactions reflects credit insurance layering and automation depth. Pricing pressure stems from API-first entrants compressing advance timelines from days to hours. Freelancers and micro-businesses exhibit highest price sensitivity, while large corporations with audited financials prioritize relationship continuity over rate minimization.
Supply Chain Analysis
Funding liquidity rests on concentrated deployment from the United States, the United Kingdom, and India as regulatory frameworks mature and institutional capital professionalizes. Balance-sheet capacity draws from bank-led arrangements, NBFC scale-based licensing, and marketplace lender aggregation. Single-source vulnerability concentrates in transportation-sector recourse structures where debtor concentration risk amplifies default exposure. Distribution runs through captive broker networks, direct ERP integrations, and embedded finance partnerships with B2B procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The invoice factoring market offers margin expansion through automation-driven cost compression in small-ticket origination and premium-tier fee stacking in insured non-recourse structures.
For Market Incumbents: To counter API-first platform erosion in small-ticket volumes, incumbents must rebuild technology stacks for real-time credit scoring or cede that tier entirely. Backward integration into captive broker networks preserves transportation-sector origination control. Investment in trade credit insurance layering defends premium-tier spread capture against automated competitors.
For New Entrants and Emerging Players: Launch via embedded finance partnerships with B2B marketplaces and procurement platforms to intercept invoice generation at origin. Cross-border trade corridors between India and the United Kingdom present the most penetrable white space, driven by payment term mismatches and multi-currency demand. GST-integrated verification infrastructure offers a defensible go-to-market angle in Indian spot factoring.
For Investors and Strategic Acquirers: Consolidation pressure builds where technology investment requirements widen capability gaps between scaled operators and regional specialists. Acquisition targets should combine transportation-sector specialization with underinvested API infrastructure. Watch Basel III endgame proposals on bank capital treatment of purchased receivables as the critical signal for institutional liquidity redirection between balance-sheet and distributed funding models.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Direct ERP connectivity compresses funding timelines from days to hours for SME borrowers. |
| Credit Insurance Layering | Non-recourse structures with A-rated carrier backing command tighter spreads from institutional investors. |
| Embedded Finance Partnership | B2B marketplace integration intercepts invoice generation and embeds advance payment at origin. |
| Cross-Border Corridor Expansion | Multi-currency factoring with FX hedging captures India-UK and India-US payment term arbitrage. |
| Regulatory Tier Professionalization | RBI scale-based NBFC licensing attracts institutional capital through mandated capital adequacy frameworks. |
Methodological Framework
Direct dialogue with factoring operations executives, credit risk officers at NBFCs, transportation fleet owners, and procurement platform engineers grounded qualitative findings in operational reality. Secondary validation drew from RBI regulatory circulars, FCA wholesale lending frameworks, SEC filings of listed specialty lenders, and industry association data on receivables financing volumes. Bottom-up transaction flow analysis and top-down macroeconomic stress testing were triangulated to anchor projections.
Bottom-up modeling segmented volume and fee pool projections across service type, client tier, invoice category, and funding source dimensions throughout the forecast period. CAGRs were derived from historical adoption curves weighted by regulatory catalyst timing and technology penetration rates. Open banking API adoption velocity and GST e-invoicing infrastructure rollout served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Basel III endgame uncertainty and sovereign payment delay scenarios. Projections reflect assumptions on working capital stress persistence and platform lender regulatory compliance costs. A small set of triggers—central bank capital treatment rulings, major invoice fraud events, and embedded finance partnership scale—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Japan Mortgage/Loan Brokers Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
Syndicated Loans Market
Loans and Leasing
Online Payday Loans Market
Loans and Leasing
Loan Brokers Market
Loans and Leasing
Unsecured Business Loans Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Debt Financing Market
Loans and Leasing
Asia-Pacific Used Car Financing Market
Loans and Leasing
Indonesia Mortgage/Loan Brokers Market
Loans and Leasing
Germany Auto Loan Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Home Equity Lending Market
Loans and Leasing
Peer-To-Peer Lending Market
Loans and Leasing
India Student Loan Market