
 Alternative Lending Platform Market | 2026-2036
Alternative Lending Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Alternative Lending Platform Market Intelligence
Traditional credit analyst hiring pipelines is collapsing as algorithmic underwriting displaces manual review cycles. LendingClub leverages machine-learning scorecards to sustain approval velocity for consumer debt consolidation. Upstart Network competes with employment-history models that anchor its non-FICO lending decisions. SoFi dominates graduate-student refinancing by controlling membership-bank cross-sell channels.
An alternative lending platform is a cloud-native financial infrastructure system that automates borrower acquisition, credit scoring, funds disbursement, and servicing through API-orchestrated workflows, typically processing decisions in under sixty seconds. Its primary purpose is to extend credit to segments excluded by conventional risk-assessment frameworks. Peer-to-peer service types attract retail capital pools that seek yield outside deposit instruments, though margin compression is intensifying as institutional buyers crowd the channel. Small-business customer types generate the fastest origination growth because legacy banks have retreated from sub-two-hundred-thousand-dollar commercial loans. Direct lending software components capture disproportionate technology spending as platforms internalize origination rather than white-label to banks.
The Consumer Financial Protection Bureau enforces fair-lending disclosures that shape platform marketing scripts and rate-quote presentation formats. The Office of the Comptroller of the Currency fintech charter pathway determines whether platforms can operate under federal preemption or remain subject to fifty-state licensing fragmentation. The SEC regulates investment-platform securities offerings, constraining how retail capital pools participate in loan funding. Stakeholders must monitor whether federal charter adoption accelerates or state-by-state compliance costs entrench regional platform fragmentation.
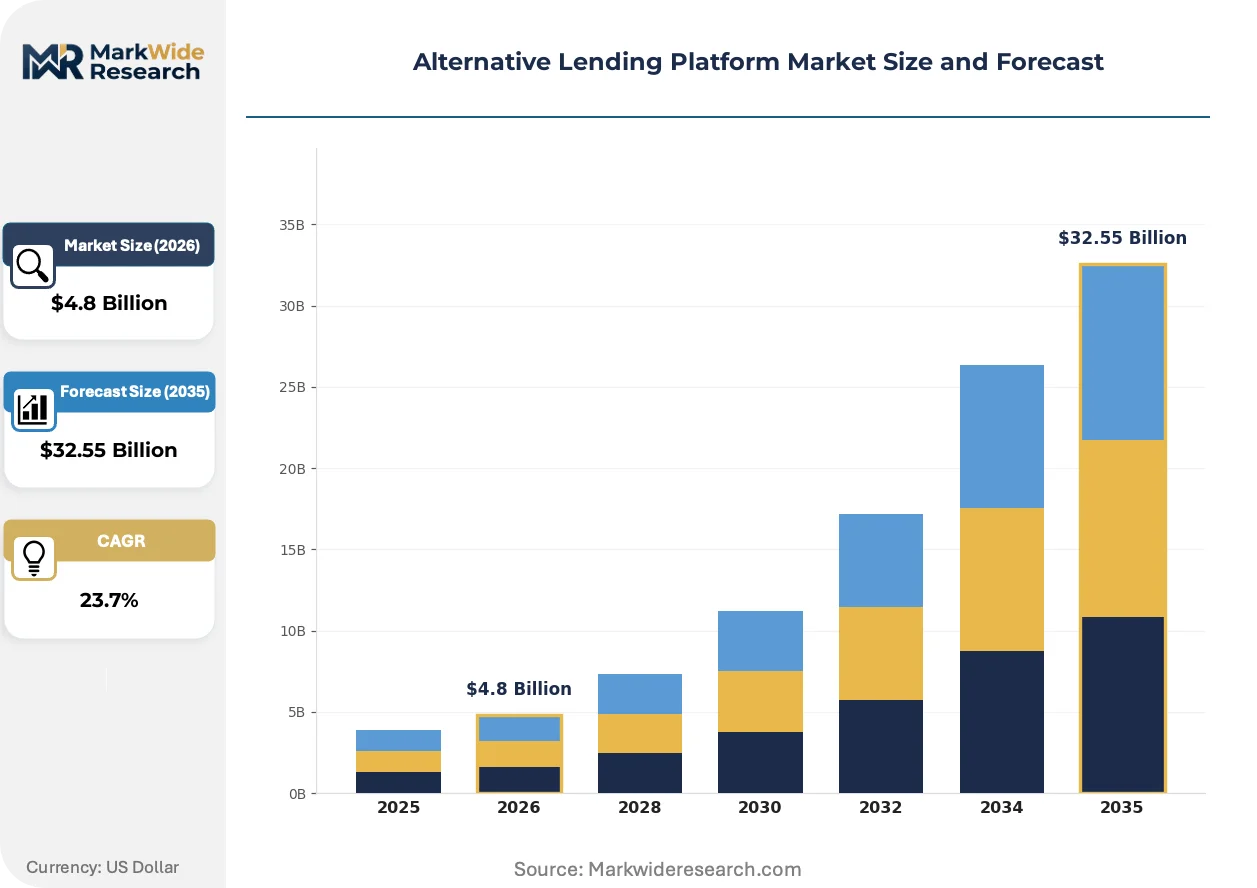
Market Dynamics
Open banking infrastructure is decomposing legacy credit decisioning timelines, compressing loan origination from weeks to seconds and forcing incumbent banks to abandon manual underwriting workflows entirely.
Growth Catalysts
- Real-time data aggregation:Open banking APIs in the United Kingdom enable instantaneous cash-flow verification, eliminating document-based income proofing for gig-economy borrowers.
- Regulatory sandbox frameworks:The United States OCC fintech charter pathway permits federal preemption, reducing state-by-state licensing costs for digital lenders seeking national scale.
- Small-business credit gaps:Traditional banks have retreated from sub-two-hundred-thousand-dollar commercial loans, redirecting demand toward algorithmic platforms.
Market Restraints
- Funding cost volatility:Institutional warehouse credit lines for direct lenders fluctuate with central bank rate cycles, squeezing net interest margins during tightening phases.
- Data concentration risk:Three dominant credit bureaus control alternative data scoring inputs, creating single-point-of-failure exposure for non-FICO underwriting models.
- Securities regulation friction:The SEC restricts retail participation in peer-to-peer loan funding, capping retail capital pools and forcing platforms toward institutional buyers.
Strategic Opportunities
- Embedded finance convergence:Point-of-sale lending integrations with e-commerce checkout flows capture borrowers at transaction intent moments.
- India's digital public infrastructure:Account Aggregator framework and UPI rails enable cash-flow-based underwriting for thin-file borrowers excluded from formal credit.
- Climate-linked loan products:EU Green Deal taxonomy-aligned lending creates regulatory tailwinds for platforms financing residential solar retrofits and electric vehicle fleets.
Industry Challenges
- Machine-learning engineer scarcity:Platforms compete for talent capable of building explainable AI scorecards that satisfy fair-lending audit requirements.
- Core banking integration complexity:Legacy bank IT architectures resist API connectivity, delaying white-label partnership launches by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternative Lending Platform Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $32.55 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Software, Infrastructure, Payment Gateway, Analytics Customer Type: Individuals, Small Businesses, Middle-Market Enterprises, Startups Loan Type: Peer-to-Peer, Microloans, Invoice Financing, Lines of Credit Service Type: Direct Lending, Investment Platforms, Crowdfunding, Brokerage Services |
| Companies Covered | LendingClub, Prosper Marketplace, Funding Circle, Upstart Network, SoFi, OnDeck Capital, Kabbage, Zopa, Affirm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternative Lending Platform Market Strategic Shifts & Innovations
Credit decisioning infrastructure is fragmenting into modular microservices, enabling platforms to swap scoring engines and funding sources without rebuilding entire technology stacks.
Embedded underwriting APIs are decomposing the traditional loan application into invisible, context-triggered credit offers at merchant checkout points. E-commerce platforms and payroll software providers embed these capabilities directly into user workflows, eliminating dedicated lending interfaces. This architecture compresses customer acquisition costs and expands addressable borrower pools beyond self-selected credit seekers.
The Consumer Financial Protection Bureau's fair-lending disclosure rules are reshaping platform marketing compliance, mandating standardized rate-quote presentations that limit teaser-rate advertising tactics. Lenders must now display annual percentage rates prominently before collecting borrower information. Direct-to-consumer platforms have restructured landing pages and chatbot scripts to satisfy these sequencing requirements.
Borrower acquisition channels are rotating from paid search toward employer-sponsored financial wellness partnerships. Human resources platforms integrate salary-linked credit products as employee benefits, capturing repayment through payroll deduction. This shift concentrates origination volume among large employers with distributed workforces, particularly in healthcare and logistics sectors where traditional credit penetration remains low.
Alternative Lending Platform Market Segmentation
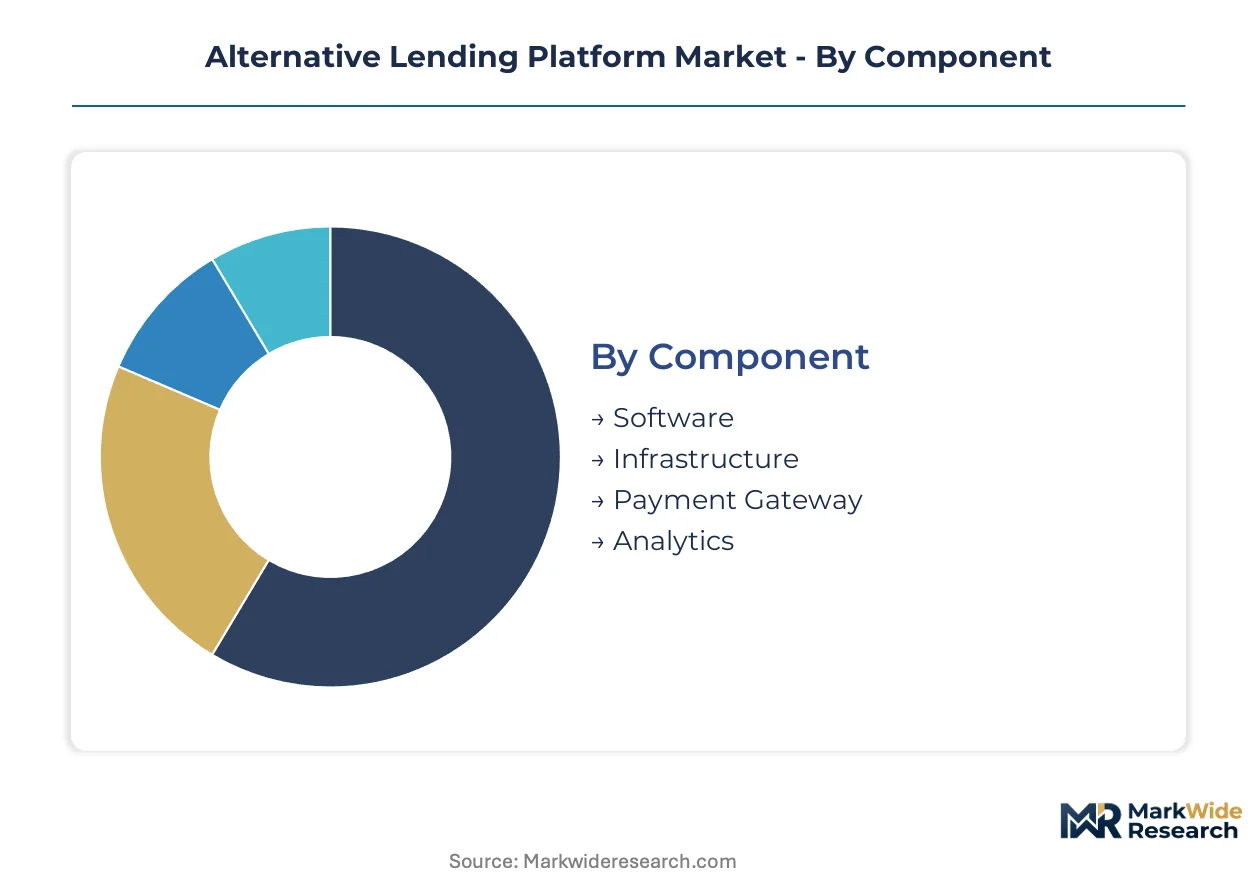
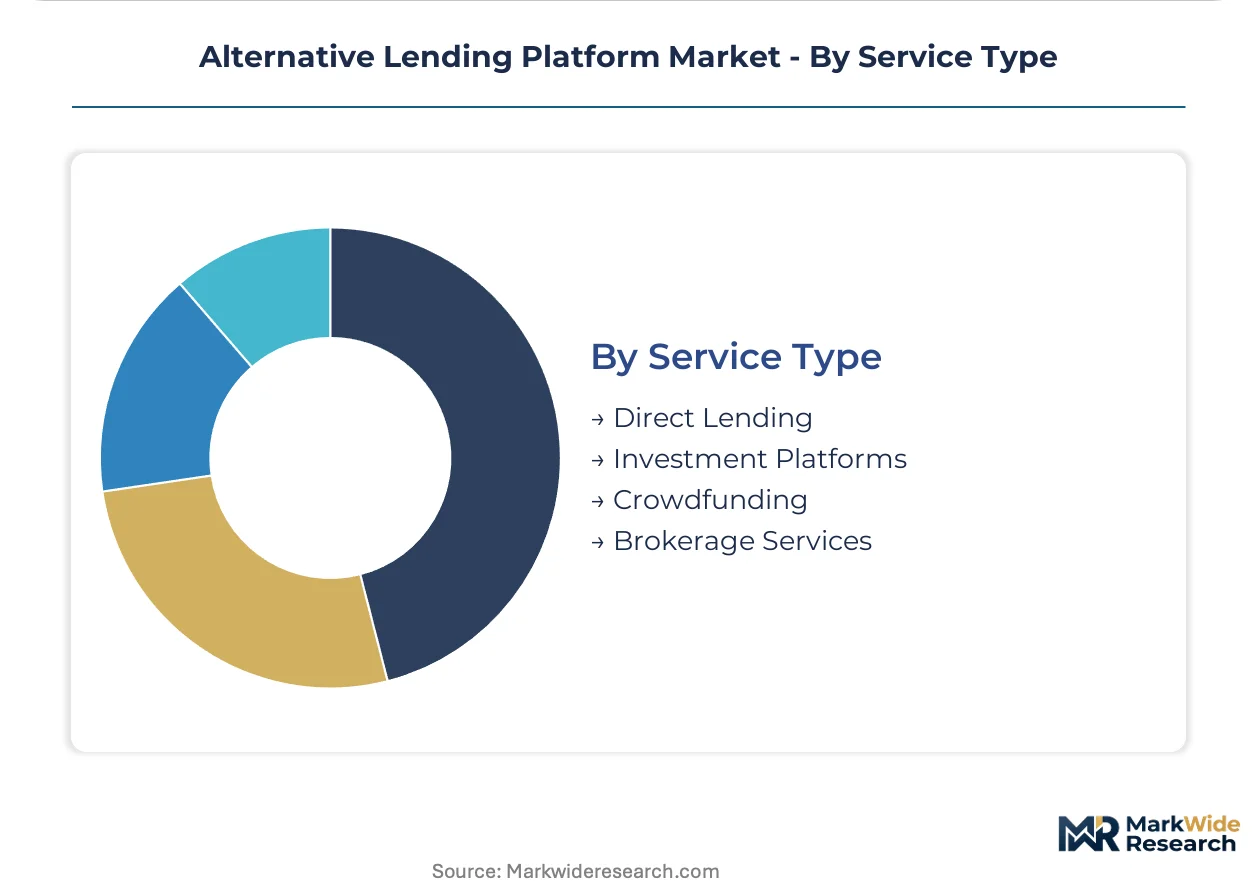
Segmentation in alternative lending platforms determines where technology budgets concentrate and which regulatory frameworks apply. Platform operators configure their technology stacks and compliance postures around these dimensions, creating distinct competitive arenas with divergent margin structures.
Component:
Margin pools concentrate in software layers that control borrower-facing interfaces and underwriting logic, while infrastructure and payment processing face commodity pricing pressure.
- Software:Core lending engines automate credit decisioning, loan origination, and servicing workflows through configurable rule sets. Demand clusters among direct lenders in the United States seeking to internalize technology ownership rather than rely on white-label vendors, driven by the OCC fintech charter pathway that rewards platform control over compliance infrastructure.
- Infrastructure:Cloud hosting, data storage, and compute resources underpin platform scalability. The segment expands most quickly in India, where the Reserve Bank of India's digital lending guidelines mandate local data residency, forcing platforms to build domestic infrastructure rather than rely on foreign cloud providers.
- Payment Gateway:Disbursement and collection rails integrate with banking networks and alternative payment systems. European platforms prioritize SEPA Instant compatibility under PSD2 open banking frameworks.
- Analytics:Predictive models and portfolio monitoring tools refine risk pricing and collections strategies. Adoption accelerates among middle-market lenders seeking explainable AI scorecards that satisfy fair-lending audit requirements.
The dominant share belongs to Software, while Analytics is closing the gap fastest as regulatory scrutiny intensifies around model explainability.
Customer Type:
Application patterns diverge sharply between consumer and commercial segments, with underwriting data sources and sales cycles driving fundamentally different platform architectures.
- Individuals:Personal loans, debt consolidation, and retail credit products serve mass-market borrowers. Platforms in the United Kingdom leverage Open Banking APIs for real-time income verification, displacing traditional credit bureau dependency for gig-economy applicants.
- Small Businesses:Sub-two-hundred-thousand-dollar commercial loans dominate origination velocity. Traditional bank retreat from this segment redirects demand toward algorithmic platforms with automated cash-flow analysis.
- Middle-Market Enterprises:Larger commercial borrowers require structured credit facilities with covenant monitoring. Platforms compete on relationship management capabilities alongside automated underwriting.
- Startups:Venture-backed companies access revenue-based financing and founder-friendly term structures. Silicon Valley platforms specialize in this segment, using equity co-investment structures to align lender-borrower incentives.
Small Businesses command the largest technology spend per deployment, though Individuals generate the highest transaction volumes.
Loan Type:
Product design choices determine funding source compatibility and regulatory classification, shaping platform business model economics.
- Peer-to-Peer:Retail investor capital pools fund individual loans through fractional ownership structures. SEC registration requirements in the United States constrain retail participation, pushing platforms toward institutional buyer relationships.
- Microloans:Small-ticket, short-duration credit serves thin-file borrowers excluded from formal banking. India's Account Aggregator framework enables cash-flow-based underwriting for this segment.
- Invoice Financing:Accounts receivable collateralization provides working capital to B2B sellers. Platforms integrate directly with accounting software APIs to verify invoice authenticity.
- Lines of Credit:Revolving facilities offer flexible drawdown for seasonal businesses. Demand concentrates in logistics and healthcare sectors with predictable revenue cyclicality.
Invoice Financing carries the highest per-loan margins, while Microloans show the steepest volume expansion trajectory in emerging markets.
Service Type:
Business model selection determines balance sheet exposure, regulatory capital requirements, and customer acquisition economics.
- Direct Lending:Platforms originate and retain loans on their own balance sheets or through affiliated special purpose vehicles. Warehouse credit line availability from institutional funders dictates origination capacity.
- Investment Platforms:Marketplace structures match borrower demand with institutional or retail capital without platform balance sheet intermediation. EU Crowdfunding Service Providers Regulation standardizes disclosure requirements across member states.
- Crowdfunding:Community-based funding pools support specific projects or social enterprises. Reward-based and equity-based variants face distinct securities regulation across jurisdictions.
- Brokerage Services:Intermediaries match borrowers with third-party lenders without direct origination. Commission economics pressure this model as platforms verticalize into direct lending.
Direct Lending captures the dominant revenue share, though Investment Platforms are gaining ground fastest as regulatory clarity improves in Europe and Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States platforms command origination premiums that United Kingdom operators cannot replicate, reflecting divergent regulatory pathways and capital market depths. This pricing-power asymmetry reshapes where technology vendors prioritize deployment resources.
United States
The Consumer Financial Protection Bureau's fair-lending disclosure mandates and the Office of the Comptroller of the Currency fintech charter pathway accelerate platform licensing velocity. Small-business credit gaps in sub-two-hundred-thousand-dollar commercial loans redirect demand toward algorithmic origination channels. Silicon Valley and New York clusters host venture-backed platforms specializing in revenue-based financing for startup borrowers.
United Kingdom
Open banking APIs enable instantaneous cash-flow verification for gig-economy applicants, displacing traditional credit bureau dependency. The Financial Conduct Authority's regulatory sandbox framework permits controlled testing of automated underwriting models. London's fintech corridor concentrates peer-to-peer lending platforms that attract retail capital pools seeking yield outside deposit instruments.
India
The Reserve Bank of India's digital lending guidelines and Account Aggregator framework enable cash-flow-based underwriting for thin-file borrowers excluded from formal credit. Mumbai and Bangalore clusters host platforms integrating with UPI rails for real-time disbursement and collection. Microloan origination velocity accelerates fastest in this market among emerging economies.
Germany
BaFin's oversight of crowdfunding service providers standardizes disclosure requirements for investment-platform structures. The EU Green Deal taxonomy-aligned lending creates regulatory tailwinds for platforms financing residential solar retrofits. Berlin and Frankfurt clusters concentrate direct lending operations targeting middle-market enterprises with covenant monitoring capabilities.
China
The national financial regulators' digital lending guidelines mandate local data residency and algorithmic transparency for non-bank credit providers. Shanghai and Shenzhen clusters host technology infrastructure providers serving regional banks with white-label origination capabilities. Embedded finance convergence at e-commerce checkout points captures borrowers at transaction intent moments.
Alternative Lending Platform Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the alternative lending platform market. Incumbent technology vendors with configurable rule sets command premium pricing from direct lenders seeking compliance infrastructure control. Balance-sheet lenders with warehouse credit line access compete on origination velocity rather than software sophistication. Strategic moves concentrate on embedded finance partnerships with e-commerce platforms and employer-sponsored financial wellness integrations.
Among established marketplace lenders, LendingClub and Prosper Marketplace exemplify the investment-platform archetype that matches borrower demand with institutional capital without balance sheet intermediation. Upstart Network occupies a position within the non-FICO underwriting specialist tier, representing machine-learning scorecard capabilities that satisfy fair-lending audit requirements. SoFi anchors the membership-bank cross-sell segment, sitting within the vertical integration archetype that controls origination through servicing.
| Leading Market Players |
|---|
| LendingClub |
| Prosper Marketplace |
| Funding Circle |
| Upstart Network |
| SoFi |
| OnDeck Capital |
| Kabbage |
| Zopa |
| Affirm |
| Others |
Cost & Logistics Intelligence
Sixty-second loan decisioning timelines compress procurement cycles for cloud infrastructure and API orchestration layers, concentrating pricing power among vendors that control real-time data aggregation pipes and regulatory-compliant underwriting engines. Platforms in the United States command origination premiums that United Kingdom operators cannot replicate, reflecting divergent OCC charter pathways and capital market depths that reshape technology vendor deployment priorities.
Pricing Analysis
United States platforms capture fifteen to twenty-five basis point origination premiums over United Kingdom equivalents, reflecting deeper institutional buyer pools and federal preemption advantages. Three-tier pricing structure across enterprise-grade, mid-market, and white-label tiers segments the software layer, with compliance infrastructure ownership commanding the highest tier. Cost compression in the payment gateway segment intensifies as SEPA Instant and UPI rails commoditize disbursement economics. Small-business direct lenders exhibit the sharpest price sensitivity, while venture-backed startup specialists accept premium pricing for covenant-light structures.
Supply Chain Analysis
Strait of Hormuz transit disruptions would cascade through institutional warehouse credit line pricing, amplifying funding cost volatility for balance-sheet lenders dependent on offshore capital pools. Technology concentration rests on United States cloud hyperscalers, Indian data residency-compliant infrastructure providers, and Chinese white-label origination vendors serving regional banks. Raw material dependencies include GPU clusters for machine-learning scorecards, open banking API licenses, and alternative data feeds from credit bureaus. Single-source vulnerability concentrates in the three dominant credit bureaus controlling non-FICO scoring inputs. Distribution runs through direct sales to platform operators, systems integrators for legacy bank modernization, and embedded finance partnerships with e-commerce and payroll software providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large institutional funders and embedded finance orchestrators, fragmenting the traditional platform-vendor relationship as procurement committees consolidate technology spend across lending, payments, and payroll verticals.
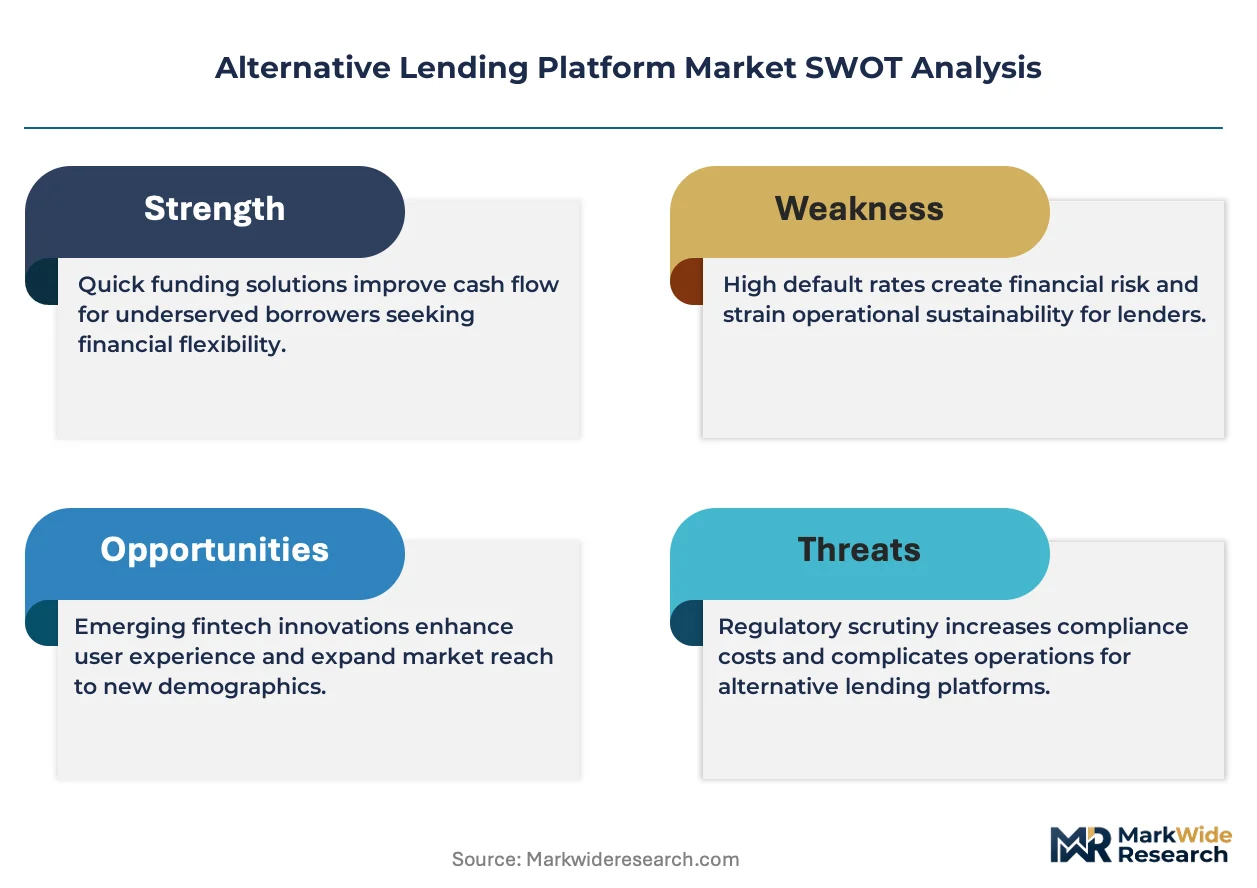
For Market Incumbents: Shield core origination velocity by deepening API integration with legacy bank core systems, the twelve-to-eighteen-month integration timeline represents the primary defensive moat against white-label competitors. Prioritize explainable AI engineering talent retention as machine-learning engineer scarcity intensifies regulatory audit risk. Balance sheet exposure to warehouse credit line volatility demands active hedging through diversified institutional funder relationships. For New Entrants and Emerging Players: Lead with India's Account Aggregator framework and UPI rails, the most penetrable geography for cash-flow-based underwriting of thin-file borrowers excluded from formal credit. Target employer-sponsored financial wellness partnerships in healthcare and logistics sectors where traditional credit penetration remains low. Pursue revenue-based financing structures for venture-backed startups as the primary go-to-market angle, using equity co-investment alignment to differentiate from incumbent term lenders. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because federal charter adoption velocity will determine whether platforms achieve national scale or remain trapped in state-by-state licensing fragmentation. Acquisition target archetype: mid-cap direct lenders with proprietary cash-flow underwriting engines and existing OCC charter relationships. Watch for inflection in SEC retail participation rulemaking, which would signal expansion or contraction of peer-to-peer capital pool access.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance Partnership | Point-of-sale lending integrations at e-commerce checkout capture borrowers at transaction intent moments. |
| Regulatory Sandbox Entry | FCA and OCC frameworks permit controlled testing of automated underwriting models before full licensing. |
| Alternative Data Licensing | Account Aggregator and open banking API access displaces traditional credit bureau dependency for gig-economy applicants. |
| Machine Learning Talent Acquisition | Explainable AI scorecard capabilities satisfy CFPB fair-lending audit requirements and differentiate risk pricing. |
| Cross-Border Infrastructure Buildout | RBI-mandated data residency compliance forces domestic cloud deployment rather than foreign provider reliance. |
Research Approach
A standing panel of chief technology officers at direct lending platforms, regulatory compliance officers navigating OCC charter pathways, institutional funder portfolio managers, and embedded finance partnership leads provided ongoing calibration across the analysis window. Primary interview findings were cross-validated against secondary sources including SEC registration filings for investment-platform structures, CFPB fair-lending disclosure enforcement actions, RBI digital lending guidelines, and FCA sandbox authorization records. Bottom-up segment sizing for software, infrastructure, and analytics components was triangulated against top-down market aggregation from capital deployment tracking.
Consistency checks validated volume and value outputs against external benchmarks including fintech venture funding databases, warehouse credit line utilization reports, and open banking API call volume disclosures. The analytical framework modeled segmentation across component type, customer archetype, loan structure, and service model throughout the projection horizon. CAGRs were derived from regression analysis of origination velocity against regulatory adoption curves and capital market depth indicators. Industry-specific forecast inputs included fintech charter approval timelines, embedded finance partnership announcement velocity, and machine-learning engineer hiring pipeline data.
Forecasts assume regulatory continuity in United States OCC preemption, United Kingdom FCA sandbox, and India RBI digital lending regimes; material policy shifts would require re-modeling origination capacity and pricing power assumptions. Scenario boundaries exclude extreme central bank rate cycle discontinuities and comprehensive SEC retail participation bans. Practitioners should keep alternative scenarios live as embedded finance partnership concentration and open banking API standardization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Online Payday Loans Market
Loans and Leasing
Alternative Financing Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
North America Motorcycle Loan Market
Loans and Leasing
Machinery Rental and Leasing Market
Loans and Leasing
Student Loan Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
India Auto Loan Market
Loans and Leasing
Invoice Factoring Market
Loans and Leasing
China Home Loan Market
Loans and Leasing
Europe Mortgage Lending Market
Loans and Leasing
Housing Finance Market
Loans and Leasing
South Korea Auto Loan Market
Loans and Leasing
Europe Syndicated Loans Market