
 Consumer Credit Market | 2026-2036
Consumer Credit Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Credit Market Intelligence
Subprime and thin-file borrowers is unwinding toward prime and near-prime households seeking debt consolidation and home improvement financing. JPMorgan Chase & Co. leverages its branch network and deposit base to dominate mortgage and card originations at scale. Capital One Financial Corporation specializes in data-driven underwriting and subprime-to-prime customer migration strategies. Klarna Bank AB competes aggressively in buy-now-pay-later integrations with retail merchants across Europe and North America.
Consumer credit encompasses secured and unsecured lending products extended to individuals for personal, household, or small business purposes, typically structured with fixed or variable interest rates, amortization schedules ranging from months to decades, and risk-based pricing tied to credit scores or alternative data profiles. Credit cards and personal loans command the highest origination velocity among product types, while mortgages retain the largest outstanding balance pool and longest duration. Online lending and peer-to-peer platforms capture the fastest growth in service type penetration, though traditional banking still anchors the majority of mortgage and student loan volumes.
The US Consumer Financial Protection Bureau enforces fair-lending standards and restricts predatory fee structures, while the SEC oversees asset-backed securities that fund much consumer credit expansion. The EU's GDPR and proposed AI Act constrain automated underwriting algorithms and alternative data usage across European markets. Stakeholders must monitor how generative AI tools for credit decisioning interact with emerging algorithmic accountability rules in multiple jurisdictions.
Market Dynamics
Open banking APIs are decomposing traditional credit underwriting by enabling real-time cash-flow verification, forcing incumbent lenders to rebuild risk models around transaction data rather than static credit scores.
Growth Catalysts
- India Stack Integration:The country's unified payments interface and account aggregator frameworks enable instant credit disbursal to thin-file borrowers previously excluded from formal banking.
- Embedded Finance Proliferation:Retail checkout integrations transform point-of-sale moments into credit origination opportunities, capturing demand at the exact instant of purchase intent.
- GDPR-Compliant Alternative Data:European lenders leverage consented utility and rental payment histories to expand near-prime underwriting without violating data protection boundaries.
Market Restraints
- Deposit Funding Concentration:US regional banks face structural liquidity pressure as rate environments compress net interest margins on core funding sources.
- Algorithmic Audit Requirements:The EU AI Act mandates explainability documentation for automated credit decisions, adding compliance friction to machine-learning underwriting pipelines.
- BNPL Regulatory Arbitrage Closure:UK and Australian regulators reclassify buy-now-pay-later products under consumer credit laws, eliminating prior exemptions from responsible lending obligations.
Strategic Opportunities
- Southeast Asia Underpenetration:Indonesia, Vietnam, and Philippines present white space where sub-20% formal credit penetration meets smartphone-first financial service adoption.
- Climate-Linked Consumer Finance:Green home improvement loans and electric vehicle financing attract subsidized capital pools from EU Green Deal-aligned institutional investors.
- Payroll-API Integration:Direct employment data feeds from workforce management platforms enable income-verified credit products with default predictability superior to bureau scores.
Industry Challenges
- Model Risk Management Talent Scarcity:Lenders struggle to hire quantitative analysts capable of validating machine-learning credit models under SR 11-7 and equivalent supervisory guidance.
- Legacy Core System Fragmentation:Decades-old loan origination platforms resist API-native architecture, forcing expensive middleware layers for open banking connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Credit Market |
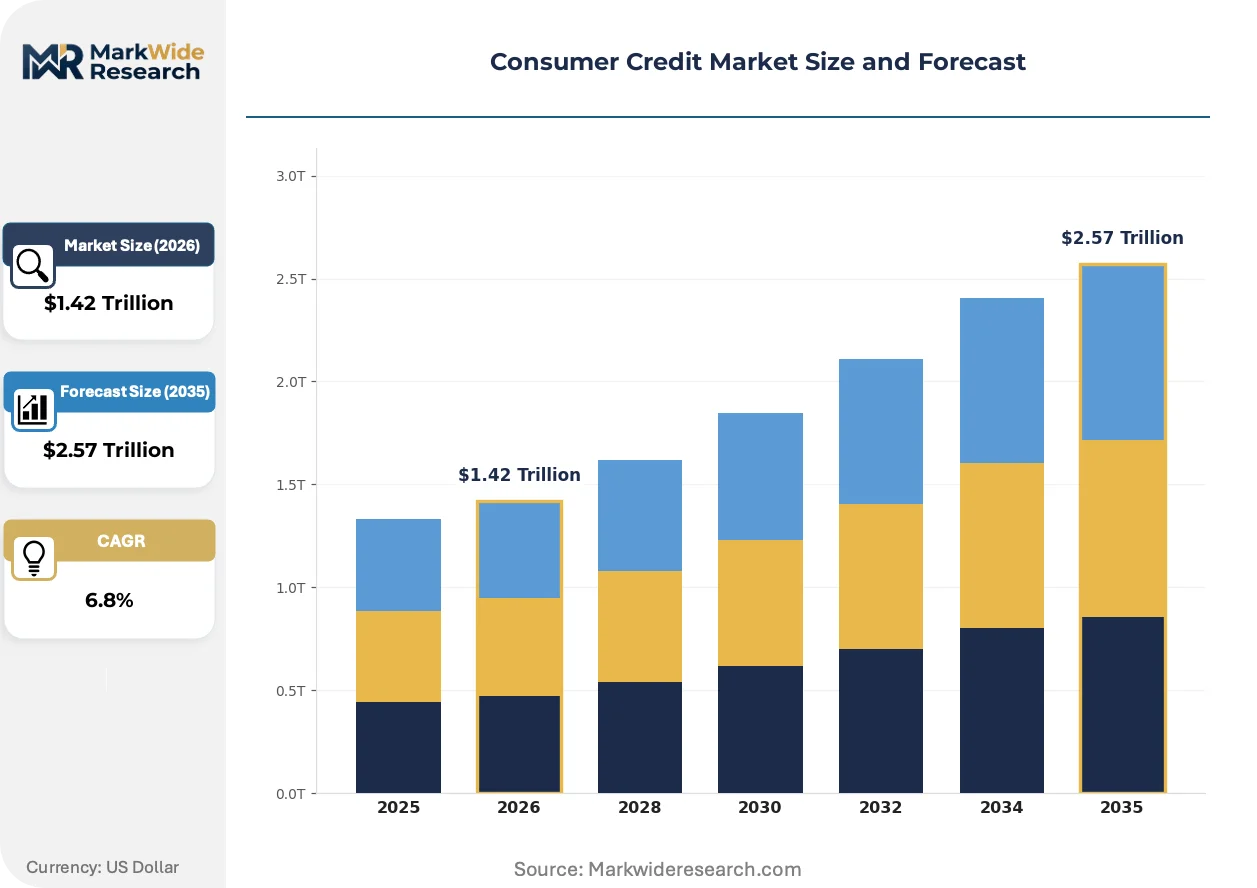
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $2.57 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Loans, Credit Cards, Mortgages, Student Loans End User: Consumers, Small Businesses, Corporations, Non-Profit Organizations Service Type: Online Lending, Traditional Banking, Peer-to-Peer Lending, Credit Unions Customer Type: First-Time Borrowers, Repeat Borrowers, High-Risk Borrowers, Low-Income Borrowers |
| Companies Covered | JPMorgan Chase & Co., Bank of America Corporation, Citigroup Inc., American Express Company, Capital One Financial Corporation, Discover Financial Services, Visa Inc., Mastercard Incorporated, Klarna Bank AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Credit Market Strategic Shifts & Innovations
Credit decisioning infrastructure is fragmenting into modular components as specialized providers unbundle what integrated banks once monopolized.
Embedded underwriting engines are decomposing the traditional loan application into invisible micro-decisions at checkout, merchant onboarding, and account opening. Fintech infrastructure providers embed these capabilities via single API calls, enabling non-financial brands to originate credit without building compliance operations. The structural consequence is compressing customer acquisition costs toward zero while shifting default risk concentration to balance-sheet-light platform operators.
Algorithmic accountability mandates from the EU AI Act and analogous US agency guidance are forcing documentation of training data provenance and proxy variable audits. Lenders must now maintain model cards demonstrating absence of prohibited discrimination across protected classes. Subprime and near-prime segments face the tightest compliance scrutiny as regulators target historically disparate impact in automated decisions.
Debt consolidation demand is rotating toward fixed-rate personal loans as revolving credit card balances lose favor among rate-sensitive households. Digital-native lenders capture this flow through rate-comparison aggregators that commoditize brand loyalty. The shift is most visible in US and UK markets where mortgage rate resets and cost-of-living pressures concentrate borrower attention on monthly payment reduction.
Consumer Credit Market Segmentation
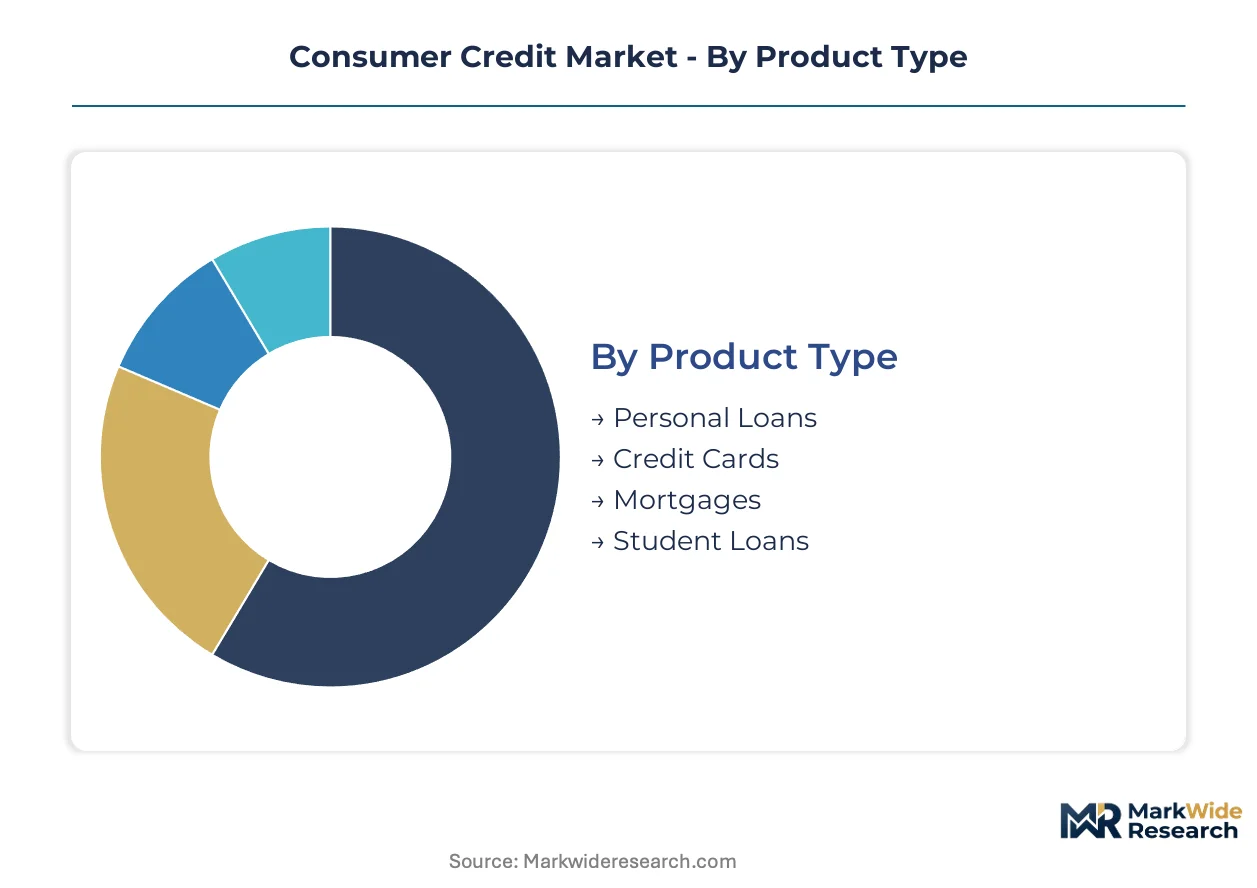
Consumer credit segmentation reveals divergent risk-return profiles across product structures and delivery channels. Lenders allocate capital differently across these boundaries, with regulatory treatment and funding costs varying substantially by category.
Product Type:
Substitution pressure runs strongest against revolving credit products as fixed-rate alternatives capture rate-sensitive households seeking payment certainty.
- Personal Loans:Unsecured installment credit with fixed amortization schedules ranging from 12 to 84 months. Demand concentrates among US and UK households pursuing debt consolidation as mortgage rate resets strain monthly budgets. Fintech lenders capture origination flow through rate-comparison aggregators that commoditize brand loyalty.
- Credit Cards:Revolving unsecured credit lines with variable interest rates tied to benchmark indices. Network operators Visa and Mastercard dominate transaction processing infrastructure while issuing banks retain credit risk. Profitability depends on interchange revenue and revolving balance yields.
- Mortgages:Long-duration secured lending collateralized by residential real estate. JPMorgan Chase leverages deposit-funded balance sheets to dominate US originations at scale.
- Student Loans:Government-guaranteed or private education financing with extended deferment periods. US Department of Education programs anchor volume despite political pressure for forgiveness restructuring.
Credit Cards retain volume leadership among unsecured products; Personal Loans hold the steepest expansion curve as debt consolidation demand accelerates.
End User:
Cost tier differentiation separates mass-market consumer offerings from specialized commercial facilities requiring bespoke covenant structures.
- Consumers:Individual borrowers seeking household liquidity for durable goods, medical expenses, or discretionary purchases. India Stack integration enables instant disbursal to thin-file borrowers previously excluded from formal banking.
- Small Businesses:Entrepreneurs accessing working capital or equipment financing through personal credit structures. Open banking APIs streamline underwriting by enabling real-time cash-flow verification beyond static credit scores.
- Corporations:Non-financial firms utilizing consumer credit architectures for employee benefit programs or vendor financing arrangements.
- Non-Profit Organizations:Mission-driven entities accessing subsidized credit facilities for community development or microfinance deployment.
Consumers anchor absolute origination volume; Small Businesses are expanding share fastest as digital onboarding reduces documentation friction.
Service Type:
Channel maturity separates established deposit-taking institutions from technology-native platforms still building regulatory compliance infrastructure.
- Online Lending:Digital-native originators using algorithmic underwriting and automated document verification. European lenders face GDPR-compliant alternative data constraints while US operators exploit regulatory arbitrage across state licensing regimes.
- Traditional Banking:Brick-and-mortar deposit institutions with legacy core systems and relationship-driven origination. Branch networks retain mortgage and student loan dominance despite digital erosion in unsecured products.
- Peer-to-Peer Lending:Marketplace platforms matching retail investors with borrower demand, now regulated as securities in multiple jurisdictions. SEC oversight of asset-backed securities constrains funding model evolution.
- Credit Unions:Member-owned cooperatives with tax-advantaged status and community charter limitations. Payroll-API integration opportunities remain underexploited relative to larger competitors.
Traditional Banking retains balance sheet dominance; Online Lending is gaining share fastest as embedded finance proliferates at retail checkout.
Customer Type:
Geographic concentration of credit-invisible populations creates divergent addressable market definitions across developed and emerging economies.
- First-Time Borrowers:Individuals establishing credit histories through secured cards or thin-file underwriting models. Account aggregator frameworks in India enable instant eligibility verification without traditional bureau scores.
- Repeat Borrowers:Established customers with demonstrated repayment histories qualifying for preferential pricing. Relationship data enables cross-sell of debt consolidation products at lower acquisition cost.
- High-Risk Borrowers:Subprime and near-prime segments facing tightened fair-lending scrutiny from the US Consumer Financial Protection Bureau. EU AI Act explainability mandates add compliance friction to machine-learning underwriting.
- Low-Income Borrowers:Households below median income thresholds accessing microfinance or earned-wage advance products. Responsible lending obligations in UK and Australian markets now capture BNPL products previously exempt.
Repeat Borrowers retain profitability leadership; First-Time Borrowers are expanding fastest as alternative data unlocks previously excluded segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Unified Payments Interface (UPI) infrastructure anchors India's role as the fastest-scaling digital credit market, processing billions of real-time transactions that feed alternative underwriting models.
United States
Mortgage rate resets and household debt consolidation propel fixed-rate personal loan demand through digital aggregators. The Consumer Financial Protection Bureau tightens fair-lending enforcement on algorithmic underwriting tools. New York and San Francisco fintech clusters concentrate venture capital flows into embedded finance infrastructure.
India
Account aggregator frameworks enable instant credit disbursal to thin-file borrowers previously excluded from formal banking. The Reserve Bank of India regulates digital lending apps through strict data localization and grievance redressal mandates. Mumbai and Bengaluru anchor the India Stack developer ecosystem driving API-native underwriting innovation.
United Kingdom
Debt consolidation demand rotates toward fixed-rate personal loans as revolving credit card balances lose favor among rate-sensitive households. The Financial Conduct Authority reclassifies buy-now-pay-later products under consumer credit laws, eliminating prior exemptions. London's fintech corridor hosts embedded finance providers integrating checkout credit at retail merchant touchpoints.
Germany
Open banking APIs decompose traditional credit underwriting by enabling real-time cash-flow verification beyond static bureau scores. The EU AI Act mandates explainability documentation for automated credit decisions, adding compliance friction. Frankfurt's banking cluster adapts legacy core systems for GDPR-compliant alternative data deployment.
Brazil
Smartphone-first financial service adoption accelerates formal credit penetration in underbanked populations. The Central Bank of Brazil's open finance regulations force incumbent banks to share customer transaction data with licensed competitors. São Paulo anchors Latin America's largest fintech ecosystem, concentrating digital lending platform headquarters and venture funding.
Consumer Credit Market Key Industry Players
Listed leaders compete with private specialists across balance-sheet capacity and technology velocity, creating a tiered structure where deposit-funded giants anchor mortgage volumes while agile fintechs capture unsecured origination growth. Incumbents leverage branch networks and regulatory licenses to defend core lending franchises. Three archetypes dominate: integrated universal banks with diversified funding bases, monoline card specialists with data-driven underwriting engines, and platform-native fintechs with embedded distribution partnerships. Competitive intensity concentrates on M&A targeting digital onboarding capabilities and strategic partnerships with retail merchants for point-of-sale credit integration.
Among deposit-funded universal banks, JPMorgan Chase & Co. exemplifies scale-driven origination dominance across mortgage and card products. Capital One Financial Corporation occupies a specialist position in subprime-to-prime customer migration strategies and algorithmic risk pricing. Klarna Bank AB represents the platform-native archetype, embedding buy-now-pay-later credit at European and North American retail checkout interfaces.
| Leading Market Players |
|---|
| JPMorgan Chase & Co. |
| Bank of America Corporation |
| Citigroup Inc. |
| American Express Company |
| Capital One Financial Corporation |
| Discover Financial Services |
| Visa Inc. |
| Mastercard Incorporated |
| Klarna Bank AB |
| Others |
Cost & Logistics Intelligence
Forty-five-day lead times on credit decisioning infrastructure compress pricing power for regional banks while amplifying margin capture for cloud-native platforms with API-native origination stacks. This temporal asymmetry rewards lenders who have rebuilt core systems around real-time data feeds rather than legacy batch processing.
Pricing Analysis
Volume-discount tiering structures separate prime-rate borrowers with deposit relationships from near-prime segments priced through risk-based models and subprime thin-file applicants assessed via alternative data premiums. Three-tier pricing stratifies across relationship-bundled, direct-to-consumer, and embedded checkout origination channels. Cost compression in the subprime tier intensifies as open banking APIs commoditize cash-flow verification and erode proprietary data advantages. Small business borrowers exhibit the highest price elasticity, while high-net-worth households with multi-product banking relationships demonstrate minimal rate sensitivity.
Supply Chain Analysis
Inventory-light balance sheet structures concentrate funding dependence on the United States, United Kingdom, and India as primary origination markets with deepest institutional investor pools for asset-backed securities. Capital formation draws from deposit bases, securitization warehouses, and peer-to-peer marketplace structures with varying cost and duration profiles. Single-source vulnerability runs through core banking platform vendors whose legacy architectures resist API-native middleware integration. Distribution runs through direct digital channels, branch networks, and embedded finance partnerships at retail merchant touchpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as open banking penetration in India, Brazil, and Southeast Asia unlocks thin-file borrower segments previously excluded from formal credit access.
For Market Incumbents: Shield core deposit-funded mortgage franchises from fintech disintermediation by accelerating API-native core system replacement and securing exclusive payroll-API data partnerships with workforce management platforms. Regulatory license moats in state-by-state US lending regimes and EU banking passports provide defensive leverage against unlicensed embedded finance entrants. Prioritize vertical integration into alternative data aggregation through account aggregator framework partnerships in India and open finance regulatory compliance in Brazil. For New Entrants and Emerging Players: Anchor in Indonesia, Vietnam, and Philippines where sub-twenty-percent formal credit penetration meets smartphone-first financial service adoption and minimal incumbent digital presence. White-space concentration appears in climate-linked consumer finance products—green home improvement loans and electric vehicle financing—where subsidized EU Green Deal capital pools reduce funding cost disadvantages against established banks. Pursue merchant-integrated point-of-sale credit origination as the primary go-to-market vector, leveraging single-API embedded finance infrastructure to bypass balance sheet and compliance buildout. For Investors and Strategic Acquirers: Long-term, this sits as a data-asset compounding play because credit underwriting algorithms trained on proprietary cash-flow datasets generate widening predictive accuracy gaps against bureau-score-dependent competitors. Acquisition targets should emphasize fintech infrastructure providers with embedded distribution partnerships and modular underwriting engines rather than monoline lenders with concentrated default risk. Monitor BNPL regulatory reclassification in UK and Australian markets as the signal to watch for responsible lending obligation expansion that could compress platform operator margins and trigger consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Core System Modernization | API-native loan origination platforms reduce middleware costs and enable real-time open banking integration for incumbent banks. |
| Payroll-API Partnership | Direct employment data feeds from workforce platforms improve default predictability beyond traditional credit bureau scores. |
| Embedded Finance Integration | Retail checkout credit origination compresses customer acquisition costs toward zero through merchant distribution partnerships. |
| Alternative Data Licensing | Account aggregator frameworks in India and open finance mandates in Brazil unlock thin-file underwriting for previously excluded borrowers. |
| Green Finance Certification | EU Green Deal-aligned institutional capital pools subsidize climate-linked consumer loan funding costs. |
Research Approach
Operator-level perspectives from chief risk officers, digital lending product heads, regulatory compliance directors, and securitization structurers anchored the qualitative base for this study. Primary fieldwork combined semi-structured interviews with secondary validation against SEC filings, RBI regulatory circulars, EU AI Act documentation, and open banking API technical specifications. Bottom-up origination volume modeling triangulated against top-down macroeconomic credit penetration benchmarks across the analysis window.
Sensitivity analysis tested forecast outputs against varying assumptions for interest rate trajectory, regulatory enforcement intensity, and alternative data adoption curves. Segmentation modeling spanned product type, service delivery channel, end-user category, and customer credit experience tier throughout the projection horizon. CAGRs were derived from fitted trend extrapolation with cross-validation against historical credit cycle amplitude, incorporating India Stack transaction velocity, EU GDPR compliance cost estimates, and US CFPB enforcement patterns as industry-specific inputs.
Decision-makers should treat outputs as directional under assumptions of continued open banking regulatory momentum and stable securitization market access; material deviation in macroeconomic conditions or algorithmic accountability enforcement would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Truck Financial Leasing Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Indonesia Mortgage/Loan Brokers Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
Alternative Lending Platform Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
Europe Syndicated Loans Market
Loans and Leasing
China Home Loan Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
North America Syndicated Loans Market
Loans and Leasing
Factoring Market
Loans and Leasing
India Car Loan Market
Loans and Leasing
Asia-Pacific Auto Loan Market
Loans and Leasing
Automotive Finance Market