
 Confectionery Flexible Packaging Market | 2026-2036
Confectionery Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Confectionery Flexible Packaging Market Outlook
Premium chocolate and functional confectionery demand is shifting toward single-serve and portion-controlled formats that require specialized barrier properties. Amcor leverages its global film manufacturing network to supply high-performance laminates for temperature-sensitive fillings. Berry Global anchors North American supply through vertically integrated resin-to-pouch production. Huhtamaki competes in emerging markets with localized paper-based flexible solutions.
Confectionery flexible packaging denotes pliable, multilayer structures—typically combining oriented polypropylene, polyethylene terephthalate, or metallized films with sealant layers—engineered to protect hygroscopic and lipid-rich products from moisture ingress, oxygen permeation, and aroma loss during distribution and retail display. Pouches and bags capture the dominant volume share as brands convert from rigid formats to reduce material weight and logistics cube. Composites lead material value pools due to their engineered barrier performance, though paper substrates are gaining structural traction where fiber-based barrier coatings meet retailer sustainability scorecards. Resealable closures command premium positioning as convenience-driven consumption patterns extend product freshness across multiple use occasions.
The US FDA maintains strict food-contact substance regulations under 21 CFR that govern additive migration limits into confectionery matrices, while the EU REACH framework restricts certain phthalates and heavy metals in printing inks and adhesives applied to primary packaging. These compliance requirements directly elevate R&D expenditure for substrate reformulation and push converters toward validated alternative chemistries. Stakeholders must monitor evolving extended producer responsibility schemes and chemical disclosure mandates that will determine which material platforms retain market access across key confectionery export corridors.
Market Dynamics
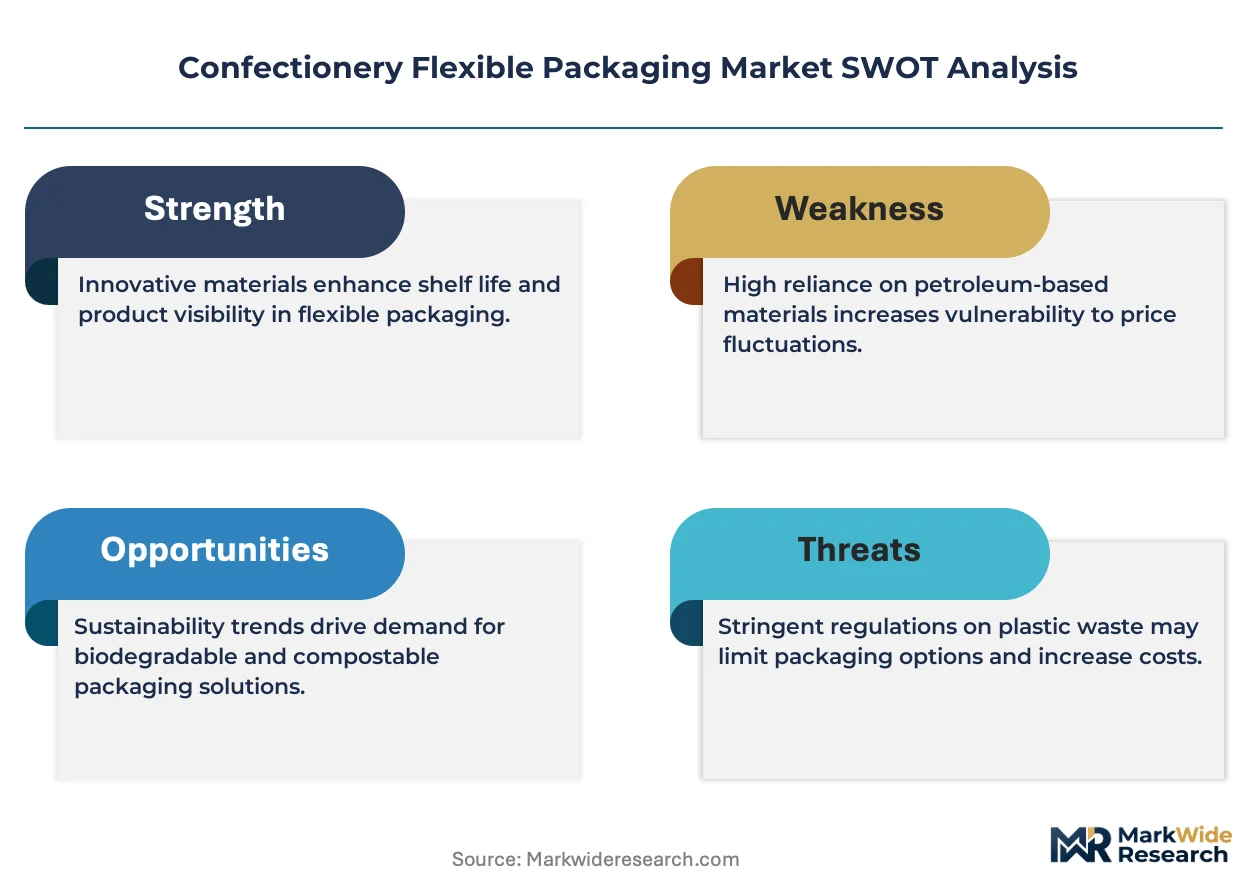
Europe's Packaging and Packaging Waste Regulation is forcing rapid substrate reformulation across multilayer film supply chains, compressing development timelines and elevating R&D expenditure for barrier coating alternatives.
Growth Catalysts
- EU Green Deal packaging mandates:Germany's confectionery exporters around Hamburg and Cologne are accelerating investment in recyclable high-barrier structures to maintain EU market access and retailer shelf placement.
- Premium chocolate portion control:Single-serve formats with resealable closures are pulling demand for engineered laminates that protect temperature-sensitive fillings across extended distribution cycles.
- Metallized film barrier performance:Oxygen and moisture ingress specifications for lipid-rich products are tightening, driving specification upgrades in oriented polypropylene and polyethylene terephthalate composites.
Market Restraints
- Resin supply concentration:Polypropylene and polyethylene feedstock volatility ties margin pressure to Gulf Coast petrochemical capacity and regional weather disruptions.
- Multilayer recyclability friction:Europe's ECHA restrictions on adhesive chemistries and the EU's extended producer responsibility schemes create compliance cost escalators for non-paper substrates.
- High-barrier coating capex:Vacuum metallization and aluminum oxide deposition equipment requires substantial capital commitment with long depreciation cycles.
Strategic Opportunities
- Paper substrate penetration:Fiber-based barrier coatings are opening shelf space with retailers scoring sustainability metrics, particularly in Nordic markets with advanced recycling infrastructure.
- Functional confectionery expansion:Probiotic and vitamin-fortified products require specialized oxygen scavenging and light-blocking properties that command specification premiums.
- India PLI scheme leverage:Domestic packaging converters can capture import substitution benefits as multinational confectionery brands localize production for South Asian distribution.
Industry Challenges
- Migration testing bottlenecks:FDA 21 CFR food-contact substance validation and EU REACH additive disclosure requirements extend product qualification timelines by 12-18 months.
- Adhesive chemistry transitions:Solvent-free and water-based lamination systems demand retraining of technical operators and recalibration of existing production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Confectionery Flexible Packaging Market |
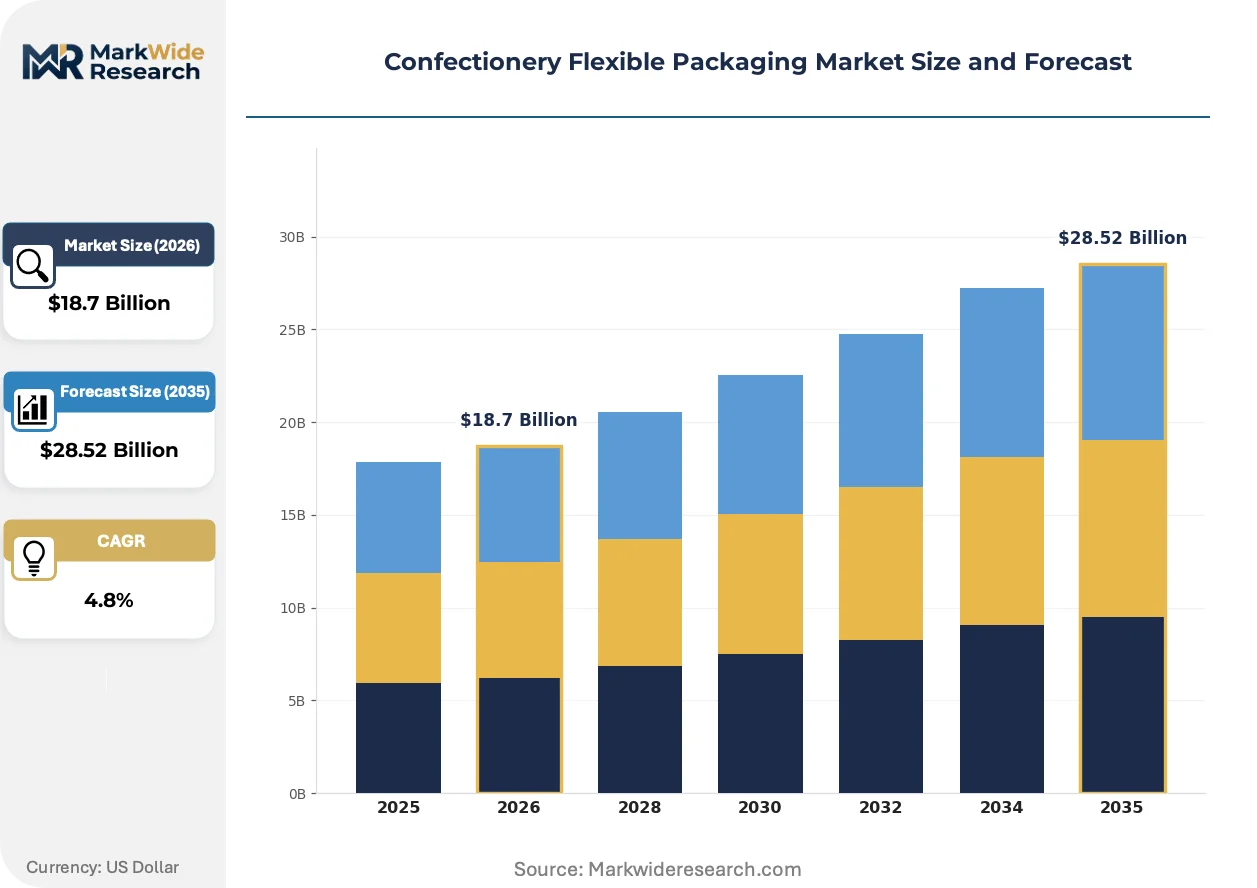
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wraps, Pouches, Bags, Films Material: Plastic, Paper, Foil, Composites Closure Type: Zip Lock, Heat Seal, Resealable, Ties End User: Retail, Food Services, E-commerce, Specialty Stores |
| Companies Covered | Berry Global, Sonoco Products, Amcor, Constantia Flexibles, Smurfit Kappa, Sealed Air, Huhtamaki, Clondalkin Group, Mondi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Confectionery Flexible Packaging Market Strategic Shifts
Barrier coating chemistry and closure engineering are converging to redefine freshness protection standards, while regulatory disclosure mandates and retailer scorecards are rewriting material specification protocols across the value chain.
Monomaterial polypropylene structures with ethylene vinyl alcohol coextrusion are consolidating technical preference for high-barrier confectionery applications. Mid-tier chocolate brands are migrating specification from aluminum-foil laminates to these recyclable alternatives at accelerating pace. This substrate shift is consolidating converter market share around film manufacturers with integrated metallization and coating capabilities.
REACH restrictions on phthalates and heavy metals in printing inks are eliminating legacy solvent-based gravure systems from EU-sourced packaging. Industrial consequence includes forced capital redeployment toward electron beam and UV curing technologies. Premium chocolate segments in Germany and Switzerland are responding fastest, demanding full chemical disclosure documentation from supply partners.
Brand-led sustainability scorecards are compressing supplier qualification cycles and unbundling traditional converter relationships. Major retailers in France and the UK are mandating fiber-based or certified recyclable packaging for private-label confectionery lines. This procurement pattern change is most visible in seasonal and gifting segments where packaging visibility drives purchasing decisions.
Confectionery Flexible Packaging Market Segmentation
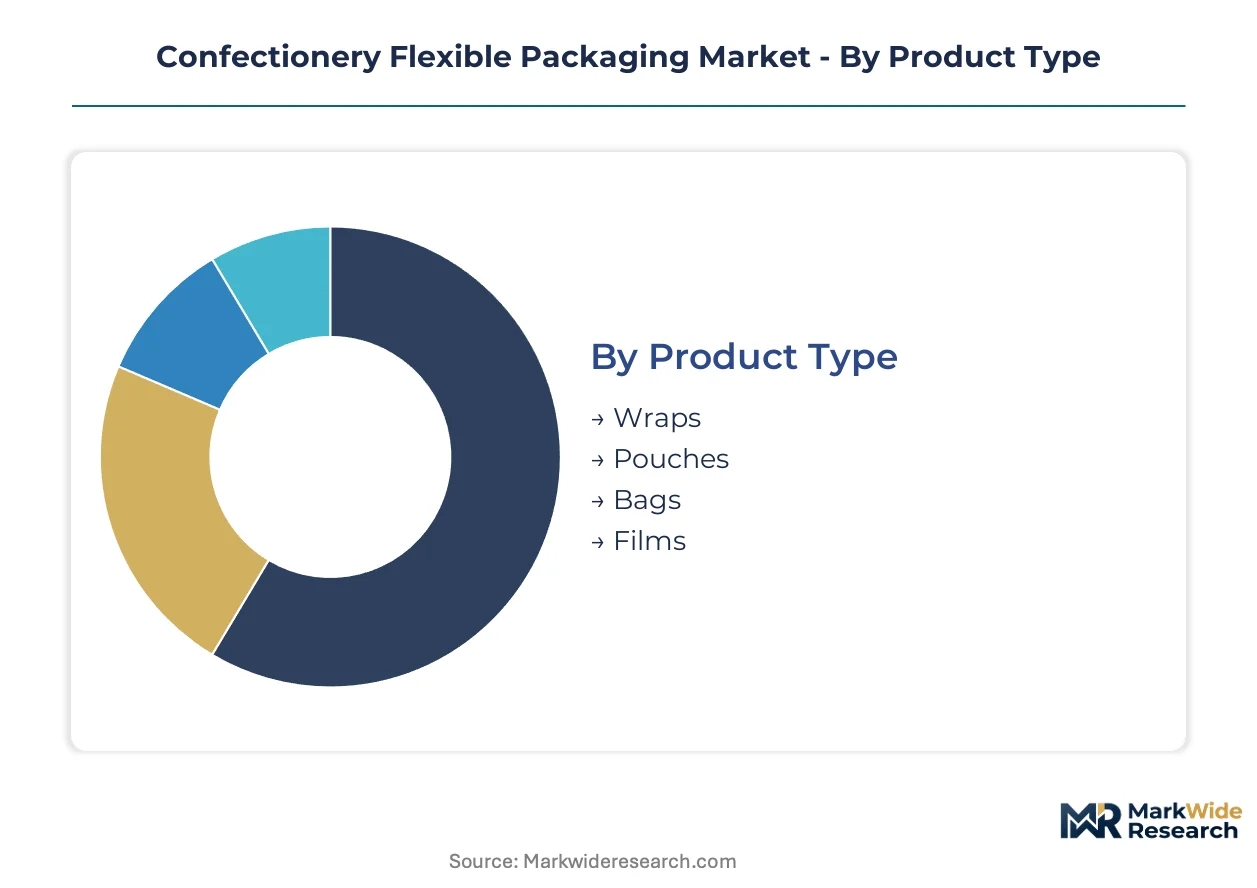
Confectionery flexible packaging segmentation reveals how capital allocation, barrier specifications, and distribution channels fragment technical requirements across substrate investments and conversion equipment. Each dimension carries distinct margin profiles and qualification timelines that reshape supplier positioning.
Product Type:
Capital intensity peaks with metallization and coating equipment for barrier-critical formats, while commodity extrusion lines serve lower-specification segments.
- Pouches:Multilayer laminates combining oriented polypropylene with sealant layers dominate premium chocolate applications. German exporters around Hamburg specify these for temperature-sensitive pralines requiring extended shelf stability.
- Bags:High-throughput form-fill-seal operations favor this format for mass-market hard candies and seasonal assortments. E-commerce fulfillment centers are pulling volume toward puncture-resistant constructions.
- Wraps:Twisted and flow-wrapped formats for individual piece counts.
- Films:Rollstock for in-house converter operations and private-label applications.
Most installed capacity flows through Bags. Expansion is steepest in Pouches.
Material:
Margin structure separates engineered barrier substrates from commodity alternatives, with sustainability premiums rewriting procurement scorecards.
- Composites:Metallized polyethylene terephthalate and aluminum oxide-coated films deliver oxygen transmission rates below 0.1 cc/m²/day for lipid-rich fillings. REACH compliance costs are accelerating specification shifts toward recyclable monomaterial alternatives in EU-sourced packaging.
- Plastic:Polypropylene and polyethylene monolayers and coextrusions anchor volume production.
- Paper:Fiber-based barrier coatings with heat-sealable layers are penetrating Nordic retail private-label lines where recycling infrastructure supports fiber recovery.
- Foil:Aluminum laminates for ultra-high barrier pharmaceutical-grade confectionery.
Composites command the highest unit economics. Paper is climbing the fastest on sustainability-driven specification changes.
Closure Type:
Convenience premiums and freshness extension requirements concentrate R&D spending on resealable mechanism engineering.
- Resealable:Press-to-close and slider mechanisms for premium chocolate portion control. Swiss and German brands mandate these for gifting formats where multiple consumption occasions drive perceived value.
- Zip Lock:Interlocking profiles for bulk and club-store formats.
- Heat Seal:Permanent closures for single-serve and sample applications.
- Ties:Twist and clip closures for traditional hard candy and seasonal products.
Heat Seal retains the broadest installed base. Resealable formats are expanding most quickly on convenience positioning.
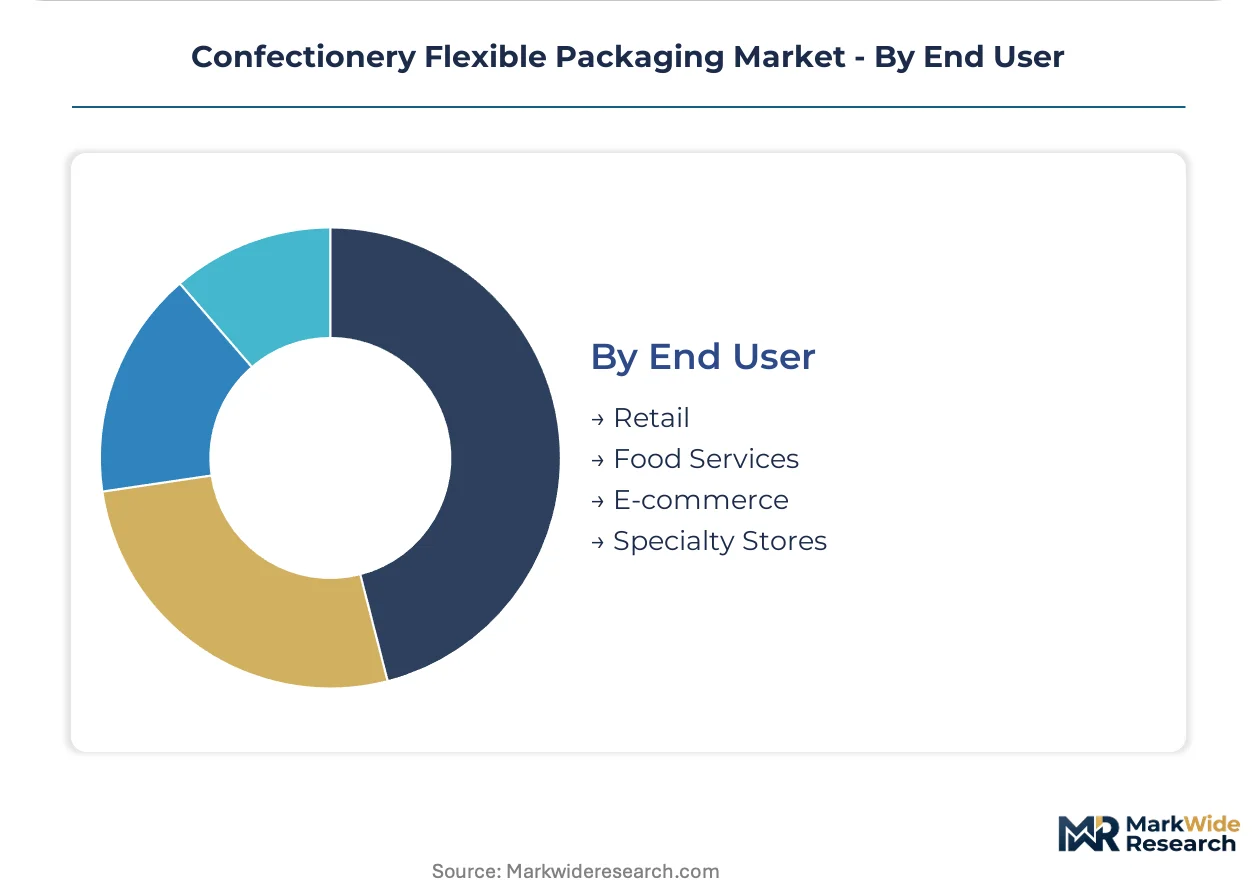
End User:
Channel-specific barrier and aesthetic requirements fragment converter customer relationships by qualification depth and order predictability.
- Retail:High-visibility shelf-ready packaging with registered graphics and hang-hole features. French and UK retailers are mandating fiber-based or certified recyclable substrates for private-label confectionery lines.
- E-commerce:Puncture-resistant, tamper-evident constructions for direct-to-consumer fulfillment.
- Food Services:Bulk formats for hospitality and institutional channels.
- Specialty Stores:Premium finishing and customization for artisanal and gifting segments.
Retail absorbs the majority of specification-qualified capacity. E-commerce is gaining share fastest on channel shift dynamics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting capital toward jurisdictions with clearer extended producer responsibility frameworks and established chemical disclosure protocols, compressing development timelines for converters operating in fragmented compliance environments.
Germany
Premium chocolate exporters in Hamburg and Cologne are driving specification upgrades for recyclable high-barrier pouches. The EU Packaging and Packaging Waste Regulation mandates recyclability targets that German converters must meet by 2030. North Rhine-Westphalia hosts the densest cluster of metallization and coating equipment serving continental European distribution.
United States
Mass-market confectionery brands and e-commerce fulfillment networks are pulling volume toward puncture-resistant bag constructions. FDA 21 CFR food-contact substance regulations govern additive migration limits into lipid-rich products. The Gulf Coast petrochemical corridor supplies polypropylene and polyethylene feedstock to converters across the Midwest and Southeast.
India
Multinational confectionery brands are localizing production for South Asian distribution, creating import substitution opportunities for domestic packaging converters. The PLI scheme incentivizes capital investment in specialized barrier film manufacturing. Maharashtra and Gujarat host emerging clusters of form-fill-seal operations serving both domestic retail and export markets.
Switzerland
Premium chocolate gifting segments are mandating full chemical disclosure documentation from supply partners. Swissmedic maintains pharmaceutical-grade standards that extend to ultra-high barrier confectionery applications. The Lake Geneva corridor concentrates specialized laminators serving luxury brand houses with extended shelf stability requirements.
France
Major retailers are mandating fiber-based or certified recyclable packaging for private-label confectionery lines. ECHA restrictions on phthalates and heavy metals in printing inks are eliminating legacy solvent-based gravure systems. The Île-de-France region anchors procurement pattern changes visible in seasonal and gifting segments.
Confectionery Flexible Packaging Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated film manufacturing capabilities commanding premium positioning in barrier-critical applications while regional converters capture volume in standardized formats. Three archetypes dominate: integrated resin-to-pouch producers with captive raw material supply, specialized metallization and coating houses with equipment scale advantages, and paper-based solution providers riding retailer sustainability scorecards. Competitive moves concentrate on M&A to secure coating technology assets and strategic partnerships to access certified recyclable substrate formulations.
Among integrated multinational packaging groups, Amcor, Berry Global, and Huhtamaki occupy positions that exemplify divergent strategic vectors—Amcor leveraging global film manufacturing networks, Berry Global anchoring North American supply through upstream resin control, and Huhtamaki competing with localized paper-based solutions in emerging markets. These three represent how scale, regional focus, and substrate specialization segment competitive positioning across premium chocolate, mass-market confectionery, and private-label retail channels.
| Leading Market Players |
|---|
| Berry Global |
| Sonoco Products |
| Amcor |
| Constantia Flexibles |
| Smurfit Kappa |
| Sealed Air |
| Huhtamaki |
| Clondalkin Group |
| Mondi |
| Others |
Value Chain & Pricing Dynamics
Monomaterial polypropylene migration is compressing converter economics while concentrating barrier-coating capability among integrated film manufacturers with captive metallization assets. This substrate transition simultaneously elevates capital requirements for oxygen transmission performance and eliminates price-competitive positioning for extrusion-only players lacking coating integration.
Pricing Analysis
Retailer markup layers for private-label confectionery lines are compressing as French and UK chains mandate fiber-based or certified recyclable substrates. Three-tier pricing structure across premium, standard, and economy levels separates Swiss chocolate gifting specifications from mass-market seasonal assortments. Cost compression in standard-tier laminates is intensifying because REACH-compliant adhesive reformulation extends qualification timelines. Mass-market hard candy brands exhibit highest price sensitivity; premium chocolate houses in Germany and Switzerland show lowest sensitivity due to gifting-occasion positioning.
Supply Chain Analysis
Dual-sourcing requirements from German exporters around Hamburg and Cologne are fragmenting order concentration across multiple converter relationships to mitigate ECHA adhesive chemistry transition risks. Resin supply concentrates in Germany, Belgium, and the Netherlands for polypropylene feedstock, while metallized film capability clusters in North Rhine-Westphalia. Raw material dependencies rest on Gulf Coast polyethylene, oriented polypropylene substrates, and aluminum oxide deposition precursors. Single-source vulnerability in vacuum metallization equipment creates bottleneck exposure. Distribution runs through continental European logistics hubs serving retail and e-commerce fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Confectionery flexible packaging operates as a late-cycle quality story where premium chocolate portion-control formats are displacing bulk packaging specifications. Brands are paying specification premiums for resealable closures and extended shelf stability that protect temperature-sensitive fillings.
For Market Incumbents: Extend barrier-coating capability through equipment acquisition or partnership to defend specification positioning as monomaterial polypropylene consolidates technical preference. Capture margin protection by anchoring resin supply through backward integration into polypropylene compounding or long-term offtake agreements with Gulf Coast petrochemical producers. Counter paper-substrate substitution threats by accelerating recyclable laminate certification with Nordic retailers scoring sustainability metrics. For New Entrants and Emerging Players: Enter via India's PLI scheme incentives for specialized barrier film manufacturing, targeting Maharashtra and Gujarat clusters where multinational confectionery brands are localizing production. Capture white-space in probiotic and vitamin-fortified functional confectionery packaging requiring oxygen scavenging and light-blocking properties. Lead with electron beam curing technology to bypass REACH restrictions on solvent-based gravure systems that eliminate legacy EU suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional converters lacking integrated metallization capability but holding established relationships with German exporters. Long-term viability over the projection horizon favors specialized coating houses with equipment scale advantages and validated alternative adhesive chemistries. Target acquisition profile centers on film manufacturers with aluminum oxide deposition assets serving Swissmedic pharmaceutical-grade standards. Watch ECHA disclosure mandate enforcement intensity as inflection indicator for compliance-cost escalators reshaping competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Monomaterial Polypropylene Migration | REACH-compliant recyclable laminates secure EU retailer shelf placement against aluminum-foil legacy specifications. |
| Electron Beam Curing Adoption | Eliminates solvent-based gravure systems restricted by ECHA phthalate and heavy metal regulations in EU-sourced packaging. |
| India PLI Scheme Leverage | Domestic converters capture import substitution benefits as multinational brands localize South Asian distribution. |
| Resealable Closure Engineering | Swiss and German gifting formats command convenience premiums through press-to-close mechanisms extending freshness. |
| Fiber-Based Barrier Coating Scale-Up | Nordic retail private-label lines reward paper substrate penetration where advanced recycling infrastructure supports fiber recovery. |
Study Parameters
Coverage spans Germany, United States, India, Switzerland, and France, with primary inputs from each jurisdiction combined with secondary validation. Interviews with packaging converters, brand procurement managers, metallization equipment suppliers, and retailer sustainability officers informed substrate specification shifts and regulatory compliance timelines. Secondary sources included EU Packaging and Packaging Waste Regulation documentation, FDA 21 CFR food-contact substance filings, ECHA REACH restriction updates, and trade flow data from German confectionery export corridors. Bottom-up capacity modeling triangulated against top-down demand projections from premium chocolate and functional confectionery growth patterns.
Granularity-level modeling operated at product type, material substrate, closure mechanism, and end-user channel dimensions, with additional segmentation by regional regulatory cluster reflecting EU Green Deal, FDA, and PLI scheme incentive structures. Volume and value outputs across the analysis window derived from installed capacity utilization rates, specification upgrade timelines, and substitution elasticity between composite and paper substrates. Industry-specific forecast inputs incorporated oxygen transmission rate requirements for lipid-rich fillings and retailer sustainability scorecard weightings.
Inputs from converter technical directors and brand R&D leads were available through the study window; gaps in real-time adhesive chemistry qualification timelines introduce uncertainty bands around monomaterial adoption velocity. Forecasts reflect assumptions regarding ECHA enforcement intensity and Nordic recycling infrastructure expansion. Deviation in EU extended producer responsibility fee structures would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Morocco Flexible Packaging Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
Canada Multilayer Flexible Packaging Market
Flexible Packaging
GCC Flexible Packaging Market
Flexible Packaging
India Flexible Packaging Market
Flexible Packaging
Thermoforming Packaging Market
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
Morocco Flexible Plastic Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
Africa Flexible Packaging Market
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
Industrial Flexible Packaging Market