
 Indonesia Construction Market | 2026-2036
Indonesia Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Construction Market Outlook
Indonesia is reshaping regional construction capacity through Nusantara capital relocation and Trans-Sumatra toll network expansion. PT Wijaya Karya (Persero) Tbk leverages state-backed infrastructure pipelines to dominate civil works procurement. PT Adhi Karya (Persero) Tbk anchors its position in railway and metro specialization. PT Waskita Karya (Persero) Tbk competes aggressively on toll road concessions and precast concrete supply.
Construction encompasses the engineering, procurement, and assembly of built assets using reinforced concrete, structural steel, and composite systems to specified load-bearing and seismic performance criteria. Its primary purpose spans shelter provision, commercial activity facilitation, and logistics infrastructure enablement. Residential project types currently lead volume absorption across Greater Jakarta and Surabaya metropolitan zones. Infrastructure segments generate the deepest margin pools given long-dated government payment guarantees and limited foreign bidder eligibility. Green building technology adoption remains nascent but is accelerating in premium commercial towers seeking EDGE or Greenship certification.
BIS standards compliance for structural steel imports, Ministry of Public Works and Housing building codes, and Bappenas national strategic project designations collectively shape contractor eligibility and material sourcing rules. These frameworks restrict foreign participation in designated strategic sectors while mandating local content thresholds. Stakeholders must monitor regulatory adjustments to domestic content requirements and Nusantara-specific procurement protocols as policy evolves.
Market Dynamics
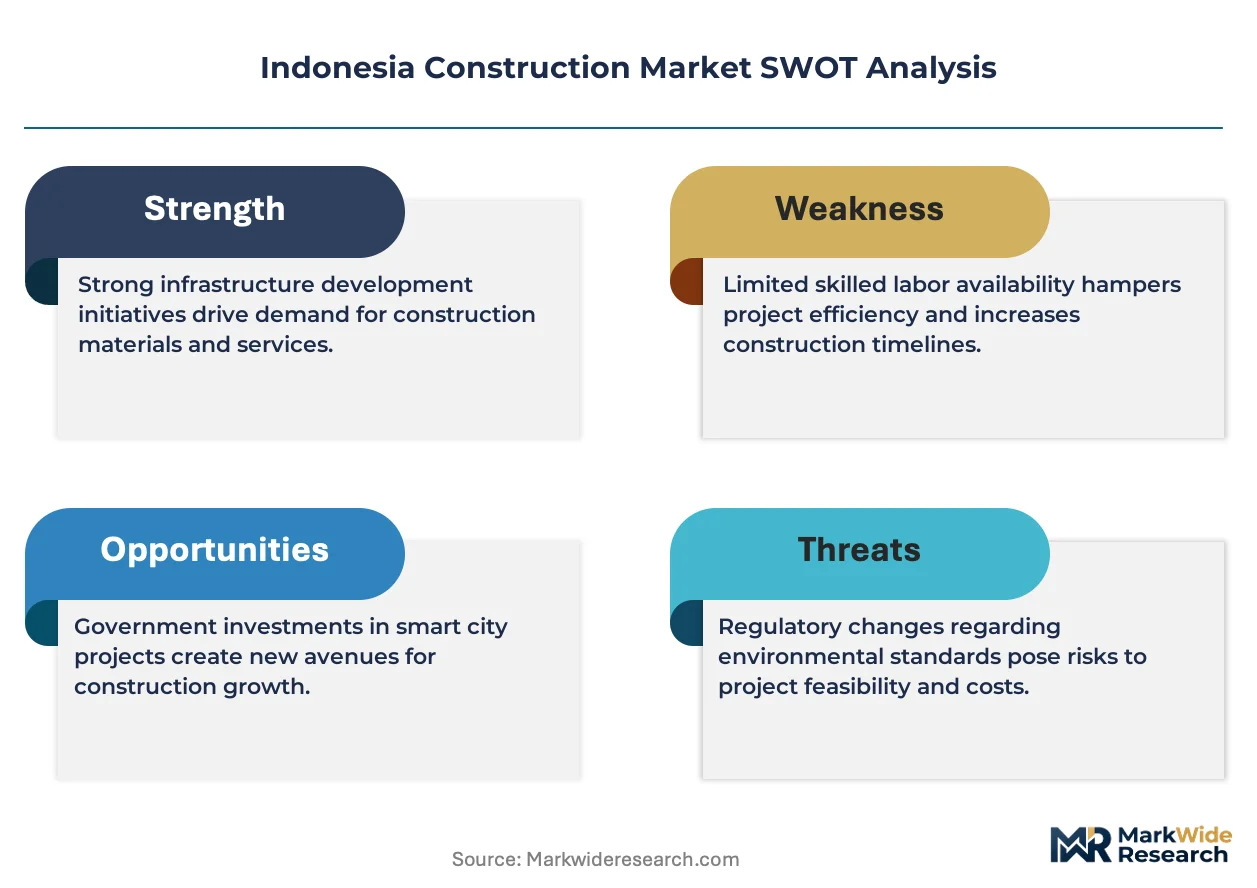
State-directed capital relocation to Nusantara is compressing traditional project pipelines while concentrating contractor eligibility around Bappenas strategic designations and local content mandates.
Growth Catalysts
- Trans-Sumatra Toll Network:The 2,800-kilometer highway program is absorbing precast concrete and asphalt supply chains across Sumatra's five provinces.
- BIS Certification Requirements:Mandatory domestic steel sourcing is redirecting procurement from imported H-beams to local mill production.
- Jakarta-Bandung High-Speed Rail:Operational corridor expansion is generating follow-on station precinct and transit-oriented development contracts.
Market Restraints
- Imported Cement Price Volatility:Bulk clinker shipments from Vietnam face unpredictable freight cost swings tied to Red Sea routing disruptions.
- Foreign Contractor Exclusion:Ministry of Public Works and Housing restrictions on strategic project bidding limit technology transfer from Korean and Japanese EPC firms.
- Geotechnical Complexity:Peatland subsidence across coastal Kalimantan sites demands specialized pile foundation techniques unavailable from domestic contractors.
Strategic Opportunities
- Eastern Indonesia Logistics Corridors:Sulawesi and Papua port modernization remains underpenetrated relative to Java-Bali saturation.
- Green Building Certification:Greenship and EDGE mandates for government buildings above 10,000 square meters are creating specialized MEP contracting niches.
- Modular Prefabrication:Factory-built volumetric units are converging with BIM workflows to compress on-site labor requirements for Nusantara residential zones.
Industry Challenges
- Geotechnical Engineering Talent Scarcity:Soft-soil specialists capable of managing peatland foundation design are concentrated in Bandung and Surabaya consulting pools.
- Multi-Tier Subcontractor Coordination:Nusantara project complexity requires integrating tier-three concrete suppliers with tier-one EPC schedulers across fragmented procurement platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Construction Market |
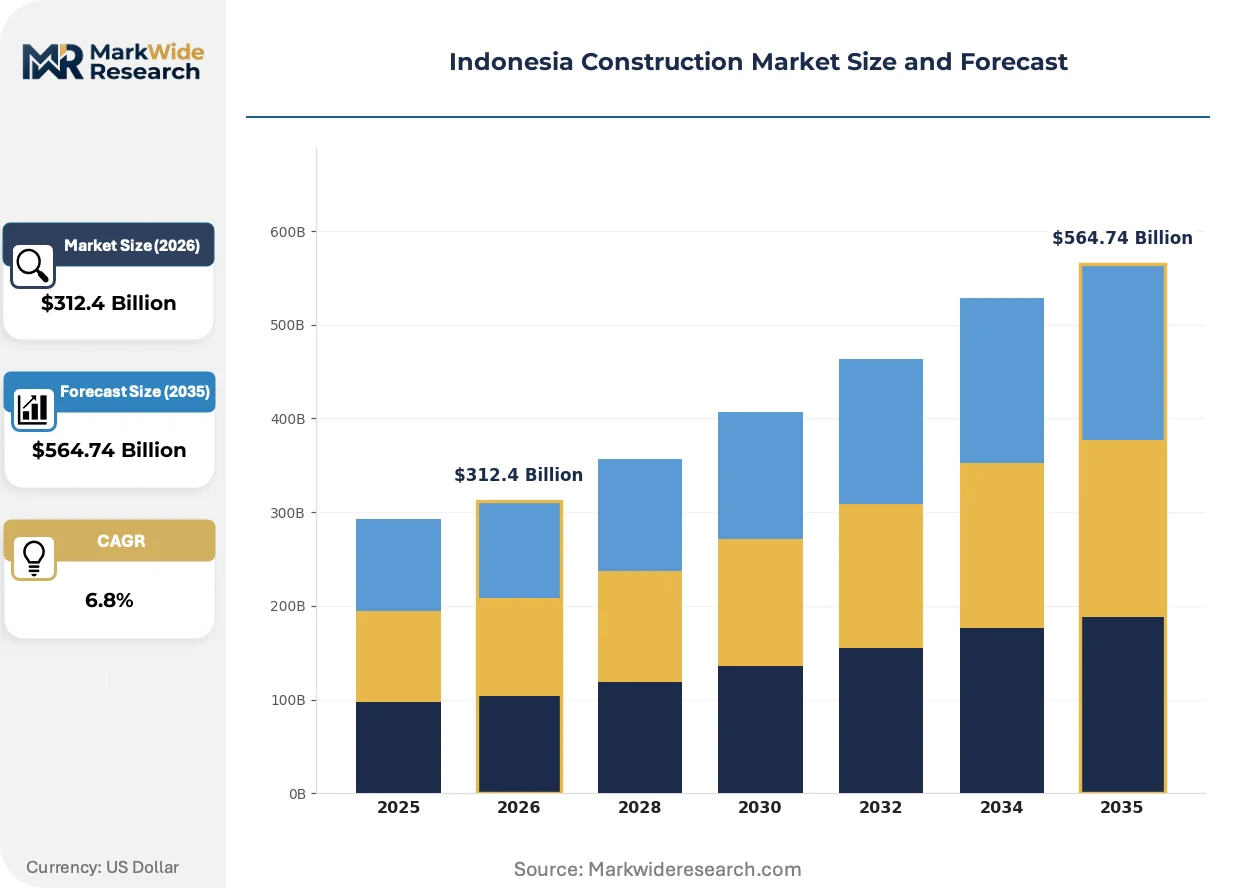
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Industrial, Infrastructure Material Type: Concrete, Steel, Wood, Glass Technology: Building Information Modeling, Prefabrication, Green Building, Smart Technologies Service Type: General Contracting, Design-Build, Construction Management, Consulting |
| Companies Covered | PT Wijaya Karya (Persero) Tbk, PT Adhi Karya (Persero) Tbk, PT Waskita Karya (Persero) Tbk, PT Pembangunan Perumahan (Persero) Tbk, PT Hutama Karya (Persero), PT PP (Persero) Tbk, PT Brantas Abipraya (Persero), PT Total Bangun Persada Tbk, PT Acset Indonusa Tbk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Construction Market Strategic Shifts
Digital fabrication and domestic material substitution are compressing traditional construction timelines while regulatory pressure accelerates environmental performance standards across public procurement.
Building Information Modeling (BIM) integrated with drone-based site surveying is collapsing the gap between design intent and as-built verification. State-owned contractors on Nusantara megaprojects are mandating 5D BIM for progress billing, forcing tier-two concrete suppliers to adopt Autodesk or Bentley platforms within compressed implementation windows. This technology convergence is collapsing traditional quantity surveying roles into integrated project delivery teams.
Ministry of Public Works and Housing Green Building regulations now mandate operational energy disclosure for commercial structures above 5,000 square meters. The framework requires post-occupancy performance verification, shifting contractor liability from construction completion to multi-year energy outcomes. Premium office developers in Jakarta CBD are responding with dedicated commissioning agent contracts and extended MEP warranty structures.
Consolidated procurement through state-owned holding companies is replacing fragmented agency contracting across toll road and railway programs. PT Wijaya Karya and PT Adhi Karya now bundle design, material supply, and maintenance into single-source agreements spanning 15-20 year concessions. This bundling is most visible in Trans-Java toll extensions where long-term performance bonds have displaced traditional defect liability periods.
Indonesia Construction Market Segmentation
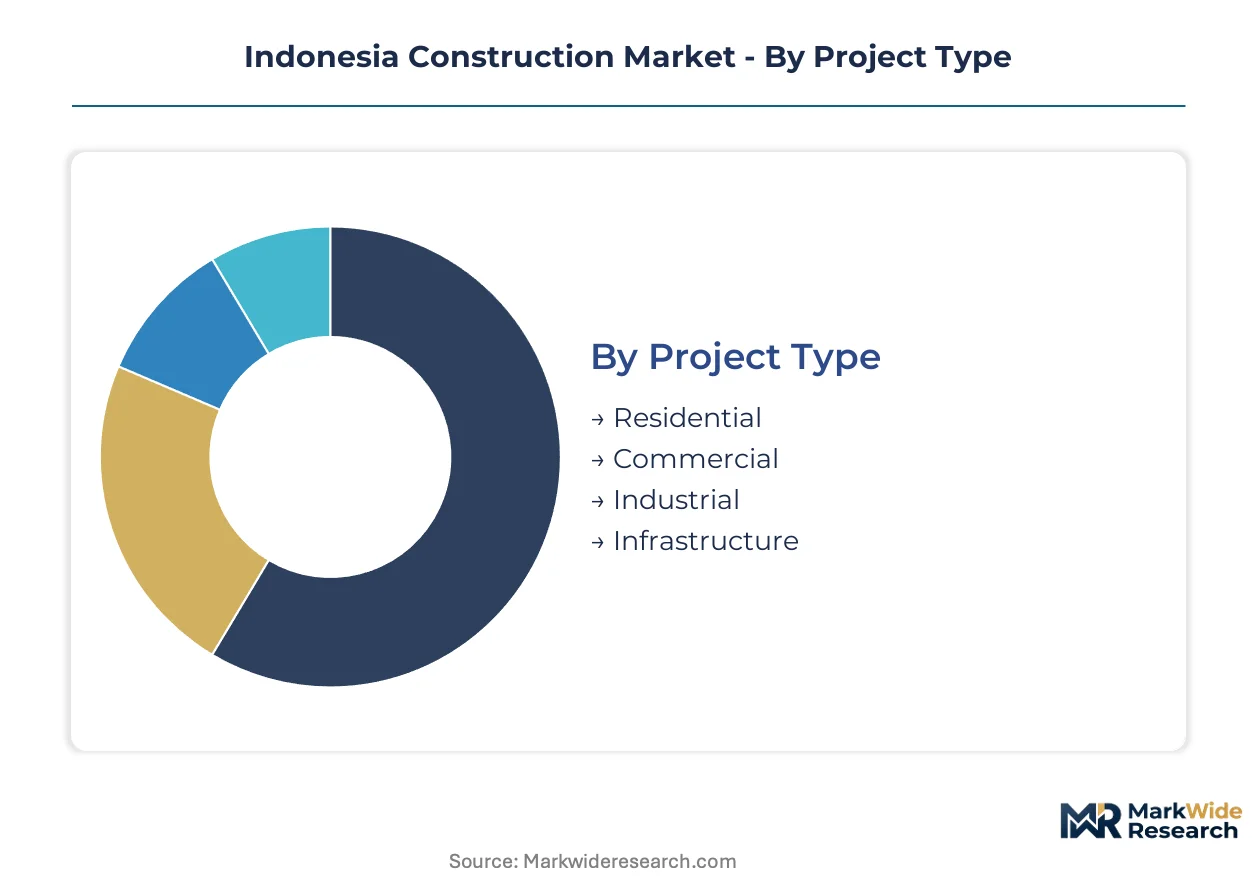
Construction market segmentation in Indonesia reveals how state-backed megaprojects and Nusantara capital relocation are redistributing contractor capacity across project scales and technical specializations. Understanding these divisions exposes where procurement rules, material sourcing mandates, and technology adoption create competitive moats.
Project Type:
Project scale spans individual housing units to thousand-kilometer transport corridors, with procurement complexity escalating alongside government payment guarantees and concession duration.
- Infrastructure:Toll roads, railways, ports, and utilities absorb the deepest capital pools through Bappenas strategic designations. Trans-Sumatra and Nusantara programs concentrate state-owned contractor eligibility around 15-20 year concession structures with performance-linked maintenance obligations.
- Residential:Vertical towers and landed housing estates dominate volume absorption across Greater Jakarta and Surabaya metropolitan zones. Developer consolidation around listed property groups is compressing subcontractor margins while accelerating modular prefabrication adoption.
- Commercial:Office towers and retail complexes in Jakarta CBD face Green Building regulations mandating operational energy disclosure above 5,000 square meters. Premium developers now embed extended MEP warranty structures to satisfy post-occupancy verification requirements.
- Industrial:Manufacturing facilities and logistics warehouses concentrate in Bekasi, Karawang, and Batang special economic zones. BIS certification requirements for structural steel are redirecting procurement from imported H-beams toward domestic mill supply.
Established volume favors Residential; emerging adoption favors Infrastructure.
Material Type:
Cost tier differentiation separates commodity bulk materials from specification-grade imports subject to certification barriers and freight volatility.
- Concrete:Precast and ready-mix formulations anchor civil works across toll road and railway programs. Domestic clinker grinding capacity expansion is reducing dependence on Vietnamese bulk shipments vulnerable to Red Sea routing disruptions.
- Steel:Structural H-beams and rebar face mandatory BIS compliance that redirects procurement toward Krakatau Steel and Gunung Raja Paksi production. Local mill capacity constraints create bottlenecks during Nusantara foundation phases.
- Wood:Engineered timber and tropical hardwoods serve low-rise residential and resort construction in Bali and Lombok. Sustainable forestry certification remains sparse, limiting access to green building premium pricing.
- Glass:Curtain wall and facade systems concentrate in Jakarta CBD premium towers seeking Greenship certification. Float glass imports from Thailand and Malaysia compete with Asahimas domestic production on lead time and specification flexibility.
Supply concentration favors Concrete; specification premium favors Steel.
Technology:
Maturity gradients separate mandated platforms on state megaprojects from discretionary adoption in private development.
- Building Information Modeling:5D BIM platforms from Autodesk and Bentley are mandatory for Nusantara progress billing, collapsing traditional quantity surveying into integrated project delivery teams. Tier-two concrete suppliers face compressed implementation windows to maintain eligibility.
- Prefabrication:Factory-built volumetric units compress on-site labor requirements for Nusantara residential zones. PT Waskita Karya precast yards are scaling capacity to serve Trans-Java toll extensions with standardized bridge components.
- Green Building:EDGE and Greenship certification accelerates in premium commercial towers seeking government tenant leases. MEP contractors with commissioning agent capabilities capture specialized niches above 10,000 square meter thresholds.
- Smart Technologies:IoT-enabled building management systems remain nascent outside Jakarta CBD flagship projects. Technology transfer restrictions limit Korean and Japanese systems integrator participation in strategic sectors.
Regulatory mandate favors Building Information Modeling; margin expansion favors Green Building.
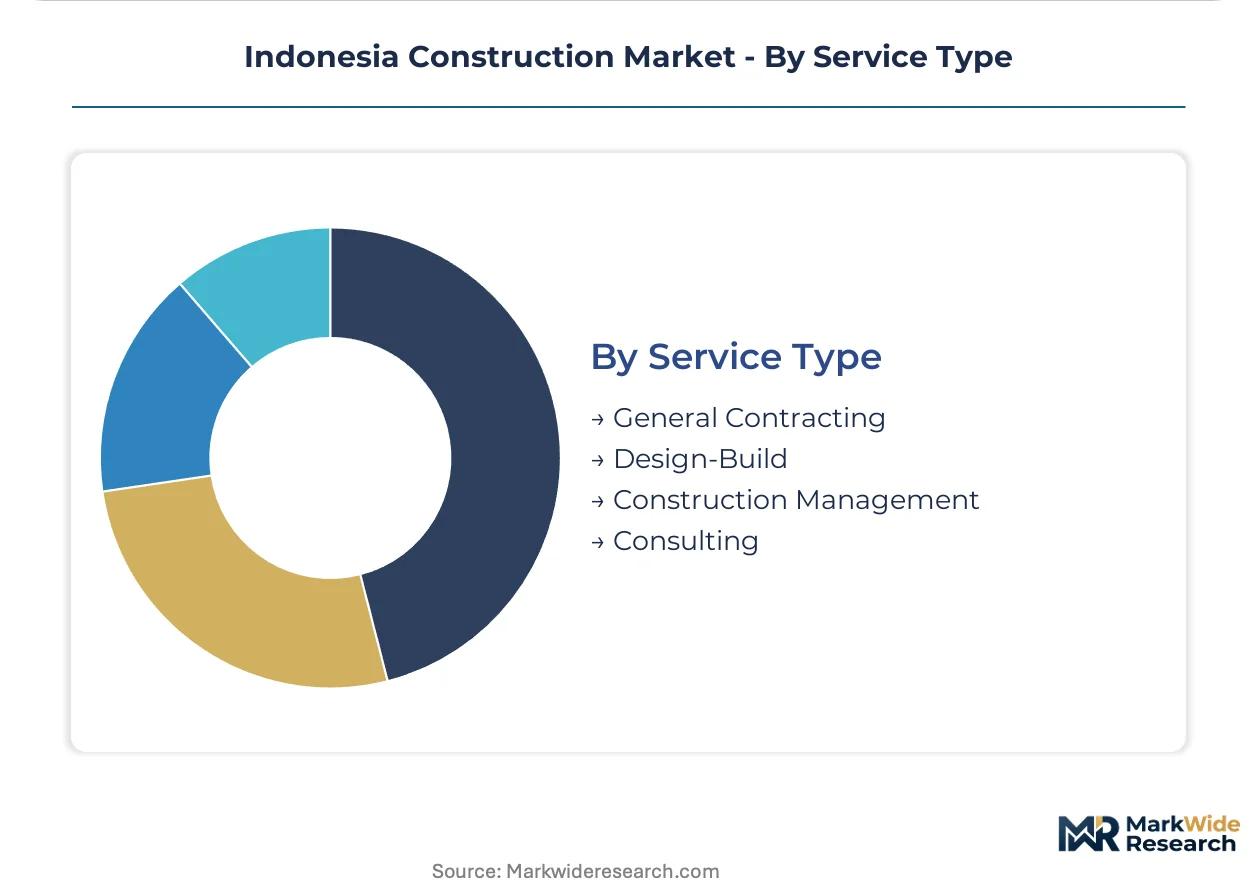
Service Type:
Customer type fragmentation separates consolidated state holding company procurement from fragmented private developer tendering.
- General Contracting:Traditional lump-sum arrangements dominate residential and commercial vertical construction. Fixed-price risk allocation is squeezing tier-three subcontractors on material price volatility.
- Design-Build:Single-source bundling of design, material supply, and maintenance spans 15-20 year concessions across Trans-Java toll extensions. PT Wijaya Karya and PT Adhi Karya leverage state-owned holding structures to capture integrated awards.
- Construction Management:Agency CM models penetrate complex Nusantara precincts requiring coordination across multi-tier subcontractor networks. Fee-based structures limit downside exposure compared to at-risk general contracting.
- Consulting:Geotechnical and structural engineering services concentrate in Bandung and Surabaya consulting pools. Soft-soil specialists capable of peatland foundation design command scarcity premiums across coastal Kalimantan sites.
Procurement consolidation favors Design-Build; technical complexity favors Consulting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction demand across Indonesia's archipelago fragments sharply between Java-Bali corridor saturation and Eastern Indonesia's logistics gaps. State capital relocation and trans-regional toll programs are redistributing contractor capacity toward frontier provinces.
Java-Bali Corridor
Jakarta CBD premium towers and Bandung-Surabaya industrial zones absorb the deepest private investment pools. Ministry of Public Works and Housing Green Building regulations mandate operational energy disclosure above 5,000 square meters. Bekasi-Karawang special economic zones concentrate manufacturing facility construction facing BIS-certified steel sourcing requirements.
Sumatra
The 2,800-kilometer Trans-Sumatra Toll Network anchors civil works demand across five provinces. Bappenas strategic project designations channel state-owned contractor eligibility toward 15-20 year concession structures. Medan and Palembang metropolitan zones generate secondary demand for precast concrete bridge components and asphalt supply chains.
Kalimantan
Nusantara capital relocation compresses traditional project pipelines while concentrating procurement around Bappenas local content mandates. Peatland subsidence across coastal sites demands specialized geotechnical pile foundation techniques. Balikpapan and Samarinda logistics hubs support precursor earthworks and material staging for the new capital zone.
Sulawesi
Makassar and Manado port modernization remains underpenetrated relative to Java-Bari saturation. The national strategic project framework designates nickel processing corridor infrastructure as priority sectors. Bitung and Morowali industrial zones attract smelter-adjacent construction with limited domestic contractor availability for process-heavy builds.
Papua
Remote logistics corridors face the widest contractor capability gaps and highest material freight costs. Ministry of Public Works and Housing restrictions on strategic project bidding limit technology transfer for specialized terrain engineering. Jayapura and Sorong anchor limited civil works demand tied to extractive industry access roads and coastal port upgrades.
Indonesia Construction Market Competitive Environment
Capability concentration sits with state-owned enterprises holding Bappenas strategic designations; scale advantage sits with diversified contractors bundling design, supply, and maintenance across multi-decade concessions. The vendor base stratifies into three tiers: integrated state holding companies capturing toll road and railway programs, mid-scale private developers competing on residential vertical construction, and fragmented tier-three concrete and steel suppliers facing compressed margins. Dominant competitive moves include 15-20 year concession bundling displacing traditional defect liability periods, and mandatory 5D BIM adoption forcing technology platform consolidation among material suppliers.
Within the state-owned tier, PT Wijaya Karya (Persero) Tbk, PT Adhi Karya (Persero) Tbk, and PT Waskita Karya (Persero) Tbk occupy positions defined by infrastructure specialization rather than private market competition. These Persero Tbk entities exemplify the integrated procurement model now standard across Trans-Java toll extensions and Nusantara megaprojects. Their concession-based structures represent a shift from agency contracting toward long-term performance obligations that reshape subcontractor risk allocation across the supply chain.
| Leading Market Players |
|---|
| PT Wijaya Karya (Persero) Tbk |
| PT Adhi Karya (Persero) Tbk |
| PT Waskita Karya (Persero) Tbk |
| PT Pembangunan Perumahan (Persero) Tbk |
| PT Hutama Karya (Persero) |
| PT PP (Persero) Tbk |
| PT Brantas Abipraya (Persero) |
| PT Total Bangun Persada Tbk |
| PT Acset Indonusa Tbk |
| Others |
Value Chain & Pricing Dynamics
Vietnamese clinker grinding capacity concentration directly determines margin distribution across Indonesia's ready-mix concrete tier, with domestic mill BIS certification mandates capturing value pools that imported H-beam suppliers forfeit.
Pricing Analysis
Long-term offtake contracts dominate infrastructure procurement, with 15-20 year concession structures bundling construction, maintenance, and performance bonds into single-source agreements. Price differentiation separates BIS-certified domestic steel from uncertified imports, while volume scale drives tiered concrete pricing across Nusantara megaprojects. Cost compression in tier-three subcontractor tiers is intensifying because fixed-price risk allocation exposes smaller suppliers to clinker freight volatility. State-owned contractors exhibit the lowest price sensitivity given government payment guarantees; private residential developers face acute margin pressure from material cost swings.
Supply Chain Analysis
Extended payment terms from state-owned holding companies are compressing working capital cycles for tier-two concrete suppliers, forcing supply-chain finance facility adoption. Geographic supply concentration centers on Vietnam for bulk clinker, China for specialty construction equipment, and domestic Krakatau Steel production for structural H-beams. Raw material dependencies include limestone feedstock, petroleum-derived asphalt binders, and copper-intensive MEP components. Single-source vulnerability runs through BIS-certified domestic mill capacity constraints during Nusantara foundation phases. Distribution runs through consolidated state holding company procurement platforms replacing fragmented agency tendering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's construction sector sits at a high-growth inflection point where mandatory 5D BIM adoption for Nusantara progress billing is collapsing traditional quantity surveying roles and forcing technology platform consolidation across the supplier base.
For Market Incumbents: Entrench concession bundling advantages by extending 15-20 year performance-linked maintenance obligations that displace traditional defect liability periods. Deepen backward integration into precast concrete production to capture Trans-Sumatra bridge component demand. Counter emerging modular prefabrication entrants by locking in BIM platform standardization across tier-two supplier networks. For New Entrants and Emerging Players: Pursue specialized geotechnical engineering niches in coastal Kalimantan peatland foundation design where domestic capability scarcity commands premium pricing. Target Eastern Indonesia logistics corridors in Sulawesi and Papua where port modernization remains underpenetrated relative to Java-Bali saturation. Lead with commissioning agent capabilities for Greenship and EDGE certification mandates above 10,000 square meter government building thresholds. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-scale private developers facing consolidation pressure around listed property groups in Greater Jakarta residential towers. Long-term viability hinges on exposure to Bappenas strategic designations and local content mandate compliance. Watch for regulatory adjustments to domestic content requirements as the primary inflection signal for contractor eligibility redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precast Concrete | Captures standardized bridge component demand across Trans-Sumatra and Trans-Java toll extensions. |
| 5D BIM Platform Adoption | Maintains eligibility for Nusantara progress billing under Ministry of Public Works mandates. |
| Greenship Certification Investment | Unlocks government tenant leases for commercial structures above 10,000 square meters. |
| Long-term Concession Bundling | Replaces fragmented agency contracting with integrated design-supply-maintenance awards. |
| Eastern Indonesia Geographic Expansion | Addresses logistics corridor gaps in Sulawesi and Papua with limited domestic competition. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with project directors at state-owned contractors, procurement managers at tier-two concrete suppliers, geotechnical engineering consultants, and Ministry of Public Works officials; and secondary validation through Bappenas strategic project databases, BIS certification registries, customs trade data for clinker imports, and SEC filings of listed construction entities. Bottom-up project pipeline aggregation triangulated against top-down macroeconomic construction spend estimates.
Forecast inputs considered infrastructure concession duration, residential developer consolidation patterns, and technology adoption curves across the projection horizon. Segmentation dimensions modeled include project type, material grade tier, technology maturity level, and service delivery model. CAGRs were derived from regression analysis of historical capital formation data against Bappenas pipeline commitments. Industry-specific inputs incorporated peatland foundation complexity premiums and BIM implementation cost curves.
Sensitivities concentrate around regulatory adjustments to domestic content thresholds, Nusantara procurement protocol evolution, and clinker freight cost volatility tied to Red Sea routing disruptions. Forecasts reflect documented assumptions about state capital relocation timelines and strategic project designation continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
3D Printing Building Construction Market
Building Construction
India Construction Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
United States Commercial Construction Market
Building Construction
Russia Prefabricated Buildings Market
Building Construction
Modular and Portable Building Market
Building Construction
Qatar Construction Market
Building Construction
UAE Facade Market
Building Construction
Brazil Construction Market
Building Construction
Middle East & Africa Infrastructure Construction Market
Building Construction
Turkey Commercial Construction Market
Building Construction
Mezzanine Floor Market
Building Construction
Japan Construction Market
Building Construction
Saudi Arabia Construction Market
Building Construction
China Construction Market
Building Construction
US Offsite Construction Market