
 Asia-Pacific Commercial Vehicles Market | 2026-2036
Asia-Pacific Commercial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Commercial Vehicles Market Outlook
Fleet operators in last-mile delivery is rotating share away from individual owner-operators across Southeast Asian urban corridors. BYD Company Limited leverages integrated battery-cell-to-chassis production to dominate electric bus tenders in Chinese megacities. Tata Motors anchors its position through in-house engine and axle manufacturing serving Indian construction and mining haulage. Isuzu Motors Limited specializes in light-duty diesel powertrains for Japanese logistics networks and ASEAN export markets.
Asia-Pacific commercial vehicles encompass motorized transport equipment engineered for goods and passenger carriage above three-and-a-half tonnes gross vehicle weight, incorporating ladder-frame chassis, multi-leaf or air suspension systems, and powertrains calibrated for 500,000-plus kilometre duty cycles. These platforms serve intercity freight, urban distribution, mining haulage, and scheduled public transit across archipelagic and continental terrain. Light-duty electric variants are capturing the fastest expansion as city governments restrict diesel entry, while heavy-duty diesel retains margin density in long-haul corridors where charging infrastructure remains sparse. Telematics integration is shifting from aftermarket retrofit to factory-fit standard as logistics end-users demand real-time payload and route optimization data.
China's MIIT enforces NEV credit mandates that compel domestic OEMs to maintain electric and hybrid production ratios, while India's BIS certification and CEA grid-integration standards shape battery-electric bus procurement protocols for state transport undertakings. Japan's METI fuel-efficiency benchmarks and Australia's ADR design rules further fragment type-approval requirements across the region. Stakeholders must monitor how divergent subsidy taper schedules and charging standards across Chinese, Indian, and ASEAN jurisdictions reshape cross-border fleet procurement and platform localization decisions.
Market Dynamics
Fleet electrification mandates across Chinese megacities and India's freight corridors are forcing OEMs to reallocate engineering resources from diesel refinement to battery-thermal management and integrated motor-axle architectures.
Growth Catalysts
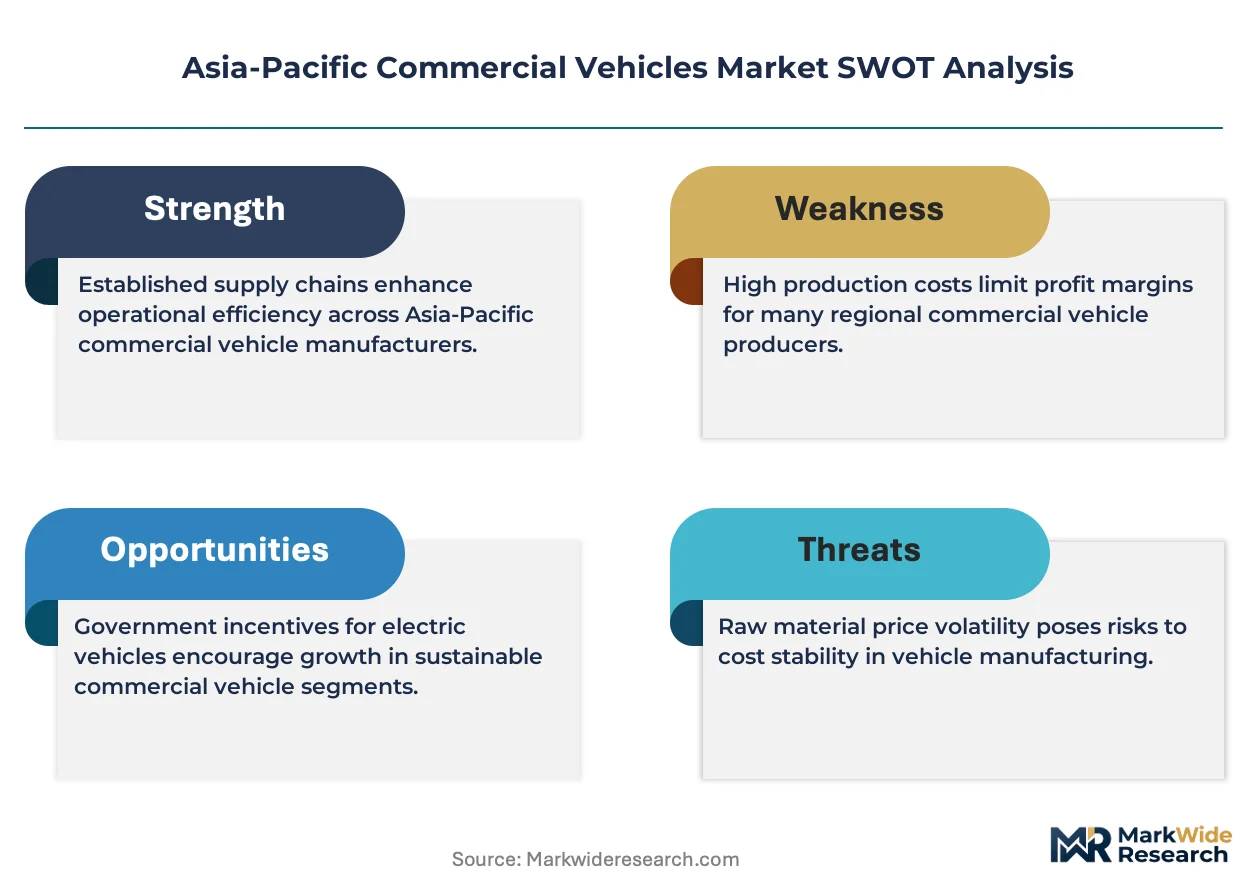
- China's MIIT NEV Credit Mandates:Domestic OEMs must maintain minimum electric and hybrid production ratios, compelling platform redesigns and joint-venture battery sourcing agreements.
- Last-mile logistics densification:E-commerce fulfillment networks in Jakarta, Bangkok, and Ho Chi Minh City are consolidating delivery volumes under fleet operators, concentrating procurement power.
- Battery-cell-to-chassis integration:Structural battery packs eliminate redundant frame members, reducing curb weight and extending range for urban bus and distribution van applications.
Market Restraints
- Lithium and rare-earth supply concentration:Cathode precursor refining clusters in specific Chinese provinces create input cost volatility and geopolitical exposure for non-Chinese OEMs.
- Heavy-duty charging infrastructure gaps:Megawatt-level charging corridors remain sparse on Australia's inland freight routes and India's Deccan Plateau highways.
- Diesel residual value uncertainty:Secondary market liquidity for pre-owned diesel trucks is compressing as ASEAN city councils accelerate entry restrictions.
Strategic Opportunities
- Vietnam and Philippines logistics modernization:Port automation and cold-chain expansion in these underpenetrated markets demand medium-duty refrigerated electric vehicles with tropical-climate thermal management.
- India's PLI scheme for automotive manufacturing:Component-level incentives for advanced chemistry cell production are attracting battery ecosystem investments adjacent to Tamil Nadu and Gujarat assembly plants.
- Telematics and payload optimization convergence:Real-time axle load monitoring combined with dynamic route algorithms enables pay-per-tonne insurance models for mining and construction haulage operators.
Industry Challenges
- High-voltage technician certification timelines:Australia's TGA-equivalent electrical safety frameworks and India's CEA grid-integration standards impose multi-month training pipelines that throttle service network expansion.
- Platform localization complexity:Divergent ASEAN type-approval requirements force OEMs to maintain parallel homologation tracks, inflating engineering overhead and compressing model-cycle economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Commercial Vehicles Market |
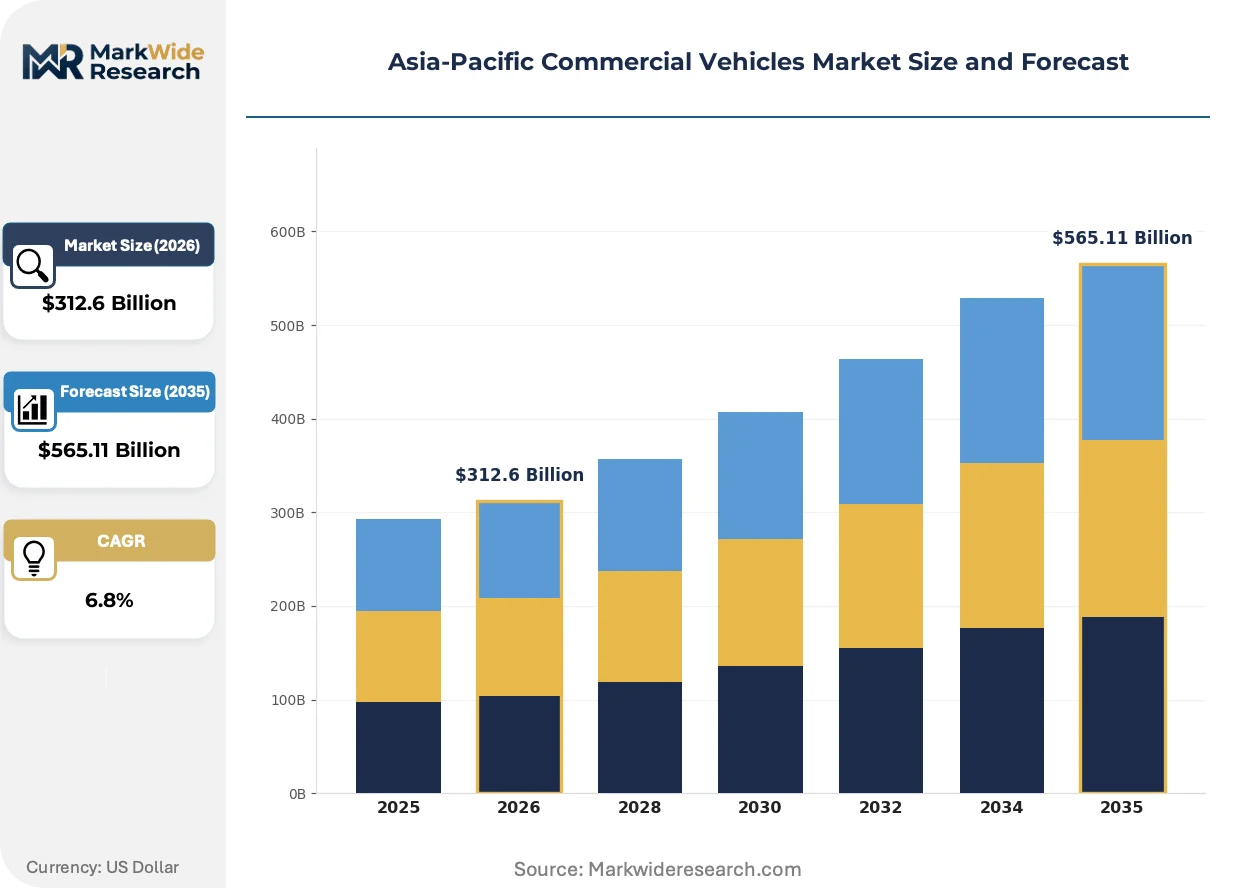
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Duty, Heavy Duty, Trucks, Buses Fuel Type: Diesel, Electric, Hybrid, CNG End User: Logistics, Construction, Public Transport, Delivery Services Technology: Telematics, Autonomous, ADAS, Infotainment |
| Companies Covered | Hino Motors, BYD Company Limited, Toyota Motor Corporation, Anhui Ankai Automobile Co. Ltd., Tata Motors, Isuzu Motors Limited, Mitsubishi Fuso Truck and Bus Corporation, Wuling Motors Holdings Limited, Dongfeng Motor Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Commercial Vehicles Market Strategic Shifts
Powertrain architectures and ownership models are diverging simultaneously as regulatory pressure and total-cost-of-ownership calculus reshape fleet procurement mathematics across the region.
Battery-electric powertrains is bifurcating the product portfolio into urban-optimized short-range variants and emerging long-haul prototypes with swappable or opportunity-charging architectures. Municipal bus operators in Shenzhen and Delhi are adopting the former at scale, while intercity freight trials in Japan and South Korea test the latter. This technical split is compressing the addressable market for conventional diesel-electric hybrids and forcing suppliers to choose specialization lanes.
India's BIS certification and CEA grid-integration standards are mandating fire-suppression protocols and charging interface specifications that exceed baseline UN regulations. These requirements are extending procurement timelines for state transport undertakings and favoring domestic battery pack assemblers with established testing relationships. The certification burden falls heaviest on light-duty electric truck categories where import volumes compete with localized production.
Fleet-as-a-service contracting is displacing traditional equipment financing in Southeast Asian urban corridors. Logistics aggregators in Singapore and Kuala Lumpur are bundling vehicles, charging infrastructure, and maintenance under per-kilometre or per-delivery tariffs. This model concentrates asset ownership with financial intermediaries and OEM-captive lessors, compressing margins for standalone dealerships and independent service providers.
Asia-Pacific Commercial Vehicles Market Segmentation
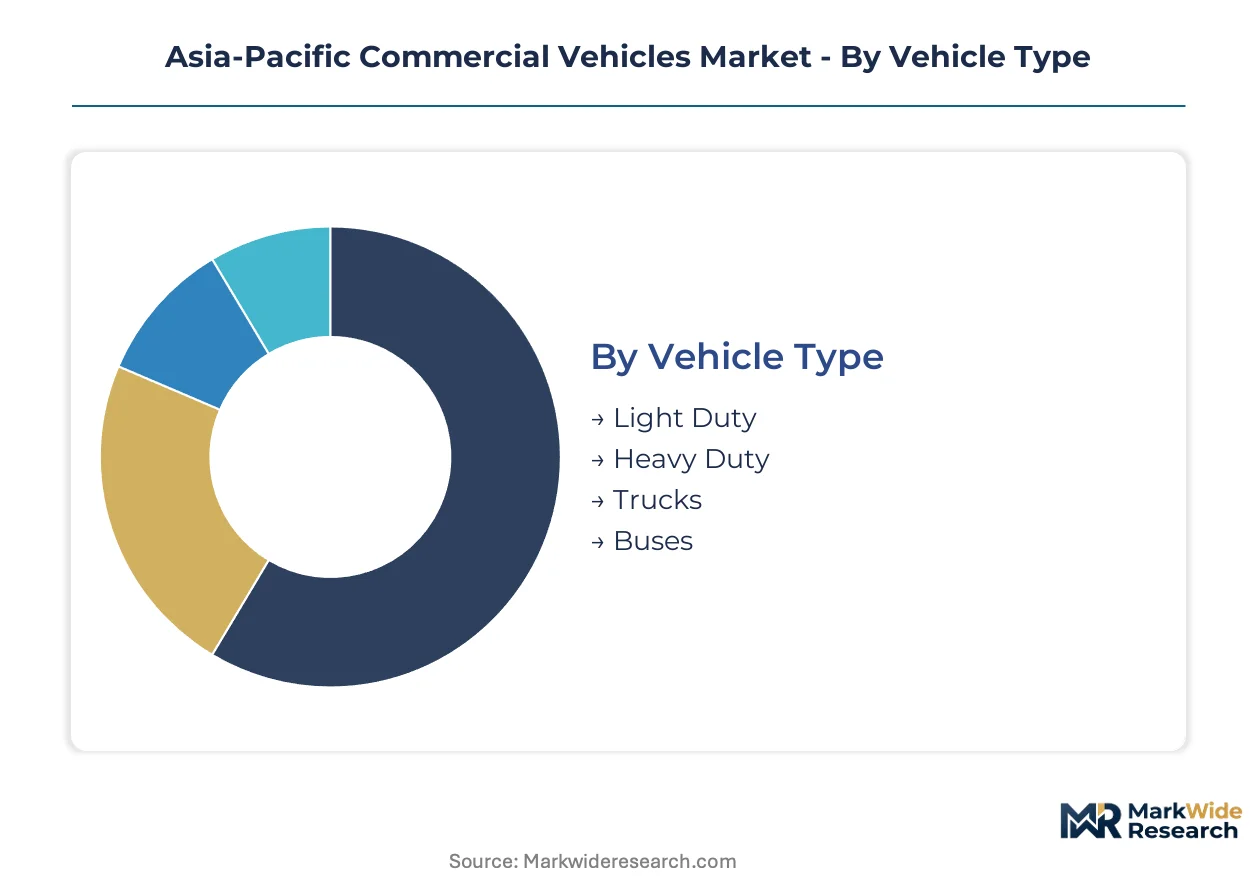
Segmentation in the Asia-Pacific commercial vehicles market reveals how divergent regulatory pressures and duty-cycle requirements are fragmenting procurement patterns across powertrain technologies and vehicle classes. Fleet operators now select platforms based on specific corridor electrification readiness rather than generalized payload capacity.
Vehicle Type:
MIIT NEV credit mandates in China and BIS certification protocols in India enforce distinct homologation requirements across weight classes, forcing OEMs to maintain parallel engineering tracks.
- Light Duty:Urban distribution vans and chassis-cab configurations optimized for sub-3.5-tonne payloads dominate last-mile logistics in Jakarta, Bangkok, and Ho Chi Minh City. Battery-electric variants capture procurement preference as municipal diesel entry restrictions tighten across ASEAN megacities.
- Heavy Duty:Multi-axle tractor-trailers and rigid trucks engineered for 40-tonne-plus gross combination weights serve mining haulage and interstate freight corridors. Diesel retains share here due to sparse megawatt charging infrastructure on Australia's inland routes and India's Deccan Plateau highways.
- Trucks:Medium-duty rigid platforms bridge urban distribution and regional freight with modular body configurations.
- Buses:Single-deck and articulated transit vehicles face accelerated electrification timelines under state transport undertaking procurement mandates.
Heavy Duty handles the majority of throughput; Light Duty is the fastest mover on share.
Fuel Type:
Cost tier differentiation separates established powertrains from emerging alternatives based on total-cost-of-ownership calculus across divergent duty cycles.
- Diesel:Compression-ignition engines with exhaust aftertreatment systems retain margin density in long-haul corridors where charging infrastructure remains sparse and residual value uncertainty compresses secondary market liquidity.
- Electric:Battery-electric powertrains with structural cell-to-chassis integration are eliminating redundant frame members to extend range for urban bus and distribution van applications in Shenzhen and Delhi.
- Hybrid:Diesel-electric parallel architectures face portfolio compression as pure electric variants mature and regulatory thresholds tighten.
- CNG:Compressed natural gas systems serve municipal refuse collection and airport ground support equipment with established refueling infrastructure.
Diesel retains volume leadership; Electric is expanding most quickly as fleet operators rotate procurement toward zero-emission mandates.
End User:
Application-specific duty cycles determine platform specifications, with mining and construction demanding durability ratings that diverge sharply from urban transit requirements.
- Logistics:E-commerce fulfillment networks concentrate procurement power under fleet operators, driving demand for telematics-integrated vehicles with real-time payload optimization across Southeast Asian urban corridors.
- Construction:Mining haulage and earthmoving applications in India's western freight corridors require ladder-frame durability and in-house axle manufacturing capabilities.
- Public Transport:State transport undertakings in India mandate BIS-certified battery packs with fire-suppression protocols exceeding baseline UN regulations.
- Delivery Services:Last-mile aggregators in Singapore and Kuala Lumpur are adopting fleet-as-a-service contracting with per-kilometre tariffs.
Logistics commands the largest procurement volumes; Delivery Services is climbing the fastest as urban densification accelerates.
Technology:
Customer type stratification separates factory-fit standard from aftermarket retrofit based on fleet size and data integration requirements.
- Telematics:Real-time axle load monitoring combined with dynamic route algorithms enables pay-per-tonne insurance models for mining and construction haulage operators.
- Autonomous:Port automation trials in Japan and South Korea test platooning and yard automation for intermodal freight transfer.
- ADAS:Advanced driver assistance systems including lane-keeping and collision mitigation face regulatory pressure for mandatory fitment.
- Infotainment:Cabin connectivity platforms serve driver retention objectives in long-haul fleet operations.
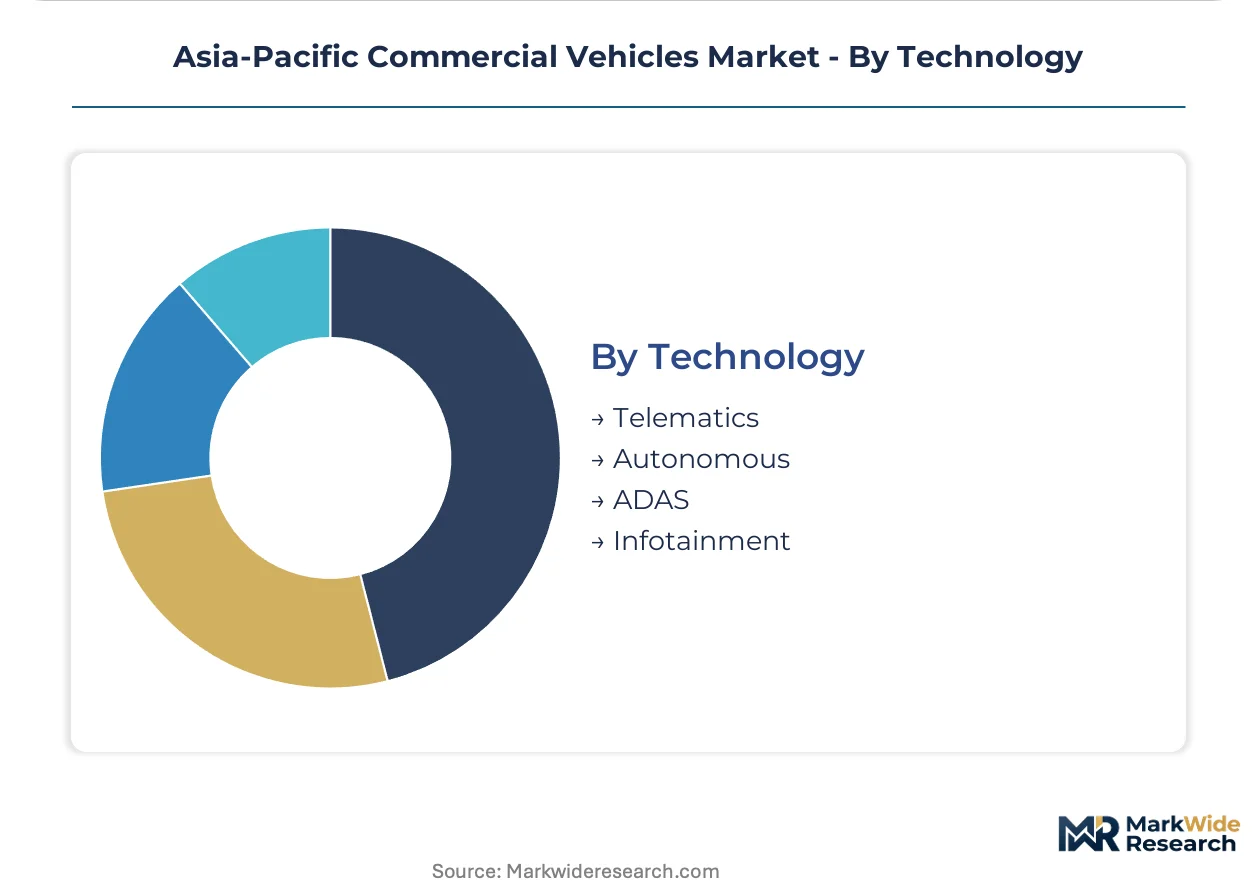
Telematics leads technology adoption; Autonomous systems are gaining share fastest in controlled-environment deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly capacity clusters along China's eastern seaboard and India's western industrial belt, with component sourcing networks radiating across ASEAN manufacturing corridors. Domestic OEMs in each jurisdiction leverage distinct regulatory frameworks to secure procurement advantages.
China
NEV credit mandates from MIIT compel domestic manufacturers to maintain minimum electric and hybrid production ratios across their portfolios. The Yangtze River Delta manufacturing cluster hosts integrated battery-cell-to-chassis production facilities serving municipal bus tenders in Shenzhen and Shanghai.
India
State transport undertakings are accelerating battery-electric bus procurement under BIS certification and CEA grid-integration standards. Tamil Nadu and Gujarat assembly plants attract PLI scheme incentives for advanced chemistry cell production adjacent to automotive manufacturing zones.
Japan
METI fuel-efficiency benchmarks shape powertrain development priorities for domestic logistics networks and ASEAN export markets. Kanto-based manufacturers specialize in light-duty diesel architectures optimized for high-frequency urban delivery cycles.
Australia
ADR design rules and sparse megawatt charging infrastructure on inland freight routes preserve diesel dominance in heavy-haul applications. Mining haulage operators in Western Australia and Queensland demand ladder-frame durability ratings exceeding standard highway specifications.
Vietnam
Port automation and cold-chain expansion in Ho Chi Minh City and Hanoi logistics corridors drive demand for medium-duty refrigerated vehicles. Tropical-climate thermal management requirements favor localized assembly partnerships over direct import strategies.
Asia-Pacific Commercial Vehicles Market Competitive Environment
Concentration sits with diversified automotive conglomerates possessing captive powertrain manufacturing and established distribution networks across multiple national markets. The competitive structure tiers into integrated battery-electric specialists, diesel-dominant regional haulage suppliers, and fleet-service bundlers. Dominant moves include joint-venture battery sourcing agreements and factory-fit telematics standardization.
Among China-based manufacturers, BYD Company Limited and Dongfeng Motor Corporation exemplify the integrated battery-electric archetype through structural cell-to-chassis architectures. Tata Motors anchors the India-based tier with in-house engine and axle production serving construction and mining segments. Hino Motors occupies a position within the Japanese specialist tier focused on light-duty diesel optimization for logistics networks.
| Leading Market Players |
|---|
| Hino Motors |
| BYD Company Limited |
| Toyota Motor Corporation |
| Anhui Ankai Automobile Co. Ltd. |
| Tata Motors |
| Isuzu Motors Limited |
| Mitsubishi Fuso Truck and Bus Corporation |
| Wuling Motors Holdings Limited |
| Dongfeng Motor Corporation |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day battery pack lead times from cathode precursor refiners in Chinese provinces concentrate pricing power with integrated cell manufacturers serving Yangtze River Delta assembly plants. This inventory compression amplifies cost pass-through to fleet operators while OEMs with captive battery sourcing maintain margin buffers against lithium carbonate volatility.
Pricing Analysis
MIIT NEV credit mandates dictate the pricing tier structure across China's commercial vehicle procurement landscape. Three-tier pricing structure across premium, standard, and economy levels separates BYD's integrated cell-to-chassis platforms from joint-venture battery sourcing arrangements and import-dependent configurations. Price differentiation hinges on certification grade under BIS protocols and volume scale commitments from state transport undertakings. Cost compression in light-duty electric truck categories is intensifying because India's PLI scheme attracts localized cell production adjacent to Tamil Nadu assembly zones. Fleet-as-a-service aggregators in Southeast Asian urban corridors exhibit highest price sensitivity; mining haulage operators in Western Australia demonstrate lowest sensitivity due to durability-rated specifications.
Supply Chain Analysis
Port congestion at Shanghai-Ningbo and container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for non-integrated OEMs. Geographic supply concentration centers on China for cathode precursors and cell manufacturing, South Korea for electrolyte and separator technologies, and Indonesia for nickel processing. Raw material dependencies span lithium carbonate from Australian spodumene, rare-earth magnets from Chinese separation facilities, and high-grade steel from Japanese blast furnaces. Single-source vulnerability in cathode precursor refining clusters creates geopolitical exposure for Tata Motors and Isuzu Motors procurement teams. Distribution runs through OEM-captive lessors consolidating asset ownership under per-kilometre tariff structures across Singapore and Kuala Lumpur logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified high-voltage technicians capable of servicing megawatt charging architectures constrains service network expansion across Australia's inland freight routes and India's Deccan Plateau highways. This capability gap favors OEMs with in-house training pipelines and joint-venture technical institutes.
For Market Incumbents: Compound defensive positioning through backward integration into battery cell production adjacent to existing assembly footprints in Tamil Nadu and Gujarat. Secure joint-venture cathode precursor agreements with Chinese refiners to buffer lithium cost volatility threatening margin density in heavy-duty diesel segments. Prioritize certification investment under Australia's TGA-equivalent electrical safety frameworks to accelerate technician pipeline expansion ahead of competitors. For New Entrants and Emerging Players: Differentiate on tropical-climate thermal management capabilities for medium-duty refrigerated electric vehicles serving Vietnam and Philippines cold-chain modernization. Target underpenetrated port automation corridors in Ho Chi Minh City and Hanoi where established OEMs lack localized assembly partnerships. Pursue fleet-as-a-service contracting with logistics aggregators bundling charging infrastructure under per-delivery tariffs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive conglomerates spinning off commercial vehicle divisions to focus on passenger electrification. Long-term viability over the next decade rests on battery ecosystem control and telematics platform ownership rather than powertrain manufacturing scale. Monitor BIS certification timeline compression for state transport undertakings as inflection indicator for domestic battery pack assembler consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Joint-venture cathode sourcing with Chinese refiners locks in lithium carbonate cost stability for OEM platform economics. |
| Platform Standardization | Structural cell-to-chassis architectures eliminate redundant frame members across urban bus and distribution van applications. |
| Geographic Manufacturing Footprint | Tamil Nadu and Gujarat assembly plants leverage PLI scheme incentives for advanced chemistry cell production localization. |
| Charging Infrastructure Partnership | Megawatt corridor development on Australia's inland routes and India's Deccan Plateau highways enables heavy-duty electric penetration. |
| Software-Defined Vehicle Investment | Factory-fit telematics standardization shifts from aftermarket retrofit to real-time payload optimization for mining haulage operators. |
Study Parameters
Operator-level perspectives from fleet procurement managers, OEM platform engineers, state transport undertaking directors, and charging infrastructure developers anchored the qualitative base. Primary interviews with Tier 1 supplier procurement teams and aftermarket service heads combined with secondary validation from vehicle production databases, IHS Markit registration data, MIIT NEV credit filings, and BIS certification records. Bottom-up segment sizing across vehicle class, propulsion architecture, and regional production clusters triangulated against top-down macroeconomic indicators.
Sensitivity analysis around lithium carbonate price bands, subsidy taper schedules, and charging infrastructure deployment rates informed the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle type, fuel architecture, end-use application, and technology integration level. CAGRs derived from historical production trajectories and policy-mandated procurement timelines incorporated fleet electrification mandates, PLI scheme incentive structures, and municipal diesel entry restrictions as industry-specific forecast inputs.
Material uncertainties — abrupt subsidy withdrawal, cathode precursor export restrictions, or megawatt charging standard fragmentation — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory continuity and mineral supply chain stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Tank Car Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
Cryogenic Liquid Transport Vehicle Market
Commercial Vehicles
France Light Commercial Vehicles Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
Global Fuel Cell Commercial Vehicle Market
Commercial Vehicles
ASEAN Commercial Vehicles Market
Commercial Vehicles
Electric Truck Market
Commercial Vehicles
Robotic Haul Trucks Market
Commercial Vehicles
Malaysia Box Truck Market
Commercial Vehicles
Compact Utility Vehicles Market
Commercial Vehicles
Commercial Vehicle Driveline Support Bearings Market
Commercial Vehicles
Waste or Garbage Collection Vehicle Market
Commercial Vehicles
Global Commercial Vehicles Market
Commercial Vehicles
Flatbed Semi-Trailer Market