
 Saudi Arabia Adhesives Market | 2026-2036
Saudi Arabia Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Adhesives Market Analytics
Construction sector procurement is restructuring the Saudi Arabia adhesives demand profile as giga-project execution intensifies across NEOM, Qiddiya, and the Red Sea coast. Sika Saudi Arabia Limited anchors its position through specialized concrete bonding and waterproofing systems tailored to desert climate conditions. Dow Saudi Arabia leverages its upstream petrochemical integration to secure feedstock cost advantages for acrylic and polyurethane resin production. H.B. Fuller Company competes through hot-melt adhesive technology leadership in packaging applications serving the Kingdom's fast-moving consumer goods sector.
Saudi Arabia adhesives encompass polymeric compounds formulated to bond substrates through mechanical interlocking, chemical reaction, or physical curing processes, with viscosities ranging from low-flow liquids to high-solid pastes depending on application requirements. These materials serve structural assembly, surface protection, and component fixation across industrial and commercial operations. Water-based technology leads volume consumption due to SASO environmental compliance pressures, while reactive systems command premium positioning in automotive and electronics durability applications. Epoxy resin formulations sustain above-average growth in wind turbine blade manufacturing and oilfield equipment repair segments.
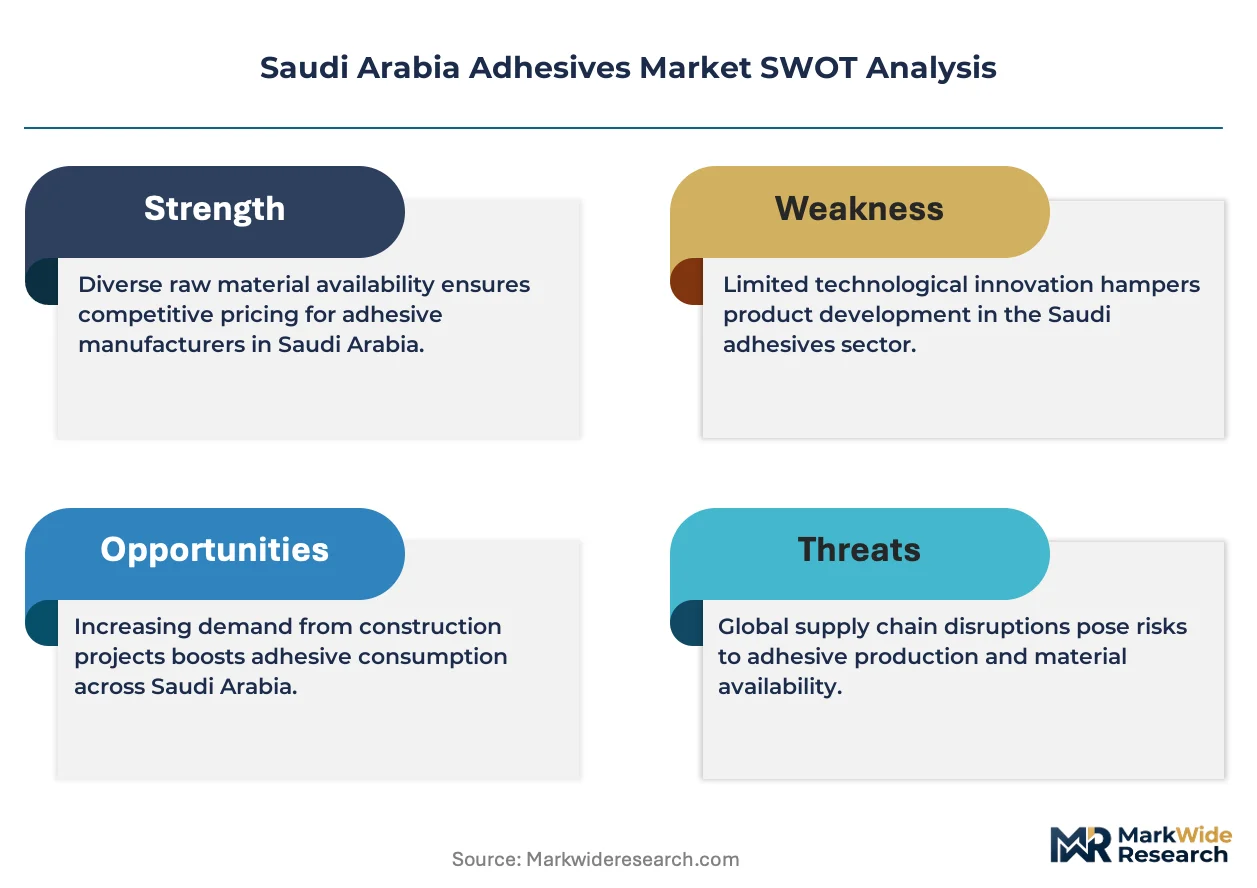
SASO technical regulations, the Saudi Building Code, and Gulf Standardization Organization (GSO) harmonized norms collectively govern product safety, VOC thresholds, and construction material performance certifications across the Kingdom. Compliance with these frameworks determines market access for imported formulations and shapes domestic formulation strategies. Stakeholders must monitor evolving green building mandates and circular economy requirements that will redefine raw material sourcing and end-of-life adhesive recovery protocols.
Market Dynamics
SASO VOC emission mandates are compressing formulation timelines as manufacturers accelerate water-based and reactive system transitions to maintain market access across Kingdom construction and industrial procurement channels.
Growth Catalysts
- NEOM Giga-Project Pipeline:Concrete bonding and waterproofing specifications across The Line and Oxagon developments are pulling specialized epoxy and polyurethane formulations into high-volume procurement cycles.
- SASO Technical Regulation 19-20-21-22:Mandatory VOC thresholds for construction adhesives are forcing domestic formulation shifts that favor compliant water-based technologies with established supply chains.
- Jubail Petrochemical Feedstock Access:Proximity to Saudi Aramco and SABIC monomer streams gives Eastern Province manufacturers captive acrylic and polyurethane precursor supply at cost-advantaged positions.
Market Restraints
- Crude-Derived Monomer Volatility:Propylene oxide and MDI pricing swings tied to Brent crude fluctuations compress margin predictability for polyurethane adhesive producers serving automotive and electronics segments.
- Import Dependency for Specialty Additives:Curing agents, rheology modifiers, and tackifiers concentrate in German and Japanese specialty chemical suppliers, exposing formulators to currency and shipping cost shocks.
- Hot-Melt Performance Ceiling:Temperature stability limitations above 80°C restrict EV battery module bonding applications where silicone and reactive systems maintain durability advantages.
Strategic Opportunities
- Tabuk Renewable Energy Manufacturing:Wind turbine blade fabrication facilities planned for the northwest province will demand high-shear epoxy formulations for composite laminate assembly.
- Saudi Green Building Code Tier 3 Certification:Premium LEED-equivalent ratings for Riyadh commercial towers specify low-emitting adhesive systems that command formulation price premiums over standard-grade alternatives.
- Digital Procurement Platforms:SABIC's unified supplier portal and emerging B2B marketplaces are compressing distributor layers, enabling direct manufacturer-to-contractor relationships for bulk construction adhesive orders.
Industry Challenges
- Formulation Chemist Scarcity:Water-based polymer stabilization and reactive system curing kinetics expertise concentrates among expatriate specialists, with limited Kingdom-based training pipelines.
- SASO Certification Timeline Compression:New product registration cycles extending 14-18 months delay market entry for imported specialty adhesives targeting oilfield equipment repair niches.
- Legacy Solvent-Based Inventory Stranded:Distributors holding pre-regulation VOC-noncompliant stock face write-down pressure as construction contractors pivot to certified formulations for giga-project compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Adhesives Market |
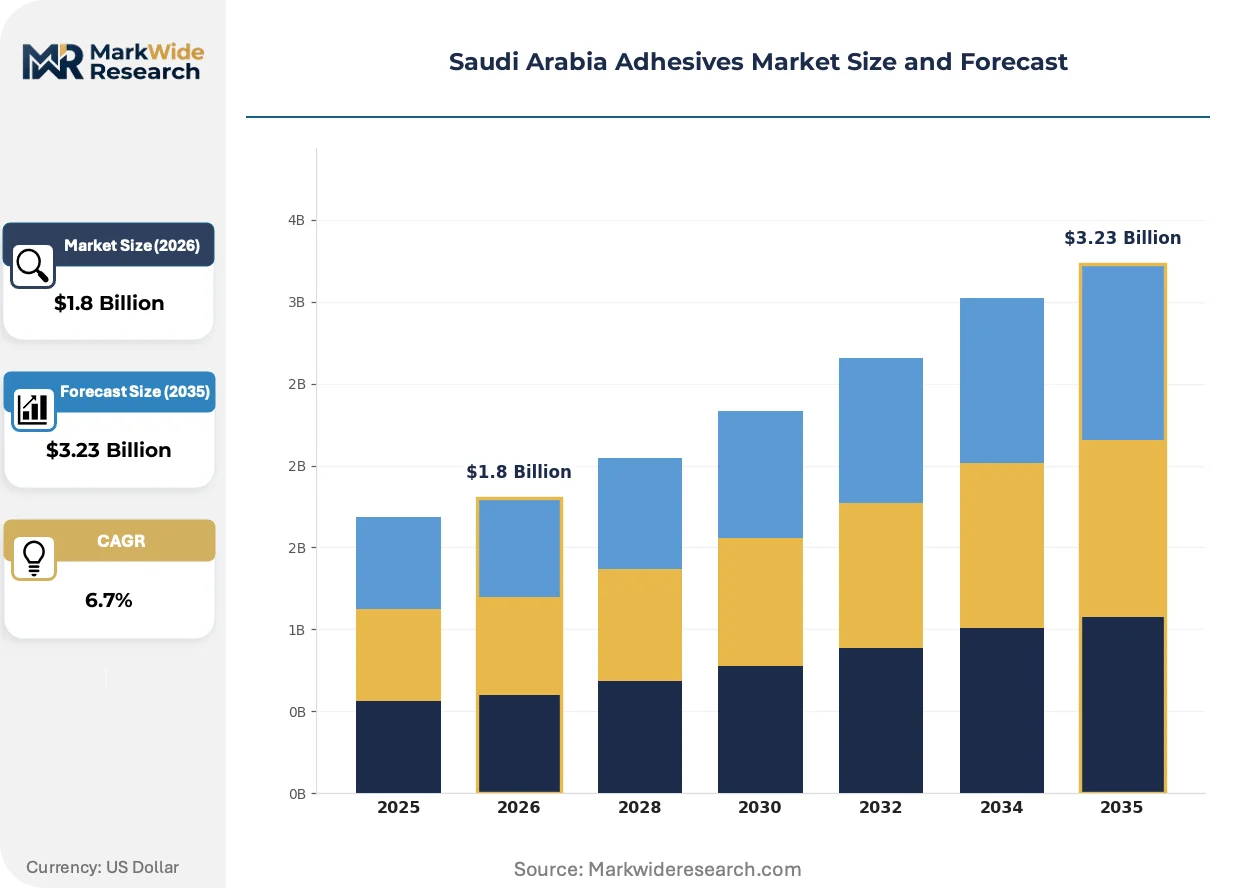
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Acrylic, Epoxy, Silicone Application: Construction, Automotive, Electronics, Packaging Technology: Solvent-based, Water-based, Hot Melt, Reactive End User: Manufacturers, Contractors, Retailers, Distributors |
| Companies Covered | Sun Chemicals Saudi Arabia Ltd, Saudi Arabian Adhesives Factory, 3M Saudi Arabia Company, Dow Saudi Arabia, Sika Saudi Arabia Limited, National Adhesives Ltd, Al Muqarram Group, H.B. Fuller Company, SABIC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Adhesives Market Evolving Landscape
Bio-based feedstock substitution and digital formulation tools are converging to compress development cycles and reshape competitive positioning across Saudi Arabia's adhesive value chain.
UV-curable acrylic oligomer systems are rewriting bonding economics in electronics assembly and medical device manufacturing by eliminating thermal curing steps and reducing energy consumption by half. Jeddah-based contract manufacturers serving Red Sea coast industrial zones are adopting these systems at pace for smartphone component fixation and disposable medical equipment production. The technology is compressing cycle times and enabling just-in-sequence delivery models that solvent-based alternatives cannot match.
SASO's 2024 update to Technical Regulation for Building Materials is tightening VOC thresholds for interior-grade adhesives used in schools and healthcare facilities. Formulators must now submit third-party emission testing under 28-day chamber protocols to maintain product registration validity. Water-based acrylic and hybrid polyurethane systems are capturing specification share in Riyadh commercial fit-out projects where Green Building Code compliance determines contractor eligibility.
Direct-to-contractor digital procurement is consolidating purchasing power among Saudi construction majors executing NEOM and Qiddiya packages. Sika and H.B. Fuller have established dedicated e-commerce portals bypassing traditional distributor markups for orders exceeding 20-tonne monthly volumes. This channel compression is most visible in Dammam and Jubail industrial corridors where procurement teams negotiate formula-locked annual contracts with price adjustment clauses tied to propylene index movements.
Saudi Arabia Adhesives Market Segmentation
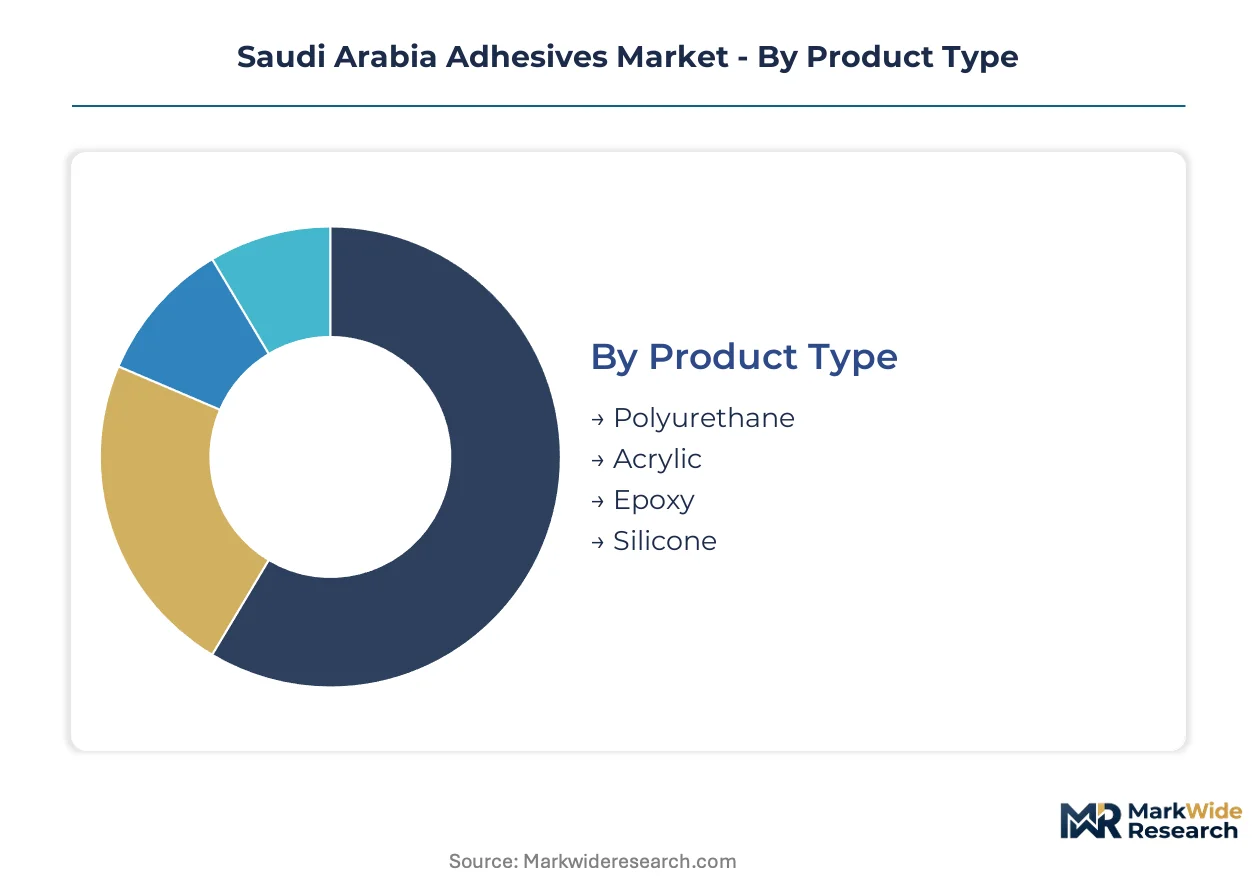
Adhesive formulation choices in Saudi Arabia trace directly to feedstock proximity, regulatory compliance timelines, and giga-project specification requirements. Segment boundaries shift as SASO VOC mandates and NEOM procurement standards redefine technical minimums across construction and industrial channels.
Product Type:
Polymer chemistry concentration in the Eastern Province petrochemical corridor determines regional supply economics and formulation accessibility for domestic manufacturers.
- Polyurethane:Two-component systems combining isocyanate and polyol resins deliver superior flexibility and chemical resistance. Demand concentrates in Dammam automotive assembly plants and Jubail oilfield equipment repair facilities where MDI precursor access from SABIC integration secures cost advantages for local formulators.
- Acrylic:Emulsion and solvent-borne variants dominate water-based formulation portfolios. Riyadh commercial tower fit-out contractors specify low-VOC acrylics for Green Building Code Tier 3 compliance, pulling volume toward certified domestic production lines.
- Epoxy:High-shear thermosetting systems serve wind turbine blade lamination and concrete structural bonding across NEOM and Red Sea coast developments.
- Silicone:RTV and heat-cure formulations maintain temperature stability above 150°C for EV battery module sealing and high-voltage electronics applications.
Today's leader: Acrylic. Tomorrow's challenger: Epoxy.
Application:
Project scale and specification intensity separate volume tiers, with giga-developments commanding dedicated supply agreements and technical service embedding.
- Construction:Concrete bonding, waterproofing membranes, and tile fixing systems absorb the majority of Kingdom adhesive procurement. NEOM, Qiddiya, and Red Sea Project packages specify Sika and BASF systems for desert climate durability, locking in multi-year supply commitments with technical support clauses.
- Automotive:Structural bonding and NVH reduction applications in Dammam assembly plants favor polyurethane and epoxy systems. SASO automotive material certifications and OEM tier-1 supplier status requirements filter out non-compliant imports.
- Electronics:Smartphone component fixation and PCB protection in Jeddah contract manufacturing zones drive UV-curable acrylic adoption for cycle time compression.
- Packaging:Hot-melt systems for corrugated box sealing and label application serve Riyadh and Jeddah FMCG distribution centers with volume-driven pricing.
Construction commands current procurement gravity. Electronics climbs fastest on UV-curable technology displacement.
Technology:
Regulatory phase-out timelines and energy consumption profiles reshape technology mix as formulators rebalance compliance costs against performance specifications.
- Solvent-based:Legacy formulations face stranded inventory risk as SASO Technical Regulation 19-20-21-22 VOC thresholds tighten for interior-grade applications. Remaining demand concentrates in oilfield equipment repair and exterior construction where rapid cure speed offsets compliance penalties.
- Water-based:Acrylic and polyurethane dispersions capture specification share across Riyadh commercial fit-out and school construction where 28-day chamber emission testing determines contractor eligibility. Eastern Province manufacturers leverage captive acrylic acid supply from Jubail petrochemical integration.
- Hot Melt:EVA and polyolefin formulations dominate packaging and woodworking applications with instant bonding and zero VOC profiles. Temperature ceiling limitations restrict penetration into under-hood automotive and battery module assembly.
- Reactive:Epoxy and polyurethane systems command premium positioning in wind turbine blade fabrication and structural concrete repair. Extended cure times require job-site technical support embedding that favors established supplier relationships.
Water-based holds installed base dominance. Reactive systems gain on durability-critical specifications.
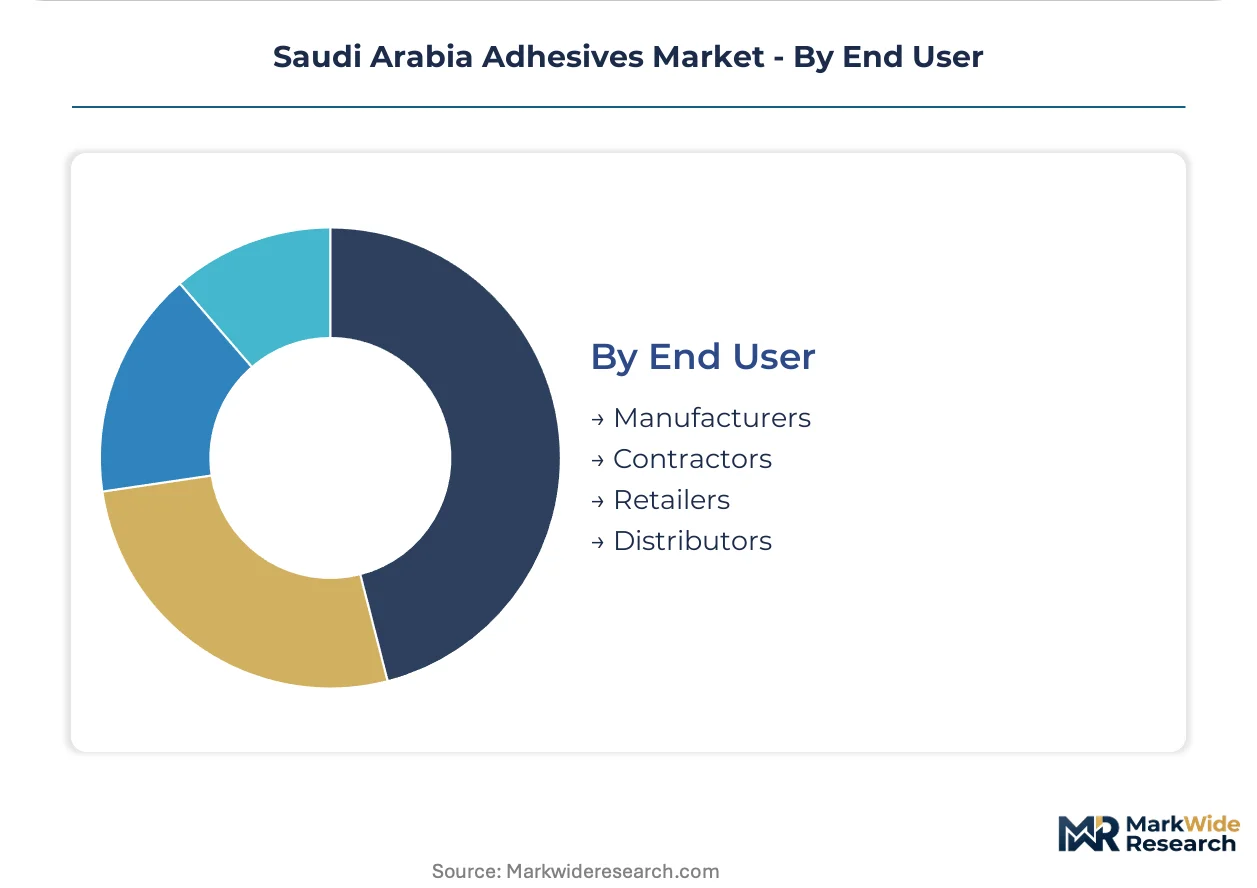
End User:
Procurement sophistication and volume scale determine channel structure, with digital platform adoption compressing traditional distributor layers among high-volume accounts.
- Manufacturers:SABIC, Saudi Aramco, and Ma'aden operations in Jubail and Yanbu purchase industrial maintenance adhesives through direct supplier relationships with annual formula-locked contracts. Technical service integration and emergency response SLAs outweigh price sensitivity in supplier selection.
- Contractors:NEOM and Qiddiya construction majors negotiate bulk adhesive procurement through SABIC's unified supplier portal and dedicated e-commerce channels. Sika and H.B. Fuller bypass distributor markups for orders exceeding 20-tonne monthly volumes.
- Retailers:Hardware and building material stores in Riyadh, Jeddah, and Dammam serve DIY and small contractor demand with standardized SKU portfolios. Inventory turns concentrate on water-based construction adhesives and general-purpose epoxies.
- Distributors:Traditional stocking distributors face margin compression as digital procurement platforms enable direct manufacturer engagement. Remaining value concentrates on technical consultation, just-in-time delivery, and credit extension for mid-tier contractors.
Contractors drive volume concentration. Manufacturers set technical specifications that cascade downstream.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Eastern Province petrochemical integration anchors Saudi Arabia's adhesive production capacity, with Jubail and Dammam manufacturing clusters supplying feedstock-advantaged formulations to Kingdom-wide construction and industrial channels.
Eastern Province
Jubail's SABIC petrochemical complexes and Saudi Aramco monomer streams provide captive propylene oxide and acrylic acid supply for polyurethane and water-based adhesive production. SASO technical regulations on VOC emissions shape formulation standards for products distributed nationally from this corridor. Dammam automotive assembly plants and oilfield equipment repair facilities pull specialized reactive systems from local formulators with technical service embedding.
Riyadh
Commercial tower fit-out and school construction specifications under the Saudi Green Building Code Tier 3 certification drive low-emitting water-based acrylic procurement. The capital's procurement teams negotiate bulk adhesive contracts through SABIC's unified supplier portal, compressing traditional distributor layers. NEOM and Qiddiya project offices in Riyadh coordinate giga-development adhesive specifications that cascade to Eastern Province manufacturers.
Western Region
Jeddah contract manufacturing zones serving Red Sea coast industrial development adopt UV-curable acrylic systems for electronics assembly cycle time compression. The region's medical device and smartphone component producers specify these technologies for just-in-sequence delivery models. SASO's 2024 Technical Regulation update for interior-grade adhesives tightens eligibility for school and healthcare facility applications across Mecca and Medina construction markets.
NEOM Northwest
Tabuk renewable energy manufacturing facilities planned for wind turbine blade fabrication will demand high-shear epoxy formulations for composite laminate assembly. The Line and Oxagon developments specify specialized concrete bonding and waterproofing systems that pull volume into dedicated supply agreements. Digital procurement platforms enable direct manufacturer-to-contractor relationships bypassing distributor markups for bulk construction adhesive orders exceeding 20-tonne monthly volumes.
Saudi Arabia Adhesives Market Competitive Landscape
Capacity expansion dominates the current landscape as Eastern Province manufacturers leverage Jubail petrochemical feedstock access to scale water-based and reactive system output. The market structure concentrates around integrated petrochemical players, specialized construction chemical suppliers, and international adhesive formulators with local blending operations. Three archetypes define positioning: upstream-integrated producers with captive monomer supply, specification-driven specialists embedding technical service, and volume-focused packagers serving FMCG distribution channels. M&A activity and direct-to-contractor digital platform investments represent the dominant competitive vectors reshaping channel economics.
Among international formulators with Saudi operations, Dow Saudi Arabia, Sika Saudi Arabia Limited, and H.B. Fuller Company occupy positions reflecting distinct strategic archetypes. Dow represents upstream-integrated production leveraging regional petrochemical assets. Sika exemplifies specification-driven technical service embedding for giga-project construction channels. H.B. Fuller sits within volume-focused packaging and consumer goods supply tiers. Domestic players including Saudi Arabian Adhesives Factory and National Adhesives Ltd compete on regional distribution density and SASO compliance agility.
| Leading Market Players |
|---|
| Sun Chemicals Saudi Arabia Ltd |
| Saudi Arabian Adhesives Factory |
| 3M Saudi Arabia Company |
| Dow Saudi Arabia |
| Sika Saudi Arabia Limited |
| National Adhesives Ltd |
| Al Muqarram Group |
| H.B. Fuller Company |
| SABIC |
| Others |
Value Network & Pricing Analysis
Propylene oxide feedstock costs from Jubail petrochemical integration cascade through three distinct pricing tiers for Saudi adhesive formulators, compressing margins at the standard-grade level while protecting premium reactive system profitability through technical service bundling.
Pricing Analysis
Distributor margin compression of 8-12 percentage points separates direct-to-contractor digital channels from traditional stocking intermediaries serving mid-tier construction accounts. Three-tier pricing structure across premium, standard, and economy levels stratifies by SASO certification grade and volume commitment, with Green Building Code Tier 3 compliant formulations commanding formulation premiums over baseline water-based alternatives. Pricing pressure stems from SABIC's unified supplier portal enabling transparent propylene index-linked contract negotiations that expose legacy distributor markups. Small contractors and DIY retailers exhibit highest price sensitivity, while NEOM package contractors prioritize technical service embedding over per-kilogram differentials.
Supply Chain Analysis
Specialty additive supply rests on German and Japanese curing agent producers, exposing Saudi formulators to currency volatility and shipping cost shocks independent of captive petrochemical feedstock advantages. Raw material dependencies center on MDI precursors from SABIC integration, acrylic acid from Jubail crackers, and imported rheology modifiers from European specialty houses. Single-source vulnerability concentrates in high-performance curing agents for epoxy wind turbine applications. Distribution runs through Eastern Province manufacturing clusters to Riyadh commercial construction and Jeddah electronics assembly zones, with digital platforms compressing traditional distributor layers for bulk accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's adhesives market represents a late-cycle quality story as NEOM giga-projects and SASO VOC mandates shift procurement gravity toward certified low-emitting formulations with embedded technical service.
For Market Incumbents: Hedge against stranded solvent-based inventory by accelerating water-based capacity conversion at Eastern Province plants before SASO Technical Regulation 19-20-21-22 enforcement tightens. Secure backward integration into acrylic acid supply through SABIC offtake agreements to defend margin position against propylene oxide volatility. Prioritize certification investment for Green Building Code Tier 3 eligibility as contractor procurement teams filter supplier pools. For New Entrants and Emerging Players: The price-point gap between Sika-grade premium construction systems and economy-grade tile adhesives offers white-space entry for mid-tier formulators with SASO compliance agility. Target Tabuk wind turbine blade fabrication facilities with high-shear epoxy technical partnerships as renewable energy manufacturing scales. Penetrate through digital procurement platform onboarding, bypassing distributor margin capture that incumbents cannot easily abandon. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented domestic formulators lack captive feedstock access and struggle to fund SASO certification timelines stretching 14-18 months. Five-to-ten year viability favors upstream-integrated players with Jubail petrochemical proximity over pure formulation houses dependent on imported monomers. Watch for SABIC portal adoption rates among NEOM contractors as inflection signal for channel compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Jubail petrochemical proximity secures captive monomer supply against propylene volatility. |
| SASO Certification Acceleration | Compressed 14-month registration timelines determine market access for specialty formulations. |
| Digital Procurement Platform Onboarding | SABIC portal adoption enables direct contractor relationships bypassing distributor markups. |
| Green Building Code Tier 3 Investment | Premium certification eligibility filters contractor supplier pools in Riyadh commercial fit-out. |
| Technical Service Embedding for Giga-Projects | NEOM and Qiddiya packages lock multi-year supply through formula-locked annual contracts. |
Research Methodology
Multiple input streams — primary interviews with plant managers and procurement leads at downstream OEMs, technical R&D directors at formulators, and distribution channel partners — were reconciled against secondary validation from customs trade data, SASO regulatory filings, and SABIC supplier portal disclosures. Bottom-up volume modeling across polymer chemistry segments was triangulated with top-down petrochemical feedstock flow analysis.
Data-stream reconciliation applied analytical frameworks across the projection horizon, modeling segmentation dimensions including technology type, application vertical, and regional procurement cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating NEOM project pipeline visibility and SASO compliance phase-out schedules. Forecast inputs included propylene index trajectory assumptions and giga-project execution cadence.
Caveats apply where crude-derived monomer volatility or SASO regulatory timeline extensions could materially shift the outlook. Forecasts reflect documented assumptions about petrochemical integration continuity and construction sector procurement patterns. A small set of named triggers — Brent crude swings, SASO Technical Regulation enforcement acceleration, NEOM package award delays — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Europe Acrylic Adhesives Market
Adhesives & Sealants
North America Acrylic Adhesives Market
Adhesives & Sealants
Global Dental Adhesives and Sealants Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
North America Construction Adhesives Market
Adhesives & Sealants
Wood to Metal Glue Market
Adhesives & Sealants
Floor Adhesive Market
Adhesives & Sealants
Global Adhesion Barrier Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market
Adhesives & Sealants
High Strength Laminated Adhesives Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
Fabric Glue Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
Middle-East and Africa Cyanoacrylate Adhesives Market