
 Two-Wheeler Market | 2026-2036
Two-Wheeler Market Size, Share, and Industry Trends Forecast 2026-2036
Two-Wheeler Market Intelligence
Market Context
Skilled battery-cell technicians are unwinding production bottlenecks for electric two-wheeler OEMs across Asia. Hero MotoCorp leverages its dealership density to sustain rural market penetration in India. Honda Motor anchors premium internal-combustion segments through manufacturing scale in Thailand and Vietnam. TVS Motor competes in connected-vehicle features across its Apache and iQube lineups.
Technical Definition and Segments
Two-wheelers encompass motorized vehicles with two inline wheels, spanning engine capacities from sub-50cc mopeds to above-400cc performance motorcycles, typically utilizing tubular steel frames and single-cylinder or parallel-twin powertrains for personal mobility and commercial dispatch. Scooters dominate urban volume across Asian megacities due to step-through ergonomics and under-seat storage utility. Motorcycles above 200cc command disproportionate margin pools in Latin America and Africa where long-distance durability matters. E-bikes represent the fastest-expanding fuel-type category as lithium-ion pack costs decline and charging infrastructure proliferates.
Regulatory Frame
India's CEA mandates AIS-156 battery safety certification for electric two-wheelers, while the EU's F-Gas Regulation and Euro 5 emission standards constrain internal-combustion engine architectures. China's MIIT enforces GB/T national standards that dictate motor efficiency thresholds and vehicle-connectivity protocols for NEV two-wheelers. Stakeholders must monitor how Indonesia's upcoming battery-swapping mandates and the EU AI Act's vehicle-autonomy provisions reshape platform economics and compliance investment.
Market Dynamics
Electrification mandates and battery-swapping infrastructure investments are compressing total cost of ownership differentials between internal-combustion and electric powertrains across Asian urban corridors. This structural shift is redirecting procurement flows from traditional dealerships toward fleet-direct channels and energy-service platforms.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for automotive manufacturing are accelerating domestic electric two-wheeler assembly capacity and attracting component localization investments from cell suppliers.
- Ride-hailing fleet electrification:Platform operators across Indonesia's Jakarta-Bandung corridor are converting motorcycle assets to electric models to reduce fuel expenditure volatility and meet emissions commitments.
- Lithium-ion cost curves:Pack-level price declines are enabling OEMs to offer electric scooters at internal-combustion parity in Southeast Asian mass-market segments.
Market Restraints
- Cobalt and nickel price volatility:Raw material input swings for cathode chemistry are compressing gross margins for electric two-wheeler manufacturers without long-term offtake agreements.
- Charging infrastructure gaps:Grid reliability constraints and public charging deserts outside Tier-1 Indian cities are limiting electric adoption in rural penetration zones where Hero MotoCorp dominates.
- Euro 5 compliance costs:Emission standard stringency is forcing internal-combustion engine redesigns that add unit costs in price-sensitive European commuter segments.
Strategic Opportunities
- Battery-as-a-service models:Swappable pack subscriptions are decoupling vehicle purchase from energy storage capital, opening electric access to Indonesia's gig-economy delivery workforce.
- Connected-vehicle data monetization:Telematics integration in TVS Motor's Apache and iQube lineups creates aftermarket revenue streams through predictive maintenance and usage-based insurance partnerships.
- Vietnam's manufacturing hub expansion:Honda Motor's Thai and Vietnamese production scale positions suppliers to capture ASEAN export demand as regional trade barriers harmonize.
Industry Challenges
- AIS-156 certification timelines:India's CEA battery safety testing protocols are creating six-to-nine-month product launch delays for electric two-wheeler startups lacking established homologation relationships.
- Cell technician scarcity:Skilled battery assembly and thermal management engineering talent pools are concentrated among a handful of Asian contract manufacturers, constraining OEM vertical integration ambitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two-Wheeler Market |
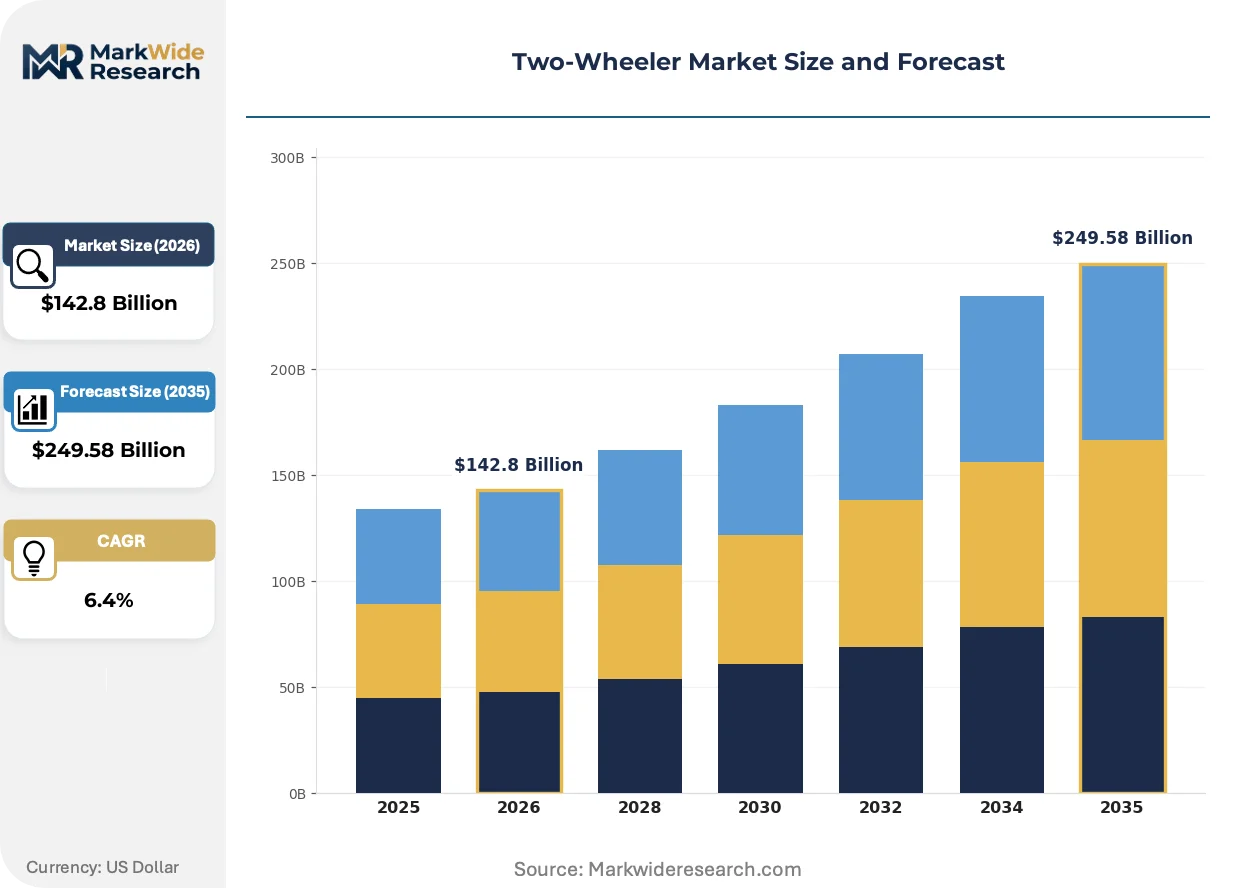
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $249.58 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scooters, Motorcycles, E-bikes, Mopeds Engine Capacity: Below 100cc, 100cc to 200cc, 200cc to 400cc, Above 400cc Fuel Type: Petrol, Diesel, Electric, Hybrid Sales Channel: Direct Sales, Dealerships, Online Retail, Second-hand Market |
| Companies Covered | Bajaj Auto, TVS Motor, Honda Motor, NIU Technologies, Haojue, Yadea, Hero MotoCorp, Lifan Motor, Yamaha Motor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two-Wheeler Market Strategic Shifts & Innovations
Power electronics integration and solid-state battery prototyping are compressing form-factor constraints while regulatory pressure on thermal runaway risks accelerates safety architecture redesigns. These forces are converging to redefine platform economics and supplier value capture.
Solid-state electrolyte research is miniaturizing battery pack footprints while maintaining energy density thresholds. Scooter OEMs targeting Southeast Asian urban density are adopting these prototypes for under-seat storage optimization. The technology is miniaturizing vehicle architecture constraints that previously dictated frame design compromises between range and utility.
China's MIIT GB/T standards are enforcing motor efficiency thresholds and mandatory vehicle-connectivity protocols for new energy two-wheelers. Domestic manufacturers must integrate prescribed telematics modules to qualify for NEV subsidies and license plate privileges. The regulation is compressing product development cycles as OEMs race to certify platforms before incentive tier reductions.
Urban last-mile delivery fleets are consolidating procurement authority away from individual rider ownership toward platform-managed asset pools. Fleet operators in Indonesia and Vietnam are negotiating direct manufacturer relationships that bypass traditional dealer networks and service bundling. This concentration is visible in Jakarta-Bandung corridor electrification programs where ride-hailing platforms specify charging infrastructure co-investment terms.
Two-Wheeler Market Segmentation
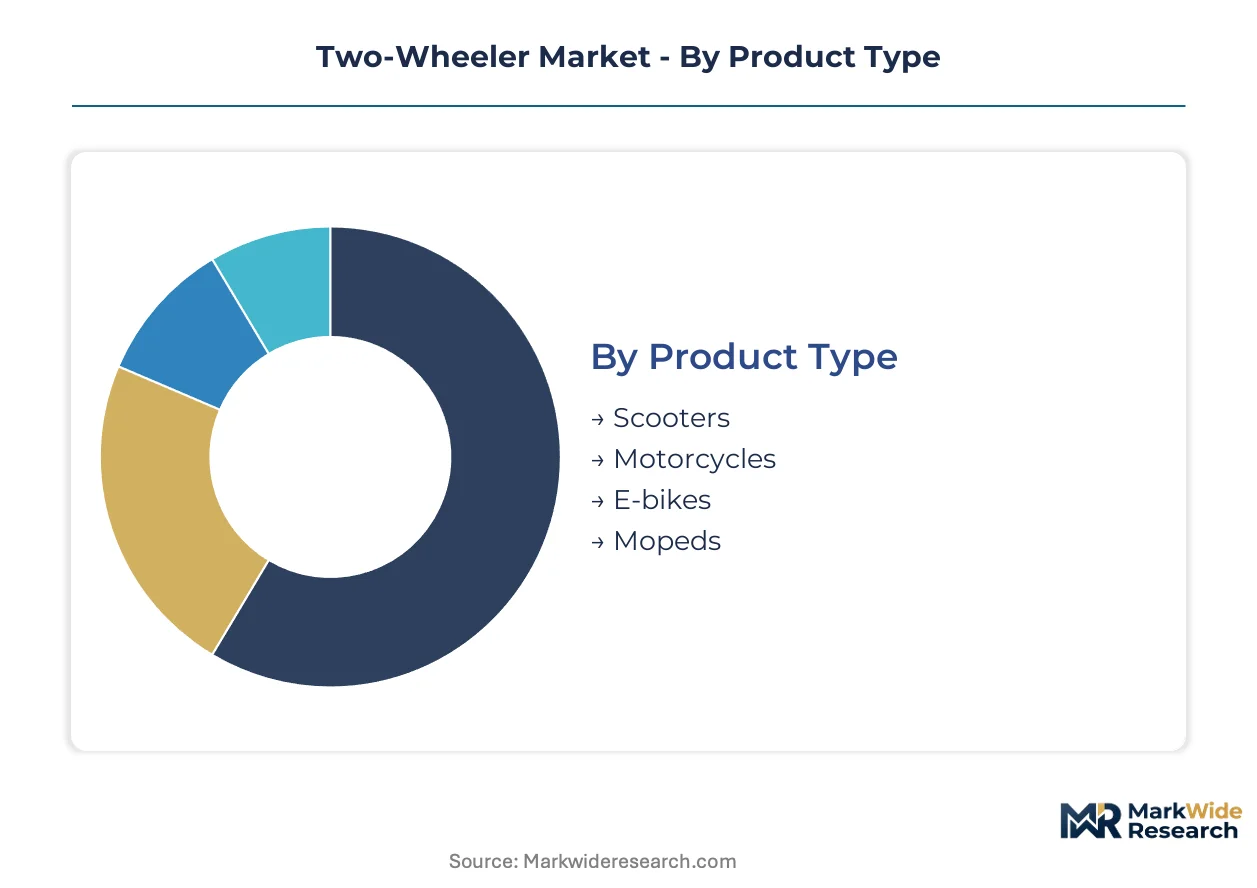
Two-wheeler segmentation reveals how regulatory pressure and infrastructure maturity split demand across powertrain technologies and distribution channels. OEMs configure product portfolios around emission compliance costs, battery-swap network density, and fleet procurement consolidation.
Product Type:
CEA's AIS-156 certification in India and MIIT's GB/T connectivity mandates in China create divergent compliance burdens across vehicle architectures.
- Scooters:Step-through frames with under-seat battery accommodation dominate Jakarta-Bandung corridor electrification programs. Ride-hailing platforms in Indonesia specify swappable-pack scooters to minimize downtime and eliminate home-charging dependencies for gig-economy drivers.
- Motorcycles:Tubular steel frames with single-cylinder or parallel-twin powertrains command margin pools in Latin America and Africa where long-distance durability outweighs urban convenience. Honda Motor's Thai and Vietnamese manufacturing scale anchors premium internal-combustion supply for these durability-sensitive markets.
- E-bikes:Pedal-assist electric bicycles with sub-750W motors face lighter homologation requirements than full-power scooters in EU markets governed by F-Gas Regulation and Euro 5 standards.
- Mopeds:Sub-50cc restricted-speed vehicles retain residual demand in European urban cores with congestion-charge exemptions.
Scooters handle the majority of throughput; E-bikes are the fastest mover on share.
Engine Capacity:
Cost tier stratification aligns with customer use-case intensity and replacement cycle length.
- Below 100cc:Entry commuter motorcycles and scooters priced at internal-combustion parity in Southeast Asian mass-market segments. Hero MotoCorp's dealership density sustains rural India penetration where charging infrastructure gaps limit electric alternatives.
- 100cc to 200cc:The largest volume tier for family transportation and light commercial dispatch across India's tier-2 and tier-3 cities. TVS Motor competes here with connected-vehicle features in Apache lineups.
- 200cc to 400cc:Performance-oriented motorcycles with liquid cooling and fuel injection command pricing premiums in Brazil and South Africa.
- Above 400cc:Premium adventure-touring and sportbike segments with Euro 5 compliance costs absorbed through manufacturer margin pools rather than price-sensitive positioning.
100cc to 200cc segments carry the volume base; above 400cc segments expand most quickly on margin contribution.
Fuel Type:
Application-driven procurement patterns concentrate fleet electrification in urban corridors while rural and long-haul segments retain liquid fuel dependence.
- Electric:Lithium-ion pack cost declines enable OEMs to offer price-competitive urban mobility solutions. Battery-as-a-service models decouple vehicle purchase from energy storage capital in Indonesia's delivery workforce.
- Petrol:Port-fuel-injected and direct-injection architectures face Euro 5 redesign costs in European commuter segments. Internal-combustion retains dominance where grid reliability constraints limit charging access.
- Diesel:Compression-ignition two-wheelers maintain niche presence in Indian commercial three-wheeler derivatives and agricultural utility applications.
- Hybrid:Series-hybrid architectures with range-extender engines remain experimental outside Japanese domestic market trials under METI efficiency programs.
Petrol retains the installed base; Electric is climbing the fastest on new registration share.
Sales Channel:
Customer type evolution redirects procurement authority from individual ownership toward platform-managed asset pools.
- Dealerships:Physical retail networks with service bundling sustain Hero MotoCorp's rural India dominance where digital penetration lags urban centers. Franchise locations handle warranty claims and periodic maintenance for internal-combustion powertrains.
- Direct Sales:Fleet-direct manufacturer relationships bypass dealer markups for Indonesian ride-hailing platforms specifying charging infrastructure co-investment terms. Gojek and Grab negotiate volume commitments against asset lifecycle management guarantees.
- Online Retail:Digital configurators with home-delivery logistics penetrate tier-1 Indian cities for electric scooter brands with standardized battery configurations.
- Second-hand Market:Informal resale channels dominate African and South Asian markets where formal financing penetration remains limited.
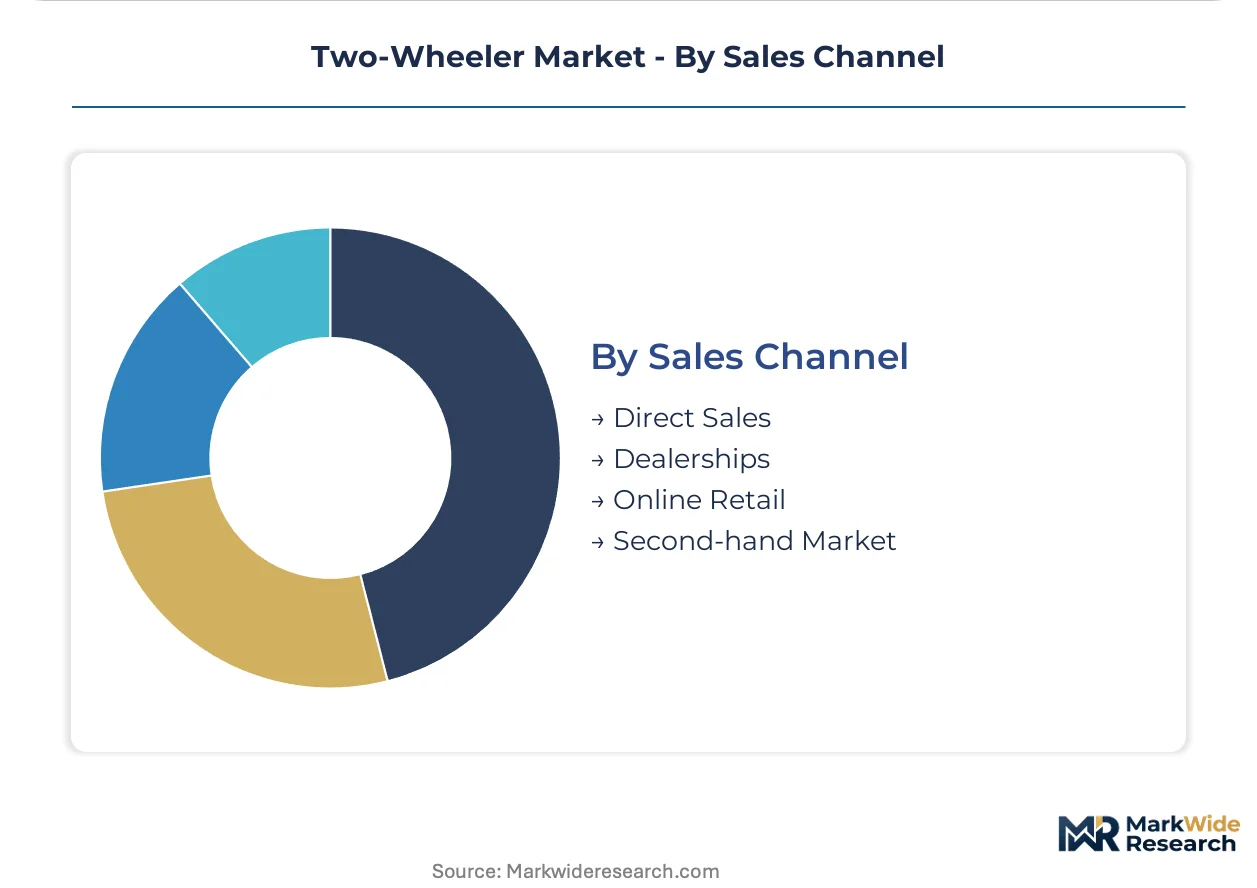
Dealerships process the majority of transaction volume; Direct Sales is gaining share fastest through fleet consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: Asian markets favor compact scooters for dense urban corridors, while Latin American and African buyers prioritize motorcycle durability for extended rural routes. Electrification timelines compress fastest where battery-swapping infrastructure and ride-hailing fleet consolidation converge.
India
Rural penetration of internal-combustion motorcycles sustains dealership networks across tier-2 and tier-3 cities, while the CEA's AIS-156 battery safety certification compresses electric two-wheeler launch timelines. The PLI scheme for automotive manufacturing accelerates domestic assembly capacity and cell supplier localization. Maharashtra and Gujarat industrial corridors concentrate OEM assembly plants and component vendor ecosystems.
China
MIIT's GB/T national standards enforce mandatory vehicle-connectivity protocols and motor efficiency thresholds for new energy two-wheelers. Domestic manufacturers integrate prescribed telematics modules to qualify for NEV subsidies and license plate privileges. The Yangtze River Delta and Pearl River Delta clusters dominate lithium-ion pack production and electric scooter assembly for domestic and export markets.
Indonesia
Ride-hailing platforms across the Jakarta-Bandung corridor electrify motorcycle fleets to reduce fuel expenditure volatility and meet emissions commitments. Upcoming battery-swapping mandates from the national energy regulator reshape platform economics and charging infrastructure investment terms. The Greater Jakarta metropolitan area concentrates fleet procurement authority and swap station deployment.
Vietnam
Manufacturing scale for premium internal-combustion engines anchors regional export supply as ASEAN trade barriers harmonize. Honda Motor's production facilities in Thai and Vietnamese industrial zones position component suppliers for cross-border demand. The Red River Delta and Southeast region cluster assembly plants serving domestic consumption and re-export channels.
Brazil
Performance motorcycles above 200cc command disproportionate margin pools where long-distance durability outweighs urban convenience factors. ANVISA and environmental agency regulations shape emission compliance architectures for internal-combustion powertrains. São Paulo state concentrates distribution infrastructure and premium segment dealership networks.
Two-Wheeler Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrated among Asian conglomerates with captive component supply and established homologation relationships. The market structure rewards manufacturing depth and distribution density over pure technology differentiation. Three archetypes dominate: diversified automotive conglomerates with two-wheeler divisions, pure-play electric specialists with battery-as-a-service platforms, and regional champions with rural dealership lock-in. Competitive moves center on backward integration into cell supply and fleet-direct procurement relationships that bypass traditional retail networks.
Among diversified automotive conglomerates, Honda Motor and Yamaha Motor occupy positions anchored by internal-combustion manufacturing scale and ASEAN production networks. TVS Motor exemplifies the connected-vehicle specialist tier, with telematics integration creating aftermarket revenue streams through predictive maintenance partnerships. These named entities represent strategic archetypes rather than exhaustive market coverage, with actual competitive dynamics extending across additional domestic champions and emerging electric pure-plays.
| Leading Market Players |
|---|
| Bajaj Auto |
| TVS Motor |
| Honda Motor |
| NIU Technologies |
| Haojue |
| Yadea |
| Hero MotoCorp |
| Lifan Motor |
| Yamaha Motor |
| Others |
Cost & Logistics Intelligence
India's CEA AIS-156 battery safety certification gates supplier qualification and price differentiation simultaneously, forcing electric two-wheeler OEMs to absorb homologation costs that separate certified premium tiers from uncertified economy offerings while compressing margins for startups lacking established testing relationships.
Pricing Analysis
Long-term offtake contracts for lithium-ion cells anchor pricing stability for established electric two-wheeler manufacturers, while spot-market cobalt and nickel exposure punishes entrants without supply agreements. Price differentiation hinges on AIS-156 certification tier and geographic delivery density to swap station networks. Cost compression in mass-market electric scooters intensifies as pack-level parity with internal-combustion alternatives eliminates brand premiums. Fleet operators in Indonesia's Jakarta-Bandung corridor exhibit lowest price sensitivity due to platform-managed asset depreciation models, while individual rural buyers in India remain most price-constrained.
Supply Chain Analysis
Strategic stockpiling of nickel and cobalt precursors dominates inventory strategy among electric two-wheeler cell suppliers, contrasting with just-in-time frame and powertrain component flows from ASEAN manufacturing hubs. Supply concentration centers on China's Yangtze River Delta for cathode active materials, South Korea for cell assembly, and Thailand for internal-combustion powertrain casting. Raw material dependencies span Indonesian nickel laterite, Chilean lithium carbonate, and Chinese processed cathode powders. Single-source vulnerability in solid-state electrolyte prototyping creates chokepoint risk for next-generation pack architectures. Distribution runs through Honda Motor and Yamaha Motor's captive ASEAN logistics networks for premium segments, while direct manufacturer relationships bypass dealer markups for Indonesian fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored by regulatory entrenchment: India's PLI scheme and Indonesia's battery-swapping mandates create compliance barriers that compound incumbent advantages through certification timelines and infrastructure co-investment requirements.
For Market Incumbents: Compound dealership density into rural India as a defensive barrier against electric pure-plays constrained by charging infrastructure gaps. Deepen backward integration into cell supply through long-term offtake agreements with Korean and Chinese cathode suppliers to neutralize cobalt price volatility. Prioritize AIS-156 certification pipeline investments to maintain launch velocity against startup competitors facing six-to-nine-month homologation delays. For New Entrants and Emerging Players: Battery-as-a-service subscription gaps in Indonesia's gig-economy delivery workforce offer immediate white-space penetration where incumbents under-serve asset-light driver economics. Target Vietnam's manufacturing hub expansion for regional export positioning as ASEAN trade harmonization accelerates. Pursue fleet-direct procurement relationships with Gojek and Grab specifying charging infrastructure co-investment terms rather than competing through traditional dealer networks. For Investors and Strategic Acquirers: Indonesia's upcoming battery-swapping mandates reshape the acquisition landscape toward platform-enabled energy-service companies with captive swap station networks. Frame long-term viability around five-to-ten year regulatory compliance moats rather than pure technology differentiation. Prioritize targets with established CEA or MIIT homologation relationships and captive component localization. Monitor AIS-156 certification backlog durations as the critical inflection signal for electric two-wheeler startup mortality rates.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-as-a-Service Platform Launch | Decouples vehicle purchase from energy storage capital for Indonesia's delivery workforce. |
| AIS-156 Certification Fast-Track Investment | Compresses product launch timelines against competitors facing CEA testing delays. |
| Swap Station Infrastructure Partnership | Locks in fleet procurement terms with Jakarta-Bandung ride-hailing platforms. |
| Connected-Vehicle Telematics Integration | Creates predictive maintenance revenue streams through TVS Motor-style data partnerships. |
| ASEAN Manufacturing Footprint Expansion | Captures regional export demand as Honda Motor's Thai-Vietnamese scale anchors supply. |
Research Approach
The analysis maps electric powertrain architectures, internal-combustion engine tiers, battery-swapping network economics, and fleet procurement channels, each validated through OEM platform engineers, battery cell procurement leads, ride-hailing fleet operations managers, and dealership network heads. Primary interview findings triangulate against secondary sources including MIIT GB/T standard filings, CEA AIS-156 certification registries, ASEAN customs trade databases, and IHS Markit vehicle registration data. Bottom-up unit economics modeling reconciles with top-down market sizing across production capacity announcements.
Consistency checks validate volume and value outputs against external benchmarks including OEM reported shipment data and energy regulator swap station deployment filings. The analytical framework segments by propulsion architecture, vehicle class, engine displacement tier, sales channel structure, and regional regulatory cluster across the projection horizon. CAGRs derive from installed base turnover rates, electrification policy intensity indices, and lithium-ion cost curve trajectories. Forecast inputs incorporate PLI scheme capacity buildout schedules and Jakarta-Bandung corridor fleet conversion commitments.
Underlying assumptions cover sustained cobalt price volatility, AIS-156 certification processing timelines, and Indonesian battery-swapping mandate implementation sequencing, with deviation risk concentrated in raw material supply disruptions and grid reliability constraints outside Tier-1 Indian cities. Revision becomes warranted when CEA certification backlogs exceed twelve months or Indonesian swap station deployment falls below platform operator procurement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycles Fuel Tank Market
Bikes and Motorcycles
Sweden Electric Bike Market
Bikes and Motorcycles
Motorcycle Boot Market
Bikes and Motorcycles
Global Motorcycle Market
Bikes and Motorcycles
Three Wheeled Motorcycle Market
Bikes and Motorcycles
Fuel Cell Bikes Market
Bikes and Motorcycles
Electric Motorsport Market
Bikes and Motorcycles
Motorcycle Chain Market
Bikes and Motorcycles
LAMEA Motorcycle ADAS Market
Bikes and Motorcycles
Motorcycle Tubeless Tire Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market
Bikes and Motorcycles
Netherlands E-Bike Market
Bikes and Motorcycles
Motorcycle Lighting Market
Bikes and Motorcycles
Motorsports Motorcycle Market
Bikes and Motorcycles
Motorcycle Drive Chain Market