

Bicycle Gear Shifter Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Gear Shifter Market Insights
ISO 4210 bicycle safety certification is collapsing the supplier base for entry-level shifter manufacturers, favoring incumbents with in-house testing laboratories. Shimano leverages its captive forging and plating facilities in Japan and Malaysia to control cost structures across mechanical and electronic lines. SRAM anchors its position through vertical control over carbon brake lever and shifter blade manufacturing in its United States facilities. Campagnolo differentiates via sustained Italian production of road-specific Ergopower integrated units with tight tolerances for pro-team specifications.
A bicycle gear shifter is a control mechanism mounted to handlebars that translates rider input into cable tension or electronic signals to reposition derailleurs across sprocket clusters, typically operating across 8 to 13 speed ranges with actuation forces between 30 and 60 Newtons depending on mechanism type. Its primary purpose is enabling efficient power transmission ratio selection across varying terrain grades and rider cadence preferences. Trigger shifters dominate mountain bicycle assemblies due to positive indexing durability under mud contamination, while electronic technology captures margin pools in road and e-bike segments where battery integration justifies premium positioning. Mechanical grip shifters retain volume in children's and entry-level hybrid categories where simplicity and low maintenance override precision demands.
FDA oversight applies to shifters integrated into medical-rehabilitation cycles, while EPA regulations on electroplating effluent constrain surface finishing operations in United States manufacturing. REACH compliance in Europe restricts hexavalent chromium in lever hardware, pushing suppliers toward trivalent conversion coatings or stainless steel substrates. Japan's JIS standards govern cable pull ratios that ensure interoperability across replacement part markets. Stakeholders must monitor how China's GB standards for e-bike component electrification reshape wireless protocol requirements across export supply chains.
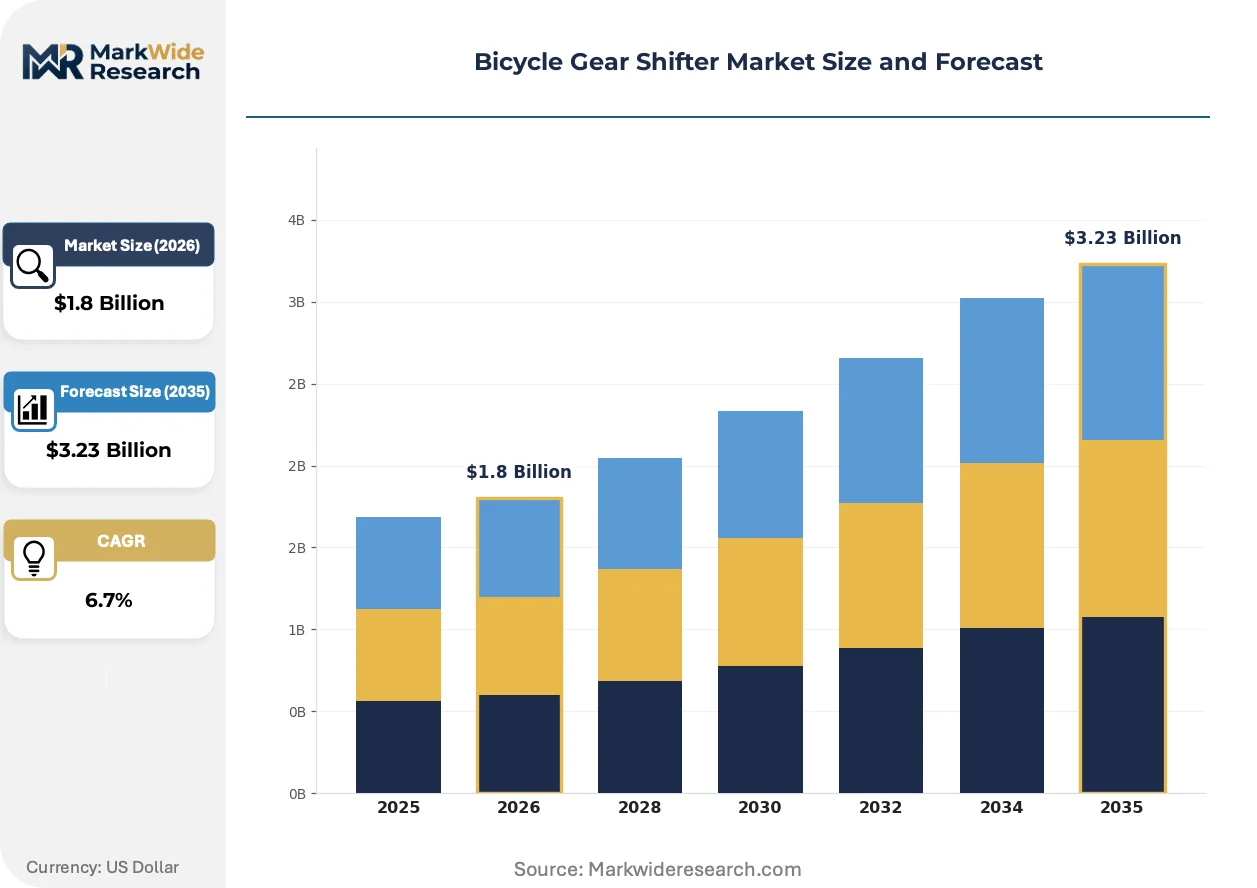
Market Dynamics
Mechanical-to-electronic shifter transitions are compressing replacement cycles while ISO 4210 certification requirements collapse the supplier base for entry-level manufacturers. Municipal fleet electrification programs and EU Green Deal transport targets are accelerating component procurement timelines across urban mobility networks.
Growth Catalysts
- EU Green Deal mandates:Transport decarbonization targets in Europe are accelerating mechanical-to-electronic shifter transitions across municipal e-bike procurement programs.
- E-bike fleet scaling:Urban mobility operators in China are expanding premium drivetrain component procurement as domestic manufacturing clusters absorb higher volumes.
- ISO 4210 certification:Bicycle safety standard enforcement is favoring incumbents with in-house testing laboratories, consolidating supply toward certified manufacturers.
Market Restraints
- Input cost volatility:Carbon fiber and rare-earth magnet prices fluctuate unpredictably, squeezing margins on electronic shifter motor assemblies.
- Supply concentration risk:Forging and plating capacity concentrates in Japan and Malaysia, creating geographic vulnerability for mechanical shifter cable pull mechanisms.
- Regulatory friction:REACH hexavalent chromium restrictions in Europe force costly conversion to trivalent coatings or stainless steel substrates.
Strategic Opportunities
- Medical-rehabilitation cycles:FDA oversight of shifters integrated into therapeutic bicycles creates specialized certification pathways for adaptive component suppliers.
- Wireless protocol standardization:China's GB standards for e-bike component electrification are reshaping export supply chain requirements for interoperable systems.
- Service channel innovation:Direct-to-consumer diagnostic tools and firmware update platforms are displacing traditional dealer networks for electronic drivetrain maintenance.
Industry Challenges
- Skill gap in electronic diagnostics:Bicycle mechanics lack training in wireless signal troubleshooting and motor calibration protocols.
- Certification timeline compression:JIS cable pull ratio compliance and ISO 4210 testing create multi-month approval bottlenecks for new product launches.
- Legacy system integration:Electronic shifters must maintain backward compatibility with mechanical derailleur geometries, constraining industrial design freedom.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Gear Shifter Market Trends and Innovations
Wireless actuation systems and embedded sensor networks are redrawing competitive boundaries between component tiers. Miniaturization of servo motors and battery cells is enabling handlebar-mounted controls that previously required frame-integrated hardware.
Micro-servo motor assemblies with integrated strain gauges are replacing traditional cable-actuated mechanisms in high-end road and e-bike segments. Pro-team specifications and enthusiast buyers are adopting these systems despite premium positioning. The technology is miniaturizing control hardware to the point where electronic shifting penetrates mid-tier price brackets previously dominated by mechanical systems.
REACH enforcement across European manufacturing is eliminating hexavalent chromium from lever hardware surface treatments. Suppliers are migrating toward trivalent conversion coatings or machined stainless steel substrates to maintain corrosion resistance. Road-specific integrated shifter-brake units face the steepest compliance costs due to tight tolerance requirements and pro-team durability expectations.
Fleet operators and large-scale municipal buyers are consolidating procurement through direct manufacturer relationships, bypassing traditional distributor tiers. Volume commitments and standardized service protocols are displacing the fragmented dealer networks that historically dominated aftermarket replacement. This concentration is most visible in China, where domestic e-bike manufacturing clusters negotiate component supply at scale.
Bicycle Gear Shifter Market Segmentation
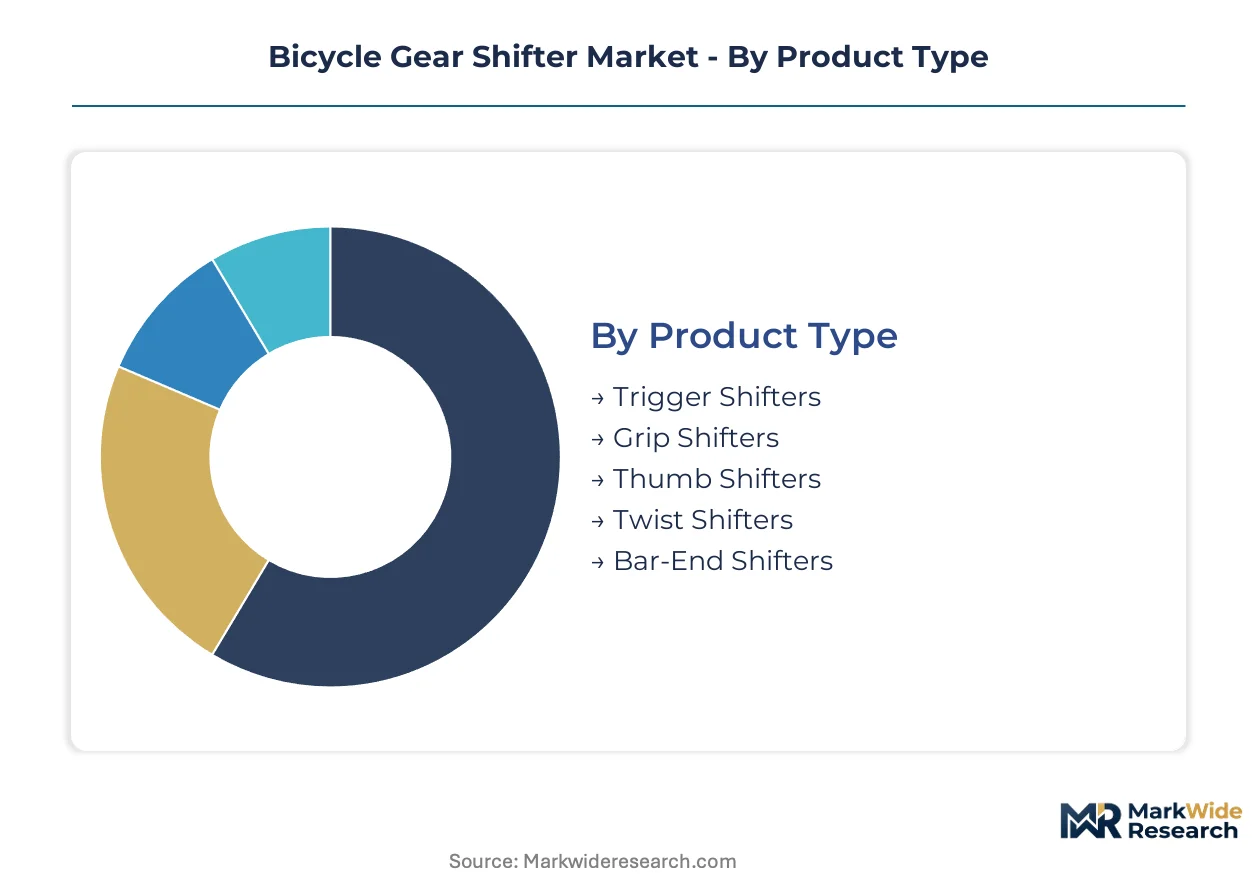
Segmentation in bicycle gear shifters reveals how procurement patterns diverge between fleet-scale municipal buyers and individual enthusiast channels. Each dimension—product form, actuation technology, bicycle category, and rider profile—carries distinct margin structures and certification requirements that reshape supplier priorities.
Product Type:
Domestic assembly lines in China and Taiwan absorb high volumes of entry-level twist and grip mechanisms, while premium trigger and bar-end variants flow primarily through European and North American export channels.
- Trigger Shifters:Index-click mechanisms with positive detent engagement dominate mountain bicycle OEM specifications. Municipal fleet operators in China specify these units for durability under contamination exposure across urban e-bike networks.
- Grip Shifters:Rotational actuation with integrated twist control simplifies maintenance for children's and hybrid categories. North American big-box retailers concentrate procurement here, prioritizing low service overhead over precision indexing.
- Thumb Shifters:Friction or indexed thumb-lever designs persist in touring and retro-fit segments where mechanical simplicity overrides ergonomic optimization.
- Twist Shifters:Cylindrical grip rotation with internal cable drum serves entry-level price brackets across Asian domestic markets.
- Bar-End Shifters:Handlebar-end mounted levers for time-trial and touring geometries where aerodynamic hand position takes precedence over rapid shifting speed.
Trigger shifters command the established base. The steepest expansion runs through grip shifters as Asian mass-market volume scales.
Technology:
Cost tier stratification separates mechanical cable systems from electronic servo architectures, with hydraulic and wireless variants occupying intermediate premium positioning.
- Mechanical:Cable-pull translation of lever input through housing maintains dominance in price-sensitive tiers. Japanese JIS standards govern interoperability across replacement markets, locking in specification stability.
- Electronic:Servo-motor actuation with programmable shift mapping captures margin pools in road and e-bike segments. EU Green Deal procurement mandates accelerate municipal adoption where battery integration justifies premium positioning.
- Hydraulic:Fluid-actuated mechanisms for integrated brake-shift units in high-performance road applications.
- Wireless:Radio-frequency signal transmission eliminates cable routing complexity for clean frame aesthetics.
- Bluetooth Enabled:Smartphone connectivity for firmware updates and ride-data integration in connected bicycle ecosystems.
Mechanical systems anchor volume foundations. Electronic architectures are climbing the fastest as fleet electrification programs scale procurement.
Application:
Volume concentration varies sharply by bicycle category, with electric and mountain segments driving divergent technology requirements.
- Mountain Bicycles:Mud-resistant indexing and impact-tolerant housing specifications define this segment. Trigger mechanisms with sealed bearing pivots satisfy pro-team durability testing protocols.
- Electric Bicycles:Motor-cutout integration and reinforced housing for torque-assist drivetrains dominate municipal fleet specifications. China's domestic manufacturing clusters absorb premium electronic volumes here.
- Road Bicycles:Lightweight integrated brake-lever units with tight tolerance stacks serve enthusiast and competitive riders.
- Hybrid Bicycles:Versatility-focused designs balancing urban commuting efficiency with occasional trail capability.
- Touring Bicycles:Reliability-optimized mechanical systems prioritizing field serviceability over weight minimization.
Mountain configurations hold the installed base. Electric bicycle integration shows the steepest expansion trajectory.
End User:
Customer type determines channel structure, with rental services and professional cyclists bypassing traditional retail tiers.
- Sports Enthusiasts:Performance-oriented buyers prioritizing weight reduction and shift precision in aftermarket upgrade cycles. North American and European specialty retailers serve this segment through dealer-certified installation.
- Bicycle Rental Services:Fleet-scale operators negotiating direct manufacturer relationships for standardized maintenance protocols. Municipal programs across European cities consolidate procurement here, displacing distributor intermediaries.
- Professional Cyclists:Pro-team specification influence drives component selection through sponsorship and technical collaboration.
- Casual Riders:Price-sensitive occasional users accepting functional adequacy over performance optimization.
Sports enthusiasts represent the revenue core. Rental services are expanding most quickly as urban mobility programs multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's transport decarbonization mandates are accelerating mechanical-to-electronic shifter transitions across municipal procurement programs. China's domestic e-bike manufacturing clusters absorb premium drivetrain volumes as urban mobility networks scale. Japan maintains specification authority through JIS cable pull ratio standards that govern replacement part interoperability.
China
Municipal fleet operators in Beijing and Shanghai are expanding component procurement as domestic e-bike manufacturing clusters absorb premium drivetrain volumes. GB standards for e-bike component electrification are reshaping wireless protocol requirements across export supply chains. The Yangtze River Delta manufacturing belt concentrates forging and plating capacity for mechanical shifter cable pull mechanisms.
Germany
REACH enforcement is eliminating hexavalent chromium from lever hardware surface treatments across Stuttgart and Munich industrial zones. The EU Green Deal's transport decarbonization targets are accelerating municipal e-bike procurement timelines in Berlin and Hamburg. Baden-Württemberg's precision engineering clusters maintain tight tolerance production for pro-team specification components.
United States
EPA regulations on electroplating effluent constrain surface finishing operations in Midwest manufacturing corridors. Carbon brake lever and shifter blade production concentrates in domestic facilities serving North American aftermarket channels. California's municipal bike-share programs are standardizing electronic drivetrain specifications across fleet procurement.
Japan
METI oversight reinforces JIS standards governing cable pull ratios that ensure interoperability across replacement part markets. Captive forging and plating facilities in Osaka and Nagoya industrial zones control cost structures across mechanical and electronic product lines. The Kanto region maintains in-house testing laboratory capacity for ISO 4210 bicycle safety certification.
Italy
Sustained domestic production of road-specific integrated units with tight tolerances serves pro-team specification requirements across European racing circuits. The Veneto and Emilia-Romagna manufacturing districts specialize in Ergopower integrated shifter-brake assemblies. Italian regulators align with EU-wide REACH restrictions while preserving heritage production methods for premium road bicycle components.
Bicycle Gear Shifter Market Competitive Landscape
Listed leaders compete with private specialists across certification capability and captive manufacturing infrastructure. The supplier base is compressing as ISO 4210 bicycle safety certification requirements favor incumbents with in-house testing laboratories. Three archetypes dominate: vertically integrated component conglomerates with captive forging capacity, regional specialists in mechanical cable systems, and technology-focused entrants in electronic servo architectures. Competitive moves concentrate on backward integration into carbon fiber lever production and strategic partnerships with municipal fleet operators.
Within the integrated tier, Shimano and SRAM anchor positions through geographic diversification of manufacturing assets. Campagnolo occupies a specialized position representing Italian heritage production of road-specific integrated units. These three exemplify how certification capability and captive infrastructure are consolidating supply toward established manufacturers with multi-decade specification authority.
| Leading Market Players |
|---|
| Shimano |
| SRAM |
| Campagnolo |
| SunRace Sturmey-Archer |
| microSHIFT |
| BOX Components |
| Tektro |
| Pinion |
| FSA |
| Others |
Pricing and Supply Chain Analysis
Captive forging and plating capacity in Osaka and Nagoya industrial zones generates scale economies that compress unit costs across mechanical and electronic product lines, simultaneously elevating price floors for uncertified entrants lacking comparable infrastructure. This concentration of in-house testing laboratories and surface finishing operations tightens supply-side control, allowing incumbent manufacturers to defend margin pools while ISO 4210 certification requirements collapse the supplier base for entry-level producers.
Pricing Analysis
Certification level creates the primary spread between premium electronic servo architectures and economy mechanical cable systems, with ISO 4210-grade components commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across pro-team specification, municipal fleet-grade, and mass-market entry levels reflects differentiation by testing rigor, materials grade, and after-sales firmware support. Cost compression in entry-level mechanical tiers is intensifying because REACH hexavalent chromium restrictions force costly conversion to trivalent coatings or stainless steel substrates. Municipal fleet operators exhibit lowest price sensitivity due to volume commitments and standardized service protocols, while Asian domestic mass-market channels remain most price-sensitive.
Supply Chain Analysis
Malacca Strait transit vulnerability underwrites logistics risk for rare-earth magnet and carbon fiber shipments feeding electronic shifter motor assemblies. Manufacturing gravity centers on Japan, Malaysia, and China, with Yangtze River Delta clusters absorbing premium drivetrain volumes and Baden-Württemberg precision engineering zones serving pro-team specifications. Raw material dependencies span carbon fiber for brake lever structures, neodymium magnets for servo motors, and specialty steels for cable pull mechanisms. Single-source vulnerability concentrates in Japanese forging capacity for mechanical shifter internals. Distribution runs through direct manufacturer relationships with municipal fleet operators, displacing traditional dealer networks for electronic drivetrain aftermarket service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless protocol standardization across China's GB standards and Japan's JIS specifications is transforming bicycle gear shifters into a platform-economics market where interoperability investments determine competitive survival. Ecosystem control over firmware update channels and diagnostic tool access is displacing traditional hardware margin pools.
For Market Incumbents: Shield market position by deepening backward integration into carbon fiber lever production and securing captive plating capacity ahead of REACH enforcement expansion. ISO 4210 certification investment represents the priority defensive lever against supplier base compression, while direct firmware distribution platforms counter emerging diagnostic-tool entrants threatening dealer network control. For New Entrants and Emerging Players: FDA certification fast-track for medical-rehabilitation cycle shifters opens specialized procurement pathways underserved by incumbent road and mountain focus. Adaptive component suppliers targeting therapeutic bicycle OEMs face lower certification barriers and reduced price competition. White-space concentration in European municipal fleet maintenance contracts offers go-to-market traction through outcome-based service agreements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component suppliers with electronic servo architectures and wireless protocol IP over pure-play mechanical cable manufacturers. Long-term viability across the projection horizon rests on firmware-enabled recurring revenue streams and fleet-scale direct relationships. Acquisition screening should prioritize testing laboratory assets and GB standards compliance capability. The signal to monitor is municipal procurement standardization velocity across European Green Deal implementation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Production | SRAM and Shimano captive facilities in United States and Malaysia insulate margin structures from input volatility. |
| ISO 4210 Certification Investment | In-house testing laboratories collapse supplier base toward certified incumbents with multi-decade specification authority. |
| Direct-to-Consumer Diagnostic Platform Launch | Firmware update channels displace traditional dealer networks for electronic drivetrain maintenance revenue capture. |
| Medical-Rehabilitation Cycle Partnership | FDA oversight creates specialized procurement pathways with reduced price sensitivity and certification barriers. |
| Wireless Protocol Standardization Alignment | China's GB standards reshape export supply chain requirements for interoperable electronic systems. |
Research Methodology
Initial hypotheses were tested against primary input from component procurement managers at municipal fleet operators, aftermarket service directors at specialty retailers, and R&D leads at drivetrain manufacturers, then refined through secondary validation. OEM platform engineers, Tier 1 supplier quality assurance heads, and bike-share program operations managers contributed additional perspective. Secondary sources included customs and trade data on carbon fiber and rare-earth magnet flows, SEC filings from listed component manufacturers, and JIS standards documentation. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers.
Variance decomposition across actuation technology, bicycle category, and end-user type segments isolated growth contribution by tier. The analytical framework projected volume and value across the modeling period by linking municipal procurement timelines to EU Green Deal implementation velocity and China's domestic e-bike manufacturing cluster expansion. CAGRs derived from segment-level unit economics and pricing trajectory assumptions. Forecast inputs incorporated REACH compliance cost pass-through rates and ISO 4210 certification timeline compression effects.
Decision-makers should treat outputs as directional under assumptions of sustained EU transport decarbonization policy and stable rare-earth magnet supply; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as China's GB standards evolution and REACH enforcement expansion reshape wireless protocol requirements and surface finishing operations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.