
 Two-Wheeler Fuel Injection Systems Market | 2026-2036
Two-Wheeler Fuel Injection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Two-Wheeler Fuel Injection Systems Market Analysis
OEM buyer concentration is hardening as motorcycle and scooter manufacturers consolidate supplier rosters around fewer qualified fuel injection partners. Robert Bosch GmbH leverages its electronic fuel injection portfolio to anchor European and Asian OEM programs. Denso Corporation sustains manufacturing scale across Japanese and Southeast Asian assembly plants. Marelli Holdings Co., Ltd. competes through integrated powertrain electronics that reduce calibration cycles for scooter platforms.
Two-wheeler fuel injection systems meter pressurized fuel through solenoid-actuated injectors at 2.5 to 5 bar operating pressure, replacing carburetors to achieve stoichiometric air-fuel ratios and lower tailpipe emissions. Gasoline electronic fuel injection dominates current revenue pools due to its penetration across commuter motorcycles and premium scooters. Port fuel injection maintains mature cost structures in mass-market segments while direct injection technology captures margin concentration in performance-oriented motorcycles where combustion efficiency thresholds are tightening.
India's CEA and BIS enforce Bharat Stage VI emission mandates that mandate closed-loop oxygen sensor feedback and precise injector mapping for domestic two-wheeler sales. Euro 5 requirements administered by the EU and Italy's KBA-equivalent technical services extend comparable stringency across European type approvals. Stakeholders must monitor regulatory divergence between Asian emission timelines and European CO2 trajectory rules to align R&D spending and certification investments.
Market Dynamics
OEM supplier consolidation around certified fuel injection partners is hardening procurement power, compressing vendor margins while elevating technical qualification barriers for new entrants seeking motorcycle and scooter platform wins.
Growth Catalysts
- Bharat Stage VI:India's CEA and BIS emission mandates require closed-loop oxygen sensor feedback and precise injector mapping, forcing carburetor displacement across domestic two-wheeler sales.
- Electronic control unit miniaturization:Smaller ECU form factors enable fuel injection retrofitting into compact scooter architectures previously reserved for carbureted powertrains.
- Vietnam production clustering:Honda and Yamaha assembly corridors around Hanoi and Ho Chi Minh City concentrate demand for port fuel injection systems at mass-market scale.
Market Restraints
- Piezoelectric injector cost structure:Precision solenoid manufacturing and ceramic stack materials sustain 40-60% cost premiums over carburetor assemblies, pressuring entry-level motorcycle margins.
- Semiconductor supply concentration:ECU microcontroller and sensor chip fabrication concentrates in Taiwan and South Korea foundries, exposing two-wheeler OEMs to foundry allocation volatility.
- Technical service network gaps:Rural India and inland China lack trained technicians for fuel system diagnostics, slowing post-warranty service coverage expansion.
Strategic Opportunities
- Indonesia underpenetration:The world's third-largest two-wheeler market maintains 70% carburetor share, creating white space for fuel injection conversion as Jakarta implements emission controls.
- Ethanol flex-fuel convergence:Brazil's ANVISA biofuel mandates and India's E20 targets are forcing injector hardware and software adaptations for variable alcohol-gasoline blends.
- Direct-to-OEM calibration services:Tier-2 suppliers are bypassing traditional tier-1 system integrators by offering engine mapping and homologation support directly to motorcycle manufacturers.
Industry Challenges
- Embedded software talent scarcity:Combustion calibration engineers with gasoline direct injection expertise command premium compensation in India and China, constraining R&D team scaling.
- Homologation timeline compression:Euro 5 and Bharat Stage VI parallel certification requirements extend type approval cycles by 8-12 months, delaying new model launches.
- Legacy platform integration friction:Carburetor-era engine architectures require substantial intake manifold redesign to accommodate injector placement and fuel rail packaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two-Wheeler Fuel Injection Systems Market |
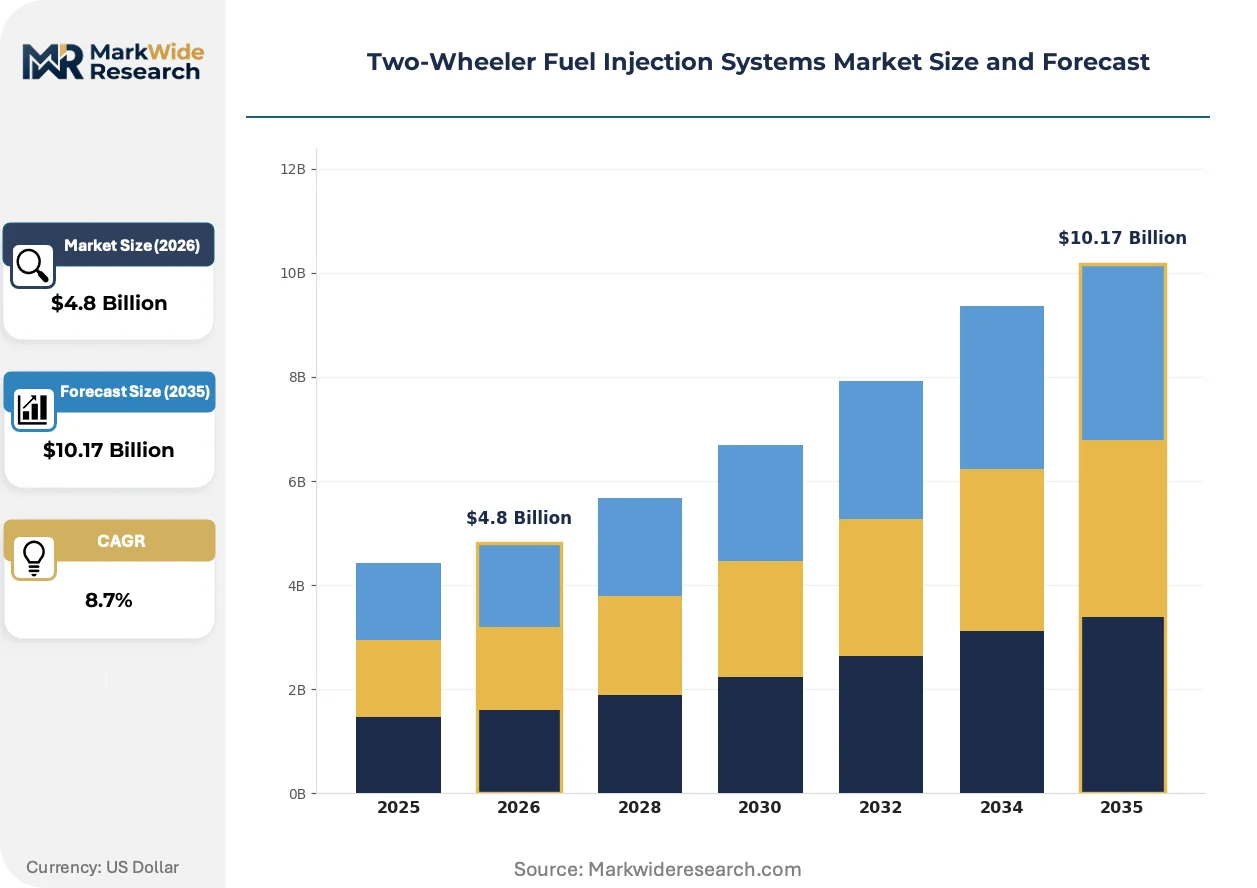
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Hybrid, Electric Technology: Electronic Fuel Injection, Mechanical Fuel Injection, Direct Injection, Port Fuel Injection End User: OEMs, Aftermarket Retailers, Fleet Operators, Service Centers Application: Motorcycles, Scooters, Moped, E-Bikes |
| Companies Covered | Robert Bosch GmbH, Marelli Holdings Co., Ltd., Denso Corporation, Mikuni Corporation, Hitachi Astemo, Ltd., Walbro LLC, SEDEMAC Mechatronics Pvt Ltd, UCAL Systems Inc., DUCATI Energia Spa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two-Wheeler Fuel Injection Systems Market Emerging Trajectories
Hardware-software decoupling is reshaping how fuel injection systems are developed, validated, and updated across two-wheeler product lifecycles. Three forces are compressing traditional engineering timelines.
Gasoline direct injection for motorcycles is modularizing from high-performance sportbike segments into mid-displacement commuter platforms. Yamaha and Kawasaki are adopting 200-350cc GDI architectures to meet Euro 5 thermal efficiency thresholds without displacement penalties. This modularity is compressing the cost gap between port and direct injection, enabling mass-market penetration by 2028.
REACH substance restrictions and EU F-Gas Regulation are banning specific fuel system sealing materials and refrigerants used in evaporative emission control. European two-wheeler manufacturers are reformulating hose compounds and charcoal canister designs to maintain type approval compliance. The scooter segment faces the steepest reformulation costs due to compact packaging constraints and evaporative emission test stringency.
Buyer concentration among top-five motorcycle OEMs is consolidating calibration specification power. Honda, Hero, and TVS Motor now demand source-code access and algorithm ownership as standard procurement terms, displacing traditional black-box supplier relationships. This specification capture is most visible in India, where domestic OEMs leverage scale to extract intellectual property concessions from Japanese and European system vendors.
Two-Wheeler Fuel Injection Systems Market Segmentation
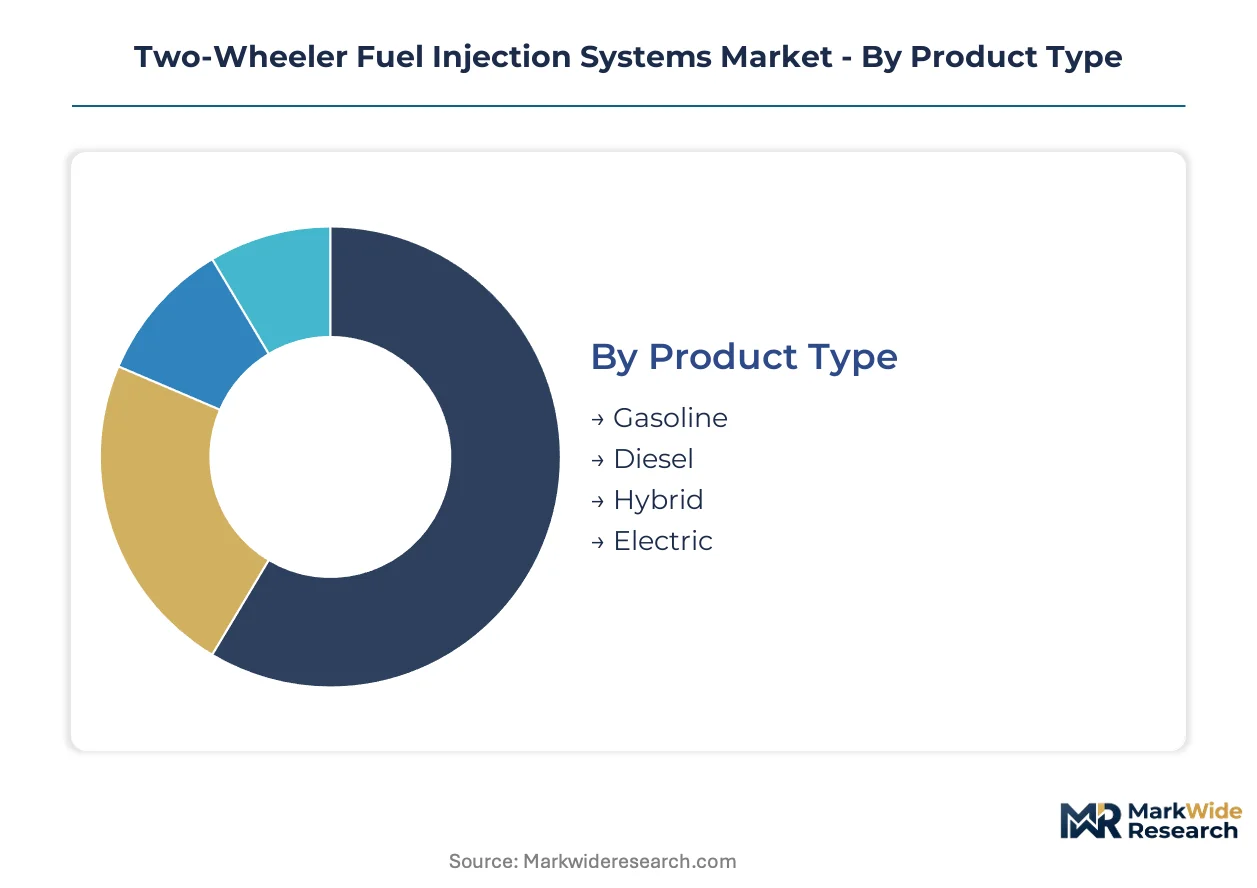
Segmentation in two-wheeler fuel injection systems tracks how engineering specifications, procurement channels, and vehicle architectures split demand across incompatible hardware configurations. Each dimension carries distinct margin profiles and supplier qualification requirements.
Product Type:
Supply concentration for fuel injection hardware clusters around gasoline system architectures, with foundry capacity and injector tooling investments aligned to spark-ignition combustion cycles.
- Gasoline:Electronic port and direct injection systems meter pressurized fuel through solenoid-actuated injectors at 2.5 to 5 bar operating pressure. Demand concentrates in India, China, and Vietnam where commuter motorcycle and scooter production volumes dominate assembly schedules. Bharat Stage VI and Euro 5 emission mandates have forced near-complete carburetor displacement in these markets.
- Diesel:Compression-ignition fuel injection operates at substantially higher pressures with specialized pump-nozzle or common-rail architectures. Demand concentrates in European and Indian commercial two-wheeler segments where torque density requirements exceed gasoline thermal efficiency limits. Euro 5 particulate matter thresholds are tightening injector precision specifications.
- Hybrid:Dual-fuel architectures combine internal combustion with electric motor assistance, requiring integrated powertrain control modules.
- Electric:Battery-electric powertrains eliminate fuel injection entirely, though range-extender variants retain small gasoline generators.
Gasoline absorbs the bulk of installed capacity; hybrid is expanding most quickly as OEMs bridge emission compliance and range anxiety.
Technology:
Cost tier differentiation separates mature port injection architectures from emerging direct injection systems competing on combustion efficiency rather than unit economics.
- Electronic Fuel Injection:Microprocessor-controlled injector pulsing enables closed-loop oxygen sensor feedback and precise air-fuel ratio management. Demand concentrates across mass-market motorcycles and scooters in India and Vietnam where CEA and BIS emission enforcement has mandated EFI as baseline equipment. ECU miniaturization is enabling retrofit into compact scooter architectures.
- Direct Injection:In-cylinder fuel spraying achieves higher compression ratios and thermal efficiency than port injection. Demand concentrates in 200-350cc performance motorcycles from Yamaha and Kawasaki where Euro 5 compliance requires combustion efficiency gains without displacement penalties. Hardware costs remain 25-40% above port injection equivalents.
- Mechanical Fuel Injection:Pump-driven fuel metering without electronic control persists in legacy commercial applications and certain racing exemptions.
- Port Fuel Injection:Intake manifold injector placement maintains mature cost structures in mass-market segments where calibration simplicity outweighs efficiency optimization.
Port fuel injection captures the highest shipment volumes; direct injection is climbing the fastest as mid-displacement platforms adopt GDI architectures.
End User:
Procurement patterns split between captive OEM supply agreements and fragmented aftermarket service networks with divergent technical capabilities.
- OEMs:Motorcycle and scooter manufacturers consolidate supplier rosters around certified fuel injection partners with homologation support capabilities. Honda, Hero, and TVS Motor demand source-code access and algorithm ownership as standard procurement terms. Supplier consolidation is compressing vendor margins while elevating technical qualification barriers.
- Aftermarket Retailers:Independent distributors serve replacement injector and fuel pump demand for out-of-warranty vehicles. Technical service network gaps in rural India and inland China constrain service coverage expansion.
- Fleet Operators:Commercial two-wheeler aggregators prioritize fuel economy monitoring and predictive maintenance integration.
- Service Centers:Authorized repair facilities perform warranty injector replacement and ECU recalibration.
OEMs command the dominant procurement share; fleet operators are gaining share fastest as mobility-as-a-service models expand.
Application:
Vehicle architecture constraints dictate injector packaging, fuel rail geometry, and evaporative emission control complexity.
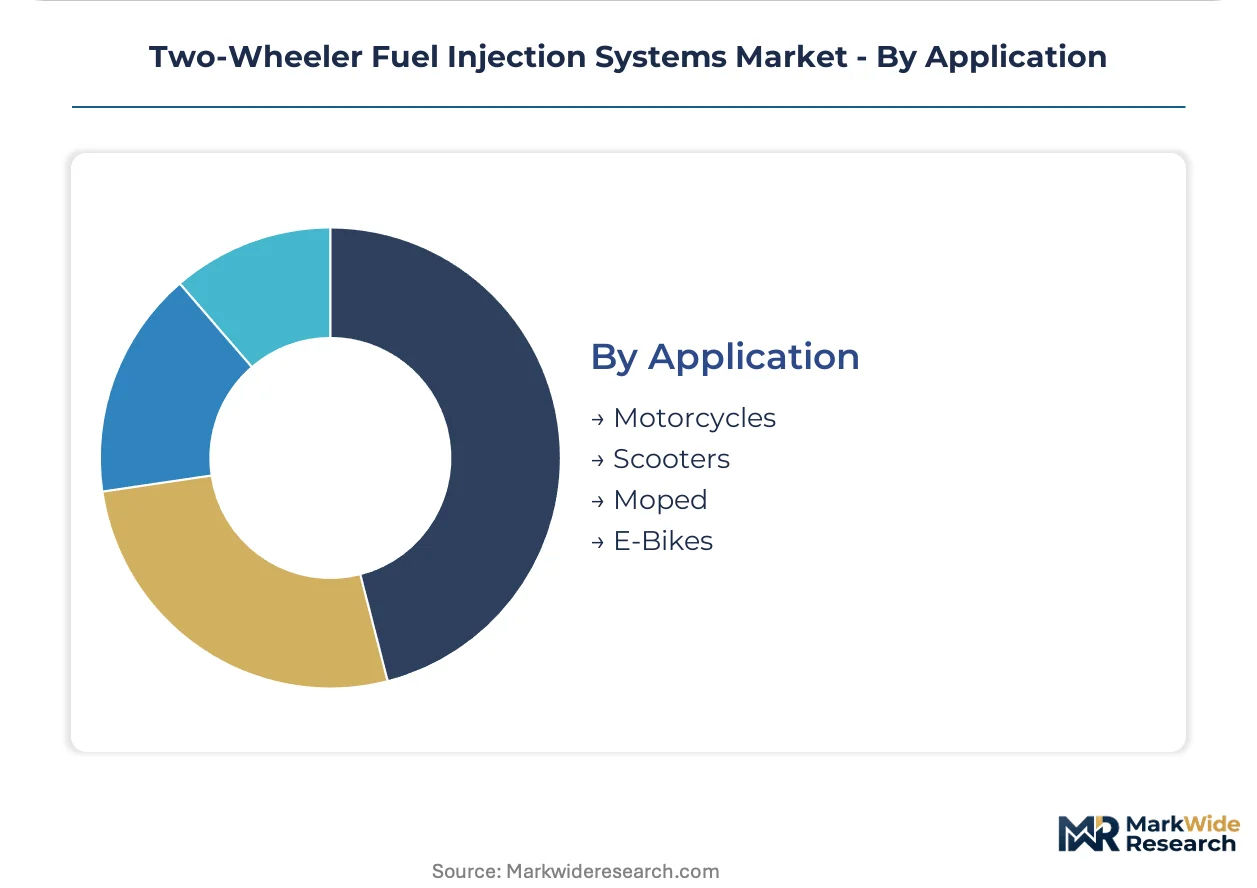
- Motorcycles:Frame geometry and fuel tank positioning accommodate varied injector configurations across commuter, sport, and touring segments. Demand concentrates in Indian and Vietnamese assembly corridors where Honda and Yamaha production lines specify port fuel injection for 100-150cc commuter platforms. Direct injection penetration is rising in 200cc-plus performance segments.
- Scooters:Compact under-seat engines and enclosed bodywork impose severe packaging constraints on fuel rail and injector placement. Euro 5 evaporative emission test stringency is forcing charcoal canister and hose compound reformulation. REACH substance restrictions are banning specific sealing materials.
- Moped:Low-displacement two-stroke and four-stroke engines in European and Southeast Asian markets.
- E-Bikes:Pedal-assist electric bicycles fall outside fuel injection scope except range-extender variants.
Motorcycles retain the largest installed base; scooters are expanding most quickly in Asian urban mobility segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum die-casting corridors in Gujarat and Tamil Nadu feed injector housing production across Indian two-wheeler assembly plants. Semiconductor fabrication in Taiwan and South Korea concentrates ECU microcontroller supply for Asian OEM programs. Precision machining clusters in southern Germany supply high-pressure injector components to European motorcycle manufacturers.
India
Domestic motorcycle and scooter production exceeding 20 million units annually anchors port fuel injection demand for commuter platforms. The CEA and BIS enforce Bharat Stage VI mandates requiring closed-loop oxygen sensor feedback across all gasoline two-wheelers. Manufacturing corridors in Pune, Chennai, and Gurugram concentrate Honda, Hero, and TVS Motor assembly lines specifying EFI as baseline equipment.
China
Export-oriented motorcycle production from Chongqing and Guangdong provinces sustains injector demand for Southeast Asian and African markets. The MIIT administers China VI emission standards tightening injector precision specifications for domestic sales. The Yangtze River Delta cluster around Shanghai houses precision component suppliers serving both domestic OEMs and export assembly operations.
Vietnam
Honda and Yamaha production lines around Hanoi and Ho Chi Minh City specify fuel injection systems for 100-150cc mass-market scooters. The country's national technical regulation agency enforces emission controls aligned with Euro 4 benchmarks. The northern industrial zone in Vinh Phuc province concentrates component suppliers feeding just-in-time assembly schedules.
Italy
Premium motorcycle manufacturers in Bologna and Milan specify direct injection architectures for performance-oriented displacement segments. The KBA-equivalent technical services administer Euro 5 type approval extending certification timelines for new powertrain introductions. The Emilia-Romagna engineering corridor maintains specialized calibration facilities supporting Ducati and MV Agusta development programs.
Indonesia
The world's third-largest two-wheeler market retains 70% carburetor penetration, creating conversion white space as Jakarta implements emission controls. The national environmental ministry is phasing in Euro 4-equivalent standards across Java and Sumatra production zones. The Bekasi industrial corridor east of Jakarta concentrates Honda and Yamaha assembly plants evaluating fuel injection adoption timelines.
Two-Wheeler Fuel Injection Systems Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue software calibration services and flex-fuel adaptation capabilities. Three strategic archetypes define competitive positioning: integrated powertrain electronics suppliers, precision injector component specialists, and regional ECU calibration houses. Supplier consolidation around certified partners is compressing vendor margins while elevating technical qualification barriers. Dominant competitive moves include strategic partnerships for semiconductor supply security and geographic expansion into underpenetrated Southeast Asian markets.
Within the integrated electronics tier, Robert Bosch GmbH and Denso Corporation exemplify full-system suppliers with homologation support capabilities. Marelli Holdings Co., Ltd. occupies a position emphasizing powertrain integration that reduces calibration cycles. Among precision component specialists, Mikuni Corporation and Hitachi Astemo, Ltd. represent Japanese fabricators with historical carburetor expertise transitioning to electronic architectures. SEDEMAC Mechatronics Pvt Ltd and UCAL Systems Inc. exemplify regional Indian suppliers capturing domestic OEM procurement share through algorithm ownership concessions.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Marelli Holdings Co., Ltd. |
| Denso Corporation |
| Mikuni Corporation |
| Hitachi Astemo, Ltd. |
| Walbro LLC |
| SEDEMAC Mechatronics Pvt Ltd |
| UCAL Systems Inc. |
| DUCATI Energia Spa |
| Others |
Supply Flow & Price Mechanics
Combustion calibration engineers concentrated in Pune and Bangalore command compensation premiums that widen spreads between economy-tier port injection modules and premium direct injection architectures. Labor-cost differentials between Indian software talent pools and European hardware fabrication clusters feed into three-tier pricing stratification across OEM procurement tiers.
Pricing Analysis
High-volume port fuel injection contracts for 100-150cc commuter motorcycles absorb thinner margins than low-volume direct injection systems for 200-350cc performance platforms. Price differentiation hinges on certification grade (Bharat Stage VI versus Euro 5) and vertical integration depth, with semiconductor sourcing costs intensifying margin pressure across all tiers. Fleet operators and mass-market OEMs exhibit acute price sensitivity, while premium motorcycle manufacturers tolerate 25-40% hardware premiums for combustion efficiency gains.
Supply Chain Analysis
Regional distribution centers in Gujarat and Tamil Nadu feed just-in-time injector housing deliveries to assembly corridors around Pune and Chennai. Precision solenoid manufacturing draws from Taiwan and South Korea foundries, while ceramic stack materials and aluminum die-casting inputs anchor production costs. Single-source vulnerability in ECU microcontroller fabrication exposes the chain to foundry allocation volatility. Distribution runs through captive OEM supply agreements rather than open-market spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity constraints prop fuel injection system pricing, with ECU chip allocation bottlenecks sustaining supplier leverage through the near-window.
For Market Incumbents: Anticipate specification capture demands from Honda, Hero, and TVS Motor by securing algorithm ownership concessions before procurement terms harden further. Defend margin position through backward integration into injector solenoid production in Tamil Nadu manufacturing corridors. Prioritize certification investment for Bharat Stage VI and Euro 5 parallel homologation to compress approval timelines. For New Entrants and Emerging Players: Aftermarket service centers in rural India represent the most penetrable buyer archetype, with technical network gaps creating white space for diagnostic tool and training service bundles. Indonesia's 70% carburetor penetration offers conversion demand as Jakarta implements emission controls. Pursue direct-to-OEM calibration services to bypass tier-1 system integrator gatekeeping. For Investors and Strategic Acquirers: The window for entry favors regional ECU calibration houses with algorithm ownership and domestic OEM relationships in India and Southeast Asia. Long-term viability rests on software-defined fuel injection architectures displacing hardware-centric legacy systems. Watch for inflection when direct injection penetration crosses into mass-market 125-150cc scooter platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Supply Security Partnership | ECU microcontroller allocation agreements with Taiwan foundries insulate against fabrication volatility. |
| Direct Injection Modularization Program | GDI architecture cost reduction enables penetration into 200-350cc commuter motorcycle segments. |
| Ethanol Flex-Fuel Hardware Adaptation | Injector and software modifications for E20 and variable biofuel blends capture Brazil and India mandates. |
| Calibration Service Capability Buildout | Engine mapping and homologation support displaces traditional tier-1 supplier relationships. |
| Southeast Asian Distribution Expansion | Vietnam and Indonesia assembly corridor proximity reduces logistics lead times for OEM programs. |
Methodological Framework
Independent corroboration across OEM procurement executives, tier-1 system integrator engineering directors, and aftermarket distributor operations managers underwrites the qualitative findings. Primary interviews with BIS certification specialists and CEA regulatory affairs officers combined with secondary validation from MIIT emission standard filings, EU type approval databases, and production volume registries. Bottom-up shipment modeling and top-down value chain triangulation anchored market sizing.
Comparable-period anchoring tied projection trajectories to historical Bharat Stage VI and Euro 5 implementation cycles across the modeling period. Segmentation dimensions spanned propulsion architecture, injection technology tier, vehicle displacement class, and regional regulatory cluster. CAGRs derived from installed base turnover rates and emission mandate compliance timelines, with semiconductor supply elasticity and foundry allocation patterns as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to emission standard acceleration, biofuel mandate revision, and electric two-wheeler substitution rates. Outputs reflect documented assumptions around OEM consolidation trajectories and supplier qualification barriers. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Automotive Chain Sprockets Market
Bikes and Motorcycles
Motorcycle Transmission Control Unit Market
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
Two-Wheeler Market
Bikes and Motorcycles
North America Bicycle Market
Bikes and Motorcycles
Two Wheeler Suspension System Market
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
UAE Motorcycle ADAS Market
Bikes and Motorcycles
Smart Bicycle Accessories Market
Bikes and Motorcycles
Child Bike Seats Market
Bikes and Motorcycles
United States E-Bike Market
Bikes and Motorcycles
Aluminum Alloy Bicycle Crankset Market
Bikes and Motorcycles
Shock Absorber Market