
 Musical Instrument Insurance Market | 2026-2036
Musical Instrument Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Musical Instrument Insurance Market Analysis
Parametric claims processing is tilting underwriting economics toward real-time damage verification and faster settlement cycles. Allianz Insurance plc leverages its global risk engineering network to sustain competitive positioning in high-value orchestral coverage. Chubb Ltd. anchors its offering on bespoke valuation services for rare string instruments, while Anderson Musical Instrument Insurance Solutions, LLC specializes in niche policies for vintage American-made guitars.
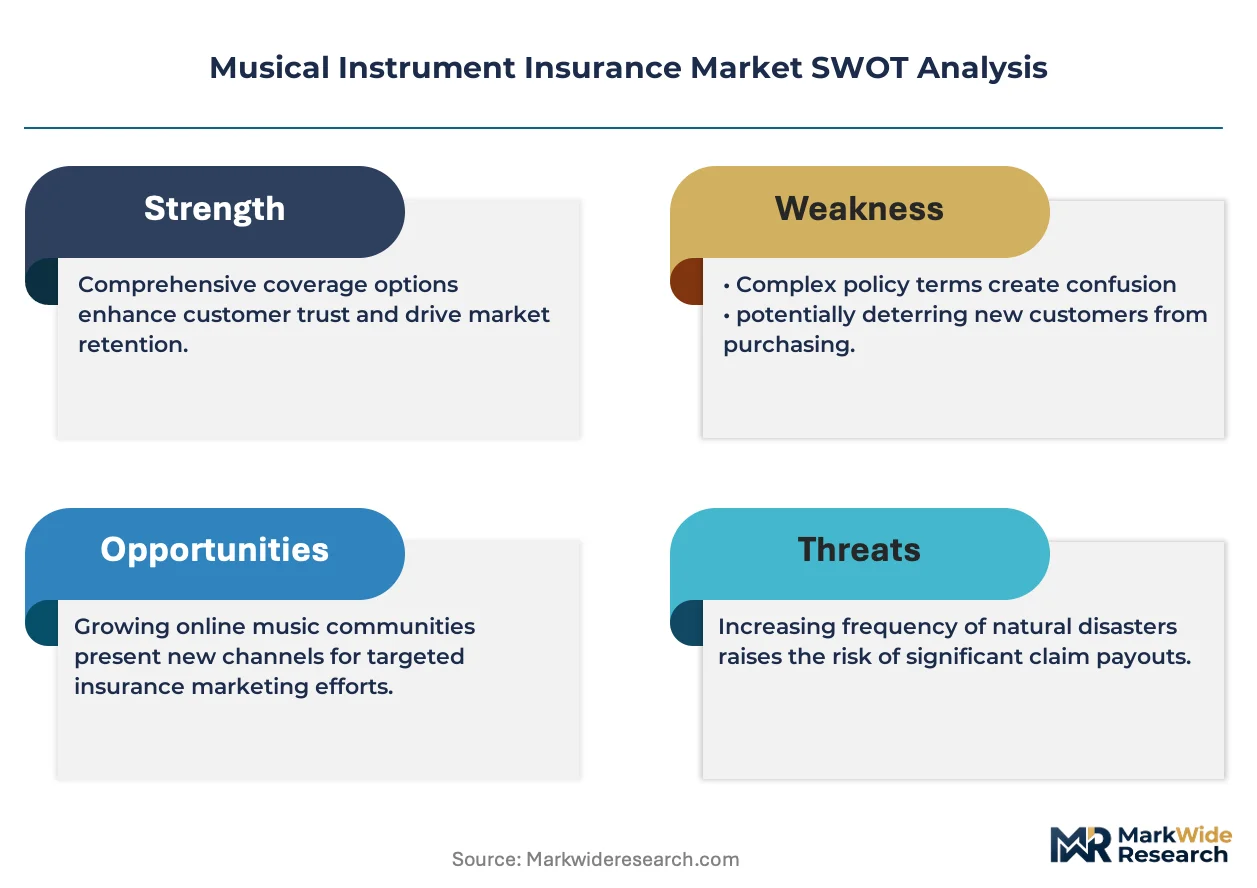
Musical instrument insurance constitutes a specialized property and casualty product designed to indemnify against physical loss, theft, accidental damage, and transit peril for owned or leased instruments, with policies typically incorporating agreed-value clauses based on independent appraisal documentation. The primary commercial purpose centers on protecting capital-intensive assets that appreciate asymmetrically and possess irreplaceable artisanal characteristics. Comprehensive policy types dominate premium volume by bundling peril coverage with liability protection, whereas agreed-value coverage models command superior margins by eliminating depreciation disputes for heirloom-grade violins and concert grand pianos. Professional musicians represent the most risk-literate customer segment, though schools and studios generate recurring institutional premiums with lower loss ratios.
Regulators across multiple jurisdictions shape market conduct, with the US National Association of Insurance Commissioners establishing reserve adequacy standards and the UK's Financial Conduct Authority enforcing policy transparency and claims-handling timelines. GDPR constraints in Europe limit granular data collection for premium personalization, while state-level insurance commissioners in the US oversee rate filings and market entry. Stakeholders must monitor evolving climate risk modeling standards and appraisal authentication technologies to maintain underwriting precision and policyholder trust.
Market Dynamics
Climate-related transit risks are reshaping underwriting economics as touring orchestras and gigging professionals demand parametric claims processing for real-time damage verification and accelerated settlement cycles.
Growth Catalysts
- EU Green Deal transit standards:Germany's concentration of collectors and luthiers drives policy uptake for high-value instrument protection under stricter environmental liability frameworks.
- Digital underwriting platforms:Risk assessment automation compresses quote-to-bind timelines for professional musicians managing irregular income streams.
- Gig economy expansion:Freelance performers in urban music clusters require flexible coverage models that traditional annual policies fail to address.
Market Restraints
- Appraisal authentication bottlenecks:Independent valuation documentation requirements create friction for heirloom-grade violins and rare string instruments where qualified assessors concentrate in select metropolitan areas.
- GDPR data constraints:European premium personalization faces hard limits on granular behavioral data collection for risk segmentation.
- Depreciation dispute exposure:Standard replacement-cost policies generate claims litigation for appreciating artisanal assets with asymmetric value trajectories.
Strategic Opportunities
- Institutional education verticals:Schools and studios generate recurring premium pools with demonstrably lower loss ratios than individual performer segments.
- Blockchain provenance integration:Distributed ledger verification is hybridizing with parametric triggers to automate claims for theft and transit damage events.
- US state-level rate deregulation:Insurance commissioners in select jurisdictions are relaxing filing requirements for specialized personal lines products.
Industry Challenges
- Climate risk modeling talent scarcity:Underwriting teams lack actuarial expertise in transit peril quantification for temperature-sensitive wooden instruments.
- Legacy system integration friction:Parametric claims platforms require costly API development to connect with established policy administration systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Musical Instrument Insurance Market |
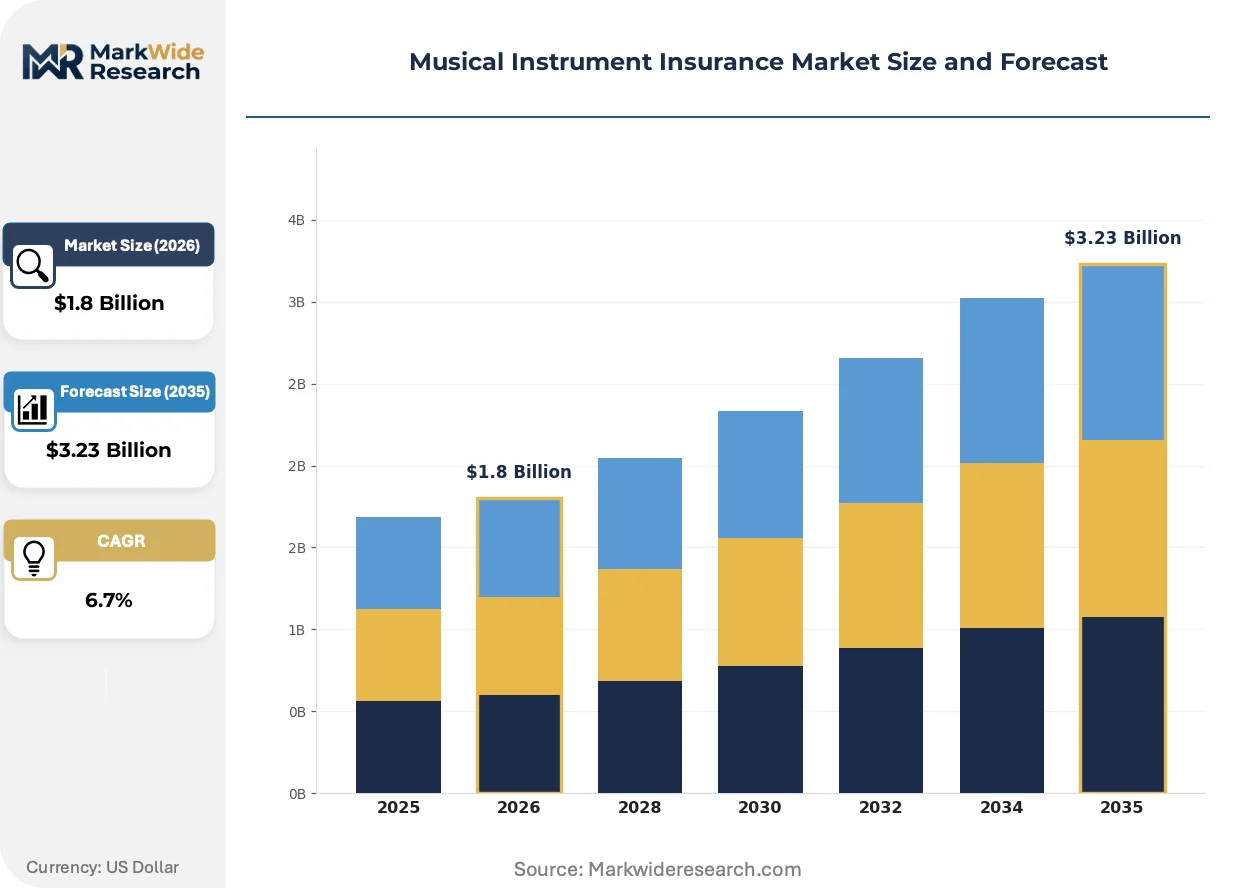
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Comprehensive, Coverage-Only, Liability, Theft Protection Instrument Type: Guitar, Violin, Piano, Drum Kit Customer Type: Professional Musicians, Amateur Players, Schools, Studios Coverage Model: Replacement Cost, Actual Cash Value, Agreed Value, Stated Amount |
| Companies Covered | Allianz Insurance plc, AXA Insurance Ltd., Anderson Musical Instrument Insurance Solutions, LLC, Chubb Ltd., Zurich Insurance Group AG, MusicPro Insurance Agency LLC, Clarion Musical Instrument Insurance, Aston Lark, Assetsure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Musical Instrument Insurance Market Emerging Trajectories
Digital infrastructure is compressing value chains across underwriting, claims, and risk engineering functions while regulatory pressure on transparency accelerates platform investment.
Parametric insurance architecture is hybridizing with IoT environmental sensors to trigger automatic payouts when temperature or humidity thresholds breach contractually defined limits during instrument transit. Symphony orchestras and touring artists are piloting these programs for high-value string collections. The technology is compressing claims cycles from weeks to hours while reducing loss-adjustment expenses.
GDPR enforcement by European data protection authorities is constraining behavioral data deployment for premium personalization across EU member states. Insurers must now obtain explicit consent for granular risk segmentation using performance history or travel patterns. German and French carriers are responding by investing in first-party data collection through policyholder-facing mobile applications.
Subscription-based coverage models are displacing traditional annual contracts among freelance musicians with irregular income and episodic performance schedules. Digital-native brokers are capturing this segment through app-based policy management and on-demand activation for specific tours or recording sessions. This shift is most visible in London, Berlin, and New York metropolitan clusters where gig economy concentration exceeds national averages.
Musical Instrument Insurance Market Segmentation
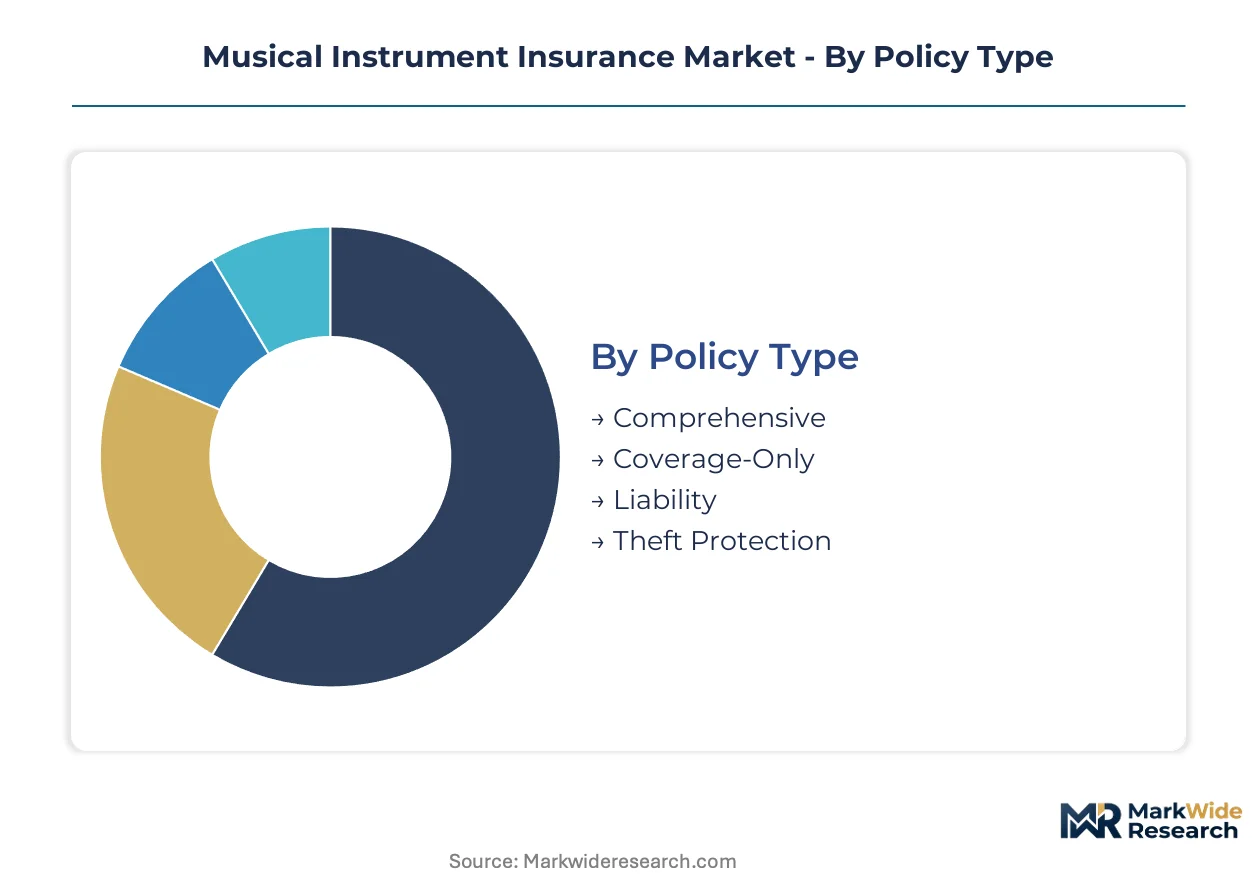
Musical instrument insurance products segment across four critical dimensions that determine underwriting economics, claims complexity, and distribution strategy. Policy architecture, instrument characteristics, customer risk profiles, and valuation methodologies each create distinct market pockets with unique margin structures and service requirements.
Policy Type:
Cost tier differentiation separates bundled protection from single-peril offerings, with premium concentration tracking toward comprehensive solutions and basic coverage serving price-sensitive entry segments.
- Comprehensive:Bundles physical damage, theft, transit peril, and liability protection into unified contracts with streamlined claims handling. Orchestras in Germany and high-net-worth collectors in London drive concentration here, prioritizing administrative simplicity over granular customization.
- Coverage-Only:Strips out liability components to deliver pure property protection at reduced premium points. Amateur players in metropolitan music clusters purchase these policies through digital-native brokers seeking basic damage and theft protection without professional liability exposure.
- Liability:Addresses third-party bodily injury and property damage arising from performance or instruction activities. Music schools in US states with stringent tort environments generate institutional demand for this segment.
- Theft Protection:Isolates criminal loss coverage for instruments with documented provenance vulnerabilities. Touring professionals with irregular transit patterns activate these policies episodically through subscription platforms.
Comprehensive commands the established base. The steepest expansion runs through Coverage-Only as digital distribution lowers acquisition costs for entry-level musicians.
Instrument Type:
Application-specific risk profiles vary dramatically across instrument categories, with wooden string instruments demanding climate-sensitive transit modeling and percussion requiring distinct damage assessment protocols.
- Guitar:Electric and acoustic variants dominate policy volume through mass-market accessibility and gig economy ubiquity. Vintage American-made models from the 1950s-60s command specialized agreed-value coverage with authentication requirements that create appraisal bottlenecks in secondary markets.
- Violin:Heirloom-grade instruments from Cremona and Mittenwald luthiers carry asymmetric appreciation trajectories that invalidate standard depreciation schedules. German collectors and orchestral principals in Berlin, Munich, and Hamburg concentrate demand for bespoke valuation services.
- Piano:Concert grands and studio uprights present divergent risk profiles—concert instruments face intensive transit exposure while institutional pianos in schools generate recurring premium pools with lower loss ratios.
- Drum Kit:Component-based construction and frequent disassembly for transport elevate damage frequency relative to other categories. Recording studios in New York and London metropolitan clusters drive commercial demand for rapid replacement coverage.
Violin coverage captures the highest premium density per policy. Guitars are climbing the fastest as subscription platforms democratize access for freelance performers.
Customer Type:
Customer sophistication and income regularity shape product design, with risk literacy varying from actuarially informed professionals to institutions seeking administrative efficiency.
- Professional Musicians:Touring artists and orchestral principals possess granular understanding of transit peril and climate sensitivity. These policyholders demand parametric triggers, agreed-value clauses, and rapid claims cycles that compress traditional loss-adjustment timelines.
- Amateur Players:Hobbyists with lower asset concentrations and irregular performance schedules favor simplified coverage with digital-first service. Subscription activation models align with episodic instrument use in urban music clusters.
- Schools:K-12 and university music programs generate institutional premiums with demonstrably favorable loss experience. Bulk instrument fleets and standardized replacement protocols reduce per-unit claims administration costs.
- Studios:Commercial recording and rehearsal facilities require hybrid coverage addressing owned equipment, client instrument custody, and premises liability. London and Berlin studio concentrations exceed national averages for this segment.
Schools anchor the recurring premium base. Professional musicians are expanding most quickly as parametric products penetrate orchestral and touring verticals.
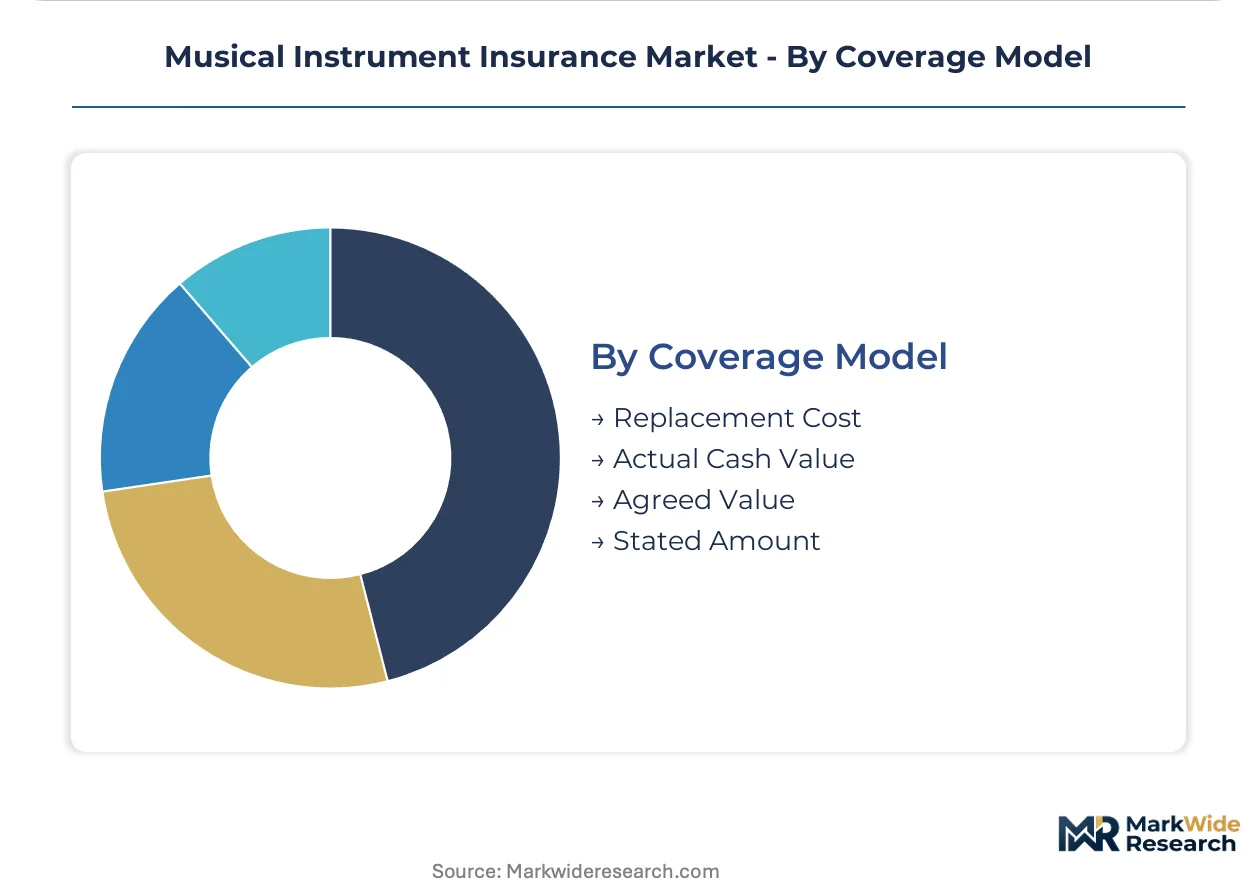
Coverage Model:
Valuation methodology determines claims dispute exposure and margin stability, with depreciation-based models generating litigation friction for appreciating artisanal assets.
- Replacement Cost:Indemnifies at current market price for equivalent new instruments, creating coverage gaps for discontinued vintage models. Standard personal lines products default to this structure, generating disputes when appreciation outpaces inflation indices.
- Actual Cash Value:Applies depreciation schedules that misalign with asymmetric value trajectories of heirloom-grade string instruments. German and French collectors avoid this model for Cremona violins and historic bows.
- Agreed Value:Locks in payout amounts through independent appraisal documentation, eliminating post-loss valuation disputes. Chubb Ltd. and specialized carriers anchor offerings here for rare instruments with concentrated assessor availability in select metropolitan areas.
- Stated Amount:Permits policyholder-declared values with limited verification, trading precision for administrative efficiency in lower-tier segments. Digital-native brokers deploy this structure for rapid quote-to-bind cycles.
Agreed Value holds the premium margin leadership. Stated Amount is gaining share fastest as automated underwriting platforms prioritize speed over granular valuation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in musical instrument insurance track the geographic concentration of high-value instrument manufacturing, collector density, and touring infrastructure. Premium generation concentrates in markets with established orchestral traditions and robust appraisal ecosystems.
United States
Touring orchestras and freelance musicians in New York, Los Angeles, and Nashville drive policy uptake for transit and climate-risk coverage. State insurance commissioners in California and New York oversee rate filings for specialized personal lines products. The Recording Academy's advocacy in Los Angeles sustains demand for studio equipment and performer liability bundles.
Germany
Collectors in Berlin, Munich, and Hamburg maintain dense concentrations of Cremona violins and historic bows requiring agreed-value coverage. The EU Green Deal transit standards impose stricter environmental liability frameworks on orchestral logistics. Frankfurt's insurance hub anchors underwriting capacity for high-value string instrument portfolios.
United Kingdom
London's orchestral principals and West End pit musicians generate demand for parametric claims processing and rapid settlement cycles. The Financial Conduct Authority enforces policy transparency and claims-handling timeline standards. Manchester and Birmingham music schools produce institutional premium pools with favorable loss experience.
Japan
Tokyo's philharmonic orchestras and traditional instrument conservatories create specialized coverage needs for both Western and wagakki collections. METI guidelines influence domestic carrier product design for cultural asset protection. Osaka's luthier workshops concentrate appraisal expertise for regional underwriting.
France
Parisian collectors and Opéra National performers demand bespoke valuation services for rare string instruments. GDPR enforcement by the CNIL constrains granular behavioral data collection for premium personalization. Lyon and Marseille music academies generate recurring institutional premiums with standardized replacement protocols.
Musical Instrument Insurance Market Vendor Landscape
On the supply side, the industry is structured around three distinct tiers: global multi-line carriers with dedicated fine arts divisions, regional specialists with luthier network access, and digital-native brokers targeting freelance musicians. Strategic archetypes include valuation-anchored underwriters, parametric technology integrators, and subscription platform operators. Competitive moves center on API partnerships with IoT sensor providers and vertical integration into appraisal authentication services.
Within the global carrier tier, Allianz Insurance plc and Chubb Ltd. occupy positions defined by risk engineering scale and bespoke valuation capabilities respectively. Anderson Musical Instrument Insurance Solutions, LLC exemplifies the specialist archetype with concentrated focus on vintage American-made guitar coverage. These three anchors illustrate how underwriting precision, geographic reach, and instrument-specific expertise stratify competitive positioning across premium and mid-market segments.
| Leading Market Players |
|---|
| Allianz Insurance plc |
| AXA Insurance Ltd. |
| Anderson Musical Instrument Insurance Solutions, LLC |
| Chubb Ltd. |
| Zurich Insurance Group AG |
| MusicPro Insurance Agency LLC |
| Clarion Musical Instrument Insurance |
| Aston Lark |
| Assetsure |
| Others |
Supply Flow & Price Mechanics
Undercapacity among qualified instrument appraisers in Germany and France compresses quote-to-bind timelines while elevating agreed-value premiums for heirloom-grade string collections. This utilization squeeze forces carriers to ration access to bespoke valuation services or absorb higher loss-adjustment expenses.
Pricing Analysis
Professional musicians anchor pricing stratification across premium, standard, and economy tiers based on risk literacy and asset concentration. Price differentiation hinges on appraisal authentication depth and parametric trigger sophistication. Cost compression in entry-level subscription products is intensifying because digital-native brokers automate underwriting without independent valuation. Amateur players exhibit highest price sensitivity; orchestral principals with Cremona violin collections show minimal elasticity.
Supply Chain Analysis
Upstream appraisal expertise feeds from luthier workshops concentrated in Germany, Italy, and Japan. Risk assessment protocols rest on climate sensor hardware from Taiwan, proprietary parametric platforms from US insurtech clusters, and blockchain provenance services from UK fintech hubs. Single-source vulnerability concentrates in Cremona violin authentication where three family firms dominate certification. Distribution runs through captive agent networks for high-value orchestral coverage and app-based brokers for freelance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Musical instrument insurance functions as a defensive-moat market where appraisal authentication networks generate switching costs that lock in high-net-worth collectors and institutional clients.
For Market Incumbents: Harden proprietary access to Cremona and Mittenwald luthier certification networks against emerging insurtech entrants deploying AI-based condition assessment. Invest in backward integration into climate sensor deployment for touring orchestras. Consolidate regional appraisal bottlenecks through exclusive partnerships with German and Italian valuation specialists.
For New Entrants and Emerging Players: Build out subscription-based micro-coverage for freelance musicians in London, Berlin, and New York metropolitan clusters where gig economy concentration exceeds national averages. Target amateur players with app-based rapid quote-to-bind products. Pursue white-label partnerships with digital music distribution platforms for embedded insurance at point of instrument purchase.
For Investors and Strategic Acquirers: Long-term, this sits as a niche compounder play because parametric technology adoption and climate risk quantification create durable underwriting advantages for first movers. Acquisition targets should exhibit concentrated appraisal network access in Germany or Japan. Monitor IoT sensor penetration rates in symphony orchestra touring contracts as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Claims Platform Integration | Allianz and Chubb compress settlement cycles from weeks to hours for touring orchestras. |
| Blockchain Provenance Verification | Distributed ledger authentication automates theft claims for rare string instruments with documented ownership chains. |
| Appraisal Network Consolidation | Exclusive partnerships with Cremona luthier families lock in competitive positioning for agreed-value coverage. |
| Subscription Coverage Launch | On-demand activation models capture freelance musicians with irregular income and episodic performance schedules. |
| Climate Sensor Deployment | IoT environmental monitoring triggers automatic payouts when temperature thresholds breach contractually defined limits during transit. |
Methodological Framework
Initial hypotheses were tested against primary input from underwriting executives at global carriers, luthier appraisers in Germany and Italy, orchestral risk managers, and insurtech platform engineers and refined through secondary validation against NAIC reserve adequacy filings, UK FCA policy transparency reports, EU Green Deal transit standard documentation, and trade association data from instrument manufacturing clusters. Bottom-up policy volume estimates triangulated with top-down premium generation analysis across the four segmentation dimensions.
Demand-supply balance modeling anchored forecast construction across the projection horizon. Segmentation dimensions included policy architecture, instrument category, customer sophistication tier, and valuation methodology. CAGRs derived from historical premium trajectory analysis and forward-looking underwriting capacity expansion. Industry-specific inputs incorporated climate risk model evolution and parametric claims adoption curves in orchestral verticals.
Stress conditions across appraisal authentication bottlenecks, GDPR enforcement intensity, and climate-related transit loss frequency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about sensor technology cost curves and regulatory timeline adherence. Cross-checking against Lloyd's of London specialty lines underwriting data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Estonia Property and Casualty Insurance Market
Insurance
Global Fine Art Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
Critical Illness Insurance Market
Insurance
Europe Extended Warranty Market
Insurance
B2B2C Insurance Market
Insurance
Insurance Big Data Analytics Market
Insurance
Agriculture Insurance Market
Insurance
France Liability Insurance Market
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
Vietnam Private Health Insurance Market
Insurance
Global Sports Insurance Market
Insurance
Canada Health and Medical Insurance Market
Insurance
Intellectual Property Insurance Market
Insurance
Telecommunication Insurance Market
Insurance
India Liability Insurance Market