
 Peru Insurance Market | 2026-2036
Peru Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Peru Insurance Market Insights
Digital infrastructure is hardening as the backbone of policy economics across Peru's insurance sector. Rimac Seguros leverages its proprietary digital platform to extend reach into previously unserved provinces. Pacifico Seguros anchors its competitive stance through specialized health coverage networks concentrated in Lima. Mapfre Peru differentiates via bancassurance partnerships that control premium flow through major retail banking channels.
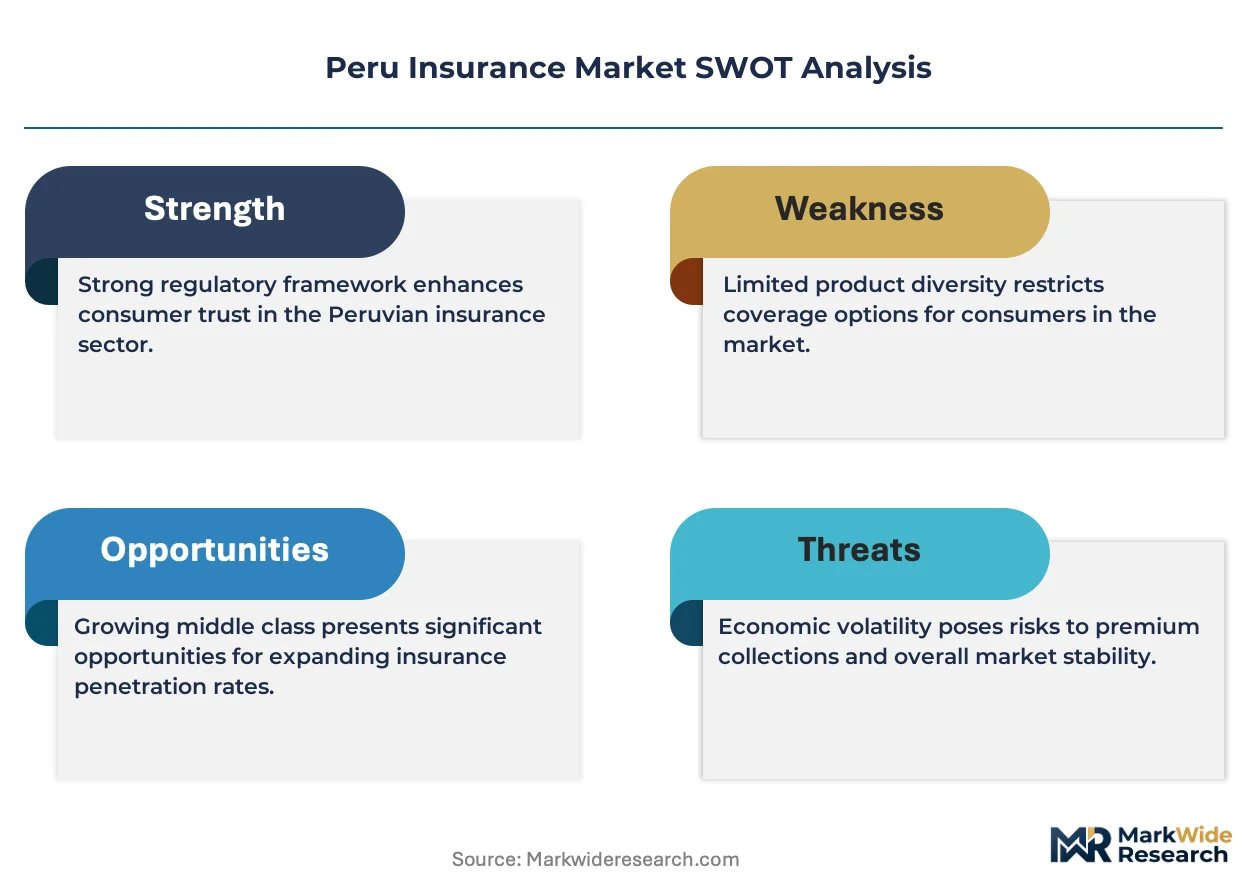
Peru Insurance constitutes risk-transfer contracts underwritten by authorized entities to indemnify policyholders against specified losses, with technical provisions governed by SBS reserve requirements and IFRS 17 accounting standards. The primary commercial purpose centers on converting contingent liabilities into predictable premium outflows for individuals and enterprises. Health Insurance and Vehicle Insurance command dominant premium shares, with Health Insurance drawing margin pools from corporate employee benefit mandates while Vehicle Insurance faces pricing pressure from saturated urban penetration. Microinsurance within Policy Type represents the fastest-expanding category, propelled by regulatory sandbox authorizations for simplified product structures targeting Peru's informal economy.
SBS, Peru's insurance and pension fund regulator, enforces solvency margins and product approval protocols that determine market access timelines for new entrants. The PLI scheme and evolving fintech regulations under the central bank reshape distribution economics by legitimating app-based policy origination. Stakeholders must monitor SBS digital-first licensing frameworks and IFRS 17 implementation costs as determinants of competitive viability in Peru's consolidating insurance landscape.
Market Dynamics
SBS digital-first licensing frameworks are compressing distribution timelines while IFRS 17 implementation costs are forcing operational consolidation among Peru's authorized underwriters. The collision between regulatory modernization and accounting standard migration is restructuring competitive viability across the sector.
Growth Catalysts
- PLI scheme expansion:Peru's evolving fintech regulations under the central bank legitimize app-based policy origination, reducing customer acquisition costs for informal economy penetration.
- Mining corridor demand:Emerging Andean mining districts generate concentrated risk-transfer requirements for employee benefit mandates and asset protection coverage.
- Microinsurance sandbox authorizations:SBS regulatory modernization permits simplified product structures that compress approval timelines for informal workforce targeting.
Market Restraints
- IFRS 17 compliance burden:Technical provision recalculation and data architecture upgrades impose capital intensity on mid-tier authorized entities.
- Lima metropolitan concentration:Premium flow clustering within the capital corridor creates geographic risk exposure and limits provincial diversification.
- Informal economy documentation gaps:Absence of formal income verification infrastructure constrains actuarial precision for microinsurance pricing.
Strategic Opportunities
- Provincial digital extension:Peru's unserved Andean and Amazonian regions present white-space origination potential via mobile-first distribution.
- Bancassurance channel deepening:Retail banking partnerships offer premium flow control through embedded product placement at point-of-sale.
- Health network convergence:Specialized coverage networks integrating telemedicine infrastructure address Lima's corporate employee benefit mandates.
Industry Challenges
- Actuarial talent scarcity:IFRS 17 technical expertise and data science capabilities command premium compensation, constraining mid-market hiring.
- Legacy system integration:Core policy administration platforms require API-layer reconstruction to support real-time digital origination workflows.
- Reserve adequacy verification:SBS solvency margin enforcement demands continuous recalibration of technical provisions against claims volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peru Insurance Market |
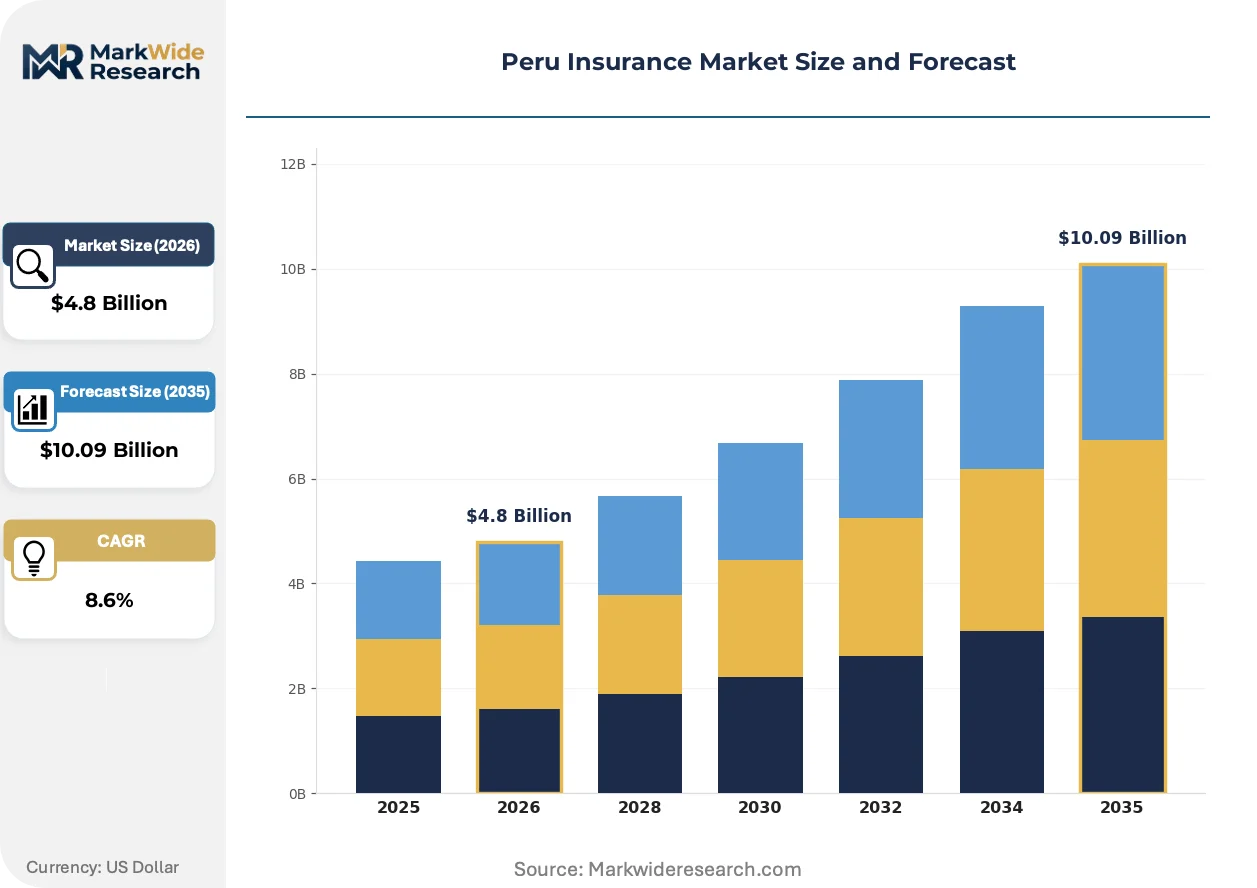
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Insurance, Health Insurance, Property Insurance, Vehicle Insurance Customer Type: Individuals, SMEs, Large Enterprises, Corporations Distribution Channel: Online, Brokers, Agents, Direct Sales Policy Type: Standard Policies, Customized Policies, Group Policies, Microinsurance |
| Companies Covered | Rimac Seguros, Pacifico Seguros, Mapfre Peru, La Positiva Seguros, Interseguro Seguros, Protecta Seguros, Vivir Seguros, Ohio National Seguros, BNP Paribas Cardif Seguros y Reaseguros, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peru Insurance Market Trends and Innovations
Digital infrastructure is compressing policy economics while regulatory sandboxes and behavioral shifts toward embedded protection are redrawing competitive boundaries. Three forces are actively restructuring how coverage reaches Peru's fragmented demand base.
Mobile-first origination platforms are decentralizing distribution access across Peru's informal workforce. Simplified underwriting algorithms enable instant policy activation without physical branch presence. Rural provinces previously excluded from agent networks now receive coverage through smartphone-enabled microinsurance enrollment.
SBS regulatory modernization expands digital distribution permissions beyond traditional broker channels. Authorized entities now originate policies through fintech partnerships without maintaining captive branch infrastructure. This regulatory tailwind compresses market access timelines for technology-enabled entrants targeting Lima's metropolitan corridor.
Informal workers are fragmenting procurement patterns away from annual premium cycles toward pay-as-you-earn micro-contributions. Embedded insurance at point-of-sale replaces standalone policy shopping for vehicle and health coverage. This behavioral rotation is most visible among Peru's gig economy participants and unbanked provincial populations.
Peru Insurance Market Segmentation
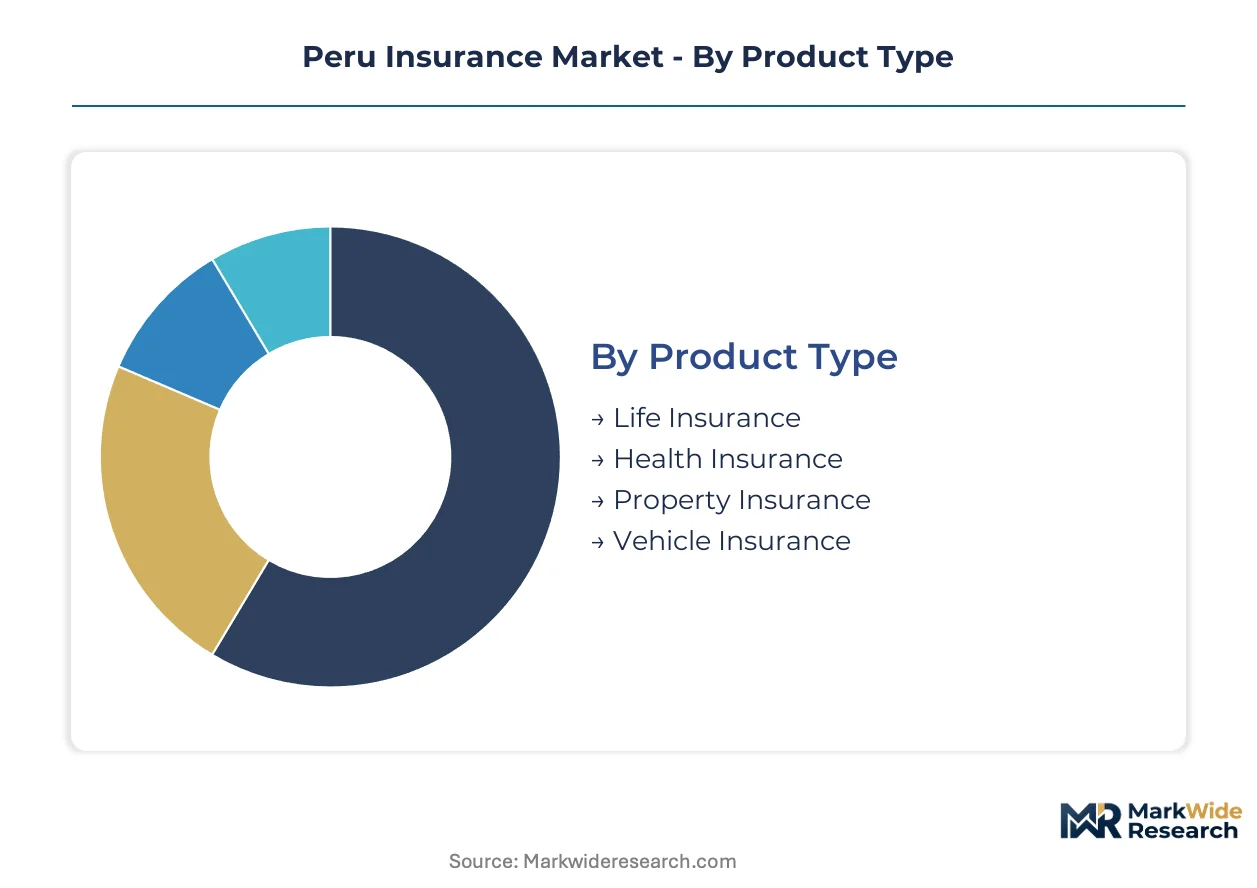
Peru's insurance market fragments across four structural dimensions that determine pricing power, distribution economics, and regulatory exposure. Product type and policy type classifications govern reserve requirements and capital intensity under SBS supervision. Customer type and distribution channel selections directly shape acquisition cost structures and persistency rates across Lima's metropolitan corridor versus provincial territories.
Product Type:
Buyers prioritize coverage scope against premium outflow predictability when selecting product categories, with corporate mandates and asset protection needs driving portfolio composition.
- Life Insurance:Long-duration contracts with guaranteed benefit structures dominate corporate employee benefit packages. Demand concentrates among large enterprises in Lima's financial district seeking tax-advantaged compensation instruments, though persistency challenges emerge from informal sector income volatility.
- Health Insurance:Specialized provider networks and reimbursement mechanisms define product differentiation. Corporate employee benefit mandates in Lima's metropolitan corridor absorb the majority of premium flow, with telemedicine integration now a standard coverage feature.
- Property Insurance:Covers physical asset protection against fire, natural disaster, and theft perils. Mining corridor expansion in the Andean region generates concentrated demand for industrial facility coverage.
- Vehicle Insurance:Mandatory third-party liability coverage intersects with comprehensive optional protection. Saturated urban penetration in Lima creates pricing pressure while provincial regions remain underpenetrated.
Volume sits with Health Insurance; growth tilts toward Life Insurance as corporate benefit mandates deepen.
Customer Type:
Scale of risk pooling and documentation infrastructure determines underwriting approach and pricing precision across customer categories.
- Individuals:Retail purchasers seeking personal coverage against mortality, health, and asset risks. Microinsurance adoption is climbing fastest among informal workers in Peru's gig economy.
- SMEs:Small and medium enterprises with limited risk management departments require bundled coverage solutions. Andean mining districts and Lima's commercial corridors generate concentrated demand for property and liability bundles.
- Large Enterprises:Sophisticated buyers with captive risk management capabilities negotiate customized terms. Employee benefit mandates drive health and life coverage procurement at scale.
- Corporations:Multinational and domestic conglomerates with complex cross-border exposure. SBS solvency requirements and IFRS 17 compliance costs factor into carrier selection criteria.
Corporations command premium pricing; SMEs are expanding most quickly as formalization incentives take hold.
Distribution Channel:
Cost per acquisition and policy servicing efficiency separate channel economics, with digital infrastructure investments reshaping competitive positioning.
- Online:Digital-first origination through proprietary platforms and fintech partnerships. SBS regulatory modernization permits app-based policy activation without branch infrastructure.
- Brokers:Independent intermediaries with multi-carrier access serving complex commercial risks. Corporate and large enterprise procurement relies heavily on broker advisory for coverage structuring.
- Agents:Captive or affiliated representatives with exclusive carrier relationships. Provincial penetration in unserved Andean and Amazonian regions depends on agent network density.
- Direct Sales:Carrier-employed sales forces targeting standardized product categories. Bancassurance partnerships embed direct sales at retail banking point-of-sale.
Brokers retain commercial dominance; online channels are gaining share fastest as PLI scheme expansion legitimizes digital origination.
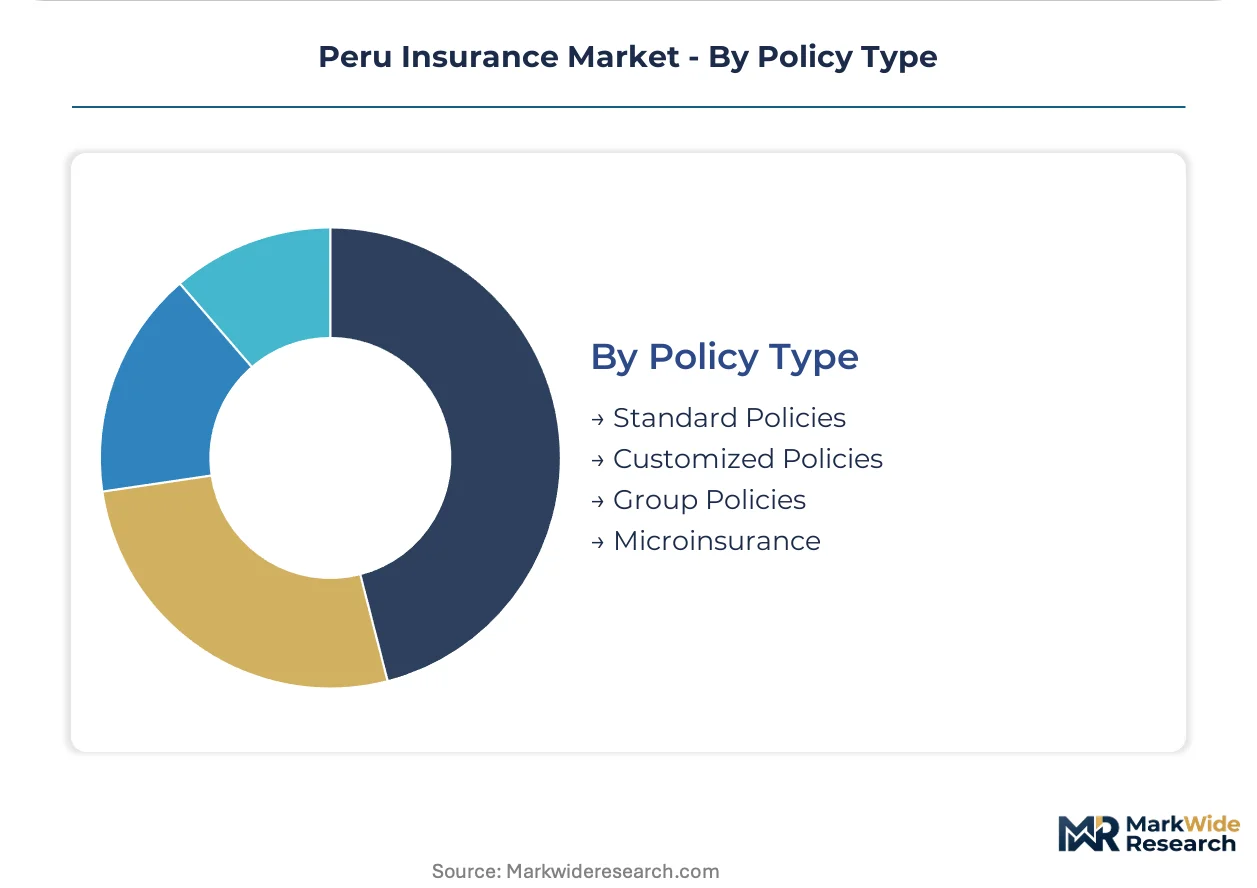
Policy Type:
Regulatory treatment and reserve calculation complexity vary sharply across policy structures, determining speed-to-market and capital requirements.
- Standard Policies:Pre-approved product templates with fixed terms and conditions. SBS product approval protocols compress launch timelines for these offerings.
- Customized Policies:Bespoke coverage structures negotiated for unique risk profiles. Large enterprises and mining operations in the Andean corridor require tailored asset protection terms.
- Group Policies:Master contracts covering defined employee or member populations. Corporate benefit mandates in Lima drive volume concentration.
- Microinsurance:Simplified structures with streamlined underwriting and pay-as-you-earn contribution models. Regulatory sandbox authorizations from SBS accelerate approval for informal workforce targeting.
Standard Policies anchor premium volume; Microinsurance shows the steepest expansion trajectory as sandbox frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peru's insurance demand concentrates in Lima's metropolitan corridor, where corporate headquarters and financial services clusters generate premium flow for health and life coverage. Provincial territories in the Andean highlands and Amazonian lowlands remain structurally underpenetrated despite rising microinsurance adoption.
Lima Metropolitan Area
Corporate employee benefit mandates and specialized health networks dominate premium generation in Peru's capital district. SBS regulatory frameworks enforce solvency margins and IFRS 17 compliance standards that shape carrier selection criteria. The financial district in San Isidro and corporate corridors in Miraflores anchor health insurance procurement for multinational and domestic conglomerates.
Arequipa and Southern Andean Corridor
Mining operations and associated service industries generate concentrated demand for property and liability coverage in Peru's second-largest city. The country's mining regulator enforces mandatory insurance requirements for extraction licenses and environmental compliance. Cerro Verde and surrounding mining districts absorb specialized risk-transfer products for asset protection and employee benefits.
Cusco and Central Highlands
Tourism infrastructure and agricultural commercialization drive property and casualty requirements in this historically significant region. Simplified microinsurance products target informal workers in hospitality and farming sectors through mobile-enabled distribution. The Sacred Valley corridor exhibits rising penetration of pay-as-you-earn contribution models for accident and health coverage.
Trujillo and Northern Coastal Zone
Agricultural export operations and emerging manufacturing clusters create demand for crop and commercial property protection. The central bank's fintech regulations enable app-based policy origination that reduces customer acquisition costs in dispersed rural territories. Chiclayo and Piura sub-regions show accelerating digital insurance adoption among SME agricultural processors.
Iquitos and Amazonian Territories
Logistics and extractive industry presence in Peru's largest Amazonian city generates specialized marine and cargo coverage requirements. Regulatory sandbox authorizations permit simplified product structures that compress approval timelines for remote territory targeting. The Loreto region represents white-space potential for mobile-first microinsurance enrollment among informal riverine economies.
Peru Insurance Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with established domestic carriers commanding corporate accounts while digital-native entrants capture informal sector volume. Peru's insurance sector exhibits tiered concentration around three authorized underwriters with dominant metropolitan presence. Strategic archetypes include legacy carriers with captive agent networks, bancassurance-anchored distributors, and technology-enabled microinsurance specialists. Competitive dynamics center on digital platform investments and bancassurance partnership deepening.
Among Lima-based authorized underwriters, Rimac Seguros exemplifies the proprietary digital platform archetype, Pacifico Seguros occupies a position within specialized health network differentiation, and Mapfre Peru represents bancassurance channel control through retail banking integration. These entities anchor competitive positioning across corporate benefit mandates and emerging provincial penetration strategies.
| Leading Market Players |
|---|
| Rimac Seguros |
| Pacifico Seguros |
| Mapfre Peru |
| La Positiva Seguros |
| Interseguro Seguros |
| Protecta Seguros |
| Vivir Seguros |
| Ohio National Seguros |
| BNP Paribas Cardif Seguros y Reaseguros |
| Others |
Pricing and Supply Chain Analysis
Corporate benefit managers in Lima's financial district anchor premium pricing power through large-scale group policy procurement, while provincial informal workers drive volume through microinsurance's pay-as-you-earn contribution models. This buyer archetype concentration splits the market between margin-rich corporate mandates and cost-compressed individual coverage.
Pricing Analysis
Volume concentrates in standardized group health policies with thin margins, while customized corporate life and mining property coverage retains pricing power. Three-tier pricing structure across premium, standard, and economy levels differentiates by network breadth and claims service speed. Pricing pressure stems from saturated urban vehicle penetration and SBS-mandated microinsurance affordability caps. SMEs exhibit highest price sensitivity due to informal documentation gaps, while multinational corporations negotiate least on premium in exchange for specialized provider network guarantees.
Supply Chain Analysis
Regional distribution centers in Lima's San Isidro and Miraflores districts operate hub-and-spoke patterns extending to Arequipa, Trujillo, and Cusco satellite offices. Actuarial services and health provider networks concentrate domestically, while reinsurance capacity draws from Bermuda, London, and Miami markets. Raw material dependencies include medical claims data infrastructure, telemedicine platform licensing, and IFRS 17 compliance software. Single-source vulnerability sits with legacy core policy administration systems requiring API-layer reconstruction. Distribution runs through bancassurance partnerships, broker networks, and emerging fintech app integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peru's insurance sector sits in a technology-transition phase where mobile-first origination platforms displace captive agent networks and branch infrastructure. Digital distribution infrastructure is replacing legacy policy administration systems as the primary competitive determinant.
For Market Incumbents: Lock in bancassurance channel control through exclusive retail banking partnerships that embed products at point-of-sale. Consolidate proprietary digital platform investments to defend against fintech-enabled entrants exploiting SBS sandbox authorizations. Prioritize API-layer reconstruction of legacy core systems to support real-time mobile origination workflows. For New Entrants and Emerging Players: Launch via fintech app partnerships targeting Peru's informal gig economy workforce with simplified microinsurance structures. White-space opportunity concentrates in Amazonian riverine economies and Andean mining districts outside Lima's metropolitan corridor. Go-to-market angle should leverage SBS regulatory modernization permitting branchless digital origination. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier authorized underwriters with established SBS licenses but lagging digital infrastructure in secondary Peruvian cities. Long-term viability hinges on 5-10 year digital platform completion and provincial network density. Watch SBS digital-first licensing framework expansion as inflection indicator for technology-enabled carrier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Integration | Proprietary mobile-first origination compresses customer acquisition costs in unserved provinces. |
| Bancassurance Partnership Deepening | Exclusive retail banking placement secures premium flow control at Lima point-of-sale. |
| Microinsurance Sandbox Authorization | SBS streamlined approval accelerates informal workforce targeting with simplified product structures. |
| Health Network Convergence | Telemedicine-integrated provider networks address corporate employee benefit mandates in metropolitan corridor. |
| Provincial Distribution Expansion | Agent network density in Andean and Amazonian regions captures mining and agricultural coverage demand. |
Research Methodology
Document review covered SBS regulatory filings, IFRS 17 implementation guidance, and central bank fintech regulations, complemented by interviews with insurance carrier strategy officers, SBS supervisory staff, and health network procurement directors. Secondary validation drew from industry association premium statistics, reinsurance market reports, and mining sector insurance requirement disclosures. Bottom-up policy volume estimates and top-down macroeconomic indicators underwent triangulation to establish market sizing.
Model outputs generated value trajectories across product type, customer type, distribution channel, and policy type segmentations over the projection horizon. CAGRs derived from historical premium growth patterns, regulatory sandbox expansion timelines, and informal economy formalization rates. Key forecast inputs included SBS digital licensing framework adoption curves and PLI scheme fintech partnership activation rates.
Regulatory enforcement intensity, IFRS 17 compliance cost escalation, and informal economy documentation infrastructure gaps are the dominant revision risks for Peru's insurance market projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Directors and Officers (Dando) Insurance Market
Insurance
Insurance Aggregators Market
Insurance
Internet of Things Insurance Market
Insurance
Title Insurance Market
Insurance
General Insurance Market
Insurance
Australia Parametric Insurance Market
Insurance
Finland Cyber (Liability) Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
South Korea Liability Insurance Market
Insurance
UK Cyber (Liability) Insurance Market
Insurance
Japan Bancassurance Market
Insurance
Vietnam Private Health Insurance Market
Insurance
Insurance Analytics Market
Insurance
Digital Innovation in Insurance Market
Insurance
Property and Casualty Insurance Market
Insurance
Intellectual Property Liability Insurance Market