
 Agricultural Drum Mowers Market | 2026-2036
Agricultural Drum Mowers Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Drum Mowers Market Insights
Modular attachment configurations is hardening as the dominant procurement pattern across drum mower lines. Krone leverages its European manufacturing footprint to dominate the premium heavy-duty segment. John Deere anchors its position through backward integration into precision cutting components. KUHN SAS differentiates via specialized hydraulic drive systems for hilly terrain.
Agricultural drum mowers are rotary cutting implements employing horizontally mounted cylindrical drums with helical blades, typically operating at 540–1000 RPM PTO speeds to sever forage crops with minimal leaf loss. The equipment serves commercial haymaking and silage operations where clean stubble height and throughput capacity determine feed quality. Heavy-duty mowers lead volume shipments due to durability requirements on large-scale dairy and beef operations. PTO-driven units sustain the largest installed base, though hydraulic drive configurations are gaining traction in high-horsepower tractor markets. Commercial farmers represent the core demand pool, with agricultural contractors expanding fastest as custom haymaking services consolidate across fragmented landholdings.
Europe's F-Gas Regulation and CE marking requirements constrain refrigerant-dependent manufacturing processes and mandate operator safety guarding standards. The US EPA and OSHA impose emissions and workplace noise thresholds that shape product design for North American export configurations. India's BIS certification and the country's PLI scheme for farm mechanization are opening import pathways for compliant equipment. Stakeholders must monitor how electric drive adoption intersects with evolving power-to-weight targets and regional subsidy eligibility.
Market Dynamics
Europe's F-Gas Regulation is forcing manufacturers to abandon hydraulic drive refrigerants, compressing development timelines and redrawing competitive boundaries around electric motor integration and power-to-weight engineering.
Growth Catalysts
- CE marking safety mandates:European guarding standards are accelerating replacement cycles as older drum mowers face retrofit costs exceeding new equipment premiums.
- Custom haymaking consolidation:Agricultural contractors across Germany's grassland corridor are absorbing fragmented dairy operations, concentrating demand for high-throughput PTO-driven units.
- India's PLI scheme:The production-linked incentive program for farm mechanization is opening import pathways for compliant equipment manufacturers.
Market Restraints
- Steel alloy volatility:Drum housing and blade material costs fluctuate with commodity markets, squeezing margin structures for mid-tier producers.
- Hydraulic component concentration:Precision drive system suppliers cluster in German industrial regions, creating single-source vulnerability for electric transition programs.
- PTO speed standardization:Legacy 540 RPM interfaces limit power transfer efficiency for next-generation cutting heads, constraining throughput gains.
Strategic Opportunities
- India's BIS certification pathway:Compliance with Bureau of Indian Standards unlocks access to the country's mechanization subsidy pools and state procurement programs.
- Silage quality premiums:Dairy operations in the Netherlands and Denmark are paying contract differentials for leaf-retentive cutting, favoring helical blade innovations.
- Battery-electric tractor convergence:Integration with autonomous electric platforms creates whitespace for intelligent cutting height control and variable-rate operation.
Industry Challenges
- Precision cutting engineering scarcity:Manufacturers struggle to recruit blade geometry specialists capable of optimizing helical angles for minimal leaf loss.
- CE recertification timelines:Revised guarding and noise standards require 18-24 month validation cycles, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Drum Mowers Market |
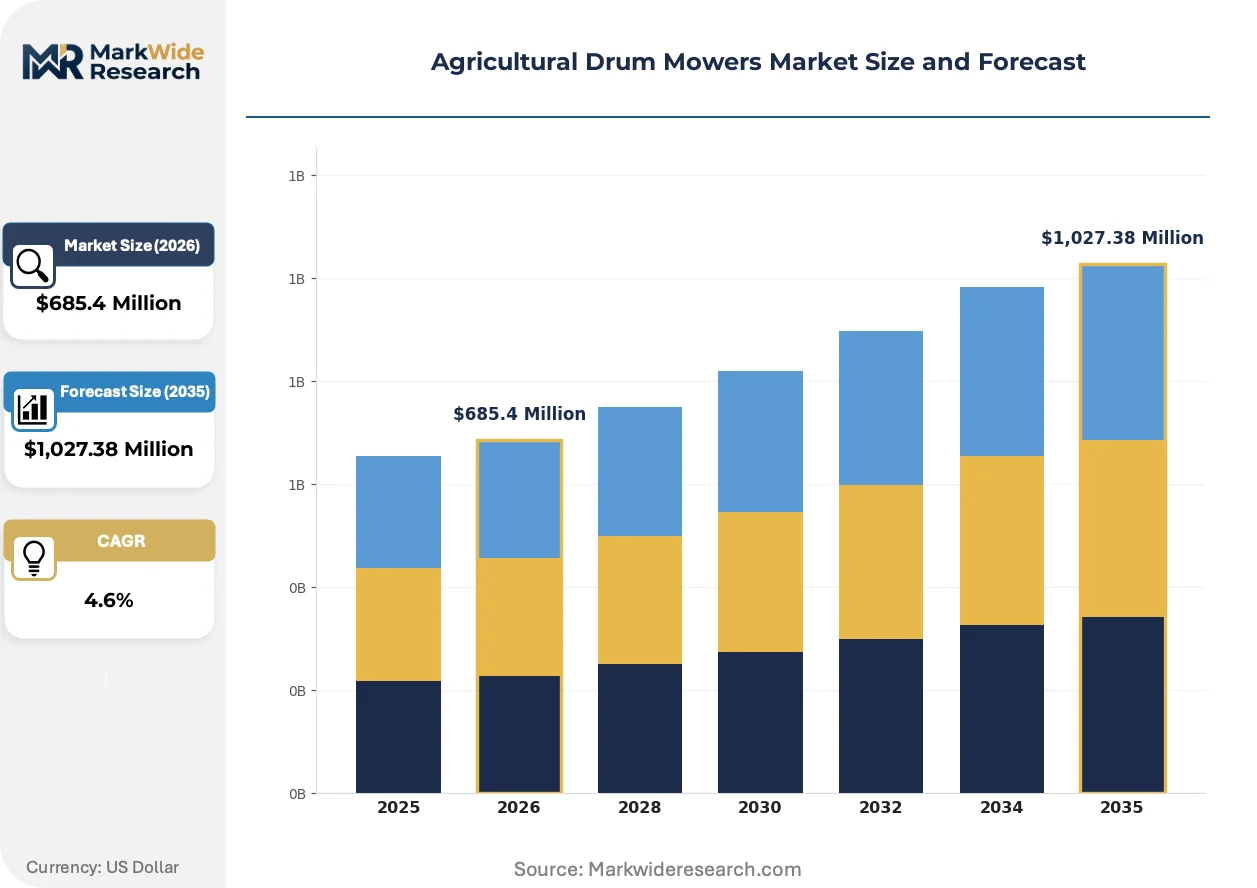
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,027.38 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Mowers, Heavy-Duty Mowers, Compact Mowers, Specialty Mowers Cutter Width: Small Width, Medium Width, Large Width, Extra Large Width Drive Type: Mechanical Drive, Hydraulic Drive, Electric Drive, PTO-Driven End User: Commercial Farmers, Agricultural Contractors, Municipalities, Others |
| Companies Covered | Krone, John Deere, New Holland Agriculture, AGCO Corp., Bernard KRONE Holding SE and Co. KG, CNH Industrial NV, KUHN SAS, Weifang Luyuan Import and Export Trading Co., Ltd, Fella-Werke, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Drum Mowers Market Trends and Innovations
Electric drive architectures are compressing the competitive window for incumbent hydraulic specialists while reshaping how power density and thermal management determine product positioning across European and North American haymaking corridors.
Permanent magnet synchronous motors are overtaking hydraulic drives in heavy-duty drum mower applications. German commercial hay producers are specifying electric configurations for tractors above 150 horsepower. This transition is overtaking traditional power transmission architectures and forcing hydraulic component suppliers into defensive repositioning.
The F-Gas Regulation is phasing out refrigerant-dependent manufacturing processes for hydraulic systems. European OEMs must redesign drive trains around sealed electric motor housings. Heavy-duty mower lines face the steepest compliance costs, pushing development budgets toward thermal management and ingress protection engineering.
Modular attachment procurement is displacing standalone equipment purchases among agricultural contractors. German custom operators now specify quick-coupler compatibility across tractor fleets, favoring standardized PTO interfaces. This pattern concentrates in the country's northern grassland belt where seasonal labor constraints favor equipment interchangeability.
Agricultural Drum Mowers Market Segmentation
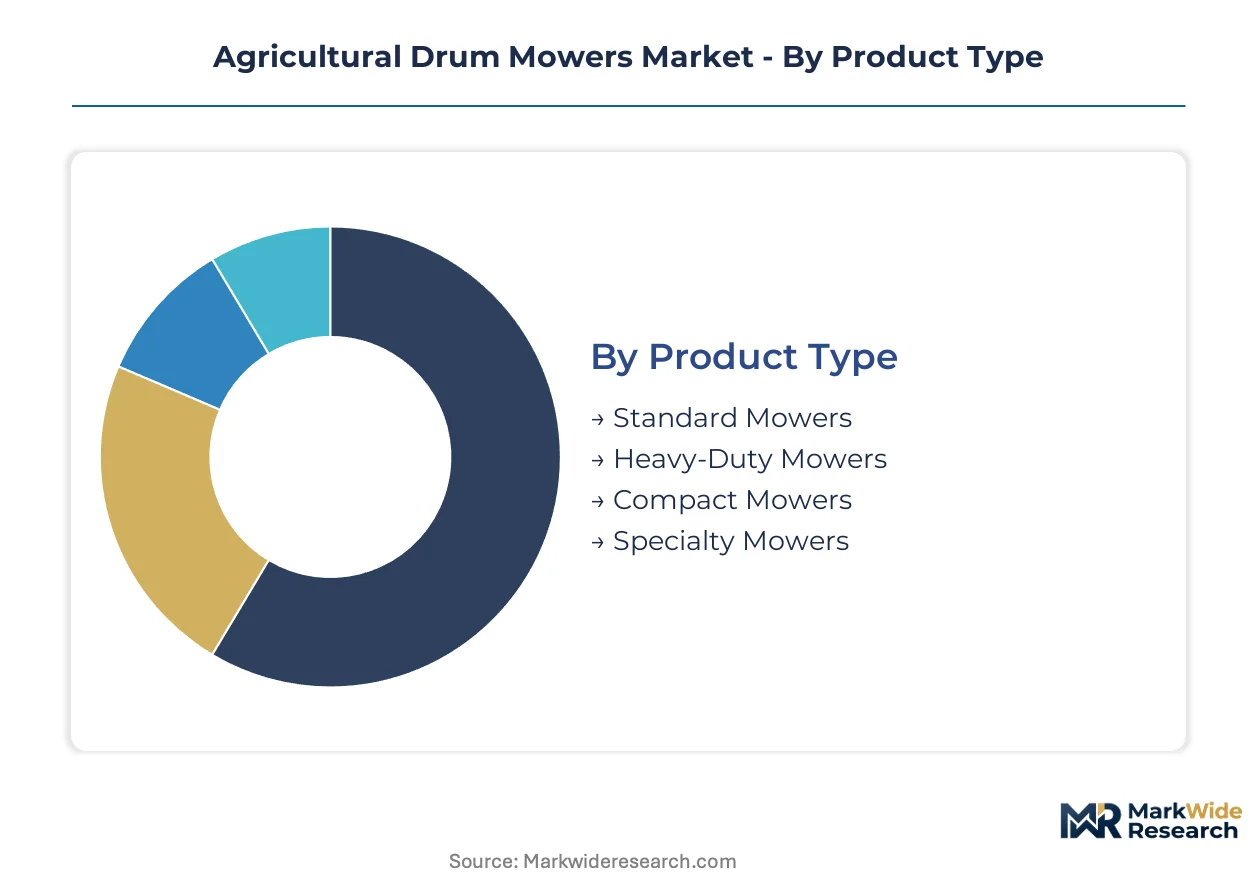
Segmentation in drum mowers reveals how buyer priorities diverge between throughput maximization and operational flexibility. Equipment specifications map directly to farm scale, terrain constraints, and power availability across haymaking corridors.
Product Type:
Buyers weigh durability premiums against replacement cycle economics when selecting mower construction class.
- Heavy-Duty Mowers:Reinforced drum housings and hardened blade carriers withstand continuous operation on large-scale dairy and beef operations. Demand concentrates in Germany's northern grassland belt where seasonal intensity justifies capital investment in extended service intervals.
- Standard Mowers:Balanced specifications serve mid-size commercial hay producers seeking reliability without premium pricing. European replacement cycles favor this tier as CE guarding mandates accelerate equipment turnover.
- Compact Mowers:Reduced cutting widths match sub-100 horsepower tractors common on fragmented European holdings.
- Specialty Mowers:Configurations for steep terrain or organic certification requirements address niche operational constraints.
Volume sits with Heavy-Duty Mowers; growth tilts toward Compact Mowers as land fragmentation persists.
Cutter Width:
Throughput requirements and tractor power availability determine width selection across contractor fleets.
- Large Width:Cutting spans exceeding 3 meters maximize acres per hour for custom operators serving consolidated dairy operations. Netherlands and Denmark contractors specify these configurations to capture silage quality premiums through rapid field clearance.
- Medium Width:Versatile dimensions accommodate mixed fleet operations where tractor horsepower varies seasonally. German agricultural contractors favor this flexibility for equipment interchangeability across client properties.
- Small Width:Narrow cutting paths navigate confined pastures and irregular field boundaries.
- Extra Large Width:Maximum throughput configurations require 200+ horsepower tractors available only on elite commercial operations.
Medium Width dominates installed base; Large Width is gaining share fastest among professional contractors.
Drive Type:
Power transmission architecture now hinges on regulatory compliance timelines rather than purely mechanical preference.
- PTO-Driven:Mechanical power take-off interfaces at 540–1000 RPM sustain the largest installed base across European haymaking regions. Legacy compatibility and repair accessibility preserve demand among cost-sensitive commercial farmers.
- Electric Drive:Permanent magnet synchronous motors eliminate hydraulic refrigerant dependencies under F-Gas Regulation. German OEMs prioritize this architecture for tractors above 150 horsepower as thermal management engineering matures.
- Hydraulic Drive:Precision speed control for hilly terrain faces phase-out pressure from refrigerant restrictions.
- Mechanical Drive:Direct gear systems persist in entry-tier equipment for emerging market export.
PTO-Driven retains volume leadership; Electric Drive shows the steepest expansion trajectory as compliance deadlines approach.
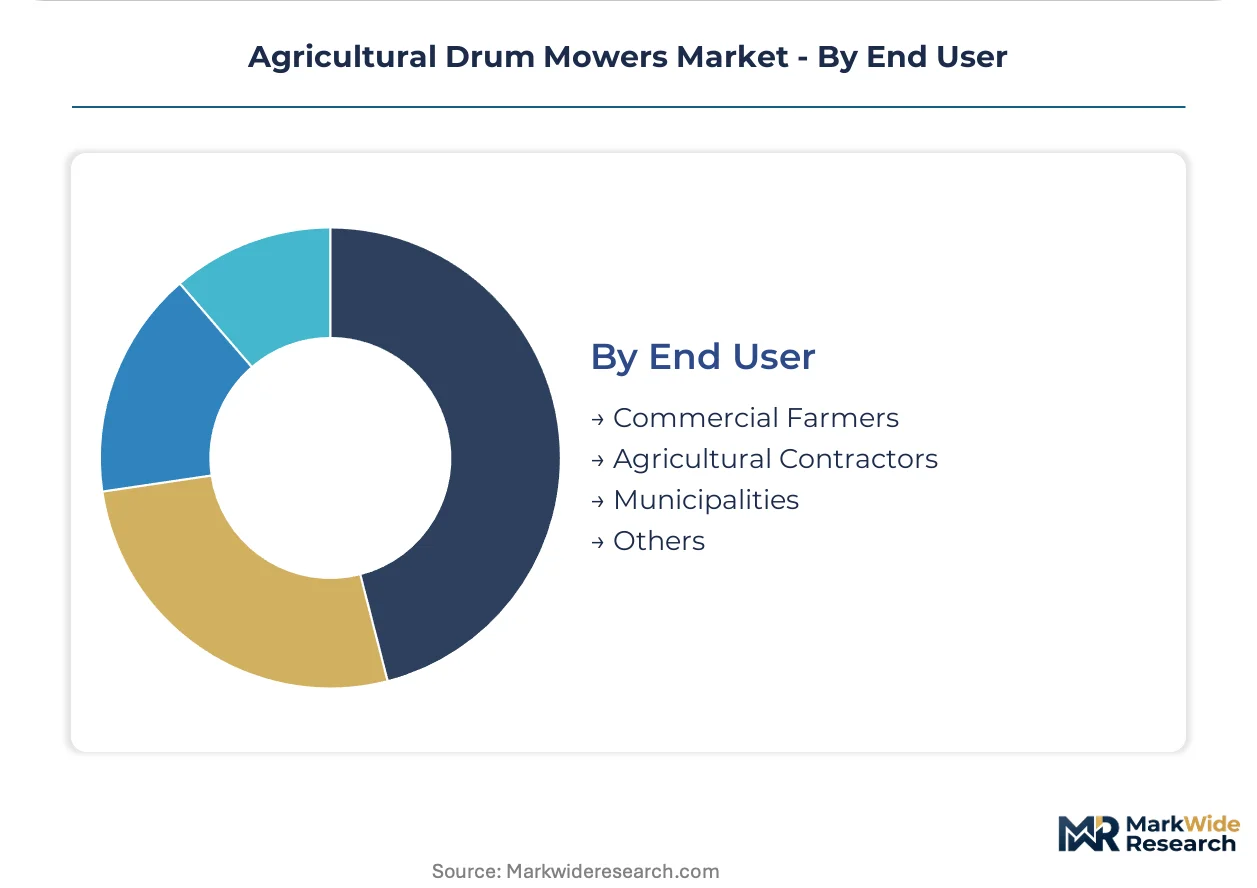
End User:
Ownership economics versus operational outsourcing reshape procurement patterns across fragmented landholdings.
- Agricultural Contractors:Custom haymaking services consolidate equipment purchasing power across multiple dairy operations. Germany's grassland corridor concentrates this demand as seasonal labor constraints favor professional operators.
- Commercial Farmers:Owner-operated dairy and beef enterprises specify equipment matched to herd size and forage requirements. Direct ownership persists where operational control outweighs contractor availability.
- Municipalities:Roadside verge maintenance and park management generate institutional demand for robust guarding and safety certification.
- Others:Research stations and demonstration farms support limited specialty equipment procurement.
Commercial Farmers anchor current volume; Agricultural Contractors are expanding most quickly as service consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lower Saxony's agricultural machinery cluster concentrates drum mower R&D investment through proximity to the F-Gas compliance deadline. Regional subsidy pools in the Netherlands and Denmark accelerate electric drive adoption among dairy cooperatives. India's PLI scheme for farm mechanization creates import pathways for European OEMs seeking volume expansion.
Germany
Commercial hay contractors across the northern grassland belt specify heavy-duty PTO-driven units for seasonal intensity. The F-Gas Regulation forces hydraulic drive phase-out, compressing electric motor integration timelines. Claas and Krone anchor production in Lower Saxony and Baden-Württemberg, shipping configured units across the EU corridor.
Netherlands
Dairy cooperatives pay contract differentials for leaf-retentive cutting quality in silage operations. CE marking mandates accelerate replacement cycles as retrofit costs exceed new equipment premiums. Wageningen University's agrotech corridor influences precision blade geometry specifications for regional OEMs.
India
State procurement programs under the PLI scheme concentrate demand in Punjab and Haryana mechanization zones. BIS certification requirements filter import eligibility for European and Chinese manufacturers. Maharashtra's dairy belt expands custom haymaking services, absorbing fragmented landholdings.
United States
EPA emissions thresholds and OSHA workplace noise standards shape export configurations for European manufacturers. Great Plains commercial beef operations sustain demand for heavy-duty durability specifications. Nebraska and Kansas grassland corridors concentrate large-scale dairy replacement cycles.
Denmark
Organic certification requirements drive specialty mower configurations for premium feed markets. The country's national agricultural regulator enforces strict stubble height standards for environmental compliance. Jutland Peninsula dairy cooperatives consolidate equipment purchasing through contractor networks.
Agricultural Drum Mowers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered equipment categories. Market structure shows moderate consolidation around premium heavy-duty segments while standard and compact tiers fragment across regional fabricators. Three archetypes dominate: European heritage manufacturers with backward integration into precision components, diversified agricultural conglomerates leveraging distribution scale, and emerging Asian fabricators competing on cost-positioning. Competitive moves center on electric drive architecture licensing and modular attachment standardization partnerships.
Within the European heritage tier, Krone and KUHN SAS exemplify specialized engineering focus, while John Deere anchors diversified agricultural equipment scale. Weifang Luyuan Import and Export Trading Co., Ltd represents cost-competitive Asian fabrication capacity serving emerging market import demand. These three occupy distinct competitive positions without direct segment overlap.
| Leading Market Players |
|---|
| Krone |
| John Deere |
| New Holland Agriculture |
| AGCO Corp. |
| Bernard KRONE Holding SE and Co. KG |
| CNH Industrial NV |
| KUHN SAS |
| Weifang Luyuan Import and Export Trading Co., Ltd |
| Fella-Werke |
| Others |
Pricing and Supply Chain Analysis
Modular attachment procurement across Germany's agricultural contractor fleets is compressing order lead times and forcing manufacturers to hold finished-goods inventory closer to the northern grassland belt, eroding margin buffers on standard-tier equipment. European F-Gas compliance deadlines are simultaneously redirecting engineering budgets toward electric drive architectures, reshaping how supply capacity gets allocated across product tiers.
Pricing Analysis
Short lead-time premiums now separate urgent replacement orders from scheduled fleet renewals in the German grassland corridor. Three-tier pricing structure across premium heavy-duty, standard mid-range, and compact economy levels tracks CE certification status and thermal management engineering investment. Price differentiation centers on F-Gas compliance readiness and electric motor integration depth. Agricultural contractors show highest price sensitivity where seasonal cash flow constraints collide with mandatory guarding retrofits. Steel alloy volatility in drum housing materials is compressing margins for mid-tier producers without captive metallurgy supply.
Supply Chain Analysis
Dual-sourcing mandates from major German OEMs now require qualified suppliers for both hydraulic and electric drive systems during the transition window. Manufacturing concentrates in Germany, Italy, and Poland for precision cutting components, with final assembly clustering in Lower Saxony and Baden-Württemberg. Raw material dependencies span hardened steel alloys for blade carriers, permanent magnet materials for synchronous motors, and specialized sealing compounds for ingress protection. Single-source vulnerability concentrates in German industrial regions for precision drive system engineering. Distribution runs through agricultural machinery dealer networks with seasonal pre-positioning at regional hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's F-Gas Regulation has erected a cost-of-compliance moat around electric drive engineering capabilities, filtering new entrants to those with capital reserves for 18-24 month CE recertification cycles and thermal management R&D.
For Market Incumbents: Anchor defensive positioning through backward integration into precision cutting components and permanent magnet motor supply chains. Accelerate capacity addition in Lower Saxony to capture contractor fleet standardization around quick-coupler compatibility. The priority lever sits with locking in modular attachment partnerships before electric architecture licensing windows close. For New Entrants and Emerging Players: Begin with India's PLI scheme compliance pathway and BIS certification investment to access state procurement programs in Punjab and Haryana. The most penetrable white space concentrates in compact mower configurations for sub-100 horsepower tractors on fragmented European holdings. Target agricultural contractor networks in Maharashtra's emerging dairy belt with lease-to-own financing structures. For Investors and Strategic Acquirers: The window for entry favors pure-play electric drive specialists with validated thermal management IP and existing CE marking pathways. Long-term viability hinges on integration timing with battery-electric tractor platform convergence. Watch for inflection signals in helical blade geometry patent filings from Wageningen-corridor engineering clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Drive Architecture Licensing | Permanent magnet motor IP partnerships with German tractor OEMs above 150 horsepower secure platform integration slots. |
| CE Marking Fast-Track Investment | Pre-validated guarding and noise compliance compresses 18-24 month certification cycles ahead of F-Gas deadlines. |
| Modular Attachment Standardization | Quick-coupler compatibility partnerships with Krone and KUHN anchor contractor fleet interchangeability requirements. |
| India PLI Scheme Compliance | BIS certification unlocks state procurement pools and mechanization subsidies in Punjab and Haryana zones. |
| Helical Blade Geometry R&D | Leaf-retentive cutting innovations capture silage quality premiums from Netherlands and Denmark dairy cooperatives. |
Research Methodology
Trade association filings, customs export records, and EU machinery registration databases formed the secondary backbone for volume estimation. Primary interviews with agricultural contractors in Germany's northern grassland belt, precision cutting component procurement leads at Claas and Krone, aftermarket service heads at dealer networks, and thermal management engineering directors supplemented secondary validation. Bottom-up equipment shipment tallies triangulated against top-down haymaking acreage and replacement cycle modeling.
Historical trendline analysis across PTO speed standardization shifts, hydraulic-to-electric drive transitions, and CE marking mandate impacts anchored the projection framework. Segmentation dimensions spanned product construction class, cutter width tier, power transmission architecture, and end-user ownership model across the modeling period. CAGR derivation incorporated tractor horsepower distribution trends, F-Gas compliance phase-in schedules, and regional subsidy pool allocations. Silage quality premium contract differentials and leaf-loss engineering specifications informed demand elasticity assumptions.
Underlying measurement precision varies by segment; electric drive adoption rates and contractor fleet consolidation carry tighter precision than emerging market import penetration. Forecasts reflect documented assumptions around regulatory enforcement timing and commodity alloy price stabilization. Deviation in F-Gas refrigerant phase-out acceleration or battery-electric tractor platform deployment would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
South America Agricultural Machinery Market
Agricultural Machinery
Germany Agricultural Tractor Machinery Market
Agricultural Machinery
Agricultural Electric Tractor Market
Agricultural Machinery
Rotary Tiller Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
Europe Utility Tractor Market
Agricultural Machinery
Japan Agricultural Machinery Market
Agricultural Machinery
Brazil Tractors Market
Agricultural Machinery
Canada Robotic Fruit Picker Market
Agricultural Machinery
Europe Agricultural Tractors Market
Agricultural Machinery
Asia-Pacific Agricultural Machinery Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market
Agricultural Machinery
Garden and Orchard Tractors Market
Agricultural Machinery
Orchard Type Tractors Market
Agricultural Machinery
Orchard Tractor Market