
 Sports Software Market | 2026-2036
Sports Software Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Software Market Outlook
Multi-source vendor strategies are rebalancing procurement patterns across collegiate athletic departments and professional franchises. Stack Sports leverages its vertical integration into league administration tools to sustain recurring revenue depth. Hudl anchors the performance analytics segment with video-centric coaching workflows. SAP SE competes at the enterprise tier through its athlete management platform integrations.
Sports software comprises digital platforms that process biometric data, schedule competitions, manage registrations, and deliver real-time statistics through cloud-native or installed architectures. These systems operate on API-driven data exchange protocols, processing telemetry from wearables and venue sensors to generate actionable intelligence for coaches, administrators, and broadcasters. Management Software occupies the largest revenue pool by automating league operations and membership billing. Cloud-Based deployment represents the fastest-expanding configuration as athletic organizations abandon server maintenance burdens. Training Applications concentrate margin in specialized biomechanics and injury-prevention modules where subscription pricing commands premium tiers.
FDA oversight applies where software functions as a medical device for athlete health monitoring, while NCAA governance frameworks in the United States mandate compliance standards for student-athlete data privacy. The EU AI Act imposes algorithmic transparency requirements on automated recruitment and scouting tools deployed across European leagues. Stakeholders must evaluate how emerging interoperability standards between wearable hardware and analytics platforms will reshape vendor lock-in risks and data portability obligations.
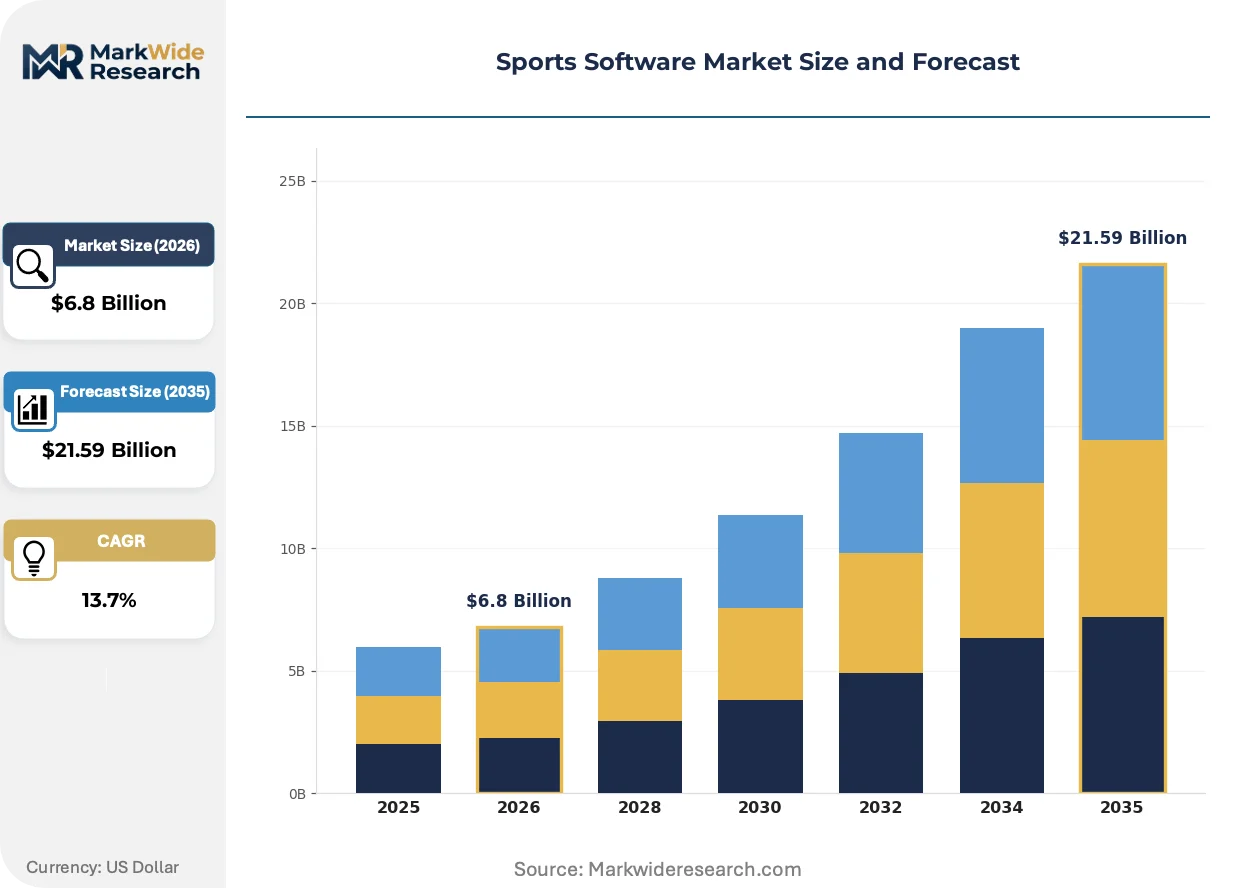
Market Dynamics
Cloud-native architectures are displacing legacy on-premise installations across professional and collegiate athletic organizations, compressing deployment timelines from months to days while shifting capital expenditure to operational models.
Growth Catalysts
- NCAA Data Privacy Mandates:United States collegiate athletic departments accelerate platform procurement to comply with student-athlete information governance frameworks. Procurement volumes concentrate in Division I institutions.
- Biomechanical Wearables:Real-time telemetry from athlete-worn sensors generates demand for analytics platforms processing force, acceleration, and kinematic data streams. Professional soccer and basketball franchises lead adoption curves.
- League Digitization Programs:Germany's Bundesliga and Australia's AFL deploy centralized competition management infrastructure, creating procurement cascades through affiliated clubs and academies.
Market Restraints
- API Fragmentation:Proprietary data exchange protocols between wearable hardware and analytics platforms lock customers into single-vendor ecosystems. Interoperability gaps inflate total cost of ownership.
- FDA Device Classification:Health monitoring functions triggering medical device oversight impose validation timelines and quality system requirements that extend product development cycles.
- Specialized Talent Scarcity:Sports data science and biomechanics engineering expertise concentrates in technology hubs, inflating compensation costs for platform vendors and athletic organizations.
Strategic Opportunities
- EU AI Act Compliance Services:Automated scouting and recruitment tools deployed across European leagues require algorithmic transparency documentation. Vendors capturing compliance workflow revenue expand addressable market.
- India Collegiate Athletics:University sports federation digitization creates greenfield demand for competition scheduling and athlete management platforms. Infrastructure investment lags create first-mover windows.
- Edge Computing Convergence:Venue-side processing of video and sensor data reduces latency for real-time coaching decisions. Integration partnerships with broadcast infrastructure vendors unlock new revenue pools.
Industry Challenges
- Legacy System Migration:Decades-old installed databases in professional franchises resist cloud migration due to custom integrations with ticketing and merchandise systems. Transition projects stall at data mapping phases.
- Cross-Border Data Sovereignty:European clubs employing athletes from multiple jurisdictions face conflicting health data residency requirements. Platform architectures must segment storage by nationality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Software Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analytics Tools, Management Software, Training Applications, Fan Engagement Platforms End User: Professional Teams, College Athletics, Sports Leagues, Fitness Centers Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Mobile Applications Application: Performance Tracking, Recruitment, Event Management, Ticketing Solutions |
| Companies Covered | SportsEngine Inc., TeamSnap Inc., Stack Sports, Active Network LLC, Jonas Club Software, LeagueApps Inc., SAP SE, Hudl, Omnify Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Software Market Strategic Shifts
Artificial intelligence inference engines are embedding directly into coaching workflows, compressing the interval between data capture and tactical adjustment while raising new questions about algorithmic accountability in competitive decisions.
Computer vision platforms are consolidating previously separate video analysis, player tracking, and tactical diagramming functions into unified coaching interfaces. NCAA Division I football and basketball programs deploy these systems across practice facilities and competition venues. The technology is consolidating vendor relationships by replacing point solutions with integrated suites.
The EU AI Act imposes documentation and human oversight requirements on automated player evaluation systems used for contract negotiations and draft selections. European football clubs and scouting agencies must maintain algorithmic audit trails. German Bundesliga and English Premier League operations teams are restructuring procurement specifications to mandate compliance certification.
Subscription pricing models displace perpetual licenses across mid-market collegiate athletic departments. Annual recurring revenue structures align vendor incentives with customer success metrics. This shift is most visible in United States Division II and III institutions where capital budgets remain constrained.
Sports Software Market Segmentation
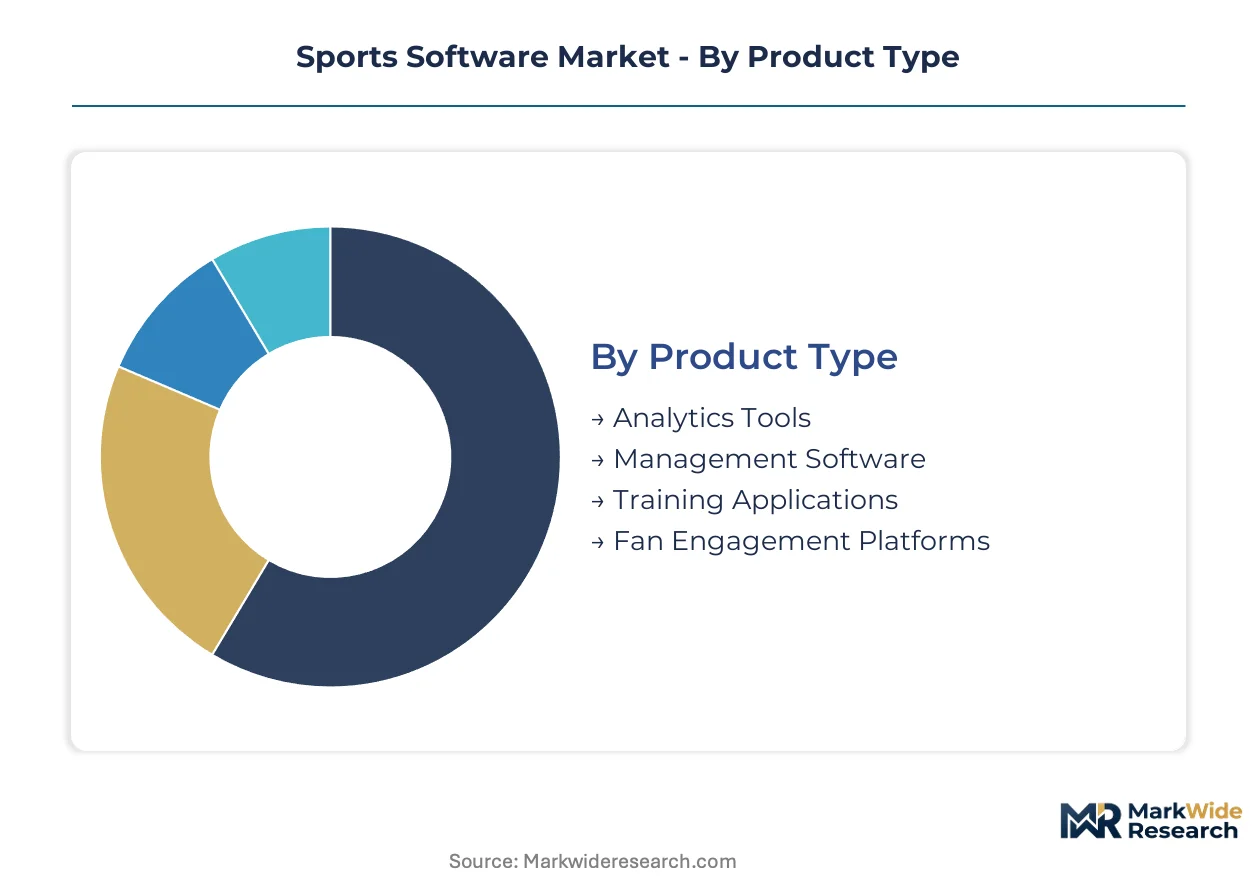
Sports software vendors architect product portfolios around distinct operational workflows, with integration depth determining whether platforms function as standalone tools or embedded components within broader athletic infrastructure. Procurement decisions increasingly favor segments that interoperate across wearable hardware, league management systems, and broadcast distribution networks.
Product Type:
Standalone analytics tools operate at the application layer with API connections to external data sources, while embedded management software sits deeper in organizational infrastructure with direct database integrations.
- Analytics Tools:These platforms process biometric telemetry, video feeds, and competition statistics through machine learning pipelines to generate tactical recommendations. Professional soccer franchises in Germany and basketball organizations in Spain concentrate procurement around real-time player tracking dashboards that integrate with wearable force sensors.
- Management Software:League administration platforms automate membership billing, competition scheduling, and regulatory compliance documentation. Australia's AFL and Germany's Bundesliga have deployed centralized systems that cascade procurement requirements through affiliated clubs and youth academies.
- Training Applications:Biomechanics and injury-prevention modules command premium subscription tiers through specialized motion-capture integrations.
- Fan Engagement Platforms:Mobile-first solutions deliver real-time statistics, augmented reality experiences, and loyalty program management to spectators.
Management Software leads volumes today; Analytics Tools is gaining share fastest.
End User:
Cost tier stratification separates enterprise deployments with dedicated implementation teams from self-service subscriptions targeting budget-constrained athletic departments.
- Professional Teams:These organizations operate multi-sport technology stacks with dedicated data science staff and custom integration requirements. NBA and English Premier League franchises lead spending on computer-vision coaching platforms that consolidate video analysis, player tracking, and tactical diagramming into unified interfaces.
- College Athletics:NCAA Division I institutions drive procurement volume through compliance mandates governing student-athlete data privacy. Division II and III programs increasingly adopt subscription models as capital budget constraints displace perpetual licenses.
- Sports Leagues:Governing bodies procure centralized infrastructure that standardizes competition formats across member organizations.
- Fitness Centers:Commercial gym operators deploy member management and class scheduling platforms with limited customization requirements.
Professional Teams lead volumes today; College Athletics is expanding most quickly.
Deployment:
Application context determines whether organizations prioritize data sovereignty through on-premise installations or operational flexibility through cloud-native architectures.
- On-Premise:Legacy server installations persist in professional franchises with decades-old custom integrations to ticketing and merchandise systems. Migration projects frequently stall at data mapping phases due to proprietary database schemas.
- Cloud-Based:Cloud-native architectures compress deployment timelines from months to days while shifting capital expenditure to operational models. North American and Western European athletic organizations have accelerated displacement of legacy installations.
- Hybrid Solutions:Split configurations maintain sensitive health data on-premise while pushing analytics workloads to cloud infrastructure.
- Mobile Applications:Native iOS and Android deployments support field-side coaching decisions and spectator engagement with reduced latency requirements.
On-Premise leads volumes today; Cloud-Based is climbing the fastest.
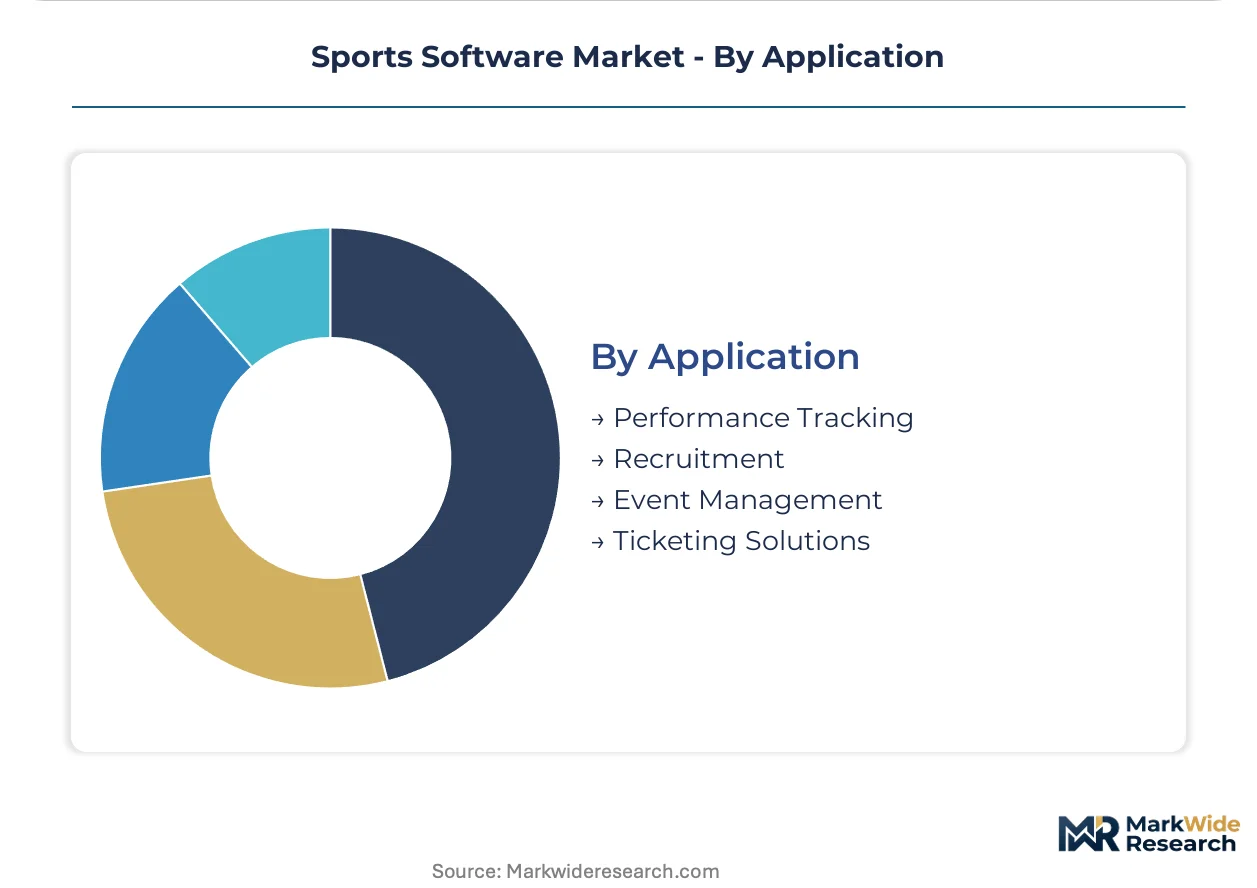
Application:
Customer maturity separates established use cases with standardized procurement specifications from emerging applications requiring vendor education and pilot programs.
- Performance Tracking:Real-time telemetry processing from athlete-worn sensors generates demand for platforms analyzing force, acceleration, and kinematic data streams. Professional soccer and basketball franchises lead adoption curves with venue-side edge computing deployments.
- Recruitment:Automated scouting tools face EU AI Act compliance requirements mandating algorithmic transparency documentation and human oversight protocols for contract negotiation and draft selection decisions.
- Event Management:Competition logistics platforms coordinate venue scheduling, official assignments, and results distribution across tournament formats.
- Ticketing Solutions:Dynamic pricing engines and access control systems integrate with broader fan engagement architectures.
Performance Tracking leads volumes today; Recruitment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between jurisdictions are redirecting sports software deployment strategies. Organizations prioritize markets where data governance frameworks align with operational architectures, creating divergent growth trajectories across national boundaries.
United States
NCAA data privacy mandates and Division I digitization programs accelerate platform procurement across collegiate athletic departments. FDA oversight applies where health monitoring functions trigger medical device classification. Austin and Boston technology clusters concentrate sports data science talent pools that vendors recruit aggressively.
Germany
Bundesliga league digitization programs cascade procurement requirements through affiliated clubs and youth academies. EU AI Act algorithmic transparency requirements reshape automated scouting tool specifications. Munich and Cologne host concentrated vendor implementation teams serving Central European football operations.
Australia
AFL centralized competition management infrastructure creates standardization mandates across member organizations and regional leagues. The country's national data protection framework governs athlete biometric data residency. Melbourne and Sydney anchor domestic software development capabilities for Asia-Pacific market expansion.
United Kingdom
English Premier League operations teams restructure procurement specifications to mandate EU AI Act compliance certification for player evaluation systems. GDPR health data segmentation requirements complicate cross-border athlete monitoring. London's sports technology venture cluster attracts North American vendor regional headquarters.
India
University sports federation digitization creates greenfield demand for competition scheduling and athlete management platforms. The country's national data protection authority establishes emerging compliance timelines for student-athlete information. Bangalore and Hyderabad technology corridors concentrate software engineering talent for vendor development centers.
Sports Software Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized biomechanics and injury-prevention modules. The vendor base stratifies across enterprise platforms with dedicated implementation teams and self-service subscriptions targeting budget-constrained athletic departments. Three archetypes dominate: vertical integrators controlling league administration toolchains, video-centric performance analytics specialists, and enterprise software conglomerates with athlete management modules. Competitive moves concentrate on API interoperability partnerships and cloud-native architecture migrations that compress deployment timelines.
Among North American platform vendors, Stack Sports exemplifies vertical integration into league administration infrastructure, while Hudl occupies a position within video-centric coaching workflows. SAP SE represents the enterprise software archetype through athlete management platform integrations. These three anchors illustrate how procurement patterns rebalance across multi-source vendor strategies in collegiate and professional athletic organizations.
| Leading Market Players |
|---|
| SportsEngine Inc. |
| TeamSnap Inc. |
| Stack Sports |
| Active Network LLC |
| Jonas Club Software |
| LeagueApps Inc. |
| SAP SE |
| Hudl |
| Omnify Inc. |
| Others |
Value Chain & Pricing Dynamics
Cloud-native architecture migrations are compressing deployment economics while concentrating vendor bargaining power among hyperscaler infrastructure providers. This dual shift simultaneously reduces customer capital burdens and reshapes margin distribution across software delivery chains.
Pricing Analysis
Direct-to-athletic-organization subscription sales bypass traditional distributor markups entirely. SaaS-tiered pricing stratifies across premium analytics suites, standard management modules, and economy scheduling tools. Cost compression in the economy tier intensifies because open-source alternatives erode baseline functionality value. NCAA Division II and III athletic departments exhibit highest price sensitivity; English Premier League operations teams show least.
Supply Chain Analysis
Refurbishment flows for wearable hardware sensors create secondary component markets that moderate raw material exposure. Software development concentrates in the United States, Germany, and India; cloud infrastructure draws from hyperscaler data centers across Ireland, Singapore, and Virginia. Dependencies include GPU compute capacity, biometric sensor arrays, and API middleware licensing. Single-source vulnerability runs through NVIDIA's AI training chip allocation. Distribution runs through direct vendor sales teams and strategic systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sports software functions as a stable compounder anchored by recurring subscription revenue and league-mandated procurement cycles that institutionalize replacement demand.
For Market Incumbents: Lock in ecosystem stickiness through exclusive API partnerships with wearable hardware manufacturers. Deepen backward integration into league administration toolchains to capture regulatory-mandated procurement flows. The EU AI Act compliance certification requirement represents a defensive moat against unqualified entrants. Prioritize R&D investment in edge computing architectures that reduce latency for real-time coaching decisions. For New Entrants and Emerging Players: Self-service onboarding portals targeting India's university sports federation digitization programs offer lowest competitive density. White-space concentration sits in biomechanics injury-prevention modules where specialized motion-capture integrations command premium pricing. A direct-to-department SaaS model with freemium tier conversion minimizes sales friction against established vendor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among vertical-integrated mid-cap specialists with captive league administration relationships. The five-to-ten year viability window favors platforms with demonstrated NCAA or Bundesliga deployment references. Acquisition target archetype: computer-vision coaching platforms consolidating previously separate video analysis functions. Monitor FDA medical device classification rulings on health monitoring software as inflection indicator for compliance-cost recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidated coaching interfaces displace point solutions across NCAA Division I facilities. |
| Geographic Expansion | India's collegiate athletics digitization creates first-mover windows for scheduling platforms. |
| Strategic Partnership | Edge computing alliances with broadcast infrastructure vendors unlock venue-side processing revenue. |
| Acquisition of Specialist Firm | Biomechanics module targets concentrate engineering talent and premium subscription pricing power. |
| Product Launch | EU AI Act compliance documentation tools address mandated algorithmic transparency requirements. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged CTOs at collegiate athletic departments, platform engineers at video analytics vendors, integration specialists connecting wearable hardware to cloud backends, and league operations directors governing procurement specifications. Secondary validation drew from SEC filings of listed software vendors, NCAA governance documentation, EU regulatory registers, and hyperscaler infrastructure expansion disclosures. Bottom-up deployment counts and top-down revenue estimates were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon to established adoption curves in cloud migration and subscription pricing transitions. The analytical framework modeled deployment model, organization size, vertical sport category, integration complexity, and regional regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs included NCAA compliance mandate timelines and Bundesliga digitization program procurement cascades.
The model assumes a particular technology adoption path; alternative pathways for edge computing convergence would alter the outlook. Forecasts reflect assumptions about sustained cloud infrastructure cost reductions and stable regulatory enforcement intensity. Practitioners should monitor FDA medical device reclassification proceedings and EU AI Act implementation guidance for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Sports Team and Clubs Market
Sports & Fitness Technology
Football Merchandise Market
Sports & Fitness Technology
Global Sports Management Software Market
Sports & Fitness Technology
Asia Pacific Sports Team and Clubs Market
Sports & Fitness Technology
United States Sports Promoter Market
Sports & Fitness Technology
Smart Fitness Trainer Market
Sports & Fitness Technology
Smart Court (Sports) Market
Sports & Fitness Technology
Reflective Sportswear Market
Sports & Fitness Technology
Crossfit Apparel Market
Sports & Fitness Technology
Sports Sponsorship Market
Sports & Fitness Technology
Smart Sports Market
Sports & Fitness Technology
North America Sports Management Software Market
Sports & Fitness Technology
UK Sports Promoters Market
Sports & Fitness Technology
Smart Fitness Device Market
Sports & Fitness Technology
3D Motion Capture Market
Sports & Fitness Technology
Europe Sports Management Software Market