
 Football Merchandise Market | 2026-2036
Football Merchandise Market Size, Share, and Industry Trends Forecast 2026-2036
Football Merchandise Market Analysis
Multi-source licensing is repositioning how clubs and federations allocate manufacturing rights across territories. Nike leverages its exclusive federation partnerships to sustain premium positioning in national team kits. Adidas competes through deep club sponsorships that anchor volume across European leagues. Fanatics controls direct-to-fan digital channels that extend reach beyond traditional retail footprints.
Football merchandise encompasses officially licensed apparel, footwear, accessories, and collectibles manufactured under club, federation, or league trademarks, typically using polyester-blend fabrics with sublimation printing for replica kits and embroidered crests for authentic matchwear. The category serves fan engagement, brand monetization, and team identity reinforcement for professional and amateur football organizations. Apparel generates the dominant revenue pool as replica kits command the highest per-unit prices and renewal frequency tied to seasonal design cycles. Online retailers represent the fastest-growing sales channel as platform infrastructure and mobile checkout optimization reduce friction for impulse purchases. Collectibles attract concentrated demand from dedicated buyer segments willing to pay premiums for limited-edition items.
FIFA licensing standards, EU consumer product safety directives through CE marking requirements, and US Consumer Product Safety Commission guidelines govern material safety, labeling accuracy, and anti-counterfeiting protocols across major supply destinations. These frameworks elevate compliance costs for unauthorized manufacturers while protecting revenue streams for rights holders. Stakeholders must monitor evolving sustainability mandates and digital authenticity verification technologies as regulatory and consumer expectations converge on traceability.
Market Dynamics
On-demand digital printing is compressing production lead times from months to days, forcing traditional batch manufacturers to retool or cede share to agile fulfillment networks serving tournament-driven demand spikes.
Growth Catalysts
- Tournament cycles:FIFA World Cup and continental championships trigger synchronized kit refreshes across national federations, creating predictable revenue windows for licensed manufacturers.
- REACH compliance evolution:EU chemical safety directives on textile dyes and finishes are accelerating substitution toward water-based sublimation inks that reduce environmental liability for European suppliers.
- Mobile commerce infrastructure:Platform-native checkout and social commerce integration are collapsing friction for impulse jersey purchases among younger fan demographics.
Market Restraints
- Polyester price volatility:Crude oil-linked feedstock costs for synthetic fabrics create margin pressure that licensed manufacturers cannot fully pass through due to fixed-price retail contracts.
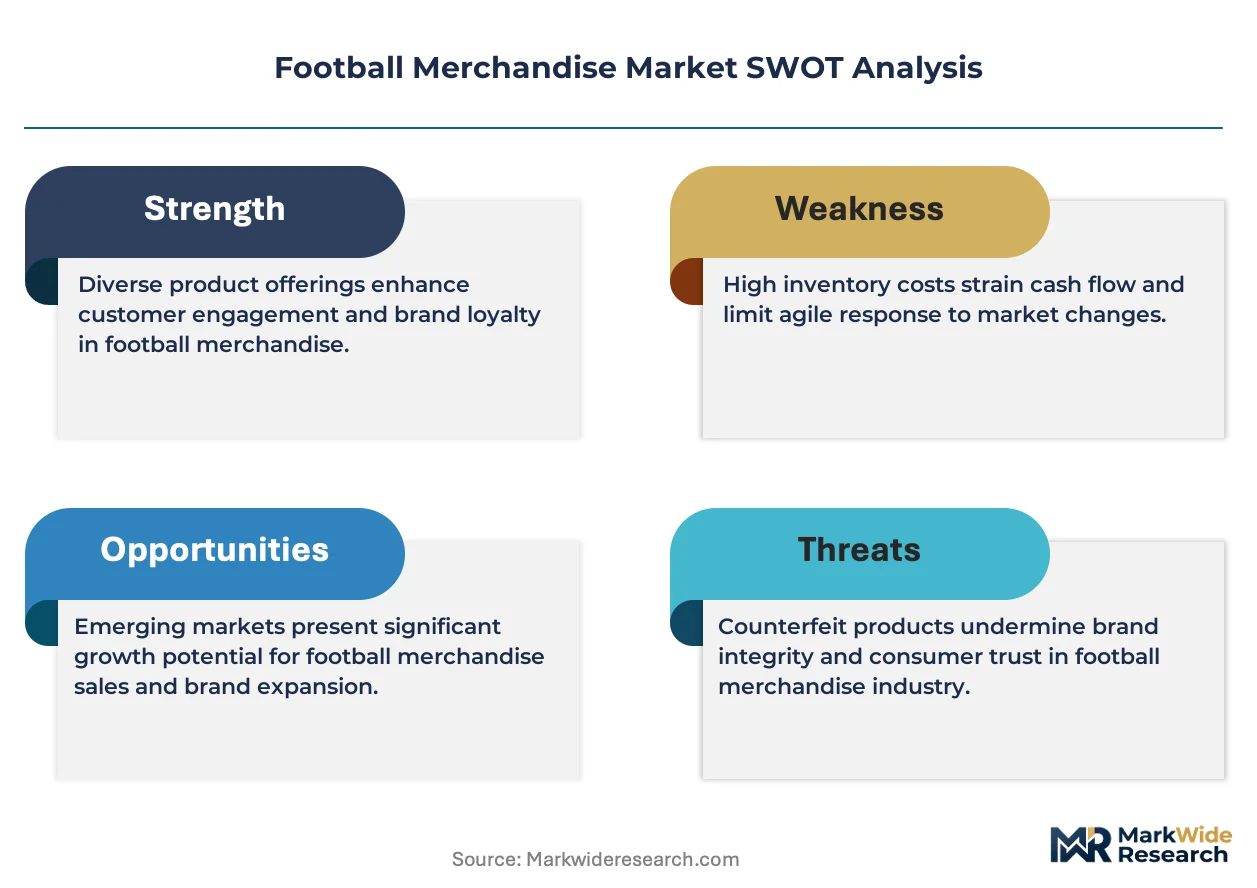
- Counterfeit supply concentration:Unauthorized replica production clusters in specific manufacturing zones undermine pricing discipline and dilute brand equity for rights holders.
- CE marking complexity:Evolving EU safety certification timelines for children's apparel extend product launch windows and increase compliance overhead for seasonal collections.
Strategic Opportunities
- India's emerging fanbase:Underpenetrated club loyalty in tier-two Indian cities offers first-mover positioning as European leagues expand broadcast reach and localized e-commerce platforms mature.
- Blockchain authentication:Convergence of NFC chips and distributed ledger verification creates premium collectible tiers with provable scarcity, capturing value from resale markets.
- Direct-to-fan subscription models:Recurring membership programs bundling exclusive merchandise access with streaming content reduce customer acquisition costs and improve lifetime value metrics.
Industry Challenges
- Digital textile engineering talent:Shortage of technicians proficient in color management for polyester sublimation constrains quality consistency across distributed print networks.
- Licensing agreement fragmentation:Multi-territory rights splits between clubs, leagues, and player image holders create IP clearance bottlenecks for co-branded product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Football Merchandise Market |
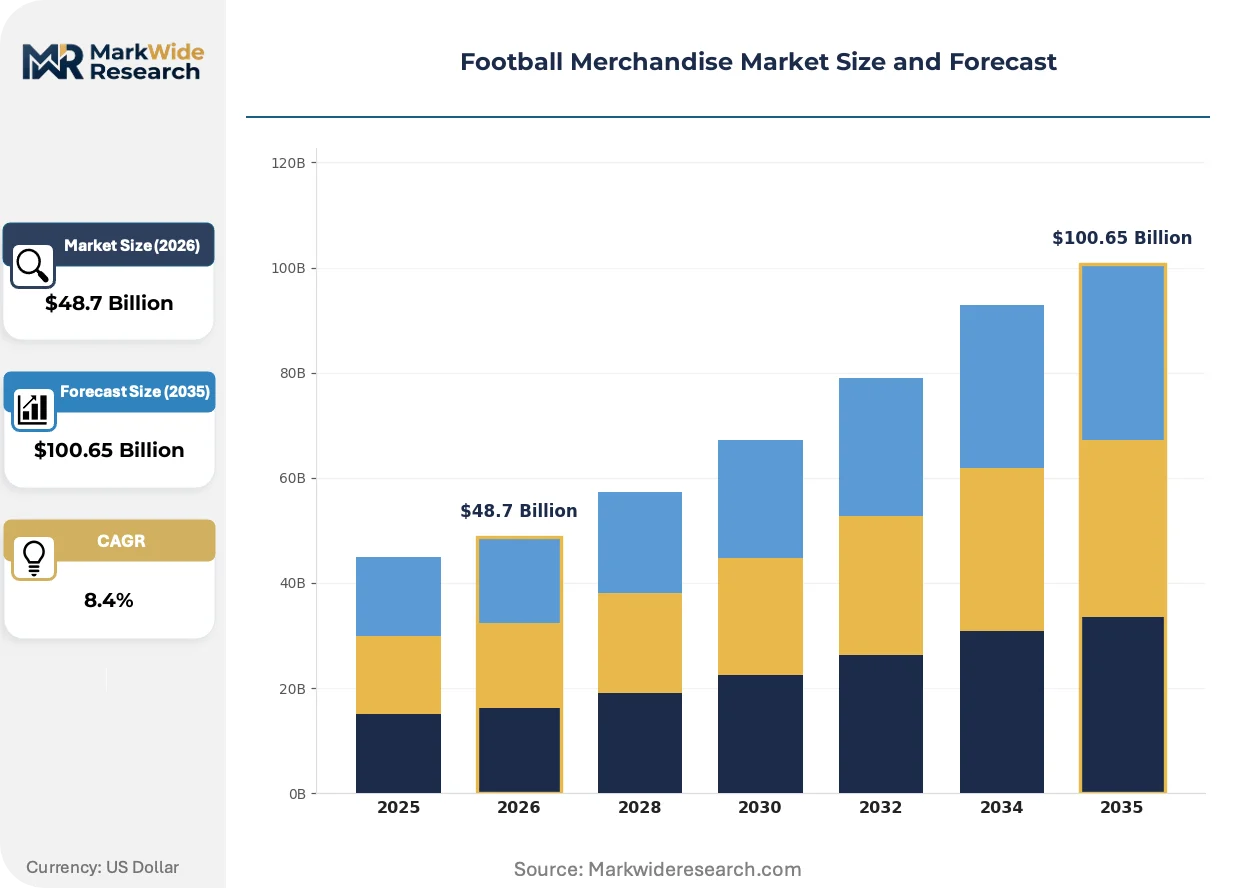
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Footwear, Accessories, Collectibles Sales Channel: Online Retailers, Sports Stores, Supermarkets, Direct Sales Customer Type: Fans, Collectors, Clubs, Corporate Clients Team Category: Professional Teams, Amateur Teams, National Teams, Others |
| Companies Covered | Fanatics, Kappa, Nike, Joma, Umbro, Adidas, New Balance, Under Armour, Puma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Football Merchandise Market Emerging Trajectories
Merchandise production is fragmenting from centralized offshore manufacturing toward distributed micro-factories positioned near demand clusters, enabled by digital workflow tools that collapse design-to-delivery cycles.
AI-driven demand forecasting is unifying historical sales data with real-time social sentiment signals to optimize inventory positioning before tournament kickoffs. Mid-tier clubs lacking dedicated analytics teams are adopting SaaS platforms that aggregate league-wide patterns into actionable production schedules. This capability is compressing working capital requirements and reducing end-of-season clearance volumes for early adopters.
EU Green Deal textile sustainability mandates are phasing in extended producer responsibility schemes that require fiber recycling infrastructure and carbon footprint disclosure. German and French retailers are already demanding batch-level traceability documentation from suppliers. Premium kit manufacturers are responding by integrating recycled ocean plastics into replica jerseys and securing third-party certifications to maintain shelf placement.
Fan purchasing behavior is gravitating toward mobile-native discovery through short-form video platforms that collapse the path from content engagement to transaction. Brazilian and Indonesian supporters increasingly encounter licensed products through influencer-curated storefronts rather than club-operated channels. This shift is fragmenting traffic sources and forcing rights holders to rebuild attribution models around platform-specific conversion funnels.
Football Merchandise Market Segmentation
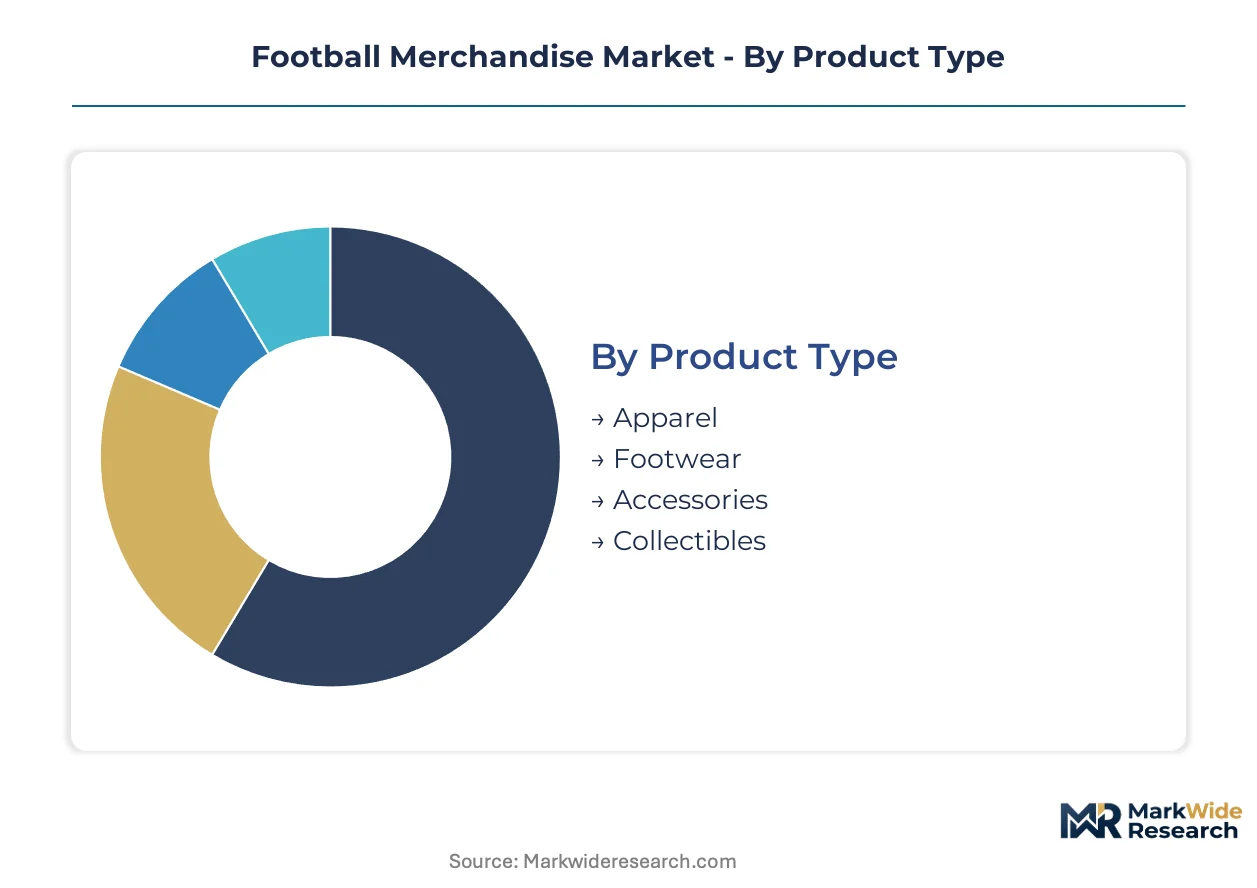
Segmentation in football merchandise reveals distinct production economics and margin profiles across product categories. Each dimension—product type, channel, buyer, and team affiliation—carries unique inventory risk, licensing complexity, and renewal cadence that manufacturers must calibrate separately.
Product Type:
Standalone products dominate shelf space and brand visibility, while embedded accessories ride on core apparel purchases to reach scale.
- Apparel:Replica kits using polyester-blend sublimation printing command the highest per-unit prices and seasonal refresh rates. Demand concentrates in Brazil, Germany, and England where club loyalty drives kit turnover tied to annual design cycles.
- Footwear:Licensed boots and lifestyle sneakers carry federation and club co-branding, with synthetic leather and knit uppers requiring specialized mold investments. Brazil and Germany absorb premium tiers as player endorsement visibility converts to fan purchases.
- Accessories:Scarves, caps, and bags extend brand reach at lower price points.
- Collectibles:Limited-edition items and memorabilia attract dedicated buyer segments willing to pay scarcity premiums.
Apparel leads volumes today; collectibles is gaining share fastest.
Sales Channel:
Channel economics diverge sharply on customer acquisition cost and inventory ownership, with digital-native platforms collapsing traditional retail overhead.
- Online Retailers:Platform-native checkout and mobile-optimized discovery reduce friction for impulse jersey purchases. England and Germany show the steepest digital shift as fan demographics skew younger.
- Sports Stores:Physical specialty retail maintains touch-and-feel advantages for boot fitting and authentic matchwear verification. Brazil retains higher in-store dependency where mall culture sustains foot traffic.
- Supermarkets:Mass retail captures casual fan purchases through seasonal promotional placement.
- Direct Sales:Club-operated channels capture full margin and first-party data on purchase behavior.
Online retailers lead volumes today; direct sales is climbing the fastest.
Customer Type:
Buyer sophistication spans from emotional, event-triggered purchases to institutional procurement with contracted renewal terms.
- Fans:Individual supporters drive volume through kit refreshes and tournament-triggered spending. Brazil and Indonesia show expanding bases as European league broadcast reach extends.
- Collectors:Dedicated buyers seek limited editions and authenticated memorabilia with provenance documentation. Germany hosts concentrated demand for premium collectible tiers.
- Clubs:Professional and amateur organizations purchase training wear and matchday kit in bulk.
- Corporate Clients:Sponsors and hospitality buyers procure co-branded merchandise for activation and gifting programs.
Fans lead volumes today; corporate clients is expanding most quickly.
Team Category:
Team affiliation determines licensing tier, production minimums, and geographic distribution rights that manufacturers must navigate.
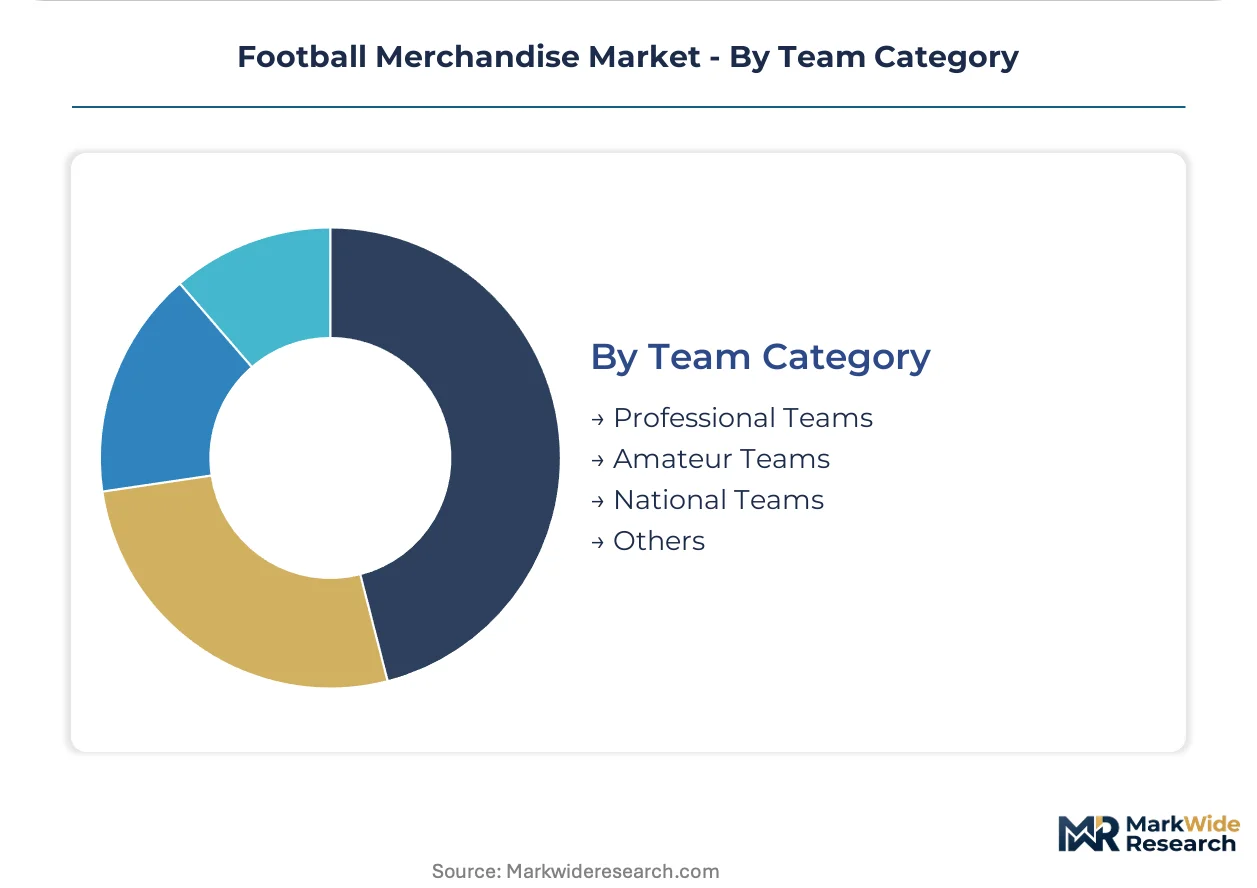
- Professional Teams:Top-tier clubs command exclusive manufacturer partnerships with multi-year guarantees and global distribution rights. England and Spain concentrate the highest-value club licenses.
- National Teams:Federation partnerships synchronize kit refreshes with World Cup and continental championship cycles. Brazil and Germany anchor federation manufacturing agreements with premium positioning.
- Amateur Teams:Grassroots and semi-professional clubs purchase unlicensed or league-generic kit at lower price points.
- Others:Esports teams and entertainment crossovers represent emerging licensing categories.
Professional teams lead volumes today; national teams is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England's Premier League licensing infrastructure generates the highest merchandise velocity per club among football markets worldwide. Tournament cycles and club loyalty systems sustain revenue windows across distinct national ecosystems.
England
Premier League broadcast reach and stadium retail networks drive kit turnover through annual design refreshes. The UK's Consumer Rights Act and Trading Standards enforcement on counterfeit goods protect licensed manufacturer margins. Manchester and London anchor production coordination for club-specific merchandise lines.
Germany
Bundesliga fan ownership models sustain higher per-capita merchandise spend than southern European leagues. REACH compliance on textile dyes accelerates water-based sublimation ink adoption across Bavarian suppliers. Munich and Dortmund concentrate kit manufacturing partnerships with premium-tier positioning.
Brazil
National team tournament cycles trigger synchronized demand spikes exceeding club merchandise volumes during World Cup years. ANVISA textile safety standards govern children's apparel imports from Asian suppliers. São Paulo hosts the largest concentration of federation-licensed production facilities in Latin America.
United States
Growing MLS viewership and European league broadcast deals expand addressable fanbases beyond traditional immigrant demographics. CPSC guidelines on product safety and flammability standards elevate compliance costs for imported replica kits. Los Angeles and New York metro areas dominate e-commerce fulfillment infrastructure for North American distribution.
India
Underpenetrated club loyalty in tier-two cities offers positioning opportunities as European league streaming rights mature. BIS certification requirements for textile imports create entry barriers for unauthorized replica suppliers. Mumbai and Bengaluru lead localized e-commerce platform development for sports merchandise.
Football Merchandise Market Vendor Landscape
Global majors compete with regional champions across licensing tiers and distribution channels. The market structures around exclusive federation partnerships, deep club sponsorships, and direct-to-fan digital platforms. Three archetypes dominate: sportswear conglomerates with multi-territory rights, specialized kit manufacturers with league-specific concentration, and digital-native retailers controlling fan data. Competitive moves center on exclusive licensing renewals and vertical integration into on-demand manufacturing networks.
Among sportswear conglomerates, Nike, Adidas, and Puma exemplify the scale-driven tier where federation and club partnerships anchor volume. Nike represents premium federation positioning through exclusive national team agreements. Adidas occupies the club sponsorship depth vector with multi-league coverage. Puma sits within the challenger archetype, competing through selective high-visibility partnerships rather than blanket coverage.
| Leading Market Players |
|---|
| Fanatics |
| Kappa |
| Nike |
| Joma |
| Umbro |
| Adidas |
| New Balance |
| Under Armour |
| Puma |
| Others |
Supply Flow & Price Mechanics
Polyester feedstock volatility cascades through replica kit pricing tiers as crude oil-linked synthetic fiber costs compress margins for manufacturers locked into fixed-price retail contracts with English and German clubs. This input-cost pressure forces differentiation between premium authentic matchwear with embroidered crests and standard replica jerseys using sublimation printing.
Pricing Analysis
Input-cost pass-through limitations constrain margin recovery for licensed manufacturers facing polyester price swings tied to oil markets. Three-tier pricing structure across premium authentic, standard replica, and economy fan versions separates buyers by crest embroidery quality and fabric weight. Price differentiation hinges on federation exclusivity and seasonal kit refresh timing. Cost compression in standard replicas is intensifying because fixed-price contracts with major retailers prevent full material cost recovery. Casual tournament-triggered buyers in Brazil and Indonesia show highest price sensitivity; dedicated collectors in Germany demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in São Paulo, London, and Los Angeles anchor hub-and-spoke fulfillment patterns that position inventory ahead of tournament demand spikes. Manufacturing concentrates in Vietnam, Bangladesh, and China for cut-and-sew assembly with specialized sublimation printing clusters in Guangdong and Zhejiang. Raw material dependencies draw from Taiwanese polyester fiber suppliers, German dye chemical producers, and Italian embroidery equipment makers. Single-source vulnerability runs through concentrated digital textile engineering talent pools in Bavaria and Lombardy. Distribution runs through Fanatics-operated direct-to-fan platforms and club-owned e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Football merchandise operates as a geographic-arbitrage play where REACH compliance costs in Germany and France create margin headroom for suppliers with pre-certified water-based sublimation ink capabilities against Asian competitors facing EU entry barriers.
For Market Incumbents: Anticipate counterfeit supply concentration in specific Asian manufacturing zones by embedding NFC chip authentication into premium collectible tiers and tightening direct-to-fan channel control. Vertical integration into on-demand micro-factories near English and German demand clusters reduces tournament-driven inventory risk. Certification investment in EU Green Deal textile traceability standards secures shelf placement with French and German retailers. For New Entrants and Emerging Players: Influencer-curated storefronts on short-form video platforms offer the most penetrable channel for reaching Brazilian and Indonesian fanbases without legacy retail overhead. White-space targets include tier-two Indian cities with maturing localized e-commerce platforms and underpenetrated club loyalty. Blockchain-authenticated limited editions for resale-capture economics represent a defensible go-to-market angle against established kit manufacturers. For Investors and Strategic Acquirers: Roll-up economics work for specialized kit manufacturers with league-specific concentration because licensing agreement fragmentation between clubs, leagues, and player image holders creates IP clearance bottlenecks that favor scaled players with dedicated legal infrastructure. Target vertically integrated mid-cap specialists with captive sublimation printing and federation relationships. Watch for inflection in India's BIS certification enforcement against unauthorized replica imports as European league streaming rights mature.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Fan Platform Integration | Fanatics and club-operated channels capture full margin and first-party purchase data. |
| Sustainability Repositioning | Recycled ocean plastic certifications secure shelf placement with German and French retailers. |
| Blockchain Authentication Launch | NFC chip verification creates premium collectible tiers with provable scarcity for resale markets. |
| Geographic Manufacturing Footprint | On-demand micro-factories near English demand clusters compress design-to-delivery cycles. |
| Distribution Channel Expansion | Influencer-curated storefronts reach Brazilian supporters outside traditional club channels. |
Methodological Framework
Bottom-up fan segmentation modeling reconciled against top-down licensed manufacturer production tracking forms the analytical core of this study. Primary interviews with kit licensing directors, federation partnership managers, textile procurement leads at sportswear conglomerates, and e-commerce platform operators combined with secondary validation against customs records, SEC 10-K filings, and EU trademark registration databases. Triangulation across these sources calibrated volume estimates for replica kit refresh cycles and tournament-triggered demand spikes.
Historical tournament cycle analysis and seasonal kit refresh patterns established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include product type, sales channel, customer sophistication tier, and team affiliation category with regional regulatory cluster overlays. CAGRs were derived from reconciling manufacturer shipment data with retail sell-through velocity. Forecast inputs incorporated REACH compliance evolution timelines and mobile commerce infrastructure penetration rates in target geographies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to polyester feedstock volatility, counterfeit enforcement intensity in Asian manufacturing zones, and EU Green Deal textile mandate implementation pace. Outputs reflect documented assumptions around tournament scheduling, licensing renewal patterns, and digital platform adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
UK Spectator Sports Market
Sports & Fitness Technology
Europe Sports Promoter Market
Sports & Fitness Technology
Reflective Sportswear Market
Sports & Fitness Technology
Sports Sponsorship Market
Sports & Fitness Technology
North America Sports Promoter Market
Sports & Fitness Technology
North America Sports Team and Clubs Market
Sports & Fitness Technology
Smart Court (Sports) Market
Sports & Fitness Technology
Sports Team and Clubs Market
Sports & Fitness Technology
Padel Court Operator Market
Sports & Fitness Technology
Smart Fitness Device Market
Sports & Fitness Technology
Sports Software Market
Sports & Fitness Technology
UK Sports Management Software Market
Sports & Fitness Technology
Europe Spectator Sports Market
Sports & Fitness Technology
Asia Pacific Sports Promoter Market
Sports & Fitness Technology
Smart Fitness Trainer Market
Sports & Fitness Technology
Sports App Market