
 North America Sports Management Software Market | 2026-2036
North America Sports Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sports Management Software Market Analytics
Youth sports leagues and amateur athletic clubs is pivoting toward integrated payment and communication platforms. Stack Sports leverages vertical integration across tournament registration and coaching education to sustain platform stickiness. SportsEngine Inc. anchors its position through deep youth league partnerships and parent-facing mobile interfaces. Active Network LLC competes aggressively in endurance event management, extending its reach into municipal recreation contracts.
North America Sports Management Software encompasses cloud-native and on-premises applications that automate scheduling, athlete registration, financial transactions, performance analytics, and compliance reporting for sports organizations. These systems typically integrate REST APIs for payment gateways, GPS-enabled mobile check-in, and role-based access controls spanning coaches, parents, and administrators. Team Management Software dominates current revenue as leagues prioritize roster automation and parent communication over advanced analytics. Cloud-Based deployment is expanding fastest among mid-market clients seeking reduced IT overhead, though On-Premises retains share in collegiate athletic departments with stringent FERPA and HIPAA data residency requirements.
FERPA governs student athlete data privacy across US collegiate deployments, while COPPA restricts data collection from users under thirteen in youth sports platforms. NCAA compliance officers now mandate audit trails for NIL transactions, creating procurement pressure on Athletic Management Software vendors. Health Canada and the Office of the Privacy Commissioner of Canada shape product requirements for cross-border youth hockey and soccer platforms operating in Ontario and British Columbia. Stakeholders must monitor how state-level biometric privacy laws in Illinois and Texas redefine consent frameworks for wearable-integrated athlete tracking systems.
Market Dynamics
NCAA NIL compliance mandates and FERPA data residency requirements are forcing athletic departments toward integrated platforms with immutable audit trails, compressing vendor selection cycles and elevating procurement standards across collegiate and youth sports organizations.
Growth Catalysts
- Cloud migration among mid-market leagues:Amateur athletic clubs in Texas and Florida are abandoning spreadsheet-based scheduling for SaaS platforms with embedded payment processing and automated roster management.
- FERPA and HIPAA data governance:Collegiate athletic departments require on-premises or hybrid deployments with role-based access controls, creating procurement pull for vendors with federal compliance certifications.
- Wearable-integrated performance tracking:GPS-enabled athlete monitoring systems are generating demand for platforms that aggregate biometric data alongside traditional scheduling and financial modules.
Market Restraints
- Input cost volatility in cloud infrastructure:AWS and Azure pricing fluctuations squeeze margins for SaaS-native vendors serving price-sensitive youth league segments.
- Supply concentration in payment processing:Dependence on Stripe and PayPal APIs creates single-point-of-failure risk for platforms without redundant gateway integrations.
- Technical debt in legacy collegiate systems:Decades-old on-premises installations at major universities resist API-based integration with modern mobile interfaces.
Strategic Opportunities
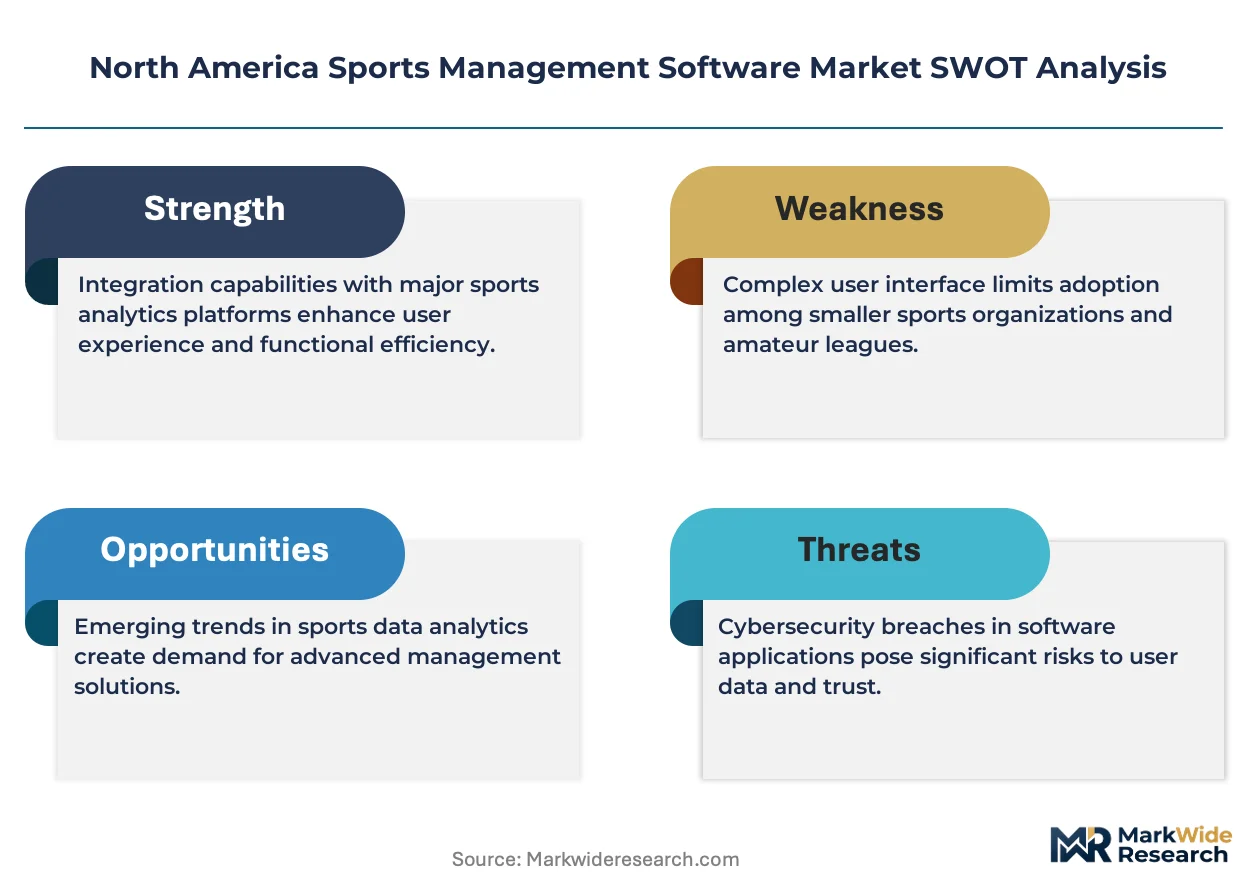
- Underpenetrated Canadian youth hockey leagues:Ontario and British Columbia associations lack integrated platforms combining tournament registration with Health Canada-compliant medical waiver tracking.
- Convergence of AI and compliance reporting:Machine learning classification of NIL transactions offers automation opportunities for NCAA athletic departments drowning in manual audit preparation.
- Municipal recreation channel expansion:Parks and departments in California cities seek unified platforms spanning facility booking, program registration, and resident billing.
Industry Challenges
- Cybersecurity certification timelines:SOC 2 Type II and ISO 27001 audits consume 12-18 months, delaying market entry for emerging vendors targeting collegiate procurement cycles.
- Integration complexity with student information systems:SIS vendors like Ellucian and Anthology maintain proprietary data formats, forcing expensive custom middleware development for roster synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sports Management Software Market |
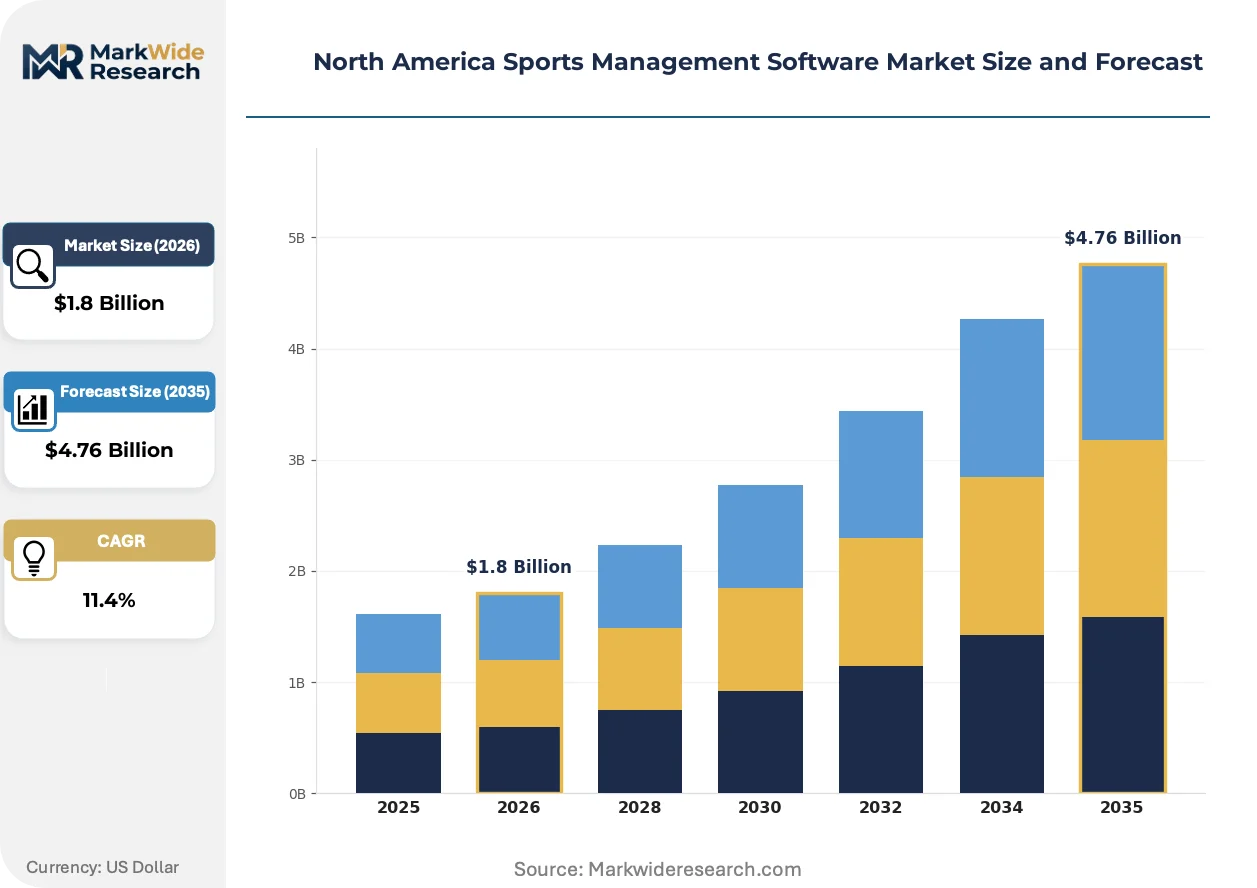
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Team Management Software, Event Management Software, Athlete Management Software, Analytics Software End User: Professional Teams, Colleges, Event Organizers, Fitness Centers Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Solutions Pricing Model: Subscription-Based, One-Time License, Freemium, Pay-Per-Use |
| Companies Covered | LeagueApps, SportsEngine Inc., Stack Sports, Active Network LLC, TeamSnap Inc., Jonas Club Software, Daktronics, Jersey Watch, SquadFusion, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sports Management Software Market Evolving Landscape
API-first architecture and mobile-native interfaces are displacing monolithic legacy platforms across the sports management software stack, compressing implementation timelines and enabling modular procurement by function rather than suite.
Embedded fintech is consolidating payment acceptance, disbursement, and reconciliation within core scheduling platforms. Youth leagues in Texas and Florida are adopting these integrated stacks fastest, eliminating separate merchant account management. This consolidation is reducing vendor count per organization from four or five separate tools to single-platform subscriptions.
NCAA NIL audit trail mandates are reshaping procurement specifications for athletic management modules. Compliance officers now require immutable transaction logging with timestamped approval workflows. Collegiate athletic departments in California and Texas are responding by prioritizing vendors with pre-built NCAA compliance templates over generalist platforms.
Parent-facing mobile interfaces are becoming the primary competitive battleground for youth league retention. Leagues in dense suburban markets around Dallas and Miami are switching providers based on app store ratings and real-time communication features. This behavioral shift elevates UX design above back-office functionality in vendor selection criteria for amateur athletic clubs.
North America Sports Management Software Market Segmentation
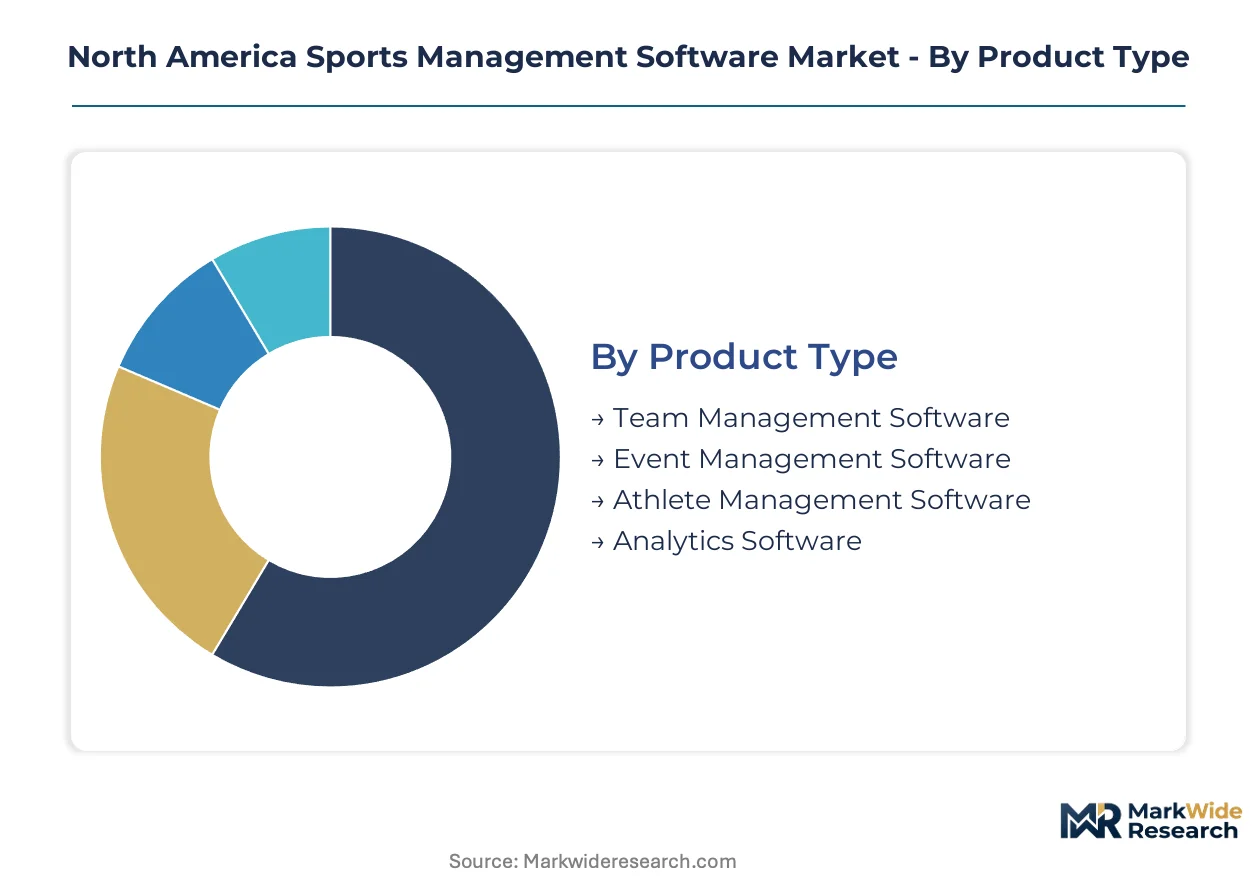
Sports management software vendors configure product portfolios around distinct operational pain points and procurement budgets. Segment boundaries shift as cloud-native platforms absorb adjacent functionality and collegiate compliance requirements tighten data governance specifications.
Product Type:
Team Management Software commands the largest revenue share, while Analytics Software captures the highest per-seat pricing and fastest expansion trajectory.
- Team Management Software:Core modules automate roster synchronization, parent communication portals, and payment collection for youth leagues. Demand clusters in Texas and Florida where high school sports participation drives dense league formation and tournament scheduling complexity.
- Event Management Software:Tournament registration, bracket generation, and facility booking tools dominate endurance racing and municipal recreation procurement. California cities prioritize these platforms for unified parks-and-recreation billing integration.
- Athlete Management Software:Compliance tracking for NCAA NIL transactions and medical waiver documentation. Collegiate athletic departments in California and Texas require immutable audit trails with timestamped approval workflows.
- Analytics Software:Performance dashboards aggregating GPS-enabled wearable data alongside traditional statistics. Emerging demand from professional academies and elite youth programs seeking biometric-informed coaching decisions.
Today's leader: Team Management Software. Tomorrow's challenger: Analytics Software.
End User:
Procurement sophistication varies sharply across buyer categories, with Colleges demanding FERPA-certified deployments and Fitness Centers prioritizing month-to-month flexibility.
- Professional Teams:Analytics-heavy platforms with API integrations to scouting databases and salary cap management tools. These organizations drive premium pricing through customization requirements and dedicated support tiers.
- Colleges:Athletic departments mandate hybrid deployments satisfying HIPAA data residency and NCAA NIL compliance audit trails. Procurement cycles extend 12-18 months due to SOC 2 certification requirements.
- Event Organizers:Cloud-native registration and payment processing for endurance races and youth tournaments. Texas and Florida endurance event operators represent the densest concentration of mid-market SaaS adoption.
- Fitness Centers:Member management and class scheduling with embedded point-of-sale functionality. Price sensitivity here favors freemium entry points and usage-based scaling.
Colleges anchor premium revenue per contract. Event Organizers are expanding most quickly across the analysis window.
Deployment:
Cloud-Based solutions dominate new customer acquisition, though On-Premises retains strategic importance for data-sovereign institutional buyers.
- Cloud-Based:Multi-tenant SaaS architectures with REST API connectivity to Stripe and PayPal payment gateways. Mid-market youth leagues in suburban Dallas and Miami markets adopt these platforms fastest for reduced IT overhead.
- On-Premises:Single-tenant installations meeting FERPA and HIPAA data residency requirements for collegiate athletic departments. Legacy systems at major universities resist API integration with modern mobile interfaces.
- Hybrid:Sensitive athlete data stored locally with scheduling and communication modules cloud-hosted. Emerging preference among Canadian youth hockey associations navigating Health Canada cross-border data guidance.
- Mobile Solutions:Native iOS and Android applications for parent-facing check-in and real-time roster updates. League retention decisions in dense suburban markets increasingly hinge on app store ratings.
Cloud-Based deployment owns current volume leadership. Mobile Solutions are gaining share fastest as parent experience becomes the primary retention lever.
Pricing Model:
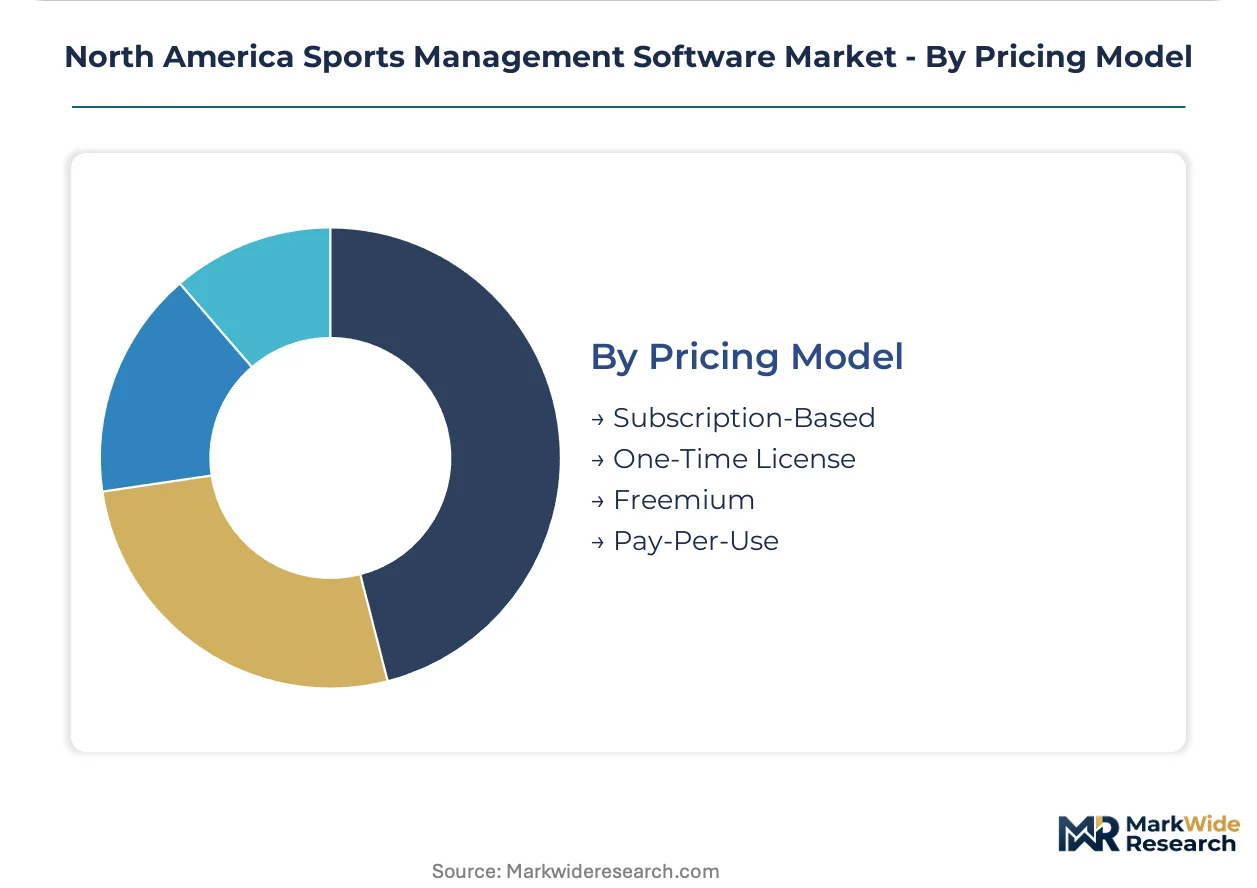
Revenue predictability concerns are shifting vendor mix toward recurring structures, though transaction-linked models retain appeal in seasonal sports.
- Subscription-Based:Annual or monthly per-team or per-athlete pricing with tiered feature access. Vendors favor this structure for reduced churn and predictable revenue recognition.
- One-Time License:Perpetual deployment rights with annual maintenance contracts. Retains presence in On-Premises collegiate installations where capital budget cycles predominate.
- Freemium:Basic scheduling and communication tools at no cost with premium payment processing and analytics upgrades. Entry point for price-sensitive youth leagues testing platform stickiness.
- Pay-Per-Use:Transaction fees on registration revenue and payment processing volume. Aligns vendor incentives with league growth but introduces revenue volatility.
Subscription-Based pricing dominates vendor strategy. Pay-Per-Use models show steepest expansion trajectory among tournament-centric event organizers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping vendor deployment strategies across North America, as FERPA data residency requirements and Health Canada privacy guidance create compliance cost gaps that influence platform architecture decisions and customer acquisition priorities.
United States
Texas and California dominate youth league adoption, with suburban Dallas leagues driving cloud-based scheduling demand and California collegiate athletic departments mandating NCAA NIL audit trail compliance. FERPA governs student athlete data privacy across university deployments. Austin and Los Angeles host the densest concentrations of mid-market SaaS vendors serving amateur athletic clubs.
Canada
Ontario and British Columbia youth hockey associations represent underpenetrated demand for integrated tournament registration platforms. Health Canada and the Office of the Privacy Commissioner of Canada shape cross-border data requirements for platforms operating in both countries. Toronto and Vancouver clusters concentrate procurement activity among municipal recreation departments seeking unified facility booking systems.
Mexico
Emerging demand from private sports academies in Mexico City and Monterrey is accelerating Spanish-language platform localization. The country's federal data protection law creates compliance thresholds for biometric-integrated athlete tracking systems. Guadalajara's expanding youth soccer league infrastructure is attracting vendor attention for payment processing integration.
North America Sports Management Software Market Competitive Landscape
Platform consolidation dominates the current landscape, with specialized vendors absorbing adjacent functionality to reduce customer vendor counts from four or five separate tools toward single-platform subscriptions. The vendor base organizes around three strategic archetypes: youth league specialists with parent-facing mobile interfaces, collegiate compliance platforms with FERPA-certified deployments, and endurance event operators with municipal recreation channel expertise. M&A activity and API-first architecture development represent the dominant competitive moves, as incumbents acquire niche scheduling tools and rebuild legacy monoliths into modular service layers.
Within the youth league specialist tier, SportsEngine Inc. and Stack Sports exemplify platform stickiness strategies through deep league partnership networks and vertical integration across tournament registration and coaching education. Active Network LLC occupies a position among endurance event management specialists, anchoring municipal recreation contract expansion in California and Texas markets where unified facility booking demand concentrates.
| Leading Market Players |
|---|
| LeagueApps |
| SportsEngine Inc. |
| Stack Sports |
| Active Network LLC |
| TeamSnap Inc. |
| Jonas Club Software |
| Daktronics |
| Jersey Watch |
| SquadFusion |
| Others |
Value Network & Pricing Analysis
Certification-tier divergence between FERPA-compliant collegiate deployments and freemium youth league offerings manifests in both pricing stratification and supply chain configuration, with SOC 2 Type II certification timelines creating 12-18 month procurement delays that compress margins for SaaS-native vendors while elevating price premiums for compliant hybrid deployments.
Pricing Analysis
Direct-to-league subscription discounts dominate the channel-margin layer, with annual per-team SaaS pricing stratifying across premium NCAA compliance tiers, standard mid-market cloud bundles, and economy freemium entry points. Price differentiation hinges on HIPAA certification grade and embedded payment processing depth. Pricing pressure stems from AWS and Azure infrastructure cost volatility squeezing vendor margins. Youth leagues in Texas and Florida exhibit highest price sensitivity, while collegiate athletic departments in California prioritize compliance premiums over cost.
Supply Chain Analysis
FERPA data residency mandates are reshaping sourcing toward domestic cloud regions and on-premises hardware procurement for collegiate athletic departments. Software development concentrates in the United States, with payment gateway integration dependencies drawing from Stripe and PayPal API ecosystems. Supply chain risk centers on single-source payment processor vulnerability. Distribution runs through direct SaaS sales teams for mid-market leagues and specialized channel partners for municipal recreation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge from compliance cost differentials between US FERPA-certified deployments and Canadian Health Canada-aligned platforms, where cross-border data guidance creates pricing advantages for hybrid cloud architectures serving Ontario and British Columbia youth hockey associations.
For Market Incumbents: To counter API-first challengers displacing monolithic legacy platforms, incumbents must accelerate modular service-layer rebuilds and deepen upstream control over payment processing infrastructure. SOC 2 certification investment in Texas and California markets anchors retention of collegiate procurement cycles against emerging SaaS-native entrants. For New Entrants and Emerging Players: Mobile-native parent interfaces offer the most penetrable entry vector, targeting suburban Dallas and Miami youth leagues where app store ratings drive switching behavior. Freemium scheduling tools with premium payment processing upgrades provide the optimal go-to-market angle for price-sensitive amateur athletic clubs testing platform stickiness. For Investors and Strategic Acquirers: Consolidation pressure builds where NCAA NIL compliance mandates compress vendor selection cycles toward integrated platforms with immutable audit trails. Long-term viability favors vendors bridging youth league SaaS agility with collegiate data sovereignty requirements. The signal to watch is municipal recreation contract expansion velocity in California cities seeking unified facility booking systems.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates payment, scheduling, and compliance modules into unified SaaS stacks for youth leagues. |
| Acquisition of Specialist Firm | Absorbs niche tournament registration tools to reduce customer vendor counts toward single-platform subscriptions. |
| Geographic Expansion | Captures underpenetrated Canadian youth hockey demand in Ontario and British Columbia markets. |
| Strategic Partnership | Aligns with Stripe and PayPal for redundant payment gateway integration mitigating single-point-of-failure risk. |
| Product Launch | Introduces AI-powered NIL transaction classification automating NCAA compliance audit preparation for athletic departments. |
Research Methodology
Bottom-up youth league and collegiate athletic department modeling reconciled against top-down cloud infrastructure and payment processing tracking forms the analytical core of this study. Primary interviews with NCAA compliance officers, youth league administrators, SaaS platform engineers, and municipal recreation procurement managers combined with secondary validation from SEC vendor filings, App Annie mobile engagement data, and Health Canada privacy guidance documents. Triangulation across deployment model adoption curves and regional participation rate differentials ensures segmentation integrity.
Historical trendline analysis of cloud migration velocity among mid-market leagues and NIL compliance procurement cycles established baseline growth trajectories. The analytical framework models deployment mode, organization size, vertical segment, integration complexity, and regional regulatory cluster across the projection horizon. CAGRs derive from elasticity-adjusted adoption curves and collegiate procurement cycle durations. Forecast inputs include wearable-integrated platform demand and municipal recreation channel expansion velocity.
The model assumes a particular technology adoption path; alternative pathways for AI-powered compliance automation would alter the outlook. Forecasts reflect assumptions around NCAA regulatory stability, cloud infrastructure pricing continuity, and youth sports participation density in Texas, California, and Florida. Cybersecurity certification timeline delays and SIS integration complexity represent specific risk factors that could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
North America Sports Team and Clubs Market
Sports & Fitness Technology
North America Sports Promoter Market
Sports & Fitness Technology
Smart Swimming Caps Market
Sports & Fitness Technology
Padel Court Operator Market
Sports & Fitness Technology
Football Merchandise Market
Sports & Fitness Technology
Crossfit Apparel Market
Sports & Fitness Technology
Europe Sports Team and Clubs Market
Sports & Fitness Technology
Smart Stadium Market
Sports & Fitness Technology
Racing Apparel Market
Sports & Fitness Technology
Sports Team and Clubs Market
Sports & Fitness Technology
Smart Fitness Trainer Market
Sports & Fitness Technology
Sports App Market
Sports & Fitness Technology
Sports Software Market
Sports & Fitness Technology
Asia Pacific Sports Team and Clubs Market
Sports & Fitness Technology
Germany Sports Teams and Clubs Market
Sports & Fitness Technology
UK Sports Team and Clubs Market