
 Sports Sponsorship Market | 2026-2036
Sports Sponsorship Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Sponsorship Market Outlook
Programmatic sponsorship analytics is reshaping how brands evaluate and execute partnership contracts. Sponsmore leverages machine-learning valuation models to price assets dynamically across leagues. Trackr.ai sustains competitive advantage through real-time engagement tracking that measures fan attention rather than impressions. Relo Metrics anchors its position with broadcast visibility analytics that quantify logo exposure during televised events.
Sports sponsorship constitutes a commercial arrangement where an entity provides financial or in-kind support to a sports property in exchange for brand association rights, typically governed by contractual terms specifying visibility tiers, activation obligations, and exclusivity clauses. Its primary purpose is to transfer audience affinity and emotional engagement from athletic competition to commercial brands. Event sponsorship within the engagement model dimension captures the largest share of committed spend, as marquee tournaments deliver concentrated viewership and hospitality access. Team sponsorship exhibits the fastest structural growth, driven by year-round content generation and direct fan relationship channels that individual athlete deals cannot replicate.
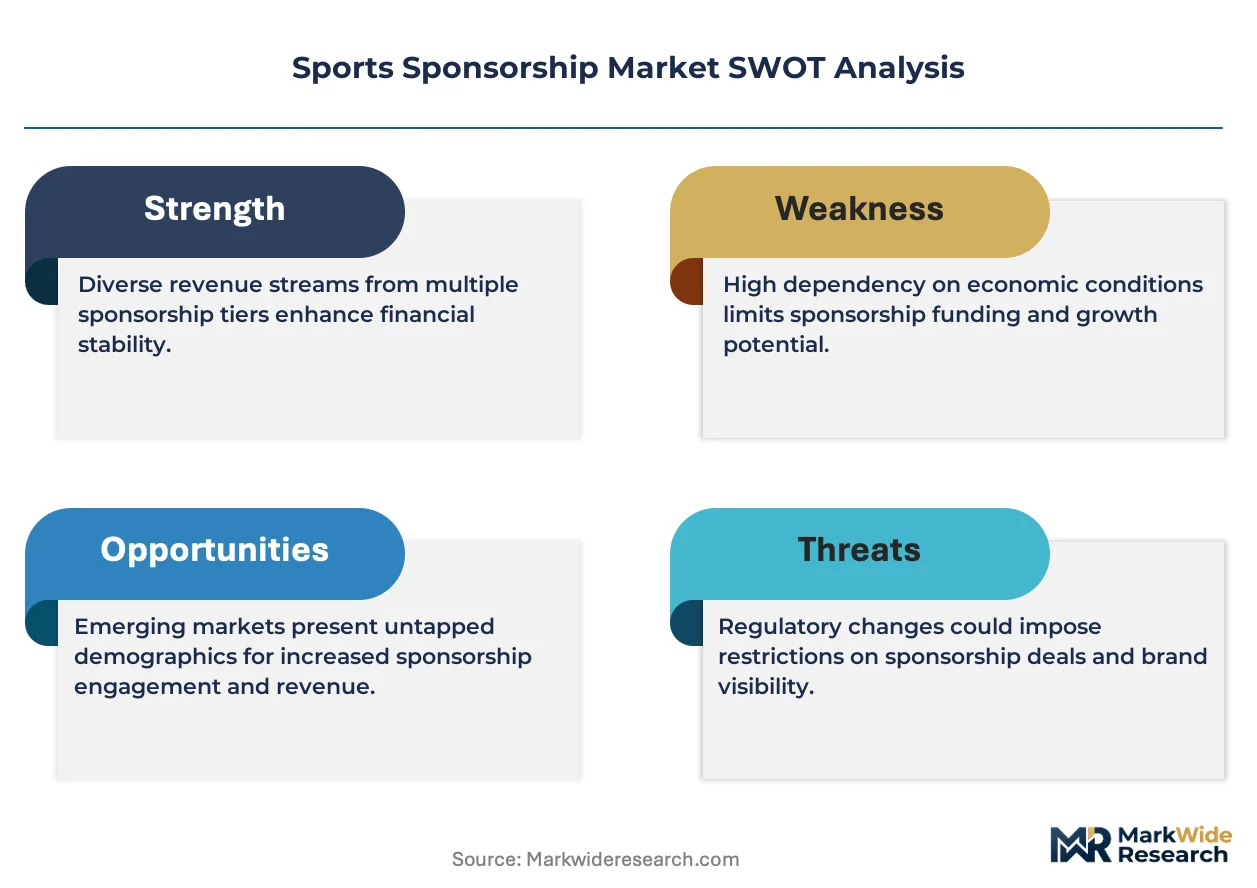
The Federal Trade Commission enforces endorsement disclosure standards that mandate clear identification of paid relationships across social and broadcast channels. The European Union's Digital Services Act imposes transparency requirements on platform-hosted sponsorship content that affect how rights holders package digital inventory. The International Olympic Committee maintains strict ambush marketing rules that restrict non-partner activation near Games venues, shaping how sponsors defend exclusivity investments. Stakeholders must weigh portfolio diversification against concentration risk as valuation methodologies fragment across legacy broadcast and emerging streaming metrics.
Market Dynamics
Programmatic sponsorship analytics is compressing valuation cycles from annual to real-time, forcing rights holders and brands to renegotiate contract structures mid-term based on engagement metrics rather than fixed media equivalency.
Growth Catalysts
- Sports betting legalization:State-level regulatory expansions across the United States have unlocked new sponsor categories previously restricted from league partnerships, particularly in the NFL and NBA.
- Digital Services Act transparency mandates:The European Union's disclosure requirements for platform-hosted content are standardizing measurement protocols that reduce friction in cross-border sponsorship deals.
- Streaming inventory expansion:Amazon Prime Video's exclusive NFL Thursday Night Football broadcasts demonstrate how digital-native rights packages attract non-traditional advertisers with addressable audience targeting.
Market Restraints
- Measurement fragmentation:The absence of unified cross-platform engagement metrics forces sponsors to maintain redundant analytics contracts with Nielsen, Comscore, and emerging social listening vendors.
- Exclusivity clause inflation:Major leagues in the United States now demand seven-figure minimum guarantees for category-exclusive rights that lock out mid-market brands from premium inventory.
- Ambush marketing enforcement:The International Olympic Committee's venue perimeter restrictions require sponsors to deploy legal teams for activation monitoring, adding fixed compliance overhead.
Strategic Opportunities
- Women's sports underpenetration:The National Women's Soccer League and WNBA command CPM discounts of 40-60% versus male-equivalent properties despite comparable audience growth trajectories.
- Virtual asset tokenization:Blockchain-based fractional sponsorship contracts enable regional brands to access marquee events through secondary trading of visibility rights.
- Environmental, Social, and Governance alignment:The EU Green Deal's corporate sustainability reporting requirements are redirecting sponsorship budgets toward properties with certified carbon-neutral operations.
Industry Challenges
- Data science talent scarcity:Rights holders struggle to hire analysts capable of integrating broadcast, social, and stadium-attendance datasets into unified valuation models.
- Legacy contract renegotiation:Multi-year deals signed before streaming dominance contain impression-based guarantees that sponsors now dispute using attention-based metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Sponsorship Market |
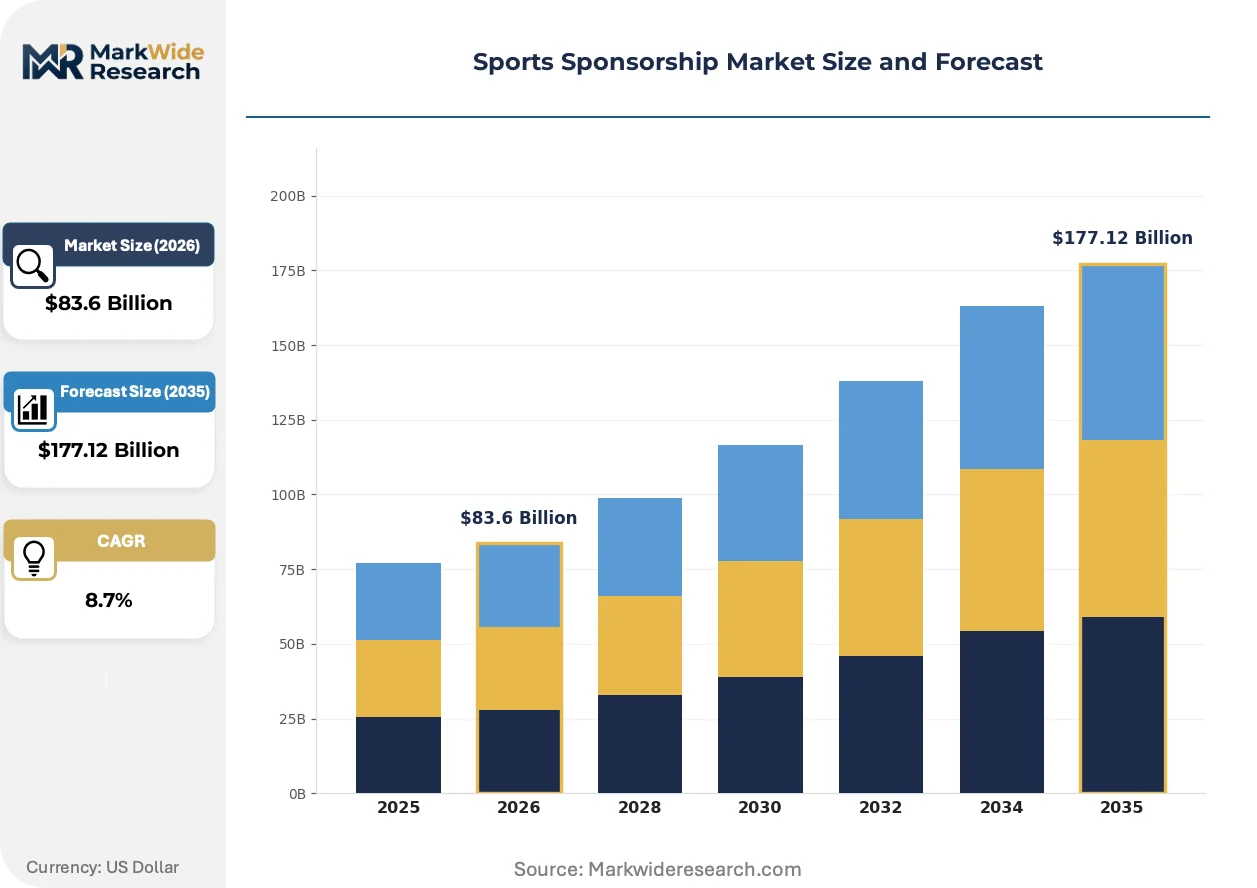
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $177.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Client Type: Corporations, Small Businesses, Startups, Non-Profits Sport Type: Football, Basketball, Soccer, Tennis Engagement Model: Event Sponsorship, Team Sponsorship, Individual Sponsorship, League Sponsorship Market Segment: Amateur, Professional, Grassroots, Elite |
| Companies Covered | Sponsmore, Trackr.ai, Relo Metrics, Renaissance Sports Group, Adstadium.io, Supponor, wehave bv, Sportbnk Ltd, NOCAP Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Sponsorship Market Strategic Shifts
Artificial intelligence is restructuring how sponsorship value gets created, measured, and traded across physical and digital touchpoints. Three distinct vectors are compressing traditional agency intermediation and enabling direct brand-to-property relationships.
Computer vision technology is digitizing logo exposure quantification in broadcast and social content. Platforms like Relo Metrics deploy frame-by-frame analysis to calculate actual screen time rather than estimated media equivalency. Sports properties in the United States are adopting these tools to defend premium pricing during renewal negotiations with Fortune 500 brands.
The European Union's Digital Services Act imposes algorithmic transparency requirements on platform-hosted sponsorship disclosures. Rights holders must now label paid partnerships with standardized metadata that feeds into content moderation systems. This regulatory architecture is forcing inventory packaging changes, particularly for influencer-athlete collaborations that previously operated in disclosure gray zones.
Attention-based buying contracts are displacing impression-guaranteed structures in premium negotiations. Brands now negotiate for minimum seconds of active fan engagement rather than raw reach metrics. This behavioral shift is most visible in the United States, where NFL team partnerships increasingly specify TikTok completion rates and Instagram Story tap-through benchmarks alongside traditional broadcast requirements.
Sports Sponsorship Market Segmentation
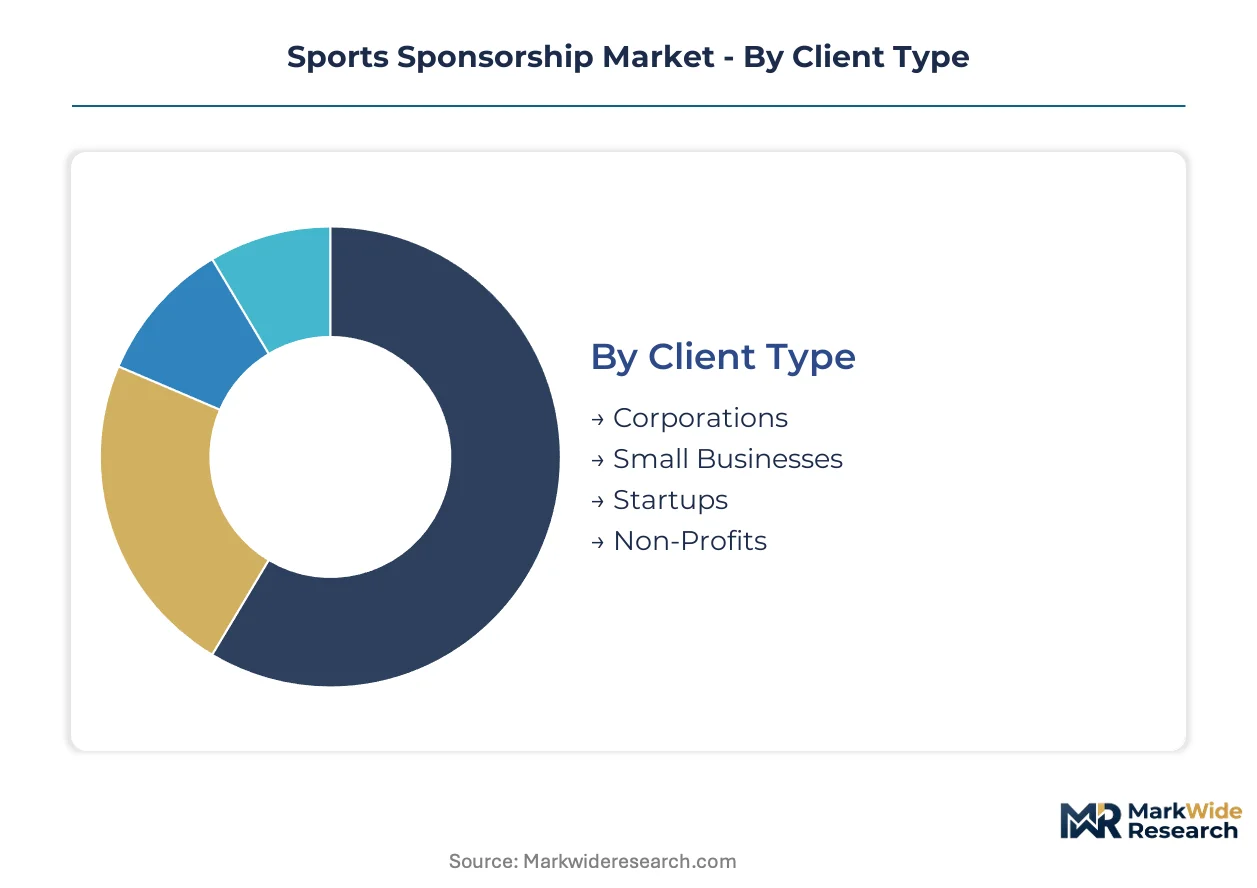
Sports sponsorship segmentation reveals distinct contracting rhythms across client sophistication levels and property tiers. Rights holders must calibrate inventory packaging and valuation models to match the renewal cadence and activation capacity of each segment cluster.
Client Type:
Corporations operate on annual budget cycles with quarterly performance reviews, while small businesses and startups refresh commitments based on cash-flow triggers rather than fixed calendars.
- Corporations:Multi-year master agreements with professional leagues and marquee events dominate this tier, driven by chief marketing officers seeking brand-safe mass reach. Fortune 500 technology and financial services firms concentrate spend in the United States and United Kingdom, where broadcast visibility metrics justify nine-figure partnership valuations.
- Small Businesses:Regional team and grassroots event partnerships with hyper-local activation rights serve this segment. Automotive dealerships and quick-service restaurant franchises in mid-sized United States metropolitan areas represent the core demand concentration.
- Startups:Short-term, performance-tied arrangements with emerging sports properties and digital-native athletes characterize startup participation. Venture-backed fintech and direct-to-consumer brands in California and New York prioritize social media engagement metrics over traditional broadcast exposure.
- Non-Profits:Cause-aligned partnerships with community sports programs and health-focused athletic events sustain this segment. Hospital systems and charitable foundations in Texas and Florida leverage sponsorship for patient outreach and donor cultivation.
Corporations anchor the volume base while startups gain share at the steepest rate.
Sport Type:
Contract durations stretch across multi-year league deals in football and basketball, whereas tennis operates on tournament-by-tournament negotiation cycles with seasonal rebooking pressure.
- Football:The National Football League commands the highest per-partner valuations through exclusive category rights and integrated broadcast packages. Sports betting operators and beverage conglomerates in the United States drive category expansion as state regulations evolve.
- Basketball:Year-round content generation through the NBA regular season, playoffs, and international exhibition tours sustains partner visibility. Athletic apparel and streaming service brands prioritize basketball for demographic alignment with younger consumer cohorts.
- Soccer:Global club partnerships with European and Latin American teams attract multinational brands seeking emerging market penetration. The UEFA Champions League and Copa Libertadores serve as anchor inventory for telecommunications and automotive sponsors.
- Tennis:Individual athlete endorsements and Grand Slam event packages dominate this segment's commercial structure. Luxury watchmakers and premium financial services firms concentrate spend around Wimbledon and the four major tournaments.
Football captures the largest committed spend while soccer demonstrates the most rapid geographic expansion trajectory.
Engagement Model:
Asset depreciation curves vary sharply: event sponsorship delivers concentrated burst value, team sponsorship generates steady amortized returns, and individual athlete deals carry the shortest effective durations due to performance volatility.
- Event Sponsorship:Marquee tournaments and one-time championships command premium pricing for concentrated viewership and hospitality access. The Olympic Games and FIFA World Cup represent apex inventory with multi-cycle bidding processes and strict exclusivity enforcement.
- Team Sponsorship:Jersey branding, stadium naming rights, and content partnership extensions provide year-round activation platforms. National Basketball Association and European football club deals increasingly incorporate social media content guarantees alongside traditional visibility.
- Individual Sponsorship:Direct athlete endorsement contracts offer flexible term structures and rapid campaign deployment. Social media follower metrics and engagement rates now dominate valuation for individual deals, displacing historical achievement-based pricing.
- League Sponsorship:Category-exclusive partnerships with governing bodies provide comprehensive access across member teams and sanctioned events. Title sponsorship arrangements with the National Football League and National Hockey League establish competitive moats for category leaders.
Event sponsorship retains the highest per-deal valuation while team sponsorship expands most quickly across digital inventory extensions.
Market Segment:
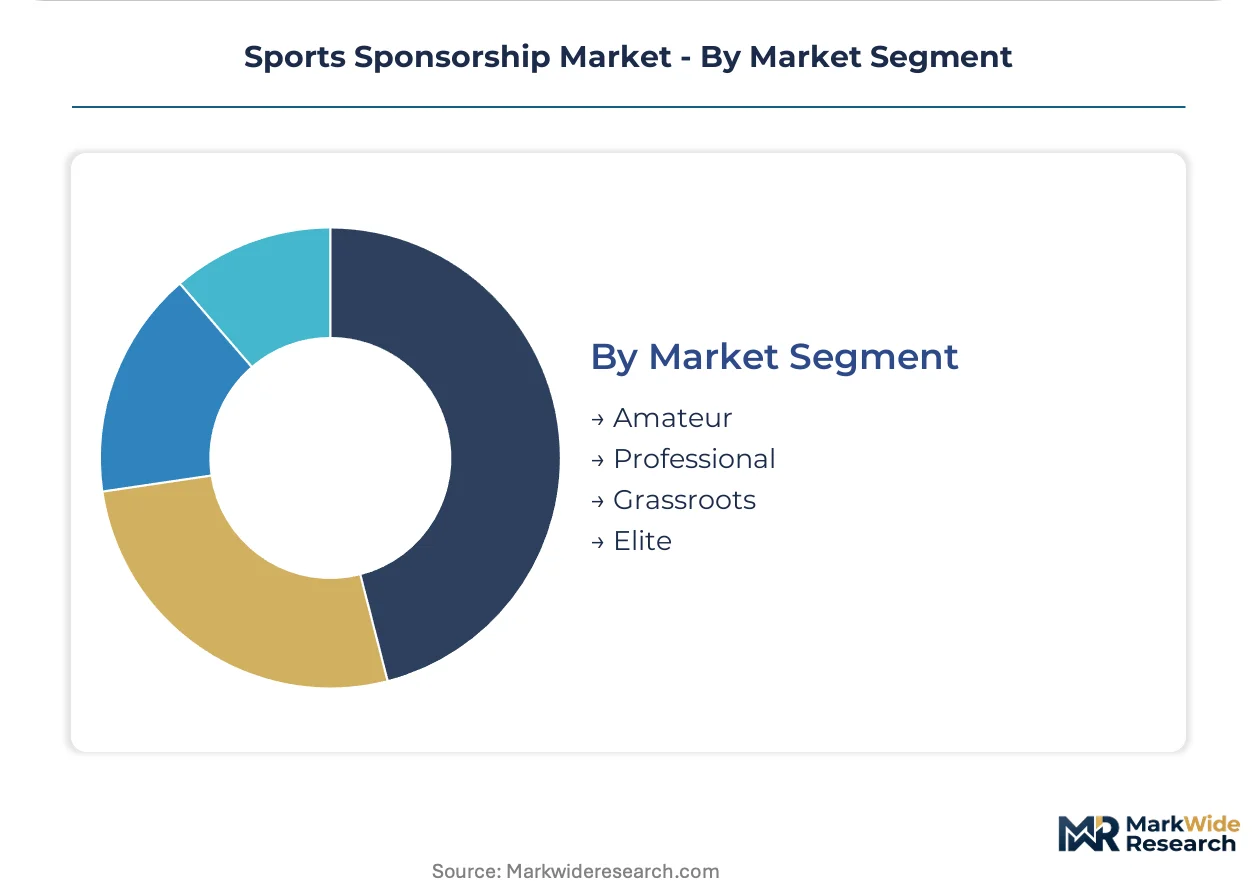
Professional and elite tiers operate on formal procurement processes with dedicated partnership departments, whereas amateur and grassroots segments rely on informal relationship-based deal flow with minimal contract standardization.
- Amateur:Community leagues and recreational tournaments serve local business visibility needs with minimal activation infrastructure. Regional insurance brokers and construction firms in the United States sustain this segment through modest five-figure annual commitments.
- Professional:Commercialized leagues with broadcast distribution and merchandise operations attract institutional sponsorship investment. The National Football League, National Basketball Association, and Major League Baseball represent the core professional inventory in North America.
- Grassroots:Youth development programs and school-based athletic initiatives offer early-stage brand relationship building. Equipment manufacturers and nutritional supplement brands prioritize grassroots access for lifetime customer acquisition.
- Elite:Olympic-caliber individual athletes and premier international competitions command scarcity premiums for association rights. National Olympic committees and international federations package elite athlete access through formal partner programs with compliance monitoring.
Professional properties anchor the revenue base while grassroots programming climbs the fastest as brands prioritize authentic community connection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based sports properties export sponsorship inventory to European and Asian brand buyers through digital streaming rights packages. Cross-border deal flow concentrates in football and basketball broadcast assets. Regulatory fragmentation across FTC disclosure rules and EU platform transparency mandates shapes contract structuring.
United States
The National Football League and National Basketball Association command premium partnership valuations through exclusive category rights and integrated broadcast packages. The Federal Trade Commission enforces endorsement disclosure standards that mandate clear identification of paid relationships across social and broadcast channels. Sports betting operators in Nevada and New Jersey drive category expansion as state-level regulatory frameworks evolve.
United Kingdom
Premier League football clubs attract multinational brands seeking global emerging market penetration through established fan bases. The Digital Services Act imposes transparency requirements on platform-hosted sponsorship content that affect how rights holders package digital inventory. London-based media agencies coordinate pan-European activation strategies for Fortune 500 technology and financial services firms.
Germany
Bundesliga football properties sustain year-round partner visibility through content generation and direct fan relationship channels. The EU Green Deal's corporate sustainability reporting requirements redirect sponsorship budgets toward properties with certified carbon-neutral operations. Munich and Dortmund industrial clusters host headquarters of automotive and telecommunications sponsors prioritizing basketball and football partnerships.
China
Domestic sports leagues expand commercial partnerships as consumer brands seek localized engagement platforms beyond international property access. The national broadcasting regulator maintains content approval requirements for sponsored programming that extend contract negotiation timelines. Shanghai and Beijing metropolitan areas concentrate demand from technology and beverage conglomerates targeting younger consumer cohorts through basketball and esports.
Australia
Australian Football League and National Rugby League properties deliver concentrated viewership for domestic brands seeking mass reach in fragmented media markets. The country's competition regulator monitors exclusivity arrangements for anti-competitive effects in broadcast rights negotiations. Sydney and Melbourne sports marketing clusters develop activation infrastructure for Asia-Pacific regional campaign deployment.
Sports Sponsorship Market Competitive Environment
Channel-controlling players compete with product-specialist players across valuation, measurement, and activation segments. The vendor base organizes into three tiers: analytics platforms with machine-learning pricing models, real-time engagement tracking specialists, and broadcast visibility quantification services. Strategic archetypes include technology-anchored scale players, niche measurement specialists, and integrated full-service agencies. Competitive moves concentrate on M&A for data asset accumulation and strategic partnerships for cross-platform measurement standardization.
Within the analytics-platform tier, Sponsmore and Trackr.ai represent machine-learning valuation and real-time engagement tracking specializations respectively. Relo Metrics anchors the broadcast visibility quantification segment with frame-by-frame logo exposure analysis. These three companies exemplify how technology differentiation displaces traditional agency intermediation in direct brand-to-property relationships.
| Leading Market Players |
|---|
| Sponsmore |
| Trackr.ai |
| Relo Metrics |
| Renaissance Sports Group |
| Adstadium.io |
| Supponor |
| wehave bv |
| Sportbnk Ltd |
| NOCAP Sports |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Nielsen and Comscore for cross-platform measurement data widens pricing spreads between analytics-integrated sponsors and those locked in legacy impression-based contracts, compressing margins for mid-tier rights holders unable to fund redundant data subscriptions.
Pricing Analysis
Legacy broadcast-guaranteed contracts trade at premiums against emerging attention-based structures, with machine-learning valuation platforms commanding SaaS-tiered subscription fees that scale with asset volume. Price differentiation rests on certification tier—Fortune 500 brands pay exclusivity premiums for category lockouts in the NFL and NBA, while regional advertisers accept standard inventory with limited activation rights. Pricing pressure stems from sponsor disputes over impression-based guarantees in pre-streaming era deals. Startups exhibit the highest price sensitivity, negotiating performance-tied arrangements with minimal upfront commitments.
Supply Chain Analysis
Upstream data feedstock from broadcast rights holders in the United States, United Kingdom, and Germany anchors valuation model training for analytics platforms. Machine-learning pricing engines draw from stadium attendance databases, social media APIs, and second-screen engagement metrics. Single-source vulnerability concentrates in Nielsen's television measurement monopoly, threatening model accuracy if access terms shift. Distribution runs through direct platform-to-brand contracts that disintermediate traditional sports marketing agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sponsor consolidation around programmatic analytics platforms has shifted bargaining power toward data-integrated buyers, fragmenting pricing power among legacy rights holders dependent on annual fixed-fee structures.
For Market Incumbents: Build proprietary data moats through captive acquisition of computer vision analytics capabilities. NFL and NBA properties should deepen in-house production of engagement measurement tools to reduce reliance on third-party valuation platforms. Sports betting operators pose the most acute substitution threat as they deploy native audience data for sponsorship targeting.
For New Entrants and Emerging Players: Women's sports properties in the National Women's Soccer League and WNBA offer the most penetrable white-space for valuation arbitrage, with CPM discounts of 40-60% against male-equivalent inventory despite comparable audience growth. Regional fintech brands should pursue short-term influencer-athlete collaborations with standardized Digital Services Act disclosure metadata to accelerate market entry.
For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors technology-anchored scale players with machine-learning pricing infrastructure. Long-term viability hinges on cross-platform measurement standardization that reduces sponsor friction. Acquisition targets should demonstrate unified broadcast-social-stadium dataset integration. The signal to watch is FTC enforcement intensity against undisclosed influencer partnerships, which would accelerate demand for compliant disclosure infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Machine-Learning Valuation Platform Launch | Sponsmore's dynamic pricing models compress contract renegotiation cycles from annual to real-time engagement benchmarks. |
| Cross-Platform Measurement Partnership | Trackr.ai's TikTok completion rate integration addresses sponsor demand for attention-based buying contracts in NFL team deals. |
| Computer Vision Analytics Acquisition | Relo Metrics' frame-by-frame logo exposure quantification defends premium pricing against Fortune 500 procurement pressure. |
| Women's Sports Inventory Expansion | NWSL and WNBA partnership packages capture undervalued audience growth trajectories before CPM normalization. |
| Digital Services Act Compliance Infrastructure | Standardized metadata labeling reduces legal overhead for EU platform-hosted influencer-athlete collaborations. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with rights holders, brand marketers, and sports betting operators across the United States and European Union, and secondary validation through SEC sponsorship disclosure filings, Nielsen media measurement reports, and European Commission Digital Services Act implementation guidance. Chief marketing officers at Fortune 500 technology and financial services firms, partnership directors at NFL and NBA properties, and compliance leads at influencer marketing platforms provided primary perspective. Bottom-up inventory valuation models triangulated against top-down market sizing from broadcast rights expenditure data.
Forecast inputs incorporated engagement model segmentation across event, team, individual, and league sponsorship structures, client type differentiation between corporations and startups, and sport type clustering around football, basketball, soccer, and tennis properties. CAGRs were derived from regression analysis of historical partnership valuation trends against streaming inventory expansion rates and sports betting regulatory adoption curves. Attention-based contract penetration and programmatic analytics platform adoption served as industry-specific demand drivers across the projection horizon.
Practitioners should monitor FTC endorsement disclosure enforcement actions and EU Digital Services Act algorithmic transparency rulings for early signals of contract restructuring pressure. Forecasts reflect assumptions about continued streaming rights fragmentation and state-level sports betting expansion that could accelerate or decelerate based on regulatory timing. Cross-checking against IEG sponsorship industry expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Smart Fitness Device Market
Sports & Fitness Technology
United States Sports Promoter Market
Sports & Fitness Technology
Virtual Reality Fitness Market
Sports & Fitness Technology
Smart Trainers Market
Sports & Fitness Technology
Smart Court (Sports) Market
Sports & Fitness Technology
Europe Sports Management Software Market
Sports & Fitness Technology
Football Merchandise Market
Sports & Fitness Technology
North America Sports Management Software Market
Sports & Fitness Technology
Smart Swimming Caps Market
Sports & Fitness Technology
Crossfit Apparel Market
Sports & Fitness Technology
Asia Pacific Sports Team and Clubs Market
Sports & Fitness Technology
Racing Apparel Market
Sports & Fitness Technology
Europe Sports Team and Clubs Market
Sports & Fitness Technology
UK Spectator Sports Market
Sports & Fitness Technology
Smart Sports Market
Sports & Fitness Technology
Asia-Pacific Fantasy Sports Market