
 Greece Solar Energy Market | 2026-2036
Greece Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Greece Solar Energy Market Outlook
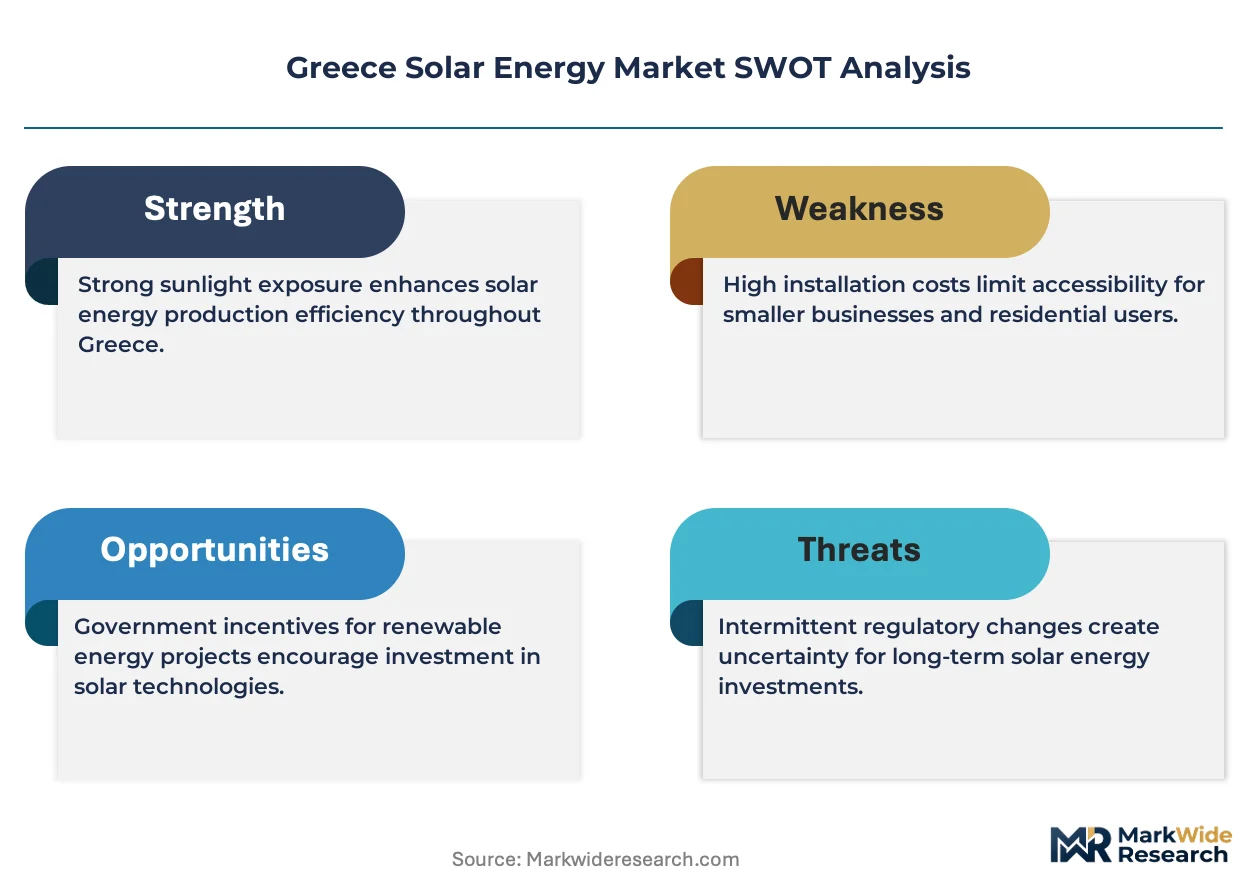
Greek utility-scale solar development is shifting toward the Peloponnese and western Macedonia as land availability and grid access improve. PPC Renewables leverages its incumbent grid relationships to secure interconnection priority for large photovoltaic parks. Terna Energy anchors its growth strategy in hybrid renewable complexes that pair solar with storage. Juwi Holding AG competes through specialized engineering services for complex terrain installations.
Solar energy in Greece encompasses photovoltaic systems that convert sunlight into electricity through semiconductor cells, typically silicon-based modules with efficiencies ranging from twenty to twenty-two percent for monocrystalline units, serving the dual purpose of reducing fossil fuel imports and meeting EU-mandated renewable quotas. Concentrated solar power retains niche relevance for island grids requiring dispatchable renewable output. Utility-scale installations dominate capacity additions, while residential adoption lags due to financing constraints and net metering caps. Bifacial technology leads module selection for ground-mounted projects seeking enhanced yield from reflected irradiance.
The Regulatory Authority for Energy, Waste and Hydrocarbons and the Hellenic Electricity Distribution Network Operator shape project economics through tariff structures and grid connection queues. EU Green Deal obligations and the revised Renewable Energy Directive tighten national targets and accelerate permitting reforms. Stakeholders must monitor grid reinforcement timelines and storage co-location requirements as the next investment cycle unfolds.
Market Dynamics
Greek solar deployment pivots on grid interconnection velocity as HEDNO queues determine project viability and capital allocation across the Peloponnese and Crete corridors.
Growth Catalysts
- EU Green Deal renewable quotas:Binding targets under the revised Renewable Energy Directive mandate member-state solar expansion, forcing Greece to accelerate photovoltaic licensing and land-use approvals.
- Bifacial module yield premiums:Ground-mounted arrays across Thessaly and Larissa exploit albedo reflection from arid terrain, lifting capacity factors without additional footprint.
- Peloponnese grid reinforcement:Priority transmission upgrades by ADMIE unlock utility-scale clusters previously constrained by substation saturation.
Market Restraints
- Polysilicon supply concentration:Greek developers remain exposed to Xinjiang-sourced wafer disruptions and EU forced-labor due diligence requirements under the Corporate Sustainability Due Diligence Directive.
- Land-use competition:Agricultural zoning protections in Thessaly block prime irradiance sites, pushing projects toward lower-yield western Macedonia terrain.
- Net metering caps:Residential segment growth stalls under Hellenic Ministry of Environment and Energy limits on self-consumption compensation rates.
Strategic Opportunities
- Hybrid solar-storage complexes:Co-located lithium-ion systems qualify for enhanced grid services contracts under the new auxiliary services market framework.
- Island microgrids:Crete and the Cyclades present captive demand for dispatchable solar-plus-storage replacing diesel generators.
- Agrivoltaic pilots:Dual-use installations combining photovoltaic canopies with olive cultivation unlock restricted agricultural lands under revised spatial planning exemptions.
Industry Challenges
- Grid code compliance timelines:HEDNO certification delays for inverter firmware upgrades extend commissioning schedules by four to six months.
- EPC talent scarcity:Specialized civil engineering for complex terrain mounting systems commands premium wages, compressing contractor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greece Solar Energy Market |
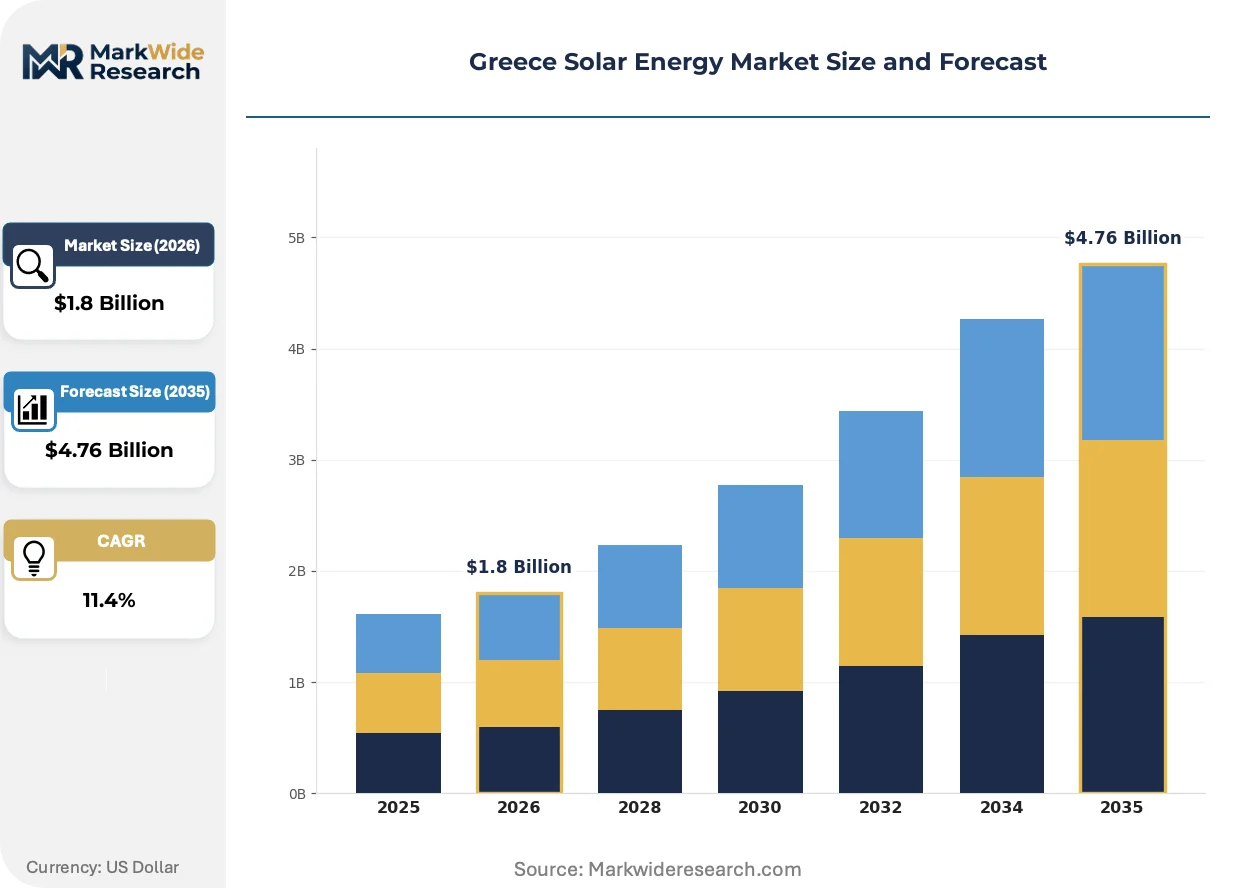
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Systems, Concentrated Solar Power, Solar Water Heating, Solar Roof Tiles Installation Type: Residential, Commercial, Utility-Scale, Off-Grid Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial End User: Households, Businesses, Government, Industrial Facilities |
| Companies Covered | PPC Renewables, TotalEnergies, EDF, Terna Energy, ELPE Renewables, Juwi Holding AG, Lightsource BP, Enel Green Power, RWE Renewables, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greece Solar Energy Market Strategic Shifts
Photovoltaic system architecture is fragmenting into standardized, replicable units that compress engineering cycles and enable non-specialized EPC participation.
Bifacial solar technology is modularizing across Greek utility-scale deployments. Dual-sided silicon modules capture direct and reflected irradiance, lifting yields in arid Peloponnese sites. Independent power producers adopt prefabricated mounting skids that slash civil works duration. This standardization is modularizing project development timelines and eroding engineering-procurement-construction premiums.
Permitting acceleration under Greece's National Energy and Climate Plan compresses environmental licensing from twenty-four to twelve months. Streamlined spatial planning for renewable zones eliminates municipal veto power over designated areas. Utility-scale developers in western Macedonia exploit these procedural gains to advance pipeline projects previously stalled in administrative backlog.
Corporate power purchase agreements displace traditional feed-in tariff dependency among Greek offtakers. Industrial manufacturers in aluminum and cement sectors contract directly with solar parks for baseload supply. This bilateral contracting concentrates in Attica and Thessaloniki manufacturing clusters where grid access costs and carbon exposure intersect.
Greece Solar Energy Market Segmentation
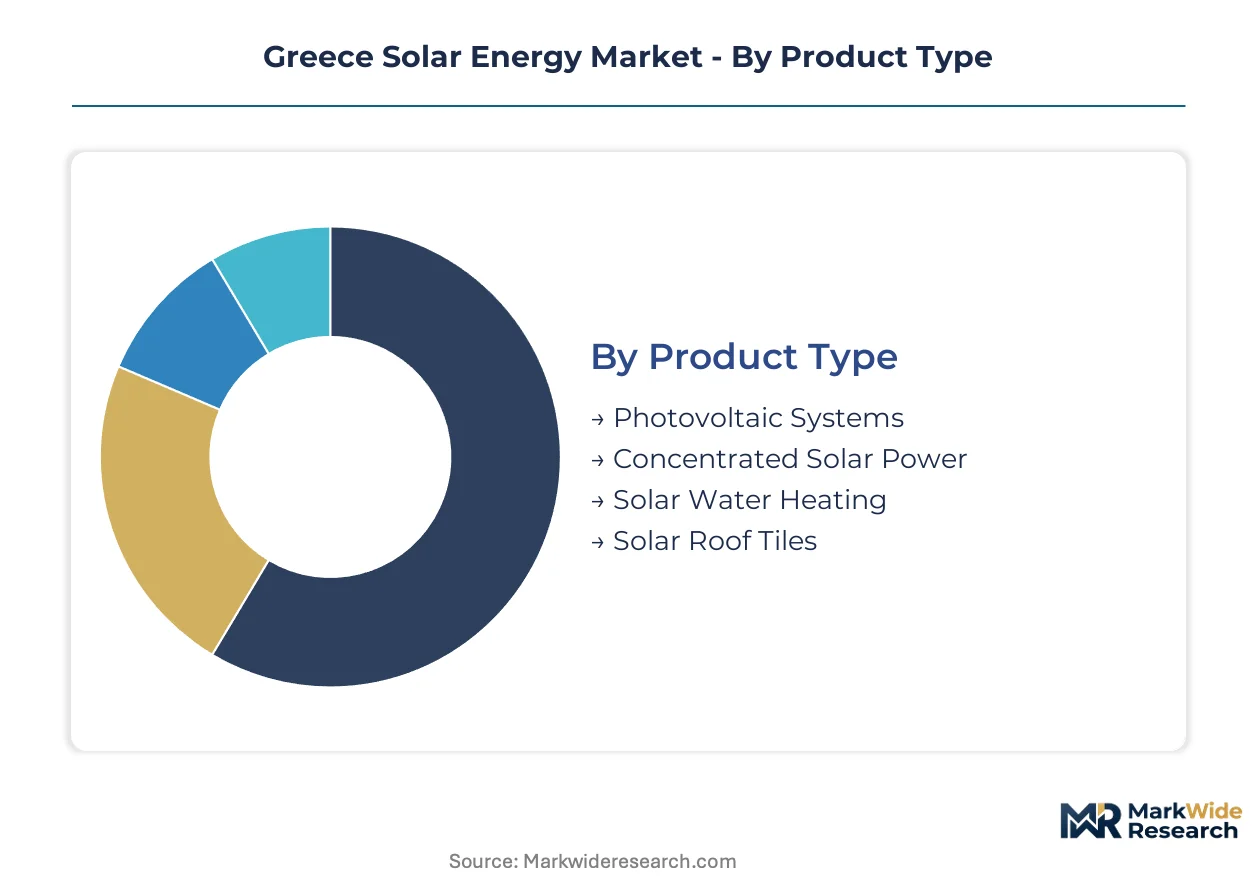
Technology differentiation and installation scale drive capital allocation across the Greek solar market. Module specifications and grid-connection voltage levels determine project economics, developer margins, and licensing pathways for each segment.
Product Type:
Photovoltaic cell chemistry and thermal conversion architecture define the technology axis across Greek deployment.
- Photovoltaic Systems:Silicon-based semiconductor arrays dominate capacity additions across the Peloponnese and Crete corridors. Utility-scale developers in western Macedonia prioritize monocrystalline modules for their twenty to twenty-two percent conversion efficiency and proven bankability with HEDNO interconnection protocols.
- Concentrated Solar Power:Parabolic trough and tower configurations with molten salt storage retain niche relevance for island microgrids requiring dispatchable renewable output. Crete's grid isolation from the mainland makes CSP economically viable despite higher capital intensity versus photovoltaics.
- Solar Water Heating:Evacuated tube and flat-plate collectors serve residential thermal demand, particularly in Aegean islands with limited natural gas infrastructure.
- Solar Roof Tiles:Building-integrated photovoltaics with aesthetic matching to traditional terracotta roofing address heritage zone restrictions in Athens and Thessaloniki historic districts.
Mature deployment sits with Photovoltaic Systems. Newer deployment is concentrated in Solar Roof Tiles.
Installation Type:
Grid connection voltage and land-use intensity shape the cost tier structure for Greek solar projects.
- Utility-Scale:Ground-mounted arrays exceeding one megawatt capacity connect at high-voltage substations across Thessaly and Larissa. ADMIE transmission reinforcement unlocks clusters previously constrained by substation saturation, compressing development timelines for IPPs.
- Residential:Rooftop systems under ten kilowatts face net metering caps imposed by the Hellenic Ministry of Environment and Energy. Financing constraints and bureaucratic complexity stall household adoption despite high irradiance levels.
- Commercial:Mid-scale installations on manufacturing facilities and logistics warehouses in Attica and Thessaloniki clusters contract through corporate power purchase agreements.
- Off-Grid:Standalone systems with battery backup serve remote agricultural operations and island settlements beyond HEDNO distribution network reach.
Volume concentrates in Utility-Scale installations. Margin pressure is most acute in Residential.
Technology:
Cell architecture and light-capture geometry differentiate module performance across Greek terrain conditions.
- Bifacial:Dual-sided silicon modules capture direct and reflected irradiance from arid Peloponnese terrain, lifting capacity factors without additional footprint. Prefabricated mounting skids slash civil works duration for EPC contractors.
- Monocrystalline:Single-crystal silicon wafers deliver premium efficiency for space-constrained commercial rooftops in Athens metropolitan area.
- Polycrystalline:Multi-crystal silicon offers cost advantages for price-sensitive agricultural applications in western Macedonia.
- Thin-Film:Cadmium-telluride and amorphous silicon layers perform in diffuse light conditions, suiting coastal zones with higher cloud cover.
Technology leadership sits with Bifacial modules. Thin-Film maintains residual presence in specialized coastal applications.
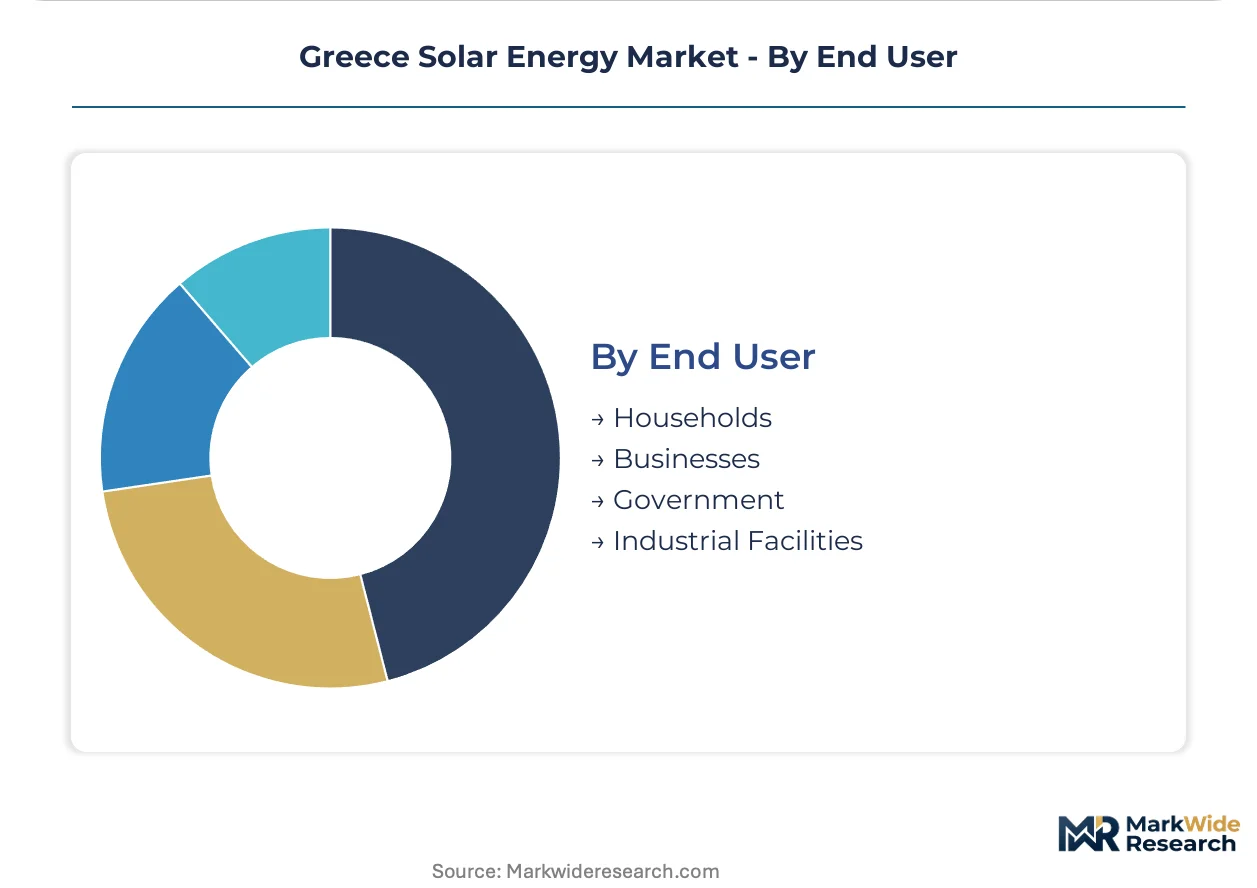
End User:
Customer type determines contracting structures, risk profiles, and policy exposure for Greek solar developers.
- Industrial Facilities:Aluminum and cement manufacturers in Thessaloniki manufacturing clusters contract directly with solar parks for baseload supply, displacing traditional feed-in tariff dependency. Carbon border adjustment exposure drives procurement urgency.
- Government:Public buildings and military installations procure through centralized tenders managed by the General Secretariat for Public Investment.
- Households:Residential consumers face self-consumption compensation rate limits that compress payback periods and financing attractiveness.
- Businesses:Small and medium enterprises in retail and services segments lag industrial offtakers in PPA sophistication.
Contracting maturity concentrates in Industrial Facilities. Households show the steepest expansion constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polysilicon feedstock flows from Xinjiang and Inner Mongolia anchor photovoltaic manufacturing economics across Mediterranean solar markets. Grid interconnection velocity and land-use policy divergence now differentiate national deployment trajectories.
Germany
Industrial offtakers in the Ruhr and Bavaria drive corporate PPA procurement for aluminum and automotive supply chains. The EEG 2023 revision accelerates tender timelines for ground-mounted solar parks. Brandenburg's former lignite mining regions host gigawatt-scale renewable clusters repurposing brownfield infrastructure.
Spain
Utility-scale developers exploit Extremadura and Andalusia's high irradiance and streamlined environmental licensing. The National Integrated Energy and Climate Plan mandates renewable capacity auctions with storage co-location requirements. Zaragoza's logistics corridor concentrates bilateral industrial contracts for cement and steel producers.
Italy
Agricultural land availability in Apulia and Sicily enables agrivoltaic pilot programs under revised spatial planning exemptions. The National Recovery and Resilience Plan channels EU funds toward southern region grid reinforcement. Catania's semiconductor manufacturing base supports domestic module assembly capacity expansion.
Portugal
Alentejo's arid plains attract bifacial array deployments leveraging high albedo reflection from dry terrain. The Simplex+ program compresses licensing timelines for renewable projects in designated acceleration zones. Sines industrial complex anchors green hydrogen electrolyzer demand tied to solar procurement.
Greece Solar Energy Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue hybrid storage integration and agrivoltaic specialization. Greek solar development concentrates around three strategic archetypes: incumbent utilities leveraging grid relationships, European energy majors deploying balance-sheet capacity, and specialized engineering contractors targeting complex terrain installations. Consolidation pressures intensify as interconnection queue priority becomes the scarce resource. Competitive moves center on strategic partnerships with transmission operators and backward integration into EPC capabilities.
Within the incumbent utility tier, PPC Renewables exemplifies grid-access advantage through established HEDNO relationships. European majors including TotalEnergies and RWE Renewables occupy the capital-deployment archetype, channeling project finance toward utility-scale pipeline accumulation. Specialized engineering contractors such as Juwi Holding AG represent the technical-services vector, capturing margin from terrain-complex installations where standardized EPC approaches fail.
| Leading Market Players |
|---|
| PPC Renewables |
| TotalEnergies |
| EDF |
| Terna Energy |
| ELPE Renewables |
| Juwi Holding AG |
| Lightsource BP |
| Enel Green Power |
| RWE Renewables |
| Others |
Value Chain & Pricing Dynamics
Module efficiency tiers bifurcate Greek procurement into premium monocrystalline and commodity polycrystalline streams, with warranty duration and performance guarantees determining both unit economics and supplier selection pathways across Hellenic project pipelines.
Pricing Analysis
Warranty bundling separates Greek solar procurement into integrated service contracts versus bare-equipment transactions. Three-tier pricing structure across premium, standard, and economy levels reflects module efficiency grades and IEC certification tiers. Cost compression in polycrystalline segments is intensifying because Chinese wafer oversupply feeds into Mediterranean spot markets. Industrial offtakers in Thessaloniki manufacturing clusters show least price sensitivity due to carbon border adjustment exposure, while agricultural cooperatives in western Macedonia face acute budget constraints.
Supply Chain Analysis
Specialized inverter firmware engineers concentrate in Germany, China, and Taiwan, constraining Greek EPC commissioning schedules when firmware upgrades require manufacturer certification. Polysilicon feedstock draws from Xinjiang and Inner Mongolia, silicon wafers from Malaysia and Vietnam, and inverters from German and Chinese assembly plants. Single-source vulnerability sits with HEDNO-certified inverter suppliers whose firmware approvals gate grid connection timelines. Distribution runs through ADMIE-sanctioned EPC contractors holding priority interconnection queue positions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Greek solar development is consolidating around interconnection queue priority as the scarce resource, with ADMIE transmission reinforcement timelines forcing weaker developers into joint ventures or asset sales.
For Market Incumbents: Extend grid-access advantages by securing forward positions in HEDNO interconnection queues before ADMIE reinforcement projects unlock new clusters. Backward integration into EPC capabilities captures margin from terrain-complex installations where standardized contractors fail. Juwi Holding AG's engineering specialization represents the entrant archetype threatening incumbent engineering premiums. For New Entrants and Emerging Players: Island microgrid developers represent the most penetrable buyer archetype given captive diesel replacement demand in Crete and the Cyclades. Agrivoltaic pilots under revised spatial planning exemptions unlock Thessaly agricultural zones previously blocked by zoning protections. Direct contracting with olive cooperatives bypasses utility-scale queue competition entirely. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid solar-storage developers given auxiliary services market framework enhancements. Long-term viability favors IPPs with secured land positions in western Macedonia and Peloponnese corridors. The signal to watch is ADMIE transmission upgrade completion announcements that unlock previously constrained substation capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Grid Interconnection Queue Positioning | ADMIE priority queue access determines project viability and capital allocation sequencing. |
| Hybrid Storage Co-location | Lithium-ion systems qualify for enhanced auxiliary services contracts under HEDNO frameworks. |
| Agrivoltaic Pilot Development | Dual-use installations unlock restricted agricultural lands under revised spatial planning exemptions. |
| EPC Capability Integration | In-house engineering-procurement-construction control compresses commissioning timelines for complex terrain. |
| Corporate PPA Direct Contracting | Bilateral agreements with aluminum and cement manufacturers displace feed-in tariff dependency. |
Study Parameters
Document review covered ADMIE interconnection databases, HEDNO regulatory filings, and EU Green Deal implementation reports, complemented by interviews with IPP project developers, EPC contractors, utility planning officers, and grid operators. Secondary validation drew from IEA renewable energy statistics, European Commission energy transition databases, and national energy regulator disclosures. Bottom-up project pipeline aggregation and top-down macroeconomic scenario analysis enabled cross-triangulation of market sizing estimates.
Historical capacity deployment patterns were cross-referenced against panel input from industry stakeholders to construct projection scenarios across the analysis window. Segmentation dimensions modeled include technology type, installation scale, end-user category, and regional grid cluster. CAGRs were derived from weighted average growth trajectories incorporating EU renewable target compliance schedules and ADMIE infrastructure investment timelines. Module cost curves and interconnection queue velocity served as primary forecast inputs.
Revisions become necessary when ADMIE transmission reinforcement delays, HEDNO regulatory framework changes, or polysilicon supply disruptions materialize beyond baseline assumptions. Forecasts reflect documented parameters regarding EU Green Deal target trajectories and national spatial planning reforms. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
Switzerland Solar Energy Market
Solar Power Systems
Solar Cell (Photovoltaic) Module Market
Solar Power Systems
Photovoltaic (PV) Materials Market
Solar Power Systems
High-Efficiency Solar Modules Market
Solar Power Systems
Europe Solar Concentrator Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
New Zealand Solar Energy Market
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
Solar Powered Elevator Market
Solar Power Systems
North America Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Laminator Market
Solar Power Systems
Czech Republic Solar Energy Market
Solar Power Systems
Asia Pacific Solar Inverter Market
Solar Power Systems
Solar PV Backsheet Market
Solar Power Systems
Solar Pontoon Market