
 Advanced Fiber-Based Gasket Market | 2026-2036
Advanced Fiber-Based Gasket Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Fiber-Based Gasket Market Outlook
India is fragmenting as new domestic compounders enter the advanced fiber-based gasket supply base. Freudenberg Sealing Technologies leverages its European R&D footprint to sustain aramid fiber formulation leadership. Klinger Group anchors Australasian distribution through localized compression molding capacity. Dana Incorporated competes on automotive platform integration with thermal management system suppliers.
Advanced fiber-based gaskets are engineered sealing components manufactured from aramid, glass, or synthetic fiber matrices bonded with elastomeric or thermoset resins, designed to maintain dimensional stability across temperatures exceeding 300°C and pressures above 100 bar in flanged joints. Their primary industrial purpose is to prevent fluid or gas leakage in critical equipment while withstanding thermal cycling and chemical attack. Non-asbestos gaskets dominate volume as legacy asbestos replacement programs mature across process industries. Metal-infused gaskets capture premium positioning in high-temperature sealing applications where creep resistance determines service life. Composite gaskets represent the fastest-expanding material architecture as hybrid constructions balance compressibility with recovery in chemical processing environments.
EPA emissions enforcement and REACH substance restrictions shape material eligibility for US and European gasket deployments, while India's BIS certification requirements govern import qualification for fiber-reinforced sealing products. The EU F-Gas Regulation indirectly tightens leakage tolerance standards for HVAC system gaskets, expanding specification scope for synthetic fiber grades. Stakeholders must monitor divergence between regional chemical hazard classifications and pressure equipment directives to align product portfolios with jurisdiction-specific compliance thresholds.
Market Dynamics
REACH substance restrictions and EPA emissions enforcement are compressing material eligibility windows, forcing compounders to accelerate aramid and glass fiber formulation validation while asbestos phase-out timelines tighten across automotive and process industries.
Growth Catalysts
- REACH compliance mandates:European chemical safety classifications are disqualifying legacy asbestos-containing components, redirecting specification-intensive procurement toward certified non-asbestos alternatives in German automotive clusters.
- Automotive platform integration:Thermal management system suppliers are consolidating gasket sourcing with advanced fiber grades that withstand exhaust gas recirculation temperatures exceeding 300°C.
- India:Domestic compounders are fragmenting the supply base as BIS certification requirements for fiber-reinforced sealing products create localized qualification pathways for import substitution.
Market Restraints
- Aramid fiber input concentration:Specialty polymer supply is concentrated among limited global producers, exposing compounders to price volatility in high-performance fiber feedstocks.
- Metal-infused gasket substitution ceiling:Premium creep-resistant constructions face technical limitations in compressibility recovery below 100 bar operating pressure, constraining addressable application scope.
- F-Gas Regulation leakage tolerance:EU HVAC system standards are tightening specification scope in ways that favor synthetic fiber grades with validated permeation coefficients, disadvantaging transitional material architectures.
Strategic Opportunities
- Hydrogen infrastructure sealing:High-pressure electrolyzer and fuel cell applications are creating specification white space for composite gasket architectures balancing compressibility with hydrogen embrittlement resistance.
- CE marking acceleration:Pressure equipment directive harmonization is streamlining cross-border qualification for validated fiber formulations, reducing jurisdiction-specific compliance duplication.
- Digital specification platforms:Engineering procurement networks are displacing traditional distributor relationships with direct technical data exchange between compounders and OEM material engineers.
Industry Challenges
- Compression molding technician scarcity:Localized capacity expansion in Australasia and India is constrained by limited availability of operators trained in precision fiber-matrix lamination control.
- Multi-jurisdiction certification timelines:Divergent chemical hazard classifications between EPA, ECHA, and BIS frameworks are elongating product launch cycles for globally specified gasket platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Fiber-Based Gasket Market |
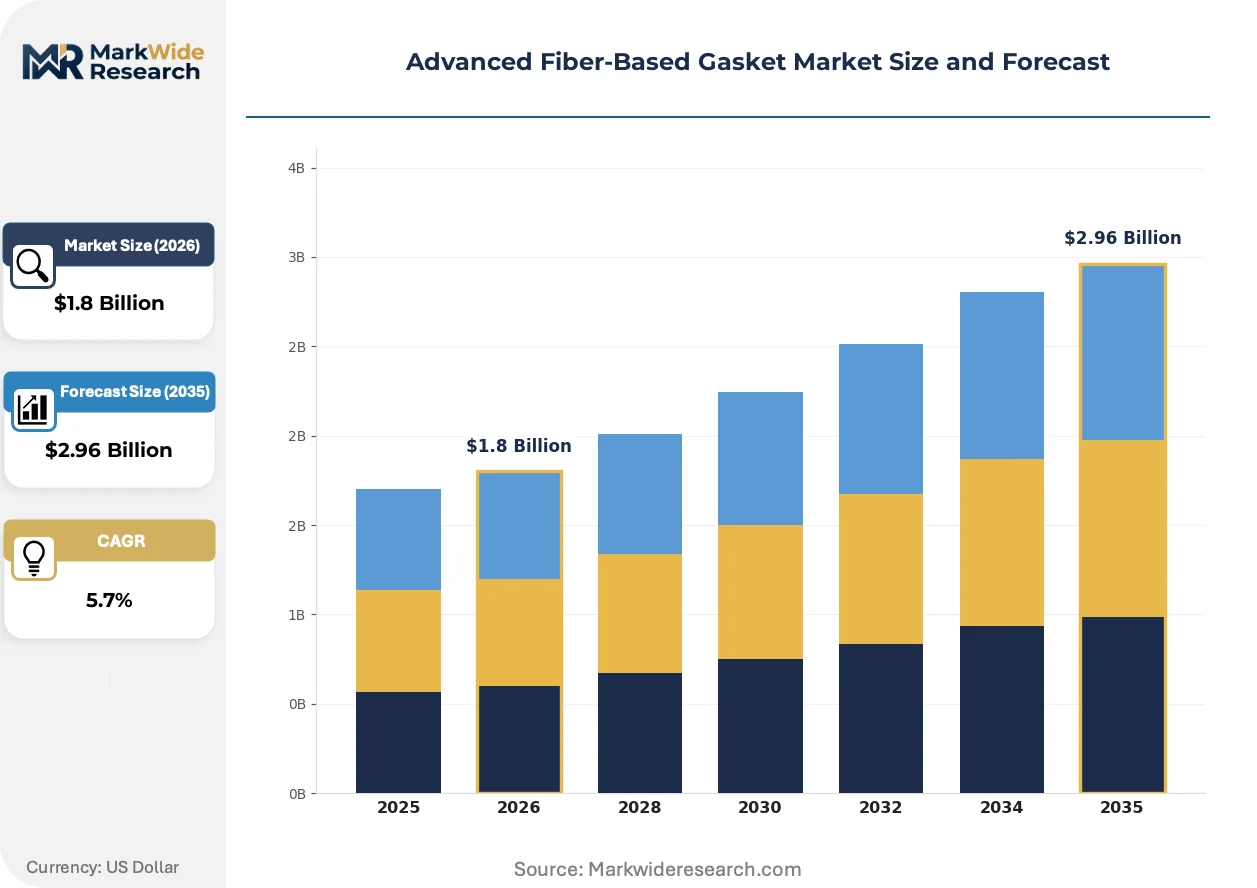
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Asbestos Gaskets, Metal-Infused Gaskets, Composite Gaskets, Organic Gaskets End User: Automotive Sector, Aerospace Industry, Marine Applications, Machinery Manufacturing Application: High-Temperature Sealing, Chemical Processing, Fluid Transfer, HVAC Systems Material: Aramid Fiber, Glass Fiber, Rubber Composite, Synthetic Fiber |
| Companies Covered | Trelleborg AB, Dana Incorporated, ElringKlinger AG, Bal Seal Engineering, Klinger Group, Freudenberg Sealing Technologies, Garlock Sealing Technologies, James Walker Group, Parker Hannifin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Fiber-Based Gasket Market Strategic Shifts
Material science convergence with digital specification workflows is compressing traditional qualification timelines while regulatory hazard reclassifications continuously reset material eligibility boundaries across automotive and process equipment sectors.
Smart manufacturing sensor integration is digitizing quality assurance protocols in compression molding operations. Tier-1 automotive suppliers are adopting real-time thickness and density monitoring at pilot scale. This capability is digitizing batch-to-batch consistency verification, reducing warranty exposure from dimensional drift in high-temperature cycling applications.
EPA emissions enforcement is tightening material disclosure requirements for industrial sealing components in flanged joint applications. Manufacturers must now document fiber matrix composition and resin bonding chemistry for import qualification. Process industries in the US Gulf Coast refining corridor are responding by consolidating supplier relationships with compounders holding validated EPA toxic substance control act premanufacture notifications.
Specification behavior is compressing switching cycles as OEM platform engineering teams centralize material engineering decisions. Traditional distributor technical sales relationships are losing influence to direct compounder-OEM collaboration on thermal cycling validation protocols. German automotive headquarters and precision engineering clusters are most visibly advancing this consolidation, with specification authority concentrating at platform thermal management system integration points.
Advanced Fiber-Based Gasket Market Segmentation
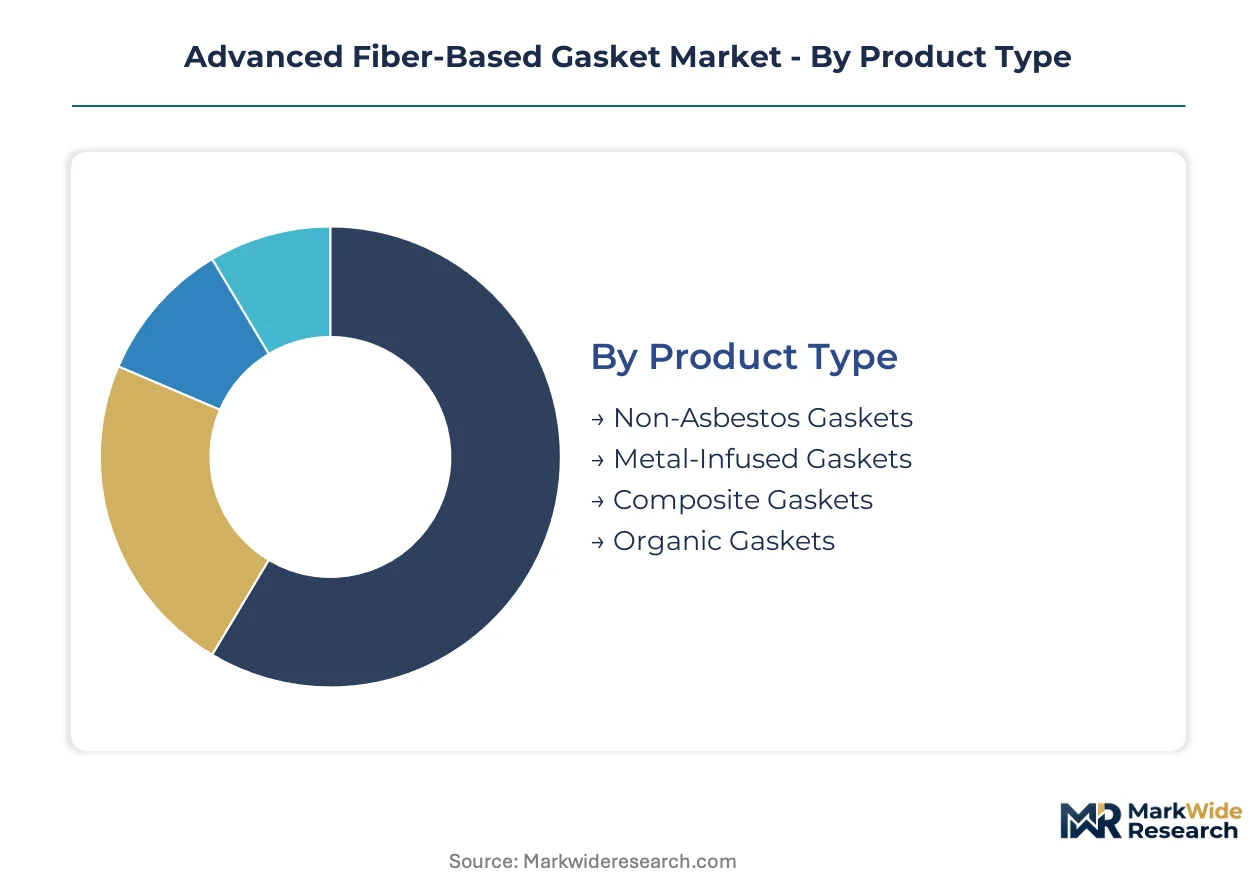
Segmentation in advanced fiber-based gaskets determines procurement pathways, certification requirements, and technical service intensity. Specification engineers prioritize material architecture and end-use thermal cycling demands when qualifying suppliers for platform integration.
Product Type:
After-sales service intensity varies sharply across product architectures, with high-temperature constructions requiring field validation support and warranty tracking that simpler organic formulations rarely demand.
- Non-Asbestos Gaskets:Engineered from aramid, glass, or synthetic fiber matrices bonded with nitrile or EPDM elastomers, these constructions serve as direct asbestos replacements in flanged joints across process industries. Demand concentrates in German automotive clusters where REACH mandates disqualify legacy materials, forcing specification-intensive procurement toward certified alternatives with documented fiber composition.
- Metal-Infused Gaskets:Hybrid constructions embed perforated metal cores within fiber matrices to deliver creep resistance above 300°C and pressures exceeding 100 bar. Procurement gravitates toward US Gulf Coast refining corridors where EPA emissions enforcement tightens disclosure requirements, consolidating supplier relationships with compounders holding validated toxic substance control act premanufacture notifications.
- Composite Gaskets:Multi-layer architectures balance compressibility with recovery through engineered fiber-resin combinations. These formulations are gaining specification share in hydrogen infrastructure sealing where hydrogen embrittlement resistance determines service life.
- Organic Gaskets:Cellulose or cork-rubber bonded constructions serve low-pressure, ambient-temperature applications with minimal technical support requirements. These products compete primarily on price in maintenance-repair-overhaul channels.
Non-asbestos gaskets hold the largest share; momentum sits with composite gaskets.
End User:
Customer type dictates specification authority concentration, with platform-integrated OEMs centralizing material engineering decisions away from traditional distributor relationships.
- Automotive Sector:Exhaust gas recirculation systems and thermal management modules specify fiber grades withstand temperatures exceeding 300°C. German OEM headquarters drive qualification protocols that cascade through tier-1 supplier networks.
- Aerospace Industry:Jet engine sealing and auxiliary power unit applications demand FAA-certified constructions with traceable fiber provenance and batch-to-batch consistency verification through smart manufacturing sensor integration.
- Marine Applications:Diesel engine gaskets and cargo containment sealing in LNG carriers require IMO-compliant formulations resistant to salt corrosion and thermal cycling. Classification society approvals elongate supplier qualification timelines.
- Machinery Manufacturing:Pump, valve, and compressor OEMs specify medium-pressure gaskets with standardized dimensions, prioritizing inventory availability over technical customization.
Automotive sector commands specification authority; aerospace climbs fastest on certification premium capture.
Application:
Volume concentration tracks process industry capital expenditure cycles, with chemical processing and fluid transfer dominating unit demand while high-temperature sealing captures value concentration.
- High-Temperature Sealing:Furnace doors, exhaust manifolds, and turbine housings specify metal-infused or aramid-fiber constructions with validated creep resistance. US refining and German automotive thermal management systems anchor demand.
- Chemical Processing:Reactor flanges and heat exchanger joints require chemically resistant fiber matrices compatible with aggressive process media. REACH substance restrictions continuously reset material eligibility boundaries.
- Fluid Transfer:Pipeline flanges and pump sealing represent high-volume, specification-standardized demand with compressed switching cycles and consolidated sourcing.
- HVAC Systems:EU F-Gas Regulation tightens leakage tolerance standards, expanding specification scope for synthetic fiber grades with validated permeation coefficients.
Chemical processing holds the largest share; high-temperature sealing gains fastest on thermal management integration.
Material:
Supply concentration shapes procurement risk profiles, with aramid fiber feedstock dependence exposing compounders to specialty polymer price volatility from limited global producers.
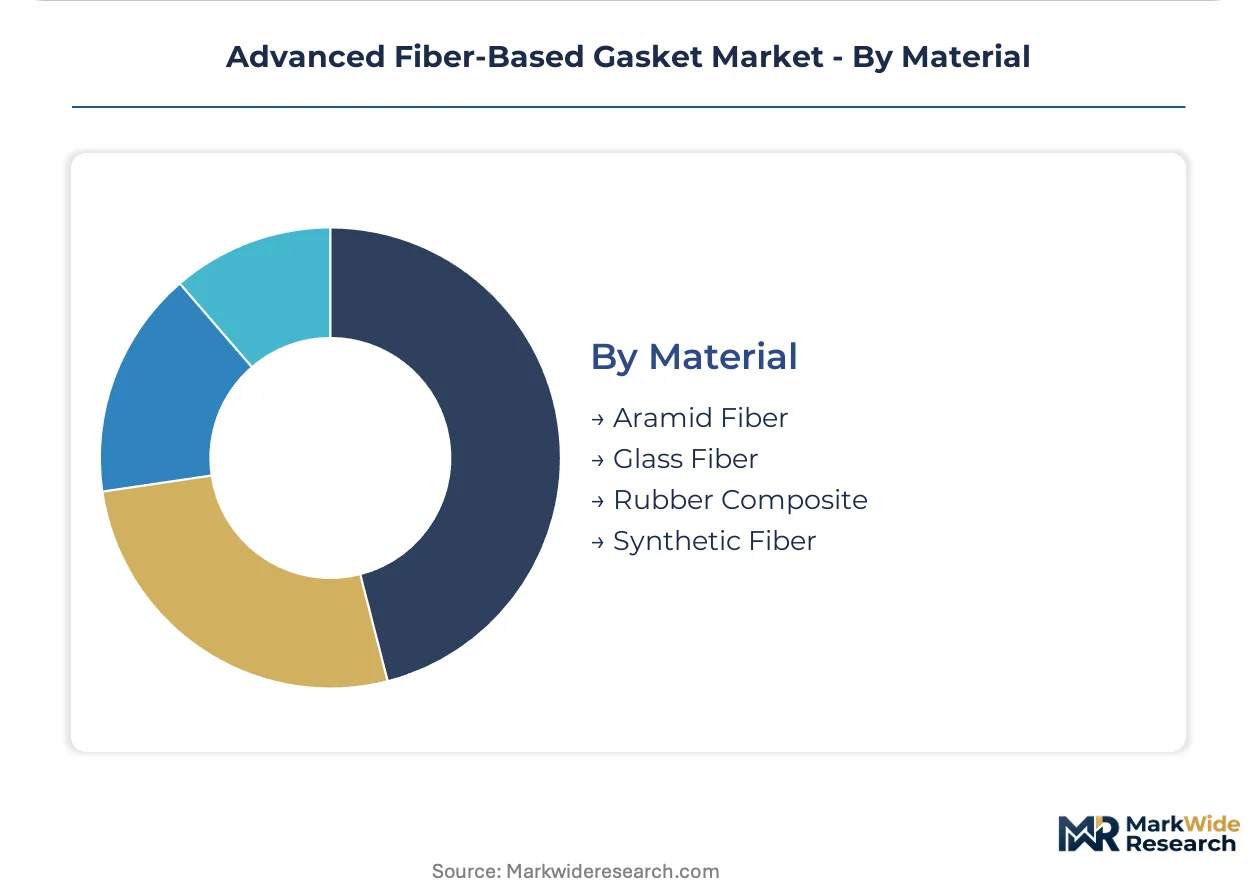
- Aramid Fiber:High-strength synthetic polymer matrices deliver thermal stability above 300°C and chemical resistance in aggressive environments. European compounders leverage R&D proximity to German automotive clusters for formulation leadership.
- Glass Fiber:Cost-effective reinforcement with excellent dimensional stability serves mid-temperature applications. Indian domestic compounders fragment supply base through localized BIS certification pathways.
- Rubber Composite:Elastomer-bonded fiber sheets balance compressibility with conformability in low-to-medium pressure sealing. These formulations dominate maintenance-repair-overhaul procurement.
- Synthetic Fiber:Engineered polymer alternatives including PTFE and carbon fiber serve specialized chemical resistance and conductivity requirements. Specification scope expands under EU F-Gas leakage tolerance tightening.
Aramid fiber holds the largest share; synthetic fiber expands most quickly on regulatory-driven material substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aramid fiber supply concentrates among a handful of specialty polymer producers, forcing compounders to locate formulation capacity near specification-intensive demand clusters. This geographic coupling explains why advanced fiber-based gasket manufacturing gravitates toward German automotive headquarters, US Gulf Coast refining corridors, and Indian domestic compounder networks.
Germany
Precision engineering clusters in Stuttgart and Munich drive specification-intensive procurement for exhaust gas recirculation systems. REACH substance restrictions disqualify legacy asbestos-containing components, redirecting OEM sourcing toward certified non-asbestos alternatives. Freudenberg Sealing Technologies leverages its European R&D footprint to sustain aramid fiber formulation leadership from Weinheim.
United States
EPA emissions enforcement tightens material disclosure requirements for industrial sealing components in flanged joint applications. Toxic Substance Control Act premanufacture notifications determine import qualification eligibility. US Gulf Coast refining corridors consolidate supplier relationships with compounders holding validated EPA documentation.
India
Domestic compounders fragment the supply base as BIS certification requirements for fiber-reinforced sealing products create localized qualification pathways. Klinger Group anchors distribution through compression molding capacity positioned to serve import substitution demand. Maharashtra and Gujarat industrial zones attract new entrant compounders seeking BIS-certified market entry.
China
Process industry capital expenditure cycles concentrate demand in chemical processing and fluid transfer applications. GB standards govern fiber-reinforced sealing product specifications for domestic procurement. Yangtze River Delta manufacturing clusters integrate gasket sourcing with pump and valve OEM supply chains.
Japan
Automotive thermal management system suppliers specify fiber grades with validated batch-to-batch consistency. METI industrial standards shape material eligibility for high-temperature sealing in hybrid vehicle platforms. Kansai and Chubu industrial corridors concentrate tier-1 supplier engineering decisions.
Advanced Fiber-Based Gasket Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in formulation and material science. The vendor base organizes around three archetypes: European compounders with R&D proximity to automotive OEMs, diversified sealing conglomerates with cross-industry portfolio breadth, and regional fabricators leveraging localized certification pathways. Consolidation pressure concentrates among mid-scale compounders seeking thermal management system integration partnerships. Capacity expansion and strategic partnerships dominate competitive moves as players position for hydrogen infrastructure qualification.
Within the European compounder tier, Freudenberg Sealing Technologies and ElringKlinger AG exemplify formulation leadership anchored to German automotive clusters. Dana Incorporated occupies a position among diversified sealing suppliers integrating gasket sourcing with thermal management system platforms. Klinger Group represents the regional fabricator archetype, leveraging Australasian and Indian distribution networks through localized compression molding presence.
| Leading Market Players |
|---|
| Trelleborg AB |
| Dana Incorporated |
| ElringKlinger AG |
| Bal Seal Engineering |
| Klinger Group |
| Freudenberg Sealing Technologies |
| Garlock Sealing Technologies |
| James Walker Group |
| Parker Hannifin |
| Others |
Value Chain & Pricing Dynamics
Aramid fiber feedstock concentration among specialty polymer producers in the United States, Japan, and the Netherlands concentrates upstream margin capture while downstream compounders in Germany and India compete on formulation proximity to specification-intensive buyers. This structural asymmetry forces gasket manufacturers to absorb input volatility or push price adjustments through long-term automotive supply contracts.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across European procurement, separating certified non-asbestos formulations from transitional architectures awaiting full material validation. Three-tier pricing structure across premium metal-infused, standard aramid-fiber, and economy glass-fiber grades reflects certification burden and thermal performance differentiation. Cost compression in standard-grade aramid formulations is intensifying because Indian domestic compounders fragment supply through localized BIS certification pathways. Maintenance-repair-overhaul channels exhibit highest price sensitivity; German automotive OEMs prioritize performance validation over unit cost.
Supply Chain Analysis
Specialty aramid polymer production draws from DuPont and Teijin facilities in the United States and Japan, with glass fiber reinforcement sourcing concentrated in China and Germany. Raw material dependencies include para-aramid pulp, elastomeric binders, and perforated metal cores for hybrid constructions. Single-source vulnerability in high-tenacity aramid fiber exposes compounders to feedstock allocation constraints during capacity tightness. Distribution runs through tier-1 automotive supplier networks and industrial distributor relationships, with direct compounder-OEM collaboration displacing traditional technical sales channels in specification-intensive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced fiber-based gasket incumbents face substitution pressure from metal-to-metal sealing technologies and advanced polymer coatings in hydrogen infrastructure applications. Defense requires locking in platform integration partnerships before alternative architectures achieve qualification.
For Market Incumbents: Harden formulation leadership through backward integration into aramid fiber compounding or captive resin bonding chemistry production. Secure thermal management system integration partnerships with German automotive OEMs before metal-to-metal sealing architectures achieve EGR temperature validation. Anchor capacity expansion in Maharashtra and Gujarat industrial zones to intercept Indian import substitution demand before domestic compounders achieve BIS certification scale. For New Entrants and Emerging Players: Pursue hydrogen infrastructure sealing qualification as specification white space where composite gasket architectures face limited incumbent validation. Target Indian BIS certification pathways in glass-fiber formulations serving chemical processing and fluid transfer applications with compressed technical service requirements. Establish direct engineering procurement network relationships to displace distributor-dependent legacy suppliers in specification digitization. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European compounders holding automotive platform integration contracts but limited hydrogen infrastructure qualification progress. Long-term viability hinges on 5-10 year thermal management system content retention as electrification shifts exhaust gas recirculation architectures. Watch for inflection in hydrogen electrolyzer gasket specification releases from German and Japanese OEMs as signal for composite architecture demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Fiber Compounding | Captures margin pool currently concentrated with DuPont and Teijin specialty polymer operations. |
| Hydrogen Infrastructure Qualification Program | Positions composite gasket architectures for electrolyzer and fuel cell sealing specification white space. |
| Indian BIS Certification Acceleration | Unlocks import substitution demand in Maharashtra and Gujarat industrial corridors before domestic compounders consolidate. |
| Direct OEM Engineering Platform Integration | Displaces distributor relationships through real-time thermal cycling validation data exchange with German automotive headquarters. |
| Smart Manufacturing Sensor Deployment | Digitizes batch-to-batch consistency verification for FAA-certified aerospace gasket traceability requirements. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, tier-1 automotive procurement leads, compression molding operations managers, and industrial distributor technical sales directors and refined through secondary validation against EPA toxic substance control act filings, ECHA REACH substance restriction updates, BIS certification registries, and customs trade data for fiber-reinforced sealing product imports. Bottom-up demand modeling from end-use application volumes was triangulated against top-down market sizing from compounder capacity disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions including material architecture, end-use thermal cycling intensity, certification tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year estimates and cross-checked against industry capital expenditure cycles and OEM platform launch timelines. Forecast inputs incorporated REACH substance restriction phase-out schedules and EPA emissions enforcement intensity assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialty polymer producers to forward-integrate into gasket compounding would shift outcomes through margin compression. Material shifts in hydrogen infrastructure sealing standards or aramid fiber supply allocation priorities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Surface Green Mining Market
Others
Global ESD Protection Devices Market
Others
Molybdenum-99 Market
Others
Latin America Fire Sprinklers Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
Sandbags Market
Others
Embedded Computer Market
Others
Global Solder Balls Market
Others
Hearables Market
Others
Middle East and Africa Cocoa Products Market
Others
Binoculars Market
Others
Fenoxanil Market
Others
Canada Laser Hair Removal Market
Others
Global Enterprise Mobility in Healthcare Market
Others
Griffin Beaker Market
Others
Cremation Furnace Market