
 Southeast Asia Seed Market | 2026-2036
Southeast Asia Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Seed Market Analytics
Gene editing and marker-assisted selection is tilting commercial breeding programs toward precision trait stacking for drought tolerance and disease resistance. Bayer AG leverages its global germplasm libraries to anchor hybrid corn and rice portfolios across the region. East-West Seed specializes in tropical vegetable genetics, sustaining market presence through farmer-extension networks in Indonesia and the Philippines. Corteva Agriscience competes with differentiated biotech trait packages tailored to Southeast Asian pest pressures.
Southeast Asia seed encompasses genetically improved propagules—hybrid or open-pollinated—engineered for specific agronomic performance traits such as germination uniformity, vigor index, and pathogen resistance, supplied to commercial and smallholder producers for crop establishment. Vegetable seeds command premium positioning as greenhouse and protected-culture operations in Vietnam and Thailand expand year-round tomato, pepper, and cucurbit production. Grain seeds remain volume-dominant through rice and corn cultivation, though margin pools concentrate in hybrid segments where intellectual property protections enable proprietary pricing. Distribution through direct sales channels and rural retail networks captures the smallholder majority, while e-commerce platforms are gaining traction among contract-farming aggregators seeking traceable certified stock.
Indonesia's Ministry of Agriculture seed certification requirements, Vietnam's plant variety protection decrees, and the ASEAN Seed and Planting Material Scheme collectively shape market access, quality standards, and cross-border germplasm flows. Thailand's national seed committee enforces field performance standards that filter substandard varieties from commercial channels. Stakeholders must monitor evolving biosafety frameworks for gene-edited crops as regulatory clarity will determine which breeding technologies enter commercial pipelines.
Market Dynamics
Hybrid seed adoption across Thailand, Vietnam, and Indonesia is compressing varietal replacement cycles from five years to eighteen months as climate stress accelerates farmer demand for drought-tolerant genetics.
Growth Catalysts
- ASEAN Seed and Planting Material Scheme:Harmonized cross-border germplasm protocols reduce quarantine delays for certified hybrid rice and corn varieties entering Vietnam and the Philippines.
- Protected-culture vegetable expansion:Greenhouse clusters in Vietnam's Mekong Delta drive year-round demand for high-germination tomato and pepper seeds with uniform vigor indices.
- Marker-assisted selection:Breeding programs stack precision traits for bacterial wilt resistance and heat tolerance, cutting development timelines for tropical vegetable lines.
Market Restraints
- Imported parent line dependency:Thai and Indonesian seed producers rely on germplasm from temperate-zone breeding stations, exposing margins to currency volatility and shipping bottlenecks.
- Field performance standard enforcement:Thailand's national seed committee mandates multi-location trials that add eighteen to twenty-four months to variety registration, delaying commercialization.
- Farmer-saved seed persistence:Open-pollinated rice varieties retain 40-60% of smallholder plantings in Laos and Cambodia, limiting addressable market for proprietary hybrids.
Strategic Opportunities
- Myanmar's underdeveloped certified seed infrastructure:Less than 15% of vegetable and grain plantings use certified stock, creating first-mover advantage for quality-assured distribution networks.
- E-commerce platform penetration:Contract-farming aggregators in Indonesia's Java and Sumatra purchase traceable certified seed through B2B digital marketplaces, bypassing traditional rural retail.
- Gene-edited crop regulatory clarity:Biosafety frameworks under review in the Philippines and Vietnam will determine which CRISPR-derived traits enter commercial pipelines ahead of conventional GMO approval paths.
Industry Challenges
- Field trial technician scarcity:Multi-location performance testing requires agronomists trained in GxE (genotype-by-environment) analysis, a skill set concentrated in Bangkok and Ho Chi Minh City research institutes.
- Seed processing facility capex:Precision grading, coating, and pelleting equipment for vegetable seeds demands USD-denominated capital outlays that strain mid-tier domestic breeders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Seed Market |
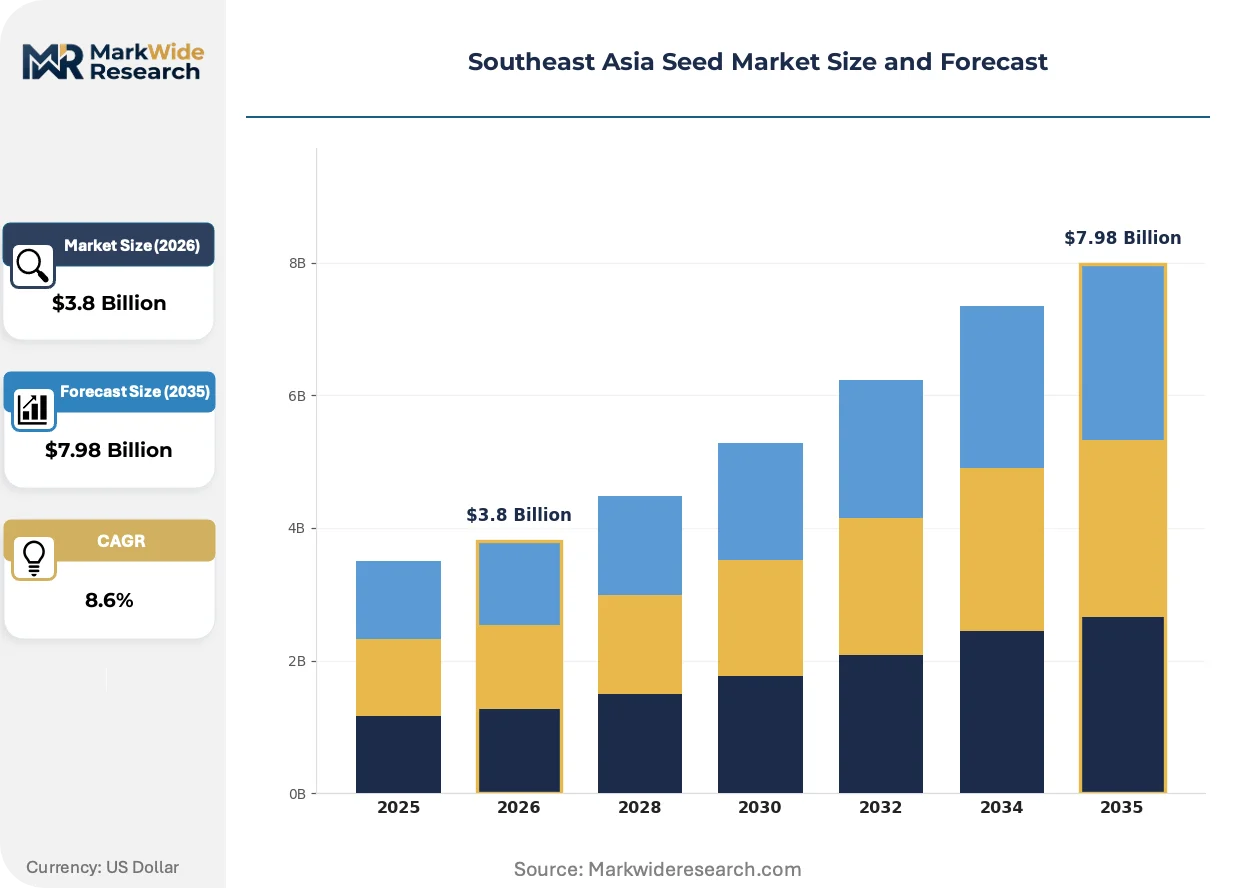
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Seeds, Flower Seeds, Fruit Seeds, Grain Seeds End Use Industry: Agriculture, Horticulture, Agroforestry, Turf Management Distribution Channel: Direct Sales, Retail Stores, E-commerce, Wholesalers Seed Treatment: Coated Seeds, Treated Seeds, Organic Seeds, Non-treated Seeds |
| Companies Covered | Groupe Limagrain, East-West Seed, Bayer AG, Enza Zaden, Rijk Zwaan Zaadteelt en Zaadhandel BV, Syngenta Group, Known You Seed Co. LTD, Corteva Agriscience, Charoen Pokphand Group, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Seed Market Evolving Landscape
Digital phenotyping platforms and climate-adaptive breeding pipelines are compressing the traditional variety development cycle while fragmenting distribution channels away from sole reliance on rural agro-dealer networks.
Speed breeding protocols combining controlled-environment chambers with LED light spectra manipulation is virtualizing the field testing phase for rice and corn lines. Bayer AG and regional breeding stations in Thailand deploy these systems to generate six generations annually versus two in open fields. The technology is compressing time-to-market for heat-tolerant hybrids while reducing land requirements for preliminary yield assessments.
Vietnam's plant variety protection decrees now require distinctness-uniformity-stability documentation for all commercial seed registrations, tightening intellectual property enforcement across the Mekong Delta and Central Highlands. The regulation is forcing domestic seed companies to invest in molecular fingerprinting capabilities or exit proprietary variety markets. Hybrid vegetable segments with shorter product lifecycles face the steepest compliance cost escalation.
Farmer-extension networks are fragmenting as agro-input aggregators in Indonesia and the Philippines consolidate procurement decisions for smallholder cooperatives. These intermediaries now specify certified seed lots with traceable batch codes, displacing anonymous bulk purchases through village-level retailers. The behavioral shift is most visible in East Java's shallot and chili contracting clusters where packer-exporters mandate varietal uniformity for export-grade harvests.
Southeast Asia Seed Market Segmentation
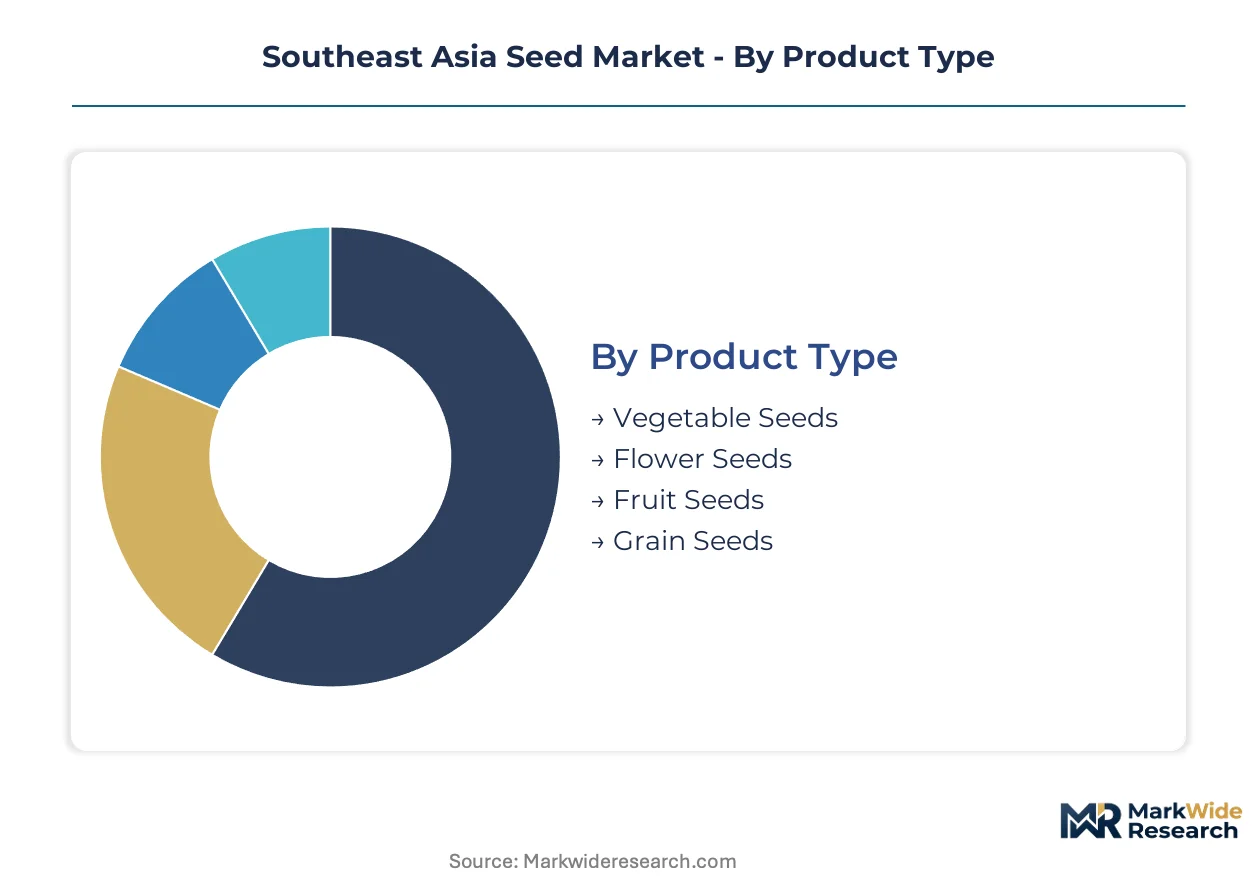
Southeast Asian seed procurement patterns diverge sharply between smallholder subsistence systems and commercial contract-farming operations, creating distinct service intensity requirements across product categories. Segmentation clarity enables suppliers to align breeding investments, distribution infrastructure, and farmer-extension resources with the specific performance demands of each buyer cluster.
Product Type:
After-sales technical support intensity varies dramatically across seed categories, with vegetable genetics requiring sustained agronomic advisory while grain seeds demand minimal post-purchase engagement.
- Vegetable Seeds:Hybrid tomato, pepper, and cucurbit varieties engineered for greenhouse vigor indices and bacterial wilt resistance command premium positioning. Protected-culture clusters in Vietnam's Mekong Delta and Thailand's Central Plains drive replacement cycles as packer-exporters mandate varietal uniformity for export-grade harvests.
- Grain Seeds:Hybrid rice and corn propagules dominate volume flows through national procurement programs and commercial aggregator channels. Indonesia's Ministry of Agriculture certification requirements and Vietnam's plant variety protection decrees shape registration timelines and intellectual property enforcement for proprietary lines.
- Flower Seeds:Ornamental genetics for cut-flower export operations concentrate in Thailand's Chiang Mai and Vietnam's Da Lat highland clusters.
- Fruit Seeds:Propagules for durian, mango, and dragon fruit establishment serve orchard replanting cycles and new plantation development in Indonesia's Sumatra and the Philippines' Mindanao.
By volume, grain seeds lead procurement flows across ASEAN member states. By growth pace, vegetable seeds are expanding most quickly as greenhouse infrastructure proliferates.
End Use Industry:
Application-specific performance benchmarks create tiered pricing structures, with horticulture and turf management segments absorbing technology premiums unavailable in broad-acre agriculture.
- Agriculture:Field crop establishment for rice, corn, and soybean cultivation serves the smallholder majority through government subsidy channels and rural retail networks. National seed committees in Thailand and Indonesia enforce multi-location trial requirements that filter substandard varieties from commercial distribution.
- Horticulture:Intensive vegetable and fruit production systems in Vietnam's Mekong Delta and Indonesia's Java demand certified stock with traceable batch codes and documented germination uniformity. Contract-farming aggregators now specify varietal parameters directly, displacing anonymous bulk purchases through traditional village-level retailers.
- Agroforestry:Timber and multipurpose tree establishment for carbon sequestration and watershed restoration programs in the Philippines and Laos operates through development-funded procurement channels.
- Turf Management:Golf course and sports field establishment in Thailand's tourism corridors and Singapore's recreational infrastructure requires specialized grass genetics with defined wear tolerance specifications.
Agriculture captures the largest addressable volume. Horticulture generates the steepest margin expansion trajectory as protected-culture investment accelerates.
Distribution Channel:
Channel selection directly determines customer acquisition economics and inventory risk profiles, with digital platforms fragmenting traditional agro-dealer dominance among commercial buyers.
- Direct Sales:Breeder-to-grower relationships serve large-scale contract farming operations and multinational plantation companies with customized variety portfolios and dedicated technical support. Bayer AG and Corteva Agriscience deploy agronomist teams for direct engagement with Thai and Indonesian corn seed buyers.
- E-commerce:B2B digital marketplaces enable traceable certified seed procurement for Indonesian Java and Sumatra aggregators seeking batch-coded inventory with documented chain of custody. Platform penetration remains concentrated among younger commercial operators with smartphone access and formal banking relationships.
- Retail Stores:Rural agro-dealer networks maintain smallholder reach in Laos and Cambodia where open-pollinated rice varieties retain significant planting share and farmer-saved seed persistence limits proprietary hybrid penetration.
- Wholesalers:Regional distributors consolidate inventory for remote island provinces and secondary markets with limited direct breeder presence.
Retail stores still move the greatest transaction volume. E-commerce channels are gaining share fastest among commercial horticulture buyers.
Seed Treatment:
Treatment category selection reflects regulatory pressure on chemical inputs and buyer willingness to pay for establishment security, with organic certification requirements reshaping product mix in export-oriented supply chains.
- Coated Seeds:Polymer-encapsulated propagules with integrated micronutrient and protectant layers improve flowability for precision planting equipment and reduce dust exposure during handling. Vegetable seed processors in Thailand and Vietnam deploy coating technology to differentiate premium price tiers.
- Treated Seeds:Conventional chemical dressing for fungal and insect protection remains standard for grain seed flows through government distribution programs, though residue monitoring for export-bound harvests is tightening application protocols.
- Organic Seeds:Uncertified and certified organic propagules serve premium vegetable export operations in Vietnam and the Philippines supplying EU and North American markets with compliance documentation requirements.
- Non-treated Seeds:Bare seed for farmer-applied custom treatment or low-input systems persists in subsistence rice cultivation across Cambodia and Myanmar's underdeveloped certified seed infrastructure.
Treated seeds dominate current volume flows. Coated seeds are climbing the fastest as precision planting technology spreads through commercial vegetable operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial vegetable farming operations and contract-farming aggregators concentrate procurement power across Thailand, Vietnam, and Indonesia, while smallholder subsistence systems in neighboring markets retain open-pollinated seed persistence that limits proprietary hybrid penetration.
Thailand
Greenhouse clusters in the Central Plains drive replacement cycles for hybrid tomato and pepper varieties with bacterial wilt resistance. The national seed committee enforces multi-location field performance standards that filter substandard varieties from commercial channels. Bangkok-based research institutes concentrate agronomist expertise for genotype-by-environment analysis required in variety registration.
Vietnam
Intensive horticulture operations in the Mekong Delta mandate certified stock with traceable batch codes for export-grade harvests. Plant variety protection decrees now require distinctness-uniformity-stability documentation for all commercial seed registrations. Da Lat highland clusters sustain ornamental genetics demand for cut-flower export operations.
Indonesia
Contract-farming aggregators in Java and Sumatra purchase traceable certified seed through B2B digital marketplaces, bypassing traditional rural retail networks. The Ministry of Agriculture certification requirements shape registration timelines for proprietary lines. East Java's shallot and chili contracting clusters enforce varietal uniformity through packer-exporter specifications.
Philippines
Farmer-extension networks fragment as agro-input aggregators consolidate procurement decisions for smallholder cooperatives. Biosafety frameworks under review will determine which CRISPR-derived traits enter commercial pipelines ahead of conventional GMO approval paths. Mindanao orchard development sustains propagule demand for durian and dragon fruit establishment.
Myanmar
Less than 15 percent of vegetable and grain plantings use certified stock, creating first-mover advantage for quality-assured distribution networks. Underdeveloped certified seed infrastructure persists across subsistence rice cultivation systems. Yangon-based intermediaries represent the primary commercial channel for hybrid corn and vegetable genetics entering from neighboring markets.
Southeast Asia Seed Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distribution tiers, creating a tiered structure where global germplasm libraries anchor premium positioning while regional breeding stations serve cost-sensitive segments. Multinational agrochemical conglomerates occupy the proprietary hybrid tier through direct sales agronomist teams. Domestic seed companies and cooperative breeding networks concentrate in open-pollinated and public variety segments. Capacity expansion in precision grading and coating equipment represents the dominant competitive move, alongside strategic partnerships for germplasm access.
Within the global germplasm tier, Bayer AG and Corteva Agriscience exemplify multinational scale advantages in hybrid corn and rice portfolios. East-West Seed occupies a specialist position in tropical vegetable genetics through farmer-extension network density. Among Dutch-based vegetable breeding specialists, Rijk Zwaan Zaadteelt en Zaadhandel BV and Enza Zaden represent precision trait development capabilities for protected-culture systems. Syngenta Group anchors the integrated crop protection and seed technology vector across ASEAN commercial farming operations.
| Leading Market Players |
|---|
| Groupe Limagrain |
| East-West Seed |
| Bayer AG |
| Enza Zaden |
| Rijk Zwaan Zaadteelt en Zaadhandel BV |
| Syngenta Group |
| Known You Seed Co. LTD |
| Corteva Agriscience |
| Charoen Pokphand Group |
| Others |
Value Network & Pricing Analysis
Undercapacity in Vietnam's precision seed processing infrastructure drives supplier prioritization toward large contract-farming aggregators and compresses margins for mid-tier domestic breeders unable to secure coating and pelleting equipment slots. This utilization squeeze simultaneously elevates pricing power for certified hybrid vegetable genetics while forcing price concessions in open-pollinated grain seed segments where excess milling capacity persists.
Pricing Analysis
Cost-plus contracts with parent line import cost indexation dominate hybrid corn and rice procurement between Thai seed producers and European breeding stations. Price differentiation rests on germination uniformity certification tiers and varietal performance documentation depth, with Vietnam's plant variety protection decrees adding compliance cost premiums to proprietary lines. Pricing pressure intensifies in vegetable seed segments as Indonesian e-commerce platforms enable direct breeder-to-aggregator comparisons that erode traditional retail markups. Smallholder rice growers in Laos and Cambodia exhibit highest price sensitivity, while greenhouse operators in Thailand's Central Plains absorb technology premiums for bacterial wilt-resistant tomato genetics.
Supply Chain Analysis
Currency volatility between Thai baht and euro-denominated parent line invoices dominates supply chain risk for hybrid corn breeders dependent on temperate-zone germplasm libraries. Geographic concentration centers on Thailand's Central Plains processing clusters, Vietnam's Mekong Delta distribution hubs, and Indonesia's Java-based coating facilities. Raw material dependencies encompass hybrid parent seeds, polymer coating substrates, and micronutrient formulations for precision grading operations. Distribution runs through direct sales agronomist teams for multinational accounts, B2B digital marketplaces for Indonesian aggregators, and rural agro-dealer networks capturing smallholder majorities in Cambodia and Myanmar.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene-edited crop regulatory clarity in the Philippines and Vietnam constitutes a high-growth disruption inflection that will bifurcate competitive positioning between CRISPR-enabled breeders and conventional GMO-dependent players across the analysis window.
For Market Incumbents: Insulate proprietary hybrid portfolios by deepening backward integration into tropical vegetable breeding stations in Indonesia and Thailand, reducing exposure to currency-denominated parent line imports. Secure molecular fingerprinting capabilities ahead of Vietnam's distinctness-uniformity-stability documentation mandates to filter domestic competitors from premium variety markets. Prioritize capacity expansion in precision coating equipment to capture margin pools shifting toward certified greenhouse vegetable genetics. For New Entrants and Emerging Players: Myanmar's underdeveloped certified seed infrastructure, where less than fifteen percent of plantings use quality-assured stock, offers first-mover positioning for traceable distribution networks bypassing Yangon-based intermediaries. Target contract-farming aggregators in East Java's shallot and chili clusters with batch-coded inventory and documented chain of custody that satisfies packer-exporter uniformity mandates. Deploy B2B digital marketplace participation as the primary go-to-market angle to displace anonymous bulk purchases through village-level retailers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vegetable seed specialists with farmer-extension network density that sustains varietal replacement cycles through technical advisory bundling. Long-term viability favors acquisition targets possessing tropical germplasm libraries and established multi-location trial capabilities for genotype-by-environment analysis. Monitor biosafety framework finalization in Vietnam and the Philippines as the critical inflection signal determining which CRISPR-derived traits achieve commercial pipeline entry ahead of conventional GMO approval timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Coating Capacity Expansion | Captures premium pricing tiers as Vietnamese greenhouse operators demand flowability-optimized vegetable seed. |
| Farmer-Extension Network Deepening | Secures replacement cycle loyalty through bacterial wilt resistance advisory in Indonesia's chili contracting clusters. |
| Molecular Fingerprinting Investment | Enables compliance with Vietnam's plant variety protection decrees filtering non-documented varieties from registration. |
| Direct E-Commerce Platform Integration | Bypasses rural retail markups for Indonesian Java and Sumatra contract-farming aggregators seeking traceable stock. |
| Tropical Germplasm Library Acquisition | Anchors heat-tolerant hybrid development pipelines independent of temperate-zone parent line import dependencies. |
Research Methodology
Operator-level perspectives from seed processing facility managers, contract-farming aggregator procurement officers, national seed committee regulators, and tropical breeding station agronomists anchored the qualitative base for this study. Primary interview insights combined with secondary validation from ASEAN Seed and Planting Material Scheme documentation, Thailand's national seed committee field performance standards, Vietnam's plant variety protection decree filings, and Indonesia's Ministry of Agriculture certification protocols. Bottom-up variety registration timelines and top-down germplasm trade flow estimates underwent triangulation to reconcile supply-side capacity with demand segmentation.
Scenario-bracketing around gene-edited crop regulatory clarity and climate stress acceleration shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, end-use industry, distribution channel, and seed treatment category alongside breeder-to-grower relationship intensity tiers. CAGRs derived from varietal replacement cycle compression rates and protected-culture expansion trajectories. Forecast inputs incorporated hybrid adoption curves in Myanmar's underdeveloped certified seed infrastructure and e-commerce platform penetration rates among Indonesian commercial aggregators.
Practitioners should monitor biosafety framework finalization timelines and parent line import cost volatility for early signals of competitive positioning shifts. Forecasts reflect assumptions regarding regulatory clarity trajectories and currency stability between ASEAN member states and temperate-zone germplasm source markets. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
China Seed Market
Seeds
Europe Sesame Seed Market
Seeds
Cotton Seed Treatment Market
Seeds
Caraway Seeds Market
Seeds
Custom Selected Seed Market
Seeds
Cherry Tomato Seeds Market
Seeds
Asia-Pacific Onion Seed Market
Seeds
Fruit Seed Waste Market
Seeds
Mexico Vegetable Seed Market
Seeds
North America Chia Seeds Market
Seeds
Glycine Soja (Soybean) Seed Extract Market
Seeds
South America Quinoa Seeds Market
Seeds
Africa Chia Seeds Market
Seeds
North America Tomato Seed Market
Seeds
Australia Forage Seed Market
Seeds
Morocco Seed Market