
 United States Forage Seed Market | 2026-2036
United States Forage Seed Market Size, Share, and Industry Trends Forecast 2026-2036
United States Forage Seed Market Analytics
Great Plains seed producers is rebalancing contracted acreage toward certified legume varieties after two seasons of poor germination rates. DLF Seeds A/S leverages its North American breeding stations to sustain proprietary alfalfa germplasm lines. Forage Genetics International LLC anchors the dairy corridor with high-performance silage varieties. Corteva Agriscience competes through stacked trait platforms that differentiate on winter hardiness and disease resistance.
Forage seed comprises the reproductive material of grasses, legumes, and clovers bred for livestock feed, soil stabilization, and ecosystem restoration, typically evaluated by germination percentage, purity standards, and seedling vigor indices under AOSA testing protocols. Its primary commercial purpose centers on establishing perennial pastures and hay fields that convert solar energy into digestible protein for ruminant agriculture. Grasses and legumes together form the dominant product pairing, with legumes commanding margin premiums due to nitrogen-fixation benefits that reduce synthetic fertilizer dependency. Dairy farming represents the most concentrated use case, where high-energy forage varieties directly influence milk production economics and herd nutritional management.
The USDA Agricultural Marketing Service enforces Federal Seed Act labeling requirements that govern germination claims and noxious weed tolerances, while state departments of agriculture in Wisconsin and California administer additional certification protocols for foundation and registered seed classes. The EPA evaluates plant-incorporated protectants and novel trait introductions through its biotechnology regulatory framework, creating compliance thresholds that shape R&D investment and product commercialization timelines. Stakeholders must monitor evolving state water quality regulations and carbon credit mechanisms, as nutrient management plans and soil carbon protocols increasingly influence forage species selection and establishment practices.
Market Dynamics
Dairy operators across Wisconsin and Minnesota are consolidating feed sourcing through vertically integrated forage programs, compressing procurement cycles and raising the bar for certified seed performance guarantees. This buyer concentration is restructuring supplier relationships around multi-year varietal contracts rather than spot purchases.
Growth Catalysts
- USDA National Organic Program:Expanding certified organic acreage mandates foundation-grade seed stocks, pulling premium legume varieties into rotation planning across the Upper Midwest.
- Alfalfa-grass mixtures:Dairy nutritionists are prescribing higher legume ratios in silage rations to boost protein content and reduce purchased concentrate costs.
- Soil carbon protocols:Perennial forage establishment qualifies for emerging carbon credit verification, incentivizing long-term pasture investments in the Corn Belt.
Market Restraints
- Foundation seed supply concentration:Limited certified production acreage in Idaho and Oregon creates bottlenecks for high-germination legume varieties.
- Synthetic nitrogen price volatility:Fertilizer cost swings distort the economic calculus of nitrogen-fixing forage adoption versus annual grain alternatives.
- APHIS biotechnology regulations:Trait approval timelines for novel alfalfa genetics extend commercialization windows beyond typical R&D depreciation schedules.
Strategic Opportunities
- Cover crop integration:Double-cropping winter cereals with annual forage brassicas opens new revenue streams for seed dealers in the Mid-Atlantic dairy corridor.
- State water quality mandates:Wisconsin's nutrient management rules are mandating buffer strips, creating pull for low-input grass seed mixtures on marginal acres.
- Precision planting technology:Drone-based seeding of irregular pastures is reducing establishment costs for rotational grazing operations in the Ozark Highlands.
Industry Challenges
- Seed pathology diagnostics:Accelerated AOSA testing protocols require upgraded laboratory infrastructure that smaller state certification programs struggle to fund.
- Genetic purity enforcement:Cross-pollination risks in alfalfa seed production districts demand isolation distances that fragment contract growing arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Forage Seed Market |
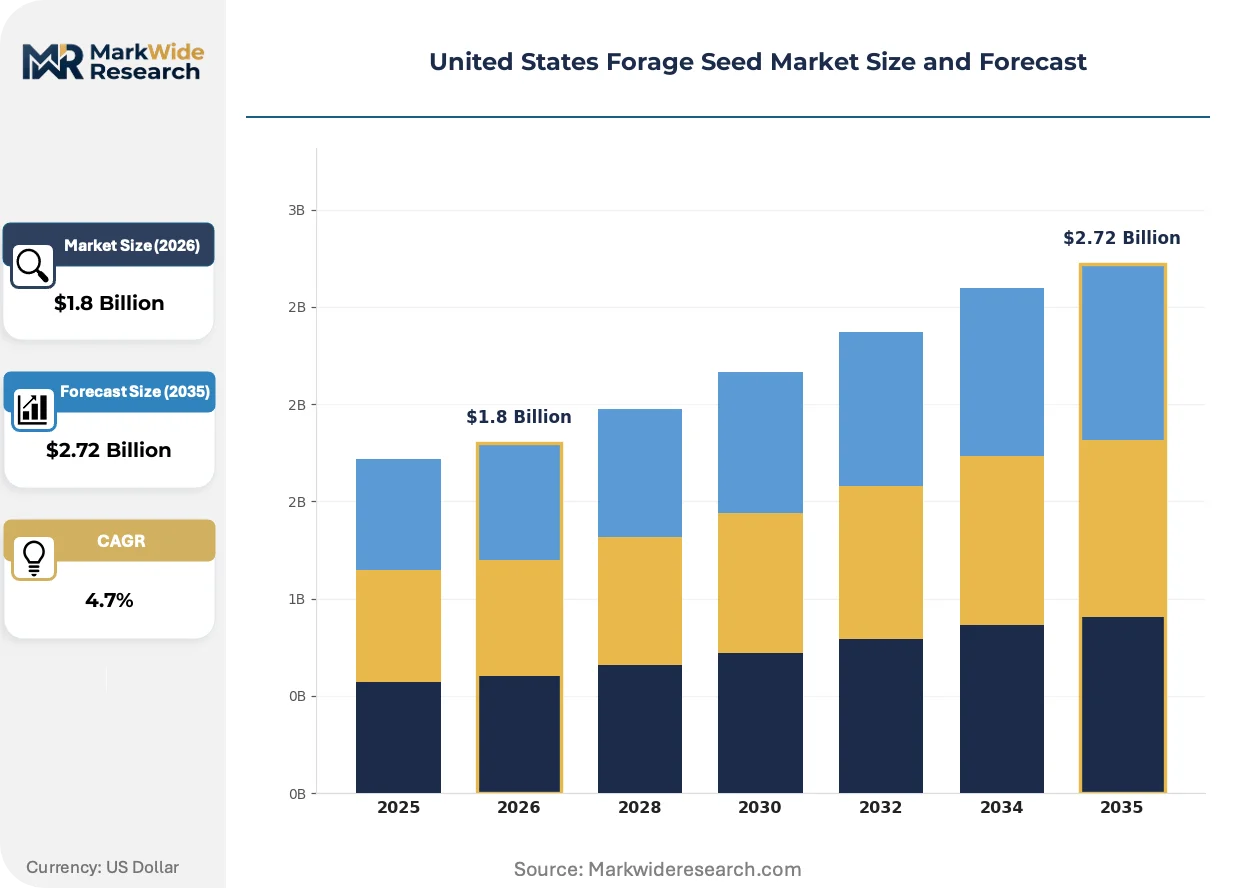
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grasses, Legumes, Clovers, Mixtures Use Case: Dairy Farming, Beef Production, Erosion Control, Wildlife Habitat Packaging Type: Bags, Bulk, Flexible Packaging, Retail Pack Distribution Channel: Wholesale, Retail, E-commerce, Direct Sales |
| Companies Covered | DLF Seeds A/S, Forage Genetics International LLC, Allied Seed LLC, Brett Young Seed Company, UPL, Corteva Agriscience, Royal Barenbrug Group, S&W Seed Co., Bayer AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Forage Seed Market Evolving Landscape
Digital phenotyping and remote sensing are compressing variety development cycles while shifting selection criteria toward stress tolerance metrics. Breeders now prioritize multi-year stand persistence over first-year yield maximization.
Genomic selection platforms are decentralizing breeding decisions away from centralized station trials. Regional seed cooperatives in the Dakotas are deploying marker-assisted selection to adapt proprietary germplasm to local soil conditions. This capability diffusion is fragmenting varietal market share and elevating region-specific performance claims.
The EPA's plant-incorporated protectant framework is tightening data requirements for novel trait submissions. Developers must now submit multi-year environmental fate studies before commercial release, extending regulatory timelines. Smaller breeding programs are responding by licensing stacked traits from technology providers rather than pursuing independent deregistration.
Direct contracting between dairy processors and seed suppliers is displacing traditional dealer networks in the Upper Midwest. Large cooperatives in Wisconsin are negotiating volume commitments that bundle genetics, establishment services, and nutritional consulting. This channel consolidation is squeezing independent retail margins while locking in varietal loyalty at the farm level.
United States Forage Seed Market Segmentation
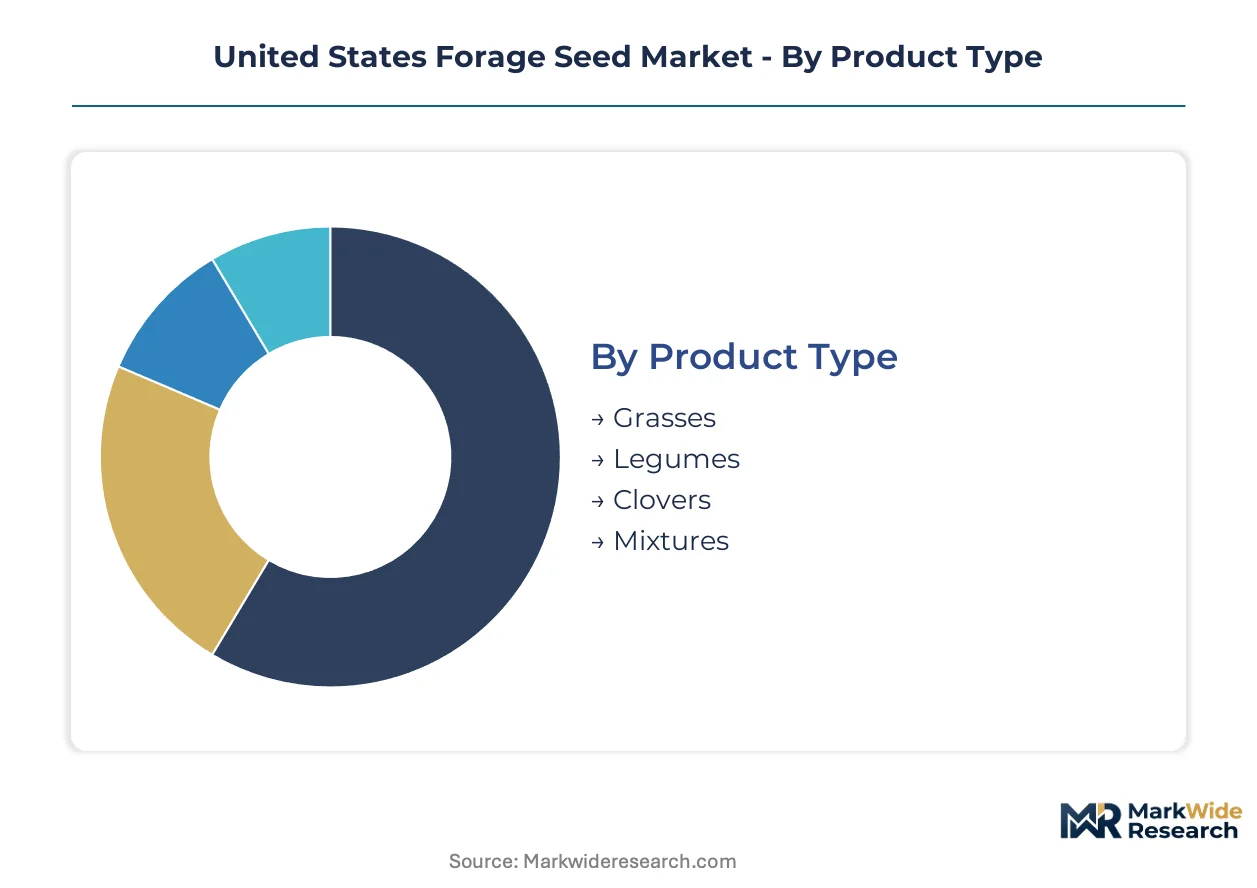
Segmentation in the United States forage seed market reveals how certification requirements, procurement scale, and end-use specifications reshape supplier economics. Each dimension carries distinct regulatory burdens and margin structures that determine competitive positioning.
Product Type:
USDA certification protocols under the Federal Seed Act impose differential testing burdens across product categories, with legume varieties requiring the most rigorous germination verification and genetic purity documentation.
- Grasses:Cool-season and warm-season perennial grasses dominate acreage in the Upper Midwest and Great Plains. Dairy operators in Wisconsin and Minnesota favor orchardgrass and tall fescue for silage compatibility with alfalfa. Demand concentrates where soil carbon protocols incentivize long-term perennial establishment.
- Legumes:Alfalfa and clover varieties command premium positioning due to nitrogen-fixation capacity that reduces synthetic fertilizer dependency. Certified organic dairy operations across the Corn Belt mandate foundation-grade legume seed stocks, tightening supply chains for high-germination varieties.
- Clovers:Red and white clover serve as companion species in pasture renovation programs.
- Mixtures:Pre-formulated grass-legume blends streamline establishment for rotational grazing operations.
Leading the category by volume: Grasses. Growing fastest: Legumes.
Use Case:
End-use concentration determines pricing power, with vertically integrated dairy programs compressing procurement cycles and demanding performance guarantees that smaller beef operations rarely negotiate.
- Dairy Farming:Concentrated livestock operations across Wisconsin's dairy corridor drive varietal selection toward high-energy silage varieties with proven stand persistence. Direct contracting between dairy cooperatives and seed suppliers is displacing traditional dealer networks, locking in multi-year volume commitments.
- Beef Production:Cow-calf operations in the Ozark Highlands and Northern Plains prioritize cost-efficient pasture establishment over nutritional optimization.
- Erosion Control:State water quality mandates in Wisconsin and Minnesota are mandating vegetative buffer strips on marginal acres, creating pull for low-input grass seed mixtures.
- Wildlife Habitat:Conservation reserve programs and private land restoration projects favor native grass and forb mixtures.
Dairy Farming captures the steepest expansion trajectory. Erosion Control is gaining share fastest.
Packaging Type:
Scale of operation dictates packaging economics, with commercial farms absorbing bulk logistics costs that retail-packaged products transfer to smaller acreage holders.
- Bags:Standard 50-pound polywoven bags remain the default for mid-scale operations purchasing through dealer networks.
- Bulk:Direct-delivered bulk seed dominates large dairy and beef operations with on-farm storage infrastructure.
- Flexible Packaging:Multi-wall paper and film laminates serve specialty organic and certified seed segments requiring moisture barrier protection.
- Retail Pack:Small-format packaging for hobby farms and equine operations carries the highest per-pound markup.
Bulk leads by volume. Flexible Packaging is climbing the fastest.
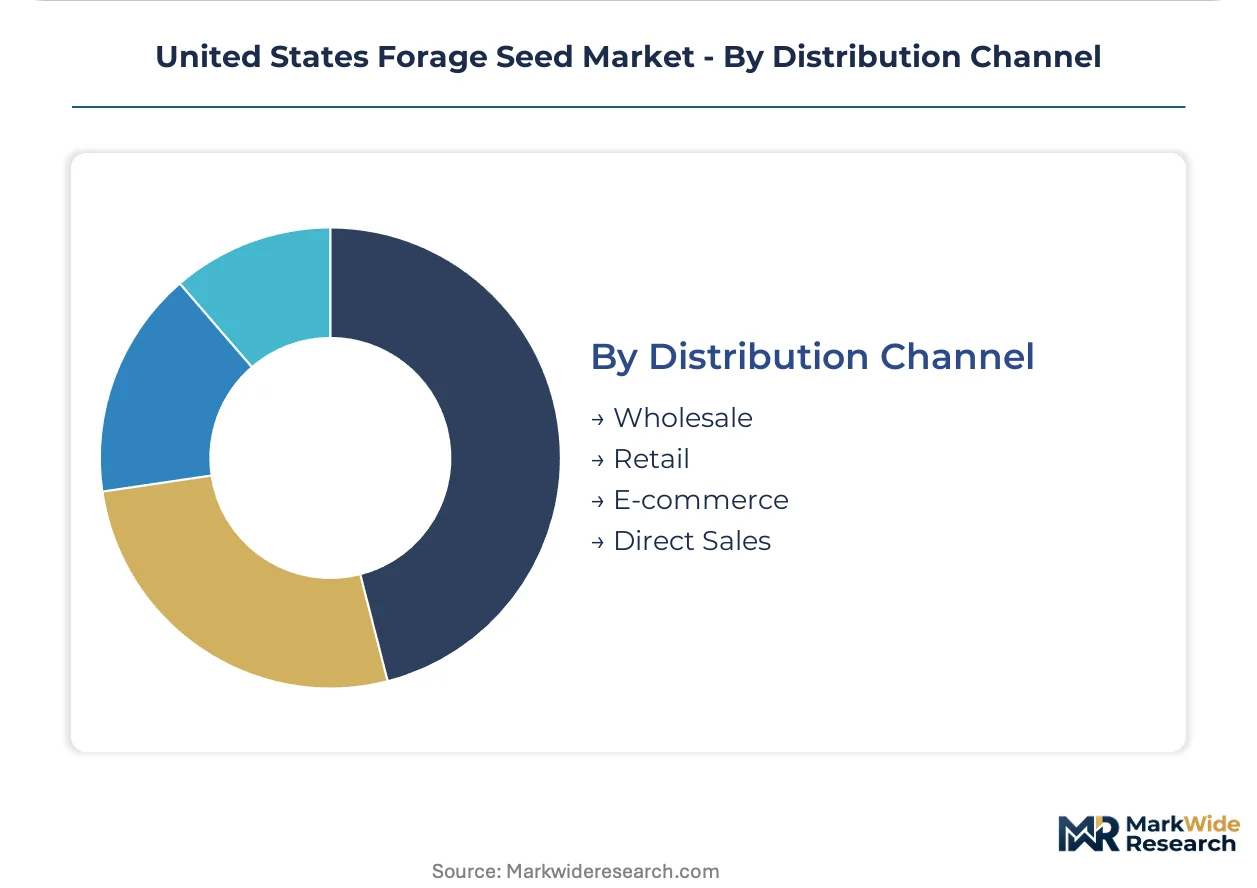
Distribution Channel:
Channel structure reflects buyer consolidation, with cooperative procurement programs extracting volume discounts that independent retailers cannot match.
- Wholesale:Regional seed cooperatives and agricultural distributors supply dealer networks across the Upper Midwest.
- Retail:Independent farm supply stores and regional chains serve smaller operations with localized agronomic support.
- E-commerce:Direct-to-farm platforms are gaining traction for specialty varieties and cover crop seed.
- Direct Sales:Large cooperatives in Wisconsin negotiate bundled contracts combining genetics, establishment services, and nutritional consulting.
Wholesale leads by volume. Direct Sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Idaho's Treasure Valley anchors certified legume seed production, supplying foundation-grade germplasm to dairy operations across the Corn Belt. Geographic concentration of breeding infrastructure and isolation acreage shapes varietal availability and procurement logistics.
Wisconsin
Dairy cooperatives in the Fox River Valley negotiate direct varietal contracts that bundle genetics with nutritional consulting. The Wisconsin Department of Agriculture administers additional certification protocols for organic seed stocks. Madison-based research stations collaborate with private breeders to adapt alfalfa germplasm to local soil conditions.
Minnesota
Consolidated feed sourcing programs across the Red River Valley compress procurement cycles for high-performance silage varieties. State nutrient management rules mandate vegetative buffer strips on marginal acres. Rochester-area distributors serve as consolidation points for bulk seed deliveries to large livestock operations.
Idaho
Foundation seed production concentrates in the Snake River Plain, where isolation distances and arid conditions support genetic purity protocols. The Federal Seed Act governs germination claims and noxious weed tolerances enforced by state inspectors. Nampa-based cleaning facilities process registered and certified seed classes for interstate shipment.
California
Specialty hay exporters in the Central Valley drive demand for non-dormant alfalfa varieties with premium hay market specifications. State water quality regulations influence forage species selection in groundwater basins. Imperial Valley contract growers supply heat-tolerant germplasm lines adapted to low-chill environments.
United States Forage Seed Market Competitive Landscape
Global majors compete with regional champions across breeding infrastructure and distribution reach. The vendor base spans multinational agriscience conglomerates with stacked trait platforms and specialized forage cooperatives with region-adapted germplasm. Three archetypes dominate: technology licensors with proprietary trait pipelines, regional seed cooperatives with local adaptation capabilities, and integrated dairy supply chain partners with captive varietal programs. Competitive moves concentrate on multi-year contracting arrangements and precision establishment service bundling.
Within the multinational technology tier, Corteva Agriscience and Bayer AG occupy positions defined by regulatory-scale biotechnology investment and broad germplasm licensing. DLF Seeds A/S and Forage Genetics International LLC exemplify the specialized forage segment, with the former representing European breeding heritage and the latter anchoring North American dairy corridor relationships. Allied Seed LLC and Brett Young Seed Company sit within the regional distribution archetype, leveraging localized agronomic support networks across the Upper Midwest and Northern Plains.
| Leading Market Players |
|---|
| DLF Seeds A/S |
| Forage Genetics International LLC |
| Allied Seed LLC |
| Brett Young Seed Company |
| UPL |
| Corteva Agriscience |
| Royal Barenbrug Group |
| S&W Seed Co. |
| Bayer AG |
| Others |
Value Network & Pricing Analysis
Wisconsin's nutrient management mandates gate both qualified supply and premium-tier pricing access, as seed lots meeting state buffer-strip specifications command foundation-grade premiums while non-compliant inventory faces spot-market discounts. The USDA Federal Seed Act and state-level certification protocols create a bifurcated sourcing landscape where certified organic dairy operations absorb price premiums unavailable to conventional beef producers.
Pricing Analysis
Performance guarantees bundled with varietal contracts separate premium-tier suppliers from unbundled spot-market transactions. Three-tier pricing structure across foundation, registered, and certified seed classes reflects germination percentage thresholds and genetic purity documentation. Price differentiation rests on AOSA testing verification and organic certification status. Pricing pressure stems from direct contracting between dairy cooperatives and seed suppliers compressing dealer margins. Beef cow-calf operations in the Ozark Highlands exhibit highest price sensitivity, while vertically integrated dairy programs prioritize stand persistence metrics over per-pound cost.
Supply Chain Analysis
Regional distribution centers in Madison, Rochester, and Nampa anchor hub-and-spoke patterns serving the Upper Midwest dairy corridor. Idaho's Treasure Valley and Oregon's Willamette Valley concentrate foundation seed production acreage for legume varieties. Raw material dependencies center on breeder seed stocks, certified cleaning facilities, and moisture-barrier packaging substrates. Supply chain risk concentrates in single-source vulnerability for high-germination alfalfa genetics during weather-stressed growing seasons. Distribution runs through cooperative procurement programs displacing independent retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Genomic selection platforms are displacing centralized station trials, forcing stakeholders to recalibrate asset deployment around decentralized breeding infrastructure and marker-assisted capabilities.
For Market Incumbents: Acquire regional seed cooperatives with established marker-assisted selection programs to secure local adaptation capabilities. Consolidate foundation seed production acreage in Idaho's Snake River Plain to lock in genetic purity isolation distances. Threat from DLF Seeds A/S and Forage Genetics International LLC leveraging proprietary germplasm lines demands captive breeding infrastructure investment. Backward integration into drone-based precision planting services anchors multi-year varietal loyalty. For New Entrants and Emerging Players: Capture cover crop integration opportunities in the Mid-Atlantic dairy corridor where double-cropping winter cereals with annual forage brassicas remains underpenetrated. Target erosion control buffer-strip mandates in Wisconsin and Minnesota as the most penetrable regulatory-driven segment. Partner with state water quality programs to position low-input grass mixtures for mandated vegetative strips on marginal acres. For Investors and Strategic Acquirers: Accelerated AOSA testing protocol adoption is the leading indicator that laboratory infrastructure investments will separate viable acquisition targets from stranded assets. Long-term viability centers on breeding programs with EPA deregistration capabilities for novel stacked traits. Target regional cooperatives with established relationships across the Red River Valley and Fox River Valley dairy belts. Watch for state carbon credit verification protocol finalization as inflection signal for perennial forage establishment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Foundation Seed Production Consolidation | Idaho and Oregon acreage concentration secures genetic purity isolation for premium legume varieties. |
| Precision Planting Technology Partnership | Drone-based seeding capabilities reduce establishment costs for Ozark Highlands rotational grazing operations. |
| Direct Contracting Program Expansion | Wisconsin dairy cooperatives bundle genetics with nutritional consulting to displace dealer networks. |
| Carbon Credit Protocol Alignment | Perennial forage establishment qualification opens revenue streams under emerging soil carbon verification. |
| Marker-Assisted Selection Licensing | Smaller breeding programs license stacked traits to bypass EPA multi-year environmental fate study requirements. |
Research Methodology
Independent corroboration across seed certification inspectors, dairy nutrition consultants, and cooperative procurement officers underwrites the qualitative findings in this study. Primary interviews with foundation seed producers, state department of agriculture regulators, and precision agriculture equipment distributors combined with secondary validation from USDA Agricultural Marketing Service germination databases, Federal Seed Act enforcement records, and state organic certification program filings. Bottom-up acreage and procurement volume estimates triangulated against top-down dairy herd nutrition modeling.
Rate-of-change decomposition across product type, use case, packaging format, and distribution channel segments structured the analytical framework over the projection horizon. CAGRs derived from varietal adoption curves, certified acreage expansion patterns, and direct contracting penetration rates. Forecast inputs incorporated AOSA testing protocol evolution timelines and state water quality mandate implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA biotechnology regulatory timeline extensions and synthetic nitrogen price volatility. Outputs reflect documented assumptions around dairy herd consolidation rates and carbon credit verification protocol adoption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Africa Vegetable Seed Market
Seeds
Chia Seeds Market
Seeds
South America Vegetable Seed Market
Seeds
Flax Crop Market
Seeds
Okra Seed Market
Seeds
Africa Peas Market
Seeds
Global Oilseed Market
Seeds
Thailand Vegetable Seed Market
Seeds
Organic Chia Seeds Market
Seeds
Citrus Seeds Market
Seeds
Eucommia Seed Oil Market
Seeds
China Seed Market
Seeds
Russia Seed Market
Seeds
Cotton Seed Treatment Market
Seeds
Myanmar Seed Market
Seeds
Europe Grain Seed Market