
 E. Angustifolium Market | 2026-2036
E. Angustifolium Market Size, Share, and Industry Trends Forecast 2026-2036
E. Angustifolium Market Analytics
Wild-harvesting cooperatives in Nordic and Baltic zones is consolidating as climate shifts alter flowering phenology and viable catchment areas. Symrise AG leverages captive sourcing relationships across Scandinavian terroirs to secure consistent resinoid quality. Sensient Technologies Corporation anchors its position through advanced supercritical CO2 extraction infrastructure. Givaudan competes on flavor-house integration, channeling fireweed-derived notes into premium beverage programs.
Epilobium angustifolium, commonly called fireweed or rosebay willowherb, denotes a perennial Onagraceae species yielding flavonoid-rich aerial parts with documented quercetin-3-O-glucuronide and myricetin glycoside profiles; processors macerate or distill dried herb for cosmetic actives, flavor modifiers, and phytotherapeutic preparations. Extracts and oils command the dominant value share, reflecting high input requirements and solvent recovery costs inherent to botanical concentration. Powder formats are gaining fastest traction in nutraceutical compounding, where encapsulation efficiency and shelf stability outperform liquid alternatives.
EMA herbal monograph standards and ECHA REACH Annex III botanical substance registrations shape European market access, while FDA New Dietary Ingredient notifications govern US nutraceutical entry pathways. Stakeholders must monitor evolving pharmacovigilance reporting obligations and adapt specification sheets to preempt border rejection risks.
Market Dynamics
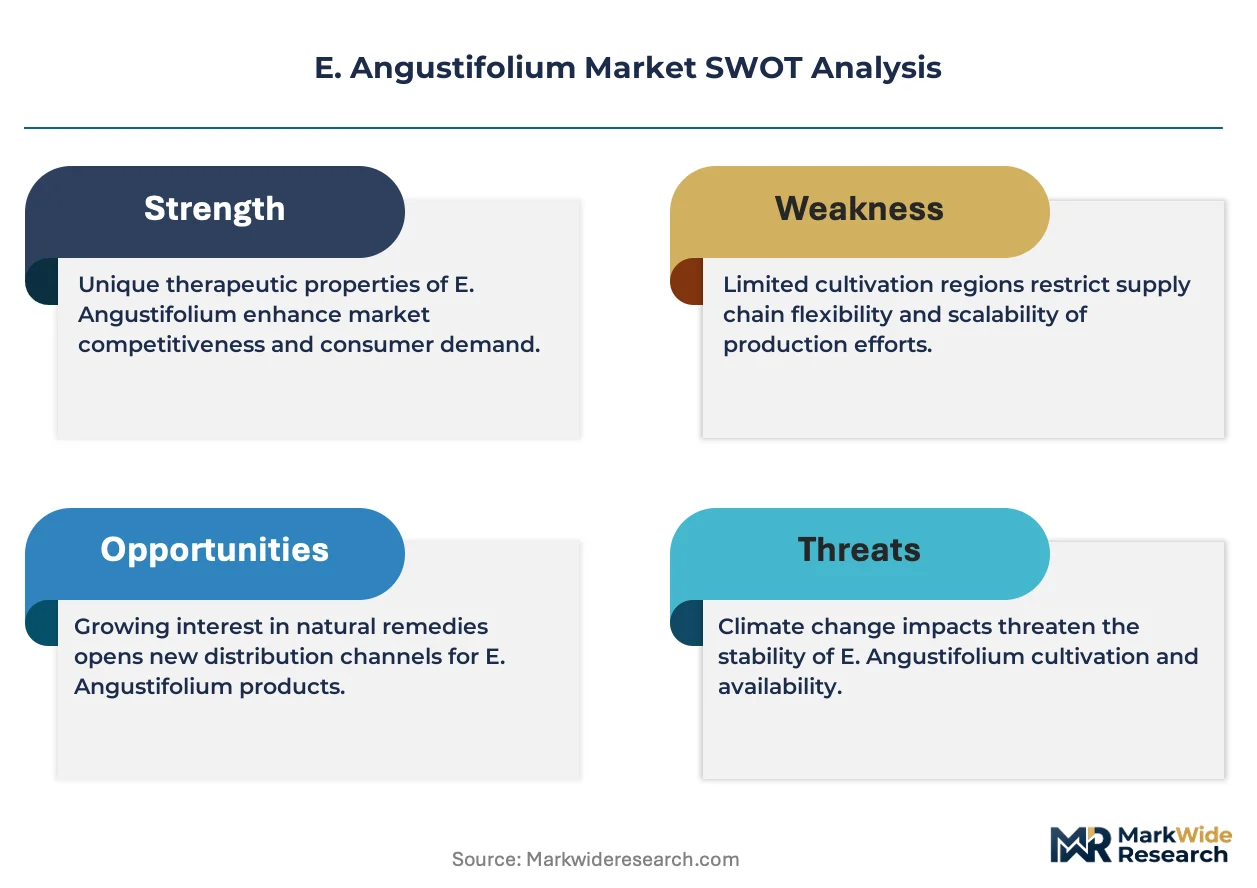
REACH Annex III botanical substance registrations are tightening raw material qualification protocols across European supply chains, forcing extractors to document allergen profiles and provenance traceability at unprecedented granularity.
Growth Catalysts
- Anti-inflammatory skincare demand:French and German cosmetics formulators are expanding E. angustifolium extract purchases for soothing topical formulations targeting reactive skin conditions.
- Apothecary-channel herbal supplement sales:German pharmacy networks sustain above-average offtake for standardized fireweed preparations, anchoring regional volume.
- Supercritical CO2 extraction maturation:Advanced solvent recovery infrastructure is lowering per-unit production costs for high-purity resinoids and flavonoid concentrates.
Market Restraints
- Wild-harvesting catchment contraction:Climate-driven phenology shifts in Nordic and Baltic zones are reducing viable flowering windows and raw herb availability.
- Input cost volatility:Dried herb maceration requires substantial solvent volumes, and energy-intensive distillation exposes processors to electricity price swings.
- Regulatory friction:FDA New Dietary Ingredient notification timelines create 12-18 month entry barriers for US nutraceutical market access.
Strategic Opportunities
- Encapsulation-ready powder formats:Nutraceutical compounders are shifting from liquid extracts to shelf-stable powders for tablet and capsule production efficiency.
- Flavor-house integration:Premium beverage programs are adopting fireweed-derived aromatic notes as botanical modifiers in craft and functional drinks.
- EMA herbal monograph alignment:Compliance with European traditional use registrations opens pharmacy and practitioner channels across EU member states.
Industry Challenges
- Pharmacovigilance reporting obligations:Evolving adverse event documentation requirements demand upgraded quality management systems and trained regulatory affairs staff.
- Provenance verification complexity:Wild-harvested material from dispersed Nordic cooperatives complicates batch consistency and organic certification audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E. Angustifolium Market |
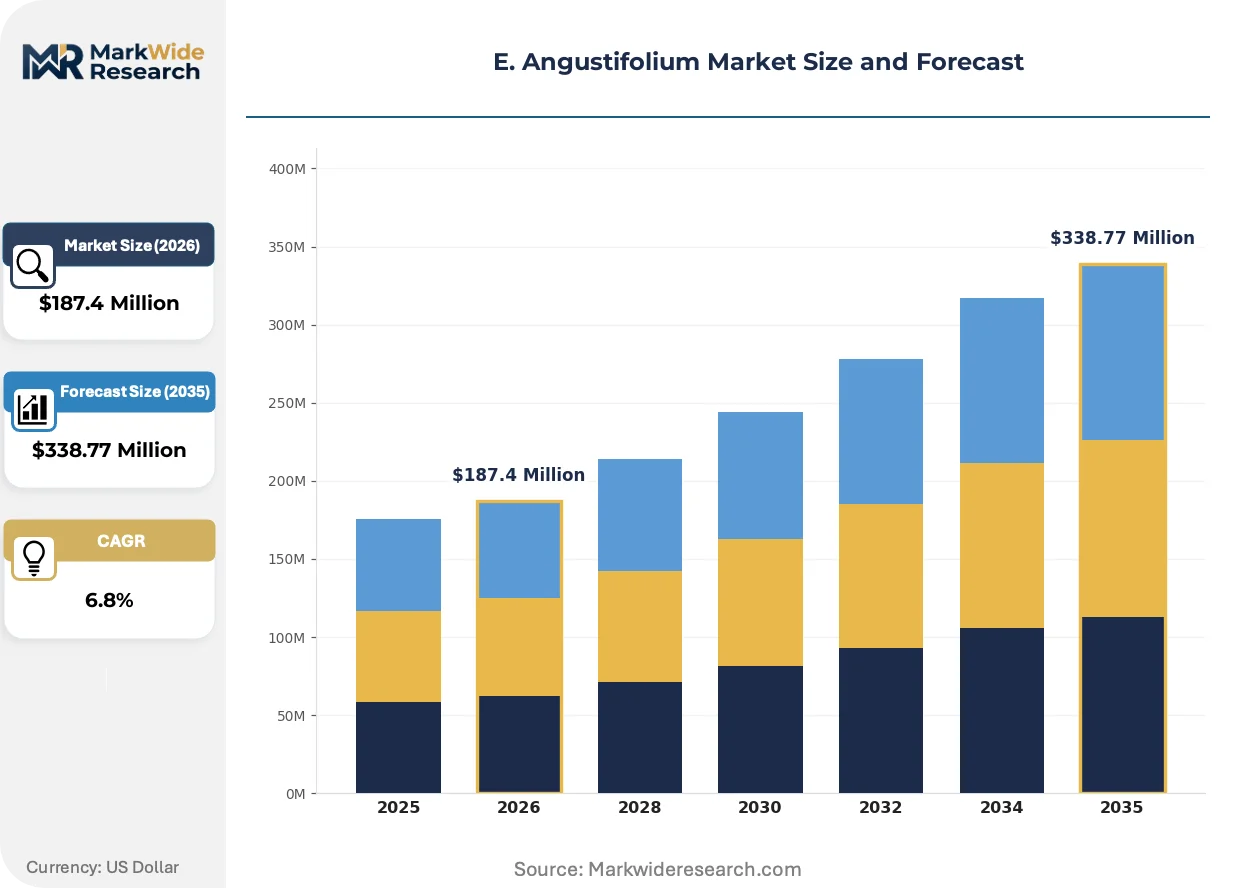
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracts, Oils, Dried Leaves, Powder Application: Pharmaceuticals, Cosmetics, Food & Beverage, Nutraceuticals Form: Liquid, Solid, Capsule, Tablet Distribution Channel: Online Retail, Wholesale, Specialty Stores, Supermarkets |
| Companies Covered | Symrise AG, Sensient Technologies Corporation, International Flavors & Fragrance Inc., Givaudan, Dohler GmbH, Synergy Flavors, Inc., PT Indesso Aroma, Kalsec Inc., V. Mane Fils SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E. Angustifolium Market Evolving Landscape
Extraction technology convergence and regulatory disclosure mandates are reshaping how processors qualify raw material and position finished actives across cosmetic, therapeutic, and flavor applications.
Supercritical CO2 extraction infrastructure is integrating into mid-scale processing facilities, enabling producers to bypass conventional solvent recovery bottlenecks while capturing heat-sensitive flavonoid fractions. German and Scandinavian extractors are retrofitting existing distillation lines with modular CO2 units to serve cosmetics clients demanding residue-free certification. This capital deployment is compressing price premiums for pharmaceutical-grade resinoids and forcing solvent-based competitors into specialty low-volume niches.
ECHA REACH compliance is expanding botanical allergen disclosure requirements, mandating that extractors quantify quercetin glycoside and myricetin derivative concentrations in specification sheets. The regulation forces reformulation of legacy cosmetic lines and triggers border rejection risks for non-compliant shipments. French formulators are responding by qualifying suppliers with pre-submitted Annex III dossiers, shifting procurement toward vertically integrated processors with in-house analytical capabilities.
Apothecary buyers are consolidating purchase volumes around certified traditional herbal preparations, displacing loose herb sales in German pharmacy channels. This concentration rewards extractors with EMA monograph-aligned production and pharmacovigilance-ready documentation, while marginalizing small-batch wild-harvest suppliers lacking quality management certification. The shift is most visible in Bavaria and Baden-Württemberg, where pharmacy chains are centralizing herbal SKU procurement under single-source contracts.
E. Angustifolium Market Segmentation
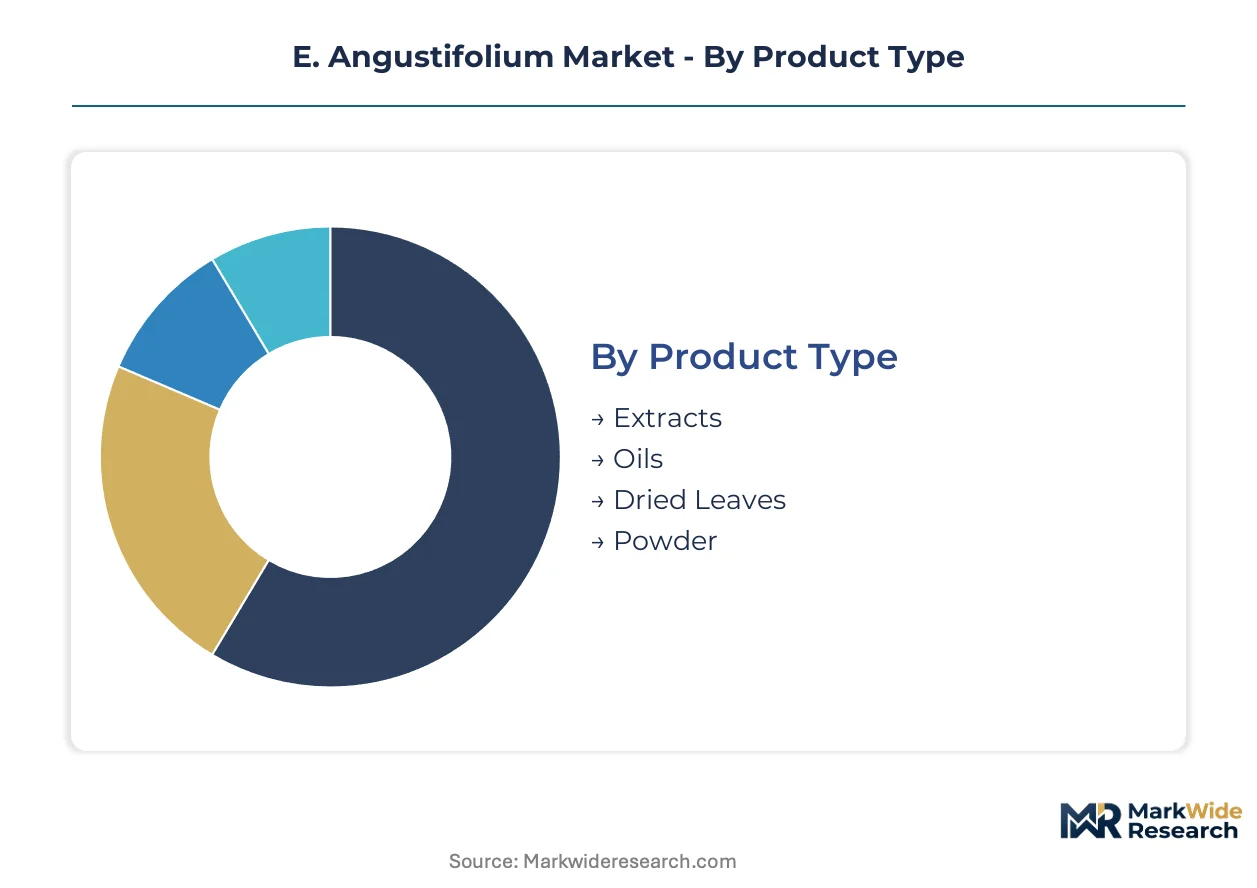
E. angustifolium processors configure production lines around extract concentration ratios and end-use certification requirements. Segmentation reflects divergent margin structures across cosmetic actives versus commodity herb formats.
Product Type:
Standardized extracts compete with artisanal wild-harvested material across a customization spectrum from pharmaceutical-grade resinoids to bulk dried herb.
- Extracts:Flavonoid-rich concentrates standardized to quercetin-3-O-glucuronide content dominate cosmetic and therapeutic applications. French formulators specify minimum 4% flavonoid thresholds for anti-inflammatory skincare lines, driving qualification protocols at Nordic extraction facilities.
- Oils:Essential oil fractions and fixed oils from aerial parts serve flavor-house and aromatherapy channels. Steam-distilled fireweed oil commands premium positioning in German apothecary networks due to EMA traditional use alignment.
- Dried Leaves:Bulk herb material supplies loose-leaf tea processors and traditional medicine practitioners. Baltic cooperatives consolidate shipments to meet volume contracts from central European distributors.
- Powder:Micronized formats enable encapsulation efficiency in nutraceutical compounding. Shelf stability and tablet compression properties accelerate substitution for liquid extracts in German pharmacy-channel supplements.
Most installed capacity flows through Extracts. Expansion is steepest in Powder.
Application:
End-use concentration varies by regulatory pathway complexity and formulation sophistication required.
- Pharmaceuticals:Standardized preparations targeting prostate and urinary tract indications follow EMA herbal monograph specifications. Bavarian pharmacy chains centralize procurement around pharmacovigilance-ready documentation.
- Cosmetics:Anti-inflammatory actives for reactive skin formulations drive extract demand from French and German formulators. REACH Annex III allergen disclosure mandates reshape supplier qualification.
- Food & Beverage:Fireweed-derived aromatic notes integrate into premium beverage programs as botanical modifiers. Flavor-house partnerships channel specialty volumes through Scandinavian processors.
- Nutraceuticals:Encapsulated supplements target oxidative stress and inflammatory markers. FDA New Dietary Ingredient notification timelines create entry barriers for US market development.
Cosmetics commands the dominant value share. Nutraceuticals is gaining share fastest.
Form:
Physical presentation determines logistics cost structures and end-user convenience profiles.
- Liquid:Tinctures and fluid extracts retain traditional pharmacy positioning. Alcohol-based preservation systems face formulation constraints in clean-label cosmetic trends.
- Solid:Bulk resinoids and dried herb formats serve compounders and tea blenders. Scandinavian processors specialize in low-moisture stability specifications for extended shelf life.
- Capsule:Hard-shell gelatin and vegetable-derived encapsulation dominates German apothecary supplement sales. Powder-to-capsule conversion efficiency rewards integrated manufacturing.
- Tablet:Compressed formulations require excipient compatibility and disintegration profiling. Direct compression grades from Nordic suppliers command specification premiums.
Capsule formats absorb the majority of pharmacy-channel volume. Tablet formats are climbing the fastest as manufacturing scales.
Distribution Channel:
Channel selection reflects buyer sophistication and regulatory documentation requirements.
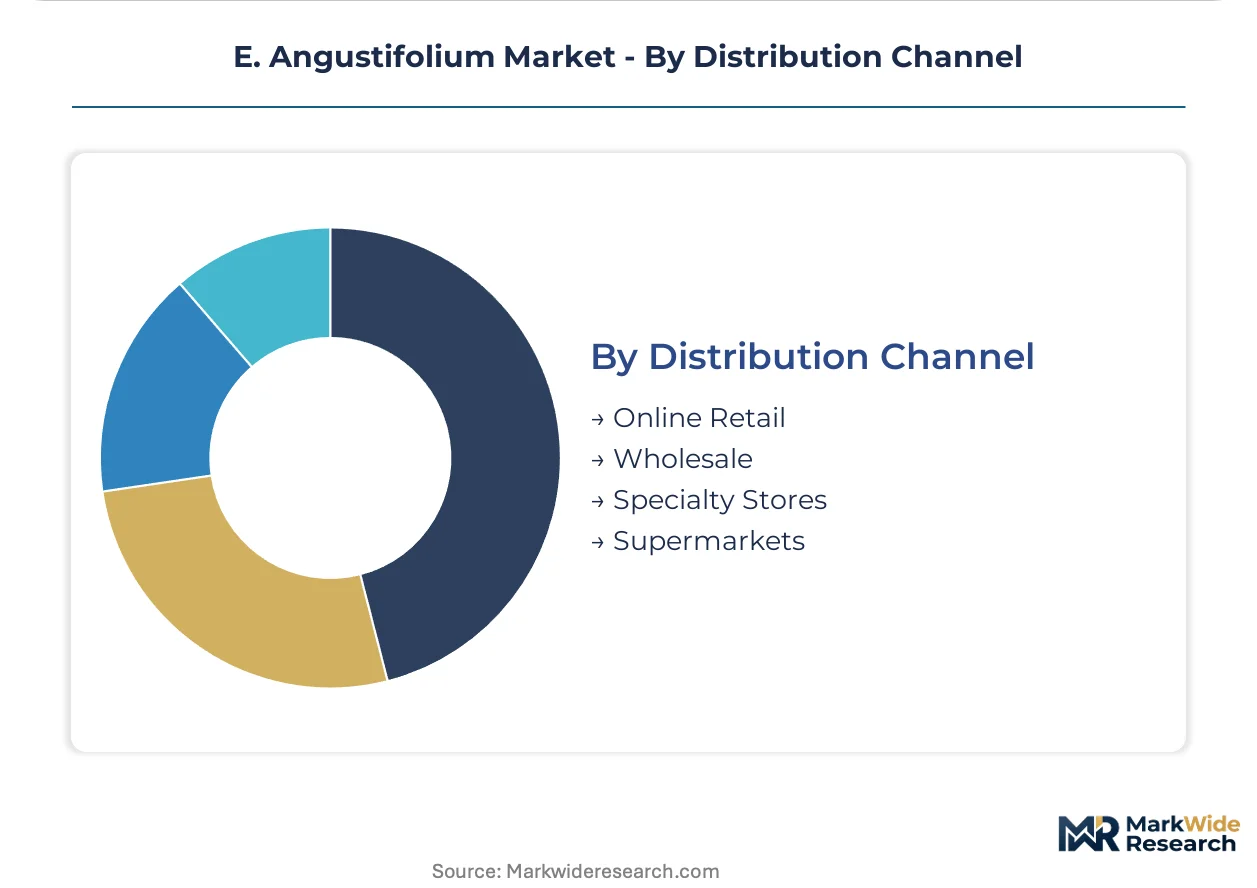
- Online Retail:Direct-to-consumer platforms serve educated supplement users and herbal enthusiasts. German-speaking markets show highest conversion for traditional preparation education content.
- Wholesale:Bulk transactions supply compounders, manufacturers, and pharmacy central purchasing. Baltic cooperative consolidation feeds into Rotterdam and Hamburg distribution hubs.
- Specialty Stores:Apothecary and herbalist channels sustain premium positioning for EMA-aligned products. Bavaria and Baden-Württemberg concentrate certified traditional herbal preparation sales.
- Supermarkets:Mass-market tea and basic supplement formats compete on price positioning. Organic certification requirements filter supplier base to audited wild-harvest operations.
Wholesale channels move the largest absolute volumes. Specialty Stores deliver the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany sustains pharmacy-channel dominance while France drives cosmetic extract demand; both markets operate under divergent regulatory intensities that reshape procurement geography.
Germany
Apothecary networks in Bavaria and Baden-Württemberg centralize procurement around EMA-aligned traditional herbal preparations. BfArM pharmacovigilance reporting obligations now mandate upgraded quality management systems for all suppliers. Processing clusters around Hamburg and Frankfurt specialize in supercritical CO2 extraction infrastructure serving cosmetic formulators.
France
Parisian and Lyon-based cosmetics laboratories specify minimum 4% flavonoid thresholds for anti-inflammatory skincare actives. ANSM cosmetic ingredient disclosure rules tighten allergen documentation requirements for fireweed-derived materials. Grasse-area flavor houses integrate fireweed notes into premium beverage programs through captive sourcing relationships.
Sweden
Nordic wild-harvesting cooperatives consolidate shipments to meet volume contracts from central European distributors. Swedish Board of Agriculture organic certification audits now require phenology-adjusted harvest windows due to climate shifts. Uppsala and Gothenburg extraction facilities retrofit distillation lines with modular CO2 units.
United States
FDA New Dietary Ingredient notification timelines create 12-18 month entry barriers for encapsulated fireweed supplements targeting oxidative stress indications. California and Colorado nutraceutical compounders shift procurement toward shelf-stable powder formats for tablet production efficiency. Denver-area processing hubs specialize in direct compression grades for pharmacy-channel distribution.
Poland
Baltic cooperative consolidation feeds bulk dried herb shipments through Gdańsk and Szczecin distribution hubs. Polish Centre for Testing and Certification (PCBC) organic audits filter supplier base to climate-adapted wild-harvest operations. Warsaw-area extractors develop low-moisture stability specifications for extended shelf-life resinoids.
E. Angustifolium Market Competitive Landscape
Scandinavian producers anchor the wild-harvest sourcing tier; German and Swiss specialists hold extraction and formulation capabilities. The vendor base stratifies across three tiers: vertically integrated flavor houses with captive Nordic supply, mid-scale extractors with supercritical CO2 infrastructure, and cooperative-fed bulk herb traders. Dominant competitive moves include backward integration into wild-harvest catchments and pharmacovigilance-ready documentation investments for pharmacy-channel access.
Within the integrated flavor-house tier, Symrise AG and Givaudan exemplify archetypes combining Nordic sourcing relationships with beverage program development. Sensient Technologies Corporation occupies a position representing advanced extraction infrastructure specialization. These three entities collectively illustrate how competitive positioning diverges between supply-captive and technology-differentiated strategies.
| Leading Market Players |
|---|
| Symrise AG |
| Sensient Technologies Corporation |
| International Flavors & Fragrance Inc. |
| Givaudan |
| Dohler GmbH |
| Synergy Flavors, Inc. |
| PT Indesso Aroma |
| Kalsec Inc. |
| V. Mane Fils SA |
| Others |
Value Network & Pricing Analysis
Specialized supercritical CO2 extraction technicians concentrated in Hamburg and Frankfurt command wage premiums that compress margin spreads between pharmaceutical-grade resinoids and commodity dried herb formats. This labor-cost differential widens pricing-tier separation across Nordic wild-harvested inputs and German-processed actives.
Pricing Analysis
Capacity additions in Scandinavian extraction facilities are reshaping price floors for flavonoid-rich concentrates. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in standard-tier extracts is intensifying because modular CO2 unit deployment reduces solvent recovery overhead. Pharmacy-channel buyers in Germany exhibit lowest price sensitivity due to EMA monograph alignment requirements, while mass-market tea processors compete primarily on procurement cost.
Supply Chain Analysis
Direct-to-cosmetic-formulator channels handle high-specification buyer demand for REACH-compliant actives. Raw material supply draws from Sweden, Finland, and Estonia through cooperative consolidation networks. Processing depends on dried herb maceration inputs, supercritical CO2 solvent systems, and pharmaceutical-grade filtration media. Single-source vulnerability runs through Baltic wild-harvest catchments facing climate-driven phenology shifts. Distribution runs through Rotterdam and Hamburg hubs serving French cosmetics laboratories and German apothecary chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E. angustifolium functions as a stable compounder anchored by sustained apothecary-channel demand for traditional herbal preparations in German-speaking markets.
For Market Incumbents: Deepen captive sourcing relationships across Scandinavian terroirs to preempt climate-driven catchment contraction. Secure pharmacovigilance-ready documentation infrastructure to defend pharmacy-channel positioning against EMA compliance escalation. Prioritize supercritical CO2 capacity additions in Hamburg processing clusters to maintain residue-free certification premiums. For New Entrants and Emerging Players: Begin with encapsulation-ready powder formats for German nutraceutical compounders seeking shelf-stable alternatives to liquid extracts. Target direct-to-consumer online retail in German-speaking markets where traditional preparation education content drives conversion. Pursue flavor-house partnerships as the most penetrable entry vector for fireweed-derived aromatic notes. For Investors and Strategic Acquirers: Flavor-house conglomerates with beverage program development capabilities represent the most active acquirer in this space. Mid-scale extractors with supercritical CO2 infrastructure and EMA-aligned quality systems offer viable acquisition targets across a 5-10 year viability window. Monitor FDA New Dietary Ingredient notification clearance timelines as the signal to watch for US nutraceutical market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wild-Harvest Catchments | Secures climate-resilient raw material supply for Nordic cooperative networks. |
| Supercritical CO2 Infrastructure Expansion | Enables residue-free certification for French cosmetics formulators under REACH. |
| EMA Monograph Alignment Investment | Opens pharmacy-channel access across Bavarian and Baden-Württemberg networks. |
| Encapsulation-Ready Powder Development | Captures German nutraceutical demand for tablet production efficiency. |
| Flavor-House Partnership Formation | Channels fireweed-derived notes into premium Scandinavian beverage programs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered extraction facility operators, cosmetics formulators, apothecary procurement managers, and regulatory affairs specialists at ECHA-aligned processors. Secondary validation drew from EMA herbal monograph databases, REACH Annex III registration filings, BfArM pharmacovigilance reports, and Nordic agricultural phenology records. Bottom-up volume estimates from processor capacity utilization triangulated against top-down demand aggregation from end-use channel surveys.
Segment-weighting applied product type, application, and form dimensions across the projection horizon. CAGRs derived from fitted growth curves incorporating EMA regulatory pathway timelines, FDA notification clearance patterns, and climate-adjusted wild-harvest yield assumptions. Forecast inputs included supercritical CO2 adoption rates in German processing clusters and pharmacy-channel SKU consolidation trajectories in Bavaria.
Several conditions sit outside the modeled scope, including extreme climate scenarios beyond current phenology adjustment protocols and abrupt REACH allergen disclosure threshold revisions. Forecasts reflect documented assumptions about cooperative consolidation sustainability and EMA traditional use registration stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Perilla Seed Oil Market
Seeds
Dodder Seed Market
Seeds
North America Seeds Market
Seeds
Garden Seeds Market
Seeds
Global Wheat Seed Market
Seeds
Uganda Seeds Market
Seeds
Europe Quinoa Seed Market
Seeds
Quinoa Seed Market
Seeds
Agricultural Seeder Market
Seeds
Dragon Fruit Seeds Market
Seeds
Seed Cracker Market
Seeds
South Africa Forage Seed Market
Seeds
Philippines Seed Market
Seeds
Global Grain Seed Market
Seeds
Africa Vegetable Seed Market
Seeds
Spain Forage Seed Market