
 India Plastic Caps and Closures Market | 2026-2036
India Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
India Plastic Caps and Closures Market Insights
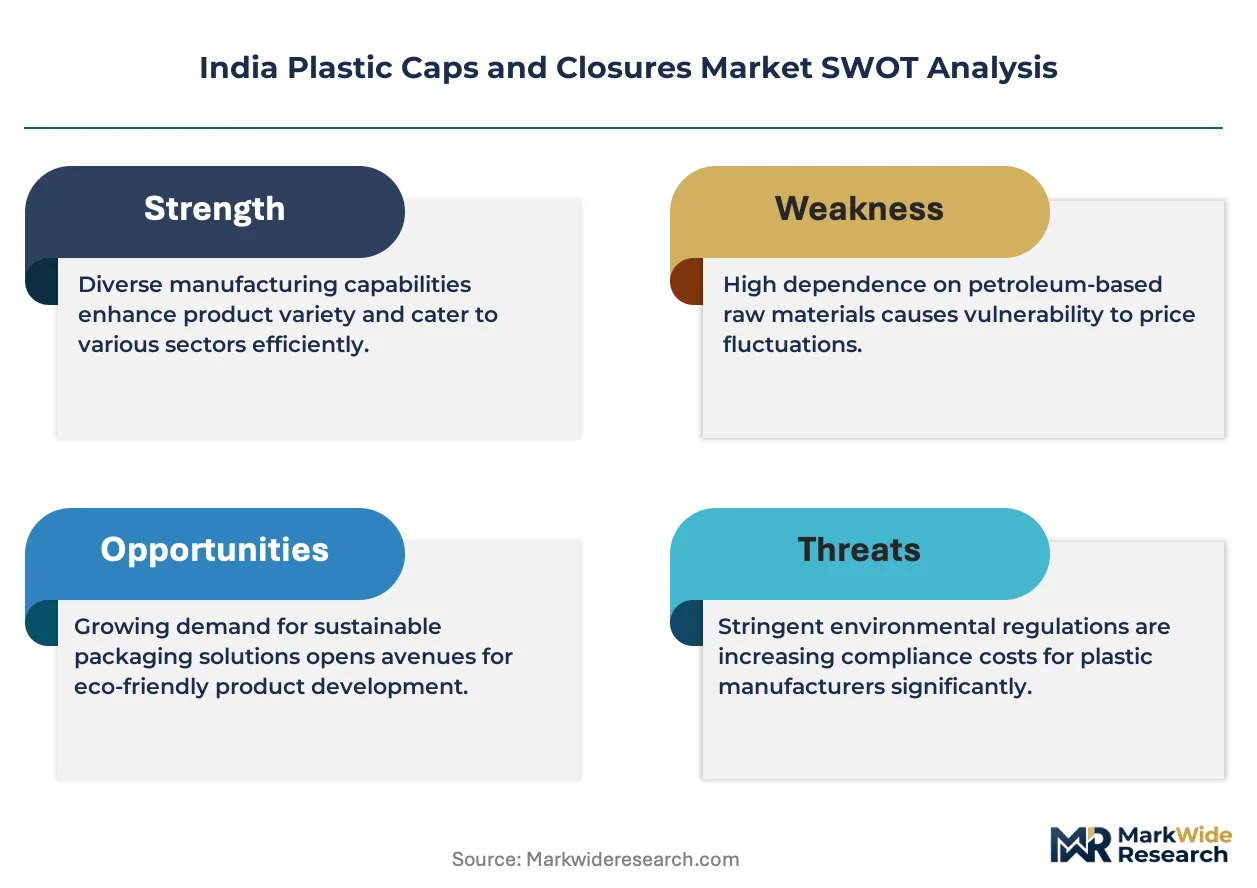
A capital-intensity divergence between domestic tooling specialists and multinational injection-molding operators is rotating competitive dynamics across the sector. Vimal Plastics leverages its western India manufacturing base to anchor supply for regional beverage bottlers. Amcor plc sustains technology leadership through advanced barrier closure platforms. KKD International competes on customized mold turnaround times for mid-tier pharmaceutical clients.
India plastic caps and closures are injection-molded or compression-molded sealing devices, typically manufactured from polyethylene or polypropylene resins with thread profiles measured in millimeter pitch standards, designed to preserve contents against contamination, leakage, and oxidation across liquid and semi-solid packaged goods. Screw caps dominate volume throughput in beverage and edible oil applications where resealability drives repeat purchase behavior. Flip top caps represent the fastest-expanding design category in personal care and pharmaceutical dispensing, where single-hand operation commands premium placement. Polypropylene material grades capture expanding share from polyethylene in hot-fill and retort applications due to superior thermal deformation resistance.
BIS standards govern food-contact migration limits for plastic closures, while CDSCO regulations mandate child-resistant design features for pharmaceutical packaging, collectively elevating compliance costs for non-certified domestic molders. The Plastic Waste Management Rules, enforced by CPCB and state pollution control boards, are extending producer responsibility obligations upstream into closure supply chains. Stakeholders must monitor evolving extended producer responsibility thresholds and BIS harmonization timelines to anticipate capital allocation requirements for compliance-ready tooling investments.
Market Dynamics
BIS certification mandates for food-contact plastics are compressing the supplier base as non-compliant molders exit, while pharmaceutical corridors in Gujarat and Maharashtra accelerate demand for child-resistant closure designs.
Growth Catalysts
- Pharmaceutical packaging corridors:Ahmedabad and Mumbai manufacturing clusters are expanding output of prescription and over-the-counter medicines, driving specialized closure demand for tamper-evident and child-resistant applications.
- FSSAI alignment with BIS:Harmonized food-contact safety standards are consolidating buyer preference toward certified suppliers with validated migration testing protocols.
- Hot-fill beverage expansion:Polypropylene grade adoption is accelerating as regional bottlers upgrade lines for juices and ready-to-drink teas requiring thermal deformation resistance above 85°C.
Market Restraints
- Petrochemical input volatility:Polypropylene and polyethylene resin prices track crude oil and naphtha spreads, compressing margin predictability for mid-tier injection molders without long-term supply contracts.
- Tooling capital intensity:Multi-cavity hot-runner molds for pharmaceutical-grade closures require 40-60 lakh rupee investments, creating entry barriers for domestic specialists competing against multinational operators.
- Aluminum and glass substitution:Premium edible oil and spirits brands are piloting metal roll-on closures and cork stoppers for perceived quality differentiation, capping plastic share in gift and export segments.
Strategic Opportunities
- North-eastern state penetration:Assam and Meghalaya beverage bottling capacity remains underdeveloped relative to per-capita consumption growth, creating first-mover whitespace for closure suppliers establishing distribution.
- Extended Producer Responsibility thresholds:CPCB enforcement of Plastic Waste Management Rules is mandating post-consumer recycled content integration, rewarding molders with approved rPP and rPE sourcing partnerships.
- Smart closure convergence:NFC-enabled and QR-integrated authentication features are merging with conventional tamper-evident designs, opening premium pricing tiers for pharmaceutical and liquor applications.
Industry Challenges
- Certification timeline compression:CDSCO child-resistant protocol validation and BIS food-contact migration testing require 8-14 month approval cycles, delaying new product launches for mid-size molders.
- Skilled toolroom technician scarcity:Precision mold maintenance and hot-runner troubleshooting expertise concentrates with aging workforces in Pune and Vadodara, constraining capacity expansion for second-tier players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Plastic Caps and Closures Market |
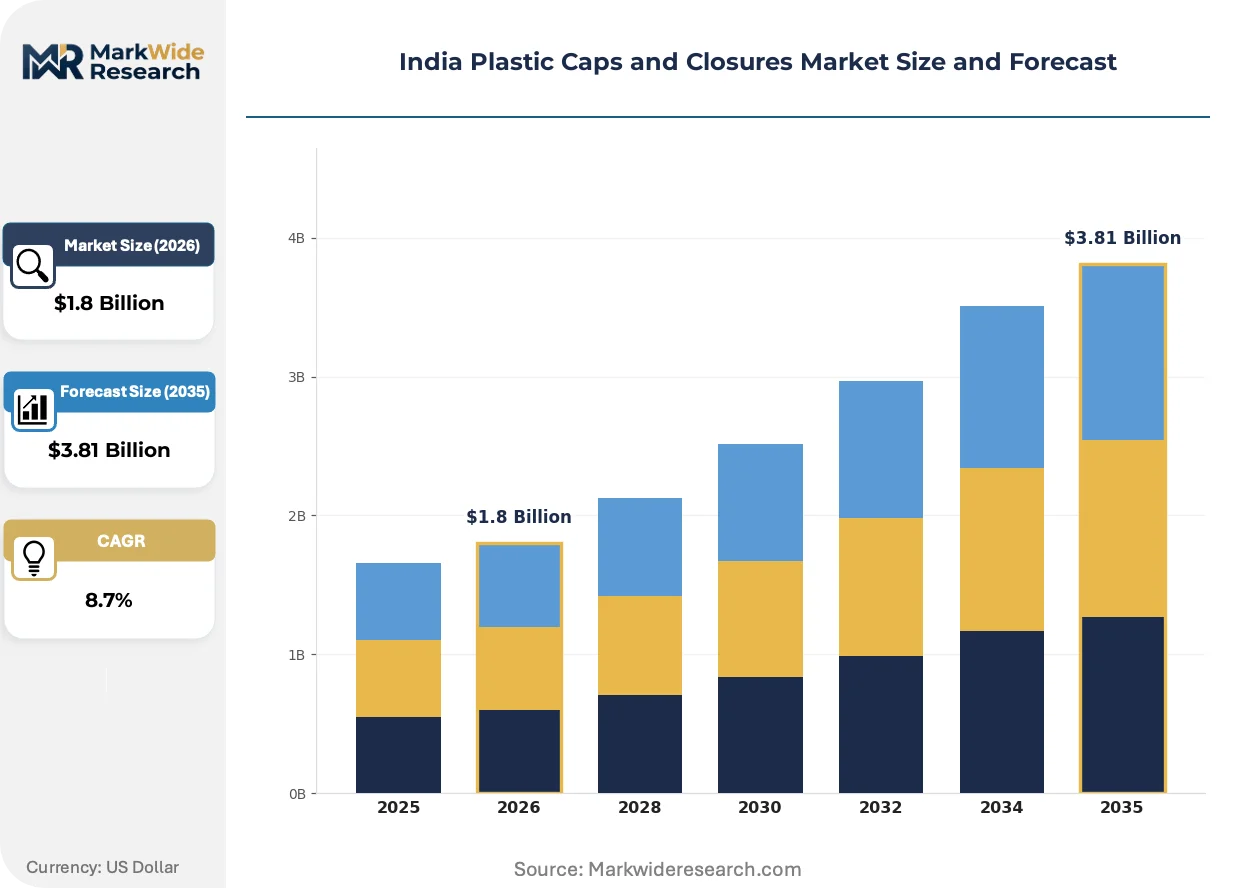
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cap Type: Screw Caps, Flip Top Caps, Tamper Evident Caps, Snap On Caps Material: Polyethylene, Polypropylene, PVC, PET End User: Beverages, Pharmaceuticals, Food & Beverage, Personal Care Design Feature: Child Resistant, Easy Open, Customized, Standard |
| Companies Covered | KKD International, Amcor plc, Aptar Group Inc., Closure Systems International, Silgan Holdings Inc., Bericap Holding GmbH, Vimal Plastics Pvt. Ltd., Guala Closures S.p.A., Berry Global Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Plastic Caps and Closures Market Trends and Innovations
Closure design intelligence is bifurcating between commodity screw formats and functional dispensing systems, with material science advances enabling thinner-wall geometries without seal integrity compromise.
Lightweighting through advanced nucleating agents is fragmenting traditional wall-thickness specifications across beverage and edible oil segments. Regional bottlers in Maharashtra are adopting 20-25% material reduction designs to offset resin cost inflation. This compression is fragmenting supplier tiers as only molders with finite element analysis capabilities qualify for revised performance specifications.
CDSCO amendments to pharmaceutical packaging guidelines are mandating senior-friendly yet child-resistant dual-function closures for analgesic and cough syrup categories. Domestic formulators in Gujarat are restructuring procurement specifications to preempt compliance deadlines. The regulatory tightening is accelerating validation partnerships between closure molders and contract packaging organizations in Ahmedabad.
Direct procurement from tier-one molders is displacing distributor-mediated purchasing among multinational beverage and pharma anchor clients. Volume concentration in Mumbai and Pune headquarters is compressing regional distributor margins and consolidating supplier relationships around technical service capability. The channel shift is most visible in western India where bottler procurement functions have centralized over the past eighteen months.
India Plastic Caps and Closures Market Segmentation
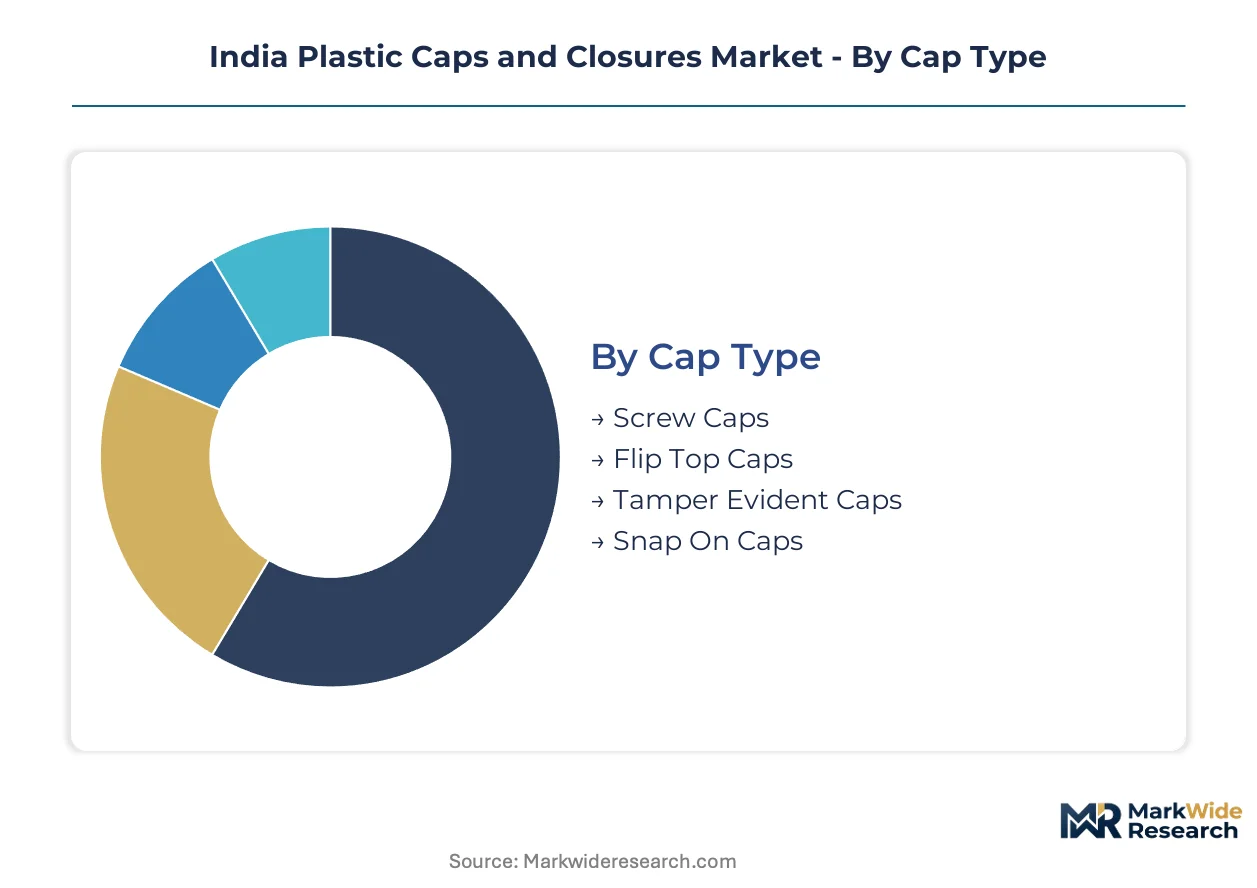
India's plastic caps and closures market segments around regulatory thresholds that reshape procurement patterns. BIS certification tiers and CDSCO compliance mandates create divergent margin structures across cap types, materials, and end-use applications.
Cap Type:
BIS migration testing requirements and CDSCO tamper-evident protocols segment this category by compliance burden rather than geometry alone.
- Screw Caps:Threaded polyethylene and polypropylene designs with standardized 28mm and 38mm pitches dominate beverage and edible oil throughput. Maharashtra bottlers specify these for resealability in repeat-consumption categories where FSSAI-aligned BIS certification is mandatory.
- Flip Top Caps:Hinged polypropylene dispensing mechanisms with integrated living hinges enable single-hand operation. Personal care formulators in Gujarat are expanding orders for these designs as premium shampoo and conditioner lines upgrade packaging functionality.
- Tamper Evident Caps:Ring-break or bridge-break indicators meeting CDSCO pharmaceutical guidelines. Required for over-the-counter medicines from Ahmedabad manufacturing clusters.
- Snap On Caps:Press-fit designs without threading for single-serve dairy and juice portions. Lower tooling costs attract regional dairy cooperatives without hot-runner investment capacity.
Established volume favors screw caps; emerging adoption favors flip top caps.
Material:
Hot-fill line upgrades and retort sterilization requirements are rotating procurement specifications toward thermal performance grades.
- Polypropylene:Semi-crystalline thermoplastic with heat deflection temperatures above 100°C enables hot-fill juice and ready-to-drink tea applications. Western India bottlers specify homopolymer grades for 85°C+ filling lines where polyethylene fails.
- Polyethylene:LDPE and HDPE grades dominate cost-sensitive edible oil and water segments. Gujarat packaging converters leverage established supply contracts with Reliance and IOCL for volume pricing on standard screw cap applications.
- PVC:Rigid formulations for chemical and agrochemical closures where solvent resistance exceeds polyolefin capabilities. Limited food-contact approval constrains expansion under FSSAI scrutiny.
- PET:Crystalline polyester for specialty pharmaceutical desiccant closures and high-clarity cosmetic dispensing. Premium positioning in Mumbai personal care contract manufacturing.
Cost tier differentiation separates polypropylene for thermal performance from polyethylene for commodity volume.
End User:
Customer procurement centralization in Mumbai and Pune headquarters is consolidating supplier relationships around technical service capability rather than distributor proximity.
- Beverages:Carbonated soft drink, bottled water, and juice bottlers across Maharashtra and Gujarat drive screw cap and sports closure demand. Coca-Cola and PepsiCo anchor clients specify BIS-certified migration-tested materials with validated 24-month shelf-life performance.
- Pharmaceuticals:Prescription and over-the-counter medicine manufacturers in Ahmedabad and Mumbai corridors require CDSCO-compliant child-resistant and tamper-evident designs. Contract packaging organizations validate closure torque specifications against USP 671 protocols.
- Food & Beverage:Edible oil and processed food packagers in Rajasthan and Madhya Pradesh specify oxygen-barrier liners for oxidation-sensitive contents. FSSAI enforcement of BIS IS 9845 standards is compressing the approved supplier base.
- Personal Care:Shampoo, conditioner, and lotion formulators prioritize dispensing convenience and shelf aesthetics. Flip top and disc top designs with custom color matching command premium positioning in urban retail.
Margin concentration sits with pharmaceuticals; volume scale concentrates in beverages.
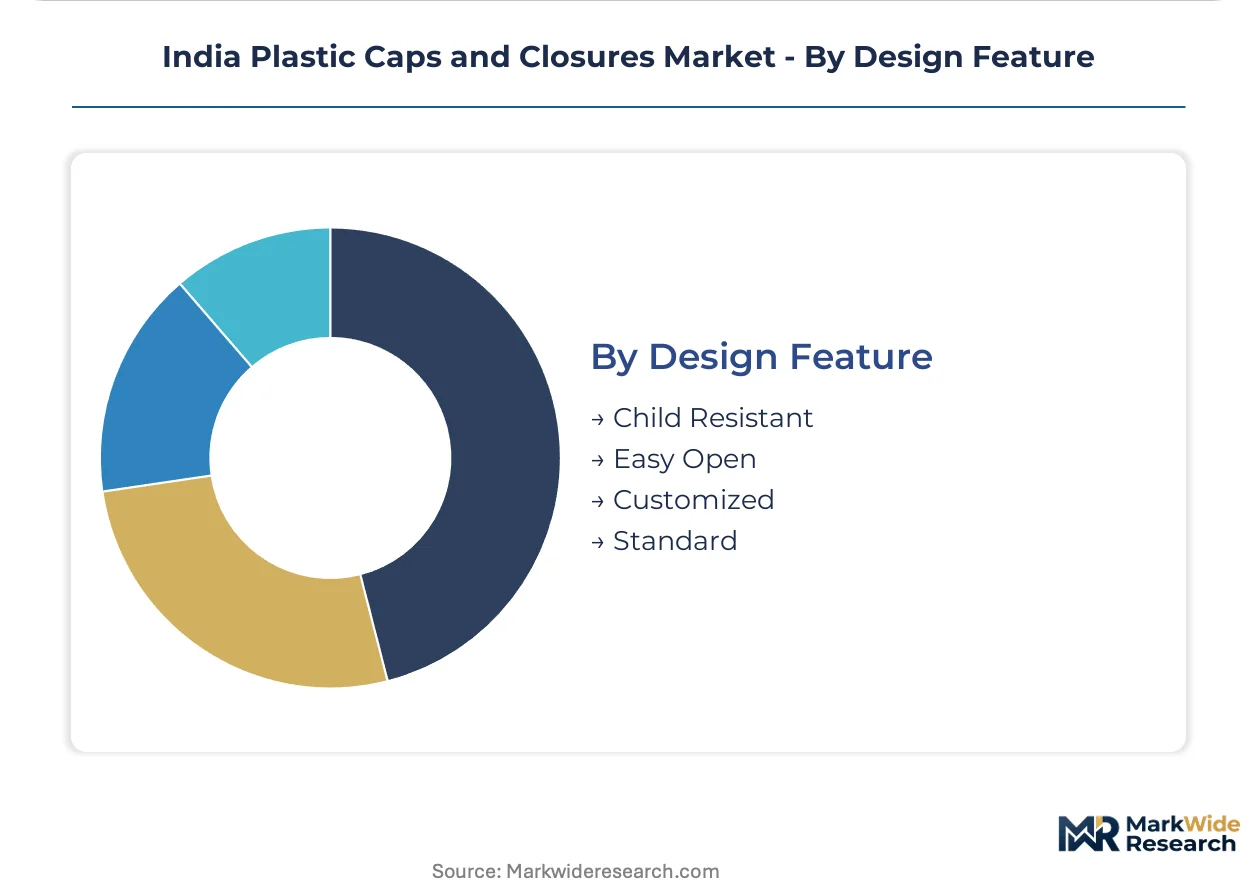
Design Feature:
Regulatory mandates and demographic targeting bifurcate this category between mandatory safety engineering and discretionary user experience.
- Child Resistant:Push-and-turn or squeeze-and-turn mechanisms meeting CDSCO senior-friendly yet child-resistant dual-function requirements. Gujarat analgesic manufacturers are restructuring procurement specifications to preempt compliance deadlines.
- Easy Open:Break-force reduction for aging demographics and accessibility requirements. Over-the-counter cough syrup lines in Maharashtra adopt these for competitive differentiation without full child-resistant certification.
- Customized:Brand-specific geometry, color, and embossed logo integration for premium spirits and cosmetic positioning. Tooling amortization across 10-million-unit annual commitments.
- Standard:Unmodified catalog designs with minimal tooling investment and fastest delivery cycles. Regional edible oil packagers in Madhya Pradesh prioritize cost minimization over differentiation.
Compliance burden favors child resistant; brand differentiation favors customized.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western India consumes plastic closures differently from eastern and southern regions, with pharmaceutical-grade specifications dominating Gujarat and Maharashtra while beverage-standard formats prevail elsewhere. This geographic split shapes procurement patterns, certification requirements, and supplier relationships across the country.
Maharashtra
Beverage bottlers in Mumbai and Pune drive screw cap demand for carbonated soft drinks and bottled water where FSSAI-aligned BIS certification is mandatory. The state pollution control board enforces Plastic Waste Management Rules compliance for closure suppliers. Manufacturing clusters around Nashik and Aurangabad are expanding hot-fill line capacity for juice applications requiring polypropylene thermal resistance.
Gujarat
Pharmaceutical manufacturers in Ahmedabad and Vadodara corridors specialize in child-resistant and tamper-evident closures for export-oriented medicine packaging. CDSCO mandates senior-friendly yet child-resistant dual-function designs for analgesic categories. The Sanand industrial zone hosts contract packaging organizations validating closure torque specifications against USP 671 protocols.
Karnataka
Bengaluru-based personal care formulators source flip top caps for premium shampoo and conditioner lines where single-hand dispensing commands retail placement. The state food safety department enforces BIS IS 9845 migration limits for food-contact closures. Mysuru packaging converters are developing distribution networks for regional edible oil cooperatives seeking oxygen-barrier liner specifications.
Tamil Nadu
Chennai pharmaceutical exporters require CDSCO-compliant closures meeting US FDA and European EMA standards for regulated markets. The Tamil Nadu Pollution Control Board extends producer responsibility obligations into closure supply chains under national Plastic Waste Management Rules. Coimbatore toolroom specialists maintain precision mold capabilities for mid-tier injection molders serving southern beverage markets.
Delhi-NCR
Haryana and Uttar Pradesh packaging hubs supply northern India edible oil and dairy segments with snap-on cap designs for single-serve portions. The Central Pollution Control Board coordinates with state regulators on extended producer responsibility threshold enforcement. Noida manufacturing corridors attract distributors seeking proximity to Uttar Pradesh and Rajasthan consumer markets.
India Plastic Caps and Closures Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational injection-molding operators commanding pharmaceutical-grade certification capacity while domestic molders compete on customized turnaround and regional logistics. Three archetypes define competitive positioning: technology leaders with advanced barrier platforms, western India-based regional suppliers anchoring beverage bottler relationships, and mid-tier specialists competing on mold customization speed. Dominant competitive moves include backward integration into resin sourcing partnerships and geographic expansion into underpenetrated north-eastern states.
Among multinational operators, Amcor plc and Aptar Group Inc. exemplify technology leadership archetypes with validated migration testing protocols and barrier closure platforms. KKD International and Vimal Plastics occupy positions within the domestic specialist tier, with the latter representing western India manufacturing base advantages for regional beverage supply. Bericap Holding GmbH anchors the European-origin multinational segment serving premium pharmaceutical and liquor applications requiring technical service depth.
| Leading Market Players |
|---|
| KKD International |
| Amcor plc |
| Aptar Group Inc. |
| Closure Systems International |
| Silgan Holdings Inc. |
| Bericap Holding GmbH |
| Vimal Plastics Pvt. Ltd. |
| Guala Closures S.p.A. |
| Berry Global Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term resin offtake agreements between Reliance Industries and western India molders lock in polypropylene supply access and compress price volatility exposure for certified suppliers serving FSSAI-mandated beverage segments. This contract structure fragments procurement power across tier-one multinationals with volume leverage versus mid-tier domestic specialists exposed to spot resin markets.
Pricing Analysis
Contract-based long-term offtake dominates procurement between Reliance, IOCL, and volume molders, while spot purchases persist for smaller Gujarat pharmaceutical specialists. Price differentiation rests on BIS certification tier and volume scale, with certified suppliers commanding premium positioning over non-compliant competitors. Pricing pressure stems from naphtha-linked resin volatility squeezing margins for molders without captive supply agreements. Regional edible oil packagers in Madhya Pradesh exhibit highest price sensitivity, while Ahmedabad pharmaceutical contract manufacturers prioritize CDSCO compliance over unit cost.
Supply Chain Analysis
Saudi Arabia, South Korea, and Singapore anchor polypropylene resin supply into Indian ports, with domestic Reliance and IOCL crackers providing partial coverage. Tool steel for multi-cavity molds draws from Germany and Japan, while hot-runner components rest on Austrian and Italian specialist imports. Single-source vulnerability concentrates in pharmaceutical-grade mold steel qualified for CDSCO-validated production. Distribution runs through Mumbai and Ahmedabad warehousing nodes serving Maharashtra and Gujarat manufacturing corridors, with secondary routing to Bengaluru and Chennai personal care formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's plastic caps and closures market sits in early-cycle expansion, with hot-fill beverage line upgrades and CDSCO pharmaceutical compliance mandates driving penetration depth ahead of saturation.
For Market Incumbents: Fortify BIS and CDSCO certification portfolios to preempt supplier base compression as regulatory timelines tighten. Backward integration into rPP and rPE sourcing partnerships secures Extended Producer Responsibility compliance ahead of CPCB threshold enforcement. Capacity addition in Assam and Meghalaya anchors first-mover position in underdeveloped north-eastern beverage bottling corridors before distributor networks consolidate.
For New Entrants and Emerging Players: Lead with customized mold turnaround capabilities for mid-tier Gujarat pharmaceutical clients seeking validated child-resistant designs without multinational minimum order constraints. Target Nashik and Aurangabad hot-fill line expansions where polypropylene thermal performance specifications outstrip incumbent polyethylene-focused supplier capabilities. Pursue direct procurement relationships with centralized Mumbai beverage bottler procurement functions, bypassing compressed distributor margins.
For Investors and Strategic Acquirers: Domestic specialists with validated USP 671 torque testing partnerships and Ahmedabad contract packaging organization relationships represent priority acquisition archetypes. Long-term viability frames around 5-10 year regulatory compliance deepening rather than commodity volume cycles. Monitor BIS harmonization timeline acceleration with FSSAI as inflection signal for certification-ready tooling investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPP Sourcing | CPCB Extended Producer Responsibility thresholds reward molders with approved recycled content partnerships ahead of mandate enforcement. |
| Hot-Fill Line Capacity Expansion | Nashik and Aurangabad bottlers upgrading to 85°C+ filling lines require polypropylene-grade closure supply unavailable from legacy polyethylene molders. |
| CDSCO Validation Partnership | Ahmedabad contract packaging organizations accelerate procurement consolidation around torque-tested suppliers preempting senior-friendly child-resistant mandates. |
| North-Eastern Distribution Buildout | Assam and Meghalaya beverage capacity gaps create first-mover whitespace before regional bottler procurement centralizes around Mumbai-tier suppliers. |
| Smart Closure NFC Integration | Pharmaceutical and liquor authentication demand merges tamper-evident designs with premium pricing tiers for track-and-trace compliance. |
Research Methodology
Initial hypotheses were tested against primary input from injection molding plant managers, beverage bottler procurement heads, pharmaceutical contract packaging executives, and toolroom engineering specialists, then refined against secondary validation from BIS certification registries, CDSCO guidance documents, FSSAI notification archives, and Reliance-IOCL petrochemical pricing disclosures. Bottom-up capacity modeling across Maharashtra and Gujarat manufacturing clusters triangulated with top-down resin consumption estimates from customs and trade flow data.
Variance decomposition across cap type, material grade, end-use application, and design feature segmentation dimensions structured the analytical framework over the projection horizon. CAGRs were derived from unit volume trajectory modeling against per-capita packaged goods consumption elasticity and line-upgrade capital expenditure cycles. Hot-fill line conversion rates and CDSCO compliance deadline phasing served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained petrochemical feedstock price stability or accelerated BIS-FSSAI harmonization timelines would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and resin supply contract renewal patterns. Recalibration cycles align with material shifts in CPCB Extended Producer Responsibility threshold announcements and CDSCO pharmaceutical packaging guideline amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
End Cap Market
Caps and Closures
Crimp-On Spouts Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Pressure Sensitive Wads Market
Caps and Closures
Dispensing Spouts Market
Caps and Closures
T-Top Closures Market
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
Clic Loc Closure Market
Caps and Closures
Overcaps Market
Caps and Closures
Polypropylene Screw Caps Market
Caps and Closures
Tube Closures Market
Caps and Closures
Thailand Plastic Caps and Closures Market
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
Magnetic Closure Box Market