
 Polypropylene Screw Caps Market | 2026-2036
Polypropylene Screw Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Polypropylene Screw Caps Market Analytics
Pharmaceutical-grade closure specifications is unwinding legacy commodity dynamics across the polypropylene screw caps landscape. Berry Global Inc. leverages its North American blow-molding infrastructure to anchor high-volume pharmaceutical contracts. Amcor plc sustains multi-continent manufacturing scale that competes on regulatory compliance breadth. Silgan Holdings Inc. specializes in metal-plastic hybrid technologies that differentiate its portfolio for sensitive drug applications.
Polypropylene screw caps are injection-molded thermoplastic closures featuring standardized thread profiles, tamper-evident bands, and dimensional tolerances typically held within 0.1mm for pharmaceutical cGMP compliance. Their primary purpose is to seal container contents against contamination, moisture ingress, and oxidation while enabling repeatable consumer access. Pharmaceutical caps command premium margin pools due to USP Class VI and child-resistant testing requirements, while beverage caps dominate unit volume through 38mm and 28mm neck finish standardization. Screw-on mechanisms retain the largest installed base, though flip-top formats are gaining share in personal care dispensing applications where single-handed operation drives consumer preference.
FDA 21 CFR Part 211, EMA Annex 1 revision, and ISO 15378 standards collectively mandate particulate control, traceability, and extractables testing that elevate barrier-to-entry for closure suppliers. The EU Green Deal's packaging waste reduction targets are forcing material lightweighting investments and post-consumer recycled content integration into virgin polypropylene streams. Stakeholders must monitor evolving pharmacopeial extractables thresholds and state-level extended producer responsibility laws that will determine which manufacturing configurations retain economic viability.
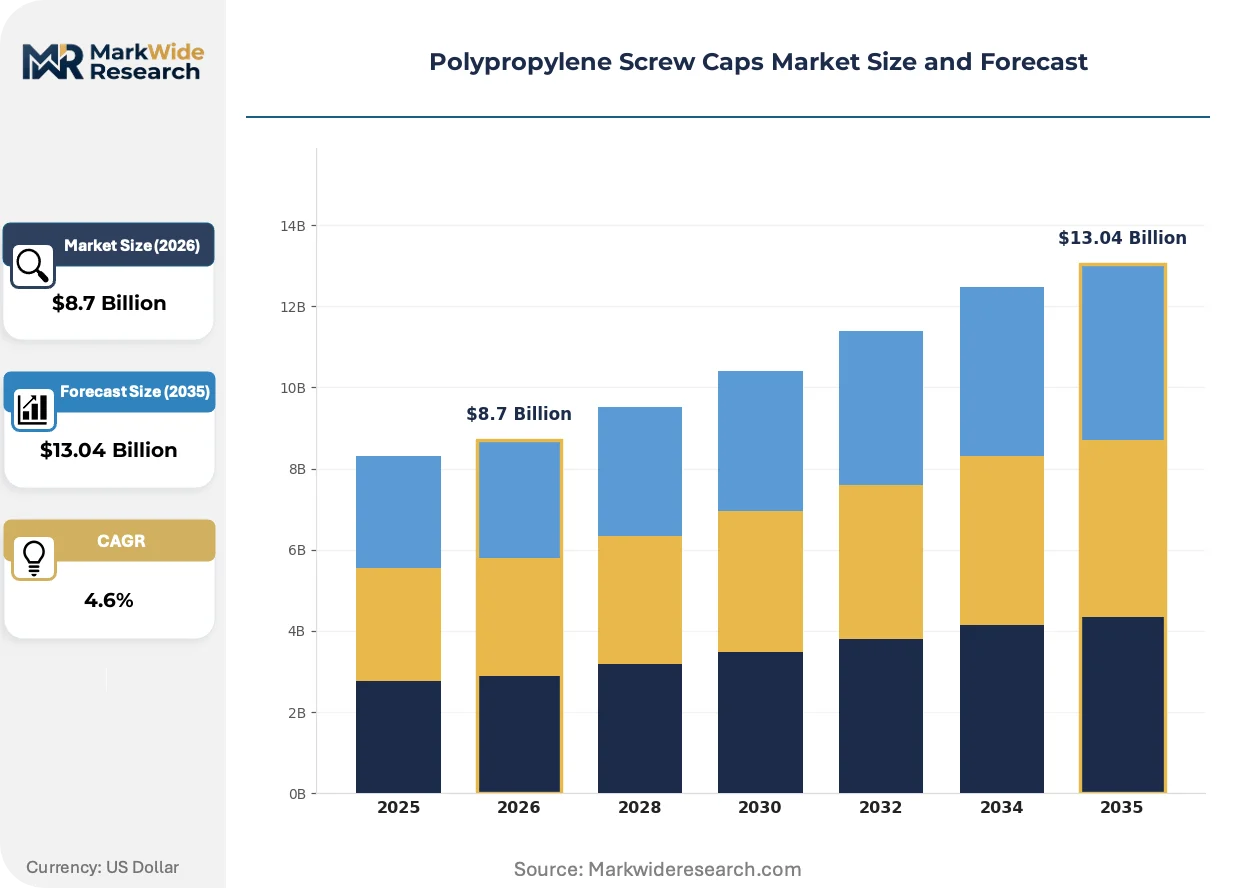
Market Dynamics
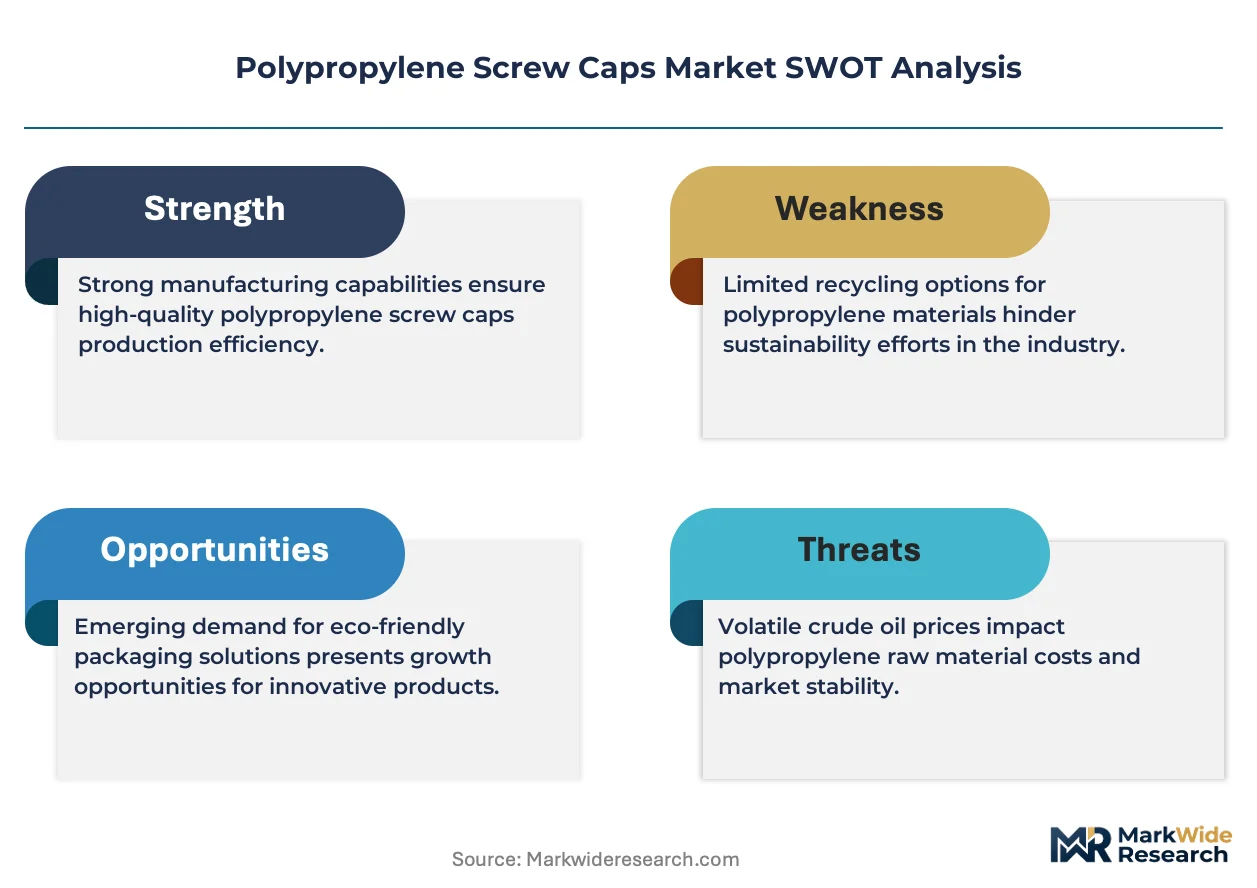
EMA serialization mandates and FDA 21 CFR Part 211 enforcement are compressing supplier margins while elevating barrier-to-entry for pharmaceutical-grade closure manufacturers. These dual regulatory pressures are forcing capital reallocation toward cGMP-compliant cleanroom infrastructure and extractables testing capabilities.
Growth Catalysts
- Chronic disease prevalence:Patient access program expansions in oncology and diabetes care are driving unit volume for prescription vial closures. Pharmaceutical contract manufacturers in India are scaling capacity to serve export markets.
- EMA Annex 1 revision:The 2022 update to sterile manufacturing guidelines mandates enhanced container closure integrity testing. This elevates demand for high-precision injection-molded caps with validated seal performance.
- Post-consumer recycled integration:EU Green Deal packaging waste targets are accelerating rPP blend development. Closure suppliers with advanced compounding capabilities are capturing premium positioning in sustainability-driven tenders.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics and regional refinery utilization swings create margin unpredictability for virgin polypropylene converters.
- Single-supplier concentration:Pharmaceutical-grade colorant and additive sourcing concentrates among three German specialty chemical houses, creating qualification bottlenecks for new market entrants.
- Aluminum substitution in sensitive biologics:Metal crimp seals retain preference for lyophilized parenterals requiring absolute oxygen barrier, limiting PP cap penetration in high-value cold-chain drugs.
Strategic Opportunities
- ASEAN pharmaceutical manufacturing:Vietnam and Indonesia are attracting FDA-inspected sterile fill-finish investments. Local closure supply remains underdeveloped relative to formulation capacity.
- Connected packaging convergence:NFC-enabled caps integrating authentication and adherence tracking are opening new revenue pools. Pharmaceutical brand owners in anti-counterfeiting verticals represent early adopters.
- Extended producer responsibility tailwinds:California's SB 54 and pending EU packaging and packaging waste regulation revisions mandate minimum recycled content. Suppliers with certified rPP supply chains gain preferential sourcing status.
Industry Challenges
- Extractables validation timelines:USP Class VI and ISO 10993 biocompatibility testing cycles extend 18-24 months for new polymer grades, compressing product development windows.
- Cleanroom capex intensity:ISO 8 or better injection molding environments require seven-figure capital commitments per production line, constraining mid-tier expansion.
- Serialization integration complexity:Aggregation of unique device identifiers at the tertiary packaging level demands IT infrastructure upgrades that many legacy closure suppliers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polypropylene Screw Caps Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Child-Resistant Caps, Spice Caps, Beverage Caps, Pharmaceutical Caps End User: Pharmaceuticals, Food & Beverage, Personal Care, Household Products Closure Mechanism: Screw On, Snap On, Flip Top, Dropper Top Size: 20mm, 38mm, 50mm, 63mm |
| Companies Covered | Berry Global Inc., Amcor plc, Silgan Holdings Inc., AptarGroup Inc., BERICAP, Closure Systems International, Guala Closures S.p.A, United Caps, Crown, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polypropylene Screw Caps Market Evolving Landscape
Material science advances and regulatory stringency are converging to redefine performance specifications across pharmaceutical and consumer packaging closures. Three developments are actively restructuring competitive positioning.
Thin-wall injection molding with in-mold labeling is supplanting conventional thick-wall designs in over-the-counter pharmaceutical applications. Major retail pharmacy chains are specifying these formats for their private-label analgesic and supplement lines. The shift enables 15-20% material reduction per unit while maintaining child-resistant torque specifications.
REACH SVHC candidate list expansions and ECHA restrictions on intentionally added microplastics are forcing reformulation of slip agents and UV stabilizers used in polypropylene closures. Compounders serving the European pharmaceutical market are accelerating migration to bio-based lubricant alternatives. The transition imposes temporary qualification delays but creates durable differentiation for compliant suppliers.
Direct-to-pharmacy distribution models are compressing traditional wholesale channel dominance in North American generic drug markets. Large health systems and pharmacy benefit managers are consolidating procurement through preferred supplier agreements that specify closure performance metrics. The concentration is most visible in 340B program purchasing, where compliance documentation requirements favor vertically integrated packaging suppliers.
Polypropylene Screw Caps Market Segmentation
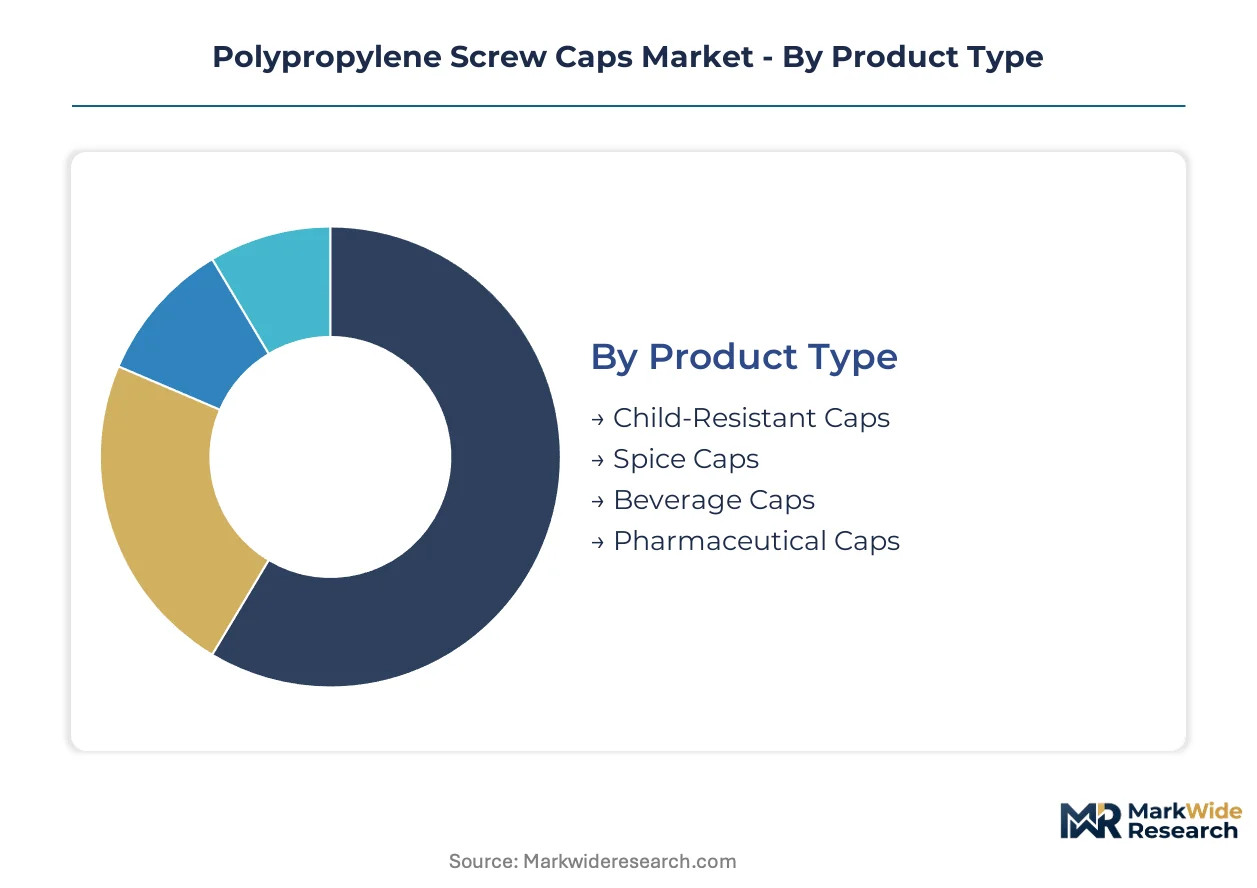
Polypropylene screw caps serve divergent performance requirements across pharmaceutical safety, food preservation, and consumer convenience applications. Channel distribution patterns vary sharply by segment—pharmaceutical caps flow through validated supply chains with cGMP documentation, while beverage caps move through high-volume procurement networks where neck finish standardization dominates sourcing decisions.
Product Type:
Channel mix varies dramatically by safety certification and volume economics, with pharmaceutical and beverage caps following entirely different distribution logic.
- Pharmaceutical Caps:These closures incorporate USP Class VI certified resins, child-resistant torque mechanisms, and tamper-evident bands validated to FDA 21 CFR Part 211. Demand concentrates in North American and European contract manufacturing organizations where serialization aggregation requirements favor suppliers with integrated track-and-trace capabilities. EMA Annex 1 revision compliance creates qualification barriers that protect incumbent positioning.
- Beverage Caps:Standardized 28mm and 38mm neck finishes dominate procurement specifications for carbonated soft drinks and bottled water. High-speed capping line compatibility and lightweighting targets drive material formulation decisions. The segment channels through beverage brand owner consolidated procurement functions where billion-unit annual contracts reward scale infrastructure.
- Child-Resistant Caps:Dual-action opening mechanisms combining push-and-turn torque profiles with senior-friendly accessibility specifications. Applications span OTC analgesics and household chemical containers where Poison Prevention Packaging Act compliance is mandatory.
- Spice Caps:Dispensing orifices with shaker or pour configurations, often integrating moisture barrier induction seals. Food-grade compliance and flavor migration resistance define material selection criteria for retail spice brand owners.
By volume, Beverage Caps leads. By growth pace, Pharmaceutical Caps is ahead.
End User:
Margin structure and qualification intensity separate these customer categories, with pharmaceutical and food applications commanding premium pricing against commoditized household segments.
- Pharmaceuticals:Sterile manufacturing requirements and extractables testing protocols elevate barrier-to-entry. ISO 15378 certification and cleanroom molding environments are baseline qualifications. Demand drivers include chronic disease prevalence expansion and biologics cold-chain growth requiring validated container closure integrity.
- Food & Beverage:Oxygen barrier performance and organoleptic neutrality specifications govern material formulation. Extended shelf-life targets for aseptic packaging are accelerating multilayer co-injection development among closure suppliers serving dairy and juice processors.
- Personal Care:Flip-top and disc-top dispensing formats dominate shampoo and lotion applications. Single-handed operation convenience drives consumer preference shifts that reshape procurement specifications for mass-market beauty brands.
- Household Products:Bleach, detergent, and cleaning chemical applications emphasize chemical resistance and child-resistant compliance. Price sensitivity is acute, with private-label concentration pressuring converter margins.
Pharmaceuticals captures the highest margin pool. Food & Beverage generates the largest unit throughput.
Closure Mechanism:
Manufacturing process economics and consumer interaction patterns create distinct competitive dynamics across opening technologies.
- Screw On:Threaded engagement with standardized pitch profiles remains the installed base majority. Pharmaceutical vial and bottle applications require validated torque removal specifications. The mechanism dominates legacy infrastructure compatibility requirements.
- Flip Top:Hinged living-hinge construction enables single-handed dispensing. Personal care and condiment applications are expanding share where convenience positioning commands shelf price premiums. Tooling complexity elevates initial capital requirements versus screw formats.
- Snap On:Radial interference fit designs for single-use applications where resealability is secondary to cost minimization. Dairy and portion-control food packaging represent primary demand concentrations.
- Dropper Top:Integrated pipette or bulb assemblies for pharmaceutical and cosmetic precision dosing. Assembly automation requirements and component count elevate manufacturing complexity versus monolithic cap designs.
Screw On retains volume leadership. Flip Top is climbing the fastest on convenience-driven substitution.
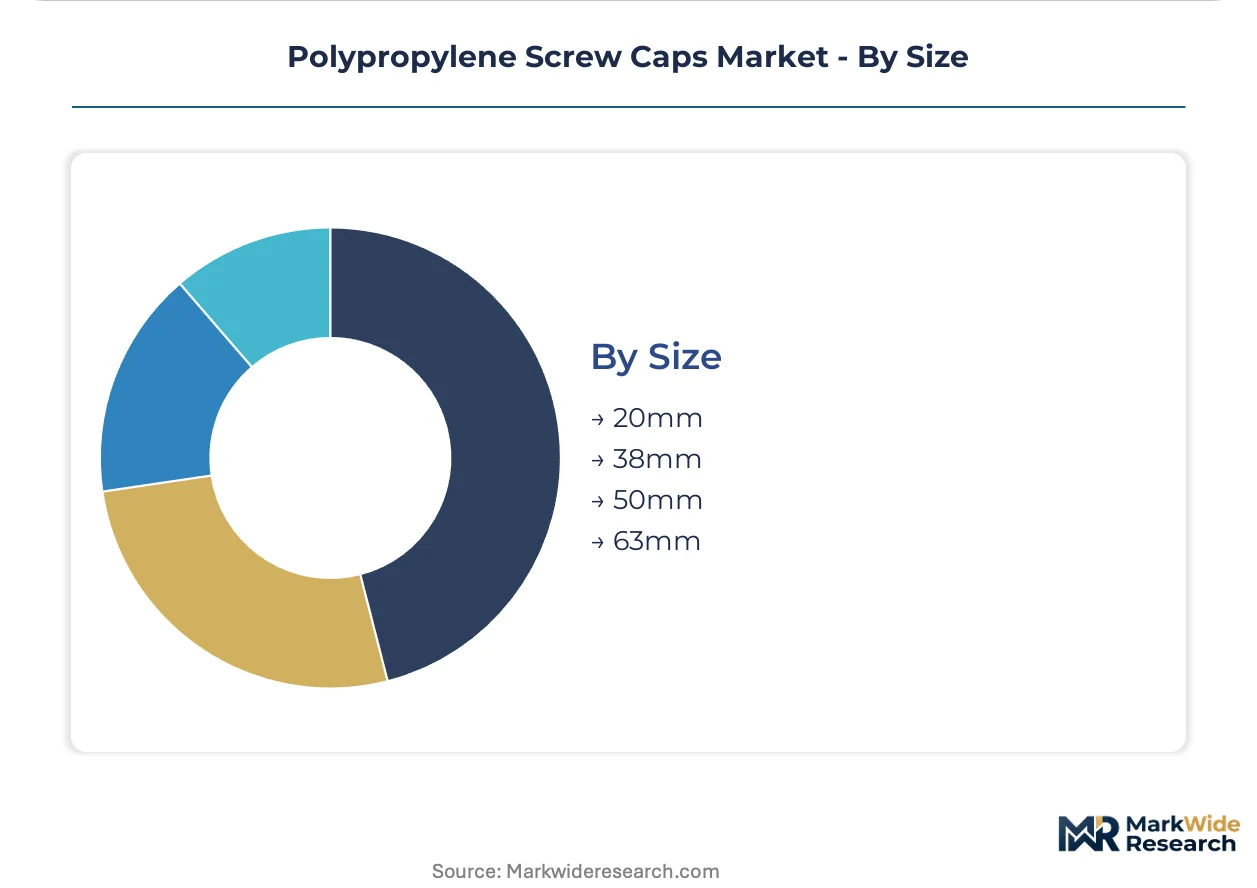
Size:
Neck finish standardization creates volume concentration effects that reshape tooling investment returns across diameter specifications.
- 38mm:Beverage industry standard for carbonated soft drinks and water bottles. High-volume procurement contracts and global equipment compatibility sustain demand concentration. Lightweighting targets are driving wall-thickness reduction initiatives among major brand owners.
- 28mm:Predominant specification for still water and single-serve beverage applications. Neck finish standardization enables converter scale economies and inventory pooling across multiple brand customers.
- 20mm:Pharmaceutical vial and small-format personal care primary specification. Precision molding tolerances and child-resistant mechanism integration elevate technical requirements versus larger formats.
- 50mm:Wide-mouth jar applications for food spreads, supplements, and institutional chemical packaging. Lower volume concentration versus beverage standards creates sourcing fragmentation.
- 63mm:Large-format container specification for industrial and bulk household product applications. Regional specification variation limits global standardization benefits.
38mm generates the highest unit volumes. 20mm is gaining share fastest on pharmaceutical packaging expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Closure manufacturing clusters concentrate in Germany, the United States, India, and China, each serving distinct regulatory and demand environments. Material compounding capabilities and pharmaceutical serialization infrastructure differentiate competitive positioning across these production centers.
United States
FDA 21 CFR Part 211 enforcement and 340B program procurement concentration drive demand for validated pharmaceutical closures. Berry Global Inc. anchors high-volume production through North American blow-molding infrastructure. The New Jersey-Pennsylvania corridor hosts contract manufacturing organizations requiring integrated track-and-trace capabilities.
Germany
EMA serialization mandates and REACH SVHC compliance requirements elevate barrier-to-entry for closure suppliers. BERICAP and Guala Closures S.p.A. maintain compounding operations serving European pharmaceutical tenders. The Baden-Württemberg cluster specializes in metal-plastic hybrid technologies for sensitive drug applications.
India
BIS certification requirements and export-oriented pharma growth drive premium closure adoption in contract manufacturing. CDSCO regulatory alignment with FDA and EMA standards enables sterile fill-finish investments in Hyderabad and Ahmedabad. Maharashtra's pharmaceutical belt concentrates demand for USP Class VI certified resins.
China
NMPA pharmaceutical packaging regulations and domestic biologics capacity expansion reshape material specifications. Yangtze River Delta injection molders serve both export and domestic health product markets. Shanghai-based compounders are developing post-consumer recycled polypropylene blends for sustainability-driven tenders.
Japan
PMDA sterile manufacturing guidelines and aging-related chronic disease prevalence expand prescription vial closure demand. METI packaging waste reduction targets accelerate lightweighting investments among Kanto region molders. Osaka pharmaceutical clusters require validated container closure integrity testing for oncology drug packaging.
Polypropylene Screw Caps Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the polypropylene screw caps landscape. The market structures around three tiers: multinational packaging conglomerates with integrated pharmaceutical serialization, regional specialists with compounding expertise, and commodity converters serving high-volume beverage applications. Strategic moves concentrate on backward integration into resin compounding and geographic expansion into underdeveloped ASEAN pharmaceutical manufacturing.
Within the multinational tier, Berry Global Inc., Amcor plc, and Silgan Holdings Inc. exemplify divergent competitive positions. Berry Global Inc. represents scale-driven infrastructure plays anchored in North American pharmaceutical contracts. Amcor plc occupies a position defined by multi-continent regulatory compliance breadth. Silgan Holdings Inc. exemplifies hybrid technology specialists serving oxygen-sensitive drug applications where metal-plastic combinations retain preference.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Amcor plc |
| Silgan Holdings Inc. |
| AptarGroup Inc. |
| BERICAP |
| Closure Systems International |
| Guala Closures S.p.A |
| United Caps |
| Crown |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day resin qualification timelines for USP Class VI certified polypropylene concentrate purchasing power among established compounders while squeezing spot-market buyers. Pharmaceutical-grade closure specifications create pricing premiums that widen during feedstock volatility, as validated supply chains command stability premiums against commodity converters.
Pricing Analysis
FDA 21 CFR Part 211 dictates the pricing tier structure across pharmaceutical-grade, food-grade, and industrial-grade closure segments. Three-tier pricing separates USP Class VI certified premium caps from ISO 15378 standard-grade and uncertified economy tiers based on extractables testing documentation and cleanroom production overhead. Cost compression in beverage-grade 28mm and 38mm formats is intensifying because lightweighting mandates force material reduction investments without commensurate price recovery. Household product buyers exhibit acute price sensitivity, while oncology drug manufacturers absorb premiums for validated container closure integrity.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for German specialty additive suppliers serving Indian pharmaceutical molders. Virgin polypropylene resin production concentrates in Saudi Arabia, South Korea, and the United States, while pharmaceutical-grade colorant compounding draws from German and Swiss specialty chemical houses. Single-source vulnerability permeates USP Class VI certified resin streams, where three qualified suppliers control global capacity. Distribution runs through validated supply chains with cGMP documentation for pharmaceutical applications, contrasting with high-volume spot procurement networks for beverage closures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified cleanroom molding capacity operates below demand growth across ASEAN pharmaceutical manufacturing corridors, creating durable scarcity rents for incumbent suppliers with established regulatory dossiers. The capability gap centers on integrated serialization infrastructure combined with extractables validation laboratories.
For Market Incumbents: Secure backward integration into pharmaceutical-grade resin compounding to defend margin structures against propylene feedstock volatility. Expand ISO 8 cleanroom capacity in Vietnam and Indonesia ahead of FDA-inspected sterile fill-finish investments. Aluminum substitution in lyophilized parenterals threatens high-value segment positioning—accelerate hybrid metal-plastic development to retain oxygen barrier applications. For New Entrants and Emerging Players: Lead with post-consumer recycled polypropylene blend capabilities targeting EU Green Deal packaging waste compliance tenders. ASEAN pharmaceutical contract manufacturing offers the most penetrable geography, where local closure supply lags formulation capacity expansion. Pursue direct qualification partnerships with Indian CDSCO-registered sterile manufacturers seeking dual USP Class VI and EMA Annex 1 compliance documentation. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational packaging conglomerates divesting non-core beverage closure assets to refocus on pharmaceutical serialization capabilities. Five-to-ten year viability favors suppliers with captive rPP supply chains and integrated track-and-trace IT infrastructure. Monitor California SB 54 implementation enforcement as the signal to watch for recycled content mandate acceleration driving preferential sourcing shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive USP Class VI supply insulates margin structures against German additive supplier concentration. |
| Cleanroom Capacity Expansion | ASEAN pharmaceutical manufacturing investments create qualified supply scarcity in Vietnam and Indonesia. |
| Post-Consumer Recycled Blend Development | EU Green Deal packaging waste targets mandate minimum rPP content in sustainability-driven tenders. |
| Serialization Infrastructure Deployment | EMA aggregation requirements and FDA track-and-trace mandates favor integrated IT-capable suppliers. |
| Hybrid Metal-Plastic Technology Investment | Oxygen barrier specifications for biologics cold-chain applications defend against aluminum crimp seal substitution. |
Research Methodology
Desk research of FDA 21 CFR filings, EMA Annex 1 revision documentation, and ISO 15378 certification registries preceded structured interviews with pharmaceutical packaging procurement directors, sterile manufacturing quality heads, and resin compounding technical leads. Primary fieldwork with contract manufacturing organizations in India and ASEAN markets combined with secondary validation through customs trade data and pharmaceutical packaging tender databases. Bottom-up unit volume estimates across neck finish specifications triangulated against top-down market value reconstruction.
Variance decomposition across product type, end-use industry, closure mechanism, and regional regulatory cluster dimensions anchored the analytical framework throughout the projection horizon. CAGRs derived from segmented growth rate blending weighted by margin pool contribution. Forecast inputs incorporated chronic disease prevalence expansion trajectories, EMA serialization mandate implementation pace, and EU Green Deal recycled content threshold evolution.
The analysis sits within stated boundaries; outcomes outside sustained pharmaceutical outsourcing trends, stable propylene feedstock economics, or unaltered regulatory compliance thresholds would require recalibration. Forecasts reflect documented assumptions regarding sterile manufacturing capacity expansion and post-consumer recycled polypropylene blend qualification timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Beverage Caps and Closures Market
Caps and Closures
Nigeria Plastic Caps and Closures Market
Caps and Closures
PVC-Free Cap Liners Market
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
Spout Closures Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Side Pour Caps Market
Caps and Closures
Peelable Lid Stock Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Plastic Caps and Closure Market
Caps and Closures
IBC Caps Market
Caps and Closures
Crimp Top Cap Market
Caps and Closures
Asia Pacific Metal Caps and Closures Market
Caps and Closures
Spray Caps Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Australia and New Zealand Plastic Caps and Closures Market