
 Bi-Injected Snap Hinge Closure Market | 2026-2036
Bi-Injected Snap Hinge Closure Market Size, Share, and Industry Trends Forecast 2026-2036
Bi-Injected Snap Hinge Closure Market Outlook
Polypropylene is shifting into bi-injected snap hinge closures as a cost-efficient alternative to engineered thermoplastics in mid-tier packaging applications. AptarGroup Inc. leverages its pharmaceutical dispensing expertise to dominate high-compliance closure segments. Berry Global Inc. sustains volume leadership through captive resin compounding and North American manufacturing scale. Silgan Holdings Inc. anchors its position via backward integration into injection molding equipment and metal closure hybridization.
A bi-injected snap hinge closure is a dual-material, single-shot molded fastening device combining a rigid substrate with a flexible living hinge, typically achieving 180-degree flex cycles exceeding 10,000 operations without fatigue failure. Its primary purpose is to deliver tamper-evident, resealable sealing in consumer goods and industrial packaging where repeated access and container integrity must coexist. The plastic product type occupies the largest volume share due to cost scalability across beverage and personal care applications, while composite formulations represent the fastest-growing margin pool as OEMs pursue weight reduction in automotive interior panels. Snap-on installation leads in unit terms across consumer electronics and furniture assembly, though screw-on variants command premium pricing in pharmaceutical and chemical containment where threaded engagement ensures hermetic seals under transport stress.
The European Chemicals Agency enforces REACH substance restrictions on phthalates and heavy metal stabilizers in polyolefin closures, directly constraining formulation choices for suppliers serving EU member states. FDA's 21 CFR Part 177 indirect food additive regulations and the EU Packaging and Packaging Waste Directive collectively shape migration testing protocols and recyclability mandates that determine market access for imported closure assemblies. Stakeholders must monitor evolving extended producer responsibility frameworks and bio-based content thresholds, as these will determine which material platforms and geographic production bases retain competitive viability through the forecast horizon.
Market Dynamics
REACH chemical compliance and the EU Packaging and Packaging Waste Regulation are forcing material reformulation across European supply chains, with Bavaria's precision molding cluster and the Rhône-Alpes plastics corridor absorbing the bulk of compliance investment.
Growth Catalysts
- Child-resistant closure mandates:Pharmaceutical packaging lines in Germany and France are expanding orders for compliant bi-injected closures, tightening specifications for pediatric safety.
- REACH substance restrictions:Phthalate and heavy metal stabilizer bans in polyolefin closures are accelerating migration toward bio-based and compliant engineered thermoplastics.
- Precision molding cluster concentration:Bavaria's tooling expertise and the Rhône-Alpes corridor's resin compounding capabilities are shortening development cycles for complex dual-material designs.
Market Restraints
- Resin price volatility:Polypropylene and engineered thermoplastic feedstock costs fluctuate with crude oil derivatives, compressing margins for mid-tier packaging converters.
- Specialized tooling concentration:Bi-injection mold fabrication depends on a narrow base of German and Swiss equipment suppliers, creating capacity bottlenecks during demand surges.
- Migration testing burden:FDA's 21 CFR Part 177 indirect food additive protocols and EFSA cumulative exposure assessments extend certification timelines for new material formulations.
Strategic Opportunities
- Automotive interior light-weighting:Composite bi-injected closures for cabin trim panels represent an emerging application as OEMs pursue gram-level mass reduction targets.
- Extended producer responsibility frameworks:EU Packaging and Packaging Waste Directive recyclability mandates favor mono-material-compatible designs and bio-based content thresholds.
- Hybrid metal-plastic convergence:Screw-on variants with metal thread inserts are penetrating pharmaceutical containment where hermetic seals under transport stress command premium positioning.
Industry Challenges
- Living hinge fatigue expertise:Tooling engineers capable of optimizing 180-degree flex cycles exceeding 10,000 operations remain scarce in emerging molding regions.
- Dual-material recycling streams:Separating rigid substrates from flexible living hinges at end-of-life requires infrastructure investment that lags regulatory timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bi-Injected Snap Hinge Closure Market |
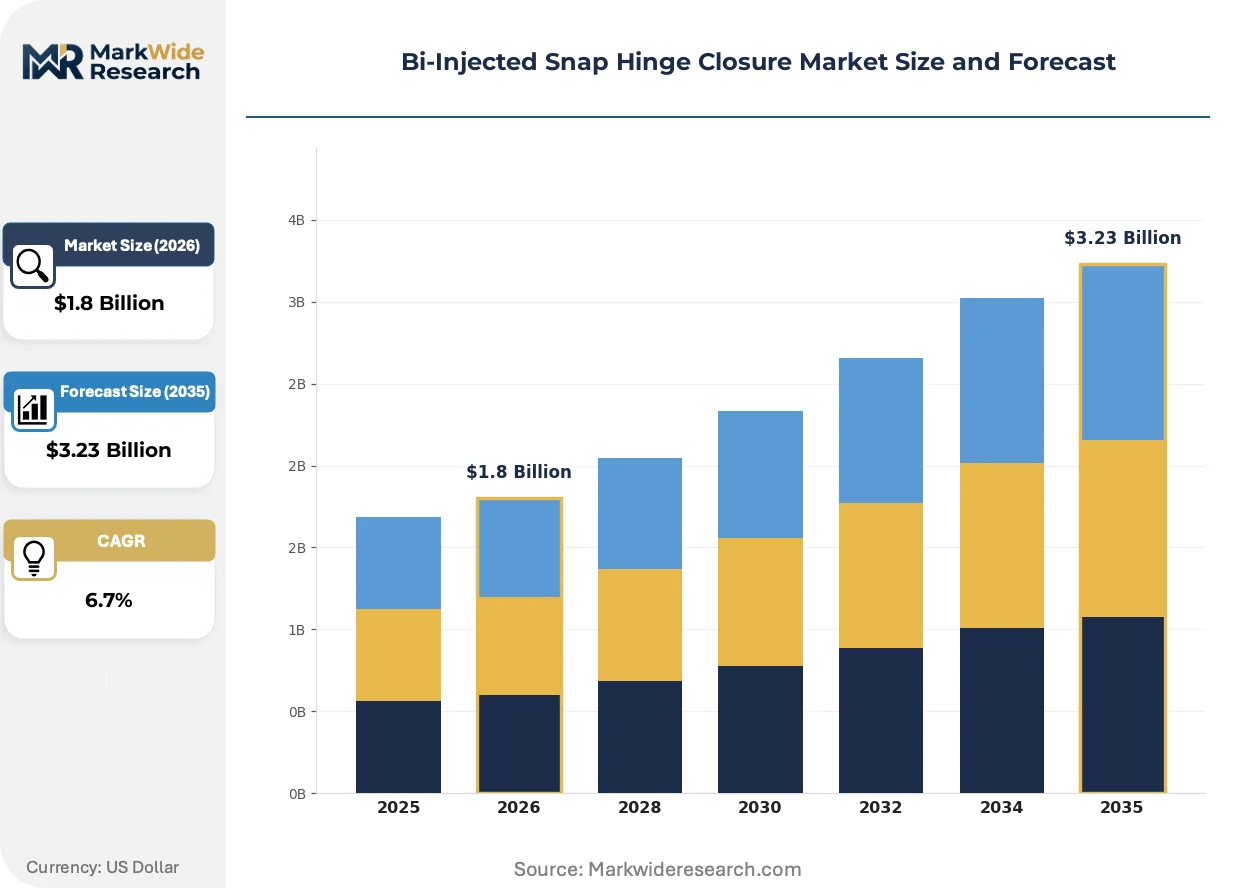
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Composite, Hybrid Application: Consumer Electronics, Packaging, Automotive Components, Furniture Installation: Snap-On, Screw-On, Adhesive, Integrated End User: Manufacturers, Distributors, Retailers, OEMs |
| Companies Covered | Silgan Holdings Inc., AptarGroup Inc., Berry Global Inc., Bericap GmbH, United Caps Luxembourg S.A., Global Closure Systems, Amcor plc, ALPLA Group, Guala Closures Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bi-Injected Snap Hinge Closure Market Strategic Shifts
Material science advances and regulatory pressure on chemical compliance are compressing development cycles while expanding the addressable application set beyond traditional packaging boundaries.
Polypropylene copolymer formulations are integrating elastomer-modified living hinge segments to achieve fatigue resistance previously requiring engineered thermoplastics. Personal care and beverage converters in Germany are adopting these grades at accelerating pace. The technology is integrating cost-efficient alternatives into mid-tier applications previously reserved for premium material platforms.
REACH Annex XVII restrictions on phthalate plasticizers and heavy metal stabilizers are constraining formulation choices for suppliers serving EU member states. Industrial consequence includes accelerated qualification of calcium-zinc and bio-based stabilizer systems. Pharmaceutical closure manufacturers in France and Germany are responding with dedicated regulatory affairs functions to manage substance authorization timelines.
Direct procurement relationships between brand owners and specialized molders are displacing traditional distributor intermediaries in high-compliance segments. Pharmaceutical and chemical containment buyers now require audit-access to compounding and molding operations. This pattern concentrates most visibly in Germany's Bavaria cluster where child-resistant certification demands transparent supply chain documentation.
Bi-Injected Snap Hinge Closure Market Segmentation
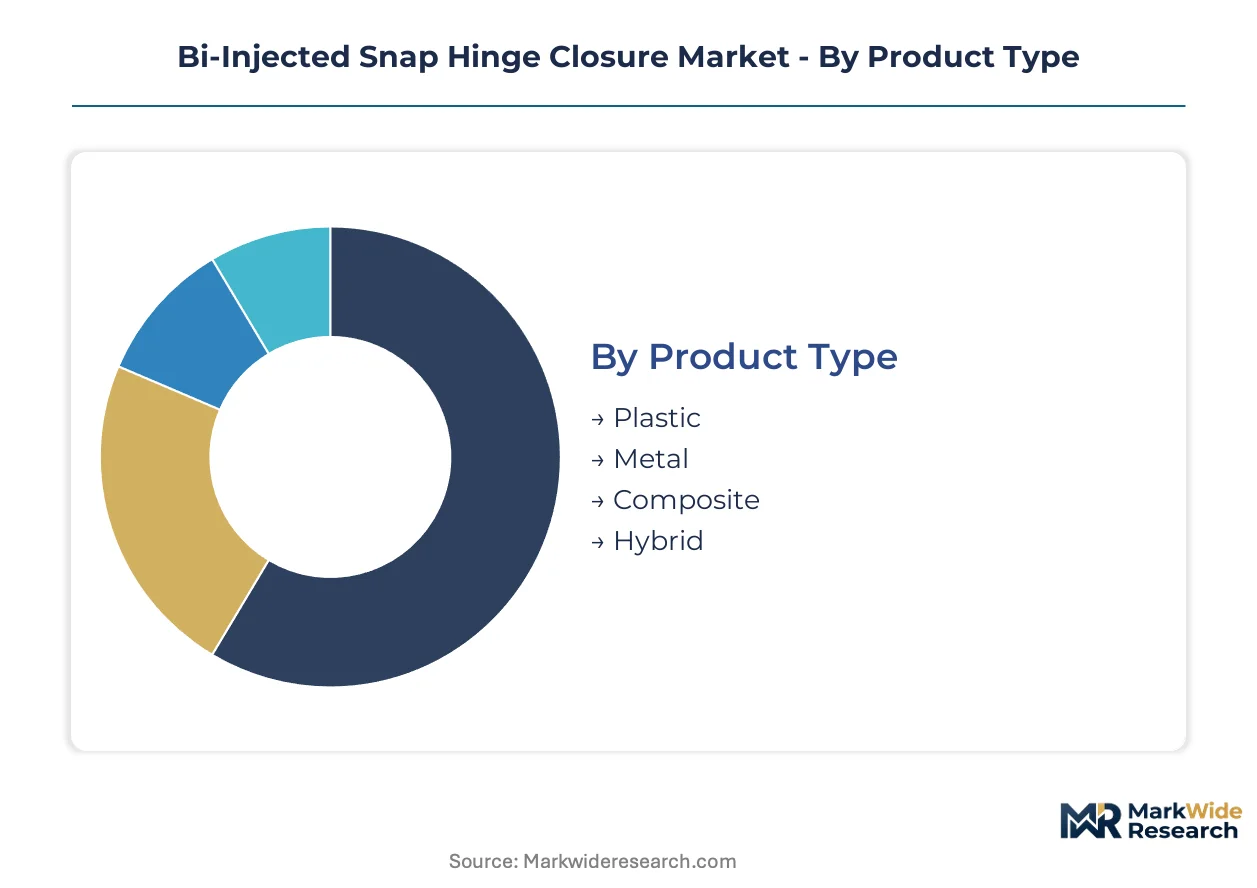
Segmentation in bi-injected snap hinge closures reveals how material selection, installation geometry, and end-user procurement power fragment pricing and compliance requirements across otherwise similar functional specifications.
Product Type:
The customization-vs-standardization spectrum runs from commodity polyolefins to engineered multi-material laminates requiring dedicated tooling investment.
- Plastic:Polypropylene copolymers dominate volume through cost-efficient living hinge fatigue resistance. Bavarian pharmaceutical packagers specify these grades for child-resistant closures under ECHA REACH substance restrictions.
- Composite:Glass-fiber reinforced thermoplastic hybrids achieve gram-level mass reduction targets for automotive interior panels. Rhône-Alpes compounders supply these formulations to French OEMs pursuing cabin light-weighting mandates.
- Metal:Aluminum and steel substrates serve high-temperature chemical containment applications requiring thermal stability beyond polymer limits.
- Hybrid:Metal thread inserts bonded to plastic bodies command premium positioning in pharmaceutical screw-on variants demanding hermetic seals under transport stress.
Leading the category by volume: Plastic. Growing fastest: Composite.
Application:
Cost tier separation distinguishes single-use consumer disposables from capital-intensive automotive qualification cycles.
- Packaging:Beverage and personal care converters in Germany drive standardization through high-volume procurement. EFSA migration testing protocols constrain material choices for food-contact closures.
- Automotive Components:Tier-1 suppliers in Stuttgart and Munich require PPAP documentation and 10,000-cycle fatigue validation for cabin trim applications.
- Consumer Electronics:Snap-on variants for device housings prioritize rapid assembly over resealability.
- Furniture:Flat-pack assembly systems favor low-cost snap hinge designs with limited cycle life requirements.
Packaging dominates unit shipments. Automotive Components expands most quickly as OEMs adopt interior panel applications.
Installation:
Customer type fragmentation separates specification-driven pharmaceutical buyers from price-sensitive furniture assemblers.
- Snap-On:Rapid engagement without tools dominates consumer electronics and furniture assembly where access frequency remains low.
- Screw-On:Threaded variants with metal inserts penetrate pharmaceutical containment where FDA 21 CFR Part 177 compliance and hermetic integrity justify premium positioning.
- Adhesive:Permanent bonding suits single-use medical device packaging requiring tamper evidence without resealability.
- Integrated:Molded-in hinge structures eliminate secondary assembly for high-volume beverage closures.
Snap-On leads in unit terms. Screw-On commands highest average selling prices.
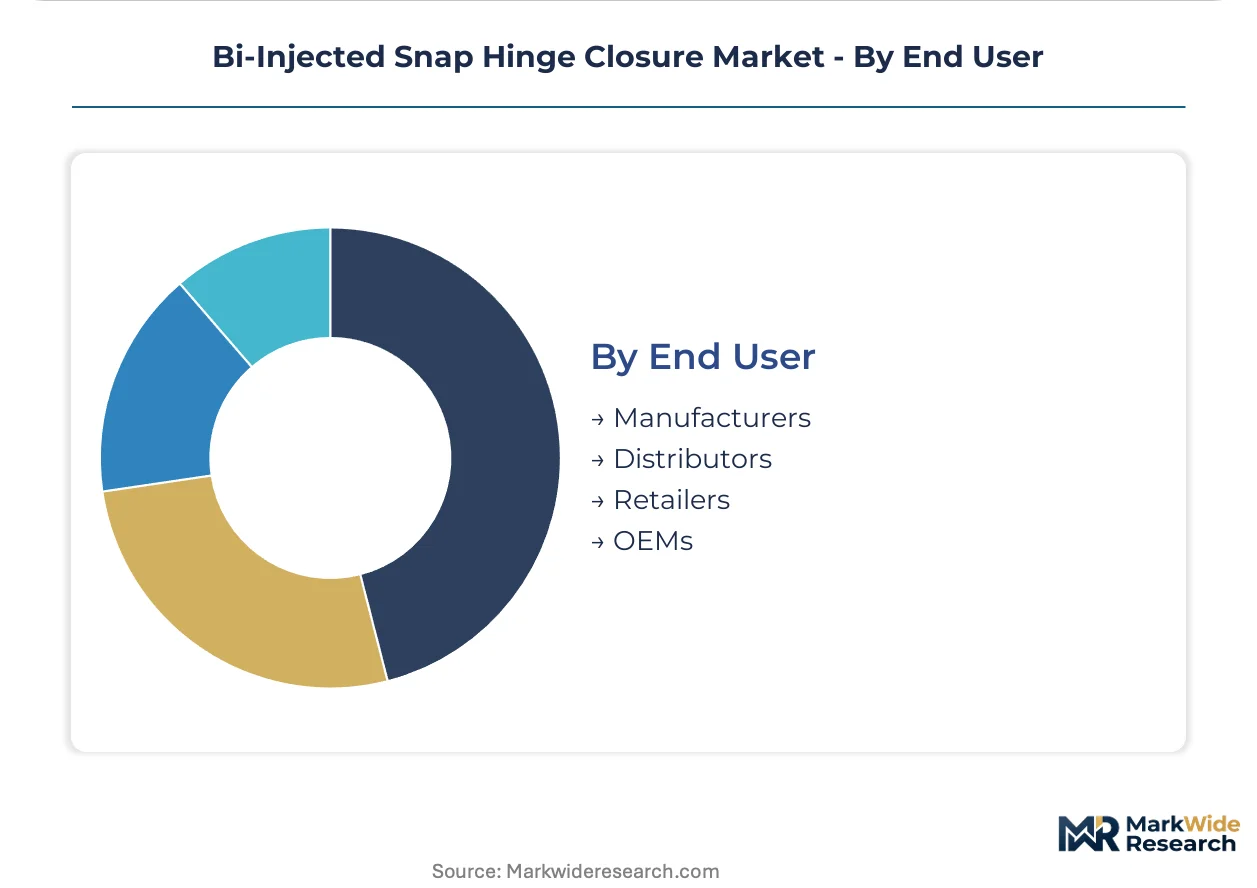
End User:
Supply concentration patterns favor direct procurement relationships in high-compliance segments over distributor intermediaries in commodity tiers.
- OEMs:Automotive and pharmaceutical original equipment manufacturers mandate audit-access to compounding and molding operations, concentrating sourcing in Germany's Bavaria precision molding cluster.
- Manufacturers:Contract converters serve mid-tier packaging applications with standardized designs and shorter lead times.
- Distributors:Inventory intermediaries retain relevance in furniture and consumer electronics where specification complexity remains low.
- Retailers:Private-label brand owners increasingly bypass distribution layers for direct mold procurement in personal care segments.
OEMs concentrate the highest-value procurement. Retailers are gaining share fastest through private-label direct sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and French pharmaceutical packaging lines are absorbing the bulk of compliance investment for child-resistant closures, while Bavaria's precision molding cluster and the Rhône-Alpes plastics corridor concentrate technical expertise for dual-material designs.
Germany
Pharmaceutical packagers in Bavaria are expanding orders for ECHA REACH-compliant child-resistant closures with 10,000-cycle fatigue validation. The EU Packaging and Packaging Waste Directive mandates recyclability thresholds that favor mono-material-compatible designs. Stuttgart and Munich anchor automotive interior panel applications where Tier-1 suppliers demand PPAP documentation.
France
Personal care converters in the Rhône-Alpes corridor are accelerating adoption of elastomer-modified polypropylene copolymers for cost-efficient living hinges. ANSM pharmaceutical safety standards tighten pediatric poisoning prevention specifications. Lyon-based compounders supply glass-fiber reinforced hybrids to French OEMs pursuing cabin light-weighting mandates.
United States
Beverage and personal care brand owners are bypassing distributor intermediaries for direct mold procurement in high-compliance segments. FDA 21 CFR Part 177 indirect food additive regulations constrain migration testing protocols for polyolefin closures. Midwest packaging converters face resin price volatility tied to crude oil derivative fluctuations.
Switzerland
Specialized bi-injection mold fabricators in the German-Swiss border region are experiencing capacity bottlenecks during demand surges. Swissmedic pharmaceutical regulations align with EMA standards for tamper-evident containment systems. Zurich-area equipment suppliers control narrow tooling supply chains critical to 180-degree flex cycle optimization.
China
Automotive Tier-1 suppliers in the Yangtze River Delta are qualifying composite bi-injected closures for interior trim panels under gram-level mass reduction targets. NMPA pharmaceutical packaging standards are converging toward international child-resistance benchmarks. Shanghai-based molders are investing in calcium-zinc stabilizer systems to preempt REACH-equivalent export barriers.
Bi-Injected Snap Hinge Closure Market Competitive Environment
Backward integration into injection molding equipment dominates the current landscape, with suppliers securing captive control over specialized tooling supply chains. The vendor base stratifies across three tiers: multinational packaging conglomerates with pharmaceutical dispensing expertise, mid-scale regional converters with precision molding capabilities, and specialized equipment-integrated fabricators. Two strategic archetypes define competitive positioning: compliance-driven specialists serving regulated pharmaceutical segments, and scale-driven volume leaders optimizing resin compounding economics. M&A activity and strategic partnerships represent the dominant competitive moves, particularly for accessing Bavarian and Rhône-Alpes cluster capabilities.
Among North American packaging conglomerates, AptarGroup Inc. and Berry Global Inc. exemplify divergent archetypes—pharmaceutical dispensing specialization versus captive resin compounding scale. Silgan Holdings Inc. occupies a position within the equipment-integrated tier, its corporate structure suggesting upstream control over tooling assets. These three entities anchor the competitive landscape without exhausting its structural variation, as European specialists like Bericap GmbH and United Caps Luxembourg S.A. represent regional compliance-driven alternatives concentrated in German and Benelux molding corridors.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| AptarGroup Inc. |
| Berry Global Inc. |
| Bericap GmbH |
| United Caps Luxembourg S.A. |
| Global Closure Systems |
| Amcor plc |
| ALPLA Group |
| Guala Closures Group |
| Others |
Value Chain & Pricing Dynamics
Backward integration into injection molding equipment anchors both supply security and margin control for bi-injected snap hinge closure suppliers serving REACH-regulated European markets. Bavarian precision molders and Rhône-Alpes compounders leverage captive tooling assets to command premium positioning in pharmaceutical compliance tiers while insulating against resin volatility.
Pricing Analysis
The volume-mass split separates commodity polyolefin beverage closures from engineered thermoplastic pharmaceutical grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with FDA 21 CFR Part 177 and ECHA REACH compliance tiers commanding substantial premiums. Pricing pressure stems from polypropylene feedstock volatility tied to crude oil derivatives, compressing margins for mid-tier packaging converters. Furniture and consumer electronics buyers exhibit highest price sensitivity, while pharmaceutical OEMs prioritize fatigue validation and audit-access over unit cost.
Supply Chain Analysis
Pharmaceutical-grade qualification gating restricts viable supply to Germany, France, and Switzerland, where EMA-aligned regulatory affairs capabilities concentrate. Raw material dependencies span polypropylene copolymers, calcium-zinc stabilizer systems, and specialized bi-injection mold steels. Single-source vulnerability runs through German and Swiss tooling fabricators, creating capacity bottlenecks during demand surges. Distribution runs through direct procurement relationships in high-compliance segments, with distributor intermediaries retained only in furniture and consumer electronics tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bi-injected snap hinge closure market sits in a material-transition phase as elastomer-modified polypropylene copolymers displace engineered thermoplastics in mid-tier fatigue applications. This substitution wave reshapes competitive positioning across cost-efficiency and compliance tiers.
For Market Incumbents: To counter resin price volatility and emerging regional compounders, secure captive supply of calcium-zinc stabilizer formulations and expand fatigue-testing capacity in Bavaria's precision molding cluster. Prioritize backward integration into mold fabrication assets to reduce dependency on Swiss equipment suppliers during demand surges.
For New Entrants and Emerging Players: Automotive Tier-1 suppliers in the Yangtze River Delta represent an underserved buyer archetype seeking gram-level mass reduction for interior trim panels. Target composite formulation qualification cycles where incumbents lack regional presence, and pursue joint development agreements with cabin light-weighting programs.
For Investors and Strategic Acquirers: Exit pathways concentrate in equipment-integrated fabricators with pharmaceutical certification assets and captive resin compounding capabilities. Long-term viability hinges on dual-material recycling infrastructure readiness as EU extended producer responsibility frameworks mature. Monitor bio-based content threshold announcements as the critical inflection signal for material platform obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mold Fabrication | Captive tooling supply secures capacity allocation during ECHA REACH compliance surges in Germany. |
| Calcium-Zinc Stabilizer System Qualification | Preempts phthalate ban enforcement under REACH Annex XVII for EU pharmaceutical closure supply. |
| Automotive Interior Panel Partnership | Opens composite formulation revenue streams tied to OEM gram-reduction mandates in France. |
| Direct Procurement Channel Development | Bypasses distributor intermediaries for audit-access relationships with Bavarian pharmaceutical packagers. |
| Dual-Material Recycling Infrastructure Investment | Aligns with EU Packaging and Packaging Waste Directive recyclability thresholds for living hinge separation. |
Study Parameters
Multi-period observation of resin price trajectories, regulatory submission timelines, and molding equipment order backlogs anchored the trend analysis, supplemented by interviews with plant managers at German precision molding facilities, regulatory affairs leads at French pharmaceutical packagers, procurement directors at automotive Tier-1 suppliers, and technical R&D directors at Rhône-Alpes compounders. Secondary validation drew from ECHA substance restriction announcements, FDA 21 CFR Part 177 guidance updates, SEC filings of packaging conglomerates, and customs data on polypropylene copolymer trade flows. Bottom-up segment sizing and top-down macroeconomic cross-checks ensured triangulation integrity.
Segment-weighting across product type, installation geometry, application vertical, and end-user procurement power shaped the analytical framework. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements across the analysis window. Industry-specific forecast inputs incorporated living hinge fatigue cycle validation rates and REACH substance authorization timelines.
Revisions become necessary when ECHA expands Annex XVII restrictions, FDA issues revised migration testing protocols, or automotive OEMs accelerate cabin light-weighting mandates beyond current qualification cycles. A model refresh is warranted upon material change in bio-based content thresholds under evolving EU extended producer responsibility frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
Cover Caps Market
Caps and Closures
Handheld Induction Cap Sealers Market
Caps and Closures
Heat Induction Cap Liner Market
Caps and Closures
Steel Ring Pull Caps Market
Caps and Closures
Bag Closure Clips Market
Caps and Closures
Poland Plastic Caps and Closures Market
Caps and Closures
Vented Caps Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Plunger Stopper Market
Caps and Closures
Non-Aerosol Overcaps Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
Laminated Tube Closure Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
Child Resistant Pipette Closures Market