
 India Pallets Market | 2026-2036
India Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
India Pallets Market Insights
The BIS certification requirement for load-bearing equipment is repositioning competitive dynamics across India's pallet manufacturing base. Aristoplast Products Pvt. Ltd. leverages backward integration into virgin polymer compounding to secure material cost advantages. Nilkamal Ltd. anchors its position through dominant channel control across institutional buyers in food processing and pharmaceuticals. Saraswati Engineering Limited specializes in metal pallet fabrication for heavy-load automotive tier-1 applications, competing on durability specifications rather than price.
A pallet is a portable platform with a top deck and bottom deck assembly, typically constructed with stringer or block configurations, designed to support goods in a stable fashion during lifting by forklifts, pallet jacks, or conveyors. Wood remains the dominant material type across India's pallet stock, though plastic variants are gaining share in pharmaceutical cold-chain applications where moisture resistance and hygiene standards matter most. Block pallets command premium positioning in export-oriented warehousing due to four-way entry compatibility with automated handling systems, while stringer pallets occupy volume-driven segments in domestic FMCG distribution where cost minimization drives procurement decisions.
BIS standards, CDSCO pharmaceutical storage guidelines, and FSSAI food safety regulations collectively shape product specifications and market access conditions for pallet suppliers serving regulated industries. The PLI scheme for logistics infrastructure creates additional demand pull for domestically manufactured load-handling equipment. Stakeholders must monitor how evolving FSSAI traceability requirements and state-level warehousing incentives reshape material preferences and regional supply patterns.
Market Dynamics
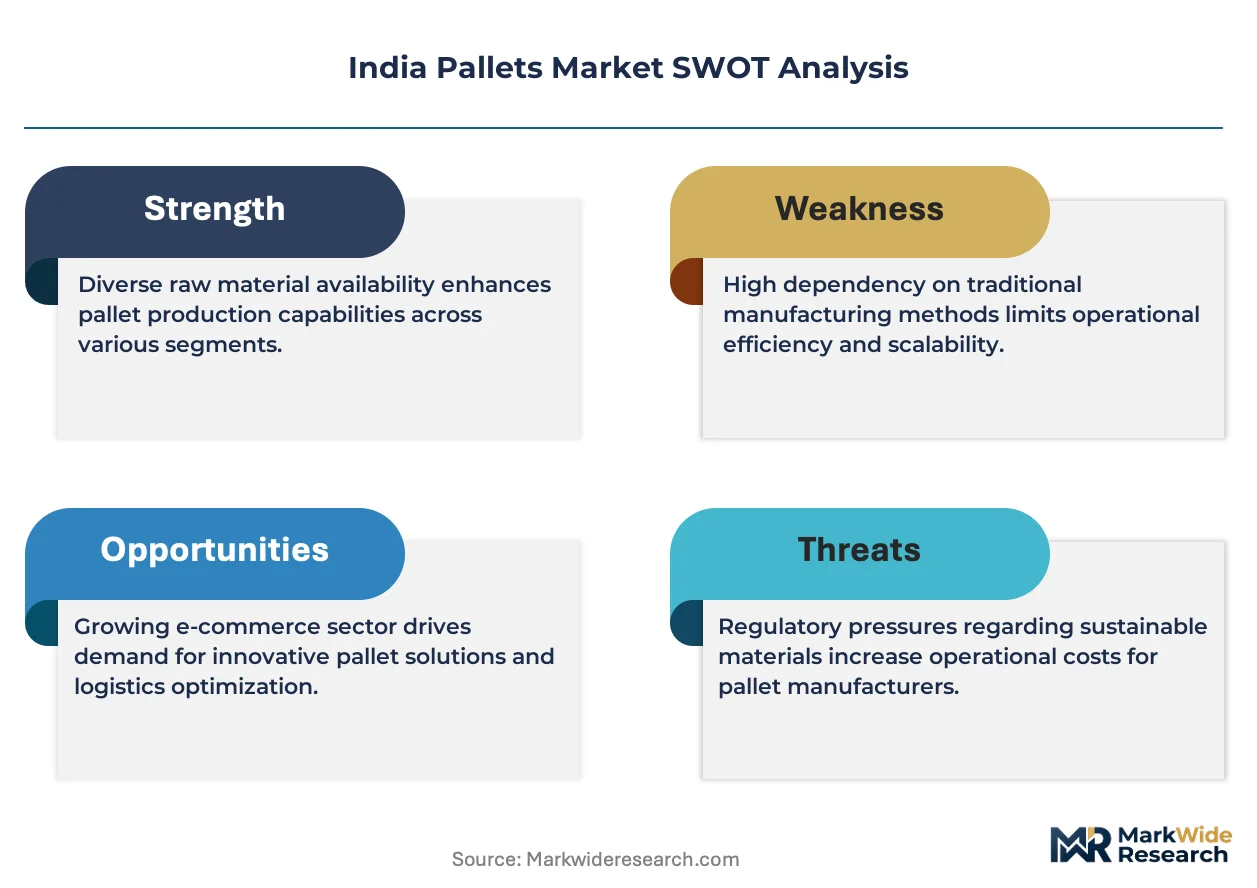
The BIS certification mandate for load-bearing equipment is compressing supplier margins while forcing quality upgrades across India's fragmented pallet manufacturing base. Tier-1 automotive and pharmaceutical buyers now demand documented compliance, filtering out informal producers.
Growth Catalysts
- CDSCO cold-chain mandates:Pharmaceutical storage guidelines require moisture-resistant pallets, pulling plastic variants into temperature-controlled logistics across Maharashtra and Gujarat.
- PLI scheme incentives:Domestic manufacturing subsidies for logistics infrastructure reduce landed costs for locally fabricated metal and polymer pallets serving export corridors.
- Automotive cluster concentration:Heavy-load tier-1 suppliers in Pune and Chennai generate sustained demand for durable block pallets compatible with automated warehouse systems.
Market Restraints
- Timber input volatility:Wood pallet producers face irregular supply from restricted forest zones and fluctuating hardwood prices in Karnataka and Kerala.
- Import dependency for virgin polymer:Plastic pallet manufacturers rely on concentrated petrochemical feedstock suppliers, exposing margins to currency and crude price swings.
- Four-way entry technical barriers:Block pallet production requires precision molding and reinforced corner blocks that exceed capabilities of small-scale fabricators.
Strategic Opportunities
- FSSAI traceability rollout:Upcoming food safety regulations mandating batch-level tracking create demand for RFID-embedded pallets in dairy and processed food distribution.
- North-eastern warehousing expansion:State-level logistics incentives in Assam and Tripura open underpenetrated territory for pallet pooling services.
- Plastic-wood hybrid convergence:Composite materials combining recycled polymer with agricultural waste fibers offer cost-positioning between virgin plastic and treated wood.
Industry Challenges
- BIS certification timeline compression:Testing and documentation requirements for load-bearing equipment strain quality assurance capacity at mid-sized manufacturers.
- Retrofit integration with legacy racking:New pallet specifications often conflict with existing warehouse infrastructure dimensions, forcing costly facility modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Pallets Market |
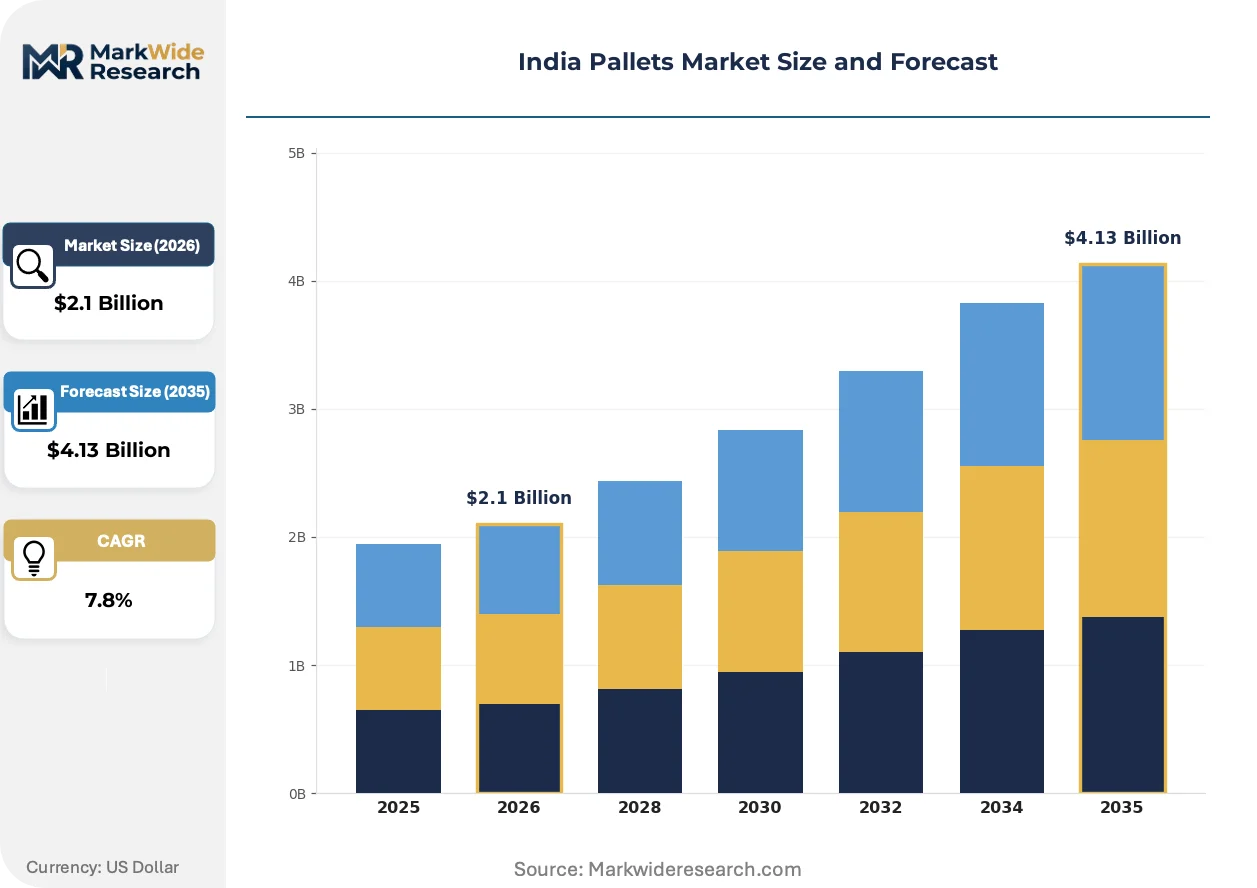
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Plastic, Metal, Presswood, Corrugated Fiberboard Pallet Type: Stringer, Block, Double-Face, Four-Way Entry, Nestable End Use Industry: Pharmaceuticals, Automotive Tier-1 Suppliers, Food Processing, Warehousing & Storage, Electronics Assembly Distribution Channel: Direct Sales, Distributors, Online Platforms, Third-Party Logistics, Rental Services |
| Companies Covered | Aristoplast Products Pvt. Ltd., Schoeller Allibert, Nilkamal Ltd., Saraswati Engineering Limited, Mekins Group, The Supreme Industries Ltd., B. D. Industries India Pvt. Ltd., DNA Packaging Systems, LEAP India Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Pallets Market Trends and Innovations
Material science advances and regulatory digitization are reshaping how pallets are specified, tracked, and recovered in Indian supply chains. Automation compatibility and circularity metrics now influence procurement alongside unit cost.
RFID and IoT sensor modules are converging with pallet substrates to create trackable load platforms. Pharmaceutical distributors in Gujarat and Maharashtra are deploying these units for real-time temperature and location monitoring. The technology is converging with warehouse management systems to enable automated inventory reconciliation and reduce shrinkage in high-value cold chains.
FSSAI's draft traceability regulations are mandating serialized packaging and handling equipment documentation. Food processors must maintain chain-of-custody records from farm to retail shelf. Dairy cooperatives in Gujarat and snack manufacturers in Maharashtra are pre-emptively upgrading to certified hygienic pallets to avoid compliance disruption.
Asset-light pallet pooling models are displacing outright purchase among FMCG distributors. Third-party pooling operators now maintain circulating fleets of standardized plastic pallets, charging per-trip fees. This shift concentrates most visibly in Western India's automotive and consumer goods corridors, where warehouse density supports viable collection economics.
India Pallets Market Segmentation
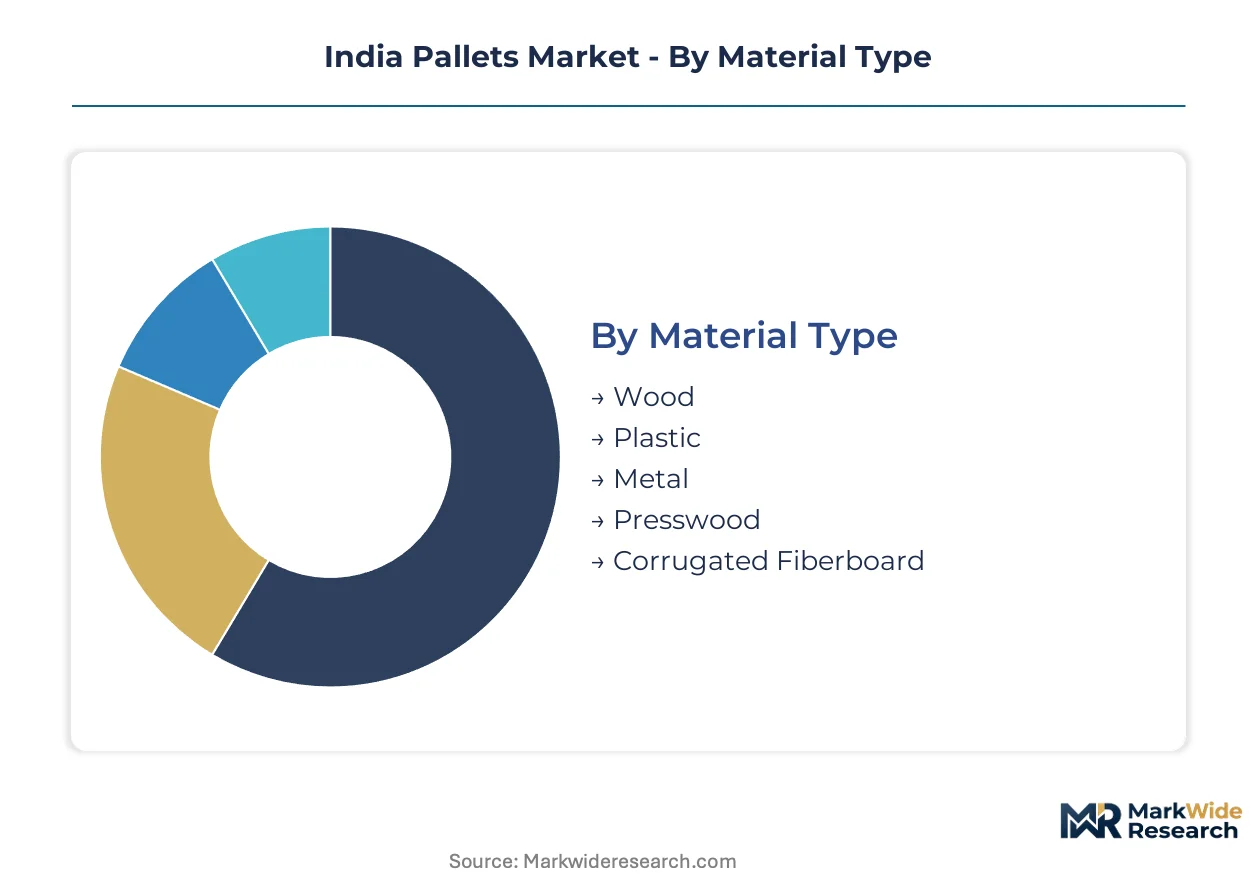
Pallet procurement in India splits across material grades, entry configurations, and channel economics that dictate replacement cycles and total cost of ownership. Understanding these segment boundaries reveals where BIS compliance investments concentrate and where informal supply still competes on upfront price.
Material Type:
Upgrade cycles vary dramatically by substrate durability and exposure conditions, with moisture-sensitive applications forcing faster replacement than dry-storage environments.
- Wood:Treated hardwood and softwood stringer assemblies dominate India's installed base due to lowest unit cost and repairability. Karnataka and Kerala timber supply irregularity is compressing margins for untreated pallet producers serving domestic FMCG distribution.
- Plastic:Virgin and recycled polymer pallets command premium positioning in pharmaceutical cold-chain logistics across Maharashtra and Gujarat, where CDSCO moisture-resistance mandates and washability requirements disqualify wood alternatives.
- Metal:Steel and aluminum fabrications serve heavy-load automotive tier-1 applications in Pune and Chennai, competing on durability specifications and racking compatibility rather than purchase price.
- Presswood:Compressed wood fiber pallets offer ISPM-15 exempt export compliance without heat treatment, finding niche adoption in electronics assembly outbound shipments.
- Corrugated Fiberboard:Single-use paper-based pallets support lightweight air freight and retail display applications where return logistics are uneconomical.
Volume placements concentrate in wood; the faster expansion belongs to plastic.
Pallet Type:
Entry configuration determines automation compatibility and warehouse throughput economics, with four-way designs commanding substantial premiums in export-oriented facilities.
- Stringer:Two-way entry with parallel longitudinal supports remains the volume standard for domestic distribution, offering lowest fabrication cost and familiar handling characteristics for conventional forklift fleets.
- Block:Four-way entry via perpendicular block supports enables automated handling system compatibility, with demand concentrating in Western India's automotive and warehousing corridors where AS/RS density justifies the specification.
- Double-Face:Deck boards on both top and bottom surfaces distribute load symmetrically, supporting rackable applications in food processing and pharmaceuticals where pallet inversion occurs.
- Four-Way Entry:Reinforced corner block designs with full perimeter base enable omnidirectional forklift access, required for high-velocity cross-docking operations in third-party logistics hubs.
- Nestable:Hollow leg designs stack empty pallets at one-quarter of assembled height, reducing return freight costs for pooling operators and rental services in FMCG closed-loop distribution.
Stringer configurations dominate unit placements; block pallets are gaining share fastest in automated warehousing investments.
End Use Industry:
Regulatory exposure and load specifications create distinct procurement patterns, with certified hygienic grades required for pharmaceutical and food contact applications.
- Pharmaceuticals:Temperature-controlled storage mandates from CDSCO and FSSAI drive specification of moisture-resistant plastic pallets with documented traceability in Maharashtra and Gujarat cold-chain infrastructure.
- Automotive Tier-1 Suppliers:Heavy component loads and just-in-sequence delivery requirements in Pune and Chennai generate demand for durable metal and reinforced block pallets compatible with automated storage systems.
- Food Processing:Dairy cooperatives in Gujarat and snack manufacturers in Maharashtra are pre-emptively upgrading to FSSAI-compliant hygienic pallets ahead of finalized traceability regulations.
- Warehousing & Storage:Third-party logistics operators in Western India's automotive corridors are shifting from purchase to rental models, concentrating demand for standardized nestable plastic pallets in pooling fleets.
- Electronics Assembly:ESD-sensitive component handling and export compliance requirements favor presswood and treated wood pallets with ISPM-15 certification for outbound shipments.
Warehousing and storage absorbs the highest pallet volumes; pharmaceuticals is climbing the fastest on regulatory compliance investment.
Distribution Channel:
Channel selection reflects customer scale and asset-light preferences, with large institutional buyers bypassing intermediaries while mid-tier operators favor rental economics.
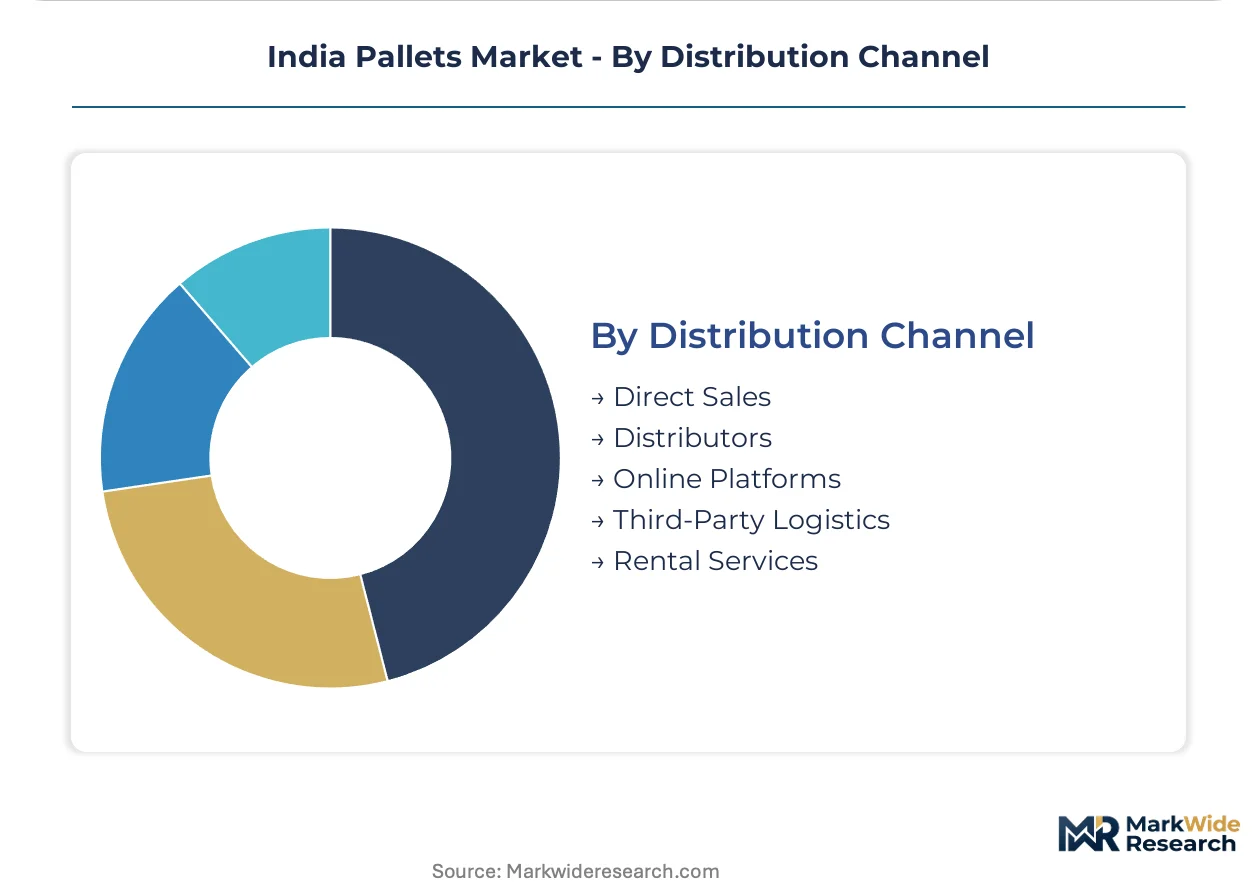
- Direct Sales:Large automotive and pharmaceutical manufacturers negotiate volume contracts with domestic fabricators, leveraging PLI scheme incentives for locally manufactured load-handling equipment.
- Distributors:Regional stocking intermediaries serve fragmented food processing and electronics assembly demand, carrying inventory of standardized wood and plastic specifications for immediate availability.
- Online Platforms:B2B marketplaces are emerging for standardized pallet specifications, though complex load requirements and certification documentation still favor direct negotiation.
- Third-Party Logistics:3PL operators bundle pallet supply with warehousing services, specifying compatible equipment for integrated material handling systems.
- Rental Services:Asset-light pooling models are displacing outright purchase among FMCG distributors in Western India, charging per-trip fees for circulating plastic pallet fleets.
Direct sales and distributors currently handle the largest volume flows; rental services are expanding most quickly as pooling economics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level warehousing incentives and pharmaceutical cold-chain investments are concentrating pallet demand across Western and Southern India. Maharashtra's automotive corridors and Gujarat's dairy cooperatives anchor premium-grade consumption, while Karnataka's timber supply volatility reshapes material sourcing patterns for domestic distributors.
Maharashtra
Pharmaceutical cold-chain logistics and automotive tier-1 manufacturing dominate pallet procurement in this state. CDSCO temperature-controlled storage mandates pull moisture-resistant plastic variants into Mumbai and Pune distribution hubs. Pune's dense concentration of heavy-load automotive suppliers sustains demand for durable block pallets compatible with automated storage systems.
Gujarat
Dairy cooperatives and processed food manufacturers are pre-emptively upgrading pallet specifications ahead of finalized FSSAI traceability regulations. The state's warehousing incentives under the PLI scheme for logistics infrastructure reduce landed costs for domestically fabricated equipment. Ahmedabad and Vadodara host expanding third-party logistics operations that specify standardized nestable pallets for pooling fleets.
Karnataka
Timber supply irregularity from restricted forest zones is compressing margins for wood pallet producers serving South Indian markets. Electronics assembly exporters in Bengaluru favor presswood and treated wood pallets with ISPM-15 certification for outbound shipments. The state's capital equipment manufacturing base generates secondary demand for metal pallet fabrications in heavy-load applications.
Tamil Nadu
Automotive component manufacturing around Chennai sustains consumption of reinforced block pallets for just-in-sequence delivery requirements. The state's port infrastructure supports export-oriented warehousing investments that specify four-way entry compatibility. Chennai's third-party logistics operators are shifting from purchase to rental models for plastic pallet fleets.
Telangana
Pharmaceutical formulation units in Hyderabad are adopting RFID-embedded pallets for real-time temperature monitoring in cold-chain distribution. State-level logistics park development creates demand for standardized load-handling equipment compatible with automated material handling systems. The region's food processing clusters are upgrading to FSSAI-compliant hygienic grades ahead of regulatory finalization.
India Pallets Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across India's fragmented pallet manufacturing base. The vendor landscape segments into three tiers: large integrated polymer processors with captive raw material supply, mid-scale regional fabricators serving specific industrial corridors, and informal wood workshops competing on upfront price. Consolidation pressure from BIS certification requirements is filtering out sub-scale producers while rewarding documented quality systems. Dominant competitive moves include backward integration into virgin polymer compounding and expansion of rental pooling fleets in Western India.
Among diversified material processors, The Supreme Industries Ltd. and Nilkamal Ltd. anchor the polymer pallet segment through integrated manufacturing footprints. Schoeller Allibert represents the multinational pooling operator archetype with standardized fleet offerings. Aristoplast Products Pvt. Ltd., Saraswati Engineering Limited, and LEAP India Pvt. Ltd. occupy distinct specialization niches across plastic fabrication, metal heavy-load applications, and rental services respectively. Mekins Group, B. D. Industries India Pvt. Ltd., and DNA Packaging Systems exemplify regional fabricators competing on customization and proximity to demand clusters.
| Leading Market Players |
|---|
| Aristoplast Products Pvt. Ltd. |
| Schoeller Allibert |
| Nilkamal Ltd. |
| Saraswati Engineering Limited |
| Mekins Group |
| The Supreme Industries Ltd. |
| B. D. Industries India Pvt. Ltd. |
| DNA Packaging Systems |
| LEAP India Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Tier-1 automotive and pharmaceutical manufacturers in Maharashtra and Gujarat anchor procurement volumes, concentrating pricing power with BIS-certified fabricators capable of documented compliance. This buyer concentration rewards backward integration into virgin polymer compounding while squeezing margin for wood-based suppliers exposed to timber volatility.
Pricing Analysis
Short lead-time premiums of 15-25% apply to certified block pallets serving Pune's just-in-sequence automotive corridors, while spot inventory of untreated wood stringers trades at discounts in Karnataka's fragmented FMCG distribution. Pricing stratifies across premium certified plastic, standard treated wood, and economy untreated grades. Cost compression in the wood segment intensifies because of irregular hardwood supply from Kerala's restricted forest zones. Domestic FMCG distributors exhibit highest price sensitivity, whereas pharmaceutical cold-chain operators prioritize moisture resistance over unit cost.
Supply Chain Analysis
Freight costs from Gujarat's petrochemical belt to Maharashtra's pharmaceutical hubs add 8-12% to landed plastic pallet costs, incentivizing regional compounding facilities. Virgin polymer supply draws from concentrated feedstock suppliers in Gujarat and Maharashtra, with recycled polymer sourcing from Tamil Nadu's industrial waste recovery networks. Single-source vulnerability in polymer resin exposes margins to currency and crude price swings. Distribution runs through direct sales contracts for large automotive OEMs, regional distributors for fragmented food processors, and emerging rental pooling operators in Western India's warehousing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over virgin polymer compounding separates margin leaders from price-takers. Players are pursuing captive resin supply to defend against petrochemical feedstock volatility.
For Market Incumbents: Cement market position by acquiring BIS certification capacity ahead of mandate enforcement, filtering out informal wood workshops. Expand backward integration into polymer compounding to secure material cost advantages against crude price swings. Prioritize channel control across institutional pharmaceutical buyers where CDSCO compliance creates switching costs. For New Entrants and Emerging Players: FSSAI traceability regulations in Gujarat and Maharashtra open a window for RFID-embedded pallet specialists serving dairy cooperatives and snack manufacturers. Target Assam and Tripura's underpenetrated warehousing corridors where state-level logistics incentives reduce competitive density. Lead with rental pooling economics rather than outright purchase to bypass capital barriers facing FMCG distributors. For Investors and Strategic Acquirers: The window for entry favors mid-scale regional fabricators with documented quality systems and proximity to Western India's automotive corridors. Acquisition targets should demonstrate BIS certification readiness and captive polymer supply or metal fabrication capabilities. Watch for FSSAI finalization of batch-level tracking mandates as the inflection signal for hygienic pallet demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin supply from Gujarat's petrochemical belt insulates margins against crude volatility. |
| BIS Certification Capacity Expansion | Documented compliance systems filter informal competitors from pharmaceutical and automotive procurement. |
| Rental Pooling Fleet Buildout | Asset-light per-trip models displace outright purchase among Maharashtra's FMCG distributors. |
| RFID-Embedded Pallet Development | Serialized tracking modules align with FSSAI draft traceability mandates for dairy and processed food. |
| North-Eastern Logistics Corridor Entry | Assam and Tripura warehousing incentives create first-mover advantage in underpenetrated territory. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across pallet manufacturing plant managers, automotive Tier-1 procurement leads, pharmaceutical warehouse operations heads, and third-party logistics channel partners. BIS certification databases, CDSCO pharmaceutical storage guidelines, FSSAI food safety regulations, and PLI scheme logistics infrastructure disclosures provided regulatory boundary conditions. Bottom-up demand modeling triangulated against top-down sectoral spend analysis.
Data-stream reconciliation combined shipment volume tracking from customs records with capacity utilization surveys across Karnataka, Maharashtra, and Gujarat fabrication facilities. Segmentation dimensions spanned material substrate, entry configuration, end-use industry vertical, and distribution channel economics. CAGRs were derived from installed base replacement cycles, regulatory compliance investment trajectories, and automation adoption curves in Western India's warehousing corridors. Pharmaceutical cold-chain expansion and automotive cluster concentration served as primary demand elasticity inputs.
The model assumes a particular technology adoption path; alternative pathways for RFID-IoT sensor convergence would alter the outlook for trackable pallet penetration. Forecasts reflect assumptions regarding BIS enforcement timelines, FSSAI traceability finalization, and polymer feedstock price stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Italy Pallets Market
Pallets Packaging
UK Pallets Market
Pallets Packaging
Germany Pallets Market
Pallets Packaging
North America Lumber Pallet Market
Pallets Packaging
China Pallets Market
Pallets Packaging
Pallet Banding Machine Market
Pallets Packaging
Mexico Pallets Market
Pallets Packaging
Stretch Hood Pallet Wrapping Market
Pallets Packaging
Disposable Plastic Pallet Market
Pallets Packaging
Wire Cage Pallet Collar Market
Pallets Packaging
PUR Shippers Market
Pallets Packaging
Pallet Jacks Market
Pallets Packaging
Thermal Pallet Covers Market
Pallets Packaging
Pallet Shippers Market
Pallets Packaging
Europe Pallet Market
Pallets Packaging
Conventional Palletizers Market