
 UK Pallets Market | 2026-2036
UK Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
UK Pallets Market Insights
Asset-light leasing and pooled pallet rental models is tilting competitive dynamics toward capital-efficient operators. Brambles Limited leverages its extensive CHEP pooling network to sustain national coverage without heavy fixed-asset burdens. Schoeller Allibert Group anchors its position through reusable plastic container and pallet integration, while Cabka differentiates via recycled plastic pallet manufacturing that competes on circularity credentials.
A pallet is a flat transport structure built to ISO standard dimensions, typically constructed from hardwood, softwood, polyethylene, or steel, designed to support goods during lifting by forklifts, pallet jacks, or front loaders. Wooden pallets dominate UK throughput due to lower unit costs and established repair infrastructure, though plastic pallets are gaining share in pharmaceutical and food-grade applications where hygiene standards and washability command premium positioning. The Food & Beverage end user industry occupies the largest demand pool, while Export Handling applications face structural pressure from post-Brexit customs complexity that extends dwell times and accelerates wear cycles.
Environment Agency regulations and the UK's transposed Waste Framework Directive shape material compliance, with timber pallets requiring heat treatment certification under ISPM 15 for cross-border movement. BSI standards for load ratings and dimensional tolerance filter market access, particularly for steel and plastic alternatives seeking industrial certification. Stakeholders must monitor how extended producer responsibility frameworks for packaging reshape total cost of ownership calculations across wooden versus plastic pallet lifecycles.
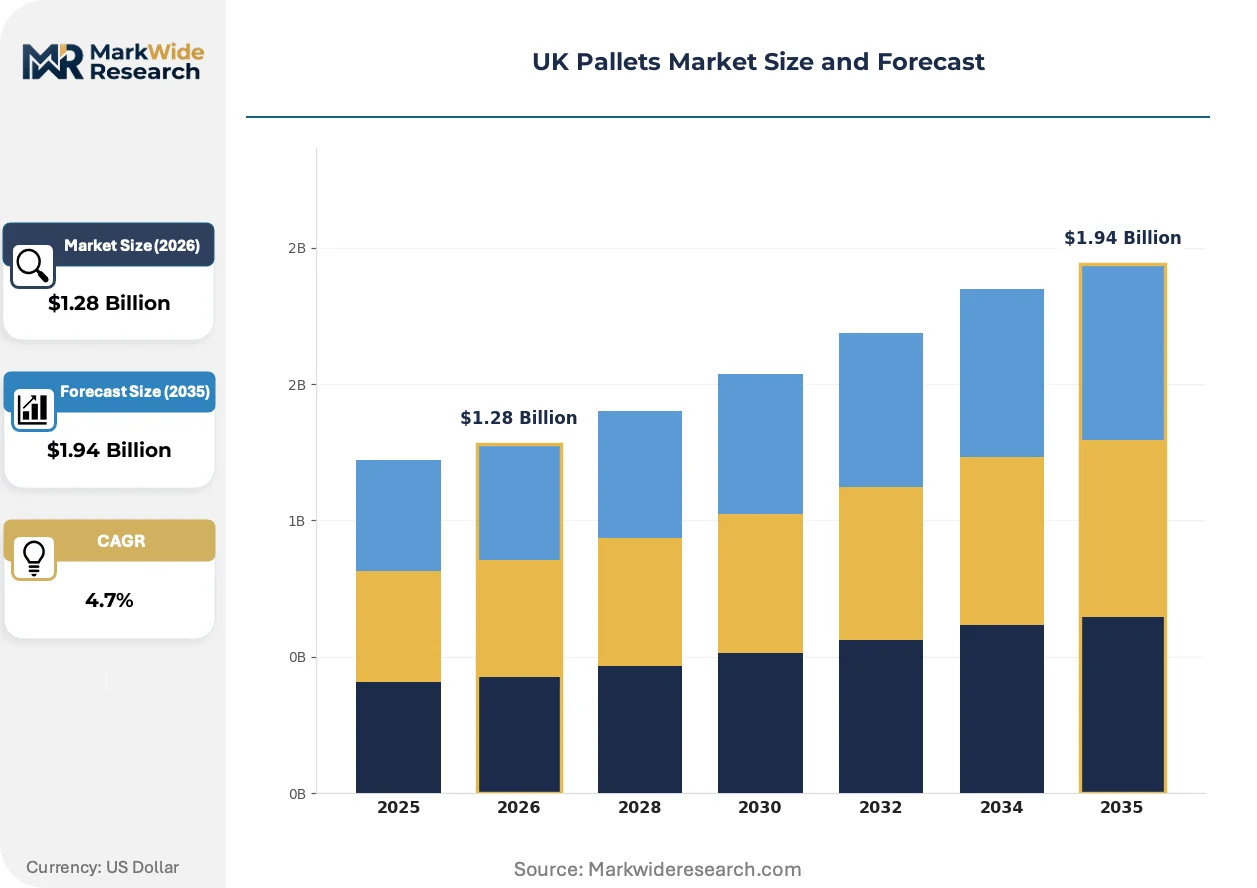
Market Dynamics
Asset-light pooling models are compressing fixed-asset requirements across British distribution networks, tilting competitive advantage toward operators with dense reverse logistics infrastructure rather than manufacturing scale.
Growth Catalysts
- Food & Beverage logistics expansion:Major supermarket chains are consolidating supplier networks around standardized pallet pools, creating concentrated demand pull across England's Midlands corridor.
- ISPM 15 heat treatment mandates:Cross-border timber movement rules under the UK's transposed phytosanitary framework are accelerating replacement cycles for untreated wooden stock.
- Plastic pallet washability:Hygiene-critical pharmaceutical and cold-chain operators are specifying polyethylene units for contamination-sensitive loads, opening premium positioning above commodity wood.
Market Restraints
- Softwood input cost volatility:Baltic timber supply disruptions and freight rate fluctuations are compressing margins for domestic wooden pallet manufacturers without long-term fiber contracts.
- Midlands distribution hub concentration:Overreliance on Birmingham-East Midlands logistics clusters creates regional vulnerability to localized labor shortages and warehouse capacity constraints.
- Plastic recycling infrastructure gaps:End-of-life recovery networks for damaged polyethylene pallets remain underdeveloped, limiting circular economy claims against regulatory scrutiny.
Strategic Opportunities
- Northern England logistics penetration:Manchester and Yorkshire distribution zones show underdeveloped pooling coverage relative to southern density, offering whitespace for network expansion.
- Extended producer responsibility frameworks:Emerging UK packaging waste regulations will shift total cost of ownership calculations toward reusable asset models with verified lifecycle tracking.
- RFID-pooling convergence:Real-time location tracking integration with rental management systems is collapsing dwell-time uncertainty and enabling dynamic pricing structures.
Industry Challenges
- ISPM 15 certification backlog:Heat treatment facility capacity constraints are extending compliance timelines for exporters facing customs detention risk at Channel ports.
- Legacy wooden pallet repair skill scarcity:Experienced technician retirements outpace apprenticeship pipelines, degrading refurbishment throughput quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Pallets Market |
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $1.94 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden Pallets, Plastic Pallets, Metal Pallets, Paper Pallets Material: Hardwood, Softwood, Polyethylene, Steel, Cardboard Application: Warehouse Storage, Distribution, Export Handling, Manufacturing Support, Retail Display End User Industry: Food & Beverage, Pharmaceuticals, Electronics, Construction, Chemicals |
| Companies Covered | Brambles Limited, Rehrig Pacific Company, Schoeller Allibert Group, Cabka, Monoflo International, ORBIS Corp., Allstate Corp, Polymer Solutions International, Perfect Pallets, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Pallets Market Trends and Innovations
Digital asset tracking and circular material flows are converging to reshape competitive positioning, compressing the information asymmetry that historically protected regional repair specialists.
RFID-embedded polyethylene pallets are collapsing the distinction between physical asset and data node, enabling real-time utilization monitoring across multi-user pools. Pharmaceutical distributors and temperature-controlled logistics operators are adopting these units fastest, lured by contamination audit trails and automated inventory reconciliation. The structural consequence is collapsing repair-network economics, as predictive damage detection shifts maintenance from reactive field fixes to centralized remanufacturing.
The UK's Waste Framework Directive implementation is tightening material provenance documentation for timber pallets entering circular reuse streams. Industrial operators must now maintain chain-of-custody records from heat treatment through end-of-life recovery, raising compliance overhead for small repair shops. Food-grade plastic pallet categories face the steepest certification burden, with auditors scrutinizing wash-cycle validation and polymer batch traceability.
Major retailers are consolidating supplier pallet specifications around pooled rental models rather than purchase-to-own arrangements. This procurement compression is displacing spot-market wooden pallet trading in favor of long-term service contracts with guaranteed availability clauses. The shift is most visible among grocery and fast-moving consumer goods chains operating national distribution centers, where asset visibility trumps unit cost minimization.
UK Pallets Market Segmentation
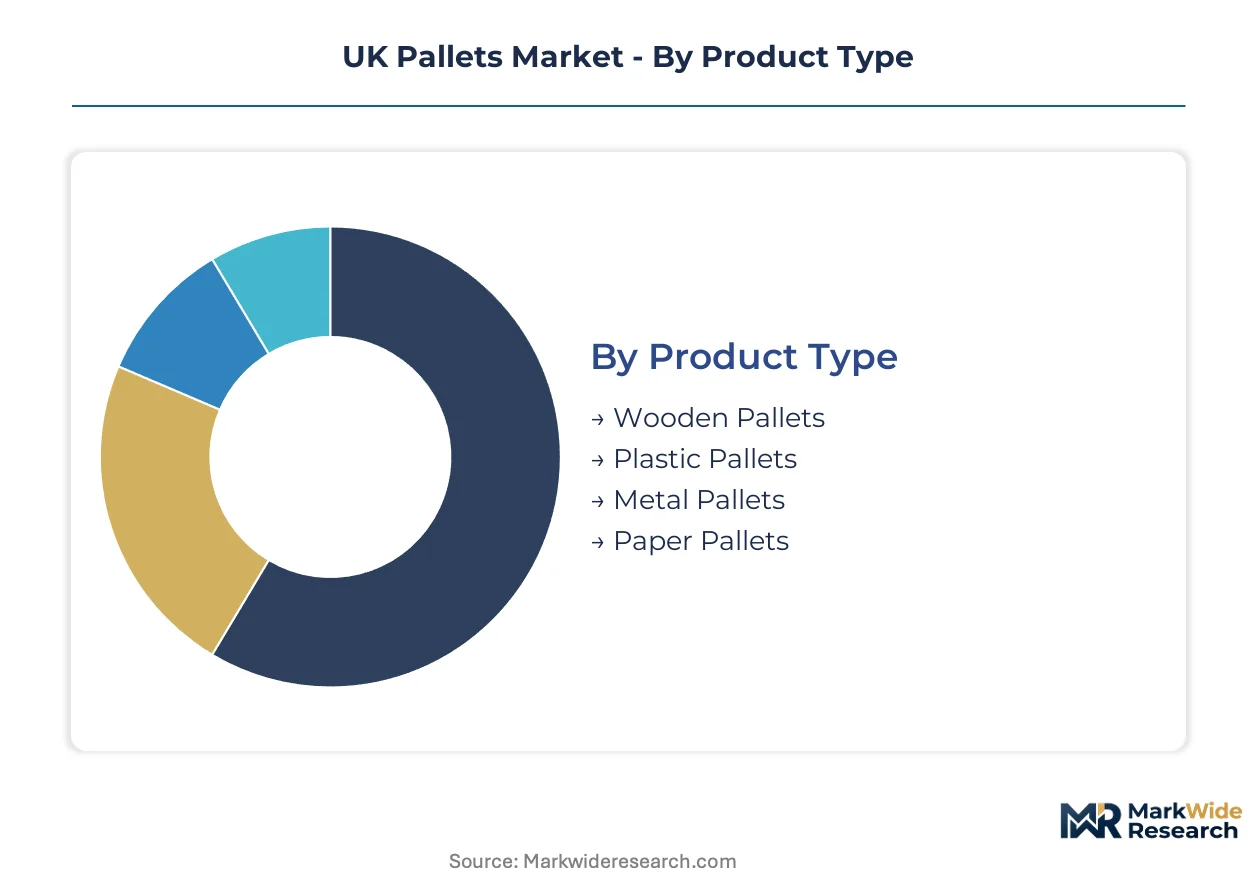
Asset turnover velocity varies dramatically across pallet categories in the UK logistics sector. Cycle times determine pooling economics, repair network density, and rental pricing structures for operators competing on capital efficiency.
Product Type:
Wooden pallets rotate through supply chains fastest due to lower unit costs and established refurbishment infrastructure, while plastic and metal alternatives command extended service lives that alter total cost calculations.
- Wooden Pallets:Constructed from nailed softwood or hardwood slats with block or stringer configurations. Demand concentrates in England's Midlands corridor where supermarket distribution hubs run high-throughput pooling programs with 4-6 trip average lifecycles before repair.
- Plastic Pallets:Molded polyethylene units withstand wash cycles and contamination audits. Pharmaceutical distributors and cold-chain operators across Birmingham and East Midlands specify these for temperature-sensitive loads where hygiene documentation trumps unit cost.
- Metal Pallets:Steel fabrication delivers extreme load ratings for heavy industrial applications. Chemicals and automotive manufacturers deploy these for captive internal loops with decade-plus service horizons.
- Paper Pallets:Honeycomb cardboard construction suits lightweight export shipments. Exporters facing ISPM 15 compliance costs for wooden alternatives trial these for single-use cross-Channel movements.
Wooden pallets anchor the volume base while plastic pallets gain share at the steepest rate.
Material:
Input cost tiers separate commodity softwood from specification-grade alternatives, with polymer and steel commanding premium positioning against volatile timber markets.
- Hardwood:Dense oak and beech slats deliver superior impact resistance for heavy manufacturing support. Construction and chemicals sectors specify hardwood block pallets for loads exceeding two tonnes.
- Softwood:Pine and spruce construction dominates UK throughput due to Baltic supply proximity. Repair shops across the Midlands corridor maintain softwood slat inventories for rapid turnaround on damaged units.
- Polyethylene:Virgin and recycled resin grades compete on circularity credentials. Food-grade washability specifications from major retailers drive virgin resin adoption despite cost premiums.
- Steel:Welded tubular construction withstands extreme warehouse handling. Narrow applications in heavy engineering and coil steel transport justify capital intensity.
- Cardboard:Engineered paperboard suits lightweight retail display and air freight. E-commerce fulfillment operators trial these for last-mile consolidation where return logistics are uneconomical.
Softwood commands the highest shipment volumes while polyethylene expands most quickly into food-grade specifications.
Application:
Geographic concentration of demand varies sharply by use case, with export handling facing distinct regulatory burdens that reshape asset economics.
- Warehouse Storage:Racking-compatible designs with four-way entry dominate high-bay facilities. Midlands distribution hubs specify uniform pallet pools to maximize cubic utilization.
- Distribution:Multi-trip pooling models concentrate demand among grocery and fast-moving consumer goods networks. Real-time tracking integration is collapsing dwell-time uncertainty across shared user pools.
- Export Handling:ISPM 15 heat treatment mandates extend compliance timelines for wooden units. Channel port detention risks accelerate replacement cycles for untreated stock.
- Manufacturing Support:Captive internal loops with dedicated fleet management. Automotive and electronics producers maintain closed-loop systems with barcode-tracked asset registers.
- Retail Display:Point-of-sale ready units with printed branding surfaces. Supermarket chains specify quarter-pallet and half-pallet formats for promotional end-cap positioning.
Distribution applications generate the densest pooling activity while export handling faces the steepest regulatory cost escalation.
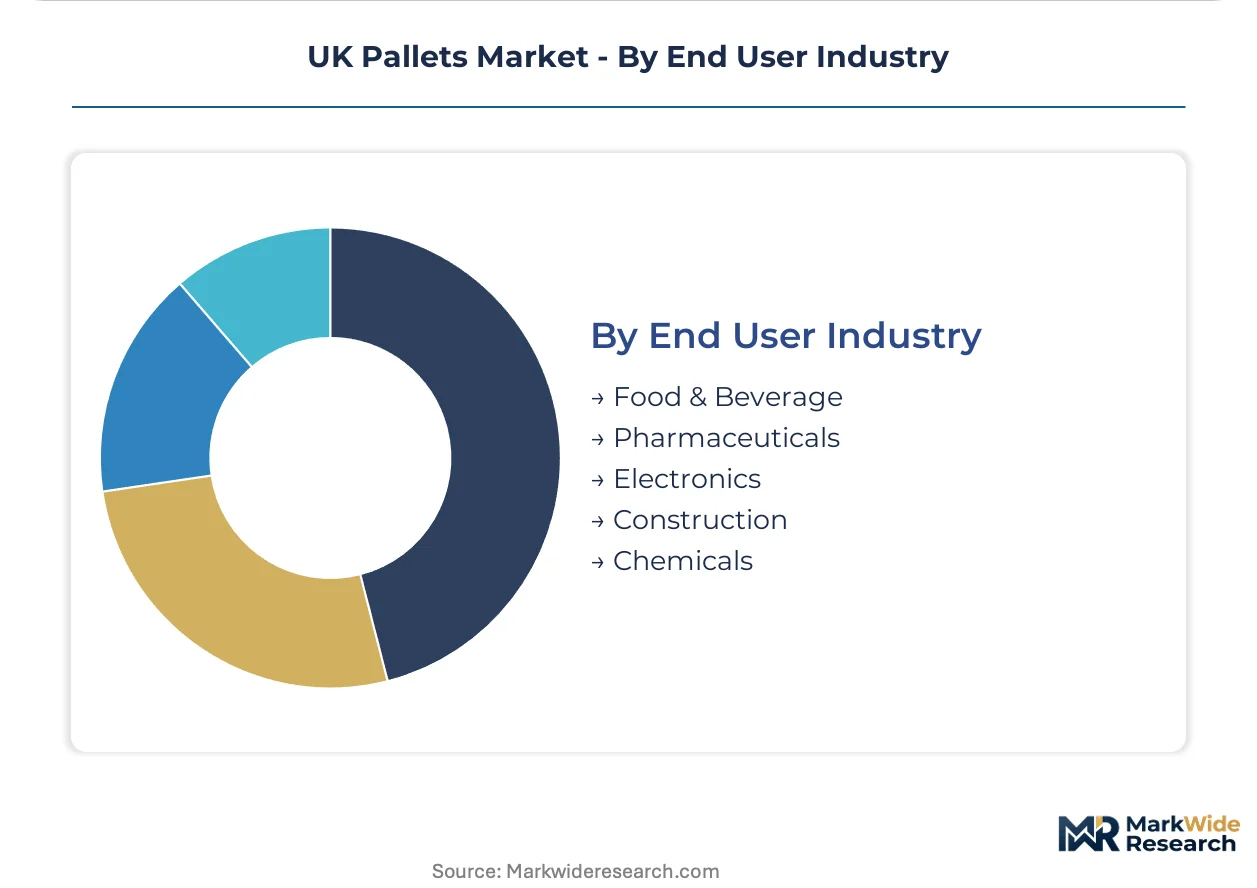
End User Industry:
Hygiene standards and traceability requirements create divergent specification tiers across customer verticals.
- Food & Beverage:The largest demand pool with consolidated supplier networks around standardized CHEP and LPR pooling programs. Major supermarket chains mandate wash-cycle documentation for plastic units in direct product contact.
- Pharmaceuticals:Temperature-controlled logistics operators specify RFID-embedded polyethylene pallets with contamination audit trails. MHRA guidance on Good Distribution Practice elevates asset traceability requirements.
- Electronics:Electrostatic discharge protection and dimensional precision for automated handling. Semiconductor distributors require conductive plastic grades for component shipments.
- Construction:Heavy-load hardwood and steel configurations for building materials. Regional builders merchants operate lower-velocity pools with less standardized specifications.
- Chemicals:Corrosion-resistant plastic and steel for hazardous material containment. UN-certified designs for dangerous goods transport command regulatory testing premiums.
Food & Beverage anchors volume concentration while Pharmaceuticals drives the steepest technology upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK's Waste Framework Directive implementation and emerging pallet reuse mandates are tightening material compliance requirements across British distribution networks. Demand concentrates in England's Midlands logistics corridor, where major distribution hubs cluster around Birmingham and the East Midlands.
Midlands
Supermarket chains are consolidating supplier networks around standardized CHEP and LPR pooling programs across Birmingham and the East Midlands. The Environment Agency's transposed Waste Framework Directive shapes material provenance documentation for circular reuse streams. Leicester and Nottingham distribution zones show dense pooling coverage with real-time tracking integration.
London and Southeast
Pharmaceutical distributors and temperature-controlled logistics operators specify RFID-embedded polyethylene pallets with contamination audit trails. MHRA guidance on Good Distribution Practice elevates asset traceability requirements for temperature-sensitive loads. Heathrow logistics clusters serve as entry points for pharmaceutical imports requiring wash-cycle documentation.
North England
Manchester and Yorkshire distribution zones show underdeveloped pooling coverage relative to southern density, offering whitespace for network expansion. ISPM 15 heat treatment mandates extend compliance timelines for wooden units moving through Channel ports. Leeds and Sheffield industrial corridors attract capital-efficient operators seeking regional hub establishment.
Scotland
Food-grade washability specifications from major retailers drive virgin resin adoption despite cost premiums in Glasgow and Edinburgh distribution networks. Scottish Environment Protection Agency regulations align with UK-wide extended producer responsibility frameworks. Aberdeen's chemicals sector deploys corrosion-resistant plastic and steel configurations for hazardous material containment.
Wales
Export handling applications face structural pressure from post-Brexit customs complexity that extends dwell times and accelerates wear cycles through Cardiff and Newport port facilities. Natural Resources Wales enforces material compliance parallel to Environment Agency standards. South Wales manufacturing support loops maintain closed-loop systems with barcode-tracked asset registers.
UK Pallets Market Competitive Landscape
Channel-controlling players compete with product-specialist players across British distribution networks. Asset-light pooling models compress fixed-asset requirements, tilting advantage toward operators with dense reverse logistics infrastructure. Three archetypes dominate: capital-efficient pooling networks, circular-material manufacturers, and hygiene-grade plastic specialists. Consolidation through strategic partnerships and RFID-technology licensing reshape competitive positioning.
Among established pooling operators, Brambles Limited exemplifies the capital-efficient network archetype through extensive CHEP infrastructure. Schoeller Allibert Group occupies a position within reusable plastic container and pallet integration. Cabka anchors the circular-material tier via recycled plastic manufacturing credentials.
| Leading Market Players |
|---|
| Brambles Limited |
| Rehrig Pacific Company |
| Schoeller Allibert Group |
| Cabka |
| Monoflo International |
| ORBIS Corp. |
| Allstate Corp |
| Polymer Solutions International |
| Perfect Pallets |
| Others |
Pricing and Supply Chain Analysis
Undercapacity at ISPM 15 heat treatment facilities across the Midlands corridor is compressing supplier margins and amplifying pricing power for certified operators serving export-facing buyers. This utilization squeeze feeds directly into contract negotiation leverage, with treated wooden pallet premiums widening against untreated spot-market alternatives.
Pricing Analysis
Certification level creates the primary spread between commodity softwood and specification-grade alternatives in UK pallet markets. Three-tier pricing structure across premium, standard, and economy levels reflects ISPM 15 compliance status, wash-cycle documentation for food-grade plastic, and RFID-embedded traceability. Cost compression in untreated softwood tiers is intensifying because Baltic timber supply disruptions and freight rate volatility squeeze domestic manufacturers lacking long-term fiber contracts. Supermarket distribution networks show lowest price sensitivity due to guaranteed availability clauses, while spot-market buyers for single-use export shipments exhibit highest sensitivity to unit cost fluctuations.
Supply Chain Analysis
Tariff exposure between the UK and EU post-Brexit customs regimes dominates supply chain risk calculations for wooden pallet flows through Channel ports. Raw material sourcing draws from Baltic states for softwood fiber, domestic Midlands sawmills for hardwood, and German-Dutch polymer suppliers for polyethylene resin. Single-source vulnerability concentrates in heat treatment certification capacity, where facility bottlenecks extend compliance timelines and detention risks. Distribution runs through England's Midlands logistics corridor, with Birmingham-East Midlands hubs anchoring national pooling networks and Manchester-Leeds zones offering whitespace penetration opportunities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across supplier consolidation patterns and emerging reuse mandates is creating niche positioning opportunities for specialized operators. Food-grade washability specifications and extended producer responsibility frameworks are splintering demand into certification-tiered segments.
For Market Incumbents: Entrench network density advantages by deepening reverse logistics infrastructure across underpenetrated Northern England zones. Invest in RFID-pooling convergence capabilities to collapse dwell-time uncertainty and enable dynamic pricing structures. Acquire regional repair specialists to offset legacy wooden pallet technician skill scarcity degrading refurbishment throughput quality. For New Entrants and Emerging Players: Manchester and Yorkshire distribution zones offer the most penetrable whitespace for pooling network establishment relative to southern density saturation. Target pharmaceutical and cold-chain operators specifying contamination-audited polyethylene units with premium positioning above commodity wood. Pursue circular-material manufacturing credentials via recycled plastic pellet supply agreements to compete on emerging extended producer responsibility compliance. For Investors and Strategic Acquirers: Long-term, this sits as a capital-efficiency play because asset-light pooling models compress fixed-asset requirements and tilt returns toward dense reverse logistics infrastructure rather than manufacturing scale. Acquisition targets should demonstrate verified lifecycle tracking capabilities aligned with Waste Framework Directive documentation requirements. Watch ISPM 15 certification backlog resolution at Channel ports as the signal indicating treatment capacity expansion and margin normalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| RFID-Pooling Convergence | Real-time location tracking integration collapses dwell-time uncertainty for CHEP and LPR network operators. |
| Northern England Network Expansion | Manchester and Yorkshire whitespace penetration addresses regional vulnerability to Midlands concentration. |
| Circular-Material Manufacturing Scale-Up | Recycled polyethylene production aligns with Environment Agency reuse mandate documentation requirements. |
| Heat Treatment Capacity Addition | ISPM 15 certification backlog resolution reduces Channel port detention risks for export-facing customers. |
| Food-Grade Wash-Cycle Validation | Contamination audit trail capabilities satisfy major retailer specifications for direct product contact applications. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with pooling network operators, timber procurement managers, pharmaceutical logistics directors, and repair shop technicians; and secondary validation through Environment Agency regulatory filings, BSI standards documentation, customs trade data, and supermarket supply chain disclosures. Bottom-up triangulation against top-down sector sizing anchored volume and value estimates across wooden, plastic, metal, and paper pallet categories.
Forecast inputs span product type rotation velocities, material cost trajectories, and regulatory compliance timeline shifts across the analysis window. Segmentation dimensions modeled include pallet material grade, end-use industry hygiene requirements, application cycle intensity, and regional logistics hub density. CAGRs derive from asset turnover velocity differentials between pooling models and purchase-to-own arrangements, with ISPM 15 mandate penetration and extended producer responsibility framework adoption as key demand modifiers.
Macroeconomic conditions sit as an overlay; deviation in Baltic timber freight rates, warehouse labor availability, and polymer resin pricing would shift the trajectory. Forecasts reflect documented assumptions about repair network capacity expansion and RFID adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Displays Market
Pallets Packaging
Pallet Shippers Market
Pallets Packaging
Japan Pallets Market
Pallets Packaging
Foldable Pallet Container Market
Pallets Packaging
Pallet Tines Market
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Disposable Plastic Pallet Market
Pallets Packaging
Corrugated Pallets Market
Pallets Packaging
Block Pallets Market
Pallets Packaging
Wooden Pallets Market
Pallets Packaging
Corrugated Pallet Containers Market
Pallets Packaging
Pallet Jacks Market
Pallets Packaging
PUR Shippers Market
Pallets Packaging
Pallet Corner Boards Market
Pallets Packaging
Foldable Plastic Pallet Boxes Market
Pallets Packaging
Paper Pallet Market