
 India Online Grocery Market | 2026-2036
India Online Grocery Market Size, Share, and Industry Trends Forecast 2026-2036
India Online Grocery Market Outlook
Last-mile delivery economics is tilting toward quick-commerce networks over scheduled slot models. Bigbasket leverages its warehouse-first infrastructure to sustain bulk-order margins across Tier-1 cities. Zepto competes through dark-store density that anchors sub-10-minute delivery promises in Mumbai and Bangalore. JioMart extends its kirana integration to control price positioning in price-sensitive segments.
India online grocery encompasses perishable and non-perishable food procurement through digital platforms, requiring temperature-controlled logistics between 2°C and 8°C for dairy and fresh produce categories to prevent spoilage rates above industry thresholds. Packaged foods dominates current transaction volumes due to standardized SKUs and longer shelf windows that reduce fulfillment risk. On-demand delivery captures the fastest expansion as urban consumers substitute platform apps for kirana visits, while subscription services still occupy a niche among planned household buyers seeking recurring staples.
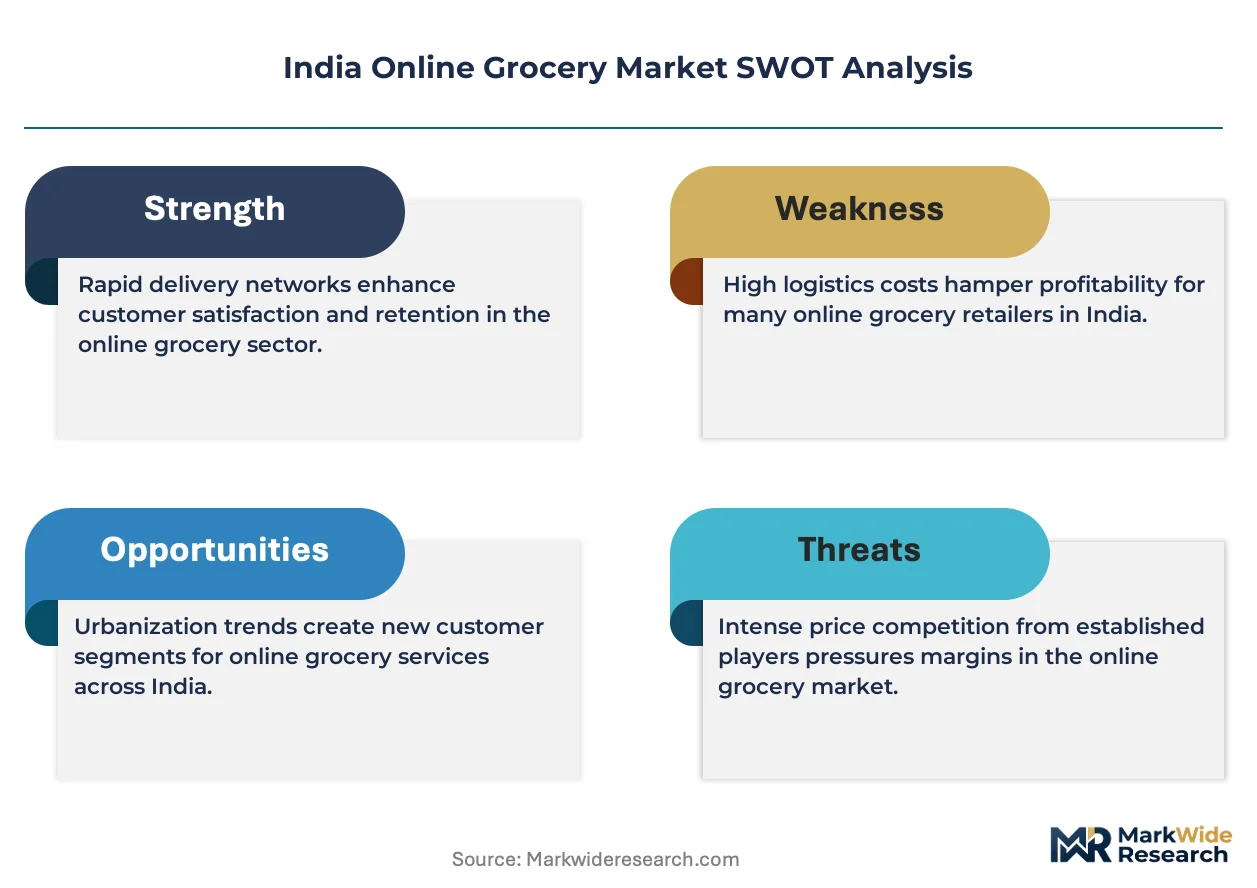
FSSAI mandates digital traceability for packaged foods, while RBI's payment aggregator rules shape wallet-based checkout flows that influence customer conversion rates. BIS certification requirements for cold-chain equipment add capital intensity for new entrants building refrigerated last-mile fleets. Stakeholders must monitor how state-level warehouse zoning policies in Maharashtra and Karnataka reshape dark-store placement economics.
Market Dynamics
Quick-commerce networks are compressing delivery windows from same-day to sub-15-minute fulfillment, forcing incumbents to reconfigure warehouse placement and inventory depth across Mumbai, Bangalore, and Delhi NCR clusters.
Growth Catalysts
- FSSAI Digital Traceability Mandate:Packaged food sellers must maintain end-to-end lot tracking, elevating platform compliance costs but filtering unorganized sellers and consolidating transaction flow toward licensed operators.
- Urban Working Professional Density:Metropolitan households with dual-income structures generate recurring high-frequency orders, creating predictable demand pools that justify dark-store capital deployment in Hyderabad and Pune.
- Refrigerated Last-Mile Fleets:Electric two-wheelers with 2°C to 8°C containment units now cover 80% of dairy and fresh produce routes, reducing spoilage liability and expanding perishable category viability.
Market Restraints
- State Warehouse Zoning Friction:Maharashtra and Karnataka municipal authorities impose restrictive commercial-use classifications on micro-fulfillment centers, inflating real estate procurement timelines by 8-12 months.
- Cold-Chain Equipment Capital Intensity:BIS-certified refrigeration units carry 40-60% premium over standard commercial variants, raising break-even thresholds for new entrants in Tier-2 expansion.
- Kirana Network Stickiness:Neighborhood provision stores retain credit-extension relationships and vernacular interface familiarity that platform apps struggle to replicate in price-sensitive segments.
Strategic Opportunities
- Telangana and Andhra Pradesh Corridor:Hyderabad's pharmaceutical logistics infrastructure offers transferable cold-chain talent and warehouse leasing ecosystems for grocery platforms seeking southern expansion.
- Subscription Staples Consolidation:Recurring delivery of rice, pulses, and cooking oil captures household budget predictability while reducing per-order logistics cost through route optimization.
- RBI Payment Aggregator Framework:Streamlined wallet-based checkout flows reduce cart abandonment at the payment stage, particularly for first-time users in cash-dominant Tier-3 towns.
Industry Challenges
- Temperature-Controlled Driver Training:Last-mile personnel require certification in handling 2°C to 8°C payloads without breach, creating workforce pipeline constraints as fleet scales.
- Legacy Kirana Integration Complexity:Inventory synchronization between platform apps and unorganized retailer stock-keeping units demands API standardization that remains fragmented across state tax regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Online Grocery Market |
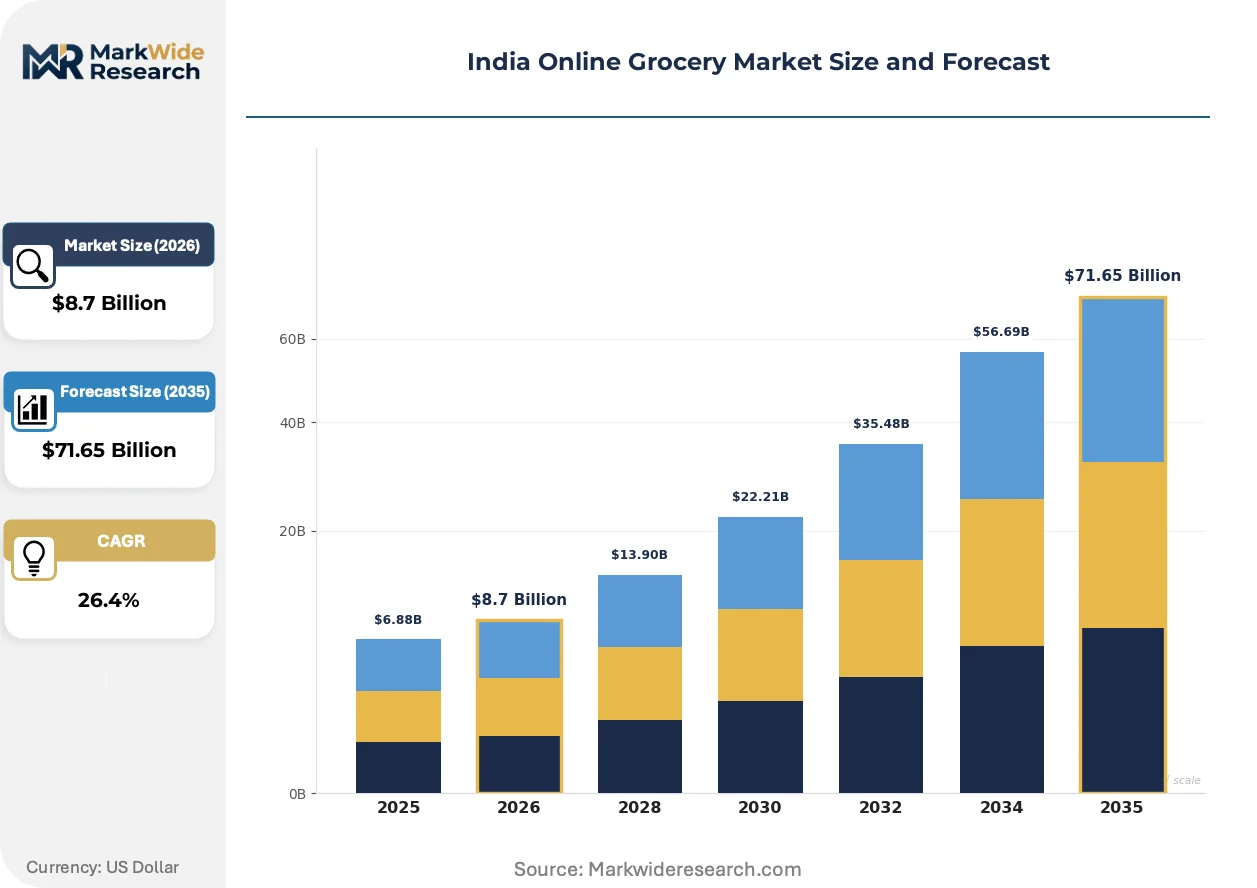
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $71.65 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Packaged Foods, Dairy Products Customer Type: Urban Consumers, Rural Consumers, Working Professionals, Families Delivery Model: Home Delivery, Click & Collect, Subscription Services, On-Demand Delivery Payment Method: Cash on Delivery, Credit/Debit Card, Mobile Wallets, Net Banking |
| Companies Covered | JioMart, Avenue Supermarts Ltd., Amazon.com Inc., Swiggy Instamart, Blink Commerce Pvt. Ltd., Bigbasket, Zepto, Dunzo Digital Pvt. Ltd., Flipkart Internet Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Online Grocery Market Strategic Shifts
Platform economics now pivot on inventory positioning rather than demand aggregation, with predictive algorithms determining which SKUs sit in forward dark-stores versus central warehouses.
AI-driven demand forecasting is migrating from batch replenishment to real-time inventory rebalancing. Quick-commerce operators in Mumbai and Bangalore deploy machine learning models that adjust stock levels hourly based on neighborhood consumption patterns. This compression of planning cycles reduces out-of-stock incidents for high-velocity SKUs while inflating working capital requirements for slower-moving inventory categories.
FSSAI's 2023 digital labeling directive requires QR-code-linked nutritional and allergen disclosure for all packaged foods sold through e-commerce channels. Manufacturers must redesign packaging artwork and backend database infrastructure to comply, with compliance costs concentrated among mid-tier regional brands supplying platform private-label programs. The mandate accelerates consolidation toward national players with dedicated regulatory affairs functions.
Households are substituting platform apps for kirana visits across India's top eight cities, with frequency rising from weekly to 3-4 times weekly for fresh produce and dairy categories. This behavioral shift compresses basket sizes while expanding total addressable transaction volume, forcing platforms to optimize for order economics at Rs 150-200 average ticket sizes rather than the Rs 800-1000 bulk-order model that sustained scheduled delivery incumbents.
India Online Grocery Market Segmentation
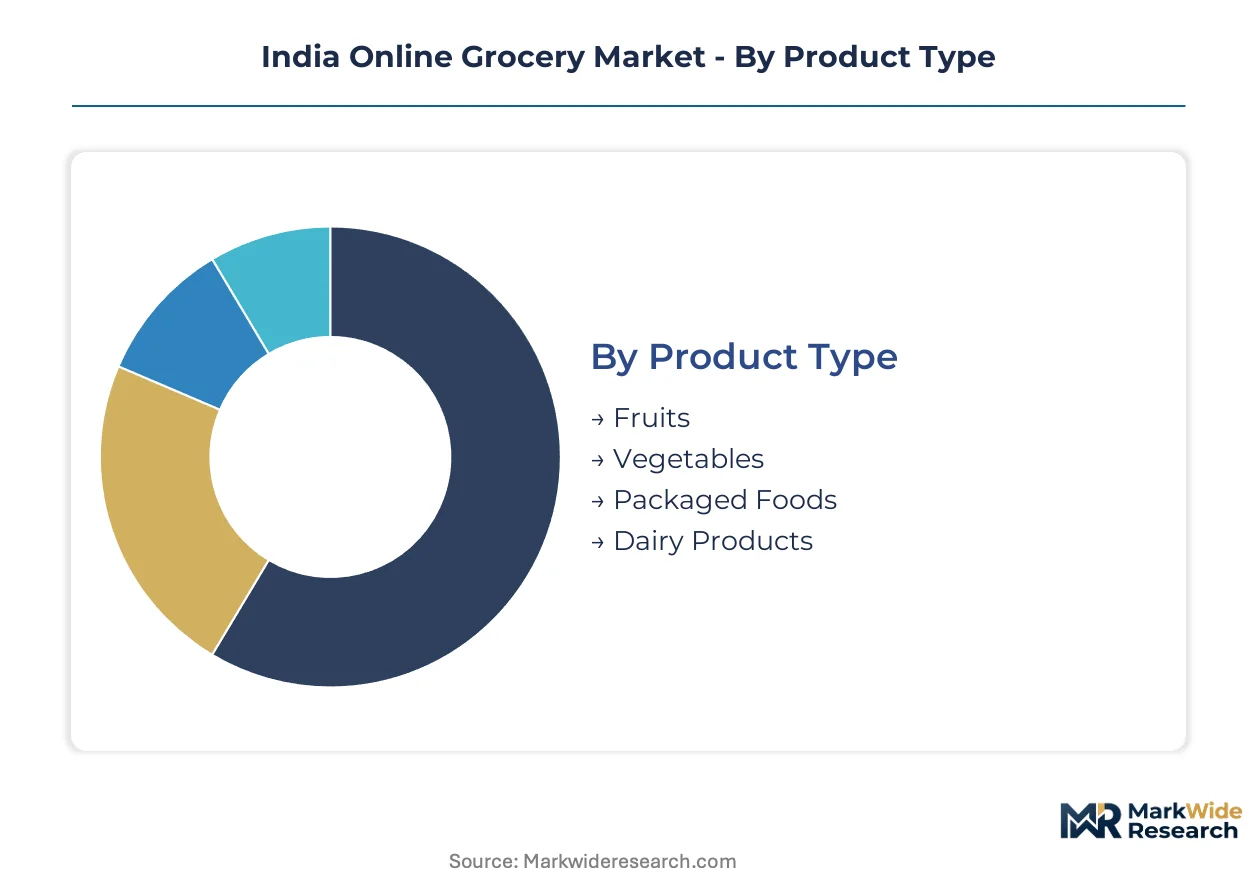
India's online grocery landscape fragments across procurement habits, infrastructure readiness, and household structures. Each dimension shapes fulfillment economics and platform positioning differently across Maharashtra, Karnataka, and Telangana corridors.
Product Type:
Cost tier determines margin structure and cold-chain capital intensity for each category.
- Packaged Foods:Standardized SKUs with extended shelf windows minimize spoilage liability. Maharashtra and Karnataka households drive recurring demand for branded staples, though FSSAI digital traceability mandates elevate compliance costs for regional suppliers.
- Dairy Products:Temperature-controlled logistics between 2°C and 8°C governs viability. Hyderabad and Bangalore density supports electric two-wheeler fleet deployment for sub-15-minute delivery windows in premium milk and curd segments.
- Fruits:Perishability demands rapid inventory turnover. Quality grading inconsistencies constrain rural sourcing scalability.
- Vegetables:Hyperlocal aggregation through mandi-linked platforms dominates procurement. Price volatility challenges margin predictability.
Packaged Foods holds installed capacity. Dairy Products is rotating up the share rankings.
Customer Type:
Application context shapes order frequency, basket composition, and platform loyalty patterns.
- Working Professionals:Dual-income metropolitan households generate 3-4 weekly orders with compressed basket sizes. Mumbai and Delhi NCR clusters justify dark-store density for impulse-driven fresh produce purchases.
- Families:Planned monthly staples procurement favors subscription models. Rice, pulses, and cooking oil bulk orders reduce per-unit logistics cost through route optimization.
- Urban Consumers:Platform app substitution for kirana visits accelerates across Tier-1 cities. Credit-extension relationships with neighborhood stores retain stickiness in price-sensitive segments.
- Rural Consumers:Limited cold-chain penetration restricts perishable category access. Cash-on-delivery dominance elevates logistics cost per transaction.
Working Professionals commands transaction velocity. Families is climbing the fastest in absolute order volume.
Delivery Model:
Volume throughput and working capital requirements diverge sharply across fulfillment architectures.
- On-Demand Delivery:Sub-15-minute promises anchor competitive positioning in Mumbai and Bangalore. Dark-store inventory depth demands predictive algorithms for hourly SKU rebalancing.
- Home Delivery:Scheduled slot models sustain bulk-order economics through warehouse-first infrastructure. Tier-2 expansion faces state warehouse zoning friction in Maharashtra and Karnataka.
- Subscription Services:Recurring staples delivery captures household budget predictability. Churn management requires flexible pause mechanisms.
- Click & Collect:Kirana integration extends platform reach without last-mile fleet investment. Inventory synchronization APIs remain fragmented across state tax regimes.
Home Delivery retains fulfillment infrastructure scale. On-Demand Delivery is gaining share fastest among metropolitan cohorts.
Payment Method:
Maturity of digital financial infrastructure shapes checkout conversion and customer acquisition cost.
- Mobile Wallets:RBI payment aggregator framework streamlines wallet-based flows. First-time user conversion in Tier-3 towns benefits from simplified KYC requirements.
- Credit/Debit Card:Urban working professional segments dominate usage. Chargeback liability concentrates platform risk management resources.
- Cash on Delivery:Rural penetration necessity elevates reverse logistics cost. Collection reconciliation delays working capital cycles.
- Net Banking:High-ticket bulk orders trigger preference for direct bank transfer. Transaction failure rates exceed mobile wallet benchmarks.
Mobile Wallets holds installed capacity. Credit/Debit Card is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dark-store density concentrates in Maharashtra, Karnataka, and Telangana where municipal zoning permits micro-fulfillment centers. State-level warehouse classifications and cold-chain infrastructure gaps fragment expansion economics across India's metropolitan corridors.
Maharashtra
Mumbai's dual-income households generate 3-4 weekly grocery orders with compressed basket sizes. FSSAI digital labeling mandates elevate compliance costs for packaged food suppliers entering the state. Thane and Navi Mumbai clusters host the highest dark-store concentration, with platforms deploying predictive algorithms for hourly SKU rebalancing.
Karnataka
Bangalore's working professional density anchors sub-15-minute delivery promises across premium dairy and fresh produce segments. BIS certification requirements for cold-chain equipment add 40-60% capital premiums over standard commercial variants. Whitefield and Koramangala industrial zones concentrate electric two-wheeler fleet deployment with 2°C to 8°C containment units.
Telangana
Hyderabad's pharmaceutical logistics infrastructure offers transferable cold-chain talent and warehouse leasing ecosystems for grocery platforms. RBI payment aggregator rules shape wallet-based checkout flows that reduce cart abandonment. Gachibowli and Hitech City corridors justify dark-store capital deployment through predictable demand pools from IT corridor employment.
Delhi-NCR
Gurgaon and Noida clusters face restrictive commercial-use classifications on micro-fulfillment centers, inflating real estate procurement timelines by 8-12 months. State warehouse zoning friction limits quick-commerce network expansion beyond established Tier-1 nodes. Cash-on-delivery dominance in peripheral towns elevates reverse logistics cost per transaction.
Andhra Pradesh
Visakhapatnam and Vijayawada corridors leverage transferable cold-chain infrastructure from Hyderabad's logistics ecosystem. FSSAI mandates filter unorganized sellers and consolidate transaction flow toward licensed operators. Limited refrigerated last-mile penetration restricts perishable category viability outside core urban zones.
India Online Grocery Market Competitive Environment
Incumbent warehouse-first operators and dark-store-native quick-commerce platforms split the market across fulfillment architecture lines. The vendor base organizes around three strategic archetypes: scheduled-slot bulk specialists, sub-15-minute promise networks, and kirana-integrated hybrid models. Consolidation pressures favor platforms with backward integration into cold-chain fleets and predictive inventory systems. Geographic expansion and technology licensing represent the dominant competitive vectors as state zoning policies reshape real estate procurement economics.
Within the quick-commerce tier, Zepto and Blinkit exemplify dark-store-native positioning through sub-10-minute delivery infrastructure. Bigbasket anchors the scheduled-slot archetype with warehouse-first economics sustaining bulk-order margins. JioMart occupies the kirana-integration vector, extending platform reach through neighborhood retailer networks without dedicated last-mile fleet investment. Each represents distinct capital intensity and working capital trade-offs that state-level regulatory fragmentation amplifies.
| Leading Market Players |
|---|
| JioMart |
| Avenue Supermarts Ltd. |
| Amazon.com Inc. |
| Swiggy Instamart |
| Blink Commerce Pvt. Ltd. |
| Bigbasket |
| Zepto |
| Dunzo Digital Pvt. Ltd. |
| Flipkart Internet Pvt. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Mumbai's dark-store concentration anchors pricing power for sub-15-minute delivery tiers, with Thane and Navi Mumbai clusters compressing margins through inventory proximity and hourly SKU rebalancing algorithms. FSSAI digital labeling mandates and BIS-certified cold-chain equipment premiums feed into platform cost structures that stratify across quick-commerce and scheduled-slot archetypes.
Pricing Analysis
Subscription revenue from recurring staples delivery drives lifetime value capture for platform operators. Three-tier pricing structure across premium, standard, and economy levels segments by delivery speed and basket composition, with urban working professionals absorbing premiums for sub-10-minute windows. Price differentiation hinges on cold-chain certification tier and geographic delivery density. Cost compression in economy tiers is intensifying because kirana networks retain credit-extension stickiness in price-sensitive segments. Rural consumers exhibit highest price sensitivity, while metropolitan dual-income households show lowest elasticity for convenience premiums.
Supply Chain Analysis
Third-party logistics providers including Delhivery and Shadowfax hold concentrated last-mile capacity for temperature-controlled fulfillment. Supply concentrates in Maharashtra, Karnataka, and Telangana where municipal zoning permits micro-fulfillment centers. Raw material dependencies span electric two-wheeler fleets with 2°C to 8°C containment units, BIS-certified refrigeration hardware, and predictive inventory software. Single-source vulnerability in dark-store real estate procurement inflates break-even timelines. Distribution runs through platform apps, kirana-integrated click-and-collect nodes, and scheduled warehouse slots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified cold-chain personnel and predictive algorithm talent constrains platform scaling economics. The gap between dark-store deployment ambition and workforce pipeline capacity defines competitive moats.
For Market Incumbents: Insulate margin structure through backward integration into captive electric refrigerated fleets and in-house demand forecasting systems. Consolidate position by lobbying state warehouse zoning authorities in Maharashtra and Karnataka for expedited commercial-use classifications. Counter emerging quick-commerce entrants through subscription lock-in for staples categories. For New Entrants and Emerging Players: Tier-2 corridors in Andhra Pradesh and Telangana represent the most penetrable entry point, leveraging Hyderabad's transferable pharmaceutical logistics talent and warehouse leasing ecosystems. Target subscription staples consolidation in family household segments with flexible pause mechanisms. Enter through white-label cold-chain infrastructure partnerships rather than owned fleet buildout. For Investors and Strategic Acquirers: Long-term, this sits as a platform infrastructure play because winner-take-most dynamics favor operators with predictive inventory systems and municipal zoning relationships. Prioritize acquisition targets with established dark-store density in Mumbai and Bangalore corridors and demonstrated FSSAI compliance infrastructure. Monitor state-level warehouse zoning policy shifts as inflection signal for expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Dark-Store Network Expansion | Sub-15-minute delivery promises in Mumbai and Bangalore clusters capture working professional frequency. |
| Backward Integration into Cold-Chain Fleets | Captive electric two-wheeler deployment with 2°C to 8°C containment reduces spoilage liability. |
| Subscription Staples Consolidation | Recurring rice and pulses delivery captures household budget predictability through route optimization. |
| Kirana Integration API Development | Inventory synchronization with neighborhood stores extends platform reach without last-mile investment. |
| FSSAI Compliance Infrastructure Investment | Digital traceability systems filter unorganized sellers and consolidate flow toward licensed operators. |
Study Parameters
Cross-validation between primary interviews with quick-commerce operations heads and secondary validation from FSSAI compliance databases anchors the qualitative findings. Conversations with dark-store network planners, cold-chain fleet managers, municipal zoning officers, and kirana association representatives informed infrastructure economics. Secondary sources include RBI payment aggregator circulars, BIS certification registries, state warehouse zoning notifications, and platform app download analytics. Bottom-up dark-store deployment modeling triangulates against top-down metropolitan household penetration estimates.
Calibration against historical quick-commerce expansion trajectories in comparable density corridors refines projection parameters. Segmentation dimensions span product type, customer archetype, delivery model, and payment method, with regional regulatory cluster as an additional modeled variable. CAGRs derive from compounding annual penetration increments across the projection horizon. Forecast inputs incorporate electric two-wheeler fleet deployment rates and municipal zoning approval timelines.
Practitioners should monitor state warehouse zoning policy shifts and FSSAI enforcement intensity for early signals of competitive repositioning. Forecasts embed assumptions on cold-chain equipment cost trajectories and working professional density growth. Quarterly review of dark-store licensing velocity and kirana network churn indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Thailand Food Service Market
Food Service
Europe Food Away from Home Market
Food Service
Galley Equipment Market
Food Service
North America Online Grocery Delivery Market
Food Service
GCC Biodegradable Food Service Disposables Market
Food Service
China Inflight Catering Market
Food Service
Charbroiler Market
Food Service
North America Food Platform-To-Consumer Delivery Market
Food Service
Shaker Bottles Market
Food Service
North America Cafes & Bars Market
Food Service
Personal Chef Services Market
Food Service
Takeout Dinner Market
Food Service
Global Combi Ovens Market
Food Service
Food and Grocery Retail Market
Food Service
Nigeria Food Service Market
Food Service
UK Smokeless Indoor Grills Market