
 US Mutual Funds Market | 2026-2036
US Mutual Funds Market Size, Share, and Industry Trends Forecast 2026-2036
US Mutual Funds Market Insights
Asset manager consolidation across the Northeast corridor is realigning distribution economics for open-end investment vehicles. Vanguard leverages its at-cost ownership structure to sustain fee compression across passive fund lineups. BlackRock anchors institutional flows through its iShares ETF-to-mutual-fund conversion capabilities. Fidelity Investments competes on hybrid active-passive strategies that differentiate its managed account platforms.
A mutual fund pools capital from multiple investors to purchase diversified portfolios of securities, with net asset value calculated daily at 4:00 PM Eastern Time using closing market prices. These vehicles provide fractional ownership access to professionally managed bond, equity, and hybrid portfolios for investors lacking minimum thresholds for separate accounts. Equity funds lead by assets under management, reflecting retail preference for domestic large-cap exposure, while passive management strategies capture the fastest flow velocity as fee-sensitive investors migrate from active mandates. Money market funds retain structural importance as cash sweep vehicles despite compressed yields, and broker-dealer distribution channels concentrate margin pools through revenue-sharing arrangements with fund complexes.
The SEC regulates fund disclosure through Form N-1A and shareholder report modernization rules, while FINRA governs broker-dealer sales practices and suitability standards for retail recommendations. The Department of Labor's fiduciary framework under ERISA shapes how retirement plan sponsors evaluate share classes and revenue-sharing arrangements. Stakeholders must monitor whether the SEC's pending swing pricing and liquidity risk management amendments alter redemption behavior in bond funds.
Market Dynamics
The SEC's shareholder report modernization rules are compressing fee disclosure timelines and forcing fund complexes to restructure revenue-sharing arrangements with broker-dealers.
Growth Catalysts
- ERISA fiduciary framework:The Department of Labor's guidance on share-class selection is driving plan sponsors toward lower-cost institutional share classes, expanding assets in target-date vehicles.
- Passive management technology:Automated portfolio rebalancing and tax-loss harvesting capabilities are accelerating flows into hybrid active-passive strategies.
- California technology sector retirement systems:Concentrated demand from Silicon Valley plan sponsors is creating dedicated target-date fund lineups with extended equity glide paths.
Market Restraints
- Revenue-sharing compression:The SEC's updated disclosure requirements are eliminating opaque 12b-1 fee arrangements, squeezing broker-dealer distribution margins.
- Money market yield compression:Sustained low short-term interest rates are eroding the structural profitability of cash sweep vehicles despite stable asset levels.
- Active manager fee resistance:Retail investors are systematically redeeming from high-expense-ratio equity funds, creating outflow pressure on traditional active complexes.
Strategic Opportunities
- ETF-to-mutual-fund conversion infrastructure:Tax-efficient share class structures that bridge exchange-traded and open-end vehicles are capturing institutional flows seeking operational flexibility.
- Managed account platform integration:Unified managed account technology is enabling advisors to blend mutual funds with direct indexing and alternative vehicles in single-dashboard environments.
- Swing pricing adoption:Early implementation of the SEC's liquidity risk management amendments is creating first-mover advantages in bond fund redemption handling.
Industry Challenges
- Portfolio manager succession pipelines:Active equity complexes face concentrated key-person risk as veteran managers retire without proven successor track records.
- Legacy technology integration:Consolidating fund families must reconcile incompatible shareholder recordkeeping systems, delaying expense ratio realization from merger synergies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Mutual Funds Market |
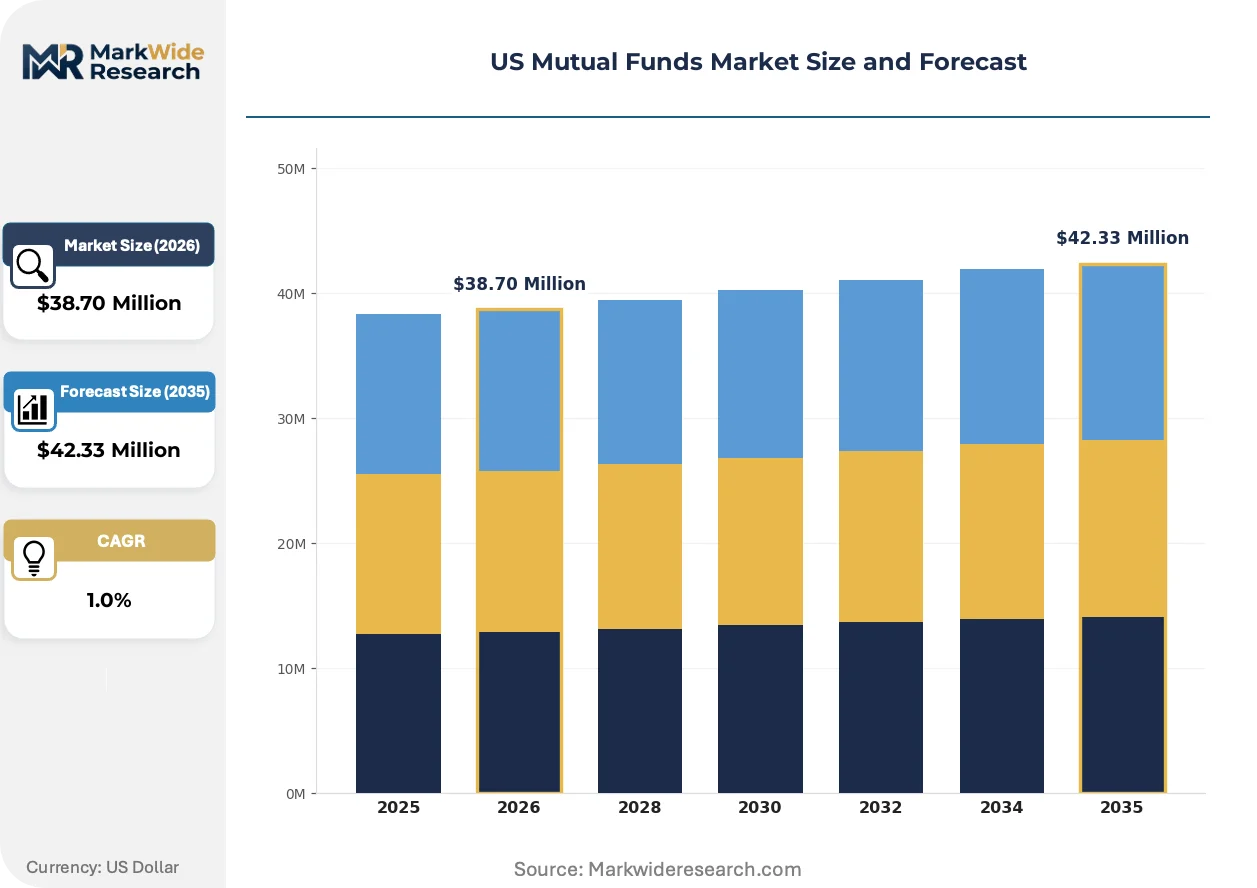
| Market Size in 2026 | $38.70 Million |
| Market Size in 2035 | $42.33 Million |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fund Type: Equity, Bond, Hybrid, Money Market Investment Strategy: Active Management, Passive Management, Indexing, Sector Focus Client Segment: Retail Investors, Institutional Investors, High Net-Worth Individuals, Corporates Distribution Channel: Direct Sales, Financial Advisors, Online Platforms, Broker-Dealers |
| Companies Covered | Vanguard, Fidelity Investments, BlackRock, American Funds, T. Rowe Price, JP Morgan Asset Management, Charles Schwab, Invesco, PIMCO, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Mutual Funds Market Trends and Innovations
Digital distribution infrastructure and regulatory transparency mandates are simultaneously compressing fee structures and expanding access to institutional-caliber portfolio construction tools.
Artificial intelligence-driven risk analytics is rewriting how target-date funds calibrate glide path equity exposure. Plan sponsors in the technology sector are adopting these tools to customize retirement readiness projections for participant cohorts with concentrated employer stock positions. The structural consequence is compressing the competitive advantage of proprietary capital market assumptions held by established target-date providers.
The SEC's pending swing pricing and liquidity risk management amendments are forcing bond fund complexes to rebuild redemption processing infrastructure. Portfolio managers must now pre-position liquidity buffers that alter yield optimization trade-offs in credit-focused mandates. Intermediate-term bond funds with concentrated corporate exposure face the most acute operational redesign requirements.
Direct indexing technology is fragmenting demand for traditional large-cap equity mutual funds. High-net-worth investors and their advisors are unbundling factor exposure through separately managed accounts that replicate index performance with tax customization. California and New York metropolitan corridors exhibit the fastest adoption velocity as advisor platforms integrate fractional share execution capabilities.
US Mutual Funds Market Segmentation
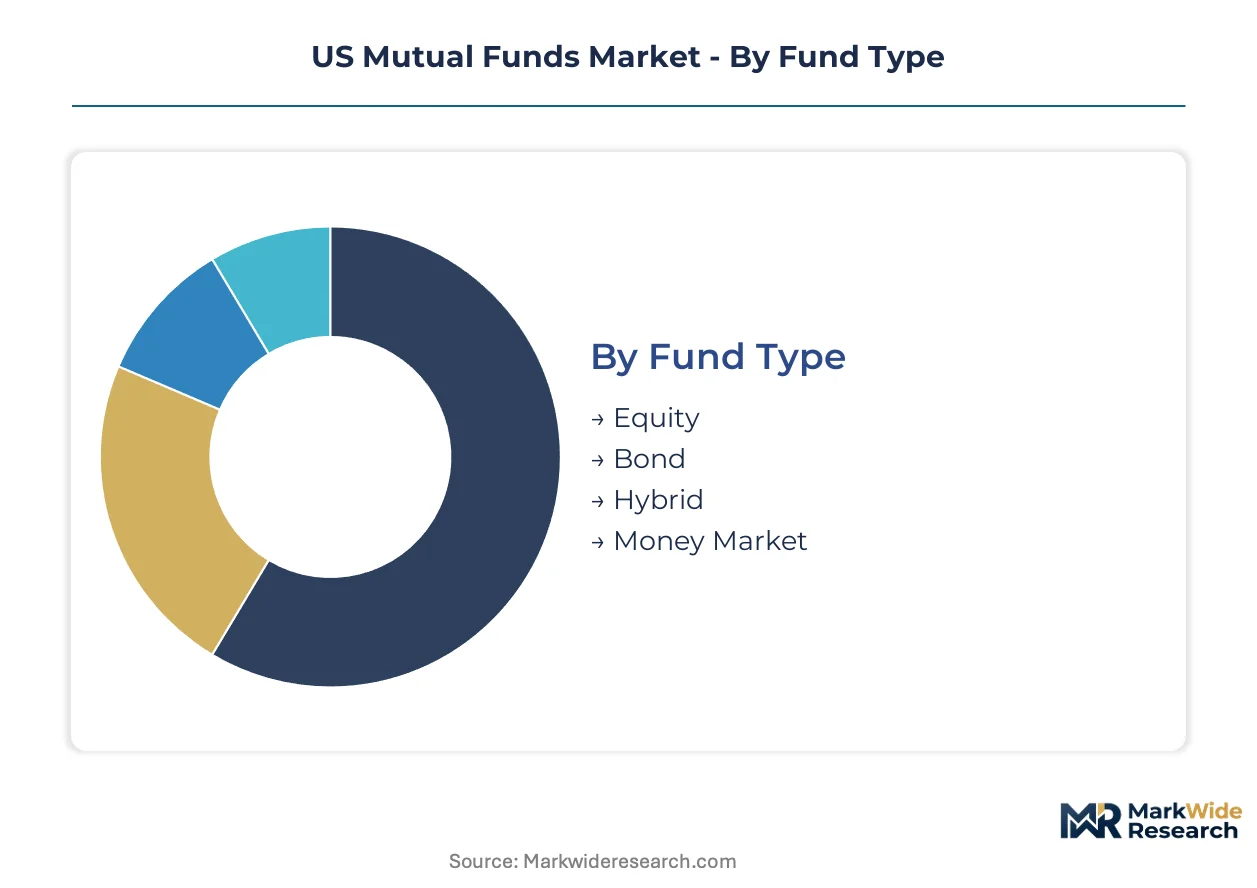
Mutual fund segmentation reveals how capital pools fragment across risk profiles, cost structures, and distribution economics. Understanding these divisions exposes where fee compression strikes deepest and where technology-enabled distribution is rewriting access patterns.
Fund Type:
Upgrade cycles in portfolio construction technology are pushing investors toward vehicles with embedded rebalancing capabilities and automated glide path management.
- Equity:Domestic large-cap allocations dominate assets under management, with S&P 500-tracking vehicles capturing the bulk of passive flows. California technology sector retirement systems concentrate demand here for extended equity glide paths in target-date lineups.
- Bond:Intermediate-term taxable funds face acute operational redesign from SEC liquidity risk management amendments, forcing portfolio managers to pre-position liquidity buffers that alter yield optimization trade-offs. Demand concentrates among institutional investors seeking duration-matched liability coverage.
- Hybrid:Allocation funds blend equity and fixed-income exposure through static or tactical mandates, serving investors seeking simplified diversification without multi-fund construction.
- Money Market:Cash sweep vehicles retain structural importance for brokerage platforms despite sustained yield compression from low short-term interest rates.
Equity sits at the top of the volume ranking, with Bond climbing the fastest as rate volatility reshapes fixed-income demand.
Investment Strategy:
Cost tier differentiation separates managers competing on expense ratio compression from those defending active premium pricing through performance attribution.
- Active Management:Traditional stock-picking mandates face systematic outflow pressure as retail investors redeem from high-expense-ratio equity funds. Fee resistance is most acute in domestic large-cap categories where passive alternatives have demonstrated tracking efficiency.
- Passive Management:Automated portfolio rebalancing and tax-loss harvesting capabilities are accelerating flows into vehicles with minimal tracking error and embedded cost efficiency. This strategy captures the steepest expansion trajectory as fee-sensitive investors migrate from active mandates.
- Indexing:Rules-based replication of market-cap-weighted benchmarks delivers precise beta exposure with minimal manager discretion, concentrating assets in vehicles with sub-basis-point expense ratios.
- Sector Focus:Concentrated industry or thematic exposures appeal to investors seeking targeted factor or macroeconomic positioning beyond broad market beta.
Passive Management commands the largest asset base, with Sector Focus expanding most quickly as thematic investing gains advisor platform integration.
Client Segment:
Margin structures diverge sharply between price-sensitive retail channels and institutional mandates with scale-negotiated fee schedules.
- Retail Investors:Individual accounts accessed through broker-dealer platforms or direct fund complexes, characterized by sensitivity to load structures and 12b-1 fee transparency.
- Institutional Investors:Retirement plan sponsors and defined contribution platforms drive share-class selection toward lower-cost institutional vehicles under ERISA fiduciary guidance, expanding assets in target-date funds.
- High Net-Worth Individuals:Investors with concentrated employer stock positions in technology sector retirement systems are adopting AI-driven risk analytics to customize glide path equity exposure.
- Corporates:Treasury departments utilize money market vehicles for cash management, with sweep arrangements tied to banking relationships rather than investment optimization.
Retail Investors hold the volume lead, with High Net-Worth Individuals gaining share fastest through direct indexing fragmentation of traditional fund demand.
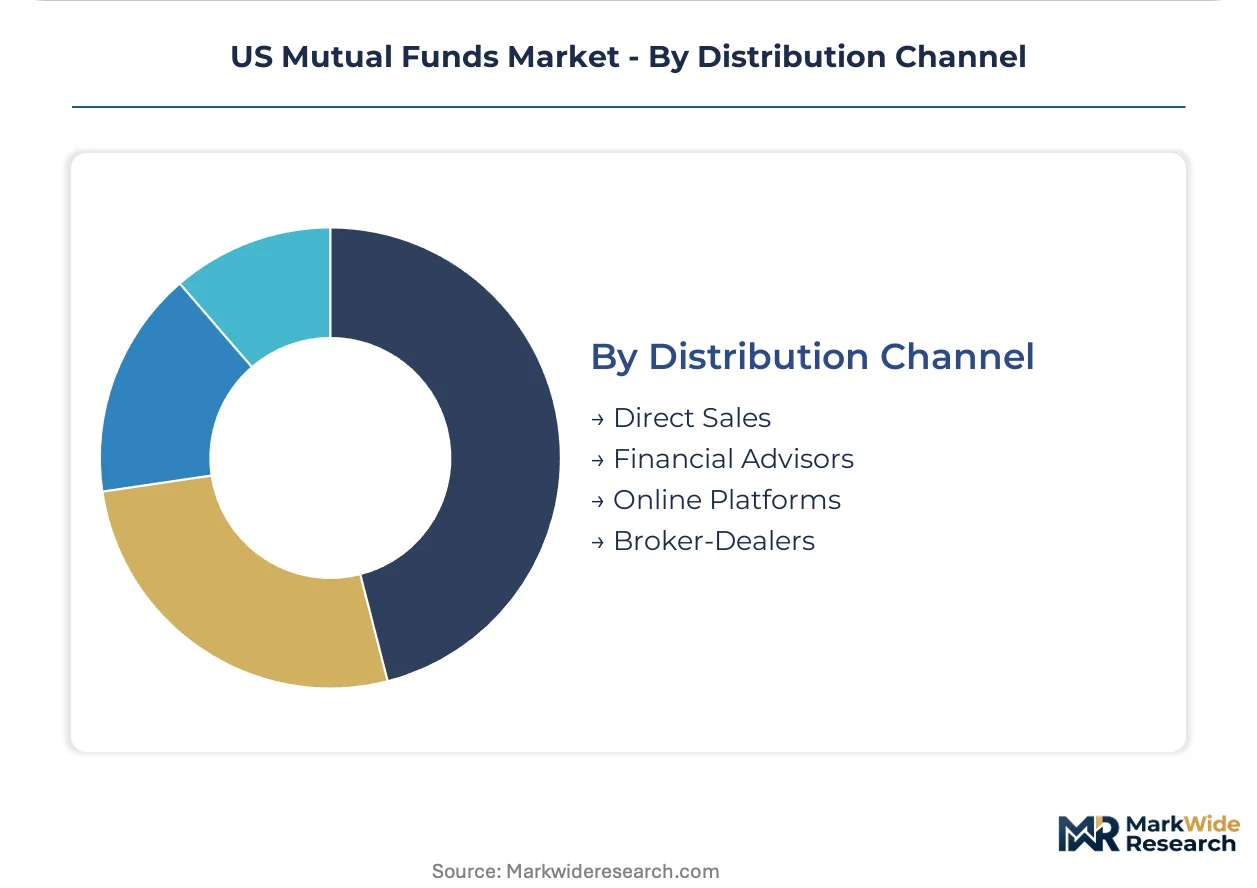
Distribution Channel:
Geography of advisor concentration shapes where digital platforms displace traditional sales relationships versus where human intermediaries retain pricing power.
- Direct Sales:Fund complexes bypass intermediaries to capture full expense ratio revenue, investing in digital onboarding infrastructure to reduce account minimum thresholds.
- Financial Advisors:Independent and wirehouse advisors blend mutual funds with direct indexing and alternative vehicles in unified managed account platforms with single-dashboard integration.
- Online Platforms:Robo-advisors and self-directed brokerage accounts compress distribution margins through automated allocation algorithms and fractional share execution capabilities.
- Broker-Dealers:Revenue-sharing arrangements with fund complexes face elimination from SEC disclosure modernization rules, squeezing margin pools that historically subsidized platform access.
Financial Advisors maintain the dominant volume position, with Online Platforms climbing the fastest as fractional share technology expands access thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California technology sector retirement systems generate outsized demand for extended equity glide paths, while Massachusetts-based asset managers anchor passive fund innovation. The SEC's disclosure modernization rules apply uniformly, yet regional advisor concentration shapes where digital platforms displace traditional distribution.
California
Silicon Valley plan sponsors drive concentrated demand for target-date vehicles with customized equity exposure. The SEC's updated Form N-1A requirements force fund complexes serving this market to compress fee disclosure timelines. San Francisco and San Jose metropolitan corridors exhibit the fastest adoption of AI-driven risk analytics for participant cohorts with concentrated employer stock positions.
Massachusetts
Greater Boston anchors hybrid active-passive strategy development for institutional retirement platforms. The Department of Labor's ERISA fiduciary guidance shapes how plan sponsors in this region evaluate share-class selection. Boston-based asset managers compete on unified managed account technology that blends mutual funds with direct indexing capabilities.
New York
New York Metro concentrates broker-dealer distribution infrastructure and wirehouse advisor platforms. FINRA governs sales practices and suitability standards for retail recommendations throughout this corridor. Manhattan-based fund complexes face acute pressure from SEC revenue-sharing disclosure rules that eliminate opaque 12b-1 fee arrangements.
Texas
Dallas-Fort Worth and Houston metropolitan areas concentrate independent advisor platforms seeking operational flexibility. The SEC's pending swing pricing amendments are forcing bond fund complexes serving this region to rebuild redemption processing infrastructure. Texas-based retirement systems are expanding target-date offerings under ERISA plan sponsor guidance.
US Mutual Funds Market Competitive Landscape
California and Massachusetts producers anchor one tier; New York specialists hold distribution infrastructure. The vendor base concentrates among asset managers with scale-negotiated institutional relationships and technology-enabled retail platforms. Three archetypes dominate: at-cost ownership structures, ETF-to-mutual-fund conversion capabilities, and hybrid active-passive strategies. Consolidation across the Northeast corridor realigns distribution economics, while fee compression forces revenue-sharing restructuring with broker-dealers.
Within the at-cost ownership tier, Vanguard exemplifies structural advantages in passive fund lineups. BlackRock occupies a position bridging exchange-traded and open-end vehicles through institutional conversion infrastructure. Fidelity Investments represents the hybrid strategy archetype, competing on managed account platform differentiation.
| Leading Market Players |
|---|
| Vanguard |
| Fidelity Investments |
| BlackRock |
| American Funds |
| T. Rowe Price |
| JP Morgan Asset Management |
| Charles Schwab |
| Invesco |
| PIMCO |
| Others |
Pricing and Supply Chain Analysis
Institutional retirement plan sponsors concentrate procurement power in the US mutual funds market, driving a three-tier pricing structure across premium, standard, and economy share classes that reflects ERISA fiduciary scrutiny and scale-negotiated fee schedules.
Pricing Analysis
Capacity additions in passive fund lineups are reshaping price floors across the industry. The dominant pricing model stratifies across institutional, advisor, and retail share classes with expense ratios differentiated by volume scale and distribution channel control. Pricing pressure stems from SEC disclosure modernization rules eliminating opaque 12b-1 fee arrangements. Retail investors exhibit the highest price sensitivity, while institutional plan sponsors leverage fiduciary mandates to extract sub-basis-point institutional pricing.
Supply Chain Analysis
Portfolio manager talent availability in Massachusetts and California financial centers constrains active management capacity expansion. Fund manufacturing draws from concentrated intellectual capital pools in Boston and San Francisco, with technology infrastructure dependencies on cloud computing platforms and custodian banking networks. Single-source vulnerability sits with legacy shareholder recordkeeping system providers. Distribution runs through broker-dealer wirehouses, independent advisor platforms, and direct digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
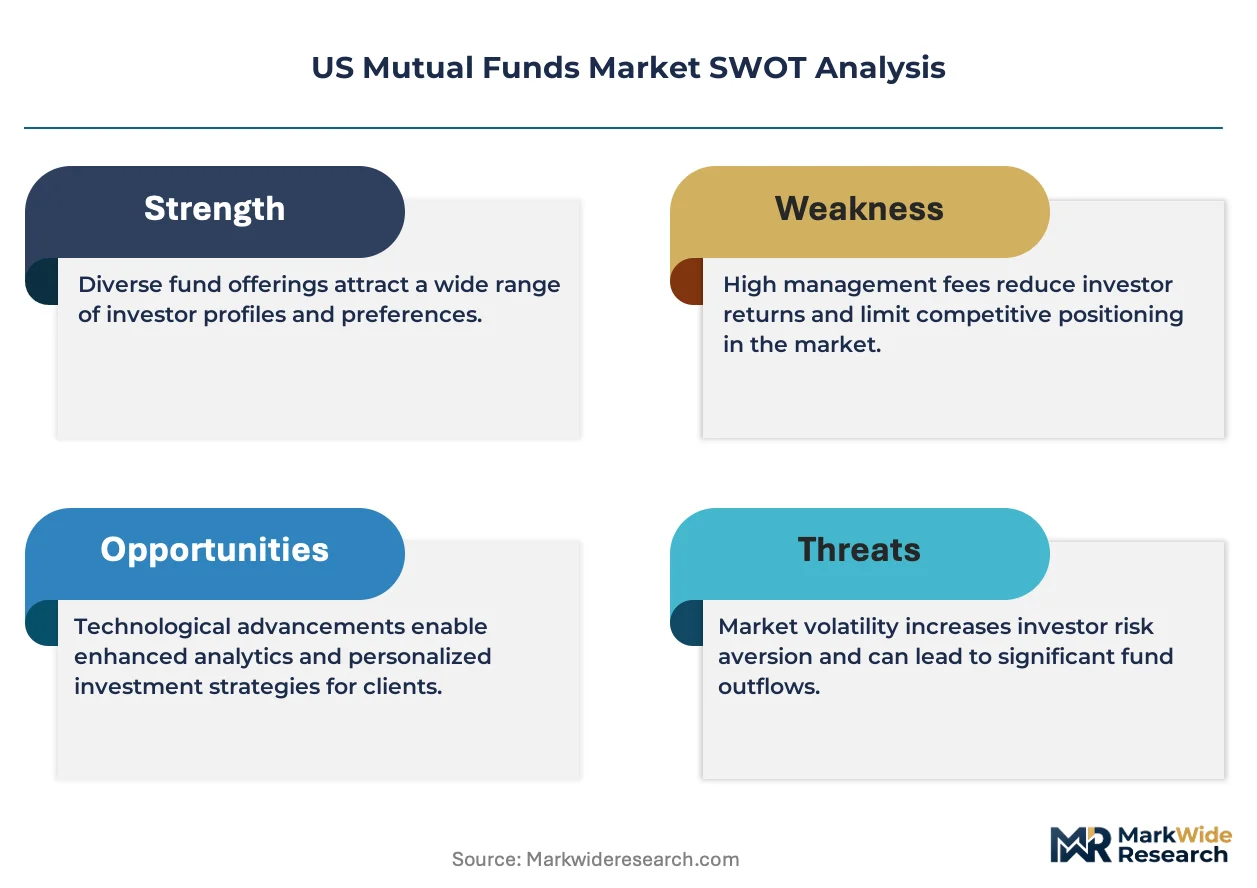
The US mutual funds market represents a late-cycle quality story as plan sponsors systematically rotate toward institutional share classes with embedded fiduciary compliance and transparent fee structures.
For Market Incumbents: Anchor defensive positioning through proprietary target-date glide path technology and captive distribution relationships with retirement plan recordkeepers. Consolidate fragmented back-office infrastructure to realize expense ratio synergies from merger activity. The threat of direct indexing fragmentation demands investment in unified managed account platforms that blend mutual funds with tax-loss harvesting capabilities. For New Entrants and Emerging Players: Begin with white-space capture in Silicon Valley technology sector retirement systems seeking customized equity exposure for participant cohorts with concentrated employer stock positions. The most penetrable segment lies in AI-driven risk analytics for glide path calibration. A go-to-market angle through advisor platform APIs enables rapid integration without proprietary distribution buildout. For Investors and Strategic Acquirers: Private equity sponsors with financial services vertical expertise are the most active acquirer in this space, targeting active equity complexes with concentrated key-person risk and unrealized expense ratio synergies. Long-term viability favors managers with scale-negotiated institutional relationships and technology-enabled retail platforms. The signal to watch is SEC swing pricing adoption velocity as a proxy for operational infrastructure readiness.| Strategic Initiative | Industry Significance |
|---|---|
| ETF-to-Mutual-Fund Conversion Infrastructure | Tax-efficient share class structures capture institutional flows seeking operational flexibility between exchange-traded and open-end vehicles. |
| Unified Managed Account Platform Integration | Single-dashboard technology enables advisors to blend mutual funds with direct indexing and alternative vehicles for high-net-worth clients. |
| Swing Pricing Adoption | Early implementation of SEC liquidity risk management amendments creates first-mover advantages in bond fund redemption handling. |
| Target-Date Glide Path Customization | AI-driven risk analytics for technology sector retirement systems with concentrated employer stock exposure differentiates proprietary offerings. |
| Revenue-Sharing Arrangement Restructuring | Transparent fee disclosure compliance with SEC modernization rules preserves broker-dealer distribution relationships under compressed margin structures. |
Research Methodology
Direct dialogue with portfolio managers, retirement plan sponsors, broker-dealer platform heads, and SEC regulatory affairs specialists grounded qualitative insights for this analysis. Secondary validation drew from SEC Form N-1A filings, FINRA regulatory notices, Department of Labor ERISA guidance documents, and investment company industry association reports. Bottom-up and top-down triangulation cross-checked asset flow data against expense ratio compression trends.
Top-down modeling anchored aggregate market size projections while bottom-up segmentation analysis validated fund type, investment strategy, and distribution channel splits across the projection horizon. Modeled dimensions included active versus passive management mandates, institutional versus retail client segments, and direct versus intermediary distribution channels. CAGRs were derived from historical flow velocity patterns adjusted for regulatory intervention effects and technology displacement curves.
Several conditions sit outside the modeled scope, including extreme interest rate volatility scenarios, unanticipated SEC rulemaking delays, and systemic redemption events in fixed-income funds. Forecasts reflect assumptions about fiduciary framework stability and technology adoption curves. Material deviation in swing pricing implementation timelines or direct indexing penetration rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Portfolio Management and Asset Allocation
Balanced Funds Market
Portfolio Management and Asset Allocation
UK Mutual Funds Market
Portfolio Management and Asset Allocation
Global Project Portfolio Management (PPM) Market
Portfolio Management and Asset Allocation
Energy Portfolio Management Market
Portfolio Management and Asset Allocation
Portfolio Analytics Market
Portfolio Management and Asset Allocation
Portfolio Management Software Market
Portfolio Management and Asset Allocation
Corporate Performance Management Market
Portfolio Management and Asset Allocation
Germany Mutual Funds Market
Portfolio Management and Asset Allocation
United States Project Portfolio Management Market