
 India Modular Kitchen Market | 2026-2036
India Modular Kitchen Market Size, Share, and Industry Trends Forecast 2026-2036
India Modular Kitchen Market Foresight
Smart manufacturing integration is fragmenting production workflows across India's modular kitchen supply chain. Hafele India Private Limited leverages German engineering protocols to sustain premium hardware positioning. Godrej Interio anchors mass-market penetration through its nationwide dealer network. Livspace competes on technology-led design visualization tools that compress project timelines.
A modular kitchen comprises prefabricated cabinet units, countertops, and storage systems engineered from moisture-resistant plywood, MDF, or particle board with laminated or acrylic finishes, designed for rapid on-site assembly in residential and commercial interiors. The premium and custom product tiers capture disproportionate margin pools as affluent consumers prioritize personalized layouts and imported hardware. Wood and plywood materials dominate structural applications, while MDF gains share in surfacing and shutter fabrication due to uniform density and machining precision.
BIS mandates dimensional stability and emission standards for engineered wood substrates, compelling manufacturers to certify material batches or risk market exclusion. The FSSAI framework governs food-contact surface safety for countertop materials used in commercial kitchen installations. Stakeholders must monitor evolving ESG disclosure obligations under the BRSR framework as institutional capital flows into organized real estate development.
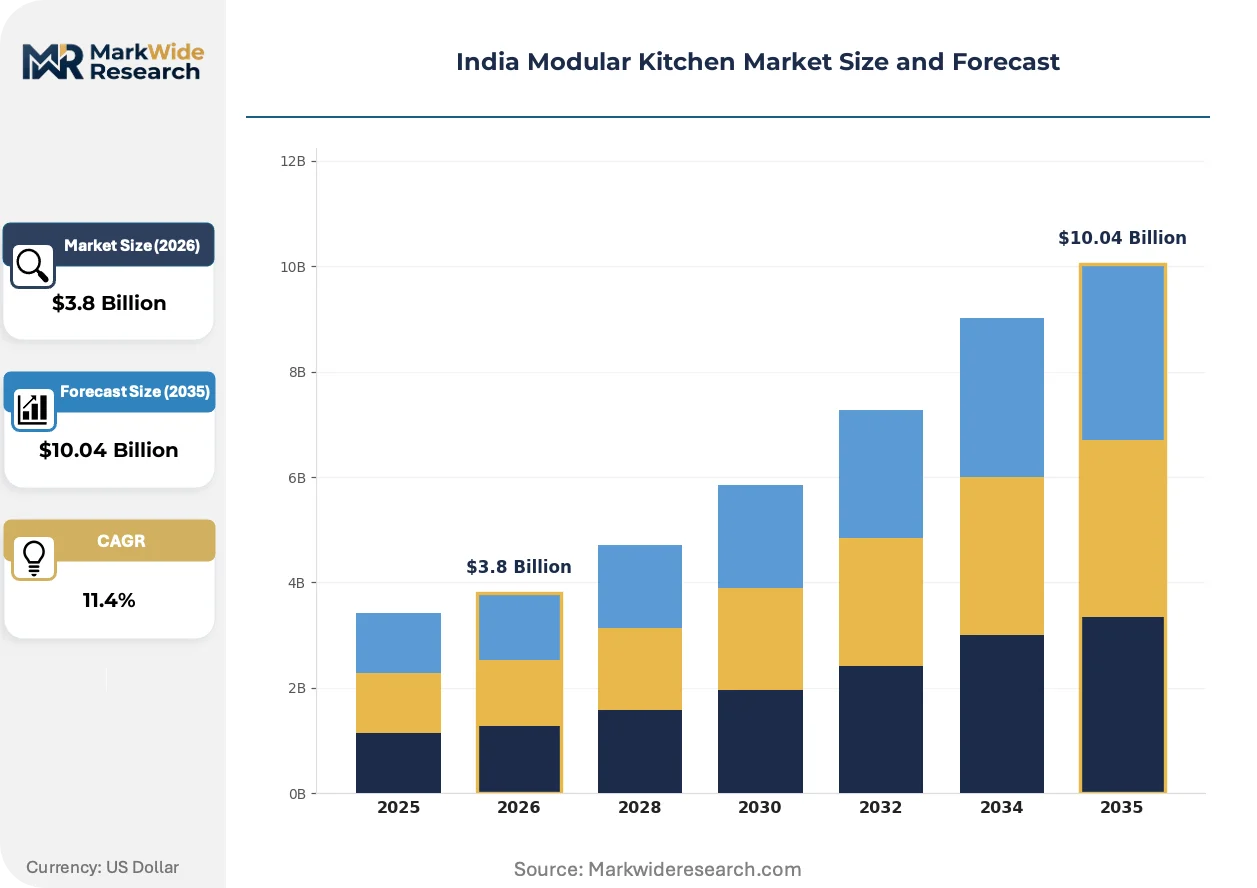
Market Dynamics
BIS certification mandates for engineered wood substrates are forcing material requalification across India's modular kitchen supply chain, compressing vendor consolidation timelines and elevating compliance costs for unorganized fabricators.
Growth Catalysts
- Nuclear family proliferation:Maharashtra, Karnataka, and Delhi NCR record the fastest expansion of compact residential units requiring space-optimized kitchen configurations.
- BIS plywood standards:Mandatory dimensional stability and emission testing under BIS certification protocols is filtering substandard suppliers and rewarding certified manufacturers with institutional project access.
- Gated community construction:Mumbai and Bangalore developers are specifying modular kitchen packages as standard fit-outs in premium residential towers, creating bundled demand channels.
Market Restraints
- Particle board import dependency:Domestic production capacity for moisture-resistant engineered wood remains concentrated among three major substrate suppliers, exposing fabricators to input cost volatility.
- Hardware import concentration:Premium hinge and slide mechanisms rely on German and Italian supply chains, creating foreign exchange exposure and extended lead times.
- Skilled installation labor scarcity:Precision assembly of acrylic-finished shutter systems requires trained technicians, with certification programs lagging market expansion in tier-2 cities.
Strategic Opportunities
- Tier-3 city penetration:Kerala and Tamil Nadu secondary markets show rising aspiration for branded modular kitchens with limited organized competition.
- PLI scheme alignment:India's production-linked incentive framework for furniture and wood products offers capital subsidy pathways for automated panel processing investments.
- Commercial kitchen vertical:FSSAI compliance requirements for food-contact surfaces in hotels and cloud kitchens create certified countertop specification demand distinct from residential segments.
Industry Challenges
- Project timeline compression:Design-to-installation cycles have shortened from twelve weeks to six weeks, straining coordination between architects, fabricators, and site contractors.
- Material batch certification delays:BIS testing backlogs for imported MDF and plywood lots extend inventory holding periods and disrupt just-in-time production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Modular Kitchen Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic, Premium, Luxury, Custom Material: Wood, Particle Board, MDF, Plywood Design Style: Contemporary, Traditional, Modern, Rustic End User: Residential, Commercial, Hospitality, Retail |
| Companies Covered | Sleek International Private Limited, Spacewood, Hafele India Private Limited, Livspace, Kutchina, Godrej & Boyce Manufacturing Company Limited, Godrej Interio, IFB Industries Ltd., Hettich India Private Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Modular Kitchen Market Shifts & Advancements
Digital design visualization and automated manufacturing are collapsing traditional friction points between specification and installation. Material science advances are redefining durability expectations. Regulatory disclosure obligations are reshaping supplier qualification protocols.
Acrylic solid surface countertops with seamless jointing and repairability are rendering obsolete natural stone alternatives in premium residential projects. Mumbai and Bangalore developers specify these surfaces for warranty-backed durability in rental and resale inventory. The shift compresses supplier margins on imported granite while elevating domestic fabrication capabilities.
BIS emission standards for formaldehyde in particle board and MDF are tightening substrate sourcing requirements. Manufacturers must now certify every material batch or face exclusion from organized real estate procurement channels. Karnataka-based fabricators have responded fastest, building in-house testing protocols ahead of enforcement deadlines.
Apartment buyers increasingly demand fixed-price turnkey contracts with defined completion guarantees rather than cost-plus arrangements with separate material and labor components. This preference shift disrupts traditional dealer-fabricator relationships in Delhi NCR, where bundled service providers capture project flow previously fragmented across multiple vendors. The model concentrates risk with integrators but accelerates decision timelines for time-constrained nuclear families.
India Modular Kitchen Market Segmentation
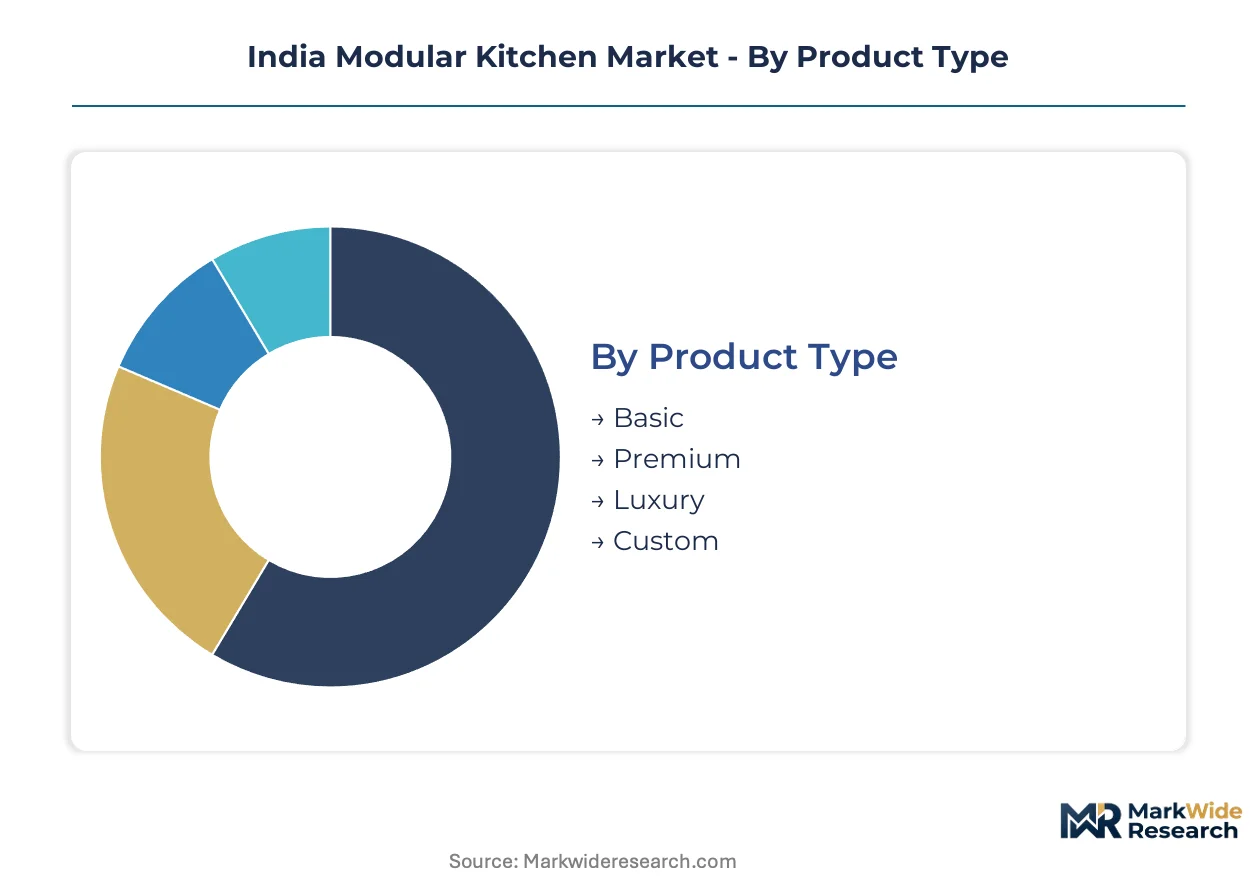
India's modular kitchen market fragments across four distinct axes, each carrying different service intensity requirements. Post-installation support demands vary sharply between mass-market particle board installations and premium acrylic-finished custom kitchens, reshaping how fabricators organize their field service networks and warranty commitments.
Product Type:
After-sales service intensity climbs steeply from basic to custom tiers, with luxury and custom segments requiring dedicated maintenance contracts and periodic refurbishment cycles that basic installations rarely trigger.
- Premium:Engineered with moisture-resistant plywood substrates and branded hardware systems, this tier targets nuclear families in Mumbai and Bangalore gated communities. BIS-certified material sourcing and standardized module dimensions enable scalable installation protocols with defined warranty terms.
- Custom:Personalized layouts incorporate imported Italian hinges, acrylic solid surfaces, and site-specific dimensional adaptations. Delhi NCR developers specify these for premium residential towers, demanding turnkey contracts with completion guarantees and post-installation service retainers.
- Basic:Laminated particle board configurations serve cost-conscious buyers in tier-2 cities with limited service infrastructure.
- Luxury:Imported stone countertops and German-engineered storage systems command extended lead times and specialized installation labor.
Premium holds the largest share; momentum sits with Custom.
Material:
Cost tier stratification across substrate categories determines margin capture and procurement risk exposure for fabricators.
- Plywood:Structural-grade moisture-resistant variants dominate cabinet carcass construction under BIS dimensional stability mandates. Maharashtra fabricators source certified batches from Kerala and Karnataka suppliers, absorbing testing backlog delays to maintain institutional project access.
- MDF:Uniform density enables precision machining for shutter fabrication and surfacing applications. Bangalore manufacturers favor MDF for acrylic-finished fronts in premium residential specifications, though formaldehyde emission standards under BIS protocols constrain supplier qualification.
- Wood:Solid hardwood framing persists in luxury custom work for structural durability and repairability.
- Particle Board:Domestic production concentration among three major suppliers exposes fabricators to input cost volatility and import dependency.
Plywood dominates volume; MDF gains share fastest in surfacing applications.
Design Style:
Application context drives style selection, with commercial and hospitality segments imposing distinct aesthetic and durability requirements.
- Contemporary:Clean lines and handle-less shutter systems align with Mumbai and Bangalore apartment buyer preferences in premium towers. Acrylic finishes and integrated appliances characterize this segment, with FSSAI-compliant surfaces specified for commercial kitchen derivatives.
- Modern:Minimalist hardware and neutral palettes serve rental inventory developers seeking warranty-backed durability and broad resale appeal.
- Traditional:Ornate detailing and wood-grain laminates persist in Kerala and Tamil Nadu secondary markets with limited organized competition.
- Rustic:Distressed finishes and visible grain patterns occupy niche positioning in boutique hospitality projects.
Contemporary commands institutional specification; Modern climbs fastest in developer bundled packages.
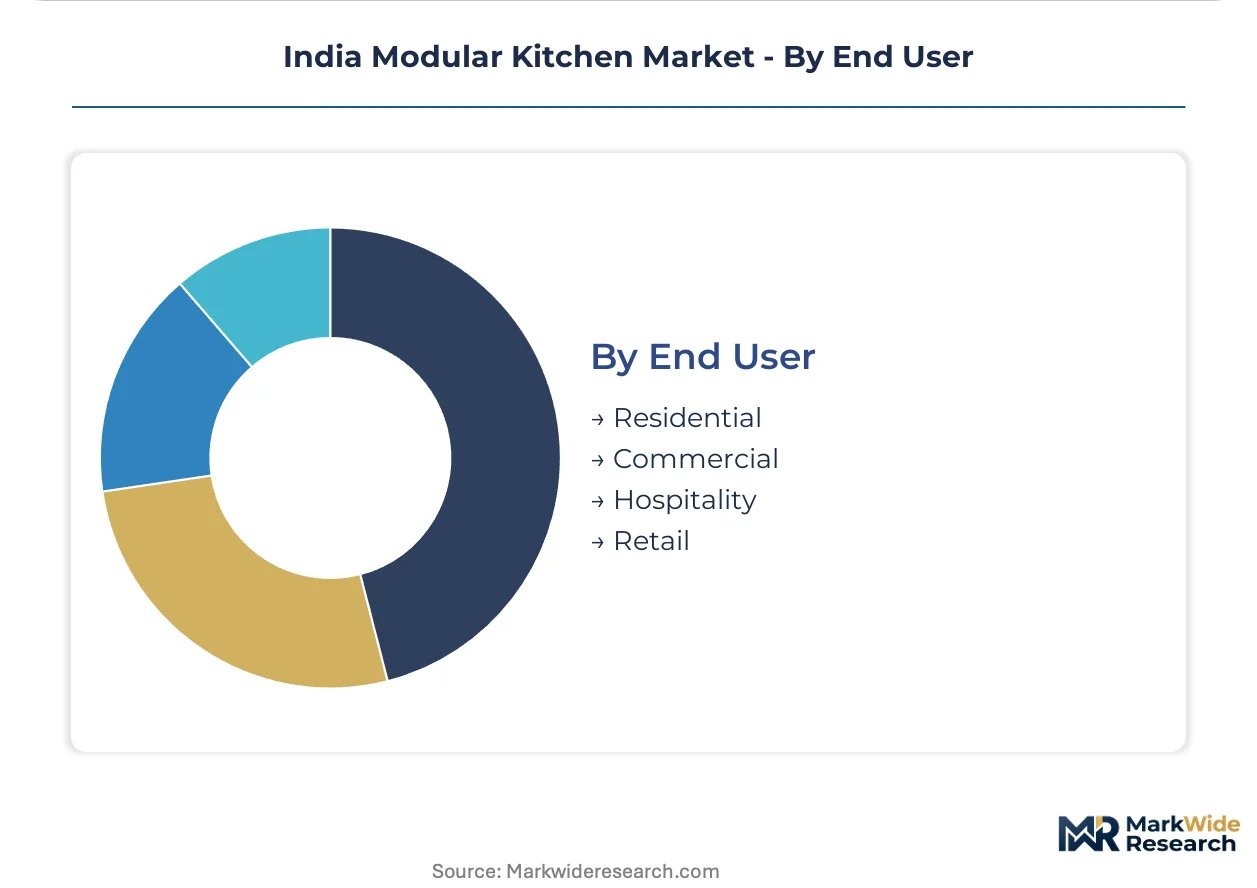
End User:
Customer type segmentation separates residential volume from commercial compliance complexity, with distinct regulatory frameworks governing each.
- Residential:Nuclear family proliferation in Delhi NCR, Maharashtra, and Karnataka drives demand for space-optimized configurations. Fixed-price turnkey contracts displace cost-plus arrangements, concentrating project risk with bundled service providers.
- Commercial:FSSAI food-contact surface requirements for hotels and cloud kitchens create certified countertop specification demand distinct from residential segments. Compliance documentation and batch traceability elevate procurement protocols.
- Hospitality:High-cycle durability requirements and standardized room configurations favor modular installation for rapid refurbishment turnover.
- Retail:Display kitchen environments in appliance showrooms and builder experience centers generate specification influence rather than direct volume.
Residential absorbs the majority of unit volume; Commercial shows the steepest expansion trajectory on compliance-driven replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hardware exports flow into Indian fabricator supply chains, while domestic production clusters concentrate in western and southern states where real estate development accelerates fastest.
Maharashtra
Mumbai's gated residential towers generate bundled modular kitchen specifications from developers seeking standardized fit-outs. BIS certification mandates for plywood substrates filter supplier qualification, rewarding certified fabricators with institutional project access. Pune's manufacturing corridor hosts moisture-resistant panel processing facilities serving western India demand.
Karnataka
Bangalore's nuclear family proliferation drives space-optimized kitchen configurations in premium apartment stock. Karnataka-based fabricators pioneered in-house BIS testing protocols ahead of enforcement deadlines, securing supply chain advantages. The state's engineered wood substrate suppliers feed regional fabrication clusters with certified material batches.
Delhi NCR
Compact residential unit expansion across Gurgaon and Noida creates demand for turnkey installation contracts with completion guarantees. FSSAI compliance requirements for commercial kitchen surfaces in hotels and cloud kitchens elevate procurement documentation standards. Noida fabrication parks concentrate acrylic-finished shutter production for northern markets.
Tamil Nadu
Chennai's secondary market aspiration for branded kitchens outpaces organized competition presence. PLI scheme incentives for furniture manufacturing attract automated panel processing investments to the state's industrial corridors. Coimbatore's woodworking machinery base supports regional fabrication capacity expansion.
Kerala
High residential ownership rates and remittance-funded renovation cycles sustain custom kitchen demand in Kochi and Thiruvananthapuram. Traditional wood-grain preferences persist alongside contemporary design adoption in premium segments. The state's plywood supplier network feeds fabrication clusters across the southwestern coast.
India Modular Kitchen Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. Organized fabricators with nationwide dealer networks anchor mass-market penetration, while German-engineered hardware specialists occupy premium positioning. Three archetypes dominate: integrated real estate service providers, component-specialist importers, and scale-driven domestic manufacturers. Consolidation pressures favor M&A activity among regional fabricators, while technology licensing agreements accelerate design visualization capability diffusion.
Among German-origin hardware specialists, Hafele India Private Limited exemplifies premium-tier positioning through engineering protocol adherence. Domestic scale players Godrej Interio and Livspace occupy distinct competitive vectors—Godrej Interio anchors mass-market penetration through extensive dealer infrastructure, while Livspace represents technology-led service integration with design visualization tools. These three entities illustrate the market's structural segmentation between hardware-centric import dependence and domestic service bundling.
| Leading Market Players |
|---|
| Sleek International Private Limited |
| Spacewood |
| Hafele India Private Limited |
| Livspace |
| Kutchina |
| Godrej & Boyce Manufacturing Company Limited |
| Godrej Interio |
| IFB Industries Ltd. |
| Hettich India Private Limited |
| Others |
Supply & Pricing Matrix
The JNPT-Mundra freight corridor's container cost dynamics amplify supply concentration effects across India's modular kitchen value chain, with BIS-certified plywood batches from Kerala and Karnataka commanding premium indexation while unorganized fabricators absorb margin compression from extended testing backlogs.
Pricing Analysis
Cost-plus contracts with plywood price indexation dominate Delhi NCR and Mumbai developer specifications, though turnkey fixed-price arrangements are displacing them in premium gated communities. Price differentiation rests on BIS certification tier and hardware import origin, with German-engineered hinge systems sustaining 40-60% premiums over domestic alternatives. Cost compression in the basic particle board tier intensifies because domestic production capacity concentrates among three suppliers. Nuclear families in tier-2 cities exhibit highest price sensitivity, while commercial kitchen operators prioritize FSSAI-compliant surface warranties over upfront outlays.
Supply Chain Analysis
Supplier-financing facilities from Karnataka-based engineered wood producers extend 90-day payment terms to certified fabricators, tightening vendor consolidation timelines. Raw material dependencies center on moisture-resistant plywood from Kerala, formaldehyde-tested MDF from domestic BIS-approved facilities, and Italian hinge mechanisms routed through Mumbai import channels. Single-source vulnerability concentrates in German hardware supply chains, with euro-denominated procurement exposing fabricators to foreign exchange volatility. Distribution runs through regional fabrication clusters in Pune, Bangalore, and Noida that feed localized installation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trained acrylic-finish technicians represent the critical capability gap constraining tier-2 and tier-3 market expansion, with certification program throughput lagging project pipeline growth by an estimated 18-24 months.
For Market Incumbents: Entrench BIS certification advantages by building in-house testing protocols ahead of enforcement deadline acceleration, mirroring Karnataka fabricator strategies. Secure captive supply arrangements with Kerala plywood suppliers to defend margin position against import cost volatility. Channel control through exclusive dealer tiering in Maharashtra and Delhi NCR creates switching costs for nuclear family buyers. For New Entrants and Emerging Players: Establish a beachhead in Tamil Nadu and Kerala tier-3 cities where branded kitchen aspiration outpaces organized competition presence. Target commercial kitchen verticals with FSSAI-compliant countertop certification as the most penetrable segment, leveraging regulatory documentation capabilities that residential fabricators underinvest in. Pursue PLI scheme capital subsidy pathways for automated panel processing to compress cost structures against unorganized rivals. For Investors and Strategic Acquirers: Regional fabricators with captive BIS testing infrastructure and established turnkey installation capabilities represent the most defensible acquisition archetype for portfolio exposure. Long-term viability hinges on backward integration into moisture-resistant substrate production or forward integration into maintenance contract recurring revenue. Monitor BIS enforcement acceleration timelines as the primary inflection signal for certified versus uncertified player valuation divergence.| Strategic Initiative | Industry Significance |
|---|---|
| In-House BIS Testing Infrastructure | Karnataka fabricators leveraged early protocol adoption to secure institutional project access ahead of competitors. |
| Turnkey Installation Contract Bundling | Delhi NCR integrators concentrate project risk while accelerating decision timelines for time-constrained nuclear families. |
| PLI Scheme Automated Panel Investment | Tamil Nadu industrial corridors attract capital subsidy pathways that compress unit economics against unorganized fabricators. |
| Commercial Kitchen FSSAI Certification | Hotels and cloud kitchens create distinct specification demand with elevated procurement documentation requirements. |
| German Hardware Supply Partnership | Hafele India sustains premium positioning through engineering protocol adherence and extended warranty backing. |
Research Methodology
Operator-level perspectives from modular kitchen fabricators, real estate developer procurement heads, BIS certification laboratory directors, and acrylic-finish installation technicians anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against BIS notification records, FSSAI food-contact surface guidelines, PLI scheme administrative filings, and western India customs data for hardware imports. Bottom-up unit shipment estimates from regional fabrication clusters triangulated against top-down real estate completion data across Maharashtra, Karnataka, and Delhi NCR.
Scenario-bracketing around BIS enforcement acceleration timelines and PLI scheme uptake rates structured the analytical framework across the analysis window. Segmentation dimensions modeled include product tier, substrate material grade, design style application context, and end-user regulatory complexity. CAGRs derived from logistic diffusion curves fitted to gated community construction pipelines and nuclear household formation rates, with cross-validation against plywood and MDF consumption trajectories from certified supplier disclosures.
Sensitivities concentrate around BIS testing backlog resolution speed, euro-rupee exchange rate volatility for hardware imports, and tier-3 city income elasticity assumptions. Forecasts reflect documented assumptions regarding enforcement consistency and subsidy program continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
Asia-Pacific Kitchen Furniture Market
Kitchen and Dining
Opalware Dinnerware and Crockery Market
Kitchen and Dining
North America Countertop Market
Kitchen and Dining
Stove Cover Market
Kitchen and Dining
Kitchen Islands and Carts Market
Kitchen and Dining
India Kitchen Furniture Market
Kitchen and Dining
Kitchen Cabinets Market
Kitchen and Dining
Modular Kitchen Market
Kitchen and Dining
Europe Kitchen Furniture Market
Kitchen and Dining
Banquet Carts and Heated Cabinets Market
Kitchen and Dining
Range Hood and Cooktop Market
Kitchen and Dining
Back Table and Cart Covers Market
Kitchen and Dining
Built-In Cabinet Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
North America Tabletop Kitchen Products Market