
 Asia-Pacific Kitchen Furniture Market | 2026-2036
Asia-Pacific Kitchen Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Kitchen Furniture Market Outlook
The premium and commodity tiers in Asia-Pacific kitchen furniture are restructuring along divergent supply chain logics, with high-end systems integrating smart storage and custom millwork while mass-market lines compete on laminate-wrapped MDF throughput and modular assembly speed. OPPEIN leverages its Guangzhou manufacturing base to sustain pan-Asian distribution through company-owned showrooms and franchise networks. GoldenHome differentiates via vertical control over quartz countertop fabrication, anchoring margin capture in the stone-to-installation value chain. Lesso Group Holdings Ltd. dominates plastic and composite building materials channels, extending its plumbing and cabinetry portfolios through shared contractor relationships across Southeast Asia.
Asia-Pacific kitchen furniture encompasses fixed and semi-fixed storage, work surface, and food preparation installations engineered for residential and commercial food service environments, typically fabricated from particleboard substrates with thermally fused melamine faces, solid timber frames, or cold-rolled stainless steel carcasses rated for moisture resistance and load-bearing performance. The primary commercial purpose centers on optimizing spatial workflow, sanitation compliance, and durable utility in high-frequency cooking environments. Cabinets and countertops together occupy the core revenue position, with island configurations representing the fastest-growing format as open-plan living penetrates middle-class housing in India and Southeast Asia. Wood and MDF materials lead volume, though stainless steel gains traction in hospitality end-use where India's FSSAI hygiene codes and China's GB standards for commercial kitchen equipment mandate non-porous, corrosion-resistant surfaces.
China's SAMR enforces GB standards for formaldehyde emissions in wood-based panels, directly shaping MDF and particleboard sourcing decisions for manufacturers serving the domestic market. India's BIS operates mandatory certification for plywood and blockboard under IS 303 and IS 710, creating compliance barriers for unqualified imports while strengthening domestic engineered wood supply chains. Japan's METI building energy codes and JIS standards for residential equipment indirectly influence kitchen system specifications through broader housing efficiency mandates. Stakeholders must monitor how divergent national labeling and emission regimes affect cross-border component sourcing and finished product market access across the region.
Market Dynamics
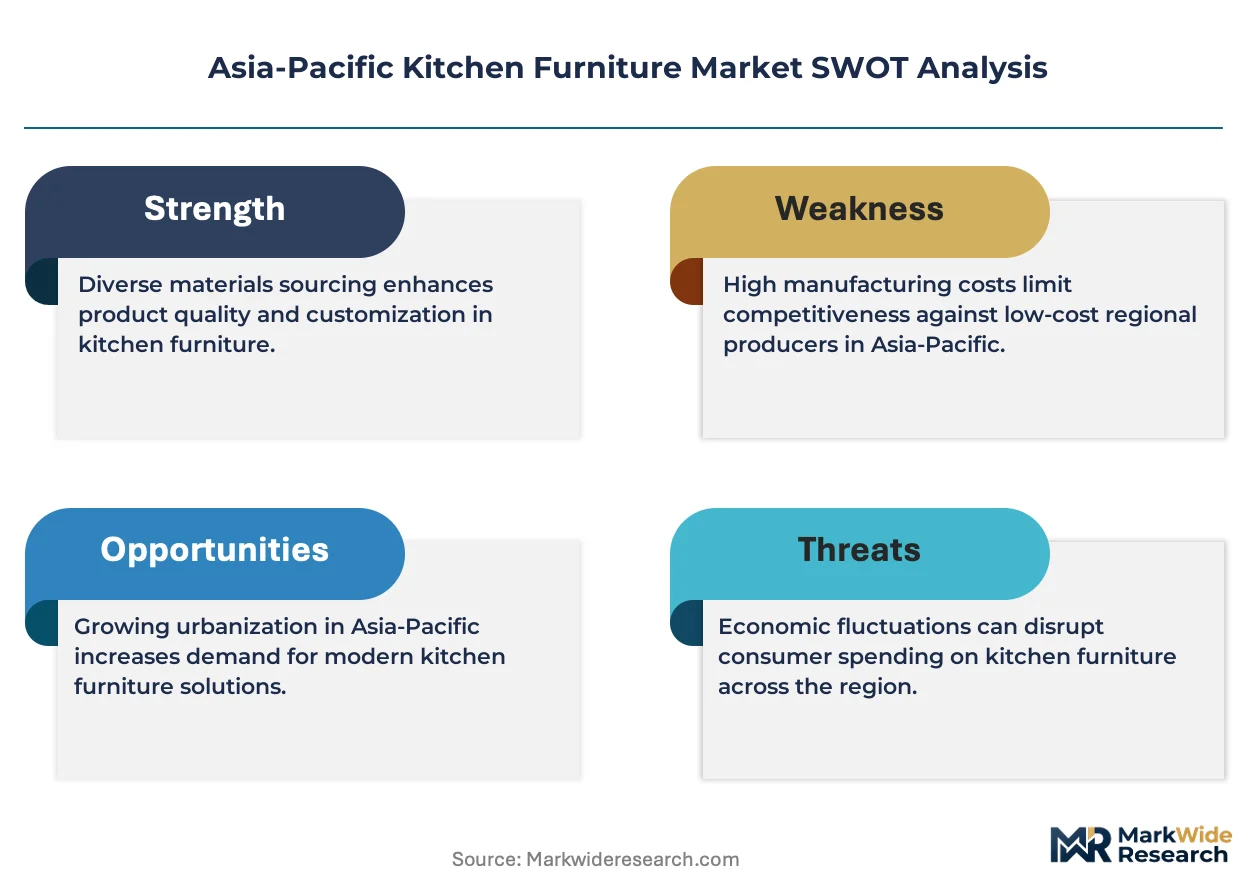
China's SAMR enforcement of GB standards for formaldehyde emissions in wood-based panels is forcing MDF and particleboard sourcing decisions across the entire Asia-Pacific supply chain, compressing margins for manufacturers unable to certify compliant substrates.
Growth Catalysts
- India's BIS Certification Mandate:Mandatory IS 303 and IS 710 certification for plywood and blockboard is elevating quality thresholds and strengthening domestic engineered wood supply chains against unqualified imports.
- Vietnam's Export Manufacturing Corridors:Concentrated demand near Ho Chi Minh City and Binh Duong province is anchoring regional production capacity for cross-border kitchen system fulfillment.
- Island Configurations:Open-plan living penetration across middle-class housing in India and Southeast Asia is accelerating format diversification beyond traditional galley and L-shaped layouts.
Market Restraints
- Formaldehyde Emission Compliance Costs:China's GB standards and Japan's JIS A 1460 requirements impose dual testing burdens on manufacturers serving multiple national markets.
- Quartz Substrate Concentration:Vertical control over engineered stone fabrication by dominant regional players limits margin capture opportunities for mid-tier cabinet specialists.
- Stainless Steel Substitution Pressure:India's FSSAI hygiene codes and China's GB standards for commercial food service are redirecting hospitality procurement toward metal carcass systems.
Strategic Opportunities
- Indonesia's Underpenetrated Secondary Cities:Surabaya and Bandung residential construction is outpacing organized kitchen furniture distribution, creating first-mover whitespace for modular system providers.
- Smart Storage Convergence:Sensor-activated lift mechanisms and LED-integrated shelving are converging with traditional millwork to command premium positioning in urban China and South Korea.
- Thailand's BOI Investment Incentives:Board of Investment privileges for advanced material processing are attracting regional headquarters for laminate and thermofoil wrapping operations.
Industry Challenges
- Skilled Installation Labor Scarcity:Precision countertop templating and cabinet leveling require certified technicians that remain concentrated in Shanghai, Guangzhou, and Mumbai metropolitan clusters.
- Multi-Jurisdiction Certification Timelines:Simultaneous BIS, GB, and JIS compliance testing extends product launch cycles by 8-14 months for pan-Asian product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Kitchen Furniture Market |
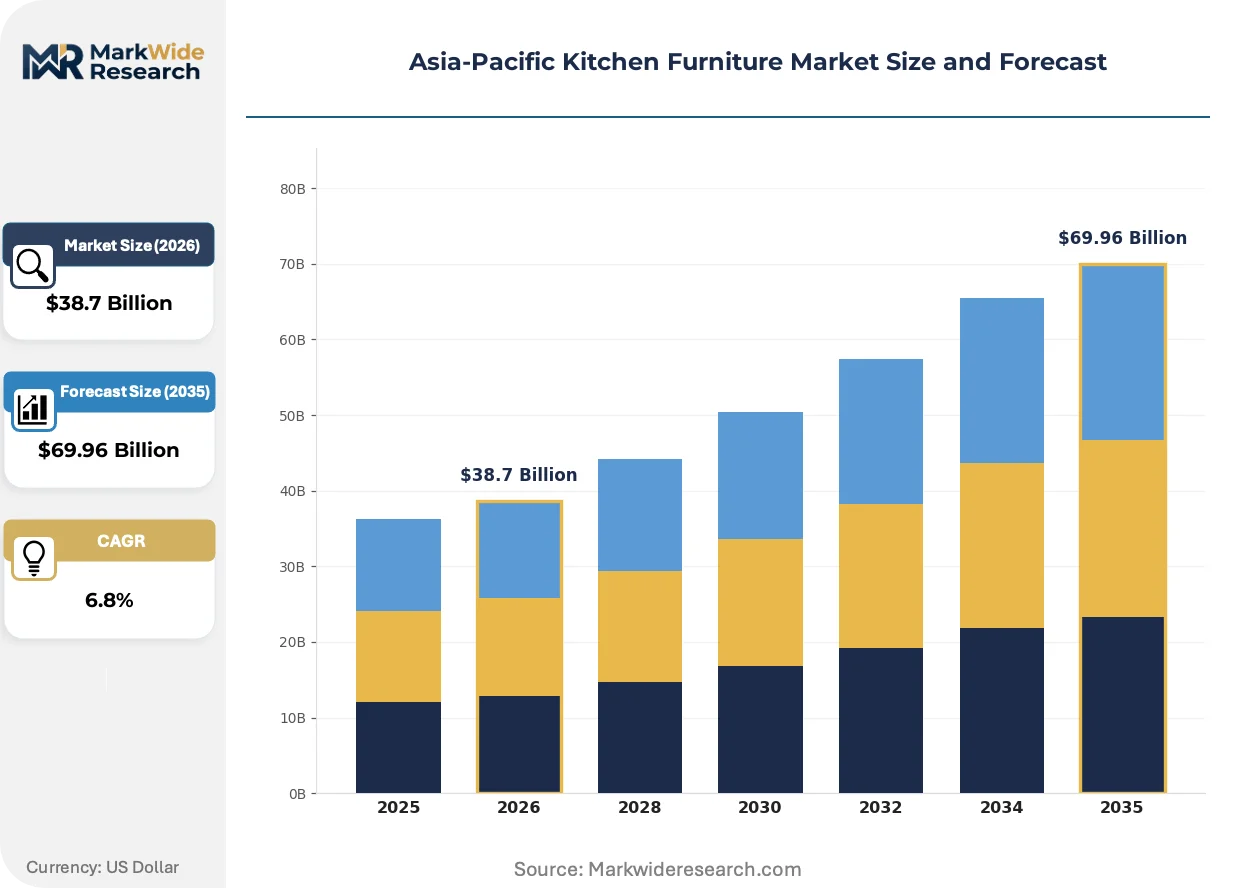
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Cabinets, Countertops, Islands, Storage Solutions Material: Wood, MDF, Stainless Steel, Laminate Style: Modern, Traditional, Rustic, Minimalist End User: Residential, Hospitality, Commercial, Retail |
| Companies Covered | Foshan Kitchen Cabinet Co., Ltd., Lesso Group Holdings Ltd., OPPEIN, GoldenHome, ZBOM Cabinets Co., Ltd., Godrej and Boyce, Vatti Kitchen Solutions Co., Ltd., QuanU, Ikea, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Kitchen Furniture Market Strategic Shifts
Digital fabrication tools and connected hardware are compressing the traditional separation between custom millwork and mass-manufactured kitchen systems across Asia-Pacific residential construction.
Thermally fused melamine faces with anti-fingerprint surface treatments are converging with particleboard substrates engineered for moisture resistance, enabling mid-market manufacturers in China's Zhejiang and Jiangsu provinces to offer premium-grade durability at laminate price points. Developers in Vietnam's Vinhomes and Gamuda Land projects are specifying these hybrid surfaces for high-turnover condominium fit-outs.
Japan's METI building energy codes are tightening thermal performance requirements for residential equipment, indirectly mandating improved cabinet sealing and insulation adjacent to HVAC-integrated kitchen zones. Housing manufacturers Sekisui House and Daiwa House are revising kitchen system specifications to maintain compliance, affecting component sourcing across their Southeast Asian supplier networks.
Direct-to-developer contracting is displacing traditional distributor-showroom channels for bulk residential procurement in India's Bengaluru and Hyderabad markets. Brigade Group and Sobha Limited are negotiating master supply agreements that bundle kitchen installation with interior fit-out contracts, compressing the role of standalone retail franchise networks in premium housing segments.
Asia-Pacific Kitchen Furniture Market Segmentation
Kitchen furniture procurement in Asia-Pacific diverges sharply by installation type, material specification, and end-use environment. Buyers prioritize moisture resistance and load-bearing performance in humid climates, while open-plan living trends are reshaping format preferences across India's metropolitan corridors and Vietnam's export manufacturing zones.
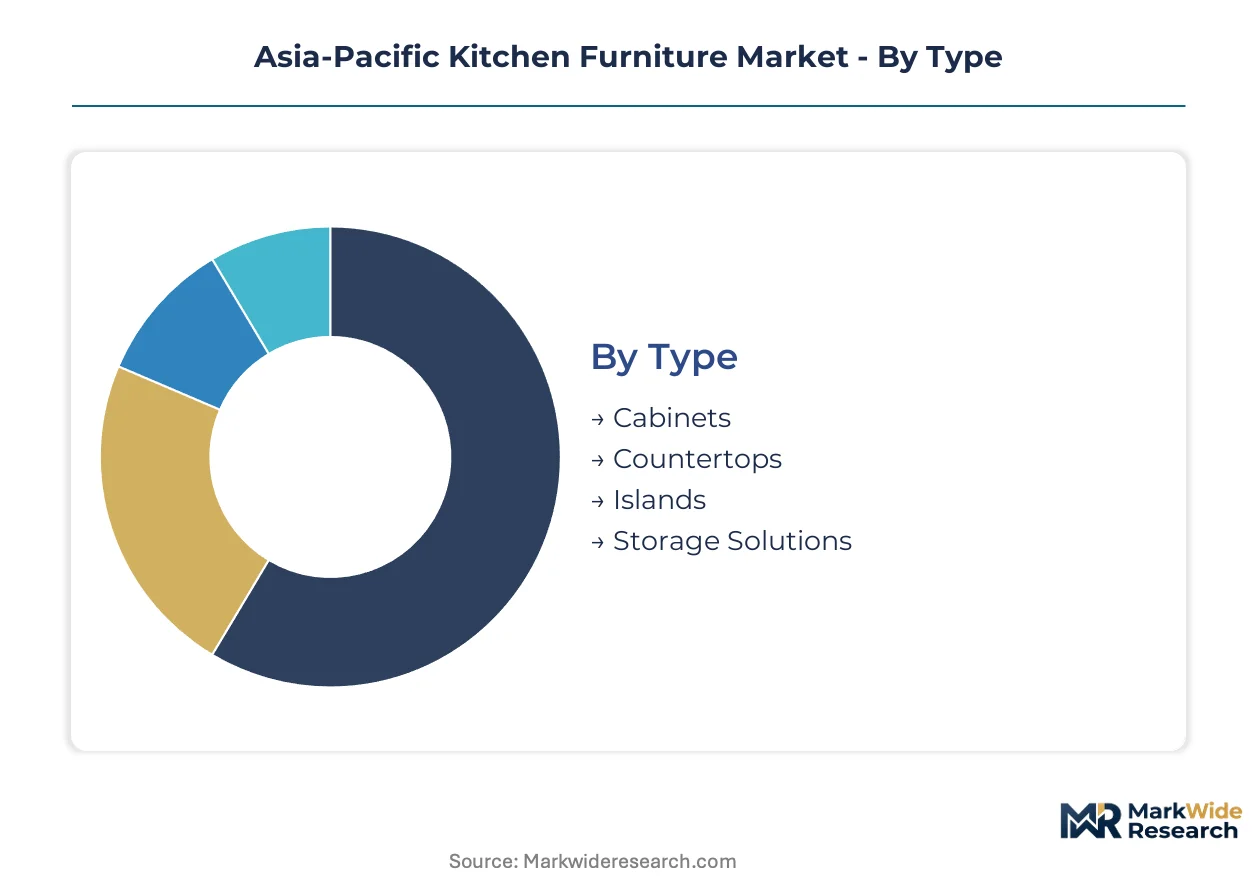
Type:
Format selection directly determines spatial workflow efficiency and installation complexity for developers and homeowners.
- Cabinets:Base and wall-mounted storage systems fabricated from particleboard with thermally fused melamine faces dominate volume. China's tier-two cities are restructuring procurement patterns as urban residential construction accelerates in Chengdu and Xi'an.
- Countertops:Work surfaces in engineered quartz, solid surface, or post-formed laminate anchor kitchen system margins. GoldenHome's vertical control over quartz fabrication in Xiamen limits margin capture opportunities for mid-tier specialists lacking stone-to-installation value chain integration.
- Islands:Freestanding central workstations are climbing the fastest as open-plan living penetrates middle-class housing in Bengaluru and Jakarta.
- Storage Solutions:Pull-out pantries, corner carousels, and drawer organizers complete system functionality. Sensor-activated lift mechanisms from South Korean suppliers are commanding premium positioning in Seoul and Shanghai.
Cabinets lead on scale; islands lead on momentum.
Material:
Substrate choice balances cost position against regulatory compliance and climate durability.
- Wood:Solid timber frames and veneer-wrapped panels serve premium residential segments. India's BIS IS 303 and IS 710 certification mandates for plywood are elevating quality thresholds and strengthening domestic engineered wood supply chains.
- MDF:Medium-density fiberboard with laminated or painted finishes offers cost-efficient workability. China's SAMR enforcement of GB formaldehyde emission standards is compressing margins for manufacturers unable to certify compliant substrates.
- Stainless Steel:Cold-rolled carcasses rated for corrosion resistance serve commercial food service. India's FSSAI hygiene codes and China's GB standards are redirecting hospitality procurement toward non-porous metal systems.
- Laminate:Thermally fused melamine faces on particleboard substrates enable mid-market durability at accessible price points. Zhejiang and Jiangsu province manufacturers are supplying Vietnam's Vinhomes and Gamuda Land condominium fit-outs.
MDF leads on volume; stainless steel leads on regulatory tailwinds.
Style:
Aesthetic positioning segments distribution channels and pricing architecture across residential sub-markets.
- Modern:Clean lines, handle-less cabinetry, and integrated appliances align with urban condominium specifications. OPPEIN's Guangzhou manufacturing base sustains pan-Asian distribution through company-owned showrooms targeting this segment.
- Traditional:Ornate detailing, raised panel doors, and decorative hardware persist in heritage property renovations and established suburban districts.
- Rustic:Distressed finishes, visible grain patterns, and farmhouse-inspired silhouettes serve vacation property and boutique hospitality installations.
- Minimalist:Extreme reduction of visual elements and concealed storage systems are gaining share fastest in Tokyo and Singapore luxury residential.
Modern styling commands the broadest addressable market; minimalist configurations are expanding most quickly in premium tiers.
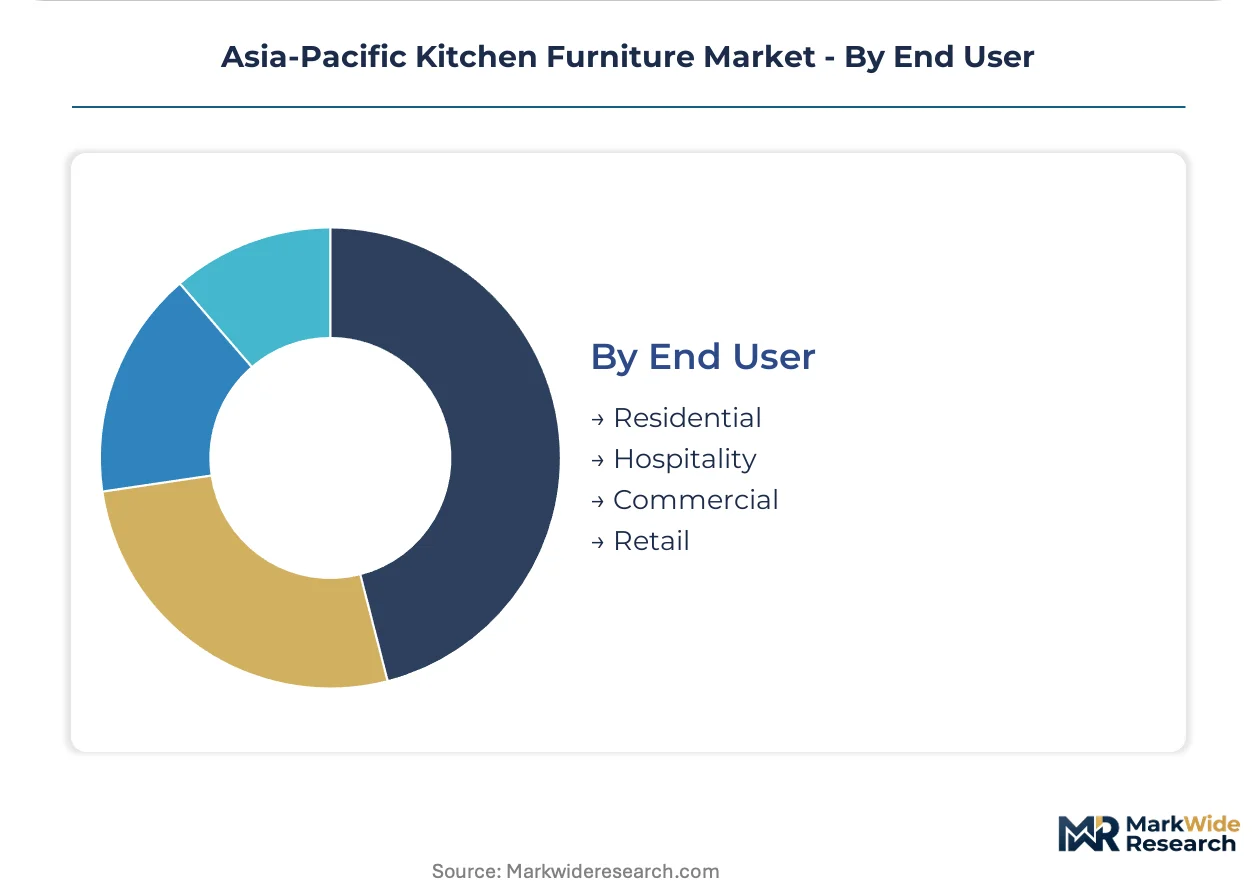
End User:
Application environment dictates performance specifications, certification requirements, and procurement channel structure.
- Residential:Single-family and multi-family housing installations represent the core revenue position. Direct-to-developer contracting in Bengaluru and Hyderabad is displacing traditional distributor-showroom channels for bulk procurement.
- Hospitality:Hotels, resorts, and serviced apartments require durable, high-turnover specifications. Japan's METI building energy codes are tightening thermal performance requirements for residential-adjacent food service zones.
- Commercial:Corporate cafeterias, institutional kitchens, and food courts demand sanitation compliance and rapid replacement cycles. Lesso Group Holdings extends its plumbing and cabinetry portfolios through shared contractor relationships across Southeast Asia.
- Retail:Showroom displays, demonstration kitchens, and food retail fixtures prioritize visual impact over heavy-use durability.
Residential applications anchor absolute volume; hospitality installations are gaining share fastest on post-pandemic travel recovery and new property development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled installation technicians cluster in Shanghai, Guangzhou, and Mumbai, creating service bottlenecks that constrain market expansion beyond primary metropolitan corridors.
China
Urban residential construction in Chengdu and Xi'an is restructuring procurement patterns for kitchen systems. SAMR enforcement of GB formaldehyde emission standards is compressing margins for manufacturers sourcing non-compliant MDF substrates. Guangzhou's manufacturing base sustains pan-Asian distribution through integrated showroom and franchise networks.
India
Direct-to-developer contracting in Bengaluru and Hyderabad is displacing traditional distributor-showroom channels for bulk residential procurement. BIS mandatory certification under IS 303 and IS 710 for plywood and blockboard elevates quality thresholds against unqualified imports. Maharashtra and Gujarat house expanding engineered wood supply chains serving domestic manufacture.
Vietnam
Export-oriented manufacturing corridors near Ho Chi Minh City and Binh Duong province are anchoring regional production capacity. Vinhomes and Gamuda Land developers specify hybrid thermally fused melamine surfaces for high-turnover condominium fit-outs. The southern manufacturing belt concentrates laminate-wrapped particleboard throughput for cross-border fulfillment.
Japan
METI building energy codes tighten thermal performance requirements for residential equipment, indirectly mandating improved cabinet sealing. Housing manufacturers Sekisui House and Daiwa House revise kitchen system specifications to maintain compliance. The Kanto region maintains precision fabrication capabilities for sensor-activated storage mechanisms.
Indonesia
Residential construction in Surabaya and Bandung outpaces organized kitchen furniture distribution, creating first-mover whitespace. Secondary city developers seek modular system providers capable of rapid installation deployment. The Java corridor presents untapped addressable market for standardized cabinet and countertop bundles.
Asia-Pacific Kitchen Furniture Market Competitive Environment
Top-tier vendors anchor premium positioning through smart storage integration and captive stone fabrication, while mid-scale competitors compete on laminate-wrapped MDF throughput and modular assembly speed. The vendor base stratifies across three functional archetypes: vertically integrated system providers controlling stone-to-installation value chains, mass-market fabricators optimizing particleboard substrate utilization, and specialist metal-carcass suppliers serving commercial food service compliance. Dominant competitive moves include backward integration into engineered stone production and direct-to-developer contracting that bypasses traditional retail franchise networks.
Among China-based fabricators, OPPEIN and GoldenHome exemplify contrasting strategic positions within the regional hierarchy. OPPEIN occupies a position representing the vertically integrated system provider archetype, while GoldenHome anchors premium-tier positioning through upstream control over quartz countertop fabrication. Lesso Group Holdings Ltd. sits within the diversified building materials segment, extending plumbing and cabinetry portfolios through shared contractor relationships. ZBOM Cabinets Co., Ltd. and QuanU represent the scale-driven mass-market tier competing on laminate-wrapped MDF throughput.
| Leading Market Players |
|---|
| Foshan Kitchen Cabinet Co., Ltd. |
| Lesso Group Holdings Ltd. |
| OPPEIN |
| GoldenHome |
| ZBOM Cabinets Co., Ltd. |
| Godrej and Boyce |
| Vatti Kitchen Solutions Co., Ltd. |
| QuanU |
| Ikea |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap fabricators in China's Zhejiang and Jiangsu provinces anchor laminate-wrapped particleboard production, translating concentrated raw material sourcing into disciplined margin management across export and domestic channels. Their ownership structure limits external capital pressure, allowing pricing stability even as India's BIS certification mandates and China's SAMR emission standards elevate compliance costs for cross-border competitors.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes kitchen furniture procurement across Asia-Pacific residential markets. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales installation bundling, with GB-compliant MDF substrates commanding measurable premiums over uncertified alternatives. Cost compression in the economy tier is intensifying because Vietnamese export manufacturers compete on laminate-wrapped throughput. Developer buyers in Bengaluru and Hyderabad demonstrate highest price sensitivity, while hospitality procurement in Tokyo and Singapore prioritizes durability over unit cost.
Supply Chain Analysis
India's BIS mandatory certification under IS 303 and IS 710 is reshaping sourcing patterns for plywood and blockboard, redirecting procurement toward Maharashtra and Gujarat domestic mills. Raw material flows draw from Indonesian timber concessions, Chinese resin and adhesive production, and South Korean hardware mechanisms. Single-source vulnerability concentrates in engineered quartz slab fabrication, where Xiamen-based captive operations limit mid-tier access. Distribution runs through direct-to-developer master agreements in Indian metropolitan corridors and franchise showroom networks across China's tier-two cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with India's BIS certification mandate and China's SAMR formaldehyde enforcement continuously elevating compliance barriers that consolidate share among certified manufacturers.
For Market Incumbents: Deploy backward integration into engineered stone production to defend margin capture against quartz substrate concentration. OPPEIN and GoldenHome exemplify divergent paths: showroom network control versus captive fabrication. Threats from stainless steel substitution in hospitality segments and skilled installation labor scarcity in secondary cities demand certification investment and technician training partnerships in Ho Chi Minh City and Mumbai clusters. For New Entrants and Emerging Players: India's BIS certification mandate opens a window for domestic engineered wood specialists to capture share from unqualified import competitors. Surabaya and Bandung present the most penetrable geography, with residential construction outpacing organized distribution. Indonesia's Java corridor rewards modular system providers capable of rapid deployment. A direct-to-developer go-to-market angle bypasses entrenched franchise networks in premium housing segments. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale laminate fabricators lacking stone-to-installation integration but possessing GB or BIS certification assets. Long-term viability over the next decade hinges on regulatory compliance durability rather than brand equity alone. Acquisition targets should demonstrate certified substrate access and installer network density. The signal to watch is BIS enforcement intensity against unqualified plywood imports, which would accelerate domestic consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Engineered Stone | Captures margin otherwise lost to Xiamen-based quartz fabricators controlling regional supply. |
| BIS Certification Investment | Creates defensible positioning against unqualified imports as India's enforcement tightens. |
| Direct-to-Developer Contracting | Displaces traditional showroom channels in Bengaluru and Hyderabad bulk residential procurement. |
| Smart Storage Mechanism Partnership | Links South Korean sensor-activated suppliers to premium urban positioning in Seoul and Shanghai. |
| Secondary City Installer Training | Addresses skilled labor scarcity constraining expansion beyond Jakarta and Mumbai metropolitan clusters. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with kitchen system procurement managers at Indian developer groups, Chinese manufacturing executives, Vietnamese export coordinators, and Japanese housing manufacturer specification teams with secondary validation. Regulatory filings from India's BIS, China's SAMR, and Japan's METI anchored compliance trend analysis. Trade flow data, customs records, and SEC disclosures from listed building materials firms provided demand-side triangulation. Bottom-up project pipeline assessment and top-down regional construction forecast reconciliation ensured coverage consistency.
Historical reference periods anchored the projection horizon, with growth trajectory modeling calibrated against urban residential construction permit volumes and hospitality development pipelines across the analysis window. Segmentation dimensions included installation type, material specification, style positioning, and end-use environment, with regulatory compliance tier and distribution channel structure as industry-specific overlay variables. CAGRs derived from fitted trend extrapolation moderated by capacity constraint assumptions and substitution elasticity estimates for stainless steel in commercial food service applications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt BIS enforcement escalation or SAMR emission standard revision. Forecasts reflect documented assumptions regarding certification timeline continuity and skilled labor availability. Specific risk factors include multi-jurisdiction testing burden extension, raw material resin price volatility, and hospitality sector demand fluctuation tied to travel recovery patterns. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Dining Table Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Serveware Market
Kitchen and Dining
Range Hood and Cooktop Market
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
Latin America Kitchen Furniture Market
Kitchen and Dining
Back Table and Cart Covers Market
Kitchen and Dining
GCC Modular Kitchen Market
Kitchen and Dining
Quartz Sink Market
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market
Kitchen and Dining
Modular Kitchen Market
Kitchen and Dining
Bahrain Kitchen Hoods Market
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
Prefabricated Kitchen Pod Market
Kitchen and Dining
Opalware Dinnerware and Crockery Market