
 Stove Cover Market | 2026-2036
Stove Cover Market Size, Share, and Industry Trends Forecast 2026-2036
Stove Cover Market Analytics
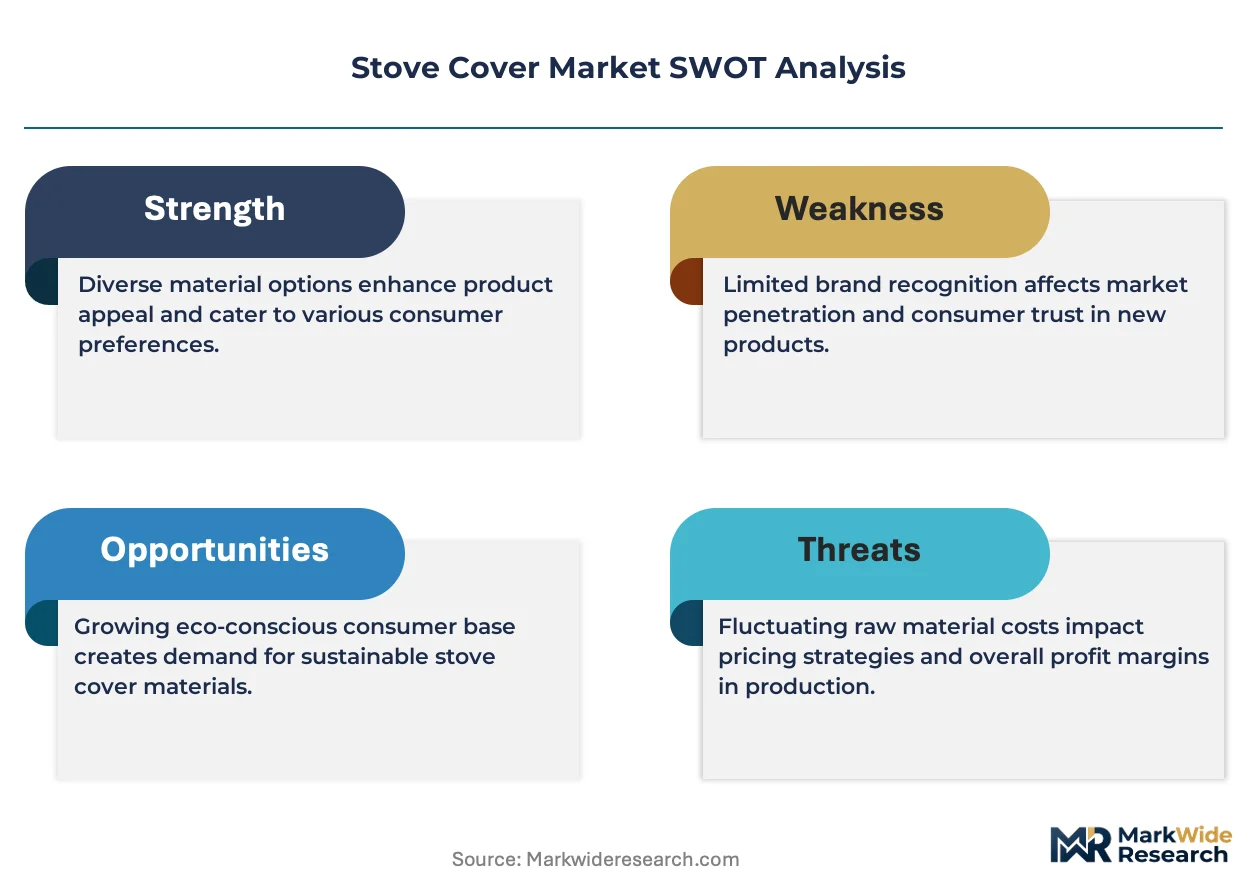
REACH compliance in Europe is consolidating material sourcing requirements for stove cover manufacturers seeking export access. GE leverages its appliance aftermarket distribution network to sustain replacement part visibility across North American retail channels. Electrolux anchors premium positioning through proprietary fit programs tied to its cooking appliance installed base. Samsung competes by integrating stove cover accessories into its smart kitchen ecosystem bundles.
A stove cover is a protective surface placed over cooktop burners to shield against spills, debris, and scratches when the appliance is not in active use, typically manufactured from heat-resistant materials such as tempered glass, stainless steel, food-grade silicone, or reinforced polymers rated for intermittent thermal exposure up to specific temperature thresholds. The primary commercial purpose centers on extending cooktop lifespan, reducing cleaning frequency, and enabling supplemental counter space in compact residential kitchens. Metal and glass variants dominate margin pools due to higher unit economics and durability premiums, while silicone formulations represent the fastest-expanding material category driven by flexibility, storage convenience, and color customization demand. Universal-type covers lead volume through broad compatibility claims, though custom-fit segments command price premiums from consumers seeking integrated aesthetic alignment with specific appliance models.
The FDA governs food-contact material safety for silicone-based covers distributed in the United States, while the EPA influences volatile organic compound limits in polymer coatings and adhesives used during manufacturing. REACH in Europe restricts certain phthalates and heavy metals in plastic cover formulations, effectively segmenting export-ready suppliers from domestic-only producers. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in California and New York, as these jurisdictions are actively developing appliance accessory disposal regulations that could reshape material selection and end-of-life collection obligations.
Market Dynamics
Residential kitchen renovation spending is consolidating demand around protective cooktop accessories, with silicone-based formulations capturing share from legacy plastics as homeowners prioritize FDA-compliant food-contact surfaces and flexible storage solutions.
Growth Catalysts
- REACH Compliance Migration:European material safety standards are filtering into North American supplier specifications, elevating formulation quality across export-oriented production bases.
- Appliance OEM Aftermarket Programs:Direct-to-consumer brands and original equipment manufacturer accessory channels are securing dedicated retail placement in home improvement chains.
- Silicone Material Substitution:Food-grade silicone formulations are displacing conventional thermoplastics due to heat resistance, foldability, and color customization capabilities.
Market Restraints
- Petrochemical Feedstock Volatility:Silicone polymer precursors and specialty polymer resins face input cost swings tied to natural gas and crude oil derivative markets.
- Asia-Pacific Supply Concentration:Raw silicone compound and molded component manufacturing clusters heavily in Chinese industrial zones, creating single-source vulnerability.
- Tempered Glass Weight Constraints:Premium glass cover variants face shipping cost penalties and breakage risk that compress margin structures in direct-to-consumer channels.
Strategic Opportunities
- Smart Kitchen Ecosystem Integration:Stove cover accessories bundled with connected appliance platforms create recurring revenue attachment opportunities.
- California Extended Producer Responsibility:State-level appliance accessory disposal regulations will favor suppliers with closed-loop material recovery capabilities.
- Custom-Fit Premium Segmentation:Proprietary fit programs tied to specific cooktop dimensions command price premiums over universal-type alternatives.
Industry Challenges
- FDA Food-Contact Certification Timelines:Silicone formulation approvals for repeated thermal cycling create 12-18 month product launch delays.
- Multi-Material Assembly Complexity:Hybrid covers combining silicone edges with glass or metal centers require specialized bonding equipment and quality control protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stove Cover Market |
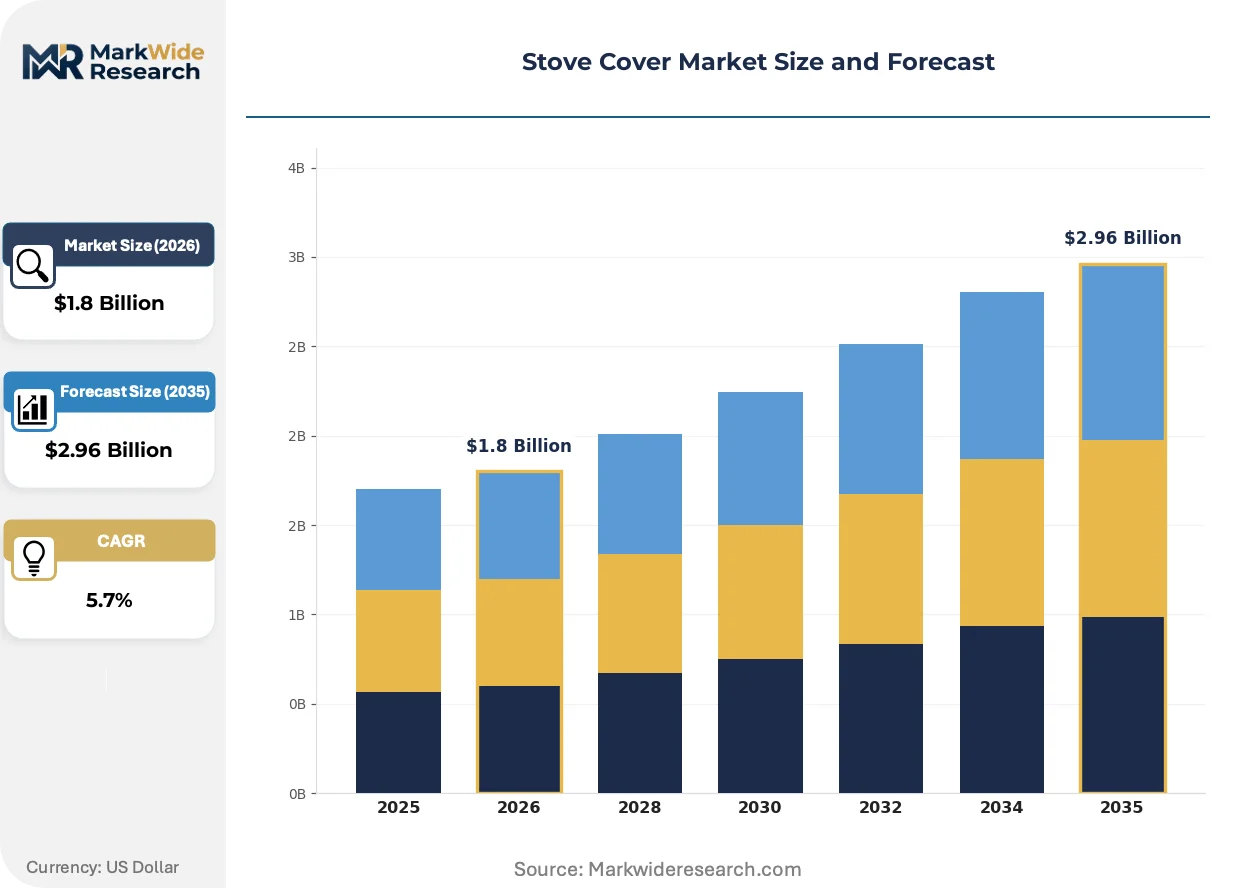
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Metal, Silicone, Plastic Type: Universal, Custom, Foldable, Decorative Size: Small, Medium, Large, Extra Large Style: Modern, Vintage, Minimalist, Rustic |
| Companies Covered | GE, Electrolux, Stove Shield, LG, Samsung, Whirlpool, Frigidaire, Maytag, Kenmore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stove Cover Market Evolving Landscape
Material science advances and regulatory harmonization are compressing product development cycles while reshaping how protective cooktop accessories reach residential end-users.
Modular silicone-glass hybrid constructions are modularizing stove cover design architectures. These configurations separate heat-resistant base layers from decorative or structural top surfaces. Custom kitchen designers and renovation contractors are specifying these adaptable systems for projects requiring both protection and aesthetic flexibility. The approach is modularizing supplier-manufacturer relationships by enabling component sourcing from specialized tier-two molders rather than integrated producers.
REACH substance restrictions on phthalates and heavy metals are tightening compliance burdens for plastic cover exporters serving European markets. The regulation forces reformulation of legacy polymer compounds and accelerates silicone substitution in cross-border product lines. North American suppliers with pre-validated material certifications are capturing shelf space from competitors facing retesting requirements.
Direct-to-consumer subscription models are replacing traditional retail replenishment cycles for replacement covers and accessory refreshes. These programs bypass big-box intermediaries while capturing lifetime value through automated reorder triggers tied to wear indicators or seasonal kitchen updates. United States metropolitan markets with high renovation velocity show the strongest adoption of this channel structure.
Stove Cover Market Segmentation
Material composition dictates thermal performance thresholds and cleaning protocols for stove covers, while dimensional precision determines compatibility across gas, electric, and induction cooktop configurations. Segmentation by use case—standalone protection versus integrated kitchen design—shapes procurement patterns among renovation contractors and direct-to-consumer buyers.
Material:
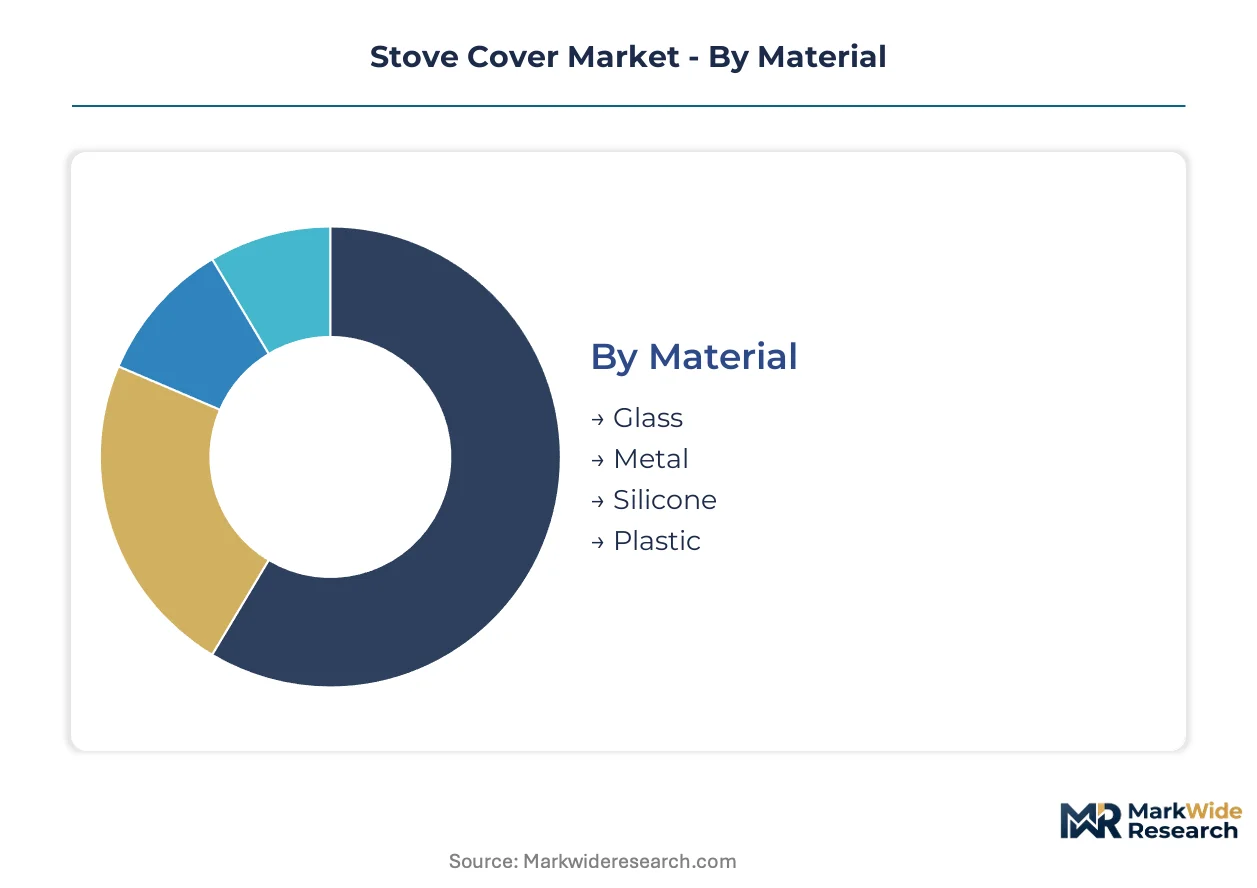
Glass and metal variants serve as permanent countertop extensions in high-end kitchen renovations, whereas silicone and plastic formulations address flexible storage needs in compact residential settings.
- Glass:Tempered borosilicate constructions rated for intermittent thermal exposure above standard cooktop temperatures. Demand clusters in United States metropolitan renovation markets where homeowners prioritize seamless counter extension and premium aesthetic integration with existing appliance finishes.
- Metal:Stainless steel and aluminum alloys offering superior scratch resistance and magnetic compatibility with induction cooktops. Stainless steel dominates commercial kitchen retrofit specifications, though weight penalties limit direct-to-consumer shipping economics.
- Silicone:Food-grade formulations meeting FDA thermal cycling standards for repeated heat exposure and refrigeration transitions. Foldability drives adoption in urban apartments with limited storage.
- Plastic:Thermoplastic polymers facing displacement pressure from silicone alternatives due to REACH phthalate restrictions and inferior heat deformation thresholds.
Glass leads volumes today; silicone is gaining share fastest.
Type:
Procurement patterns diverge between mass-market retail channels favoring broad compatibility claims and specialty distributors capturing premium margins through precision-fit programs.
- Universal:Standardized dimensions accommodating multiple cooktop brands and burner configurations. Big-box retailers and e-commerce marketplaces concentrate inventory in this category due to inventory turnover velocity and reduced SKU complexity.
- Custom:Proprietary measurements tied to specific appliance model dimensions. Custom-fit programs command price premiums from homeowners seeking integrated aesthetic alignment with premium cooktop installations.
- Foldable:Silicone-dominant constructions enabling compact storage in drawer or cabinet spaces. Urban residential markets with sub-800 square foot kitchens drive specification.
- Decorative:Patterned, colored, or textured surfaces prioritizing visual integration with kitchen design themes. Interior designer specifications influence demand concentration.
Universal-type covers dominate unit volumes; custom-fit segments capture the steepest margin expansion trajectory.
Size:
Dimensional segmentation correlates directly with cooktop burner count and kitchen footprint constraints across residential construction vintages.
- Small:Single-burner coverage for compact apartments and auxiliary cooking surfaces. Studio and one-bedroom unit renovations in dense urban districts concentrate demand.
- Medium:Two to three burner protection for standard residential cooktops. This specification aligns with the most common replacement cycle timing in owner-occupied housing.
- Large:Four-burner coverage for full-size residential appliances. Large-format silicone variants face shipping cost optimization challenges in direct-to-consumer channels.
- Extra Large:Professional-grade and commercial cooktop protection spanning five or more burners. Restaurant equipment suppliers and commercial kitchen contractors specify this category.
Medium dimensions anchor current procurement volumes; large-format specifications are expanding most quickly with suburban renovation activity.
Style:
Aesthetic segmentation enables price stratification beyond functional protection, with design-forward variants capturing margin premiums in renovation-driven markets.
- Modern:Clean lines, neutral palettes, and minimal surface texture. Contemporary kitchen renovations in coastal United States metropolitan areas specify this category.
- Vintage:Retro patterns, pastel colorways, and decorative edge treatments. Second-home and vacation property markets show concentrated interest.
- Minimalist:Ultra-thin profiles and monochromatic finishes prioritizing visual disappearance. High-end condominium developments favor this specification.
- Rustic:Wood-grain textures, earth tones, and farmhouse-inspired detailing. Rural and exurban residential markets drive adoption.
Modern styling leads current specification rates; minimalist designs are climbing the fastest in premium urban segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled polymer chemists and industrial designers concentrate in manufacturing clusters across four major economies, anchoring regional production capabilities for heat-resistant kitchen accessories.
United States
Residential renovation contractors in metropolitan markets drive specification of premium glass and silicone variants. FDA food-contact certification requirements create 12-18 month product launch timelines for new silicone formulations. Manufacturing activity clusters in Ohio and Michigan industrial corridors, where appliance OEM aftermarket programs coordinate with specialized cover fabricators.
Germany
REACH substance restrictions on phthalates and heavy metals filter into supplier qualification protocols across European distribution channels. ECHA enforcement of SVHC candidate list updates forces reformulation of legacy polymer compounds. Industrial design studios in Bavaria and Baden-Württemberg develop precision-fit measurement systems for premium cooktop integration.
China
Raw silicone compound and molded component manufacturing concentrates in Guangdong and Zhejiang industrial zones, supplying global OEM accessory programs. GB standards for food-contact materials govern domestic distribution while export-oriented facilities align with FDA and REACH specifications. Shenzhen-based logistics hubs manage direct-to-consumer fulfillment for North American and European e-commerce channels.
Japan
Compact urban residential kitchens in Tokyo and Osaka metropolitan areas drive demand for foldable silicone constructions with minimal storage footprints. METI energy efficiency guidelines influence material selection for accessories bundled with induction cooktop promotions. Nagoya-area industrial clusters supply precision metal forming for stainless steel cover variants targeting commercial kitchen retrofits.
India
Rising middle-class kitchen renovation activity in Mumbai and Delhi-NCR markets accelerates adoption of protective cooktop accessories. BIS certification requirements for food-contact plastics create compliance differentiation between organized and unorganized sector suppliers. Tamil Nadu and Gujarat manufacturing zones develop silicone molding capabilities for export-oriented appliance OEM programs.
Stove Cover Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Appliance OEMs leverage installed base visibility and aftermarket distribution networks to secure retail shelf space, while independent fabricators compete on material innovation and direct-to-consumer channel control. Three archetypes dominate: integrated appliance manufacturers with captive accessory programs, specialized kitchen protection brands, and contract manufacturers serving private-label retailers. Competitive moves center on strategic partnerships with home improvement chains and portfolio diversification into smart kitchen ecosystem bundles.
Among diversified appliance manufacturers, GE, Electrolux, and Samsung occupy positions spanning integrated aftermarket distribution and smart home platform integration. GE exemplifies the OEM-captive archetype through appliance aftermarket network leverage. Electrolux represents premium positioning through proprietary fit programs. Samsung anchors the connected-ecosystem vector with accessory bundling into smart kitchen platforms.
| Leading Market Players |
|---|
| GE |
| Electrolux |
| Stove Shield |
| LG |
| Samsung |
| Whirlpool |
| Frigidaire |
| Maytag |
| Kenmore |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap silicone fabricators in Guangdong and Zhejiang provinces anchor raw compound production, translating concentrated upstream ownership into disciplined contract pricing for North American and European OEM accessory programs. This ownership structure limits spot-market volatility transmission while reinforcing long-term offtake agreements with appliance manufacturers seeking FDA-compliant formulation stability.
Pricing Analysis
Bundled smart-kitchen ecosystem accessories command premium positioning against unbundled standalone covers sold through retail intermediaries. Three-tier pricing structure across premium, standard, and economy levels separates custom-fit glass-and-metal hybrids from universal silicone variants and entry-level plastic alternatives. Price differentiation rests on FDA certification grade and geographic delivery cost, with direct-to-consumer channels absorbing shipping penalties for glass variants. Pricing pressure stems from petrochemical feedstock volatility in silicone precursor markets, compressing margins most acutely in economy-tier plastic segments where buyers exhibit highest price sensitivity.
Supply Chain Analysis
Regional distribution centers in Shenzhen and Ningbo manage hub-and-spoke fulfillment patterns for North American and European e-commerce channels. Raw silicone compound manufacturing concentrates in China, with specialty polymer resin production anchored in Germany and the United States. The supply chain draws from silicone polymer precursors, tempered glass substrates, and stainless steel sheet inputs. Single-source vulnerability in Guangdong molding clusters creates structural risk for OEM accessory programs. Distribution runs through appliance manufacturer captive networks, home improvement retail chains, and direct-to-consumer fulfillment platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-compliant European formulation standards and California's emerging extended producer responsibility frameworks, rewarding suppliers with pre-validated material certifications across both jurisdictions.
For Market Incumbents: Lock in proprietary fit programs with appliance OEMs to defend against silicone-specialist entrants capturing share through direct-to-consumer subscription models. Deepen backward integration into food-grade silicone compounding to secure FDA certification timelines and buffer petrochemical feedstock volatility. Channel control through home improvement retail shelf-space agreements remains the critical defensive lever against emerging private-label competitors. For New Entrants and Emerging Players: Capture white-space opportunity in custom-fit premium segments for induction cooktop retrofits, where precision measurement capabilities command price premiums over universal alternatives. Target foldable silicone constructions for urban residential markets with sub-800 square foot kitchens, leveraging Shenzhen logistics infrastructure for direct-to-consumer fulfillment. Go-to-market execution should emphasize interior designer specification channels rather than retail intermediaries. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers serving private-label retailers, offering entry points before consolidation around REACH-compliant suppliers accelerates. Long-term viability across the projection horizon favors targets with closed-loop material recovery capabilities aligned with California extended producer responsibility developments. Watch FDA food-contact certification backlog duration as the inflection signal for supplier margin expansion versus compression.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Kitchen Ecosystem Integration | Samsung and GE bundle stove covers into connected appliance platforms, creating recurring revenue attachment. |
| Backward Integration into Silicone Compounding | Specialist fabricators in Guangdong acquire precursor production to secure FDA certification timelines. |
| Direct-to-Consumer Subscription Launch | Stove Shield and independent brands bypass retail intermediaries through automated reorder triggers. |
| REACH Compliance Pre-Validation | North American suppliers capture European shelf space from competitors facing retesting requirements. |
| Custom-Fit Precision Measurement Systems | Electrolux and Bavarian design studios develop proprietary fit programs for premium cooktop integration. |
Research Methodology
Coverage spans the United States, Germany, China, and Japan, with primary inputs from each market anchoring regional demand calibration. The approach combines primary interviews with appliance OEM procurement directors, silicone compound plant managers, home improvement category buyers, and direct-to-consumer brand operations heads with secondary validation. Secondary sources include FDA food-contact material filings, ECHA SVHC candidate list updates, SEC 10-K disclosures from diversified appliance manufacturers, and customs trade data for silicone polymer precursor flows. Bottom-up demand modeling and top-down market sizing triangulate volume estimates across material and type segments.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include material composition, type specification, dimensional category, and aesthetic styling tier. CAGRs derive from fitted trend extrapolation adjusted for regulatory inflection points and channel shift dynamics. Industry-specific forecast inputs incorporate residential kitchen renovation spending velocity and appliance replacement cycle timing from housing stock vintage analysis.
Underlying measurement precision varies by segment; silicone material categories carry tighter precision than plastic alternatives due to consolidated supplier reporting. Forecasts reflect documented assumptions regarding REACH enforcement stringency and California extended producer responsibility implementation timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Hobs Market
Kitchen and Dining
United States Kitchen Furniture Market
Kitchen and Dining
Asia-Pacific Kitchen Furniture Market
Kitchen and Dining
Restaurant Chairs Market
Kitchen and Dining
GCC Modular Kitchen Market
Kitchen and Dining
Pull Out and Down Kitchen Faucet Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
Asia-Pacific Modular Kitchen Market
Kitchen and Dining
Skillets and Frying Pans Market
Kitchen and Dining
Banquet Carts and Heated Cabinets Market
Kitchen and Dining
Kitchen Sinks Market
Kitchen and Dining
Global Kitchen Woks Market
Kitchen and Dining
US Tableware Market
Kitchen and Dining
Kitchen Furniture and Fixtures Market
Kitchen and Dining
North America Kitchen Furniture Market
Kitchen and Dining
Saudi Arabia Kitchen Hoods Market