
 North America Quinoa Seeds Market | 2026-2036
North America Quinoa Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
North America Quinoa Seeds Market Analytics
Subscription-based replenishment services for organic quinoa is decoupling bulk commodity sales from direct-to-pantry delivery models. Ancient Harvest LLC leverages its established retail partnerships to sustain shelf presence across conventional and natural grocery channels. Ardent Mills LLC anchors North American supply security through its integrated milling and grain handling infrastructure. Bob's Red Mill Natural Foods differentiates via heritage brand positioning and certified gluten-free processing protocols.
Quinoa seeds are gluten-free pseudocereals from Chenopodium quinoa, containing complete protein profiles with all nine essential amino acids and saponin-coated hulls requiring mechanical abrasion or washing prior to consumption. Organic quinoa commands premium positioning as the fastest-growing product type, driven by dual-certification requirements for both domestic production and import channels. The food industry end-use segment dominates volume absorption, while health food stores and online retail distribution channels capture expanding margin pools through private-label and direct-to-consumer formats.
The USDA National Organic Program and Canada Organic Regime enforce strict origin documentation and pesticide residue thresholds for quinoa marketed as organic across both countries. The FDA Food Safety Modernization Act mandates preventive controls for foreign and domestic quinoa suppliers entering the U.S. supply chain. Stakeholders must monitor evolving phytosanitary protocols and domestic breeding program outputs to secure compliant, scalable seed supply without overreliance on Andean imports.
Market Dynamics
The North America quinoa seeds market is being reshaped by tightening USDA National Organic Program traceability mandates, which are forcing importers and domestic growers to rebuild supply chains around certified origin documentation and domestic breeding investments rather than Andean bulk sourcing.
Growth Catalysts
- USDA National Organic Program Certification:Dual-certification requirements for imported and domestic quinoa are pulling investment into Pacific Northwest contract farming networks and regional processing infrastructure.
- Plant-Forward Dietary Shifts:Health food stores and specialty grocers across the United States and Canada are expanding shelf space allocation for quinoa-based products as consumer protein preferences pivot.
- Mechanical Abrasion Technology:Advances in saponin hull removal equipment are reducing post-harvest processing costs and improving finished seed quality consistency for food industry buyers.
Market Restraints
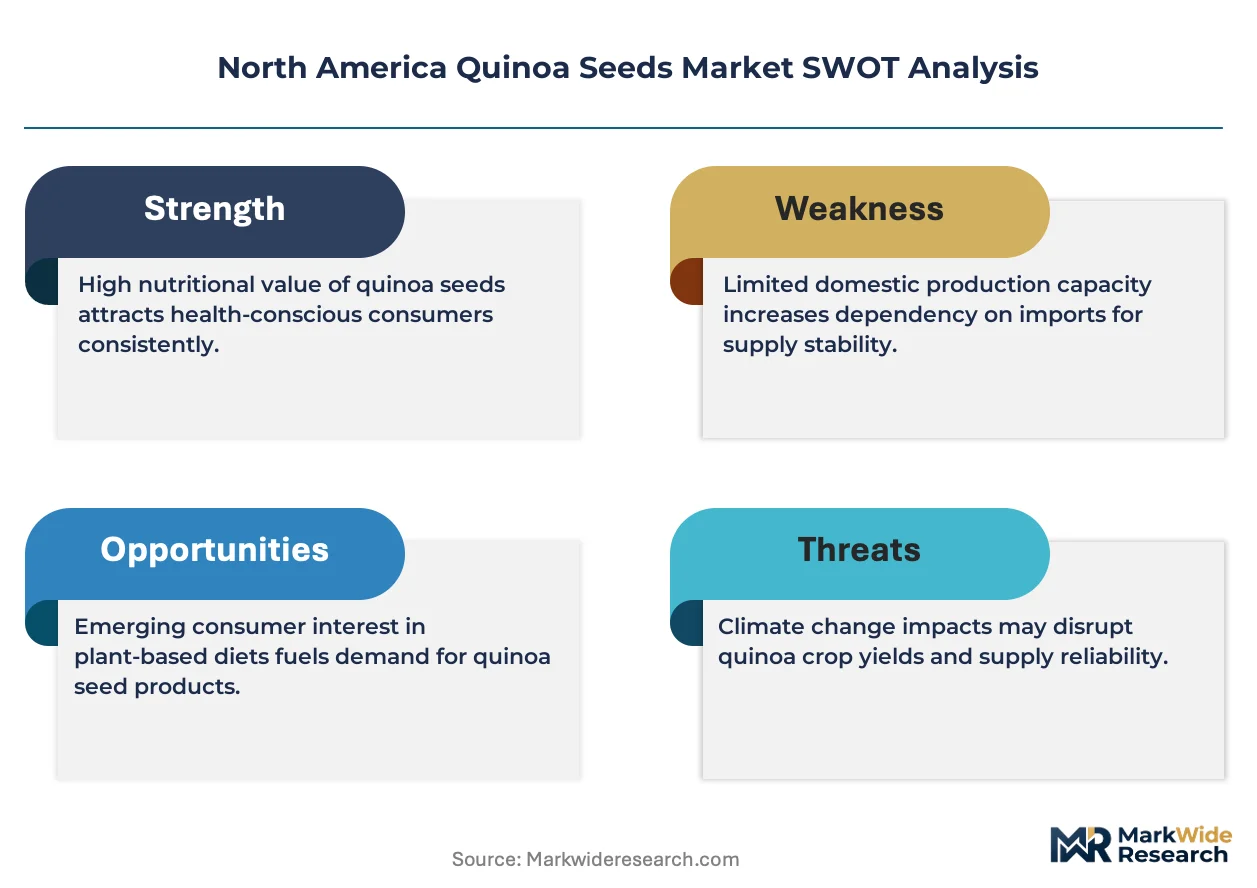
- Andean Import Concentration:Overreliance on Peruvian and Bolivian seed supply exposes buyers to phytosanitary protocol disruptions and currency volatility.
- FDA Food Safety Modernization Act Compliance:Preventive controls mandates for foreign suppliers create documentation burdens and inspection delays at U.S. ports of entry.
- Amaranth and Millet Substitution:Alternative gluten-free pseudocereals compete for shelf space and formulation contracts in bakery and snack applications.
Strategic Opportunities
- Subscription-Based Replenishment:Direct-to-pantry delivery models for organic quinoa are decoupling bulk commodity sales from conventional retail distribution.
- California Contract Farming Expansion:Underdeveloped acreage in the Central Valley offers scalable domestic sourcing outside Pacific Northwest concentration.
- Health Canada Organic Regime Alignment:Harmonized cross-border certification protocols create unified North American private-label opportunities for integrated processors.
Industry Challenges
- Domestic Breeding Program Timelines:Development of climate-adapted Chenopodium quinoa cultivars suitable for North American latitudes requires multi-year agronomic trials and varietal registration.
- Gluten-Free Facility Certification:Certified gluten-free processing protocols demand capital-intensive facility segregation and testing regimens that constrain mid-scale miller participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Quinoa Seeds Market |
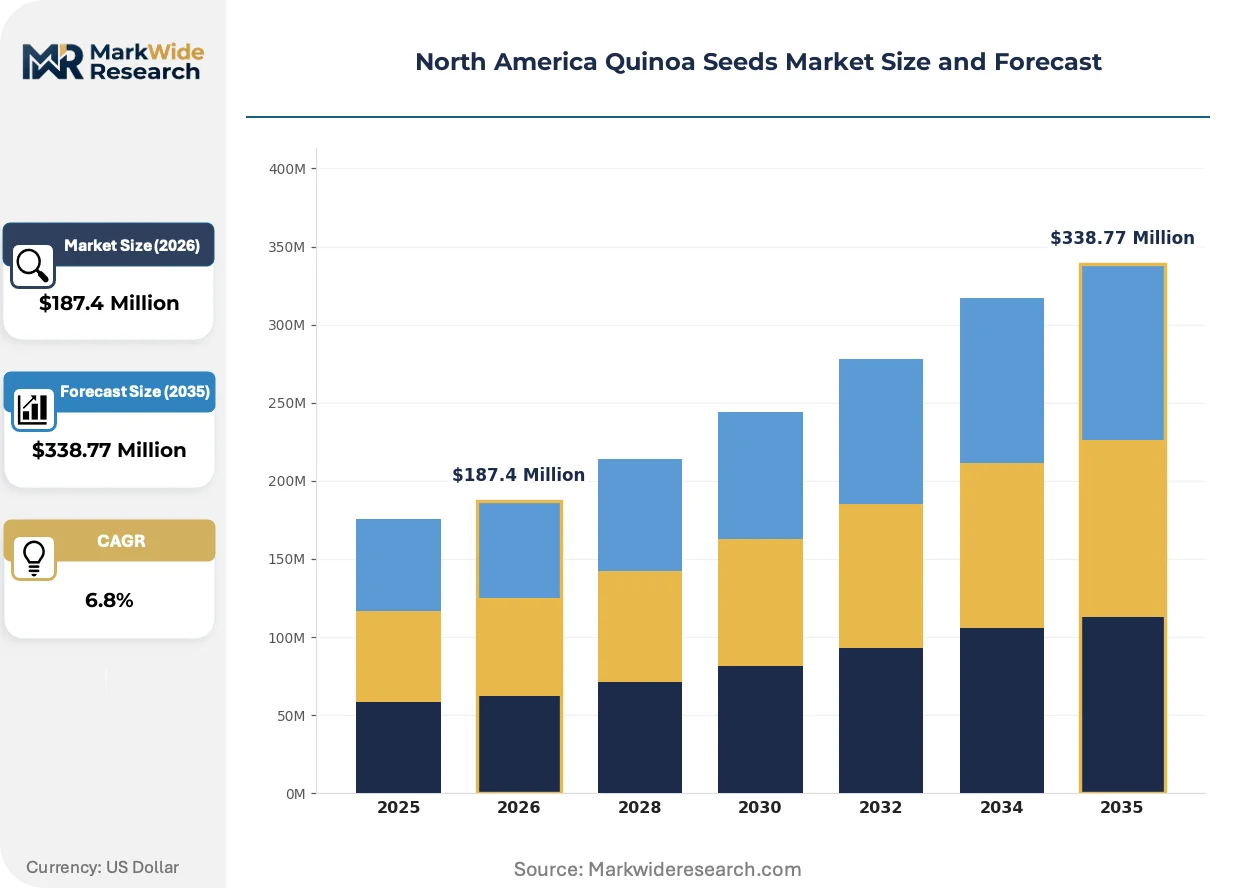
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Quinoa, Conventional Quinoa, Red Quinoa, White Quinoa End Use Industry: Food Industry, Beverage Industry, Cosmetics, Animal Feed Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Distributors Packaging Type: Bags, Boxes, Tins, Bulk Containers |
| Companies Covered | Ancient Harvest LLC, Ardent Mills LLC, Northern Quinoa Production Corporation, Above Food Inc., The Hain Celestial Group Inc., Quinoa Corporation, Bob’s Red Mill Natural Foods Inc., Keen One Foods LLC, Andean Naturals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Quinoa Seeds Market Evolving Landscape
Technology convergence, regulatory tightening, and channel fragmentation are simultaneously compressing legacy supply models while opening new margin pools for agile participants across the value chain.
Mechanical saponin removal systems are converging with optical sorting technology to automate hull abrasion and defect detection in a single processing line. Mid-scale regional processors in California and the Pacific Northwest are adopting these integrated systems to reduce labor intensity and improve batch consistency. This convergence is compressing the cost gap between imported pre-washed seed and domestically processed supply.
The FDA Food Safety Modernization Act foreign supplier verification program is extending preventive controls documentation requirements to Andean quinoa exporters. Importers must now maintain written hazard analysis and risk-based preventive controls for each foreign supplier. Small-to-mid importers lacking compliance infrastructure are exiting the market, concentrating import volume among integrated handlers with in-house regulatory affairs capacity.
Direct-to-consumer subscription models are displacing bulk club-store purchases among urban organic buyers. Specialty e-commerce platforms and health food store private-label services are capturing recurring pantry replenishment demand previously served by conventional grocery bulk bins. This behavioral shift is most visible in metropolitan corridors of California, Washington, and British Columbia where delivery density supports unit economics.
North America Quinoa Seeds Market Segmentation
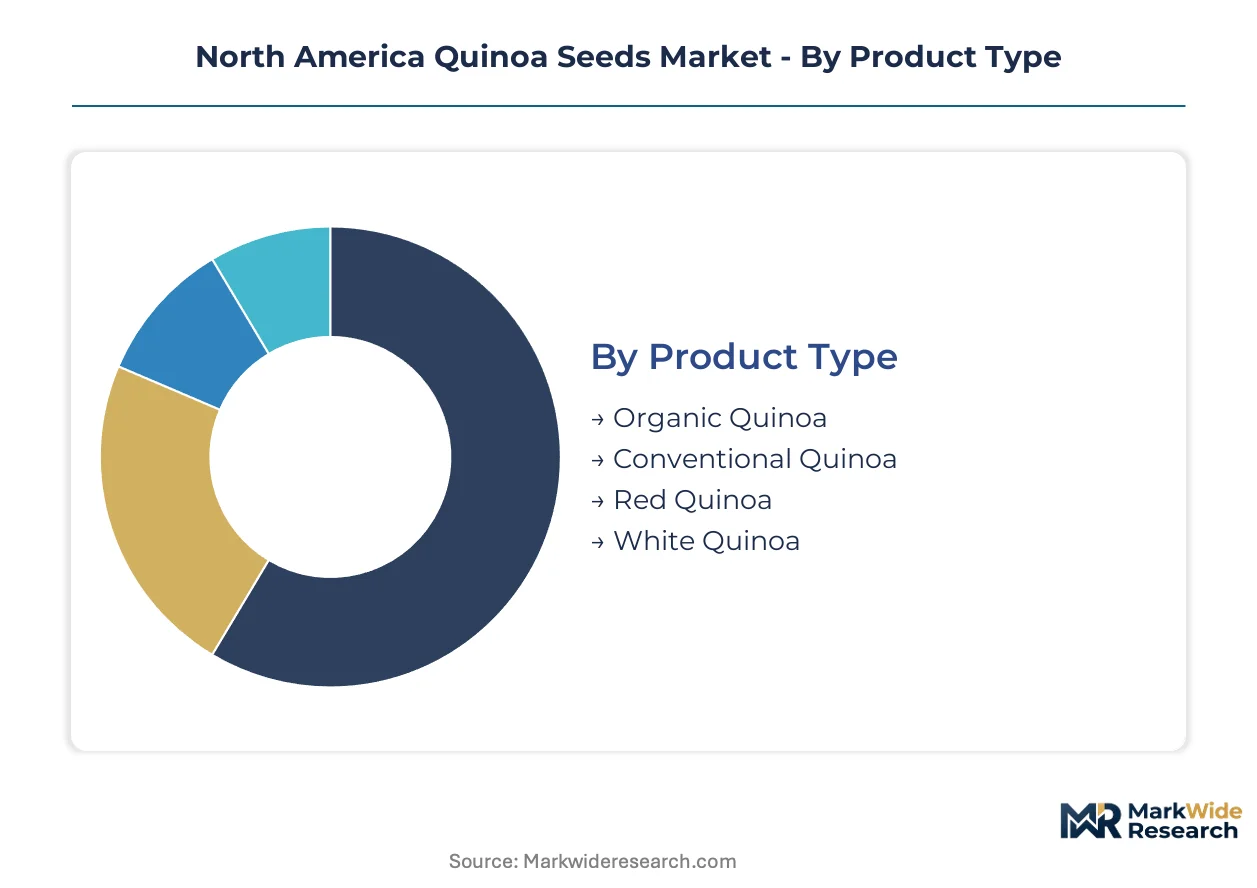
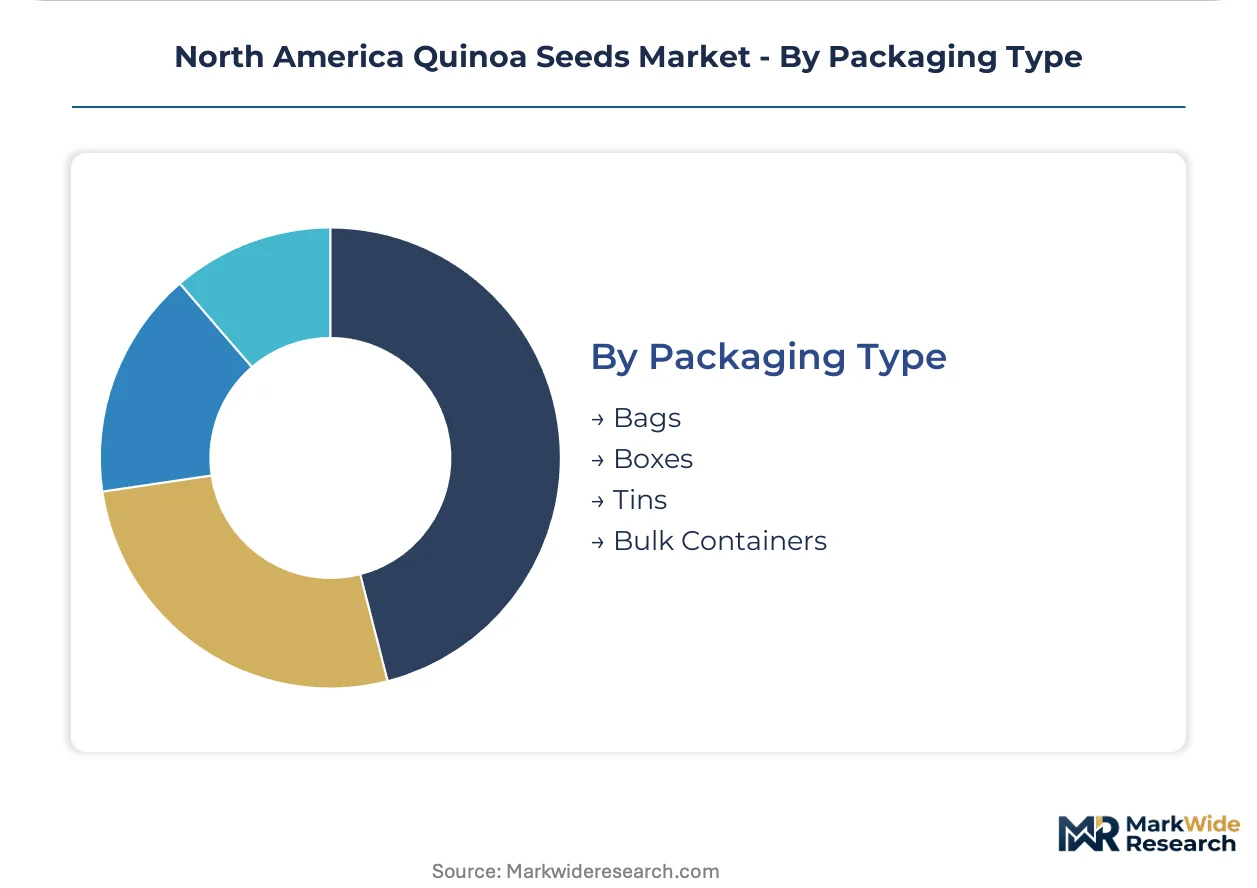
Segmentation in the North America quinoa seeds market reveals how certification tiers, channel strategies, and packaging formats allocate margin pools across distinct buyer workflows. Each dimension carries regulatory and operational implications that reshape supplier positioning.
Product Type:
Integration depth varies sharply across product types, with standalone certified organic commanding premium positioning while conventional grades embed into commodity food manufacturing supply chains.
- Organic Quinoa:Dual-certified under the USDA National Organic Program and Canada Organic Regime, requiring traceable origin documentation and pesticide residue thresholds. Pacific Northwest contract farming networks absorb the bulk of domestic sourcing investment as importers face tightening foreign supplier verification mandates.
- Conventional Quinoa:Sourced primarily through Andean bulk channels with saponin hulls intact, serving food industry buyers with in-house mechanical abrasion capacity. FDA Food Safety Modernization Act preventive controls create documentation burdens that favor integrated handlers over small-to-mid importers.
- Red Quinoa:Pigmented variety with elevated anthocyanin content targeting specialty health food formulations and premium direct-to-consumer channels.
- White Quinoa:Mild-flavored standard grade dominating supermarket shelf placement and conventional bakery ingredient specifications.
Volume placements concentrate in conventional quinoa; the faster expansion belongs to organic quinoa.
End Use Industry:
Cost tier stratification separates commodity-scale absorption from margin-capture in branded finished goods.
- Food Industry:Dominates volume absorption across bakery, cereal, and plant-based meat formulations. Mechanical saponin removal systems integrated with optical sorting compress processing cost gaps between imported pre-washed and domestically processed supply.
- Beverage Industry:Emerging application in protein-fortified drinks and dairy alternatives. California and Pacific Northwest processing infrastructure supports regional contract volumes.
- Cosmetics:Saponin extracts and protein isolates for hair and skin formulations, requiring certified gluten-free processing protocols that constrain mid-scale supplier participation.
- Animal Feed:Low-grade screenings and hull byproducts channel into pet food and specialty livestock nutrition, competing with amaranth and millet substitution.
Revenue concentration sits with food industry buyers; cosmetics applications are climbing the fastest.
Distribution Channel:
Customer type fragmentation splits recurring pantry replenishment from intermittent bulk procurement.
- Online Retail:Subscription-based replenishment services decouple bulk commodity sales from direct-to-pantry delivery models. Metropolitan corridors in California, Washington, and British Columbia support delivery density economics.
- Supermarkets:Conventional grocery bulk bins face displacement as private-label quinoa migrates to center-store shelf-stable placement.
- Health Food Stores:Expanding shelf space allocation captures margin pools through certified organic and gluten-free SKUs with heritage brand positioning.
- Distributors:Integrated handlers with in-house regulatory affairs capacity consolidate import volume as small-to-mid importers exit under FDA foreign supplier verification program burdens.
Transaction volume flows through supermarkets; health food stores and online retail are gaining share fastest.
Packaging Type:
Supply concentration in regional processing infrastructure dictates packaging format availability and cost structures.
- Bags:Standard retail pouches dominate supermarket and health food store shelf placement with resealable convenience features.
- Boxes:Premium gift and subscription formats targeting direct-to-consumer channels with heritage brand storytelling.
- Tins:Long-shelf-life formats for specialty export and emergency preparedness segments.
- Bulk Containers:Food industry totes and super sacks serve manufacturing buyers with in-house processing and repackaging capacity.
Shipment volumes run through bulk containers; bags capture the steepest expansion trajectory in retail-facing channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quinoa consumption in North America far outpaces domestic production, with the United States and Canada importing the majority of supply from Andean sources while building Pacific Northwest and California growing networks. Mexico emerges as a secondary production zone with cross-border processing linkages. Regional infrastructure investments concentrate where organic certification and traceability requirements are tightest.
United States
Plant-forward protein demand drives quinoa absorption across California, Washington, and Oregon metropolitan corridors. The USDA National Organic Program enforces dual-certification traceability for imported seed, redirecting investment toward domestic contract farming networks. Pacific Northwest regional processors expand mechanical saponin removal capacity to close cost gaps with pre-washed Andean supply.
Canada
Prairie provinces Saskatchewan and Manitoba host expanding organic quinoa acreage under the Canada Organic Regime certification framework. Health Canada alignment with USDA protocols enables unified North American private-label sourcing for integrated processors. British Columbia health food store chains and subscription services capture recurring pantry replenishment demand in Vancouver and Victoria corridors.
Mexico
Central Mexican highland regions develop quinoa cultivation for cross-border processing into U.S. organic supply chains. The country's national agricultural regulator coordinates phytosanitary protocols with USDA Animal and Plant Health Inspection Service requirements. Bajío Region contract farming networks supply raw seed to California and Texas milling facilities.
North America Quinoa Seeds Market Competitive Landscape
Top-tier vendors anchor integrated milling and heritage brand positioning, while mid-scale regional processors and specialty importers occupy fragmented niche tiers. Market structure stratifies across three functional archetypes: legacy natural foods brands with retail shelf dominance, grain handling conglomerates with captive supply infrastructure, and Andean-focused importers with foreign supplier verification capacity. Dominant competitive moves include backward integration into Pacific Northwest contract farming and portfolio diversification into subscription-based direct-to-consumer channels.
Within the integrated grain handler tier, Ardent Mills LLC represents scale-driven supply security through milling and handling infrastructure. Ancient Harvest LLC and Bob's Red Mill Natural Foods occupy heritage brand positions, with the former leveraging established retail partnerships and the latter differentiating through certified gluten-free processing protocols. These three entities exemplify the competitive vectors reshaping North American quinoa distribution.
| Leading Market Players |
|---|
| Ancient Harvest LLC |
| Ardent Mills LLC |
| Northern Quinoa Production Corporation |
| Above Food Inc. |
| The Hain Celestial Group Inc. |
| Quinoa Corporation |
| Bob’s Red Mill Natural Foods Inc. |
| Keen One Foods LLC |
| Andean Naturals Inc. |
| Others |
Value Network & Pricing Analysis
USDA National Organic Program dual-certification mandates for imported seed are forcing importers to absorb compliance costs or pivot toward Pacific Northwest contract farming, compressing margins on Andean bulk supply while elevating domestic organic premiums.
Pricing Analysis
Margin tightening in conventional quinoa traces to mechanical saponin removal technology convergence, which narrows cost gaps between imported pre-washed and domestically processed supply. Three-tier pricing structure across organic certified, conventional pre-washed, and bulk hull-intact grades reflects certification burden and processing intensity. Pricing pressure accelerates in conventional tiers as FDA Food Safety Modernization Act documentation burdens push small importers toward exit. Food industry buyers exhibit highest price sensitivity; health food stores and subscription services absorb organic premiums with lower elasticity.
Supply Chain Analysis
Regional distribution centers in California's Central Valley and Washington's Columbia Basin anchor hub-and-spoke patterns for organic quinoa. Supply concentrates in Peru, Bolivia, and Ecuador for conventional grades, while domestic sourcing draws from Pacific Northwest and Canadian prairie networks. Raw material dependencies rest on Chenopodium quinoa seedstock, mechanical abrasion equipment, and optical sorting systems. Single-source vulnerability in Andean import channels creates exposure to phytosanitary protocol disruptions. Distribution runs through integrated handlers with in-house regulatory affairs capacity, consolidating volume as small importers exit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America quinoa seeds market is consolidating around regulatory compliance capacity, with FDA foreign supplier verification program burdens forcing weaker importers toward exit and concentrating volume among integrated handlers.
For Market Incumbents: Deepen backward integration into Pacific Northwest contract farming networks to secure organic supply outside Andean import concentration. Invest in certified gluten-free facility segregation to defend margin position against Bob's Red Mill Natural Foods heritage brand positioning. Ardent Mills LLC anchors supply security through captive milling infrastructure; replicate this model in California Central Valley acreage. For New Entrants and Emerging Players: Launch via subscription-based direct-to-pantry delivery models targeting metropolitan corridors in British Columbia, Washington, and California where delivery density supports unit economics. White-space sits in organic red quinoa specialty formulations for cosmetics and premium health food channels. Avoid conventional bulk commodity positioning where FDA compliance infrastructure requirements create barriers. For Investors and Strategic Acquirers: The window for entry favors integrated processors with foreign supplier verification program capacity and Pacific Northwest contract farming relationships. Long-term viability hinges on domestic breeding program outputs reducing Andean import dependence. Watch Health Canada-USDA certification harmonization progress as inflection indicator for unified North American private-label scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | Pacific Northwest acreage expansion reduces Andean import concentration risk under tightening USDA traceability mandates. |
| Certified Gluten-Free Facility Investment | Capital-intensive segregation protocols capture cosmetics and premium health food margins inaccessible to mid-scale millers. |
| Subscription-Based Direct-to-Consumer Launch | Metropolitan corridor delivery density decouples organic quinoa sales from conventional grocery bulk bin displacement. |
| Mechanical Abrasion Technology Upgrade | Optical sorting convergence compresses labor intensity and improves batch consistency for food industry buyers. |
| Health Canada Organic Regime Alignment | Cross-border certification harmonization enables unified private-label sourcing across British Columbia and prairie provinces. |
Research Methodology
Multi-period observation of USDA National Organic Program certification trends, FDA foreign supplier verification program compliance rates, and Pacific Northwest contract farming acreage anchored the trend analysis, supplemented by interviews with grain handling executives, organic certification specialists, health food store category buyers, and food industry procurement directors. Secondary validation drew from USDA National Organic Program enforcement data, FDA Food Safety Modernization Act guidance documents, Canada Organic Regime certification statistics, and customs import records. Bottom-up volume triangulation across product type, end-use industry, and distribution channel segments converged with top-down macroeconomic drivers.
Segment-weighting approaches modeled organic versus conventional quinoa splits, food industry versus cosmetics end-use absorption, and online retail versus supermarket channel shares across the projection horizon. CAGRs derived from fitted growth curves applied to baseline consumption patterns, adjusted for mechanical abrasion technology adoption curves and domestic breeding program timeline assumptions. Forecast inputs incorporated Health Canada-USDA regulatory harmonization scenarios and subscription service penetration rates in metropolitan corridors.
Phytosanitary protocol disruptions, domestic breeding program delays, and subscription service unit economics failure are the dominant revision risks warranting forecast sensitivity analysis. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Asia-Pacific Vegetable Seed Market
Seeds
Thailand Seed Market
Seeds
Melon Seed Market
Seeds
South and Southeast Asia Seed Market
Seeds
Organic Chia Seeds Market
Seeds
Agricultural Seeder Market
Seeds
Asia-Pacific Grain Seed Market
Seeds
Thailand Vegetable Seed Market
Seeds
North America Tomato Seed Market
Seeds
Drought Tolerant Seeds Market
Seeds
Citrus Seeds Market
Seeds
Psyllium Seed Market
Seeds
Mexico Vegetable Seed Market
Seeds
Europe Amaranth Market
Seeds
India Vegetable Seed Market
Seeds
Asia-Pacific Quinoa Seeds Market