
 Citrus Seeds Market | 2026-2036
Citrus Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Citrus Seeds Market Outlook
The gap between certified disease-free rootstock seeds and untreated commodity seeds is realigning procurement patterns across citrus-growing regions. Louis Dreyfus Company leverages its integrated supply chain to control seed distribution from Brazilian orchards to international nurseries. Citrosuco S.A. anchors its position through captive seed production tied to its juice processing footprint in São Paulo state. Sucocitrico Cutrale Ltd. competes by specializing in high-germination-rate varieties for commercial replanting programs.
Citrus seeds are the reproductive units of Citrus species, typically containing embryos within lignified teguments with oil-rich cotyledons that require stratification or chemical scarification to achieve germination rates above 75 percent in commercial settings. Their primary purpose spans rootstock propagation for grafted orchard establishment, direct-seeding of rootstock lines tolerant to Tristeza virus and citrus greening, and oil extraction from cold-pressed seeds for cosmetic and nutraceutical applications. Sweet orange seeds dominate volume due to established rootstock demand, while grapefruit seeds command premium positioning in phytochemical extract channels. The horticulture end-use segment shows structural expansion as protected nursery cultivation displaces field-seeding in disease-prevalent zones.
The USDA's Animal and Plant Health Inspection Service enforces quarantine protocols on citrus seed imports to prevent HLB and canker spread, directly limiting supplier eligibility for US market access. Brazil's Ministry of Agriculture (MAPA) mandates phytosanitary certification for seed exports, creating compliance tiers that favor vertically integrated processors over independent traders. Stakeholders must monitor evolving seed treatment registration requirements under EPA and state-level environmental regulations, as biofumigation alternatives to methyl bromide face accelerated review timelines that will reshape propagation economics.
Market Dynamics
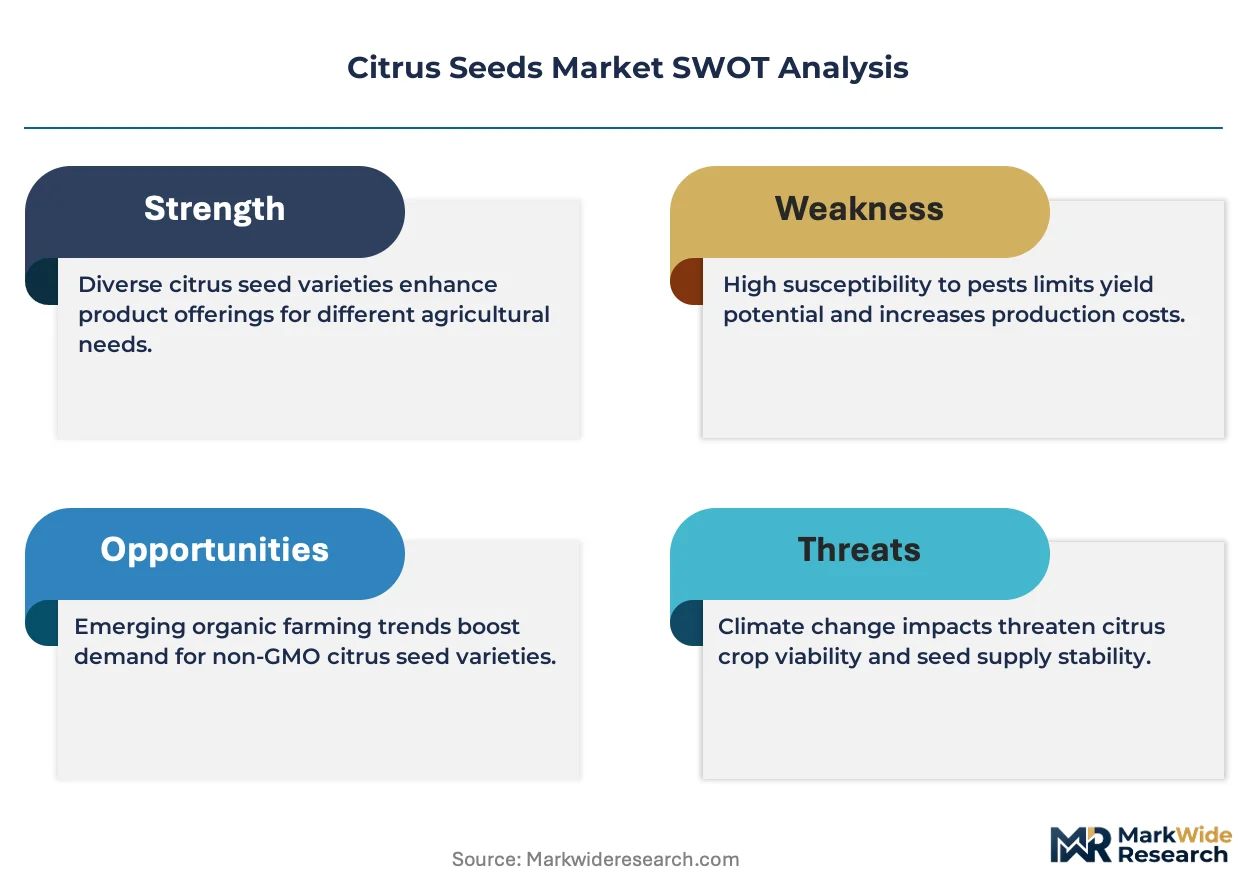
Certified disease-free rootstock propagation is compressing procurement timelines across citrus nurseries, as HLB disease pressure forces growers to abandon field-seeding for controlled greenhouse protocols.
Growth Catalysts
- USDA Quarantine Enforcement:The Animal and Plant Health Inspection Service mandates phytosanitary screening on all citrus seed imports, creating a structural premium for certified suppliers with established compliance infrastructure.
- Integrated Juice Processing:Brazilian processors in São Paulo state now operate captive seed propagation facilities, internalizing rootstock supply chains that previously relied on third-party traders.
- Greenhouse Cultivation:Protected nursery systems achieve germination rates above 75 percent through controlled stratification, displacing open-field seeding in disease-prevalent zones.
Market Restraints
- Input Cost Volatility:Methyl bromide phase-out under EPA environmental regulations is forcing nurseries toward biofumigation alternatives with unproven cost structures at commercial scale.
- Supply Concentration Risk:Brazil's Ministry of Agriculture certification requirements favor vertically integrated processors, marginalizing independent seed traders without captive orchard networks.
- Technical Limitation:Chemical scarification protocols for lignified teguments require precise timing; suboptimal treatment destroys embryo viability and triggers replanting delays.
Strategic Opportunities
- Phytochemical Extraction Channel:Grapefruit seed oil for cosmetic and nutraceutical applications commands premium positioning outside commodity rootstock markets.
- EU Plant Health Regulation Tailwind:Tightening seed import protocols create first-mover advantage for suppliers with pre-certified propagation facilities and documented traceability systems.
- California Nursery Expansion:Commercial citrus nurseries in the Central Valley are scaling certified rootstock programs to replace HLB-compromised orchard stock.
Industry Challenges
- Certification Timeline Compression:Phytosanitary documentation under MAPA and USDA protocols extends seed-to-sale cycles, straining working capital for non-integrated traders.
- Skill Scarcity in Embryo Rescue:Controlled germination techniques require specialized horticultural technicians; training pipelines lag behind greenhouse capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus Seeds Market |
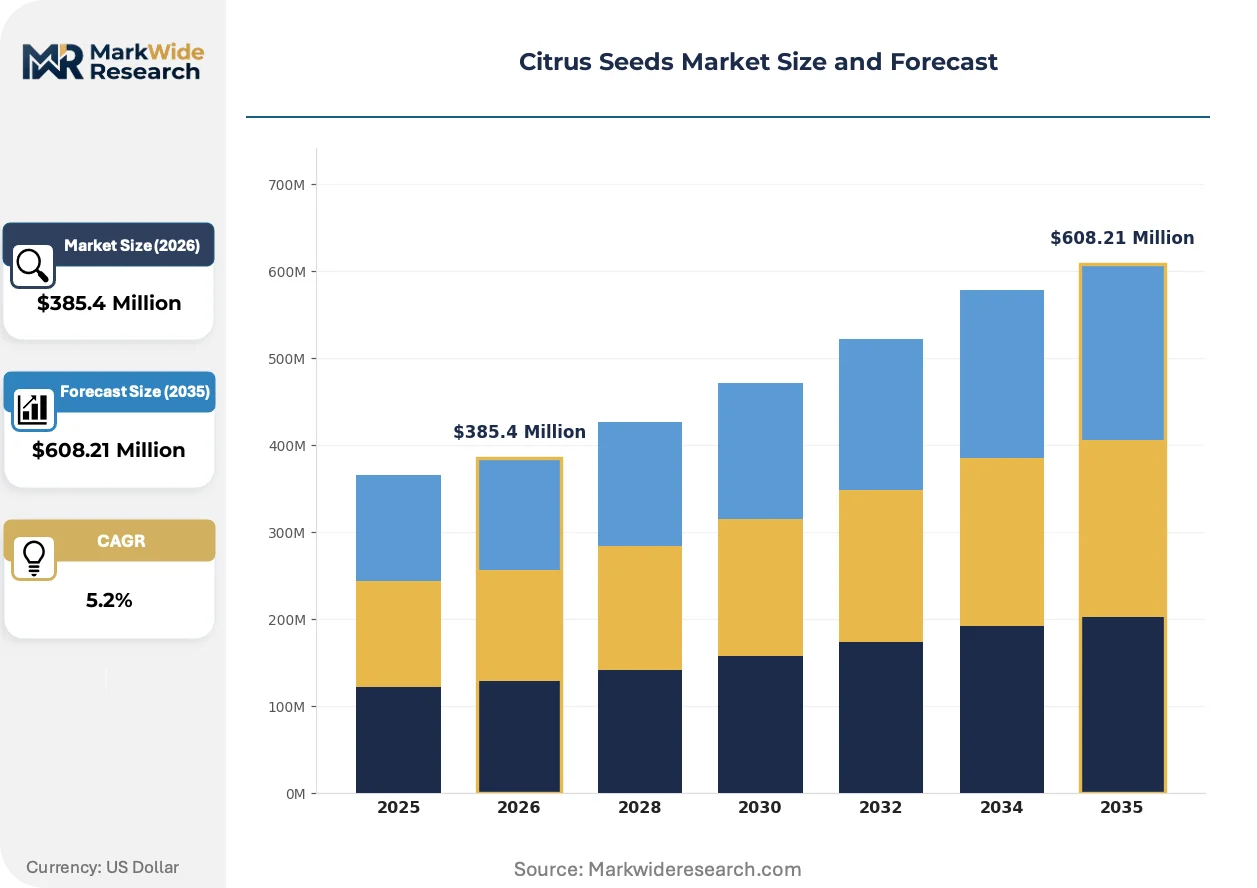
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Orange, Lemon, Grapefruit, Lime End Use Industry: Agriculture, Horticulture, Food Processing, Home Gardening Distribution Channel: Online Retail, Supermarkets, Garden Centers, Wholesale Packaging Type: Bags, Boxes, Jars, Sachets |
| Companies Covered | Louis Dreyfus Company, Citrosuco S.A., Vita-Pakt Citrus Products, Lemon Concentrate S.L., Yantai North Andre Juice Co. Ltd., Sucocitrico Cutrale Ltd., Parchem Trading, Sunkist Growers Inc., Dole Food Company Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus Seeds Market Strategic Shifts
Biotechnology adoption and regulatory tightening are converging to transform how citrus seeds move from orchard to nursery, with propagation control becoming the central competitive battleground.
CRISPR-assisted trait selection is rewriting rootstock breeding economics. Commercial nurseries in Florida and California now deploy gene-edited lines targeting Tristeza virus tolerance. The technology compresses varietal development from decade-long cycles to multi-year programs, enabling faster response to emerging pathogen pressures.
REACH-compliant seed treatment chemistries are reshaping EU import eligibility. The European Chemicals Agency accelerated review timelines for biofumigation alternatives, forcing Brazilian exporters to reformulate scarification protocols. Suppliers with pre-registered treatment regimens capture preferential market access ahead of 2025 compliance deadlines.
Buyer consolidation among integrated juice processors is eliminating spot-market intermediation. São Paulo-based operators now contract directly with certified propagation facilities, bypassing traditional seed traders. This channel compression is most visible in Brazil, where captive supply chains account for the majority of commercial rootstock distribution.
Citrus Seeds Market Segmentation
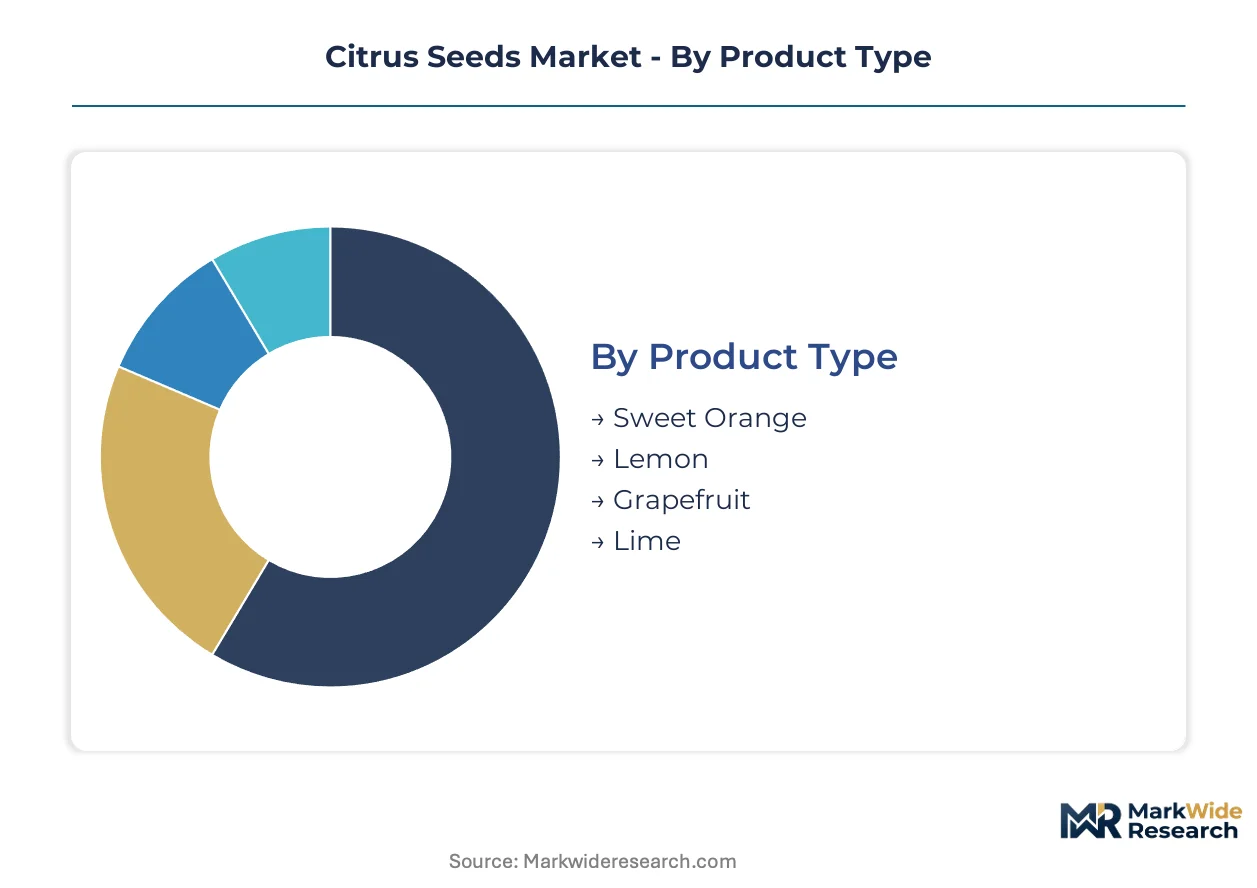
Citrus seed procurement splits sharply between commodity rootstock volume and specialized phytochemical channels. Segmentation reveals how disease pressure and regulatory compliance are reallocating value across product tiers and distribution pathways.
Product Type:
Sweet orange seeds anchor volume demand through established rootstock propagation networks, while grapefruit seeds capture premium positioning in extract markets.
- Sweet Orange:These seeds contain oil-rich cotyledons within lignified teguments requiring stratification for commercial germination. Brazilian integrated juice processors in São Paulo state now internalize sweet orange seed supply through captive propagation facilities, displacing third-party traders.
- Grapefruit:Higher limonoid and flavonoid concentrations drive phytochemical extraction demand for cosmetic and nutraceutical applications. California and Florida nurseries prioritize grapefruit rootstock lines with documented HLB tolerance under USDA quarantine protocols.
- Lemon:Acidic oil profiles suit Mediterranean climate orchards and specialty food-grade extract channels.
- Lime:Mexican and Persian varietal seeds serve distinct regional nursery programs with specific Tristeza virus resistance requirements.
Today's leader: Sweet Orange. Tomorrow's challenger: Grapefruit.
End Use Industry:
Application concentration tracks the shift from open-field seeding to controlled greenhouse protocols.
- Agriculture:Commercial orchard establishment demands certified disease-free rootstock with phytosanitary documentation under MAPA and USDA protocols. Field-seeding of untreated commodity seeds is contracting as HLB pressure forces growers toward greenhouse propagation.
- Horticulture:Protected nursery cultivation achieves germination rates above 75 percent through controlled stratification and chemical scarification. The EU's Plant Health Regulation tightening is redirecting procurement toward suppliers with pre-certified traceability systems.
- Food Processing:Cold-pressed seed oil extraction for flavoring and functional ingredients operates outside rootstock commodity economics.
- Home Gardening:Small-scale demand concentrates through garden center retail with minimal certification requirements.
Agriculture commands current volume. Horticulture shows the steepest expansion trajectory.
Distribution Channel:
Channel structure reflects buyer consolidation among integrated processors and compliance-driven procurement.
- Wholesale:Vertically integrated Brazilian juice processors now contract directly with certified propagation facilities, bypassing traditional seed traders. Bulk transactions dominate commercial rootstock movement with mandatory phytosanitary certification.
- Online Retail:E-commerce penetration is accelerating for home gardening and small-scale horticulture segments, though commercial nurseries remain reluctant due to traceability requirements.
- Garden Centers:Physical retail maintains position in hobbyist and landscaping segments with immediate availability.
- Supermarkets:Limited shelf space for seasonal seed packets targets consumer gardening rather than commercial propagation.
Wholesale retains commercial dominance. Online retail is gaining share fastest in non-certified segments.
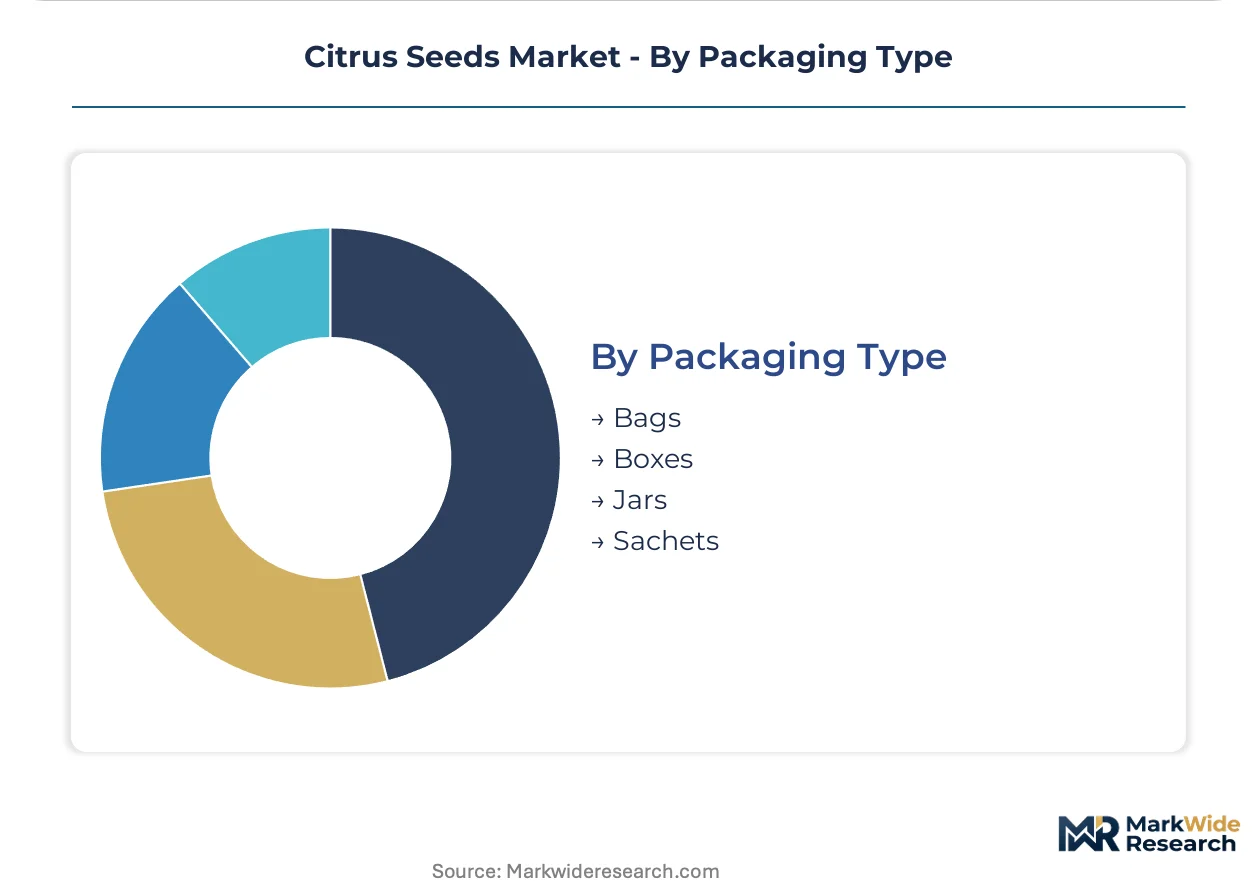
Packaging Type:
Packaging selection tracks seed treatment status and shelf-life requirements across distribution tiers.
- Bags:Laminated multi-layer structures with moisture barriers protect stratified seeds during extended storage. Bulk bag formats serve integrated processors with captive orchards in São Paulo state.
- Sachets:Unit-dose packaging aligns with REACH-compliant treatment chemistries for EU-bound shipments, enabling precise scarification protocol documentation.
- Boxes:Rigid packaging protects embryo viability during international transport under USDA APHIS quarantine handling requirements.
- Jars:Re-sealable containers suit retail horticulture with repeated access needs.
Bags lead commercial volume. Sachets are climbing the fastest on regulatory compliance demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil and the United States operate divergent citrus seed procurement models, with São Paulo's integrated processors controlling captive propagation while California nurseries rebuild certified stock under federal quarantine pressure.
United States
USDA APHIS quarantine protocols on citrus seed imports restrict supplier eligibility to certified propagation facilities with documented HLB screening. Florida's commercial nurseries deploy gene-edited rootstock lines targeting Tristeza virus tolerance through greenhouse protocols. California's Central Valley nurseries scale certified programs to replace disease-compromised orchard stock.
Brazil
São Paulo state concentrates integrated juice processing and captive seed propagation facilities that internalize rootstock supply chains. MAPA phytosanitary certification requirements favor vertically integrated processors over independent traders. The state's captive supply networks now account for the majority of commercial rootstock distribution across Brazilian citrus regions.
Spain
Mediterranean climate orchards drive demand for lemon rootstock lines suited to regional growing conditions. REACH-compliant seed treatment chemistries reshape import eligibility under ECHA accelerated review timelines. Valencia's nursery cluster adapts scarification protocols to meet 2025 compliance deadlines for EU-bound shipments.
China
Yangtze River Delta processing facilities source sweet orange seeds for domestic rootstock propagation networks. The country's national agricultural regulator enforces phytosanitary documentation on imported propagation materials. Shandong Peninsula cold-pressing operations extract citrus seed oil for cosmetic and nutraceutical channels.
Mexico
Jalisco and Veracruz citrus zones source rootstock seeds through wholesale channels tied to North American nursery demand. The country's national plant health authority coordinates with USDA APHIS on cross-border quarantine alignment. Michoacán's propagation facilities serve both domestic orchard establishment and export-oriented supply contracts.
Citrus Seeds Market Competitive Environment
Top-tier vendors anchor integrated processing and captive propagation, while mid-tier traders face margin compression from certification burdens and channel consolidation. The vendor base stratifies across three archetypes: juice processors with backward integration into seed supply, specialized propagation facilities with certified greenhouse capacity, and commodity traders dependent on spot-market intermediation. Competitive moves concentrate on M&A-driven captive orchard acquisition and technology licensing for gene-edited rootstock lines.
Among Brazil-based integrated processors, Citrosuco S.A. and Sucocitrico Cutrale Ltd. exemplify the captive propagation archetype, while Louis Dreyfus Company represents traders with supply chain control extending from Brazilian orchards to international nursery destinations.
| Leading Market Players |
|---|
| Louis Dreyfus Company |
| Citrosuco S.A. |
| Vita-Pakt Citrus Products |
| Lemon Concentrate S.L. |
| Yantai North Andre Juice Co. Ltd. |
| Sucocitrico Cutrale Ltd. |
| Parchem Trading |
| Sunkist Growers Inc. |
| Dole Food Company Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive propagation integration by Brazilian juice processors anchors both supply security and pricing power across the citrus seeds market. São Paulo-based operators internalize rootstock production through backward integration into certified greenhouse facilities, compressing procurement timelines while capturing margin that previously flowed to independent traders.
Pricing Analysis
Capacity additions in Brazil's São Paulo state are reshaping price floors for certified disease-free rootstock seeds. Three-tier pricing structure across certified disease-free, treated commodity, and untreated bulk grades tracks phytosanitary documentation under USDA APHIS and MAPA protocols. Pricing pressure stems from methyl bromide phase-out costs forcing nurseries toward biofumigation alternatives. Independent traders show highest price sensitivity due to working capital strain from extended certification timelines, while integrated processors absorb cost volatility through captive supply.
Supply Chain Analysis
Skilled horticultural technician shortages in Florida and California propagation facilities constrain greenhouse capacity expansion. Supply concentrates in Brazil, the United States, and Spain, with raw material dependencies on certified parent orchard stock, scarification chemistries, and stratification infrastructure. Single-source vulnerability runs through São Paulo's integrated processor networks that control the majority of commercial rootstock distribution. Distribution runs through direct contracts between certified propagation facilities and integrated juice processors, bypassing traditional wholesale intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The citrus seeds market reads as a late-cycle quality story as HLB disease pressure forces demand toward certified disease-free rootstock specifications with full phytosanitary traceability.
For Market Incumbents: Lock in certified propagation capacity through greenhouse facility expansion in California and Florida. Defend against margin compression from biofumigation cost uncertainty by securing pre-registered REACH-compliant treatment chemistries for EU-bound shipments. Prioritize gene-edited rootstock line development through CRISPR licensing to compress varietal breeding timelines. For New Entrants and Emerging Players: Enter via phytochemical extraction channels for grapefruit seed oil serving cosmetic and nutraceutical applications outside commodity rootstock competition. Target Spain's Valencia nursery cluster where REACH compliance deadlines create first-mover openings for suppliers with documented scarification protocols. Lead with sachet-based unit-dose packaging enabling precise treatment documentation for EU regulatory submission. For Investors and Strategic Acquirers: Roll-up economics work for specialized propagation facilities with certified greenhouse capacity because buyer consolidation among integrated processors has eliminated spot-market intermediation. Five-to-ten year viability hinges on captive orchard network control and phytosanitary certification infrastructure. Watch for accelerated EPA registration of biofumigation alternatives as inflection signal for propagation cost structure normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Greenhouse Expansion | Florida and California nurseries scale protected cultivation to achieve germination rates above 75 percent under USDA quarantine. |
| Gene-Edited Rootstock Development | CRISPR-assisted breeding compresses Tristeza virus tolerance development from decade-long cycles to multi-year programs. |
| REACH-Compliant Treatment Registration | Pre-registered biofumigation alternatives capture preferential EU market access ahead of ECHA accelerated review deadlines. |
| Captive Orchard Network Acquisition | Backward integration into certified parent stock secures supply chain control for São Paulo-based integrated processors. |
| Phytochemical Extraction Capacity Buildout | Grapefruit seed oil production for cosmetic channels commands premium positioning outside commodity rootstock economics. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged nursery operations managers at commercial propagation facilities, procurement leads at integrated juice processors, regulatory affairs specialists handling USDA APHIS and MAPA certification, greenhouse cultivation technicians, and seed treatment chemistry suppliers. Secondary validation drew from USDA APHIS quarantine protocol documentation, ECHA REACH registration databases, Brazilian MAPA export certification records, and customs trade data for citrus seed movements. Bottom-up propagation facility capacity estimates triangulated against top-down juice industry rootstock demand projections.
Segment-weighting approaches modeled value and volume across product type, end-use industry, and distribution channel dimensions. Sweet orange and grapefruit seed categories received distinct growth assumptions reflecting divergent rootstock versus phytochemical extraction demand profiles. Agriculture and horticulture end-use splits incorporated greenhouse displacement of field-seeding trends. CAGRs derived from facility capacity expansion pipelines, parent orchard stock availability, and regulatory compliance timeline impacts. Forecast inputs included methyl bromide phase-out schedules and CRISPR trait development commercialization curves.
Inputs from propagation facility operators and integrated processor procurement teams were available through the study window; gaps in long-term gene-edited rootstock adoption rates introduce uncertainty bands around penetration assumptions. Forecasts reflect documented assumptions on certification timeline compression and biofumigation cost normalization. Material deviation in EPA alternative treatment registration pace or ECHA enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
North America Seeds Market
Seeds
Hemp Seeds Market
Seeds
North America Forage Seed Market
Seeds
Africa Peas Market
Seeds
Organic Sesame Seed Market
Seeds
India Forage Seed Market
Seeds
Ghana Seeds Market
Seeds
Global Fruit and Vegetable Seeds Market
Seeds
Americas Seeds Market
Seeds
Spain Forage Seed Market
Seeds
Dodder Seed Market
Seeds
India Vegetable Seed Market
Seeds
Asparagus Seeds Market
Seeds
South America Forage Seed Market
Seeds
Russia Seed Market
Seeds
South America Vegetable Seed Market