
 Africa Chia Seeds Market | 2026-2036
Africa Chia Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Chia Seeds Market Outlook
Kenya's Rift Valley is fragmenting as smallholder cooperatives scale chia cultivation alongside commercial estates. Kenya Chia Seed Farmers Cooperative leverages collective bargaining to secure better seed pricing and processing contracts. African Chia anchors its operations in Tanzanian highlands, controlling organic certification pipelines for European buyers. Navitas Organics competes through established North African distribution partnerships that extend shelf reach in Moroccan and Egyptian retail channels.
Chia seeds are the edible grains of Salvia hispanica, containing approximately 34-40% oil by weight with alpha-linolenic acid as the dominant omega-3 fatty acid, primarily used as a functional food ingredient for texture modification and nutritional fortification. Organic chia seeds command premium positioning due to stringent EU import protocols and limited certified acreage across East Africa. The food industry application leads volume absorption, while nutritional supplements extract higher per-unit margins through direct-to-consumer channels and specialized health food stores.
Kenya's national agricultural regulator and Tanzania's crop export authority shape market access through phytosanitary certification and organic equivalency agreements with European import frameworks. FSSAI-equivalent standards in South Africa and Nigeria's national food safety codes determine product eligibility for West African retail expansion. Stakeholders must monitor evolving organic certification reciprocity between African producer states and EU regulatory bodies to secure long-term export viability.
Market Dynamics
East African smallholder cooperatives are consolidating cultivation acreage around Mount Kenya and Tanzania's Southern Highlands, creating collective bargaining power that redirects margin capture from traders toward farming clusters.
Growth Catalysts
- EU organic equivalency agreements:Tanzania's crop export authority has secured streamlined phytosanitary certification pathways, reducing border delays for certified consignments bound for European food manufacturers.
- Functional food ingredient demand:Nigerian health-conscious households are absorbing chia-enriched nutritional supplements through direct-to-consumer channels, expanding the addressable consumer base beyond traditional retail.
- Mount Kenya farming clusters:Concentrated cultivation around this geographic hub enables shared processing infrastructure and quality standardization that lowers unit costs for export-grade seed.
Market Restraints
- Input cost volatility:Organic certification compliance costs and irrigation infrastructure requirements strain smallholder balance sheets during drought cycles in Kenya's Rift Valley.
- Supply concentration risk:Dependence on a narrow corridor of high-altitude farming clusters in Tanzania's Southern Highlands exposes volume planning to localized weather disruptions.
- Technical limitation:Post-harvest oil degradation in alpha-linolenic acid content restricts shelf-life extension for bulk shipments to distant processing facilities.
Strategic Opportunities
- Underpenetrated West African retail:Nigeria's national food safety codes are stabilizing, creating eligibility pathways for chia-based products in Lagos and Abuja supermarket chains.
- Emerging cosmetic application:Chia oil extraction for skincare formulations is gaining traction among Moroccan and Egyptian personal care manufacturers seeking natural emollient alternatives.
- Distribution innovation:Cooperative-owned e-commerce platforms are disintermediating traditional export brokers, enabling Kenyan smallholders to capture premium pricing from European specialty buyers.
Industry Challenges
- Certification timeline compression:EU regulatory bodies are tightening organic certification reciprocity audits, forcing East African exporters to accelerate documentation workflows.
- Skill gap in quality assurance:Laboratory testing capacity for omega-3 fatty acid profiling remains concentrated in Nairobi and Dar es Salaam, creating bottlenecks for rural cooperative samples.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Chia Seeds Market |
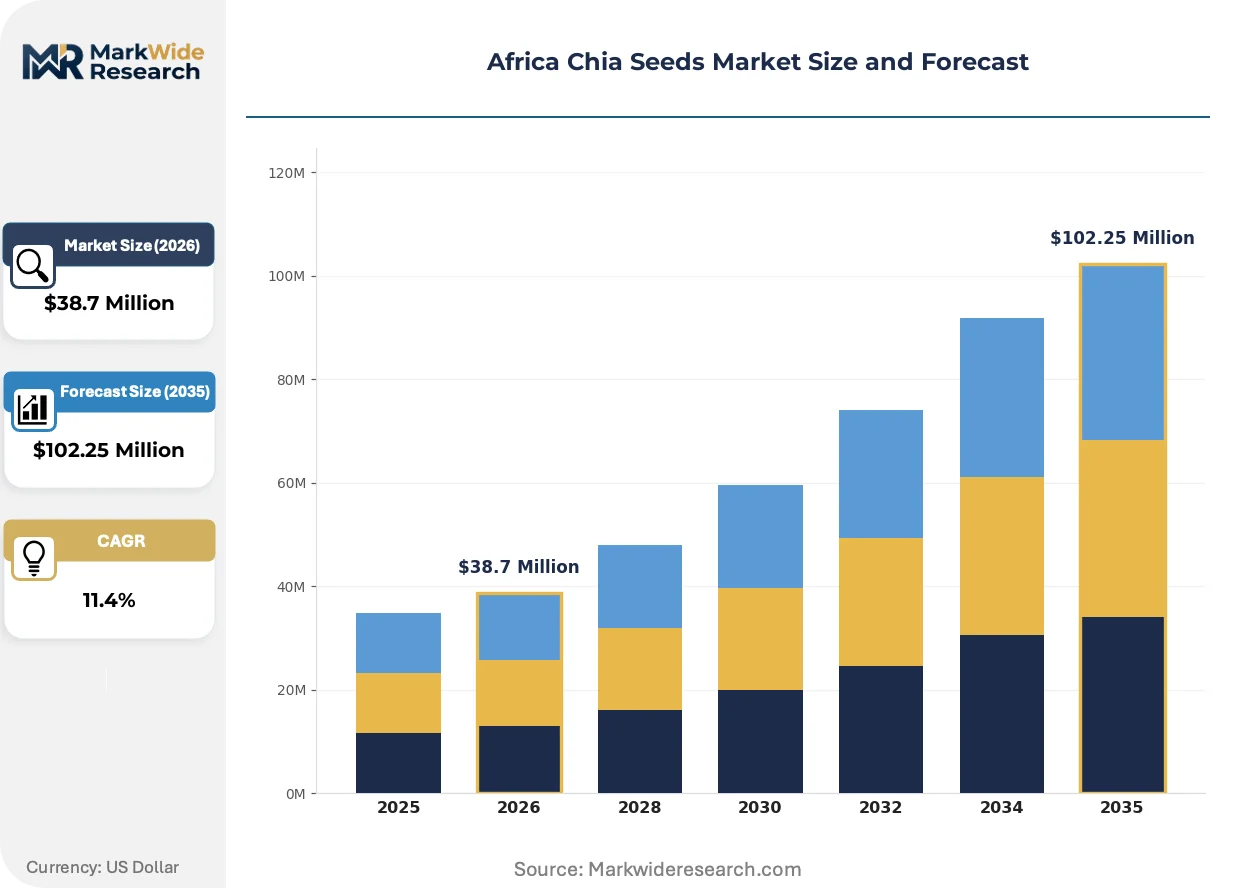
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $102.25 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Chia Seeds, Conventional Chia Seeds, White Chia Seeds, Black Chia Seeds Application: Food Industry, Beverage Products, Nutritional Supplements, Bakery Products Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops End User: Households, Food Manufacturers, Health Enthusiasts, Athletes |
| Companies Covered | Kenya Chia Seed Farmers Cooperative, Ubelhor, Chia Seed Company, Spectrum Organic Products, Talia Group, African Chia, Eden Foods, Navitas Organics, Tanzania Chia Co. Ltd, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Chia Seeds Market Strategic Shifts
Mechanical harvesting technologies and blockchain traceability systems are compressing cost structures and authentication timelines across East African chia supply chains.
Mechanical seed harvesting equipment is collapsing labor-intensive manual collection cycles in Kenya's Rift Valley cooperatives. Commercial estates and large smallholder collectives are deploying modified combine systems originally developed for sesame. This technology is collapsing the seasonal labor bottleneck that previously constrained peak-harvest volume throughput.
Kenya's agricultural regulator has mandated digital phytosanitary certificates for all superfood crop exports, eliminating paper-based authentication delays. The industrial consequence is accelerated customs clearance at Mombasa port for organic-certified consignments. Tanzanian highland exporters are responding by retrofitting existing certification workflows to interface with Kenya's digital platform architecture.
Direct purchasing contracts between European health food brands and East African cooperatives are displacing multi-layered broker networks. Specialty retailers in Germany and the Netherlands are establishing minimum-volume commitments with named farming clusters. This pattern is most visible in Mount Kenya cooperatives that have secured three-year offtake agreements with omega-3 supplement manufacturers.
Africa Chia Seeds Market Segmentation
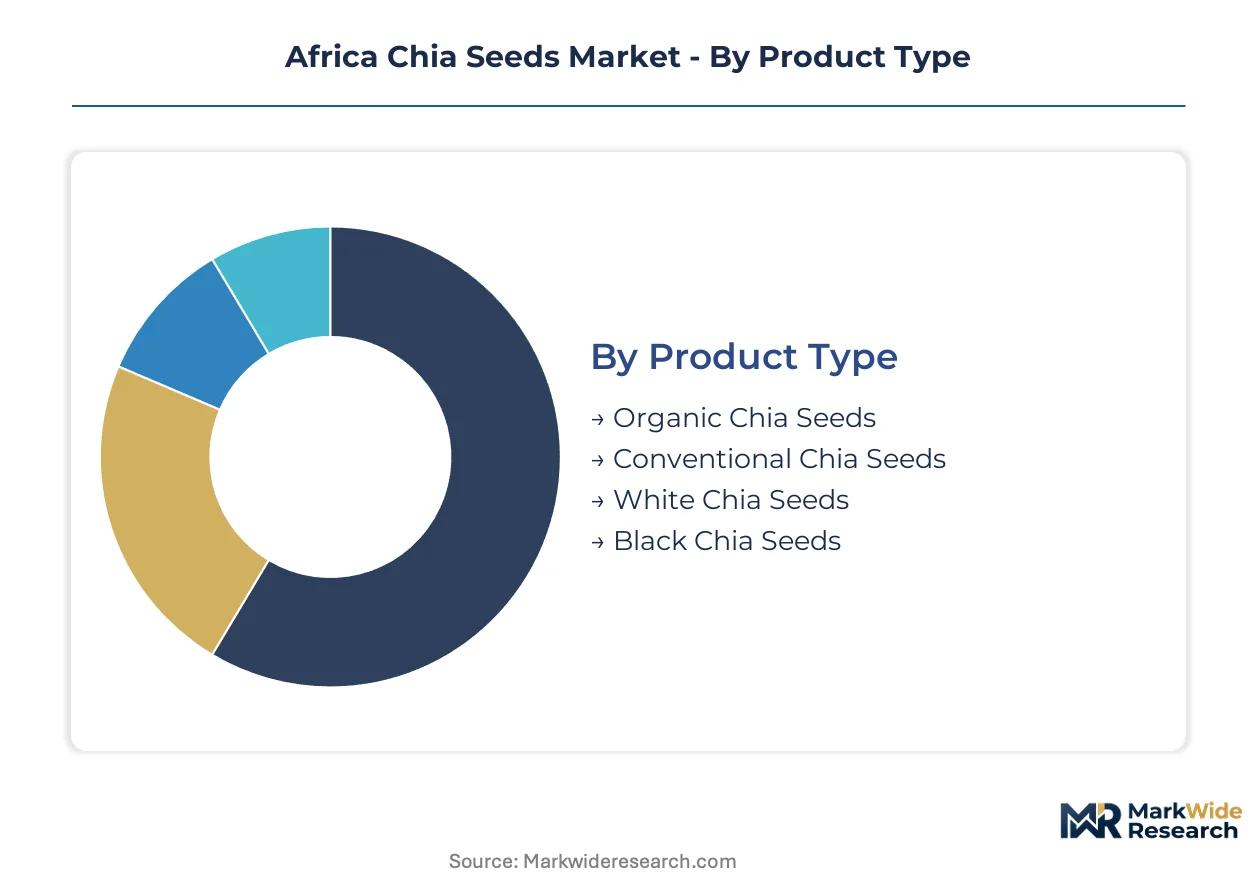
Chia seed segmentation across Africa reveals how certification premiums, functional positioning, and channel access create distinct commercial tiers. Understanding these divides exposes where margin capture concentrates and which buyer profiles command supplier attention.
Product Type:
Certification tier and seed coloration separate pricing bands and export eligibility across East African supply chains.
- Organic Chia Seeds:These seeds carry EU organic equivalency certification, requiring three-year conversion periods and residue-free cultivation protocols. German and Dutch health food brands concentrate procurement around Mount Kenya cooperatives that have secured multi-year offtake agreements.
- Conventional Chia Seeds:Non-certified production dominates volume output in Tanzania's Southern Highlands, serving price-sensitive African regional markets and bulk ingredient processors. Input cost pressures from irrigation infrastructure and fertilizer prices constrain smallholder margins during drought cycles.
- White Chia Seeds:Pale seed variants command aesthetic premiums in bakery applications and visual-forward packaged goods.
- Black Chia Seeds:Dark-hued seeds retain traditional nutritional positioning and broader culinary versatility across West African retail channels.
Organic Chia Seeds holds installed capacity. White Chia Seeds is rotating up the share rankings.
Application:
End-use function determines processing requirements, margin extraction, and regulatory scrutiny intensity.
- Food Industry:Bulk ingredient absorption by manufacturers of cereals, snack bars, and dairy alternatives requires standardized oil content and moisture specifications. Nigerian food safety codes are stabilizing eligibility for chia-enriched products in Lagos supermarket chains.
- Nutritional Supplements:Direct-to-consumer capsules and powders extract premium pricing through omega-3 fatty acid content claims. Laboratory testing capacity for alpha-linolenic acid profiling remains bottlenecked in Nairobi and Dar es Salaam, slowing rural cooperative sample turnaround.
- Beverage Products:Hydration drinks and smoothie bases incorporate chia for texture modification and nutritional fortification.
- Bakery Products:Artisan and industrial bakeries utilize chia for moisture retention and clean-label ingredient positioning.
Food Industry holds installed capacity. Nutritional Supplements is climbing the fastest.
Distribution Channel:
Channel structure dictates margin distribution between producers, intermediaries, and final price realization.
- Health Food Stores:Specialized retailers in Morocco and Egypt stock chia alongside complementary superfoods, targeting health-conscious urban consumers with premium positioning. Navitas Organics leverages established North African distribution partnerships to extend shelf reach.
- Online Retail:Cooperative-owned e-commerce platforms are disintermediating traditional export brokers, enabling Kenyan smallholders to capture premium pricing from European specialty buyers through direct purchasing contracts.
- Supermarkets:Mass retail chains in Abuja and Johannesburg are expanding chia shelf space as consumer familiarity broadens.
- Specialty Shops:Independent organic and natural product retailers serve niche demand in East African urban centers.
Health Food Stores holds installed capacity. Online Retail is gaining share fastest.
End User:
Buyer sophistication and volume scale create divergent service requirements and contract structures.
- Food Manufacturers:Industrial buyers demand consistent supply volumes, quality documentation, and traceability systems for ingredient integration. Blockchain authentication is compressing verification timelines for contract-bound farming clusters.
- Health Enthusiasts:Individual consumers seeking functional nutrition drive direct-to-consumer channel expansion and subscription purchasing models.
- Households:Domestic cooking and baking applications absorb retail-packaged volumes through conventional grocery channels.
- Athletes:Performance-oriented consumers prioritize protein content and recovery positioning in specialized sports nutrition formulations.
Food Manufacturers holds installed capacity. Health Enthusiasts is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East African highlands concentrate certified organic production, while West African urban centers absorb retail volume growth. Kenya and Tanzania dominate export-grade cultivation through phytosanitary-aligned farming clusters. Nigeria and South Africa anchor domestic consumption expansion with evolving food safety frameworks.
Kenya
Mount Kenya farming clusters supply EU-certified organic chia through collective bargaining structures. Kenya's agricultural regulator mandates digital phytosanitary certificates for all superfood exports, eliminating paper-based delays at Mombasa port. Rift Valley cooperatives deploy mechanical harvesting equipment to collapse seasonal labor bottlenecks.
Tanzania
Southern Highlands estates control organic certification pipelines for German and Dutch health food manufacturers. Tanzania's crop export authority secured streamlined EU equivalency agreements, reducing border delays for certified consignments. African Chia anchors operations here, managing traceability systems for European specialty buyers.
Nigeria
Lagos and Abuja supermarket chains expand chia shelf space as health-conscious households drive nutritional supplement uptake. Nigeria's national food safety codes are stabilizing eligibility pathways for chia-enriched products. Direct-to-consumer channels bypass traditional retail infrastructure in urban centers.
South Africa
Johannesburg mass retail chains integrate chia into mainstream grocery categories beyond health food niches. FSSAI-equivalent standards determine product eligibility for regional distribution networks. Post-harvest processing capacity concentrates in Gauteng province for quality standardization.
Morocco and Egypt
Casablanca and Cairo health food stores stock chia alongside complementary superfoods targeting urban wellness consumers. Navitas Organics leverages established North African distribution partnerships to extend shelf reach. Personal care manufacturers in both markets experiment with chia oil extraction for natural emollient formulations.
Africa Chia Seeds Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in certification and cultivation. The Africa chia seeds market structures around cooperative collectives, commercial estate operators, and international brand distributors. Three archetypes dominate: smallholder cooperatives with collective bargaining power, vertically integrated estate operators controlling organic pipelines, and North American/European brand owners managing distribution reach. Competitive dynamics center on organic certification acquisition and direct purchasing contract negotiation.
Among cooperative-based cultivators, Kenya Chia Seed Farmers Cooperative represents collective bargaining archetypes securing multi-year offtake agreements. African Chia occupies a position within vertically integrated estate operations, anchoring Tanzanian highland production for European buyers. Navitas Organics exemplifies international brand distributors leveraging established North African partnerships.
| Leading Market Players |
|---|
| Kenya Chia Seed Farmers Cooperative |
| Ubelhor |
| Chia Seed Company |
| Spectrum Organic Products |
| Talia Group |
| African Chia |
| Eden Foods |
| Navitas Organics |
| Tanzania Chia Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Kenya's Rift Valley mechanical harvesting infrastructure is compressing seasonal labor costs and shifting supplier bargaining power toward cooperatives that control peak-season throughput. This utilization squeeze forces commercial estates to absorb upfront equipment investment or cede margin to collective bargaining structures, while EU organic equivalency certification creates tiered price floors that insulate certified clusters from spot-market volatility.
Pricing Analysis
EU organic equivalency agreements dictate the pricing tier structure across East African export channels, separating premium-certified Mount Kenya cooperatives from conventional Southern Highlands output. Three-tier pricing structure across organic premium, EU-compliant standard, and regional economy levels reflects certification investment, alpha-linolenic acid testing documentation, and volume scale. Price differentiation hinges on phytosanitary compliance costs and laboratory testing access in Nairobi and Dar es Salaam. Cost compression in conventional tiers is intensifying because drought cycles strain smallholder irrigation infrastructure. Food manufacturers commanding multi-year offtake contracts show lowest price sensitivity; regional bulk traders absorbing non-certified Tanzanian volume exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between Tanzania and EU destination markets dominates supply chain risk planning as equivalency agreement renegotiations loom. Geographic supply concentration centers on Kenya's Mount Kenya corridor, Tanzania's Southern Highlands, and emerging Nigerian cultivation clusters in Plateau State. Raw material dependencies include irrigation equipment, organic fertilizer inputs, and alpha-linolenic acid testing reagents. Single-source vulnerability concentrates in phytosanitary certification workflows managed through Kenya's agricultural regulator digital platform. Distribution runs through Mombasa port consolidation for European health food manufacturers, cooperative-owned e-commerce platforms for direct specialty sales, and Lagos-Abuja retail channels for West African domestic absorption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat where EU organic equivalency certification creates switching costs that lock in multi-year offtake relationships and deflect price-based competition.
For Market Incumbents: Entrench certification pipelines through backward integration into laboratory testing capacity in Nairobi and Dar es Salaam, eliminating rural cooperative sample bottlenecks that threaten contract fulfillment. Deepen channel control by acquiring cooperative-owned e-commerce platforms displacing traditional export brokers. Margin pressure from mechanical harvesting equipment leasing costs demands captive supply of processing infrastructure to defend premium positioning against emerging Tanzanian estate operators.
For New Entrants and Emerging Players: Establish a beachhead in Nigeria's nutritional supplement direct-to-consumer channel where food safety code stabilization is creating first-mover eligibility advantages. White-space targets include Lagos supermarket chain shelf expansion and Abuja health-conscious household subscription models. Go-to-market angle centers on FSSAI-equivalent compliance documentation that unlocks South African regional distribution networks.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Mount Kenya cooperatives with multi-year European offtake agreements and embedded organic certification pipelines. Long-term viability over a multi-year horizon rests on regulatory reciprocity durability between African producer states and EU import frameworks. Acquisition target archetype: vertically integrated estate operators controlling Tanzanian highland organic acreage with traceability systems already deployed. Signal to watch: compression in EU organic certification audit timelines indicating regulatory capacity expansion or equivalency agreement stress.
| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Pipeline Expansion | EU equivalency agreement maintenance secures premium export tier access for Mount Kenya clusters. |
| Mechanical Harvesting Technology Deployment | Modified combine systems collapse seasonal labor bottlenecks in Kenya's Rift Valley cooperatives. |
| Direct-to-Consumer Channel Development | Cooperative-owned e-commerce platforms disintermediate traditional export brokers for European specialty buyers. |
| Laboratory Testing Capacity Investment | Nairobi and Dar es Salaam omega-3 profiling facilities eliminate rural cooperative sample turnaround delays. |
| West African Retail Distribution Expansion | Lagos and Abuja supermarket shelf space captures Nigerian health-conscious household nutritional supplement demand. |
Study Parameters
A spread of perspectives from cooperative cultivation managers, export certification officers, European health food procurement leads, and Nigerian retail category buyers converged on the working assumptions governing volume and value trajectories. Primary interviews with East African smallholder collective leadership and Tanzanian estate operations directors combined with secondary validation from Kenya's agricultural regulator phytosanitary disclosure records, Tanzania's crop export authority equivalency documentation, EU organic import compliance databases, and Nigerian national food safety code filings. Bottom-up acreage and yield estimates triangulated against top-down European import absorption data.
Demand-supply balance modeling across the analysis window integrated cultivation capacity expansion in Mount Kenya and Southern Highlands clusters against German and Dutch health food manufacturer procurement commitments. Segmentation dimensions included certification tier, application function, distribution channel structure, and end-user sophistication. CAGRs derived from recursive substitution of annual volume assumptions against price trajectory inputs. Industry-specific forecast inputs encompassed drought cycle frequency in Rift Valley growing regions and EU organic certification audit timeline compression.
Stress conditions across drought severity, equivalency agreement renegotiation outcomes, and mechanical harvesting equipment import cost fluctuations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding phytosanitary certification digital platform adoption rates and cooperative consolidation velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Fruit and Vegetable Seeds Market
Seeds
Europe Vegetable Seed Market
Seeds
Vietnam Seed Market
Seeds
Poppy Seed Market
Seeds
Sprouted Grains and Seeds Market
Seeds
Pigeon Pea Market
Seeds
Okra Seed Market
Seeds
South America Quinoa Seeds Market
Seeds
Pasture Seeds Market
Seeds
Australia Forage Seed Market
Seeds
Watermelon Seeds Market
Seeds
Europe Cannabis Seeds Market
Seeds
Wax Gourd Seed Market
Seeds
Flaxseed (Linseed) Market
Seeds
Celery Seed Oil Market
Seeds
South America Chia Seeds Market