
 Sweet Corn Seeds Market | 2026-2036
Sweet Corn Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Sweet Corn Seeds Market Analytics
Food processing demand is shifting toward higher-sugar, tender-kernel varieties that suit frozen and canned product lines. Syngenta leverages its vegetable seed platform to supply processors with uniform-ripening hybrids. Bayer anchors its position through digital farming tools bundled with seed portfolios. Corteva Agriscience competes via its broad germplasm library and regional adaptation programs.
Sweet corn seeds are sexually propagated kernels of Zea mays saccharata bred for elevated soluble sugar content, typically harvested at the milk stage before polysaccharide conversion advances. Hybrid varieties dominate commercial acreage due to heterosis expression in yield, ear uniformity, and disease resistance, while open-pollinated types persist in home gardening and heritage farming niches. The food processing segment commands premium pricing for contract-specified traits such as kernel depth and husk protection. Agricultural stores and wholesale channels still handle the bulk of volume, though online retail is capturing smaller-scale growers seeking specialty organic and non-GMO labels.
The USDA regulates interstate seed commerce through the Federal Seed Act, while the EPA oversees pesticide-treated seed registrations that affect coated and inoculated product lines. China's Ministry of Agriculture and Rural Affairs enforces varietal approval and seed production licensing under its national seed law framework. Breeders and distributors must track evolving phytosanitary protocols and gene-editing classification decisions across multiple jurisdictions to secure market access.
Market Dynamics
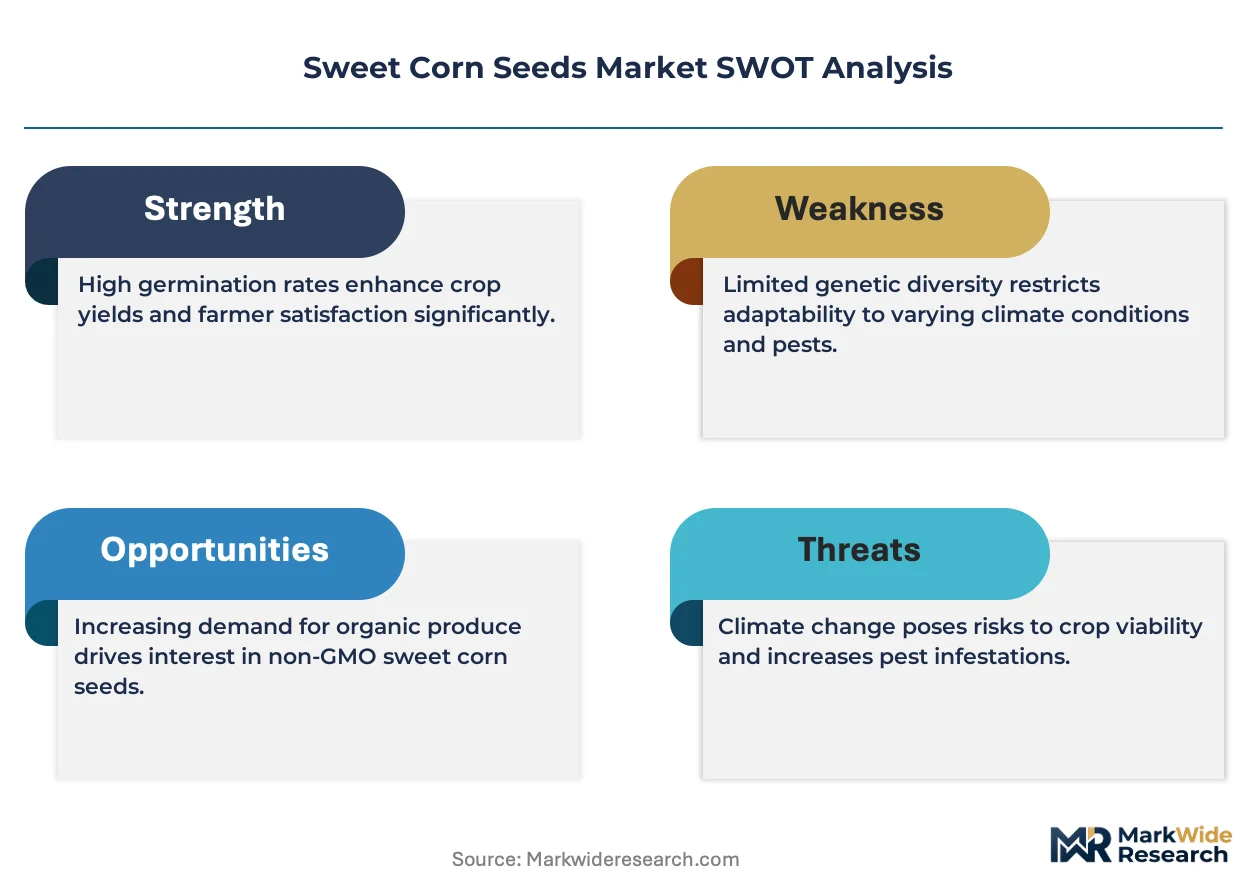
Gene-editing acceleration through CRISPR-Cas9 systems is compressing varietal development cycles from eight years to under four, forcing seed houses to restructure R&D workflows and intellectual property strategies around accelerated trait validation pipelines.
Growth Catalysts
- Fresh Processing Demand:Frozen food manufacturers in the United States are contracting directly with seed suppliers for tender-kernel hybrids with specified sugar retention profiles, bypassing traditional commodity channels.
- EPA Seed Treatment Framework:Streamlined pesticide-coated seed registrations under the Federal Insecticide, Fungicide, and Rodenticide Act are reducing time-to-market for disease-resistant inoculated varieties.
- Marker-Assisted Selection:DNA marker platforms are enabling breeders to stack multiple disease-resistance loci without phenotypic screening delays, accelerating hybrid release schedules.
Market Restraints
- Parent Line Concentration:Elite inbred germplasm for heterotic hybrid production concentrates among three major breeding programs, creating supply vulnerability for independent seed distributors.
- Input Cost Volatility:Nitrogen fertilizer price swings directly compress contract farmer margins, reducing replanting rates and seed purchase volumes in price-spike years.
- Regulatory Divergence:China's SAMR classification of gene-edited crops under distinct approval pathways from transgenic varieties creates dual-track compliance burdens for multinational breeders.
Strategic Opportunities
- Urban Vertical Farming:Controlled-environment agriculture operators in Singapore and the Netherlands are piloting dwarf sweet corn varieties for year-round local production, creating premium seed demand outside traditional row-crop geographies.
- Organic Channel Expansion:E-commerce platforms serving home gardeners are capturing specialty open-pollinated and heirloom varieties with non-GMO verification, bypassing agricultural wholesale networks.
- EU Green Deal Incentives:Carbon farming certification schemes under the EU's Common Agricultural Policy are rewarding nitrogen-efficient corn varieties, creating pull-through for low-input hybrid development.
Industry Challenges
- Gene-Editing Patent Thickets:Overlapping intellectual property claims on CRISPR delivery methods in maize are forcing licensing negotiations that delay commercial trait deployment.
- Phenotyping Bottleneck:Automated high-throughput field screening systems require capital investments exceeding mid-tier breeding program capacities, widening capability gaps between seed house tiers.
- Phytosanitary Recertification:Evolving seed health testing protocols for maize lethal necrosis virus are disrupting cross-border seed shipments and requiring redundant laboratory infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweet Corn Seeds Market |
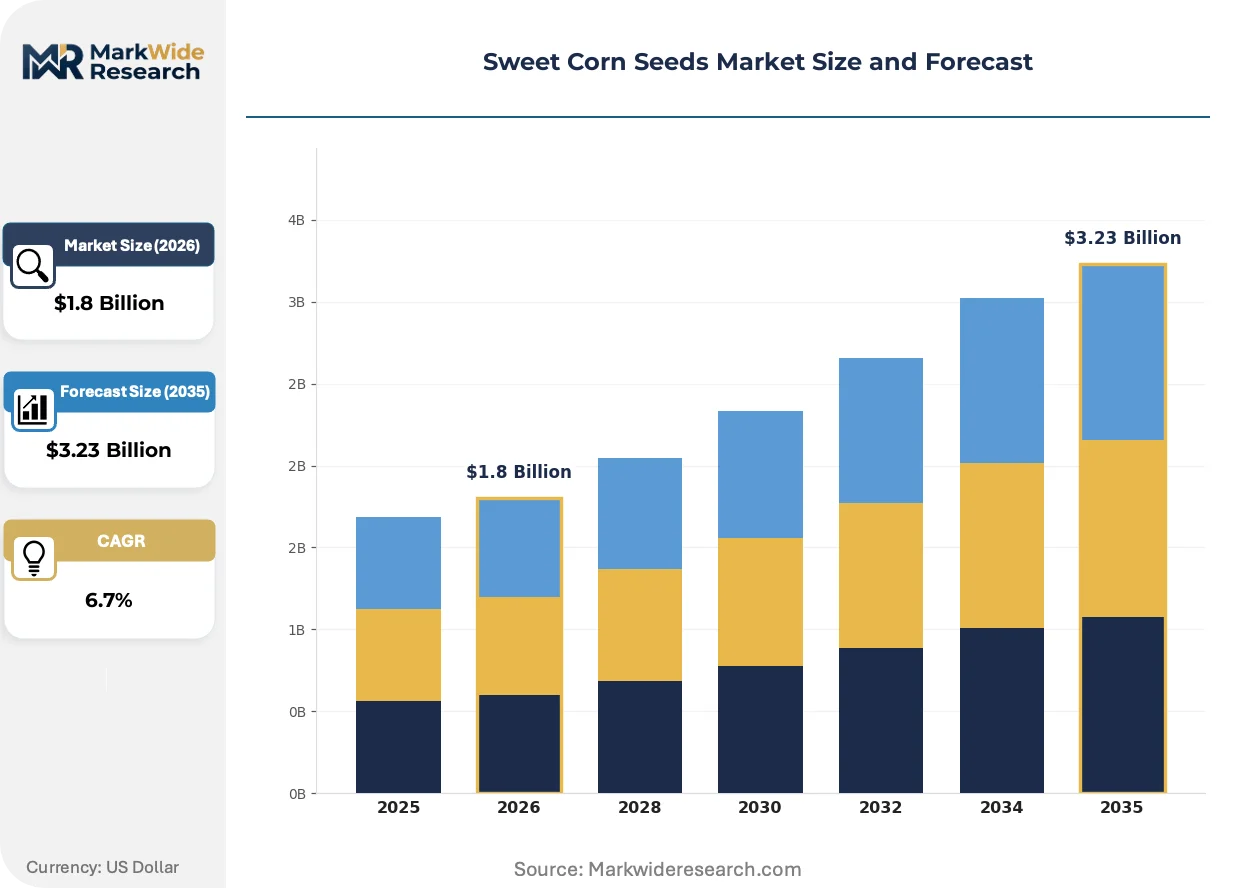
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid, Open-Pollinated, Organic, Non-GMO End Use Application: Agricultural, Food Processing, Home Gardening, Animal Feed Distribution Channel: Online Retail, Agricultural Stores, Supermarkets, Wholesale Seed Treatment: Untreated, Coated, Treated, Inoculated |
| Companies Covered | Syngenta, Bayer, Corteva Agriscience, KWS SAAT SE, Sakata Seed Corporation, Advanta Seeds, Limagrain, Takii & Co., Enza Zaden, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweet Corn Seeds Market Evolving Landscape
Digital breeding infrastructure is fusing with molecular biology platforms to compress trait-to-market timelines, while regulatory frameworks scramble to classify gene-edited outputs and demand patterns fragment across industrial processing, fresh retail, and direct-to-consumer channels.
Genomic selection is converging with unmanned aerial vehicle phenotyping to enable real-time canopy assessment during inbred line development. Mid-sized seed houses in Brazil and Argentina are adopting these integrated platforms to bypass traditional multi-location yield trial networks. The technology compression is enabling regional breeders to compete with centralized R&D operations on trait turnaround speed.
China's NMPA seed varietal approval system is tightening documentation requirements for imported germplasm with novel trait stacks, extending registration timelines for multinational submissions. Domestic seed producers with established local trial networks are capturing first-mover advantage in gene-edited waxy corn segments. Processors in Shandong and Guangdong provinces are adjusting procurement specifications to favor pre-approved domestic hybrid lines.
Contract specifications from frozen food processors are displacing commodity-grade seed purchasing across the North American Corn Belt. Sysco and McCain Foods are mandating kernel depth, row count, and husk tightness parameters that require dedicated hybrid development programs. This specification-driven procurement is concentrating seed supply relationships around processor-aligned breeding houses in Illinois and Minnesota.
Sweet Corn Seeds Market Segmentation
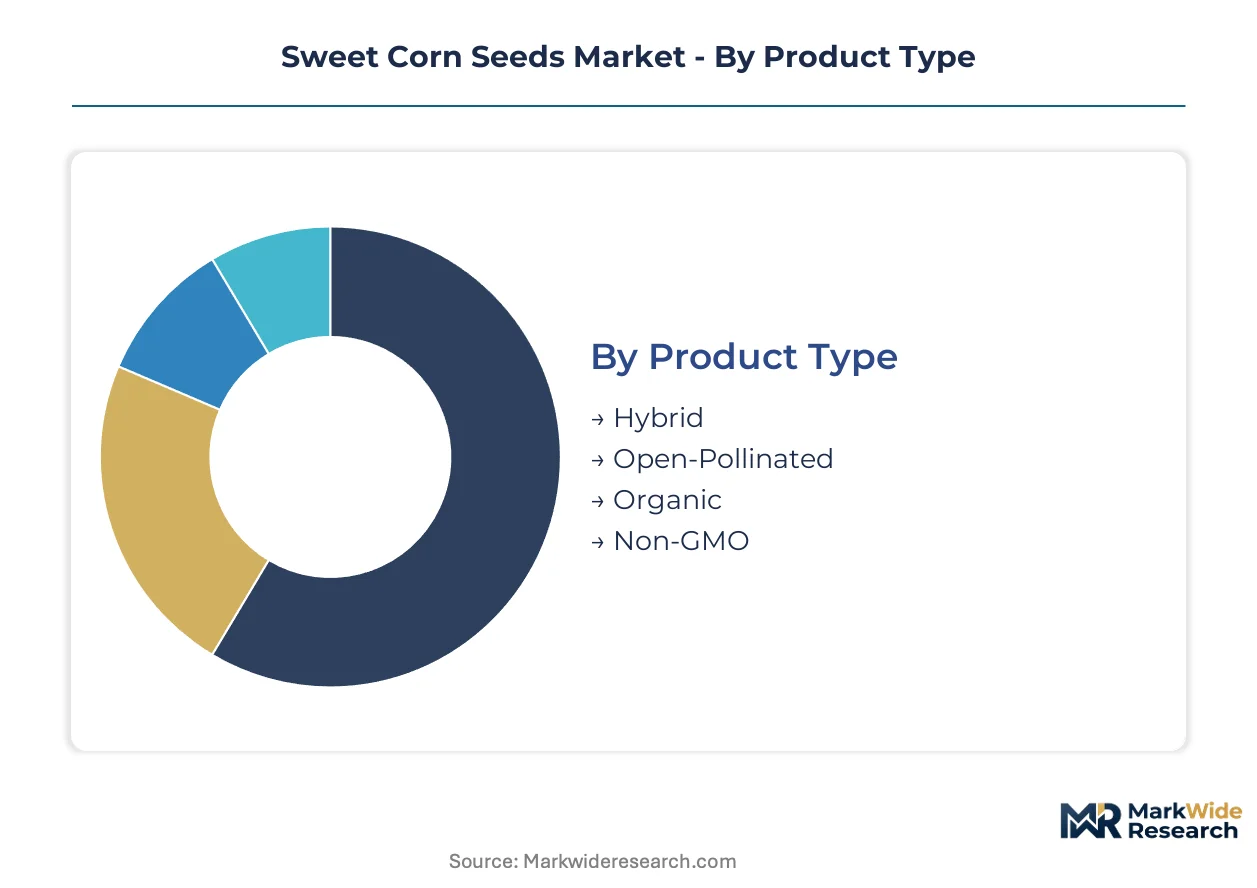
Sweet corn seed purchasing fragments across distinct buyer profiles with incompatible technical requirements. Processor contracts demand uniform-ripening genetics with specified kernel architecture, while home gardeners prioritize flavor diversity and seed-saving legality.
Product Type:
Volume concentration sits with commodity-grade hybrids, while premium pricing attaches to certified organic and verified non-GMO categories.
- Hybrid:F1 crosses exploit heterosis for standardized ear size, disease resistance, and synchronized maturity. Frozen food processors in the United States and Brazil contract exclusively for hybrid lines with documented sugar retention curves and husk protection scores.
- Open-Pollinated:Stable genetic lines enable farmer seed saving and regional adaptation through repeated selection cycles. Heritage farming operations and seed sovereignty advocates in Mexico and the American Midwest maintain demand for open-pollinated varieties despite yield penalties.
- Organic:Certified production excludes synthetic inputs and requires documented isolation distances from conventional pollen sources.
- Non-GMO:Identity-preserved supply chains with third-party verification command 15-25% premiums over commodity hybrids in European and North American retail channels.
Mature deployment sits with Hybrid. Newer deployment is concentrated in Organic.
End Use Application:
Application-driven segmentation separates industrial procurement with technical specifications from discretionary purchasing with aesthetic preferences.
- Food Processing:Frozen and canned manufacturers impose strict contract terms on kernel depth, row count, and sugar-to-starch ratios at harvest. McCain Foods and Sysco mandate dedicated hybrid development programs with Illinois and Minnesota breeding houses.
- Agricultural:Fresh-market growers prioritize appearance traits including husk color, flag leaf retention, and tip fill for roadside and wholesale distribution.
- Home Gardening:Small-scale growers select for flavor novelty, ornamental value, and seed-saving legality rather than yield maximization.
- Animal Feed:Silage-oriented varieties emphasize total digestible nutrients and fiber digestibility over human-consumption quality standards.
Established infrastructure serves Agricultural. Steepest expansion trajectory belongs to Food Processing.
Distribution Channel:
Channel structure reflects scale economies in logistics versus information intensity in specialty positioning.
- Wholesale:Bulk seed moves through distributor networks serving commercial row-crop operations with volume discounts and credit terms tied to planting seasonality.
- Agricultural Stores:Local input suppliers provide technical advice, custom seed treatment, and delivery coordination for mid-scale growers.
- Online Retail:E-commerce platforms capture home gardeners and organic producers seeking heirloom varieties, detailed variety descriptions, and non-GMO verification documentation.
- Supermarkets:Mass-market retail chains stock limited seasonal offerings with minimal technical support or genetic transparency.
Volume leadership remains with Wholesale. Gaining share fastest is Online Retail.
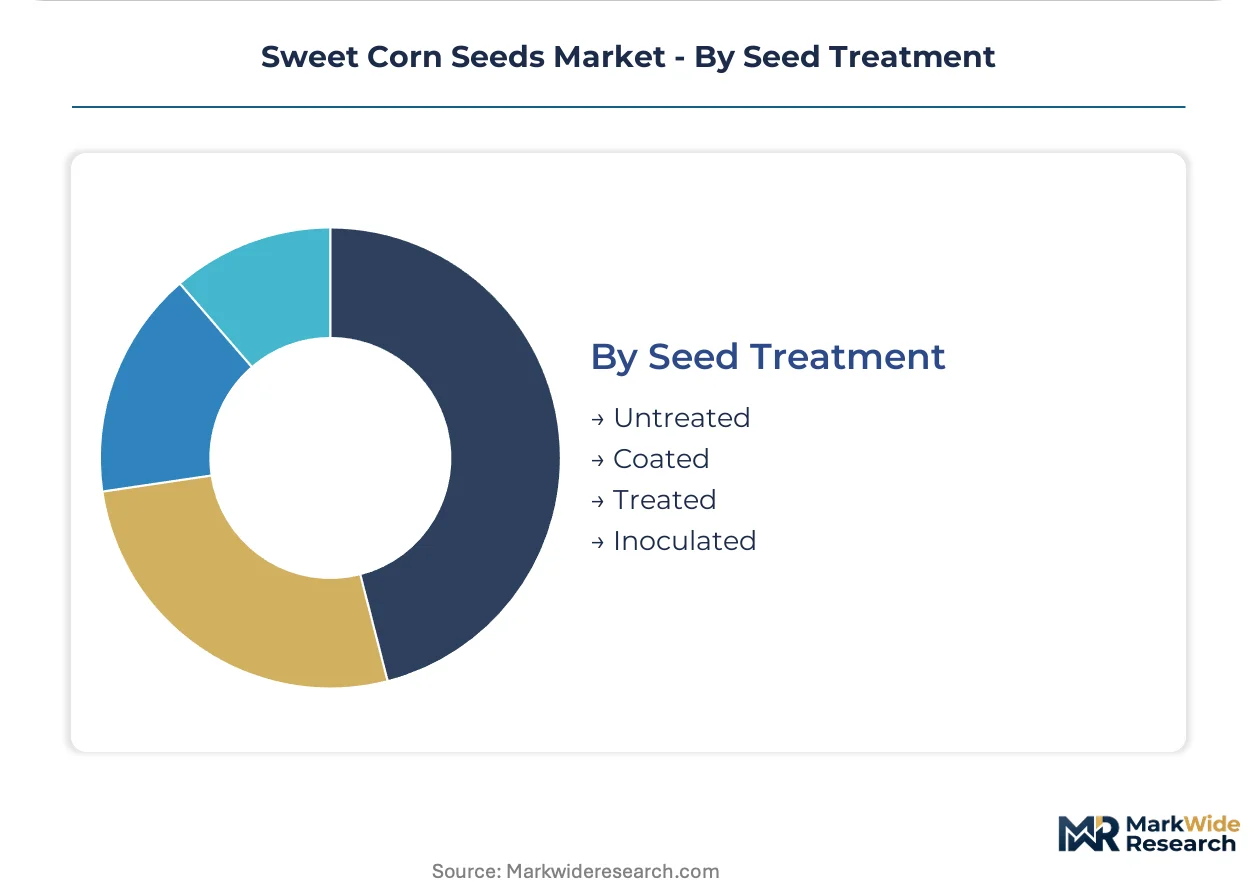
Seed Treatment:
Treatment intensity correlates with disease pressure, planting window risk, and regulatory requirements for pesticide-coated seed handling.
- Treated:Fungicide and insecticide coatings protect germinating seed from soil-borne pathogens and early-season pests. EPA registrations under FIFRA govern active ingredient combinations and application rates for interstate commerce.
- Coated:Polymer films improve flowability through planters and enable visual differentiation of variety blends without biological active ingredients.
- Inoculated:Biological amendments with plant-growth-promoting rhizobacteria or mycorrhizal fungi target organic production systems with restricted synthetic chemistry.
- Untreated:Raw seed satisfies organic certification requirements and specialty contracts prohibiting synthetic inputs, though germination rates suffer under adverse conditions.
Regulatory standardization centers on Treated. Biological innovation is concentrating in Inoculated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shandong and Guangdong provinces concentrate China's seed processing infrastructure, while contract farming corridors in Illinois and Minnesota anchor North American hybrid development. Brazil's Cerrado expansion zones and the Netherlands' controlled-environment agriculture clusters round out the primary geographic concentrations shaping varietal demand.
United States
Frozen food processors including Sysco and McCain Foods mandate kernel architecture specifications that bypass commodity channels. The USDA's Federal Seed Act governs interstate commerce with varietal labeling requirements. Illinois and Minnesota breeding houses now operate dedicated hybrid programs for processor-contracted tender-kernel lines with documented sugar retention curves.
China
Domestic processors in Shandong and Guangdong provinces favor pre-approved local hybrid lines over imported germplasm. The Ministry of Agriculture and Rural Affairs enforces varietal approval and seed production licensing under national seed law frameworks. Yangtze River Delta breeding stations accelerate gene-edited waxy corn development through established local trial networks.
Brazil
Cerrado expansion zones drive demand for disease-resistant hybrids suited to tropical production windows. ANVISA regulates pesticide-treated seed registrations affecting coated and inoculated product lines. São Paulo-based distributors supply contract farmers with nitrogen-efficient varieties as fertilizer price volatility compresses margins.
Netherlands
Controlled-environment agriculture operators pilot dwarf sweet corn varieties for year-round urban production. The EU Green Deal's Common Agricultural Policy rewards carbon farming certification schemes favoring low-input hybrid development. Wageningen research clusters integrate genomic selection with unmanned aerial vehicle phenotyping for real-time canopy assessment.
India
Fresh-market growers prioritize appearance traits including husk color and tip fill for roadside distribution. FSSAI and state agricultural departments enforce seed quality standards under the Seeds Act. Maharashtra and Karnataka input suppliers provide technical advice and custom seed treatment for mid-scale growers expanding hybrid acreage.
Sweet Corn Seeds Market Competitive Landscape
Top-tier vendors anchor consolidated germplasm ownership, while mid-tier regional breeders compete on trait turnaround speed. The structure concentrates elite inbred parent lines among three major breeding programs, creating supply vulnerability for independent distributors. Strategic archetypes include integrated agrochemical-seed conglomerates, regional adaptation specialists, and organic-certified niche operators. Dominant competitive moves center on digital farming tool bundling and accelerated R&D workflow restructuring around gene-editing pipelines.
Within the integrated conglomerate tier, Syngenta and Bayer exemplify platform-scale positioning through vegetable seed portfolios and digital agriculture bundling. Corteva Agriscience occupies a distinct archetype as a germplasm library operator with regional adaptation programs. KWS SAAT SE and Sakata Seed Corporation represent mid-tier specialists competing via marker-assisted selection platforms and localized trial networks. These five entities collectively illustrate the competitive spectrum from centralized R&D scale to regional breeding agility.
| Leading Market Players |
|---|
| Syngenta |
| Bayer |
| Corteva Agriscience |
| KWS SAAT SE |
| Sakata Seed Corporation |
| Advanta Seeds |
| Limagrain |
| Takii & Co. |
| Enza Zaden |
| Others |
Value Network & Pricing Analysis
Plant breeder concentration in the US Corn Belt and Yangtze River Delta generates labor-cost differentials that widen pricing-tier spreads between processor-contracted hybrids and commodity open-pollinated lines. These regional skill premiums translate directly into seed pricing stratification across premium, standard, and economy levels.
Pricing Analysis
Short lead-time premiums attach to CRISPR-accelerated hybrid releases with documented trait stacks, while spot inventory of conventional lines trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates processor-contracted genetics with sugar retention guarantees from agricultural wholesale hybrids and untreated open-pollinated seed. Pricing pressure stems from nitrogen fertilizer cost volatility compressing contract farmer margins and reducing replanting rates. Home gardeners through online retail channels show least price sensitivity for heirloom and organic-certified varieties, while commercial row-crop operations in Brazil's Cerrado exhibit highest sensitivity during input cost spike years.
Supply Chain Analysis
Direct-to-processor channels handle frozen food manufacturer demand with mandated kernel architecture specifications, while wholesale distributor networks serve commercial agricultural operations. Elite inbred parent line concentration in the United States, China, and Brazil creates geographic supply concentration with germplasm ownership narrowing to three major breeding programs. Raw material dependencies include nitrogen fertilizer inputs, polymer coating materials, and biological inoculant substrates. Single-source vulnerability in elite hybrid parent lines disrupts independent seed distributor procurement during varietal approval delays. Distribution runs through agricultural input suppliers providing technical advice and custom seed treatment coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Elite inbred germplasm scarcity props pricing power for integrated breeding houses, as parent line concentration among three major programs constrains supply expansion. This capacity bottleneck limits independent distributor access and sustains premium tiers for processor-aligned genetics.
For Market Incumbents: Acquire regional trial network infrastructure to compress trait validation timelines and defend against mid-tier Brazilian and Argentinian breeders adopting integrated genomic selection platforms. Consolidate backward integration into biological inoculant production to capture organic channel premiums and offset synthetic input cost volatility. Secure exclusive processor contracts with frozen food manufacturers mandating documented sugar retention curves. For New Entrants and Emerging Players: E-commerce platforms serving home gardeners represent the most penetrable channel, offering direct access to specialty open-pollinated and heirloom varieties with non-GMO verification. Target urban vertical farming operators in Singapore and the Netherlands piloting dwarf sweet corn varieties for controlled-environment production. Pursue white-label supply agreements with established organic certification bodies to bypass agricultural wholesale network barriers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier regional breeders given gene-editing platform adoption accelerating trait turnaround speed. Long-term viability over a five-to-ten year window favors entities with established local trial networks in China's Yangtze River Delta capturing domestic varietal approval advantages. Watch for inflection in processor procurement specifications displacing commodity-grade seed purchasing across the North American Corn Belt.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Trait Pipeline Acceleration | Compresses varietal development timelines from eight years to under four for processor-contracted hybrids. |
| Processor Contract Securement | Sysco and McCain Foods mandates for kernel depth and husk tightness anchor dedicated hybrid programs. |
| Regional Trial Network Expansion | Mid-tier Brazilian breeders bypass multi-location yield trials through UAV phenotyping integration. |
| Organic Certification Investment | Documented isolation distances and non-GMO verification capture 15-25% retail channel premiums. |
| Biological Inoculant Development | Plant-growth-promoting rhizobacteria formulations target organic production systems with restricted synthetic chemistry. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant breeding directors, seed production managers, frozen food processor procurement leads, and agricultural input distributors. USDA Federal Seed Act documentation, EPA FIFRA registration databases, and China's Ministry of Agriculture varietal approval records provided regulatory validation. Bottom-up acreage and pricing estimates triangulated against top-down market sizing from seed industry associations and customs trade flows.
Segmentation-level granularity modeled product type, end-use application, distribution channel, and seed treatment intensity across the projection horizon. Hybrid versus open-pollinated genetics, food processing versus fresh-market demand, and treated versus inoculated seed coatings represented core analytical dimensions. CAGRs derived from historical volume trajectories, processor contract expansion rates, and gene-editing platform adoption curves. Nitrogen fertilizer price elasticity and replanting rate sensitivity informed scenario-based forecast stress-testing.
Several conditions sit outside the modeled scope, including unanticipated gene-editing regulatory reclassification, maize lethal necrosis virus containment failures, and abrupt processor procurement specification shifts. Forecasts reflect assumptions regarding CRISPR-Cas9 approval pathway stability and continued frozen food manufacturer demand for tender-kernel hybrids. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
United States Seed Market
Seeds
Cotton Seed Treatment Market
Seeds
South Africa Seed Market
Seeds
Global Alfalfa Seed Market
Seeds
North America Alfalfa Seed Market
Seeds
North America Maize Seed Treatment Market
Seeds
Buckwheat Seed Market
Seeds
Asia-Pacific Maize Seed Market
Seeds
Ghana Seed Extract Market
Seeds
Global Fruit and Vegetable Seeds Market
Seeds
Europe Amaranth Market
Seeds
Seed Health Market
Seeds
Cover Crop Seed Varieties Market
Seeds
Europe Cannabis Seeds Market
Seeds
China Seed Market
Seeds
Flower Seed Market