
 United States Garden Seeds Market | 2026-2036
United States Garden Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
United States Garden Seeds Market Analytics
Market Dynamics
Modular seed assortments is repositioning how American consumers build home gardens, shifting from single-variety packets toward curated collections for container gardens, pollinator patches, and seasonal succession planting. Bayer AG leverages its vegetable seed portfolio to dominate commercial grower relationships across the Midwest and Southeast. Sakata Seeds Corporation specializes in heat-tolerant hybrid varieties that anchor its position in the Southern and Southwestern states where summer stress limits germination rates.
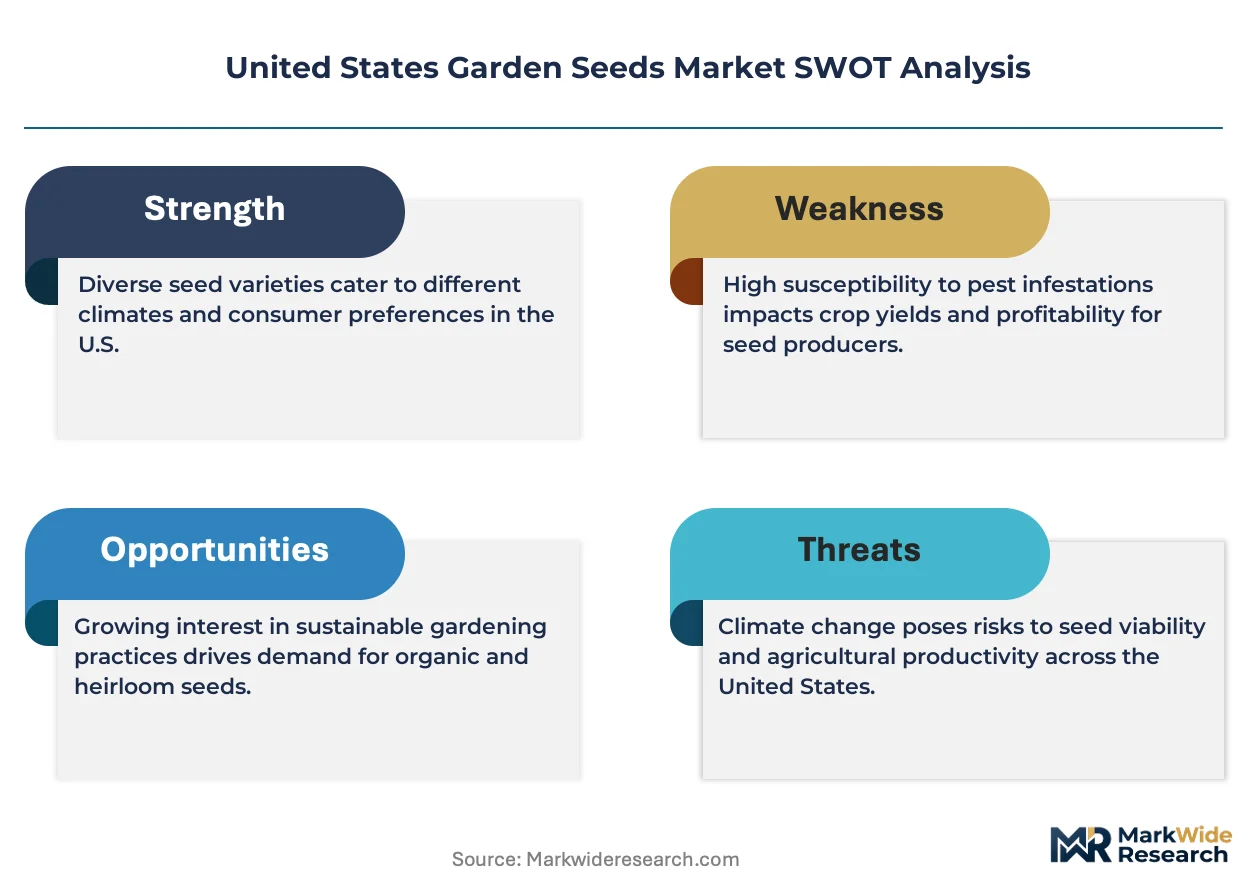
United States garden seeds comprise genetically stabilized or hybridized propagules, typically ranging from 85% to 98% germination rates under controlled conditions, bred for specific phenotypic traits including disease resistance, drought tolerance, and flavor profiles to serve home gardeners, commercial landscapers, and small-scale market farms. Vegetable seeds and herb seeds lead volume, with heirloom seeds capturing premium shelf positioning at specialty retailers while organic seeds command price multiples in channels targeting environmentally certified growers. Online retailers represent the fastest-growing distribution channel, though garden centers retain margin concentration through bundled soil-and-seed transactions and staff-guided variety selection.
The USDA National Organic Program, EPA pesticide tolerance regulations, and state-level seed certification standards administered by agencies such as the California Department of Food and Agriculture collectively shape product labeling, treatment disclosures, and interstate commerce compliance for garden seed suppliers. Stakeholders must monitor evolving state preemption debates around GMO labeling and pollinator-protection seed-coating restrictions that could reshape formulation strategies and channel obligations.
Market Dynamics
Modular seed assortments are displacing single-variety packets as the dominant transaction format, forcing suppliers to reconfigure inventory toward curated collections and compressing margins on legacy SKUs.
Growth Catalysts
- USDA National Organic Program certification:Organic seed premiums attract environmentally certified growers into commercial channels, expanding addressable demand beyond conventional home gardeners.
- Container gardening adoption:Urban dwellers in dense metropolitan corridors drive volume for compact, balcony-optimized varieties with specific days-to-maturity requirements.
- Heat-tolerant hybrid development:Southern and Southwestern states with summer stress conditions create sustained pull for germination-stable varieties that perform above 95°F.
Market Restraints
- Input cost volatility:Fertilizer and treatment chemical prices fluctuate with natural gas benchmarks, compressing formulation margins for coated seed products.
- Supply concentration risk:California's Central Valley dominates organic seed multiplication acreage, creating single-point vulnerability for certified supply chains.
- Regulatory friction:State-level preemption debates around pollinator-protection seed-coating restrictions generate formulation uncertainty and interstate commerce compliance costs.
Strategic Opportunities
- Pacific Northwest corridor expansion:Washington and Oregon's mild maritime climates support extended growing seasons for succession-planting seed collections.
- Direct-to-consumer channel innovation:Subscription-based seed delivery models capture recurring revenue from home gardening enthusiasts with automated seasonal curation.
- Native pollinator patch mandates:Municipal biodiversity programs in Midwestern cities create institutional demand for wildflower and beneficial insect forage mixes.
Industry Challenges
- Genetic purity certification timelines:USDA-accredited laboratories face testing backlogs that delay organic and heirloom seed lot releases by 6-12 weeks.
- Climate adaptation R&D capex:Developing drought-tolerant varieties requires multi-year field trials across divergent agroclimatic zones before commercial viability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Garden Seeds Market |
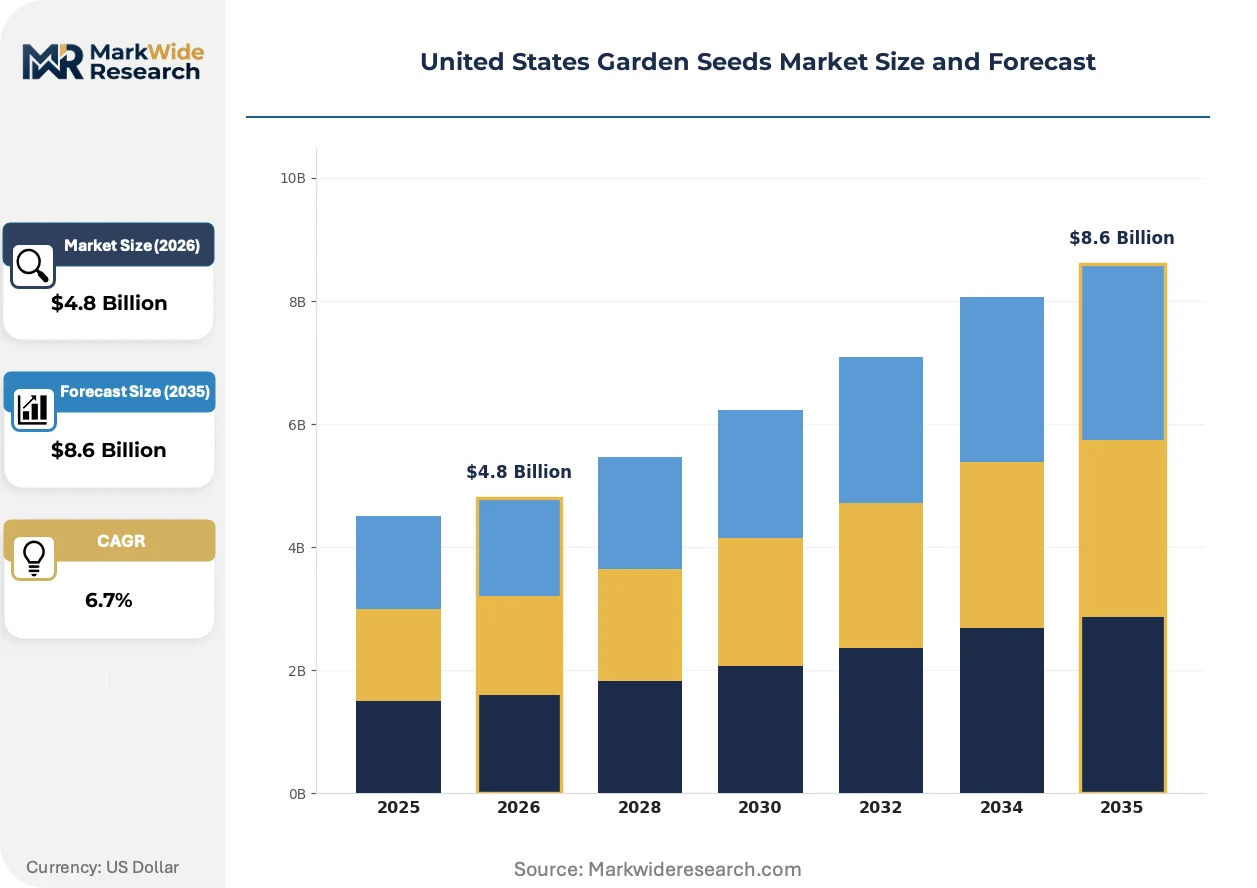
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Seeds, Flower Seeds, Herb Seeds, Fruit Seeds Packaging Type: Bulk Packaging, Retail Packs, Eco-friendly Packs, Reusable Containers Distribution Channel: Online Retailers, Garden Centers, Supermarkets, Specialty Stores Seed Variety: Heirloom Seeds, Hybrid Seeds, Organic Seeds, GMO Seeds |
| Companies Covered | Bayer AG, Syngenta Group, BASF SE, Groupe Limagrain, Sakata Seeds Corporation, Takii & Co., Bejo Zaden, Enza Zaden, Rijk Zwaan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Garden Seeds Market Evolving Landscape
Digital phenotyping and precision breeding platforms are compressing variety development cycles while consumer-facing channels fragment toward specialized curation models that prioritize experiential gardening outcomes over commodity seed transactions.
Gene editing via CRISPR-Cas9 is expanding into disease-resistance trait stacking for vegetable seed lines, enabling breeders to pyramid multiple resistance loci without traditional backcrossing timelines. Commercial growers in the Southeast are adopting these varieties at accelerating rates. The technology is compressing variety release schedules from 8-10 years toward 4-6 years.
EPA pesticide tolerance regulations are tightening maximum residue limits for seed treatment chemistries, forcing reformulation toward biological and biochemical alternatives. Seed coating suppliers must revalidate product registrations under amended toxicity testing protocols. Organic-certified growers and specialty retailers are responding by accelerating untreated and film-coated seed SKU expansion.
Home gardeners are consolidating purchases through bundled soil-and-seed transactions at garden centers, displacing standalone packet purchases through mass retail. Staff-guided variety selection services capture margin concentration that online retailers struggle to replicate. This behavioral shift is most visible in suburban markets surrounding major metropolitan areas where experiential retail investments have concentrated.
United States Garden Seeds Market Segmentation
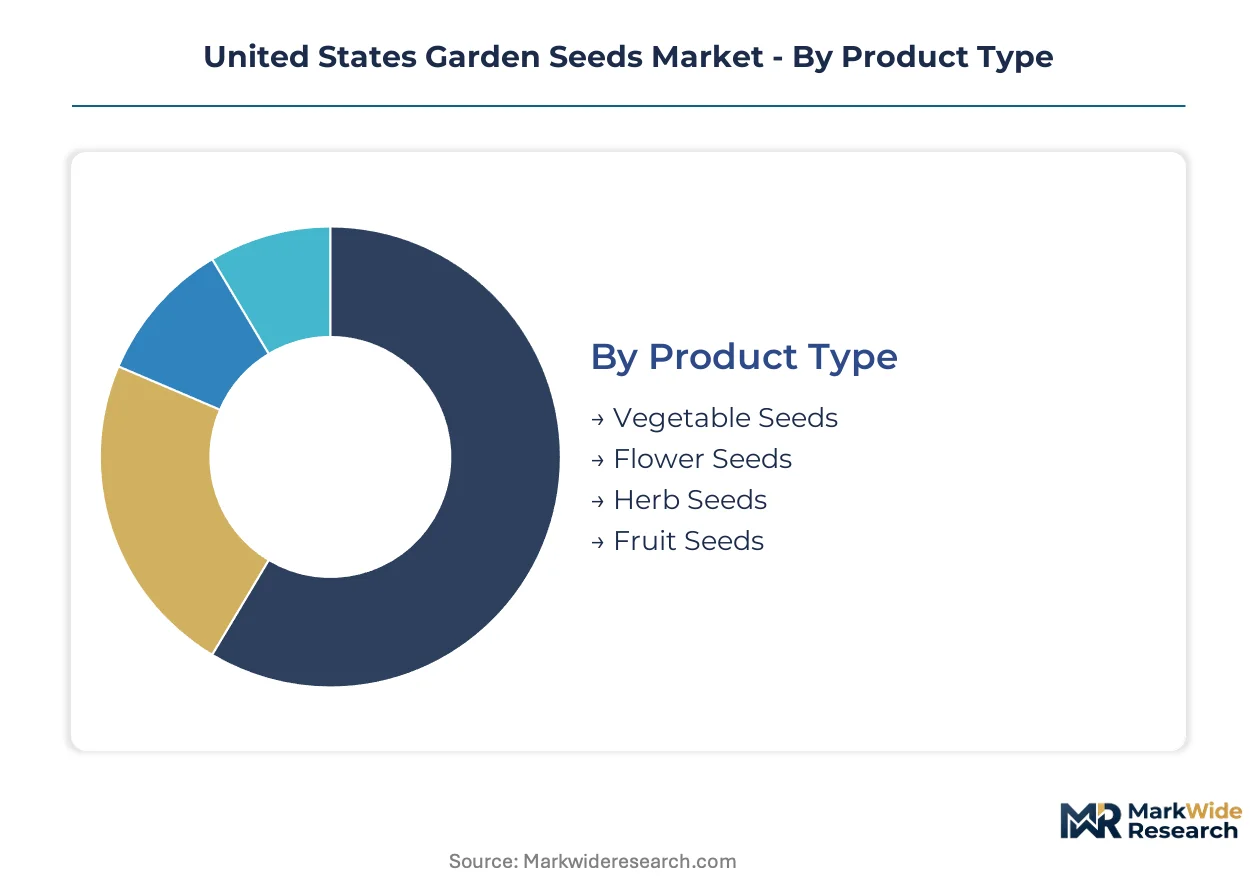
Segmentation in the United States garden seeds market reveals how purchasing behavior fragments across product purpose, environmental values, and channel convenience. Suppliers must align inventory and marketing to distinct consumer psychographics rather than treating home gardeners as a uniform demographic.
Product Type:
Volume concentrates in edible categories while ornamental seeds capture premium positioning through aesthetic differentiation and pollinator marketing.
- Vegetable Seeds:Comprising tomatoes, peppers, leafy greens, and root vegetables bred for specific days-to-maturity and disease-resistance markers. Demand clusters in suburban markets surrounding Atlanta, Dallas, and Phoenix where backyard plot cultivation surged post-2020. The USDA National Organic Program certification drives price multiples for untreated vegetable seed lots.
- Herb Seeds:Compact varieties optimized for container gardening and culinary freshness, including basil, cilantro, and Mediterranean perennials. Urban balcony gardeners in Chicago, Seattle, and Denver drive volume for compact, quick-germinating selections with continuous harvest potential.
- Flower Seeds:Ornamental varieties for cutting gardens and landscape color, with native wildflower mixes gaining institutional traction through municipal pollinator programs.
- Fruit Seeds:Berries, melons, and vine fruits requiring longer growing seasons, concentrated in Pacific Northwest and Southeast corridors with extended frost-free periods.
Today's leader: Vegetable Seeds. Tomorrow's challenger: Herb Seeds.
Packaging Type:
Environmental compliance pressures and retail channel requirements are reshaping material specifications and unit economics across all format tiers.
- Retail Packs:Standard paper-and-foil packets dominating mass merchant and garden center shelves, with treated seed coatings requiring EPA-compliant labeling disclosures. California's Department of Food and Agriculture enforces additional germination rate testing that delays lot releases.
- Eco-friendly Packs:Compostable films and soy-based inks responding to municipal plastic reduction mandates in Portland, Seattle, and San Francisco. Premium positioning depends on third-party compostability certifications.
- Bulk Packaging:Multi-pound sacks for commercial landscapers and market farms, with volume discounts compressing per-unit margins.
- Reusable Containers:Metal tins and glass jars with seed-saving instructions, capturing gift market and heirloom collector segments through specialty retail.
Retail Packs anchor current revenue. Eco-friendly Packs are climbing the fastest as regulatory pressure intensifies.
Distribution Channel:
Channel selection determines margin structure and customer acquisition cost, with experiential retail defending against digital disintermediation through service bundling.
- Garden Centers:Staff-guided variety selection and bundled soil-and-seed transactions defend margin concentration that pure e-commerce cannot replicate. Independent operators in the Midwest and Northeast have invested in demonstration gardens and seasonal workshops.
- Online Retailers:Subscription models and algorithmic curation capture recurring revenue from enthusiasts seeking succession-planting automation. Direct-to-consumer shipping faces rising last-mile cost pressure in rural zip codes.
- Supermarkets:Impulse placement near produce sections drives seasonal volume for basic vegetable varieties with minimal staff support.
- Specialty Stores:Heirloom and organic seed assortments at premium price points, with certified organic SKUs requiring USDA-accredited supplier verification.
Garden Centers hold the installed base. Online Retailers show the steepest expansion trajectory.
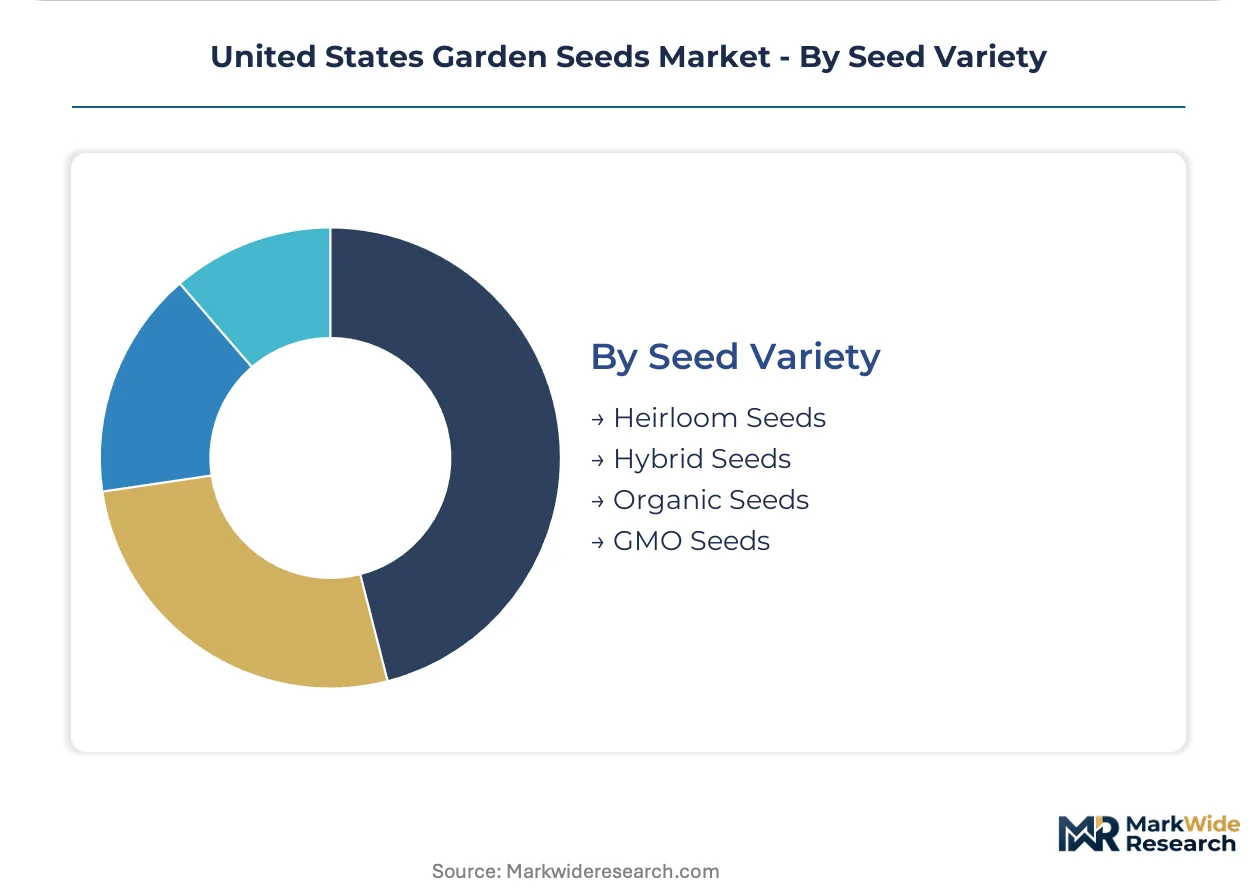
Seed Variety:
Genetic provenance shapes pricing architecture and regulatory exposure, with certification requirements fragmenting supplier compliance obligations.
- Hybrid Seeds:Commercial F1 varieties with stacked disease resistance and climate stress tolerance, dominating Southern and Southwestern states where summer heat limits open-pollinated performance. Bayer AG and Sakata Seeds anchor supply relationships with commercial growers.
- Heirloom Seeds:Open-pollinated varieties with generational seed-saving potential, commanding premium shelf positioning at specialty retailers and farmers market channels. Genetic purity testing backlog at USDA-accredited laboratories creates 6-12 week release delays.
- Organic Seeds:USDA National Organic Program certification requires untreated stock and documented organic multiplication acreage, with supply concentrated in California's Central Valley.
- GMO Seeds:Limited to specific vegetable lines with trait stacking for commercial production, facing state-level preemption debates on labeling requirements.
Hybrid Seeds dominate commercial volume. Heirloom Seeds are gaining share fastest through premium positioning and seed-saving culture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States garden seeds industry traces its commercial lineage to the early twentieth-century seed catalog boom, when regional breeders in the Midwest and Northeast established the varietal foundations that still underpin heirloom collections today.
California
Organic seed multiplication concentrates in the Central Valley, where USDA National Organic Program certification requirements have created specialized acreage for untreated stock production. The California Department of Food and Agriculture enforces germination rate testing protocols that delay lot releases by several weeks. Sacramento and Fresno anchor the state's seed processing infrastructure, with regional cooperatives managing organic certification compliance for national distribution.
Pacific Northwest
Washington and Oregon's mild maritime climates support extended growing seasons that drive demand for succession-planting seed collections. Municipal plastic reduction mandates in Portland and Seattle accelerate compostable packaging adoption among regional suppliers. The Willamette Valley hosts specialized organic seed farms that serve environmentally certified growers across the western states.
Southern States
Heat-tolerant hybrid varieties dominate Texas, Florida, and Georgia where summer stress conditions above 95°F limit open-pollinated germination rates. Backyard plot cultivation surged post-2020 in suburban Atlanta, Dallas, and Phoenix corridors. Regional extension services coordinate with breeders to validate drought-tolerant lines for home gardener adoption.
Midwest
Commercial grower relationships with hybrid seed suppliers concentrate in Illinois, Iowa, and Ohio where vegetable production serves processing and fresh markets. Independent garden centers in suburban Chicago and Detroit have invested in demonstration gardens and seasonal workshops to defend margin concentration against digital channels. Municipal pollinator patch programs in Midwestern cities create institutional demand for native wildflower mixes.
Northeast Corridor
Urban balcony gardeners in New York, Boston, and Philadelphia drive volume for compact herb varieties with quick germination and continuous harvest potential. Specialty retailers in the region command premium positioning for heirloom seed assortments with generational seed-saving potential. USDA-accredited laboratories in the Northeast face testing backlogs that delay organic and heirloom seed lot releases.
United States Garden Seeds Market Competitive Landscape
The competitive structure tilts toward diversified agrochemical conglomerates with vegetable seed portfolios. Bayer AG and Syngenta Group leverage crop science R&D infrastructure to dominate commercial grower relationships, while specialized vegetable breeders occupy premium positioning in heat-tolerant and heirloom segments. Three archetypes define the field: integrated life-science conglomerates, regional hybrid specialists, and heritage-focused open-pollinated suppliers. Capacity expansion in organic multiplication acreage and strategic partnerships for CRISPR trait licensing represent the dominant competitive moves.
Within the integrated conglomerate tier, Bayer AG and Syngenta Group exemplify scale-driven positioning through vegetable seed portfolios that anchor commercial grower supply relationships. BASF SE occupies a position among European-based chemical conglomerates with seed assets. Sakata Seeds Corporation represents the regional hybrid specialist archetype, with its corporate structure indicating Japanese origin and heat-tolerant variety focus. Among heritage-oriented suppliers, Groupe Limagrain exemplifies the cooperative-owned model with French agricultural roots. These named entities serve as anchors for understanding how competitive positioning fragments across scale, specialization, and provenance dimensions.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta Group |
| BASF SE |
| Groupe Limagrain |
| Sakata Seeds Corporation |
| Takii & Co. |
| Bejo Zaden |
| Enza Zaden |
| Rijk Zwaan |
| Others |
Value Network & Pricing Analysis
USDA National Organic Program certification gates both qualified supply and premium-tier pricing access, concentrating untreated seed multiplication in California's Central Valley while commanding price multiples that conventional treated varieties cannot match. This regulatory filter compresses margins for non-certified suppliers and concentrates pricing power among accredited organic producers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic SKUs from conventional treated varieties and bulk commercial lines. Price differentiation hinges on certification grade and volume scale, with organic premiums widening as California supply constraints tighten. Cost compression in economy-tier retail packs is intensifying because fertilizer and treatment chemical prices fluctuate with natural gas benchmarks. Home gardening enthusiasts show least price sensitivity for heirloom collector assortments, while commercial landscapers drive hardest bargains on bulk sack orders.
Supply Chain Analysis
Organic seed multiplication rests on California's Central Valley acreage, with secondary propagation clusters in Oregon's Willamette Valley and Washington's Skagit Valley. Raw material dependencies include untreated parent stock, biological coating formulations, and compostable film substrates. Single-source vulnerability concentrates in California's organic certification infrastructure, where germination testing backlogs delay national distribution. Distribution runs through garden center networks for bundled soil-and-seed transactions, with direct-to-consumer subscription models capturing fastest-growing channel share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States garden seeds market functions as a geographic-arbitrage play between California's regulatory-intensive organic certification costs and the Pacific Northwest's lower-compliance propagation economics. Suppliers can exploit this cost differential by shifting multiplication acreage northward while maintaining California processing infrastructure.
For Market Incumbents: Extend organic certification coverage into Pacific Northwest multiplication sites to reduce California concentration risk. Deepen backward integration into biological coating formulation to offset EPA pesticide tolerance tightening. These moves defend against emerging regional hybrid specialists capturing Southern state market share through heat-tolerant variety superiority. For New Entrants and Emerging Players: Begin with municipal pollinator patch mandates in Midwestern cities, where institutional procurement for native wildflower mixes remains underpenetrated by established suppliers. Target subscription-based direct-to-consumer channels with algorithmic succession-planting curation, leveraging lower customer acquisition costs than garden center incumbents can match. For Investors and Strategic Acquirers: Valuations sit cheapest among heritage-focused open-pollinated suppliers with generational seed-saving customer bases and USDA-accredited laboratory relationships. Long-term viability over the coming decade hinges on CRISPR trait licensing access and climate adaptation R&D pipelines. Watch for inflection when EPA announces amended toxicity testing protocols for seed treatment chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Organic Multiplication | Adds certified acreage in Oregon's Willamette Valley to reduce California supply concentration risk. |
| Backward Integration into Biological Coatings | Captures formulation margin and accelerates EPA compliance for pollinator-protection mandates. |
| Direct-to-Consumer Subscription Launch | Automates seasonal curation and locks recurring revenue from home gardening enthusiasts. |
| Strategic Partnership for CRISPR Licensing | Compresses variety development timelines from traditional backcrossing toward precision breeding platforms. |
| Geographic Expansion into Pacific Northwest | Exploits mild maritime climates for extended growing season succession-planting collections. |
Research Methodology
Direct dialogue with seed company executives, organic certification coordinators, garden center operators, and USDA-accredited laboratory directors anchored qualitative findings. Secondary validation drew from California Department of Food and Agriculture germination testing records, EPA pesticide tolerance regulatory filings, and USDA National Organic Program certification databases. Bottom-up triangulation across multiplication acreage estimates and top-down cross-check against retail channel shipment data ensured figure integrity.
Bottom-up modeling segmented volume and value across product type, seed variety, packaging format, and distribution channel, with additional stratification by regional climate zone adoption patterns. CAGRs were derived from trend extrapolation calibrated to historical organic certification growth curves and container gardening penetration rates. Forecast inputs incorporated EPA regulatory amendment timelines and CRISPR variety commercialization trajectories.
Caveats apply where state-level preemption debates around GMO labeling or pollinator-protection seed-coating restrictions could materially shift the outlook. Forecasts reflect assumptions about California water availability for organic multiplication and Pacific Northwest compostable packaging mandate expansion. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Celery Seed Oil Market
Seeds
Organic Sesame Seed Market
Seeds
Grass Seed Market
Seeds
Drought Tolerant Seeds Market
Seeds
Seed Cracker Market
Seeds
Europe Sesame Seed Market
Seeds
China Rice Seed Market
Seeds
Asia-Pacific Quinoa Seeds Market
Seeds
Rapeseed Market
Seeds
Ghana Seeds Market
Seeds
Dragon Fruit Seeds Market
Seeds
North America Alfalfa Seed Market
Seeds
Europe Forage Seed Market
Seeds
Fruit Tomatoes Seed Market
Seeds
Apple Seed Oil Market
Seeds
Asparagus Seeds Market