
 Chamomile Seeds Market | 2026-2036
Chamomile Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Chamomile Seeds Market Outlook
Precision breeding and marker-assisted selection is fragmenting the traditional chamomile seed supply chain into specialized tiers. Bejo Zaden B.V. leverages its vegetable seed infrastructure to advance hybrid chamomile genetics for pharmaceutical-grade cultivars. Johnny's Selected Seeds anchors the North American heirloom segment with open-pollinated Roman chamomile lines suited to small-scale organic farms. Territorial Seed Company differentiates through regionally adapted Pacific Northwest germplasm with documented essential oil profiles.
Chamomile seeds are dried reproductive units of Matricaria chamomilla or Chamaemelum nobile, typically requiring 65-75% germination rates under controlled temperature and moisture conditions for commercial viability; they serve as the foundational input for essential oil distillation, herbal extract production, and direct sowing in medicinal herb cultivation. German chamomile dominates volume flows due to its higher azulene content preferred by pharmaceutical extractors, while Roman chamomile commands premium positioning in cosmetics applications where ester-rich oil profiles justify specialized cultivation contracts. The wholesale distribution channel retains structural importance for bulk seed transactions to industrial processors, though online retail gains traction among artisanal growers and small cosmetic formulators seeking certified organic germplasm in smaller lot sizes.
The European Commission's EFSA and the USDA's National Organic Program jointly shape seed purity standards and phytosanitary certification requirements that govern cross-border germplasm trade. REACH compliance for seed treatment residues and the EU Organic Regulation's mandatory lot traceability impose documentation burdens that favor integrated seed houses with in-house certification capabilities. Stakeholders must monitor evolving botanical drug monographs from pharmacopeial authorities, as tightening assay specifications for chamazulene and bisabolol content will cascade backward into seed selection criteria and varietal breeding priorities.
Market Dynamics
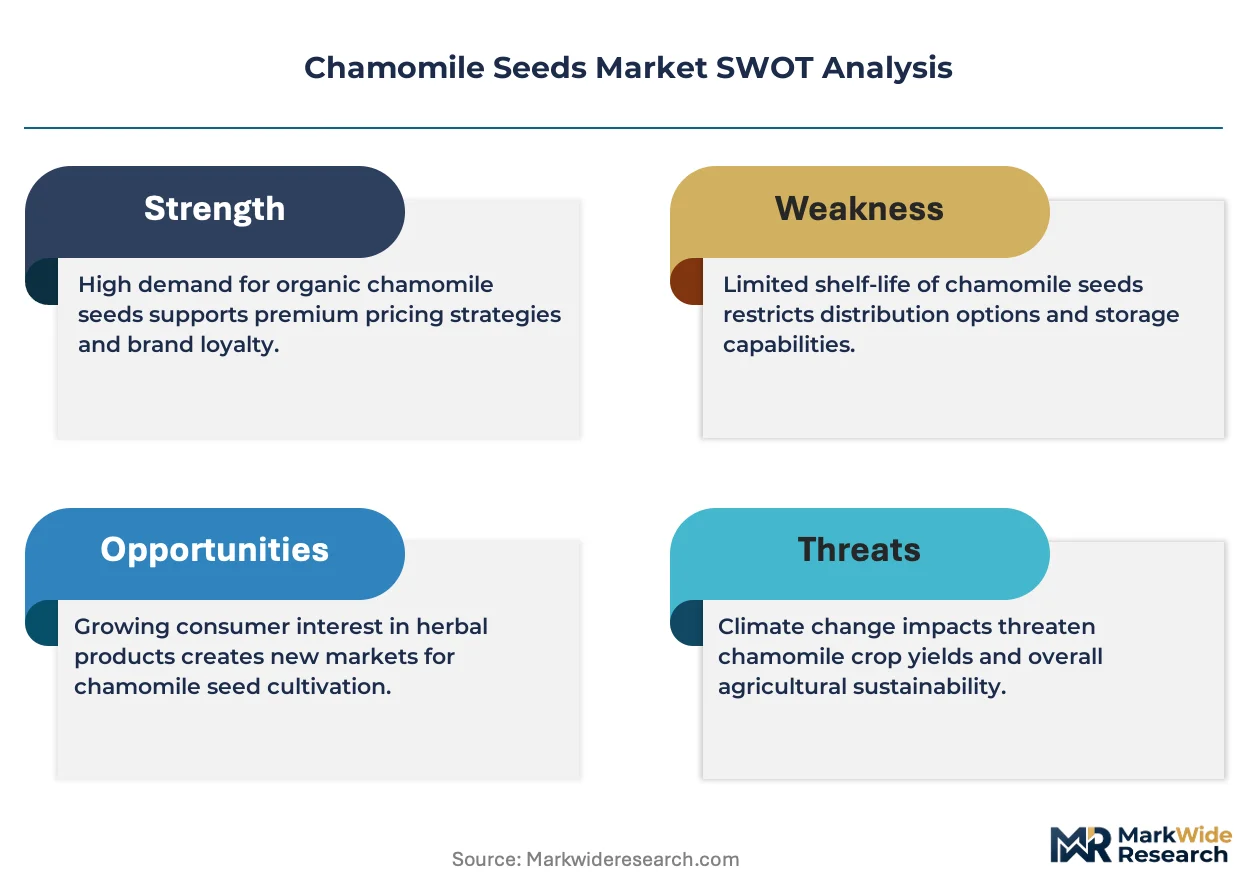
EU Organic Regulation 2018/848 is compressing chamomile seed supply chains into traceable, certified tiers, forcing smaller suppliers to consolidate or exit while integrated seed houses capture pharmaceutical and cosmetic contract flows.
Growth Catalysts
- Pharmaceutical extraction standards:Tightening pharmacopeial assay specifications for chamazulene and bisabolol content are pulling demand toward certified German chamomile genetics with documented essential oil profiles.
- France:Organic cosmetic formulators in this market are driving uptake of certified German chamomile seed stock through specialized cultivation contracts tied to premium positioning.
- Marker-assisted selection:This breeding technology is enabling precision development of pharmaceutical-grade cultivars with consistent secondary metabolite expression.
Market Restraints
- Input cost volatility:Irrigation water scarcity in Egyptian contract cultivation zones is elevating production risk for Mediterranean basin essential oil extraction operations.
- Regulatory friction:REACH compliance for seed treatment residues imposes documentation burdens that disproportionately burden small-scale open-pollinated seed producers lacking in-house certification capabilities.
- Substitution threat:Synthetic bisabolol and chamazulene isolates from petrochemical feedstocks compete with botanical extracts in cost-sensitive cosmetic applications.
Strategic Opportunities
- Spain:Contract cultivation expansion in this Mediterranean basin hub offers white space for vertically integrated seed-to-oil operations serving EU pharmaceutical extractors.
- Online retail channels:Direct-to-grower platforms are capturing artisanal cosmetic formulators seeking certified organic germplasm in smaller lot sizes outside traditional wholesale distribution.
- Technology convergence:Integration of near-infrared spectroscopy with seed sorting equipment enables real-time essential oil potential assessment before sowing.
Industry Challenges
- Phytosanitary certification timelines:Cross-border germplasm trade governed by EFSA and USDA National Organic Program standards creates multi-month clearance delays for urgent contract plantings.
- Genetic purity maintenance:Open-pollinated Roman chamomile lines require isolation distances and hand-roguing protocols that strain labor availability on small-scale organic farms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chamomile Seeds Market |
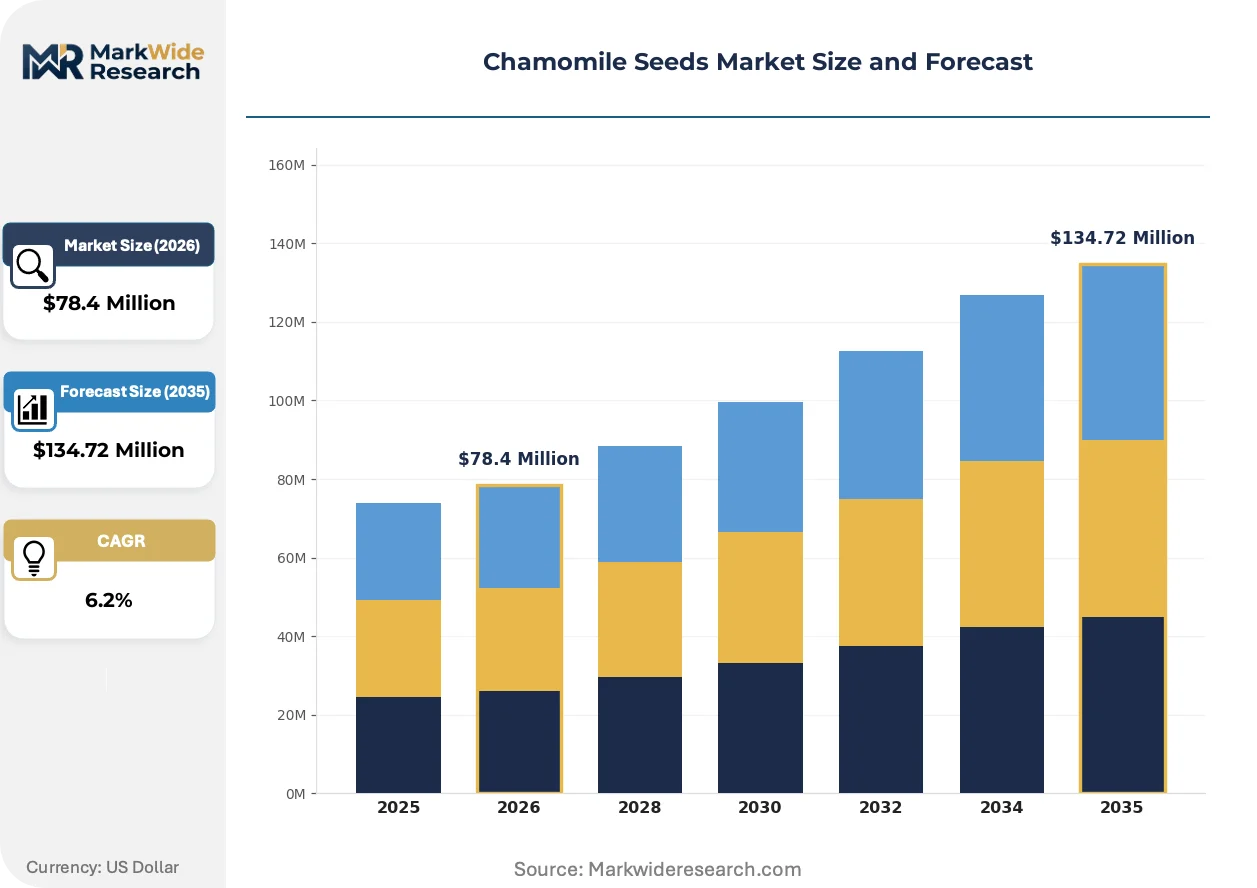
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $134.72 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: German Chamomile, Roman Chamomile, Wild Chamomile, Others End Use: Pharmaceuticals, Cosmetics, Food & Beverages, Nutraceuticals Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales Form: Whole Seeds, Extracts, Powder, Oil |
| Companies Covered | Bejo Zaden B.V., Baker Creek Heirloom Seed Co, Johnny's Selected Seeds, Semillas Fitó, B&T World Seeds, The Green Seed Company, Mountain Rose Herbs, Territorial Seed Company, Seattle Seed Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chamomile Seeds Market Strategic Shifts
Digital seed quality assessment and blockchain traceability systems are restructuring how chamomile germplasm is authenticated, financed, and traded across fragmented supplier networks.
Spectral imaging systems for non-destructive seed viability prediction are virtualizing traditional germination testing workflows. Pharmaceutical extractors in Germany are adopting these platforms to pre-qualify seed lots before contract sowing. This compression of quality assurance timelines is enabling just-in-time procurement models that reduce working capital requirements for essential oil processors.
REACH seed treatment residue thresholds are forcing reformulation of chemical coatings toward biological alternatives. EU-based seed houses are responding by building in-house analytical laboratories capable of batch-level contaminant screening. The wholesale distribution channel faces margin compression as integrated producers bypass intermediaries to deliver certified-clean germplasm directly to industrial processors.
Cosmetic formulators are unbundling seed procurement from traditional commodity brokers, instead contracting directly with regional adaptation specialists for documented terpene profiles. Pacific Northwest germplasm with specific ester ratios commands position premiums in this channel. Small-scale organic farms in North America are capturing this demand rotation through cooperative aggregation platforms that consolidate lot sizes for cosmetic-grade contracts.
Chamomile Seeds Market Segmentation
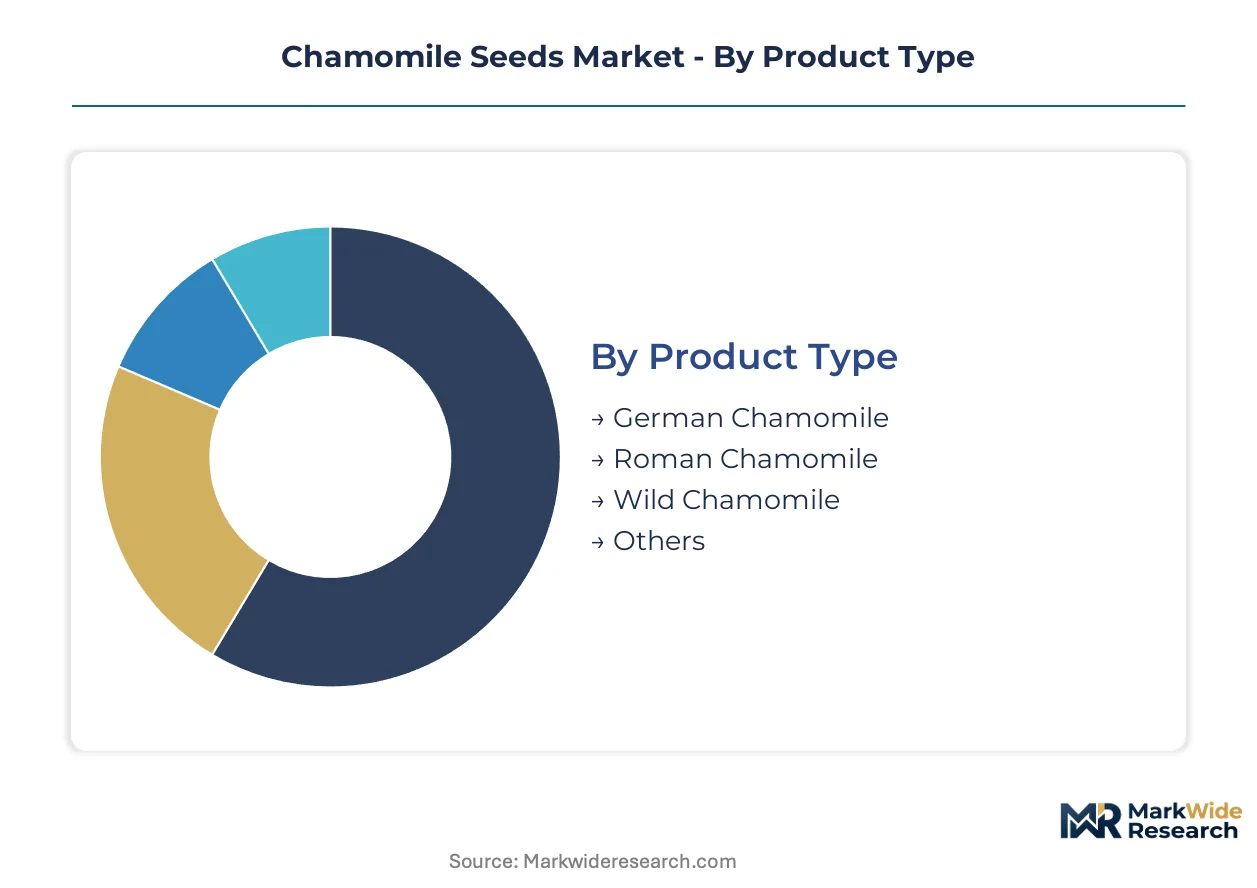
Chamomile seed procurement cycles vary dramatically across product types and end-use channels. Pharmaceutical extractors operate on multi-year varietal development timelines, while cosmetic formulators rotate seed stock seasonally based on terpene profile trends. Distribution channel selection directly dictates lot size minimums, certification documentation depth, and payment terms.
Product Type:
German chamomile turns over fastest in commercial channels due to annual pharmaceutical contracting cycles, while wild chamomile moves slowest through artisanal supply chains with multi-year foraging permits.
- German Chamomile:Matricaria chamomilla varieties with elevated azulene and bisabolol content dominate pharmaceutical extraction feedstocks. French and German organic cosmetic formulators drive contract demand for certified seed stock with documented essential oil profiles under EU Organic Regulation 2018/848 traceability mandates.
- Roman Chamomile:Chamaemelum nobile lines produce ester-rich oils preferred in premium cosmetic applications. Small-scale organic farms in the Pacific Northwest capture cooperative aggregation demand for regionally adapted germplasm with specific terpene ratios.
- Wild Chamomile:Uncultivated Matricaria populations harvested under seasonal foraging permits supply niche aromatherapy channels.
- Others:Hybrid experimental lines and landrace preservation stocks circulate through botanical garden networks and research consortia.
German chamomile anchors the volume base while Roman chamomile gains share at the steepest rate.
End Use:
Cost tier separation runs deepest in this category, with pharmaceutical-grade seed commanding certification premiums that cosmetic and nutraceutical channels rarely justify.
- Pharmaceuticals:Pharmacopeial assay specifications for chamazulene and bisabolol content mandate precision-bred genetics with batch-level analytical documentation. EFSA and USDA National Organic Program standards govern cross-border germplasm trade for industrial extractors.
- Cosmetics:Organic formulators in France and Germany contract directly for ester-profiled Roman chamomile seed stock, bypassing commodity brokers.
- Food & Beverages:Whole seed and milled powder applications for herbal tea blending require lower terpene potency thresholds.
- Nutraceuticals:Capsule and tincture manufacturers source standardized extract precursors through wholesale distribution channels.
Pharmaceuticals anchors the volume base while Cosmetics climbs the fastest.
Distribution Channel:
Customer type fragmentation shapes channel selection, with industrial processors consolidating through wholesale while artisanal formulators fragment across direct and online platforms.
- Wholesale:Bulk seed transactions to Mediterranean basin essential oil processors and Egyptian contract cultivation operations retain structural importance for volume flows. REACH compliance documentation and phytosanitary certification favor integrated seed houses with in-house analytical capabilities.
- Online Retail:Direct-to-grower platforms capture artisanal cosmetic formulators seeking certified organic germplasm in smaller lot sizes outside traditional wholesale minimums.
- Specialty Stores:Regional agricultural cooperatives and heirloom seed networks serve small-scale organic farms with open-pollinated Roman chamomile lines.
- Direct Sales:Vertical seed-to-oil operations in Spain contract cultivation directly with pharmaceutical extractors, bypassing intermediaries.
Wholesale anchors the volume base while Online Retail expands most quickly.
Form:
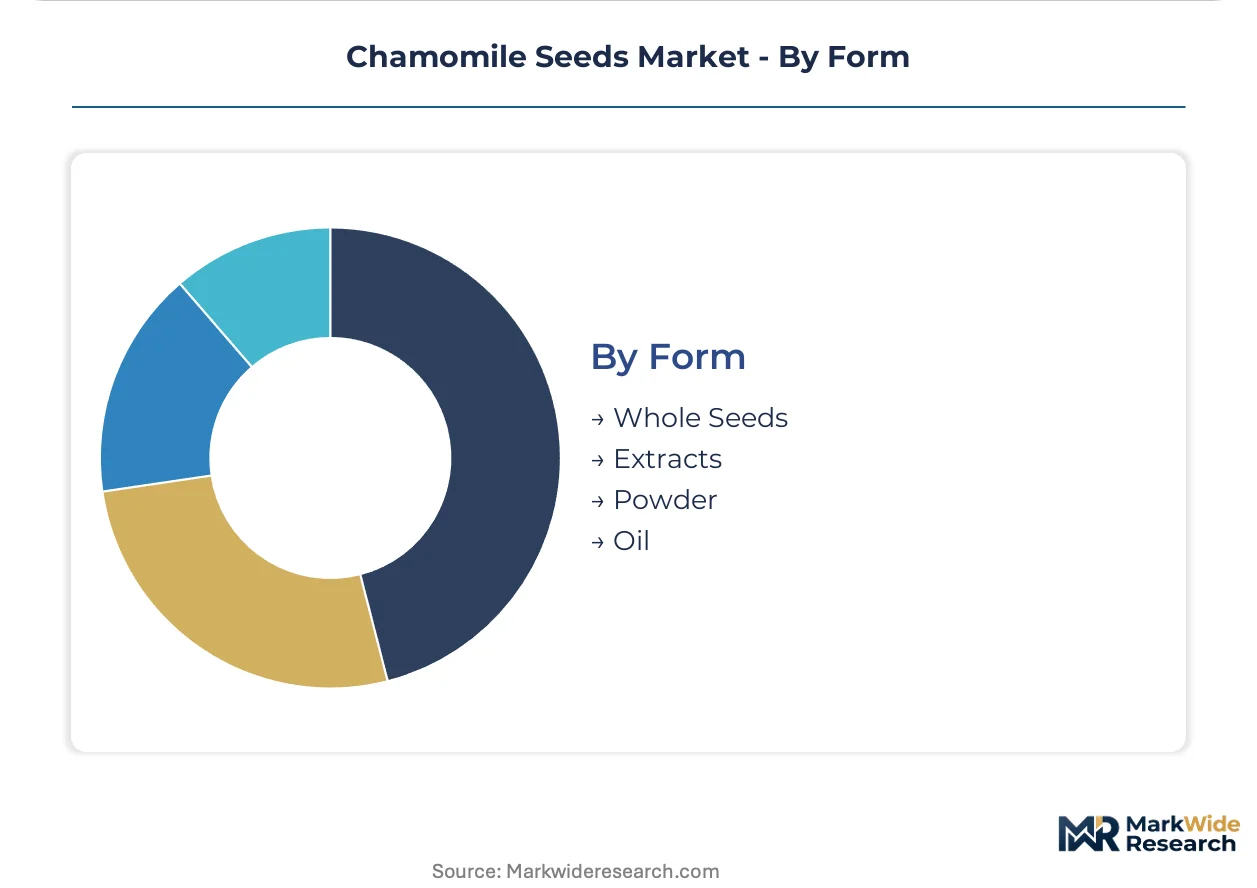
Supply concentration varies by processing depth, with whole seeds consolidating through agricultural wholesale while extracts and oils fragment across specialized processors.
- Whole Seeds:Dried reproductive units requiring 65-75% germination rates under controlled temperature and moisture conditions serve as foundational inputs for cultivation operations. Spain and Egypt expand contract cultivation for essential oil extraction in the Mediterranean basin.
- Oil:Steam-distilled essential oil products command premium positioning in cosmetic applications where ester-rich profiles justify specialized cultivation contracts.
- Extracts:Solvent and CO2-extracted concentrates supply standardized nutraceutical and pharmaceutical intermediate channels.
- Powder:Milled seed material for herbal tea and food ingredient applications moves through commodity botanical trading networks.
Whole seeds anchors the volume base while Oil shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egyptian contract cultivation zones export raw botanical material to German and French pharmaceutical extractors, forming the dominant Mediterranean trade corridor for chamomile seed derivatives.
Germany
Pharmaceutical-grade extraction facilities in Saxony-Anhalt and Bavaria drive demand for certified German chamomile genetics with documented azulene profiles. EFSA seed purity standards and REACH compliance for treatment residues govern cross-border germplasm procurement from Mediterranean suppliers. The Baden-Württemberg cluster concentrates precision breeding operations serving industrial extractors with batch-level analytical documentation.
France
Organic cosmetic formulators in Provence-Alpes-Côte d'Azur contract directly for Roman chamomile seed stock with specific ester ratios. EU Organic Regulation 2018/848 mandates lot traceability that compresses supply chains into certified tiers. Grasse-area perfumery houses anchor premium positioning for ester-rich oil profiles in high-end cosmetic applications.
Spain
Andalusian and Castilla-La Mancha cultivation zones expand contract sowing for essential oil extraction serving EU pharmaceutical channels. The country's national pharmaceutical regulator aligns phytosanitary certification with EFSA timelines. Murcia-based vertical seed-to-oil operations bypass wholesale intermediaries to deliver certified germplasm directly to industrial processors.
Egypt
Nile Delta contract farming operations supply raw chamomile biomass to European essential oil distillers under seasonal cultivation agreements. Irrigation water scarcity elevates production risk for Mediterranean basin extraction operations. Kafr El Sheikh governorate concentrates smallholder cultivation networks coordinated through export-oriented aggregation platforms.
United States
Pacific Northwest small-scale organic farms supply heirloom Roman chamomile lines to artisanal cosmetic formulators through cooperative aggregation. USDA National Organic Program standards govern germplasm certification for cross-state distribution. Oregon's Willamette Valley anchors regionally adapted germplasm development with documented terpene profiles for premium positioning.
Chamomile Seeds Market Competitive Environment
On the supply side, the industry is fragmenting into specialized tiers distinguished by certification depth and genetic documentation capabilities. Precision breeding specialists with in-house analytical laboratories capture pharmaceutical contract flows, while heirloom preservation networks serve artisanal cosmetic channels. Three archetypes dominate: integrated seed houses with backward integration into cultivation, regional adaptation specialists with documented germplasm libraries, and open-pollinated preservation networks. Competitive moves concentrate on geographic expansion into Mediterranean contract cultivation zones and technology licensing for marker-assisted selection platforms.
Among Dutch-integrated seed houses, Bejo Zaden B.V. occupies a position exemplifying vegetable seed infrastructure repurposed for pharmaceutical-grade chamomile genetics. Johnny's Selected Seeds and Territorial Seed Company represent the North American heirloom segment, with the former anchoring open-pollinated Roman chamomile lines for small-scale organic farms and the latter sitting within the regional adaptation specialist tier through Pacific Northwest germplasm with documented essential oil profiles.
| Leading Market Players |
|---|
| Bejo Zaden B.V. |
| Baker Creek Heirloom Seed Co |
| Johnny's Selected Seeds |
| Semillas Fitó |
| B&T World Seeds |
| The Green Seed Company |
| Mountain Rose Herbs |
| Territorial Seed Company |
| Seattle Seed Company |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Egyptian contract cultivation zones is compressing supplier margins while elevating pricing power for integrated seed houses with captive Mediterranean production. This utilization squeeze forces smaller open-pollinated producers toward cooperative aggregation or exit, concentrating procurement leverage among pharmaceutical-grade genetics suppliers.
Pricing Analysis
Conventional open-pollinated seed stock trades at commodity benchmarks while precision-bred pharmaceutical-grade cultivars with documented azulene profiles command substantial premiums, and next-generation marker-assisted selection lines are entering pilot pricing tiers. Three-tier pricing structure across certified organic, conventional commercial, and heirloom preservation levels separates buyers by certification depth and analytical documentation requirements. Pricing pressure stems from REACH compliance costs for seed treatment residue screening, which disproportionately burdens small-scale producers lacking in-house laboratory capabilities. Artisanal cosmetic formulators show highest price sensitivity due to lot size fragmentation, while pharmaceutical extractors absorb premiums for batch-level traceability under EU Organic Regulation mandates.
Supply Chain Analysis
Murcia-based vertical seed-to-oil operations and Andalusian contract cultivation networks anchor European capacity, while Nile Delta smallholder aggregations and Pacific Northwest cooperative platforms hold regional supply positions. The chain draws from irrigation-dependent Egyptian biomass, German precision breeding germplasm, and French cosmetic-grade ester-profiled stock. Single-source vulnerability concentrates in Nile Delta water-scarce production zones where climate stress elevates contract default risk. Distribution runs through wholesale botanical brokers for industrial processors, though direct-to-grower platforms fragment artisanal channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic bisabolol and chamazulene isolates from petrochemical feedstocks pose a credible substitution threat that seed-to-oil incumbents must neutralize through certification differentiation and traceability investments.
For Market Incumbents: Build regulatory moats by embedding EU Organic Regulation 2018/848 lot traceability into proprietary digital platforms, creating non-replicable documentation depth. Pursue backward integration into Murcia and Castilla-La Mancha cultivation zones to secure captive supply for pharmaceutical contract flows. Counter synthetic substitution threats by financing near-infrared spectroscopy seed sorting deployments that pre-qualify essential oil potential before sowing.
For New Entrants and Emerging Players: Build out white-space positions in Pacific Northwest cooperative aggregation platforms serving artisanal cosmetic formulators seeking regionally adapted Roman chamomile germplasm. Target Spain's vertical seed-to-oil expansion corridor where pharmaceutical extractors seek bypass relationships outside established wholesale channels. Deploy direct-to-grower digital platforms with batch-level terpene documentation as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision breeding and in-house analytical laboratory capabilities, favoring scaled integrated seed houses over fragmented open-pollinated networks. Prioritize acquisition targets with documented germplasm libraries and existing EU Organic Regulation certification infrastructure. Monitor irrigation water allocation policies in Egyptian contract zones as the critical inflection signal for Mediterranean supply security.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Breeding Platform Investment | Marker-assisted selection capabilities lock in pharmaceutical-grade contract flows from Saxony-Anhalt extractors. |
| Backward Integration into Cultivation | Murcia-based seed-to-oil operations bypass wholesale intermediaries to capture margin from EFSA-compliant germplasm. |
| Digital Traceability Infrastructure | Blockchain lot tracking satisfies EU Organic Regulation 2018/848 mandates for French cosmetic formulators. |
| Spectral Imaging Seed Sorting | Near-infrared systems enable real-time essential oil potential assessment for German pharmaceutical pre-qualification. |
| Regional Germplasm Library Expansion | Pacific Northwest adaptation specialists capture premium positioning from Oregon Willamette Valley terpene-documented stock. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with seed house breeding directors, pharmaceutical extraction procurement leads, organic cosmetic formulators, and Mediterranean contract cultivation coordinators; and secondary validation through EU Organic Regulation compliance filings, EFSA phytosanitary certification databases, USDA National Organic Program standards documentation, and REACH seed treatment residue threshold records. Bottom-up cultivation area estimates and top-down essential oil demand projections were triangulated to anchor volume assumptions.
Forecast inputs span German chamomile pharmaceutical-grade genetics adoption curves, Roman chamomile ester-profiled cosmetic contract growth, and wild chamomile foraging permit constraints across the analysis window. Segmentation dimensions modeled include product type tier, end-use channel certification requirements, distribution channel fragmentation, and regional production hub water security profiles. CAGRs were derived from essential oil extraction capacity expansion timelines and pharmacopeial assay specification tightening trajectories.
Practitioners should monitor synthetic isolate pricing spreads, Nile Delta irrigation allocation policies, and pharmacopeial monograph revision schedules for early signals of forecast revision. Quarterly review of EFSA seed purity enforcement intensity and REACH residue threshold adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Russia Forage Seed Market
Seeds
Asia-Pacific Rice Seed Market
Seeds
Avena Sativa Market
Seeds
Flax Crop Market
Seeds
South America Forage Seed Market
Seeds
Agricultural Seeder Market
Seeds
Sweet Corn Seeds Market
Seeds
Asia-Pacific Cotton Seed Market
Seeds
Vietnam Vegetable Seed Market
Seeds
Hemp Seed Oil Market
Seeds
Europe Quinoa Seed Market
Seeds
Sesame Seeds Market
Seeds
Guar Market
Seeds
Africa Vegetable Seed Market
Seeds
North America Quinoa Seeds Market
Seeds
Commercial Seed Market