
 Global Furniture Fittings Market | 2026-2036
Global Furniture Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Furniture Fittings Market Analysis
A capital-intensity divergence between automated forging operations and manual assembly lines is redrawing competitive boundaries in furniture fittings. Hettich leverages robotic stamping cells to sustain cost leadership on high-volume hinge programs. Blum differentiates through captive R&D on push-to-open mechanisms, while Sugatsune specializes in precision stainless-steel hardware for premium architectural interiors.
Furniture fittings comprise mechanical hardware components—hinges, slides, handles, and locking systems—typically fabricated from cold-rolled steel, zinc alloys, or engineered polymers through progressive die stamping, injection molding, and surface finishing processes; these components govern the functional movement, security, and ergonomic interface of case goods, cabinetry, and seating assemblies. Hinges and drawer slides anchor the largest value pools given their ubiquity across residential and commercial installations, while composite-material handles represent the fastest-expanding segment as sustainability mandates reduce dependence on virgin metal feedstocks. The hospitality end-user channel commands above-average margins due to specification-grade durability requirements and bulk procurement cycles.
REACH restrictions on hexavalent chromium coatings and the EU Green Deal's embodied-carbon thresholds are forcing reformulation of metal surface treatments across European supply chains, while China's GB standards for indoor air quality propagate through export-oriented OEMs. The US EPA oversees volatile organic compound limits on finishes applied to domestic-sourced hardware. Stakeholders must monitor evolving chemical-compliance deadlines and decide between reformulating existing product lines or accelerating migration toward bio-based polymer alternatives.
Market Dynamics
REACH chemical restrictions on hexavalent chromium coatings and the EU Green Deal's embodied-carbon thresholds are forcing wholesale reformulation of metal surface treatments across European supply chains, while Chinese OEMs propagate GB indoor air quality standards through export manufacturing clusters.
Growth Catalysts
- Residential renovation waves:Germany and Italy are experiencing sustained retrofit activity that lifts specification-grade hinge and concealed drawer system volumes.
- REACH compliance deadlines:The ECHA-mandated phase-out of toxic metal coatings accelerates investment in bio-based polymer alternatives and PVD surface finishing.
- Guangdong manufacturing concentration:China's furniture OEM clusters in Foshan and Dongguan source fittings at scale, creating procurement pull for standardized hinge and slide platforms.
Market Restraints
- Zinc alloy input volatility:Cold-rolled steel and zinc feedstock price swings compress margin stability for mid-tier stamping operations.
- Supply concentration risk:Precision forging capacity clusters in China's Pearl River Delta, exposing buyers to single-region disruption scenarios.
- Technical substitution pressure:Adhesive bonding and magnetic mounting systems displace mechanical fasteners in lightweight furniture assemblies.
Strategic Opportunities
- Underpenetrated Indian residential:India's urban housing stock lacks soft-close hardware penetration, presenting volume expansion potential for standard slide and hinge platforms.
- EU Green Deal tailwind:The EU's circular economy action plan rewards fittings with recycled-content certification and take-back program integration.
- Direct-to-fabricator digital channels:B2B platforms connecting Vietnamese and Indonesian furniture workshops to component suppliers bypass traditional distributor markups.
Industry Challenges
- Surface engineering talent scarcity:PVD coating and electrochemical finishing expertise concentrates in German and Japanese supplier bases, constraining technology transfer.
- Multi-certification capex burden:Simultaneous compliance with REACH, EPA VOC limits, and China's GB standards demands redundant testing infrastructure.
- Legacy ERP integration friction:Furniture OEMs running on-premise MRP systems face data interoperability barriers when adopting IoT-enabled smart hinge platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Furniture Fittings Market |
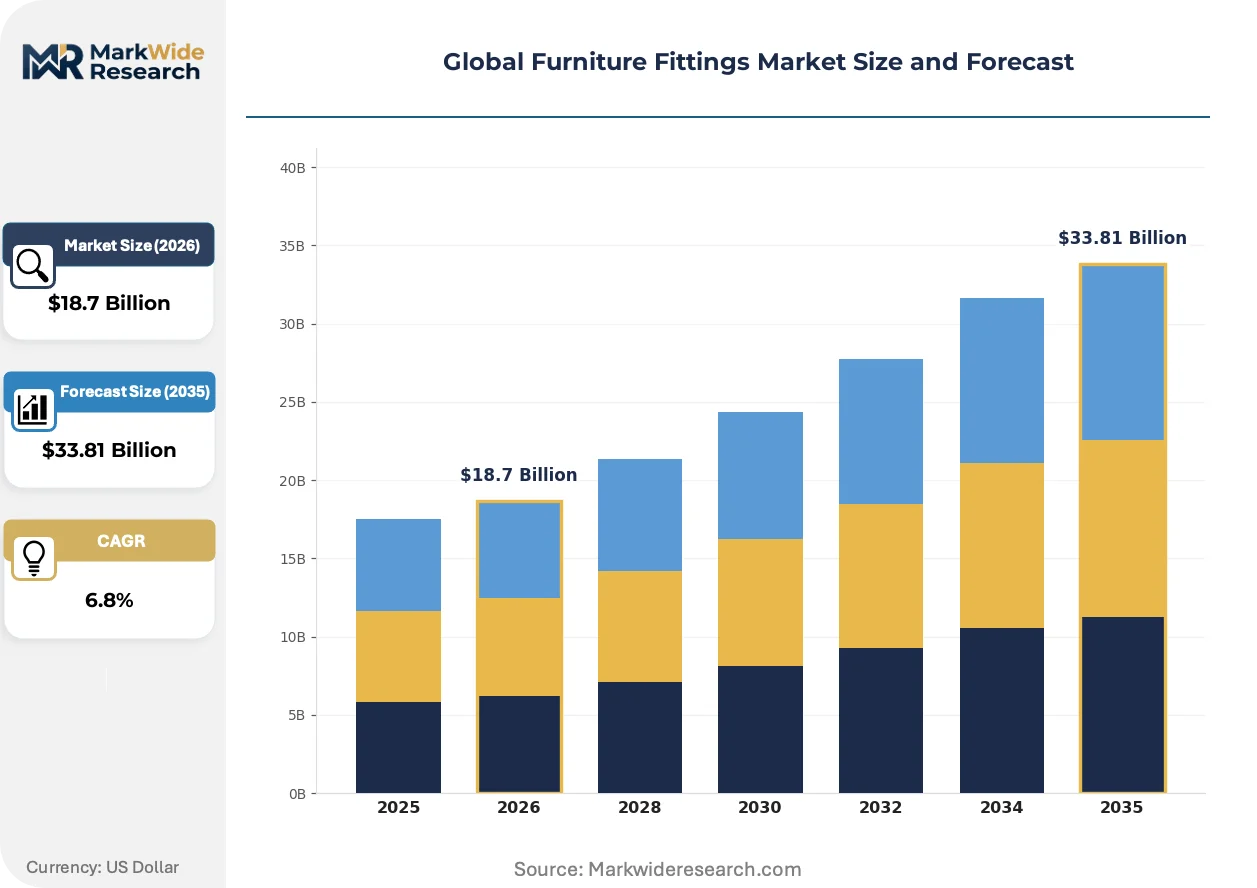
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hinges, Drawer Slides, Handles, Locks Material: Metal, Plastic, Wood, Composite End User: Residential, Commercial, Industrial, Hospitality Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Häfele, Accuride, Hettich, King Slide Works, Titus Group, Blum, Salice, Sugatsune, Grass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Furniture Fittings Market Emerging Trajectories
Actively reshaping this market are three intersecting forces: mechanical component miniaturization for space-constrained urban furniture, regulatory chemistry reformulation across multiple jurisdictions, and procurement model evolution driven by e-commerce platform penetration.
Micro-hinge architectures incorporating torque-adjustable friction damping are miniaturizing. High-density residential developers in Tokyo and Singapore specify these for built-in cabinetry where millimeter-clearance tolerances dominate. The technology compresses traditional three-piece hinge assemblies into single-unit stamped forms, reducing hardware weight by half while maintaining load ratings.
The EPA's volatile organic compound emission limits on architectural coatings now extend to furniture hardware finishes applied in domestic U.S. manufacturing. This forces reformulation of solvent-based lacquers toward waterborne UV-cured alternatives. Hospitality specification buyers in California and New York now require third-party VOC certification as a procurement gate.
Consolidated procurement through vertical e-commerce marketplaces is displacing traditional two-step distribution through regional hardware wholesalers. Medium-sized furniture fabricators in Poland and Mexico now source slides and handles directly from Guangdong suppliers via Alibaba and Made-in-China platforms, compressing lead times from twelve weeks to four while eroding distributor margin pools.
Global Furniture Fittings Market Segmentation
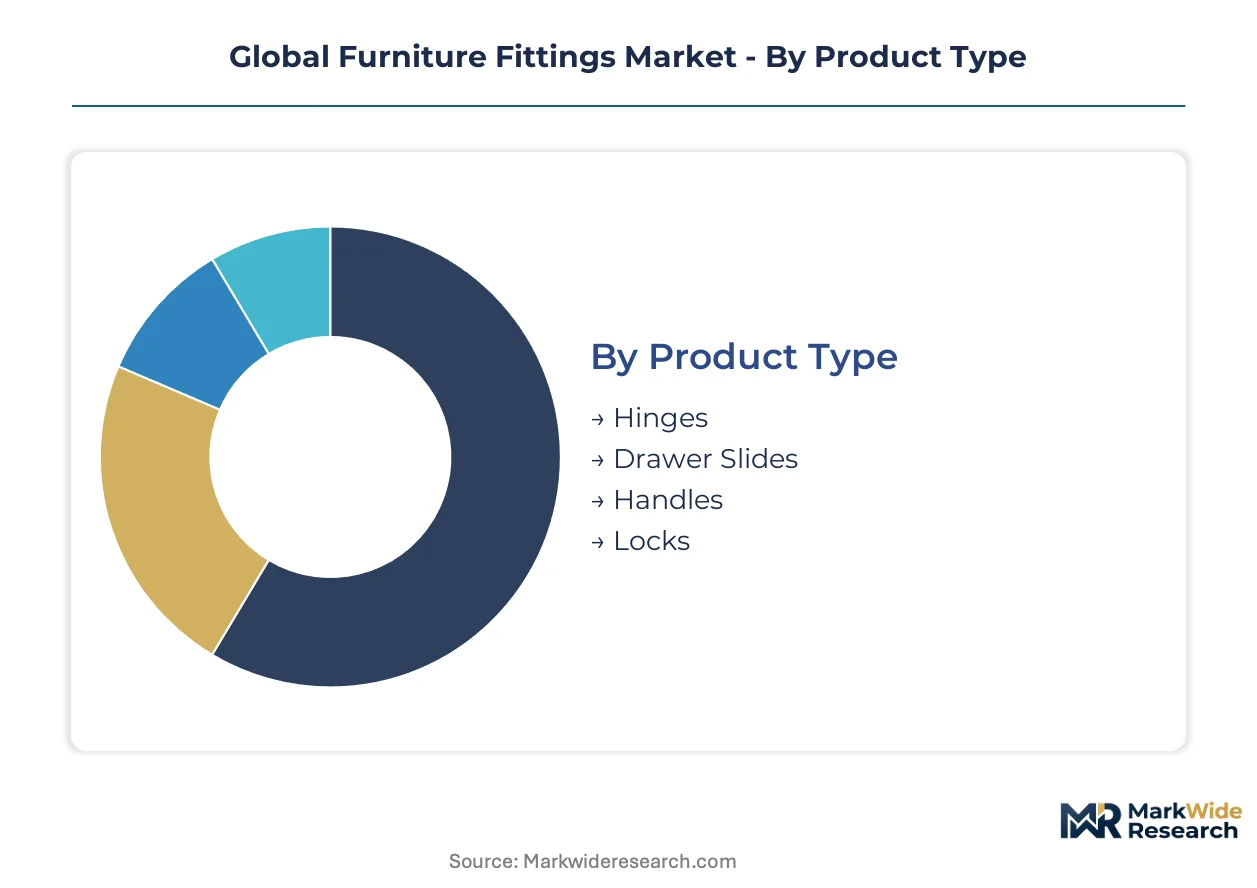
Furniture fittings traverse highly differentiated procurement paths, with specification-grade hardware for hospitality projects moving through dedicated sales teams while standardized residential components flow via e-commerce platforms. Understanding segment-channel alignment reveals where margin pools concentrate and which material innovations gain scale fastest.
Product Type:
Hinges and drawer slides dominate bulk procurement through wholesale distributors serving Guangdong furniture clusters, while handles and locks fragment across specialty retail and project-direct channels depending on customization depth.
- Hinges:Mechanical assemblies fabricated from cold-rolled steel or zinc alloys with surface treatments ranging from electroplated nickel to PVD coatings. German and Italian residential renovation projects specify soft-close torque mechanisms, driving volume for concealed cup hinges with integrated damping.
- Drawer Slides:Telescoping rail systems engineered for load-bearing capacity and extension travel, typically constructed from galvanized steel with polymer glide inserts. China's OEM manufacturers in Foshan and Dongguan source standardized ball-bearing slides at scale, creating procurement concentration for 45mm and 35mm width platforms.
- Handles:Ergonomic grip components spanning pull bars, knobs, and recessed profiles; material mix shifts toward recycled-content composites under EU Green Deal circular economy requirements.
- Locks:Security mechanisms for cabinetry and furniture enclosures, including cam locks and electronic RFID systems; hospitality specification buyers demand master-key compatibility and fire-rating compliance.
By volume, hinges lead. By growth pace, handles are expanding most quickly.
Material:
Cost tier stratification separates premium architectural specifications from mass-market residential, with metal commanding hospitality and commercial projects while plastics and composites penetrate economy residential segments.
- Metal:Cold-rolled steel, zinc alloys, and stainless steel deliver structural integrity for load-bearing applications. REACH-mandated hexavalent chromium phase-outs are accelerating PVD and electroless nickel adoption across European supply chains.
- Plastic:Engineered polymers including glass-filled nylon and ABS for cost-sensitive hardware; China's GB indoor air quality standards propagate through export-oriented OEMs, restricting phthalate and formaldehyde content.
- Wood:Solid timber and veneer-wrapped substrates for decorative handles in premium residential; supply constraints on certified sustainable hardwoods limit scalability.
- Composite:Bio-based and recycled-content materials combining natural fibers with polymer matrices; EU Green Deal embodied-carbon thresholds reward suppliers with Environmental Product Declarations.
Metal retains the largest value share. Composite formulations are gaining share fastest.
End User:
Application requirements dictate performance specifications, with hospitality and commercial buyers prioritizing cycle-life durability while residential trade-offs favor cost and aesthetic flexibility.
- Residential:Single-family and multi-family housing stock drives volume for standardized hinge and slide platforms; India's urban housing expansion presents underpenetrated demand for soft-close mechanisms.
- Commercial:Office and institutional furniture requires heavy-duty hardware with extended warranty terms; specification-grade durability commands above-average margins.
- Industrial:Workshop and storage applications prioritize load capacity over finish quality; procurement flows through wholesale distributors with volume pricing structures.
- Hospitality:Hotels and cruise ships demand fire-rated, corrosion-resistant hardware with master-key systems; bulk procurement cycles and brand-standard compliance create sticky supplier relationships.
Residential generates the highest unit volumes. Hospitality delivers the steepest margin expansion trajectory.
Distribution Channel:
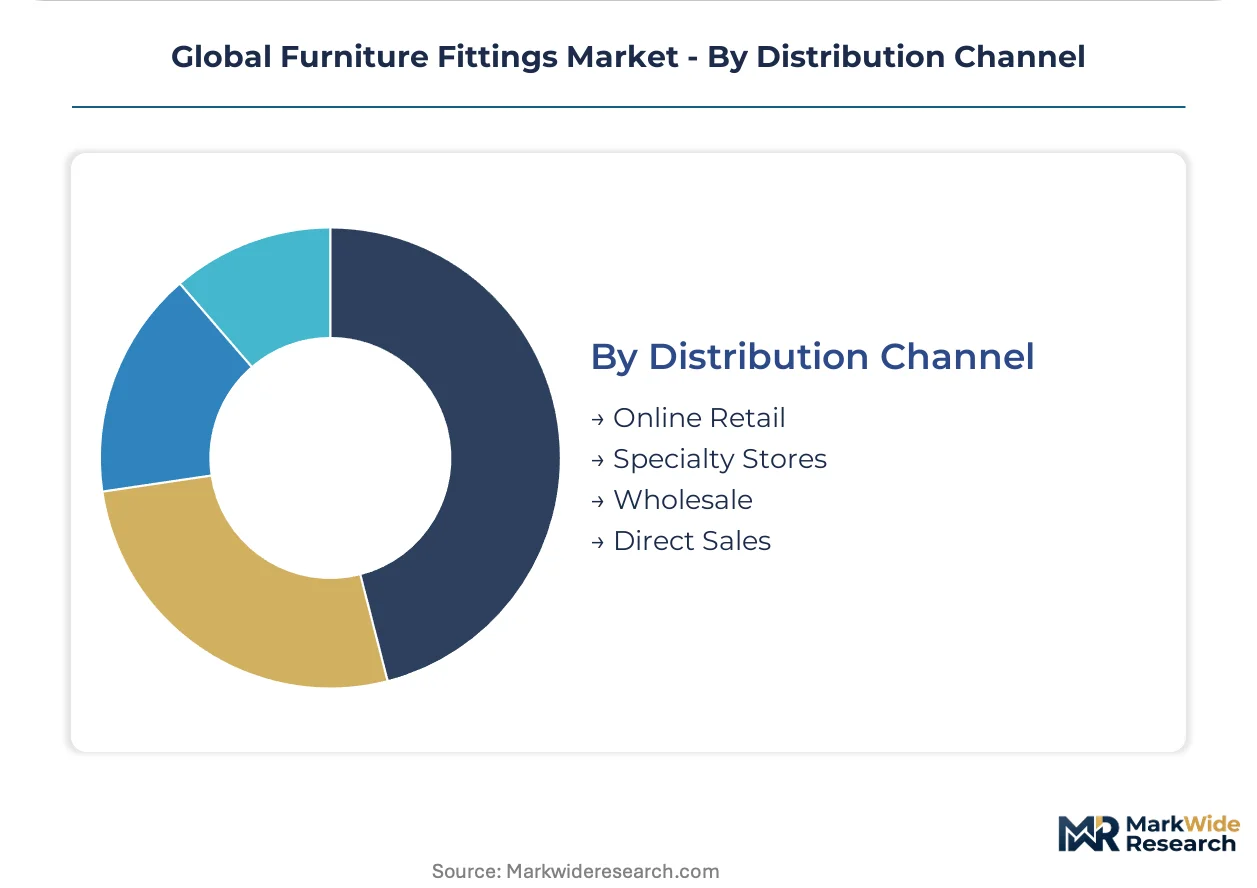
Customer type and order scale determine channel selection, with large fabricators bypassing intermediaries while smaller workshops rely on platform aggregation.
- Online Retail:Vertical e-commerce marketplaces including Alibaba and Made-in-China compress lead times for Polish and Mexican furniture fabricators sourcing Guangdong suppliers directly.
- Specialty Stores:Regional hardware wholesalers with physical showrooms serve renovation contractors requiring same-day availability and technical consultation.
- Wholesale:Two-step distribution through national distributors stocks inventory for mid-tier furniture manufacturers with predictable production schedules.
- Direct Sales:Manufacturer-employed specification teams engage hospitality and commercial project developers for custom-engineered solutions.
Wholesale moves the largest tonnage. Online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Italy show low price elasticity for specification-grade hardware, while Vietnamese and Indonesian workshops prioritize cost minimization over performance tiers. China's Guangdong province anchors procurement volume for standardized hinge and slide platforms.
China
Foshan and Dongguan furniture OEM clusters source ball-bearing slides and concealed hinges at scale for export manufacturing. GB standards for indoor air quality propagate through supplier networks, restricting phthalate content in polymer glide inserts. Pearl River Delta forging capacity concentrates precision stamping operations for 45mm and 35mm slide platforms.
Germany
Residential renovation activity in Berlin and Munich sustains specification-grade demand for soft-close torque mechanisms and PVD-coated hardware. ECHA-mandated REACH compliance deadlines accelerate hexavalent chromium phase-outs across metal surface treatment facilities. Baden-Württemberg industrial clusters house captive R&D operations for push-to-open mechanism development.
United States
Hospitality specification buyers in California and New York require third-party VOC certification as a procurement gate for furniture hardware finishes. EPA volatile organic compound limits extend to solvent-based lacquers applied in domestic manufacturing. Southeast distribution hubs serve mid-tier furniture fabricators with volume pricing structures.
India
Urban housing stock in Mumbai and Delhi-NCR lacks soft-close hardware penetration, presenting volume expansion potential for standard slide platforms. BIS certification requirements for imported mechanical hardware create compliance barriers for unbranded suppliers. Gujarat manufacturing corridors attract stamping operations serving domestic OEM assembly lines.
Italy
Milan and Turin renovation contractors specify concealed cup hinges with integrated damping for high-end residential cabinetry. EU Green Deal embodied-carbon thresholds reward suppliers with Environmental Product Declarations for recycled-content hardware. Lombardy precision engineering clusters maintain expertise in electrochemical finishing and PVD coating technologies.
Global Furniture Fittings Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Automated forging specialists command premium positioning through robotic stamping cells and captive R&D pipelines, while manual assembly operators compete on price for standardized residential components. Three archetypes dominate: scale-driven mass producers, precision engineering specialists, and vertically integrated component fabricators. M&A activity concentrates precision forging capacity, and strategic partnerships link Guangdong suppliers to European specification channels.
Among German-based manufacturers, Hettich GmbH exemplifies the scale-driven archetype through automated production systems, while Blum anchors the technology leadership tier with captive innovation pipelines. Japanese precision specialists represented by Sugatsune occupy positions serving architectural-grade specification channels. These three companies illustrate how geographic origin and organizational structure correlate with competitive positioning across cost-sensitive and performance-driven market segments.
| Leading Market Players |
|---|
| Häfele |
| Accuride |
| Hettich |
| King Slide Works |
| Titus Group |
| Blum |
| Salice |
| Sugatsune |
| Grass |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Guangdong forging clusters and European OEMs lock in zinc alloy feedstock access while capping price volatility exposure across quarterly procurement cycles. These arrangements tether margin stability to Pearl River Delta capacity utilization rates and REACH-compliant surface treatment premiums.
Pricing Analysis
After-sales service revenue from hinge refurbishment and slide replacement programs drives lifetime value for specification-grade suppliers. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale. Cost compression in mid-tier stamping operations is intensifying because zinc feedstock volatility compresses margin buffers. Hospitality specification buyers in California and New York show lowest price sensitivity, while Vietnamese furniture workshops prioritize cost minimization above performance tiers.
Supply Chain Analysis
Just-in-time inventory preferences dominate among Guangdong OEM clusters serving export markets, though European distributors maintain strategic stockpiles of REACH-compliant hardware ahead of regulatory deadlines. Supply concentrates in China, Germany, and Italy for precision forging and surface finishing. The chain draws from cold-rolled steel, zinc alloys, and engineered polymer feedstocks. Single-source vulnerability in Pearl River Delta stamping capacity exposes buyers to regional disruption scenarios. Distribution runs through vertical e-commerce marketplaces displacing traditional two-step wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Furniture fittings constitute a defensive-moat market where regulatory entrenchment creates sticky supplier relationships through multi-certification compliance burdens and specification-grade durability requirements.
For Market Incumbents: Compound switching-cost advantages by embedding IoT-enabled smart hinge platforms into legacy ERP systems, deepening captive R&D pipelines for push-to-open mechanisms, and expanding precision forging capacity in Baden-Württemberg clusters to offset Pearl River Delta concentration risk. For New Entrants and Emerging Players: Differentiate on bio-based polymer alternatives to hexavalent chromium coatings, targeting India's underpenetrated urban housing stock for soft-close hardware adoption, and leveraging direct-to-fabricator digital channels to bypass established distributor markups. For Investors and Strategic Acquirers: Precision forging specialists with PVD coating expertise represent the most compelling acquisition targets for portfolio exposure to EU Green Deal tailwinds. Long-term viability hinges on circular economy certification integration and take-back program scalability. Watch for inflection when Environmental Product Declaration adoption rates cross hospitality procurement thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Surface Treatment Migration | ECHA-mandated hexavalent chromium phase-outs accelerate PVD and electroless nickel adoption across European supply chains. |
| Backward Integration into Zinc Alloy Feedstock | Captive smelting operations insulate mid-tier stamping facilities from commodity price volatility in cold-rolled steel markets. |
| Direct-to-Fabricator Digital Channel Launch | Alibaba and Made-in-China platforms compress lead times for Polish and Mexican furniture workshops sourcing Guangdong suppliers. |
| IoT-Enabled Smart Hinge Platform Development | Integration with furniture OEM MRP systems creates data interoperability barriers that reinforce incumbent switching costs. |
| Environmental Product Declaration Certification | EU Green Deal embodied-carbon thresholds reward suppliers with recycled-content verification and circular economy program integration. |
Methodological Framework
Desk research of customs trade data, SEC filings from listed component suppliers, and ECHA regulatory databases preceded structured interviews with furniture OEM procurement directors, hospitality specification buyers, surface treatment facility operators, and precision forging plant managers. Primary fieldwork combined with secondary validation across REACH compliance documentation and GB standards filings enabled bottom-up and top-down triangulation of market sizing.
Variance decomposition across product type, material grade, end-user application, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories and value-per-unit assumptions incorporated zinc alloy price elasticity, renovation cycle timing, and certification adoption curves as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained residential renovation activity in Germany and Italy or uninterrupted Pearl River Delta manufacturing operations would require recalibration. Forecasts reflect documented assumptions regarding REACH enforcement timelines and GB standards propagation through export-oriented OEMs. Revision becomes warranted when adhesive bonding substitution rates for mechanical fasteners cross hospitality specification thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Europe Sustainable Furniture Market
Furniture
Armchair on Casters Market
Furniture
Indonesia Furniture Market
Furniture
Ready-To-Assemble (RTA) Furniture Market
Furniture
United States Upholstered Furniture Market
Furniture
Saudi Arabia Home Furniture Market
Furniture
Bar Stools Market
Furniture
US Sustainable Furniture Market
Furniture
Global Furniture Market
Furniture
Global Smart Furniture Market
Furniture
Lecterns Market
Furniture
Study Carrels Market
Furniture
UAE Home Furniture Market
Furniture
United Kingdom Home Furniture Market
Furniture
Ergonomic Chair for Children Market
Furniture
North America Free Standing Electrical Height-Adjustable Tables Market