
 Luxury Furniture Market | 2026-2036
Luxury Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Furniture Market Analysis
Ultra-high-net-worth residential buyers are unwinding the hospitality sector's historical dominance in luxury furniture procurement. Poltrona Frau anchors its position through vertical integration of leather tanning and upholstery craftsmanship in its Tolentino facilities. Molteni&C competes via R&D intensity in modular storage systems and architectural interior solutions. Roche Bobois dominates the French contemporary segment through controlled distribution of its licensed designer collections.
Luxury furniture comprises handcrafted or limited-production interior furnishings manufactured from premium materials such as full-grain leather, solid hardwoods, and engineered metal alloys, typically finished to tolerances of 0.1 millimeter for joinery and upholstery fit. Sofas and chairs command the largest margin pools due to upholstery complexity and brand premiumization, while tables sustain growth through artisanal woodcraft positioning in residential and hospitality channels. The hospitality end-user segment leads volume absorption, though residential demand for contemporary and modern design styles is accelerating faster in urban core markets.
REACH governs chemical restrictions on leather tanning agents and textile dyes across European supply chains, while the EU Green Deal's deforestation-free product requirements reshape sourcing of tropical hardwoods. The US EPA and California Air Resources Board regulate formaldehyde emissions from composite wood substrates, elevating compliance costs for imported case goods. Stakeholders must monitor evolving Extended Producer Responsibility frameworks and decide whether to absorb certification costs or reposition toward domestically sourced material streams.
Market Dynamics
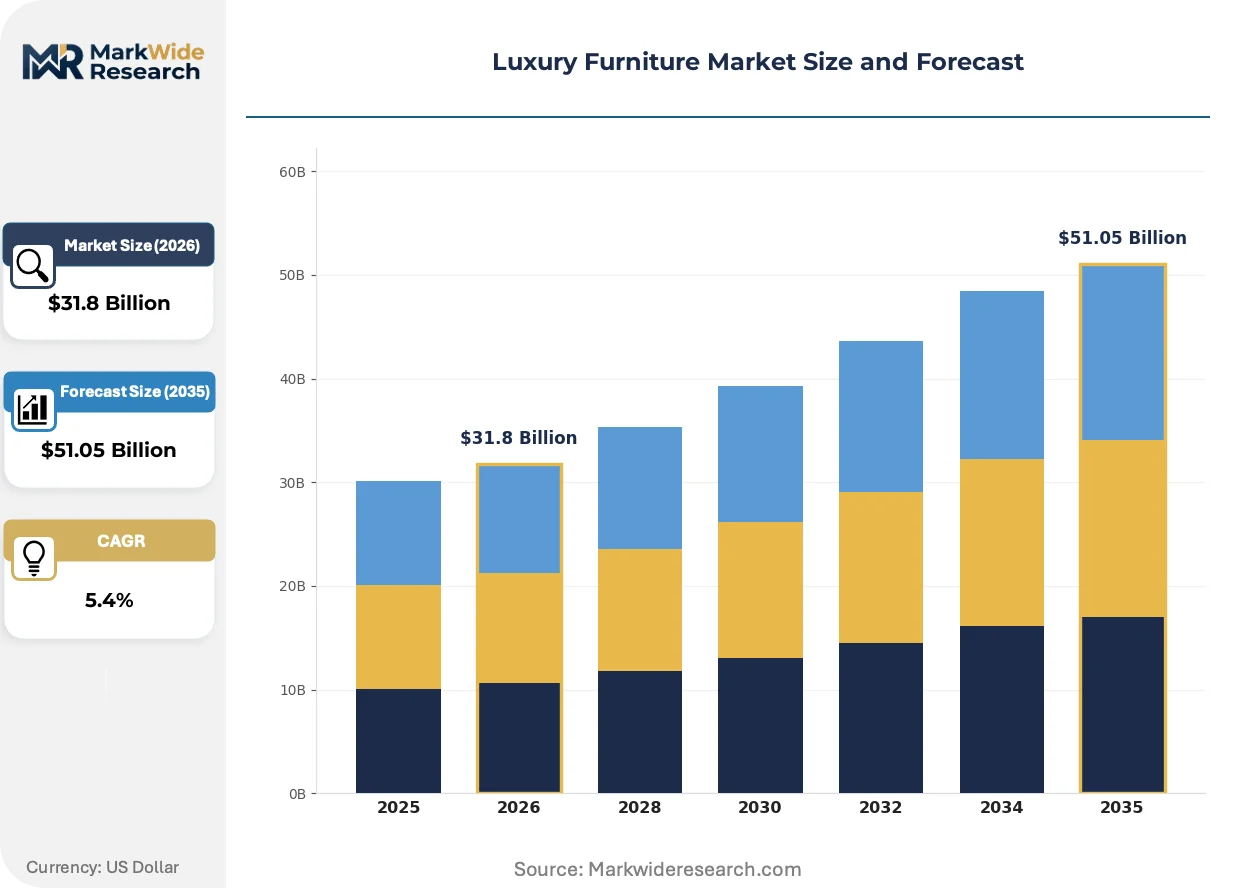
The EU Ecodesign for Sustainable Products Regulation is forcing material traceability restructuring across upholstered goods supply chains, while hospitality procurement of bespoke seating concentrates demand in Italy's Brianza manufacturing cluster.
Growth Catalysts
- Hospitality Design Procurement:Hotel and restaurant designers are expanding acquisition of custom seating and case goods, pulling volume toward limited-production workshops capable of rapid customization cycles.
- REACH Chemical Compliance:Leather tanning agents and textile dyes face tightened restrictions across European supply chains, advantaging tanneries with pre-certified chemical management systems.
- Brianza Cluster Concentration:Manufacturing gravity centers on the Milan-adjacent furniture district, where subcontractor density enables rapid prototyping and artisanal finishing at scale.
Market Restraints
- Tropical Hardwood Sourcing:The EU Green Deal's deforestation-free product requirements are compressing available supply of certified mahogany and teak, elevating raw material costs for solid wood tables.
- Composite Wood Emissions:US EPA and California Air Resources Board formaldehyde regulations impose compliance burdens on imported case goods, disadvantaging distant suppliers without captive substrate production.
- Skilled Upholstery Labor:Master craftsmen capable of 0.1 millimeter tolerance finishing remain concentrated in Northern Italy and select Portuguese workshops, constraining production scaling.
Strategic Opportunities
- Extended Producer Responsibility Frameworks:Evolving take-back mandates in Germany and France create first-mover advantage for brands establishing circular collection infrastructure.
- Residential Ultra-High-Net-Worth Segment:Private buyers in urban core markets are accelerating contemporary and modern design acquisition faster than traditional hospitality channels.
- Architectural Interior Solutions:Modular storage systems integrating with built-in environments represent underpenetrated white space beyond standalone furniture positioning.
Industry Challenges
- Master Craftsman Recruitment:The pipeline of artisans trained in traditional joinery and hand-finishing techniques is narrowing across European manufacturing regions.
- Certification Timeline Compression:Dual carbon goals in China and evolving ECHA substance restrictions are shortening product development cycles while lengthening compliance verification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Furniture Market |
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $51.05 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Sofas, Tables, Beds Material: Wood, Leather, Metal, Soft Fabrics Design Style: Modern, Traditional, Contemporary, Rustic End User: Residential, Hospitality, Office, Retail |
| Companies Covered | Poltrona Frau, Cassina, Minotti, Natuzzi, Roche Bobois, Poliform, Molteni&C, Fendi Casa, B&B Italia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Furniture Market Emerging Trajectories
Digital material passports and blockchain traceability systems are reshaping how luxury furniture brands document provenance and environmental credentials across multi-tier supply chains.
Plant-based leather alternatives derived from mycelium and agricultural waste are displacing conventional full-grain hides in contemporary seating collections. Hospitality designers in Copenhagen and Amsterdam are specifying these materials for high-traffic lobby installations. The shift is compressing traditional tannery margins while opening premium positioning for biofabrication specialists with certified production scales.
The EU Green Deal's deforestation-free regulation is mandating satellite-verified chain-of-custody documentation for all tropical hardwood imports. Case goods manufacturers sourcing from Southeast Asia must now integrate geolocation tracking from forest concession to finished product. Italian table producers are responding by accelerating domestic walnut and oak sourcing from managed Alpine forests.
Direct-to-designer platforms are bypassing traditional showroom networks for residential and commercial project specification. Ultra-high-net-worth buyers in London, New York, and Singapore are commissioning bespoke pieces through digital interfaces with manufacturing visibility. This channel compression is most visible in contemporary segment growth, where lead-time transparency commands premium pricing over physical retail presence.
Luxury Furniture Market Segmentation
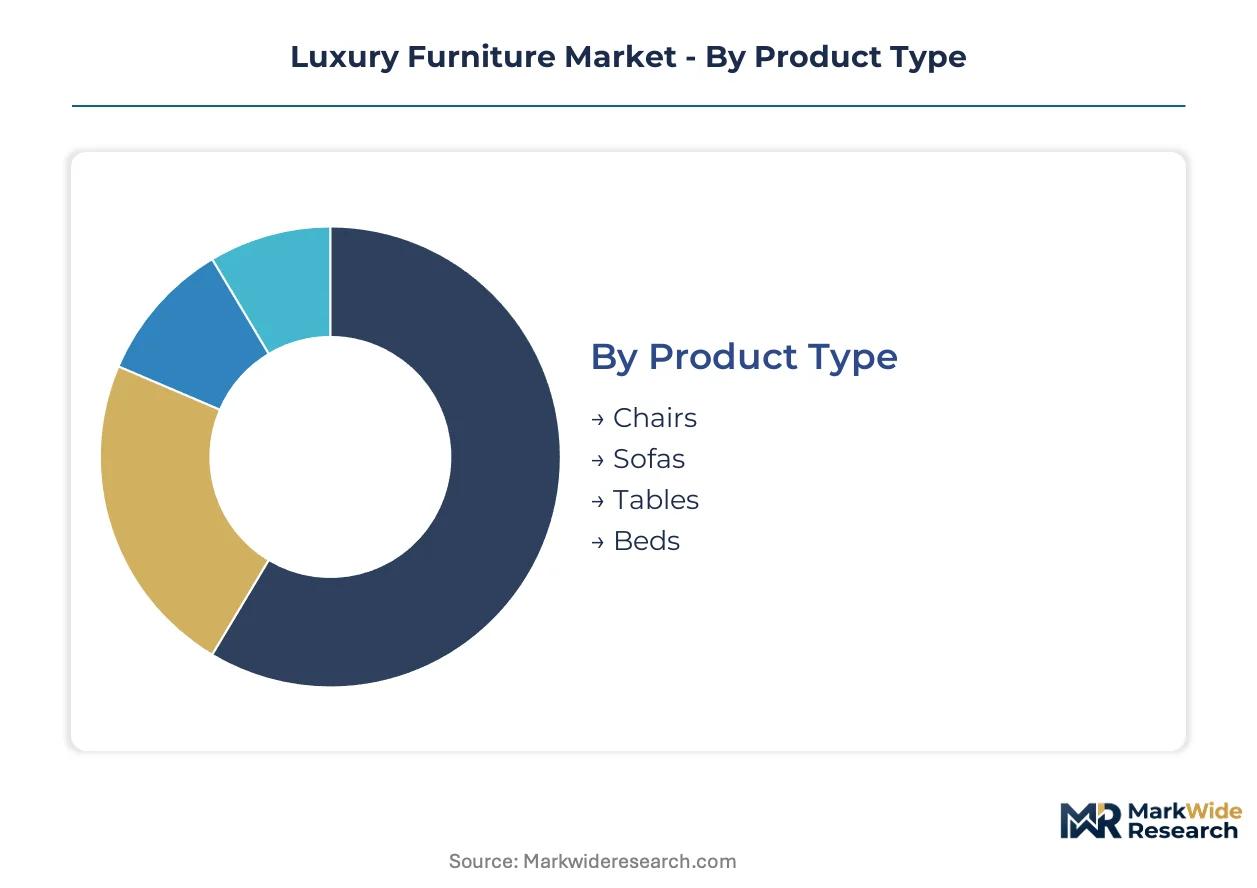
Segmentation in luxury furniture reveals how procurement channels fragment across end-use requirements and material specifications. Understanding these divisions exposes where margin pools concentrate and where supply chains face compliance pressure.
Product Type:
Channel mix varies sharply by product complexity, with upholstery-intensive categories flowing through designer-specified procurement while case goods move through broader retail networks.
- Sofas:Multi-component upholstered systems requiring precision-fit joinery at 0.1 millimeter tolerances. Demand concentrates in Italy's Brianza cluster where subcontractor density enables rapid customization cycles for hospitality procurement.
- Chairs:Seating spans dining, lounge, and accent configurations with varying upholstery complexity. Ultra-high-net-worth residential buyers in urban core markets are accelerating contemporary design acquisition faster than traditional hospitality channels.
- Tables:Artisanal woodcraft positioning drives specification in residential and hospitality channels alike. EU Green Deal deforestation-free requirements are compressing certified tropical hardwood supply and elevating raw material costs.
- Beds:Bedroom systems integrate upholstered headboards with solid wood or metal frames. Master craftsmen capable of hand-finishing remain concentrated in Northern Italy and select Portuguese workshops.
Sofas dominate installed base. Chairs are where expansion concentrates.
Material:
Cost tier stratification separates heritage material positioning from engineered alternatives, with certification premiums widening price spreads.
- Leather:Full-grain hides processed through vegetable tanning command heritage positioning. REACH restrictions on tanning agents and textile dyes advantage tanneries with pre-certified chemical management systems in European supply chains.
- Wood:Solid hardwoods and engineered substrates span case goods and structural frames. US EPA and California Air Resources Board formaldehyde regulations impose compliance burdens on imported goods without captive substrate production.
- Metal:Engineered alloys enable slender structural profiles in contemporary collections. Precision finishing requirements pull fabrication toward specialized workshops with investment casting capabilities.
- Soft Fabrics:Woven textiles and velvet upholstery provide color and texture variation at lower material cost. Plant-based alternatives derived from mycelium and agricultural waste are displacing conventional hides in Copenhagen and Amsterdam hospitality specifications.
Wood dominates installed base. Leather alternatives are climbing the fastest.
Design Style:
Customer type segmentation separates legacy wealth preservation from contemporary acquisition patterns, with channel preference diverging by buyer age cohort.
- Contemporary:Clean-lined forms with material experimentation appeal to urban residential buyers. Direct-to-designer platforms are bypassing traditional showroom networks for project specification in London, New York, and Singapore.
- Modern:Mid-century influenced geometries sustain hospitality procurement volume. Modular storage systems integrating with built-in environments represent underpenetrated white space beyond standalone furniture positioning.
- Traditional:Ornamented forms with heritage craft associations anchor estate and legacy residential demand. Master craftsman recruitment challenges constrain production scaling across European manufacturing regions.
- Rustic:Distressed finishes and reclaimed material narratives target secondary residence markets. Sourcing verification requirements complicate authentic reclaimed wood procurement.
Traditional dominates installed base. Contemporary is gaining share fastest.
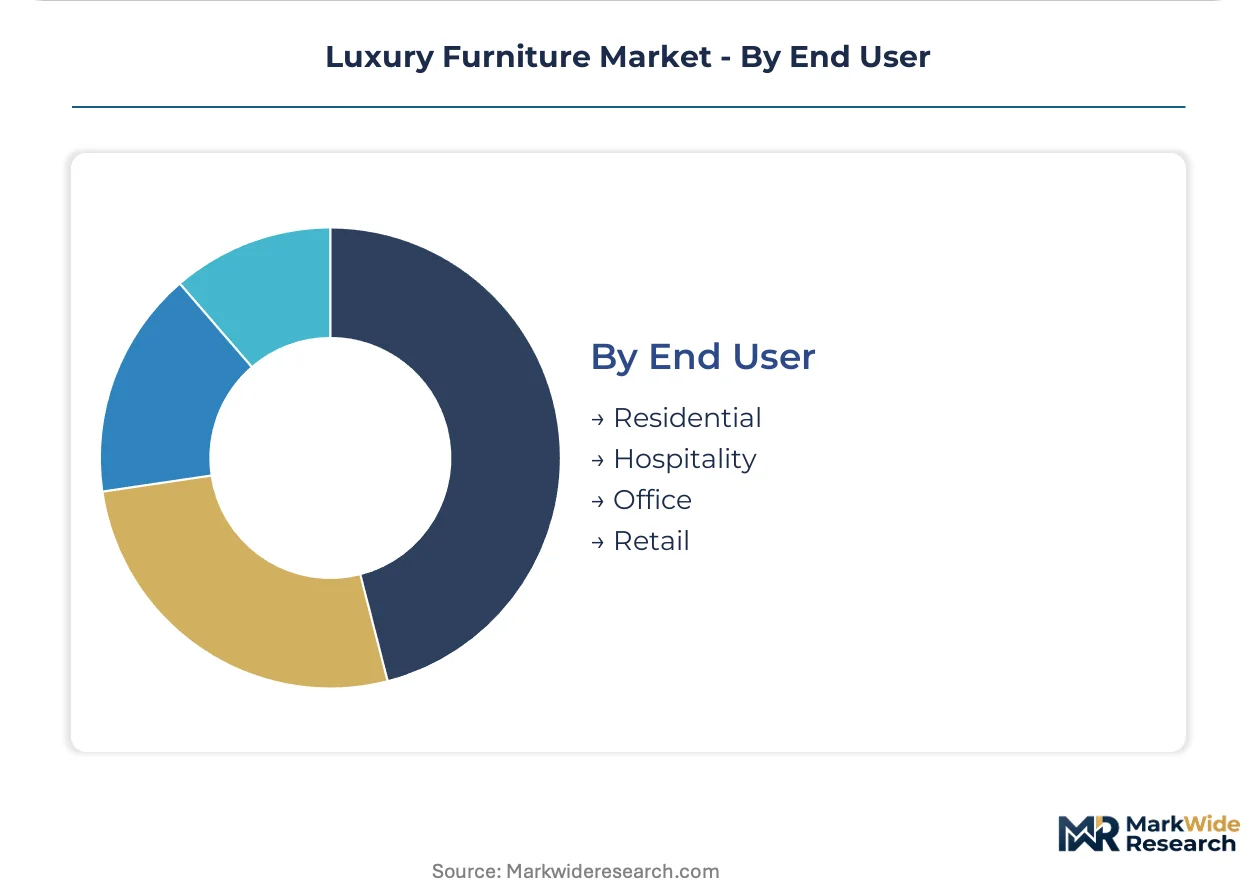
End User:
Application-driven segmentation reveals where volume absorbs versus where margin concentrates, with procurement authority residing in distinct decision-maker profiles.
- Hospitality:Hotel and restaurant designers specify custom seating and case goods with rapid customization cycles. Procurement concentrates in Italy's Brianza manufacturing cluster where subcontractor density enables rapid prototyping.
- Residential:Private buyers commission bespoke pieces through digital interfaces with manufacturing visibility. Ultra-high-net-worth segments in urban core markets are unwinding hospitality's historical dominance in luxury furniture procurement.
- Office:Executive workspace furnishings balance residential comfort cues with commercial durability specifications. Lead-time transparency commands premium pricing over physical retail presence in this channel.
- Retail:High-end showroom and boutique fixtures require brand-aligned custom fabrication. Extended Producer Responsibility frameworks in Germany and France create first-mover advantage for brands establishing circular collection infrastructure.
Hospitality dominates installed base. Residential is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's Adriatic port infrastructure at Trieste and Ravenna underwrites European luxury furniture import flows, while the US East Coast rail network from Savannah to New York distributes containerized case goods to interior design hubs.
United States
Ultra-high-net-worth residential buyers in Manhattan and Los Angeles commission bespoke pieces through direct-to-designer platforms. The EPA and California Air Resources Board regulate formaldehyde emissions from composite wood substrates. High-end upholstery workshops concentrate in North Carolina's High Point region, where legacy craft training programs sustain finishing expertise.
Italy
Hospitality designers specify custom seating with rapid customization cycles for hotel and restaurant installations. REACH restrictions on leather tanning agents advantage tanneries with pre-certified chemical management systems. The Brianza manufacturing cluster near Milan anchors subcontractor density for rapid prototyping and artisanal finishing at scale.
France
Contemporary design acquisition accelerates among private buyers in Paris and Lyon urban cores. The EU Green Deal's deforestation-free product requirements reshape tropical hardwood sourcing verification. Licensed designer collections dominate specification through controlled distribution networks centered on Paris showrooms.
Germany
Extended Producer Responsibility frameworks in Germany mandate take-back infrastructure for circular collection systems. ECHA substance restrictions tighten compliance timelines for imported case goods. Modular storage system specialists concentrate in North Rhine-Westphalia, integrating architectural interior solutions with built-in environments.
China
Dual carbon goals compress manufacturing timelines while lengthening compliance verification for export-oriented upholstery workshops. The country's national environmental regulator enforces emissions standards for substrate production facilities. Precision metal fabrication for contemporary collections clusters in Guangdong province near Shenzhen port infrastructure.
Luxury Furniture Market Vendor Landscape
Concentration sits with vertically integrated heritage houses and design-led architectural specialists. The vendor base spans three tiers: legacy Italian leather craftsmen, French contemporary licensing platforms, and modular systems engineers. Strategic moves center on backward integration into captive tannery operations and rapid customization cycle compression for hospitality procurement.
Among Italy-based heritage manufacturers, Poltrona Frau, Molteni&C, and Cassina exemplify the integrated craftsmanship archetype. These entities anchor positions through in-house production of premium materials and upholstery finishing capabilities. Roche Bobois occupies a position within the French contemporary licensing model, while Minotti and Poliform represent the architectural interior solutions specialization. The competitive dynamic pits territorial craft preservation against scale-enabled customization responsiveness.
| Leading Market Players |
|---|
| Poltrona Frau |
| Cassina |
| Minotti |
| Natuzzi |
| Roche Bobois |
| Poliform |
| Molteni&C |
| Fendi Casa |
| B&B Italia |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between hospitality procurement teams and Brianza-based workshops lock in both supply access and price visibility across multi-year furniture installation cycles. These arrangements shield Italian manufacturers from raw material volatility while anchoring buyer commitments to fixed upholstery and case goods volumes.
Pricing Analysis
Volume-discount tiering structures separate single-piece residential commissions from bulk hospitality orders, with the latter commanding 15-30% unit cost reductions at scale. Certification premiums for REACH-compliant leather and EU Green Deal-verified hardwoods widen spreads between compliant and non-compliant supply tiers. Pricing pressure intensifies in the standard-grade segment as Southeast Asian workshops compete on composite wood substrates. Ultra-high-net-worth residential buyers exhibit lowest price sensitivity, prioritizing lead-time transparency and customization depth over unit economics.
Supply Chain Analysis
Inbound logistics costs from Adriatic ports through Trieste and Ravenna fluctuate with container availability on Asia-Europe trade lanes, compressing margins for imported substrate components. Manufacturing gravity centers on Italy, Portugal, and select North Carolina workshops for upholstery finishing, while precision metal fabrication clusters in Guangdong province. Raw material dependencies span full-grain hides from European tanneries, certified tropical hardwoods facing deforestation-free verification, and engineered substrates subject to formaldehyde regulations. Single-source vulnerability concentrates in master craftsman availability across Northern Italy. Distribution runs through designer-specified procurement channels and direct-to-designer platforms bypassing traditional showroom networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from biofabricated leather alternatives and modular flat-pack systems that compress delivery timelines and erode artisanal premium positioning.
For Market Incumbents: Consolidate backward integration into captive tannery operations to secure REACH-compliant leather supply against biofabrication displacement. Compress customization cycle times through digital material passport integration, defending hospitality procurement relationships from agile competitors.
For New Entrants and Emerging Players: CE marking fast-tracks for EU Green Deal compliance unlock specification access in German and French hospitality markets. Target the architectural interior solutions segment where modular storage integration with built-in environments remains underpenetrated. Lead with direct-to-designer platform positioning in London and Singapore urban cores.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated heritage houses with in-house finishing capabilities. Long-term viability hinges on circular collection infrastructure ownership under Extended Producer Responsibility frameworks. Watch ECHA substance restriction announcements as inflection indicators for compliance cost acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannery Operations | REACH compliance secures leather supply access against regulatory compression. |
| Digital Material Passport Deployment | Blockchain traceability satisfies EU Ecodesign documentation requirements for upholstered goods. |
| Circular Collection Infrastructure Buildout | Extended Producer Responsibility mandates in Germany and France create first-mover advantage. |
| Direct-to-Designer Platform Launch | Channel compression captures ultra-high-net-worth residential buyers in London and New York. |
| Domestic Hardwood Sourcing Transition | Alpine walnut and oak substitution defends against EU Green Deal tropical timber restrictions. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs records, hospitality procurement databases, and ECHA regulatory filings. Primary interviews engaged furniture manufacturing executives, hospitality design specification leads, tannery operations managers, and EU regulatory affairs specialists. Secondary validation drew from Brianza cluster trade association reports, Italian customs export data, and EPA formaldehyde compliance disclosures. Bottom-up unit economics triangulate against top-down market sizing across product type, material, design style, and end-user segmentation.
Segmentation dimensions modeled include product complexity tier, material certification grade, design style cohort, and procurement channel type across the analysis window. CAGRs derive from fitted growth curves anchored to disclosed production volumes and import-export trajectories. Forecast inputs incorporate REACH chemical restriction timelines and EU Green Deal deforestation-free implementation phases.
Decision-makers should treat outputs as directional under sustained artisanal labor availability and stable regulatory enforcement intensity; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
US Contract Furniture and Furnishing Market
Furniture
Australia Smart Furniture Market
Furniture
North America School Furniture Market
Furniture
Russia Home Furniture Market
Furniture
Europe Free Standing Electrical Height-Adjustable Tables Market
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
China Home Furniture Market
Furniture
USA and Canada Teak Veneer Sheet Market
Furniture
Europe Wood Decorative Wall Panel Market
Furniture
India Furniture Market
Furniture
Indonesia Home Furniture Market
Furniture
UAE Home Furniture Market
Furniture
Kids Table and Chair Market
Furniture
Ready-To-Assemble (RTA) Furniture Market
Furniture
High End Furnitures Market
Furniture
Wood Furniture Market