
 China Automotive Engine Oils Market | 2026-2036
China Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
China Automotive Engine Oils Market Outlook
Aftermarket service revenue is reshaping margin capture in the China Automotive Engine Oils Market as lubricant suppliers compete for recurring drain-interval contracts. Royal Dutch Shell Plc leverages its premium synthetic formulations to dominate coastal urban service bays. China Petroleum & Chemical Corporation anchors volume through captive supply to domestic OEM assembly plants. Jiangsu Lopal Tech Co Ltd specializes in biodegradable blends targeting municipal fleet tenders in eastern provinces.
China automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and prevent wear in internal combustion engines operating across temperature extremes from minus 35°C to 150°C. Their primary commercial purpose is to extend engine operational life while maintaining fuel efficiency compliance under China's tightening corporate average fuel consumption standards. Synthetic formulations command premium positioning as OEM fill rates climb, while mineral grades retain volume in price-sensitive aftermarket channels across inland provinces. Distribution through auto workshops captures the highest per-unit margins as technicians influence brand selection during service events.
China's Ministry of Ecology and Environment enforces dual carbon goals that mandate lower viscosity grades and extended drain intervals, directly steering R&D toward 0W-20 and 5W-30 formulations. GB standards issued by SAMR define lubricant performance benchmarks for domestic market access, while NMPA-aligned testing protocols for imported additive packages create compliance barriers for foreign suppliers. Stakeholders must monitor regulatory alignment between provincial environmental bureaus and national standard-setters to anticipate formulation requirement shifts that will determine product registration timelines and manufacturing license renewals.
Market Dynamics
China's dual carbon goals are compressing formulation cycles as MEE mandates force lubricant suppliers to recalibrate viscosity portfolios ahead of GB standard revisions. The structural pressure to decarbonize commercial fleets is redrawing competitive boundaries between synthetic and mineral grade suppliers.
Growth Catalysts
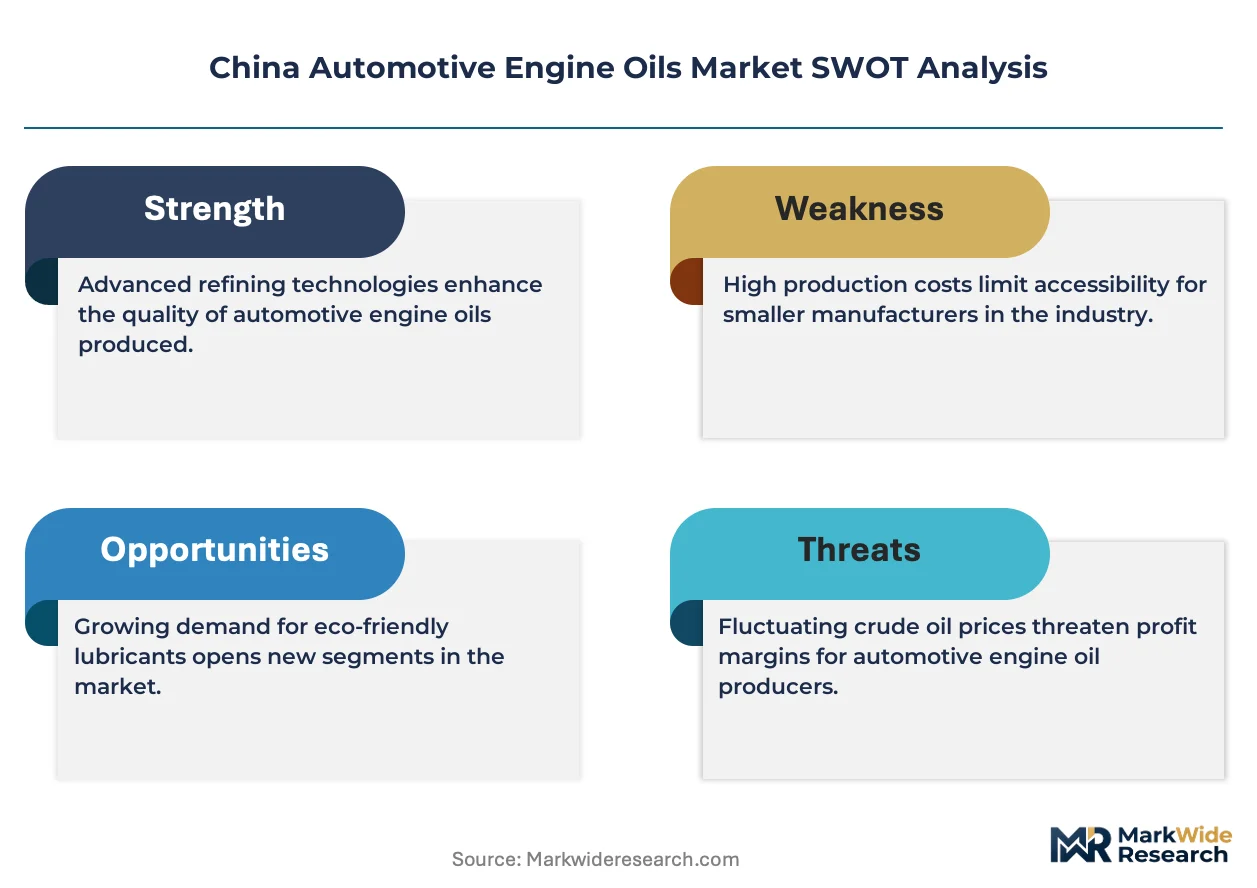
- Dual carbon mandate:MEE enforcement of lower viscosity grades accelerates 0W-20 and 5W-30 adoption across Yangtze River Delta commercial fleets.
- Synthetic technology:OEM fill rate requirements for extended drain intervals pull formulation R&D toward PAO and ester base stocks.
- Municipal fleet electrification:Hybrid powertrains in eastern provinces sustain lubricant demand through thermal management fluid diversification.
Market Restraints
- Additive package concentration:NMPA-aligned testing protocols for imported additive packages create compliance barriers for non-domestic suppliers.
- Base oil supply volatility:Group III+ base stock availability fluctuates with regional refinery maintenance schedules in Shandong and Liaoning.
- Mineral grade price floors:Inland aftermarket channels in Henan and Sichuan resist synthetic premiums, capping margin expansion.
Strategic Opportunities
- Biodegradable segment:Jiangsu municipal tenders for biodegradable blends open procurement channels outside traditional mineral supply chains.
- GB standard alignment:SAMR pre-registration pathways reward early movers with accelerated manufacturing license renewals.
- Workshop channel capture:Auto service bay technician influence over brand selection remains underexploited by formulation marketers.
Industry Challenges
- Formulation talent scarcity:Lubricant chemists with dual expertise in low-viscosity synthesis and China-specific additive compatibility command premium compensation.
- Provincial regulatory fragmentation:Environmental bureaus in Zhejiang and Guangdong interpret MEE circulars with divergent enforcement timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive Engine Oils Market |
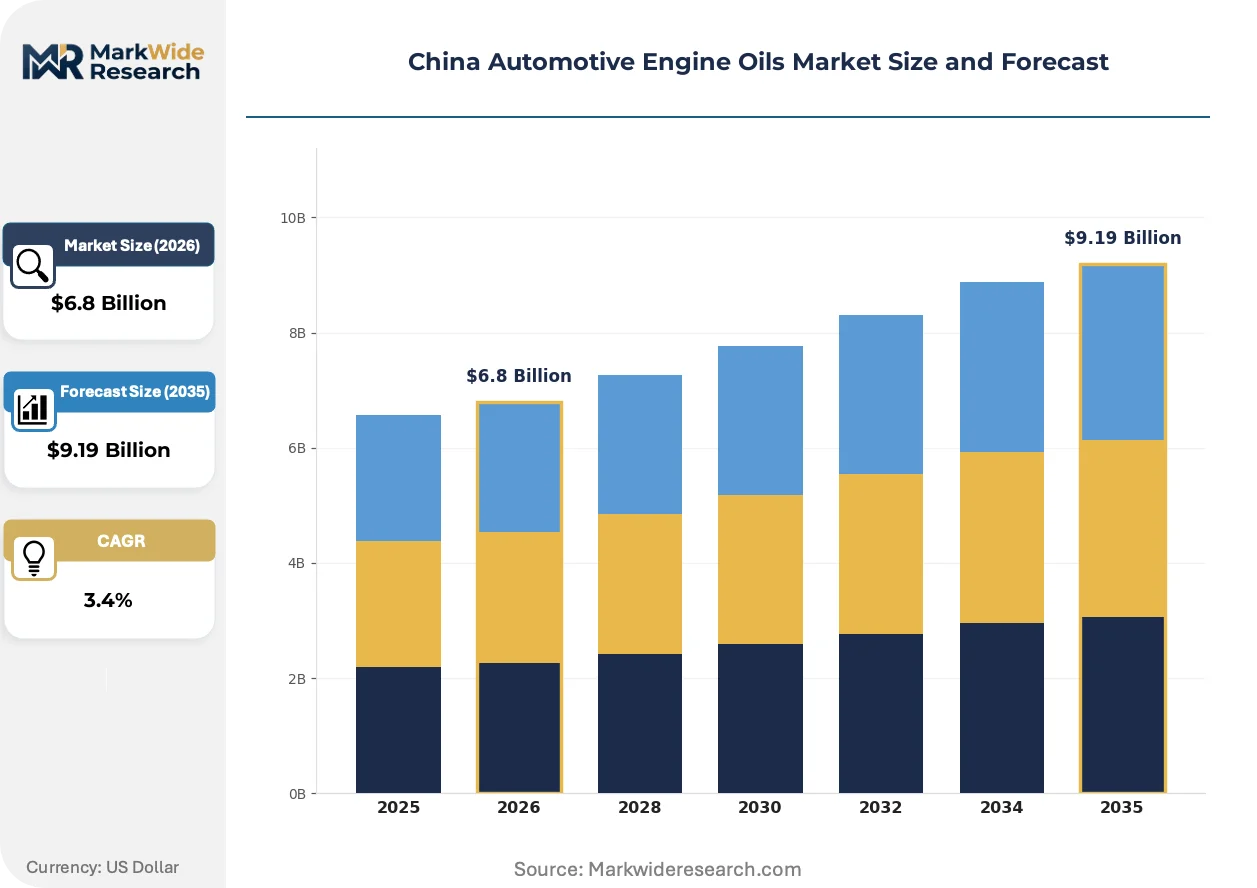
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.19 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Semi-Synthetic, Mineral, Biodegradable End User: Personal Vehicles, Commercial Vehicles, Heavy-Duty, Lubrication Providers Distribution Channel: Retail Stores, Online Sales, Auto Workshops, Distributors Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 |
| Companies Covered | ExxonMobil Corporation, TotalEnergies, BP PLC (Castrol), Jiangsu Lopal Tech Co Ltd, Chevron Corporation, China National Petroleum Corporation, Royal Dutch Shell Plc, Qingdao COPTON Technology Co Ltd, China Petroleum & Chemical Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive Engine Oils Market Strategic Shifts
Formulation science is converging with emissions compliance architecture as lubricant performance becomes inseparable from vehicle efficiency certification. Three forces are compressing traditional product lifecycles.
Polyalphaolefin (PAO) synthetic base stocks are hybridizing with Group III mineral oils to create mid-tier formulations that satisfy GB 11121-2006 wear specifications while meeting OEM demands for fuel economy credits. Domestic blenders in Jiangsu and Zhejiang are accelerating this hybridization to capture fleet operators transitioning from pure mineral grades. The resulting product tier is compressing price differentiation between premium synthetics and economy mineral oils.
MEE's 2024 circular on corporate average fuel consumption tightens lubricant viscosity allowances, forcing immediate formulation shifts toward 0W-16 and 0W-20 grades for new vehicle certification. Domestic OEMs in Shanghai and Guangzhou are responding with captive lubricant specifications that lock aftermarket competitors out of warranty service intervals. The policy is concentrating R&D investment in coastal formulation labs with SAMR direct registration pathways.
Fleet procurement departments are consolidating lubricant contracts around multi-year drain-interval agreements that bundle oil, filter, and analysis services. Workshop chains in the Yangtze River Delta are displacing independent service bays as the primary decision node for brand selection. This consolidation is most visible among logistics operators running 500-plus vehicle fleets across Jiangsu and Anhui provinces.
China Automotive Engine Oils Market Segmentation
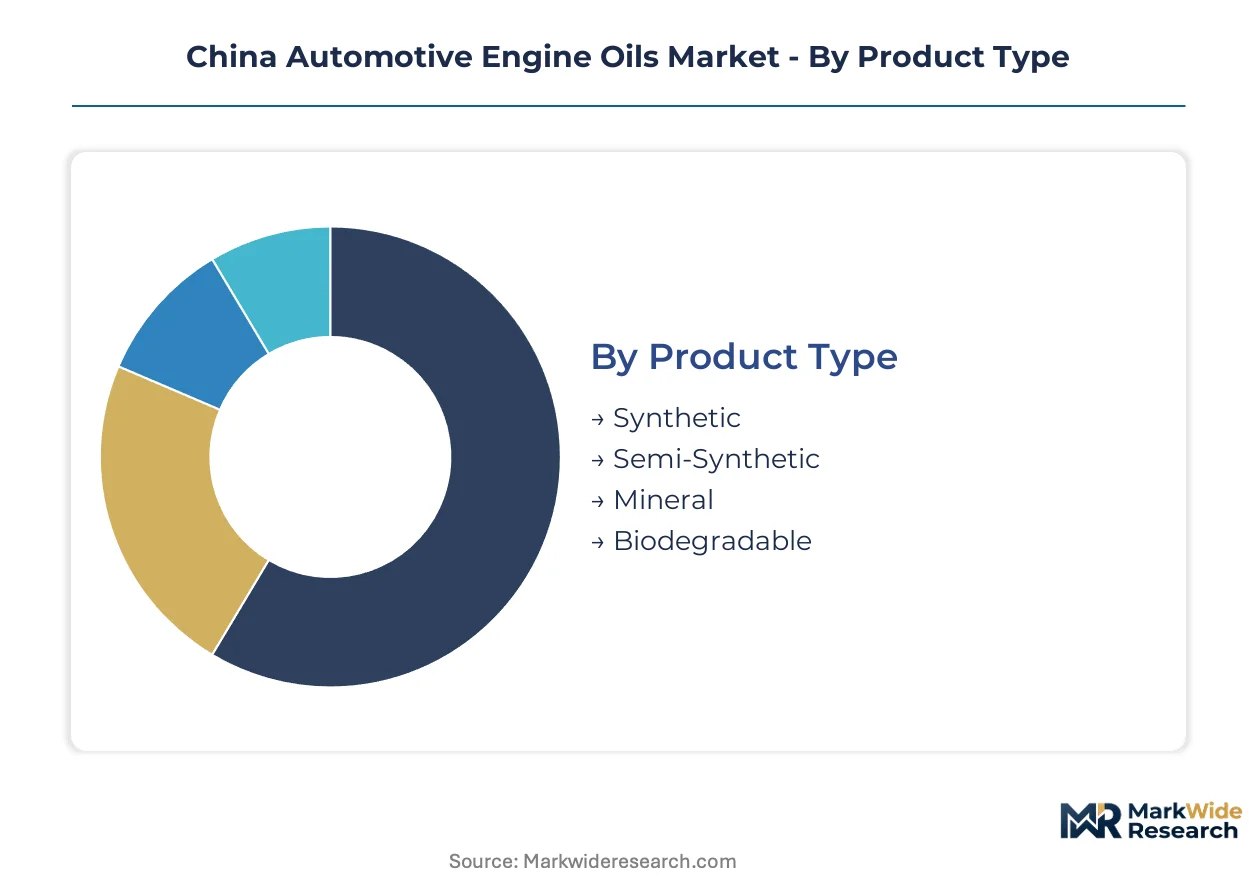
Segmentation in China's automotive engine oils market determines margin capture and R&D allocation as dual carbon mandates force divergent formulation strategies across product tiers. Fleet procurement patterns and workshop channel dynamics create distinct competitive battlegrounds within each dimension.
Product Type:
Cycle times vary dramatically across this category, with synthetic formulations turning over fastest as OEM specifications accelerate while mineral grades persist through price-sensitive aftermarket channels.
- Synthetic:PAO and ester base stocks deliver extended drain intervals and thermal stability under MEE-mandated low-viscosity requirements. Yangtze River Delta commercial fleets concentrate procurement here as dual carbon compliance tightens.
- Mineral:Group I and Group II base stocks retain volume in inland provinces where price floors dominate purchasing decisions. Henan and Sichuan aftermarket channels resist synthetic premiums despite gradual GB standard alignment.
- Semi-Synthetic:Hybrid formulations blending Group III mineral oils with synthetic additives capture fleet operators transitioning between pure grades.
- Biodegradable:Vegetable-derived base stocks target Jiangsu municipal tenders for environmental compliance in urban fleet operations.
Mineral grades anchor the volume base while synthetic formulations gain share at the steepest rate.
End User:
Cost tiers separate this category, with heavy-duty operators absorbing premium pricing for extended drain intervals while personal vehicle owners prioritize per-liter economy.
- Commercial Vehicles:Logistics fleets running 500-plus vehicle contracts across Jiangsu and Anhui consolidate procurement around bundled oil-filter-analysis services. Workshop chains displace independent bays as decision nodes.
- Heavy-Duty:Mining and construction equipment in northern provinces demands high-load formulations with enhanced detergent packages for severe operating conditions.
- Personal Vehicles:Urban car owners in Shanghai and Guangzhou follow OEM captive specifications that lock aftermarket competitors out of warranty intervals.
- Lubrication Providers:Third-party blending facilities in Shandong and Liaoning supply private-label formulations to regional distributors.
Commercial vehicles generate the highest per-account revenue while heavy-duty applications show the steepest expansion trajectory.
Distribution Channel:
Margin concentration varies inversely with volume throughput, with auto workshops capturing premium technician-influenced selection despite slower inventory turns than retail.
- Auto Workshops:Service bay technicians in the Yangtze River Delta exercise decisive brand influence during drain-interval events, commanding the highest per-unit margins.
- Distributors:Regional wholesalers in Jiangsu and Zhejiang provinces aggregate demand from smaller independent service providers.
- Retail Stores:Hypermarket and automotive specialty chains move volume through self-selection but lack technical consultation leverage.
- Online Sales:E-commerce platforms capture growing share among digitally native vehicle owners in tier-one cities.
Distributors handle the greatest volume throughput while auto workshops deliver the steepest margin expansion.
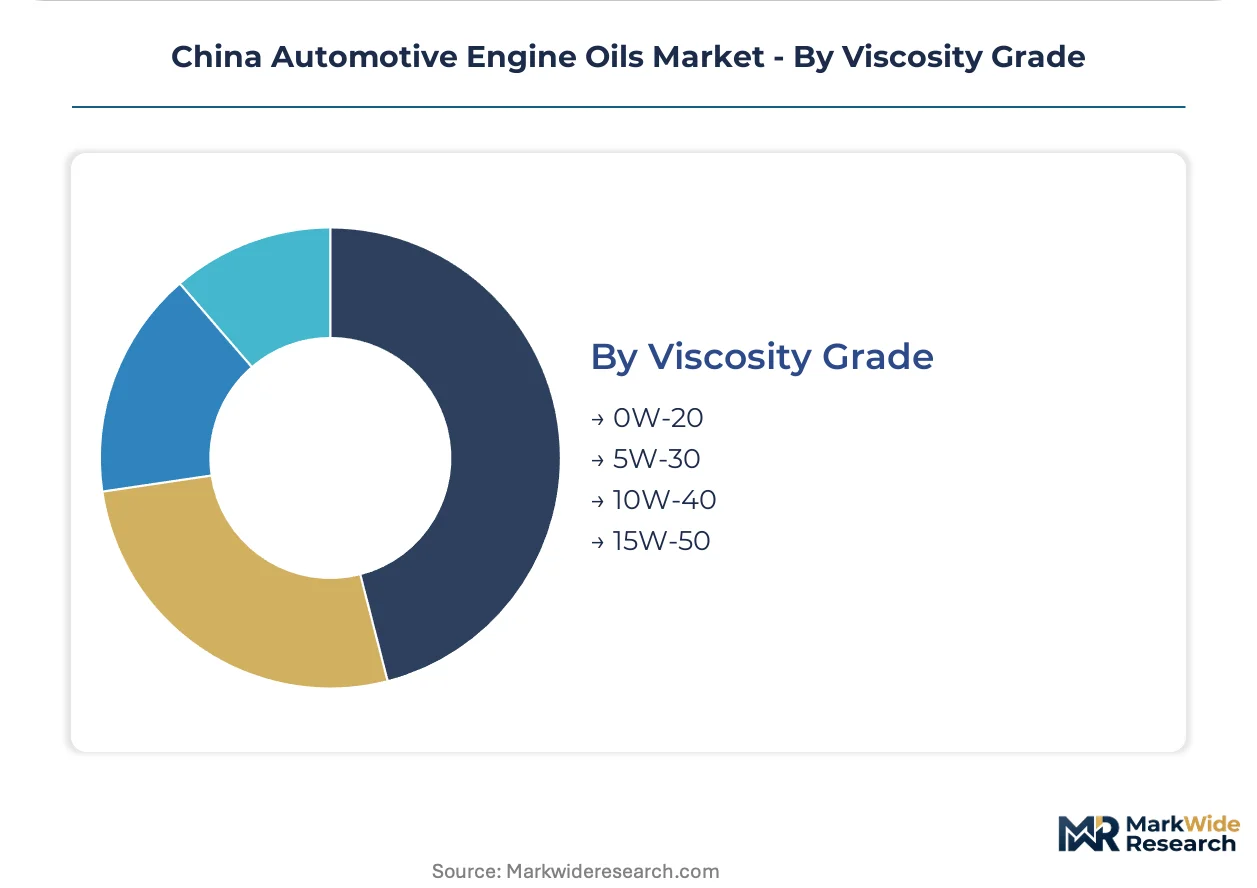
Viscosity Grade:
Application requirements and regulatory pressure stratify this category, with lower viscosity grades climbing fastest as MEE circulars tighten corporate average fuel consumption allowances.
- 0W-20:Ultra-low viscosity formulations enable OEM fuel economy certification under MEE's tightened standards. Shanghai and Guangzhou domestic manufacturers specify captive variants.
- 5W-30:The workhorse grade balances cold-start protection with high-temperature stability across China's temperature extremes from minus 35°C to 150°C.
- 10W-40:Older vehicle parc and commercial fleet legacy specifications sustain demand in inland aftermarket channels.
- 15W-50:High-viscosity protection for severe-duty applications in construction and mining equipment operating in harsh thermal environments.
5W-30 anchors the volume base while 0W-20 climbs the fastest as GB standard revisions accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in inland provinces exhibit the highest price elasticity, squeezing mineral-grade margins, while coastal fleet operators absorb synthetic premiums to meet compliance deadlines. Yangtze River Delta manufacturers face the tightest dual carbon enforcement, creating a demand bifurcation between east and west.
Yangtze River Delta
Shanghai-based logistics fleets consolidate procurement around 0W-20 synthetic formulations to satisfy MEE corporate average fuel consumption benchmarks. SAMR pre-registration pathways reward early movers with accelerated license renewals. Jiangsu and Zhejiang formulation labs concentrate R&D investment as domestic OEMs issue captive lubricant specifications.
Pearl River Delta
Guangzhou manufacturers specify ultra-low viscosity grades that lock aftermarket competitors out of warranty service intervals. MEE circulars on emissions compliance tighten faster here than national baselines. Shenzhen workshop chains displace independent service bays as the primary decision node for fleet lubricant contracts.
Beijing-Tianjin-Hebei
Heavy-duty mining equipment in northern provinces sustains demand for high-viscosity 15W-50 formulations with enhanced detergent packages. GB standards enforcement prioritizes winter cold-start protection in this temperature-extreme corridor. Tianjin blending facilities supply private-label formulations to regional distributors serving legacy commercial fleets.
Sichuan-Chongqing
Inland aftermarket channels in this western hub resist synthetic premiums despite gradual regulatory alignment. Price floors dominate purchasing decisions among independent service providers. Chengdu distributors aggregate fragmented demand from smaller workshops unable to commit to multi-year drain-interval contracts.
Shandong Peninsula
Group III+ base stock availability fluctuates with regional refinery maintenance schedules, creating supply volatility for domestic blenders. Qingdao COPTON Technology anchors formulation production for price-sensitive coastal markets. Provincial environmental bureaus here interpret MEE circulars with enforcement timelines diverging from eastern coastal standards.
China Automotive Engine Oils Market Competitive Environment
Capability concentration sits with multinational blenders commanding premium synthetic formulations; scale advantage sits with state-owned refiners integrating captive base oil supply. The market structures around three tiers: international majors with SAMR direct registration pathways, national oil companies with assembly plant supply contracts, and domestic specialists capturing municipal fleet tenders. Competitive moves center on formulation R&D acceleration and workshop channel capture through technician training programs.
Among international majors, Royal Dutch Shell Plc and ExxonMobil Corporation occupy positions defined by coastal urban service bay dominance and premium synthetic portfolios. China Petroleum & Chemical Corporation anchors the state-owned tier through captive supply relationships with domestic OEM assembly plants. Jiangsu Lopal Tech Co Ltd exemplifies the specialist archetype, targeting biodegradable blend procurement channels in eastern provincial municipal fleets. These three patterns—multinational premium positioning, state-backed volume integration, and niche compliance specialization—define competitive boundaries as dual carbon mandates tighten.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| TotalEnergies |
| BP PLC (Castrol) |
| Jiangsu Lopal Tech Co Ltd |
| Chevron Corporation |
| China National Petroleum Corporation |
| Royal Dutch Shell Plc |
| Qingdao COPTON Technology Co Ltd |
| China Petroleum & Chemical Corporation |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Ningbo freight corridor shapes cost dynamics across China's automotive engine oils market, concentrating supply-side leverage among Yangtze River Delta blenders while downstream price differentiation splits between coastal fleet operators absorbing synthetic premiums and inland buyers resisting grade upgrades. MEE-mandated viscosity shifts compress margin structures as formulation R&D costs concentrate in SAMR-registered facilities.
Pricing Analysis
Aftermarket service revenue drives lifetime value capture as workshop chains bundle drain-interval contracts with filter and analysis services. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy mineral levels reflects GB standard certification tiers and OEM captive specifications. Cost compression in mineral grades intensifies because inland distributors in Henan and Sichuan prioritize per-liter economy over performance metrics. Personal vehicle owners in tier-one cities show least price sensitivity, while independent service providers in western provinces exhibit highest elasticity.
Supply Chain Analysis
Export-control restrictions on advanced additive package technologies limit flows from US and European specialty chemical suppliers, forcing domestic blenders toward NMPA-aligned testing protocols. Base oil supply concentrates in China, South Korea, and Singapore, with Group III+ stocks fluctuating around Shandong and Liaoning refinery schedules. Raw material dependencies span PAO synthetic stocks, ester base oils, and detergent-dispersant additive packages. Single-source vulnerability runs through imported high-performance additive suppliers. Distribution runs through regional distributors aggregating fragmented workshop demand into consolidated procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated logistics fleets running 500-plus vehicle contracts, fragmenting decision authority away from independent service bays toward procurement departments with multi-year lubricant agreements.
For Market Incumbents: Build formulation moats around SAMR pre-registration pathways for 0W-16 and 0W-20 grades ahead of GB standard revisions. Deepen captive supply relationships with domestic OEMs in Shanghai and Guangzhou to lock aftermarket competitors out of warranty intervals. Counter emerging biodegradable specialists by accelerating hybrid synthetic-mineral R&D in Jiangsu formulation labs. For New Entrants and Emerging Players: Establish a beachhead in municipal fleet tenders across Jiangsu and Zhejiang provinces where environmental compliance requirements outpace incumbent response capacity. Target biodegradable blend procurement channels outside traditional mineral supply chains. Penetrate through direct technician training programs that bypass established distributor relationships in the Yangtze River Delta workshop chains. For Investors and Strategic Acquirers: Domestic blenders with SAMR direct registration capabilities and coastal formulation lab assets represent the most defensible acquisition targets as regulatory compliance barriers steepen. Long-term viability hinges on positioning ahead of MEE's tightened corporate average fuel consumption circulars. Watch for inflection when provincial environmental bureaus in Guangdong and Zhejiang diverge on enforcement timelines, creating arbitrage opportunities for early movers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Shandong and Liaoning refinery control secures Group III+ supply against maintenance volatility. |
| SAMR Pre-Registration Investment | Early GB standard alignment accelerates manufacturing license renewals ahead of formulation requirement shifts. |
| Workshop Chain Technician Training | Yangtze River Delta service bay influence over brand selection remains underexploited by formulation marketers. |
| Biodegradable Blend Development | Jiangsu municipal tenders open procurement channels outside traditional mineral supply chains. |
| Multi-Year Drain-Interval Contracts | Fleet procurement consolidation around bundled oil-filter-analysis services displaces spot purchasing. |
Study Parameters
A spread of perspectives from lubricant formulation chemists, fleet procurement managers, aftermarket service technicians, and SAMR regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against customs records, GB standard filings, MEE circular archives, and vehicle production databases. Bottom-up volume builds across viscosity grades and end-use segments triangulated against top-down market sizing from refinery output and additive package import flows.
Demand-supply balance modeling anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, end user category, distribution channel, and viscosity grade. CAGRs derived from regression analysis against OEM fill rate trajectories and fleet electrification patterns. Industry-specific inputs included MEE enforcement timelines for dual carbon goals and provincial environmental bureau interpretation divergence.
Stress conditions across base oil price volatility, additive package import restriction severity, and workshop chain consolidation speed were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about GB standard revision timing and SAMR registration pathway efficiency. Material shifts in MEE circular enforcement intensity or provincial regulatory fragmentation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Malaysia Automotive Engine Oils Market
Lubricants
Global Process Oil Market
Lubricants
Angola Lubricants Market
Lubricants
North America and Europe Forestry Lubricants Market
Lubricants
Brazil Commercial Vehicles Lubricants Market
Lubricants
Bangladesh Lubricants Market
Lubricants
Argentina Lubricants Market
Lubricants
Food Grade Lubricant Market
Lubricants
Global Compressor Oil Market
Lubricants
United States Commercial Vehicles Lubricants Market
Lubricants
Malaysia Automotive Lubricants Market
Lubricants
Italy Automotive Lubricants Market
Lubricants
Japan Lubricants Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
Poland Automotive Engine Oils Market
Lubricants
Africa Heavy Equipment Lubricants Market